
 Asia-Pacific Oriented Strand Board Market | 2026-2036
Asia-Pacific Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Oriented Strand Board Market Outlook
Buyer concentration among Asia-Pacific construction contractors is broadening as state-led housing programs fragment procurement across regional developers while modular home builders gain purchasing scale. West Fraser Timber Co. Ltd. leverages its coastal British Columbia timber base to supply Asian import channels with structural-grade panels. Georgia-Pacific LLC anchors its position through phenolic resin technology leadership that meets Japan's JIS standards for exterior sheathing. Kronospan competes via integrated strand mills in Central Europe that feed Pacific Rim distribution networks.
Oriented Strand Board consists of layered wood strands arranged in cross-oriented configurations, bonded with waterproof adhesives under heat and pressure to achieve specific mechanical strength ratings such as MOR values exceeding 3,800 psi for structural applications. The engineered panel serves primarily as load-bearing sheathing in residential and commercial framing systems where dimensional stability and cost efficiency replace plywood. Structural OSB dominates volume flows across the region's construction channels, while moisture-resistant grades capture margin pools in tropical climates where humidity cycling degrades standard panels. Fire-retardant OSB occupies a narrower but higher-value niche in multi-story commercial builds across Australian cities subject to stringent bushfire construction codes.
Japan's METI enforces JIS A 5908 standards that govern panel density and adhesive durability, while Australia's NCC mandates bushfire attack level ratings for external wall systems in designated fire-prone zones. China's SAMR administers GB/T 4897 compliance for structural wood-based panels entering commercial projects, creating certification barriers for uncured imports. Stakeholders must monitor how Indonesia's national building code revisions incorporate engineered wood standards, as this will determine which resin systems and density grades gain preferential access to Southeast Asia's largest construction pipeline.
Market Dynamics
China's SAMR is tightening GB/T 4897 formaldehyde emission limits, forcing mills toward phenolic resin systems and reshaping competitive positioning across the Asia-Pacific panel supply base.
Growth Catalysts
- Indonesia's Java-Bali corridor:Prefabricated building clusters are absorbing rising OSB volumes for wall sheathing and floor substrates as state-led housing programs accelerate.
- Japan's JIS A 5908 standards:Exterior sheathing specifications for panel density and adhesive durability are pulling moisture-resistant grades into commercial framing systems.
- Phenolic resin technology:Waterproof adhesive systems are displacing urea-formaldehyde binders as China's GB standards tighten structural wood panel compliance.
Market Restraints
- Softwood strand supply concentration:Coastal British Columbia timber bases anchor structural-grade panel flows, creating geographic vulnerability to Pacific shipping disruptions.
- Formaldehyde emission compliance costs:China's SAMR certification barriers for uncured imports raise working capital requirements for cross-border distributors.
- Plywood substitution in tropical climates:Traditional hardwood panels retain cost advantages in Indonesian residential construction where humidity cycling is moderate.
Strategic Opportunities
- Australian bushfire construction codes:Fire-retardant OSB grades command premium positioning in multi-story commercial builds across Sydney and Melbourne subject to NCC-mandated attack level ratings.
- Modular home builder procurement scale:Factory-based construction channels in Thailand and Vietnam are consolidating panel purchasing away from fragmented site-based contractors.
- Central European strand mill integration:Pacific Rim distribution networks can leverage existing phenolic resin capacity to serve Southeast Asia's tightening emission standards.
Industry Challenges
- Resin formulation technical expertise:Mills transitioning from urea-formaldehyde to phenolic systems face skilled chemist shortages in Indonesia and Vietnam.
- GB/T 4897 certification timelines:China's SAMR structural wood panel compliance creates six-to-nine-month market entry delays for new import suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Oriented Strand Board Market |
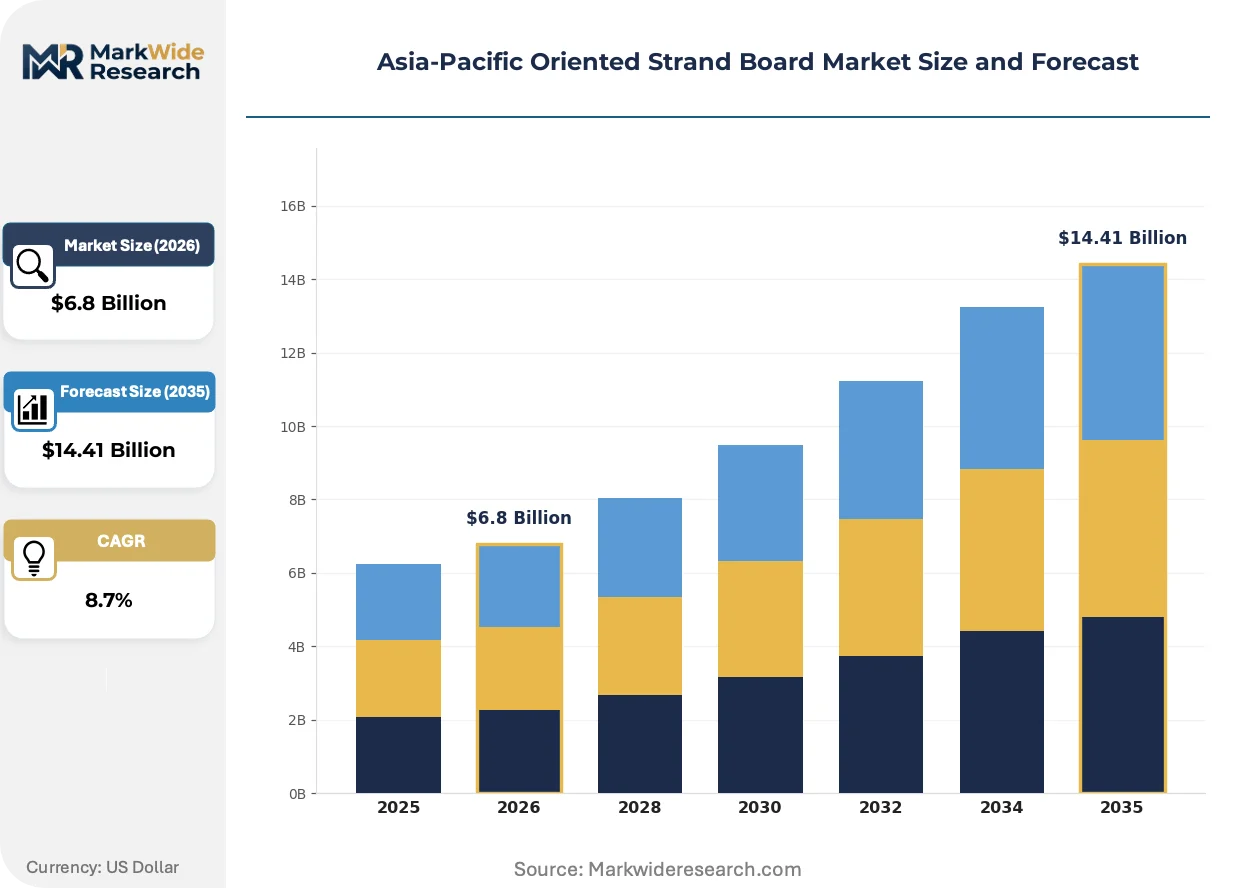
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard OSB, Fire-Retardant OSB, Moisture-Resistant OSB, Industrial OSB, Structural OSB Application: Wall Sheathing, Floor Substrate, Roof Decking, Packaging, Furniture Manufacturing End User: Construction Contractors, Furniture Makers, Packaging Manufacturers, Modular Home Builders Distribution Channel: Direct Sales, Wholesalers, Retail Lumberyards, Online Platforms |
| Companies Covered | West Fraser Timber Co. Ltd., Coilite, Egger Group, Nine Dragons Paper (Holdings) Limited, Georgia-Pacific LLC, Kronospan, Sonae Arauco, Tolko Industries Ltd., SWISS KRONO Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Oriented Strand Board Market Strategic Shifts
Adhesive chemistry advances and prefabricated construction methods are compressing traditional plywood dominance while reshaping how structural panels move through Asia-Pacific distribution channels.
Phenolic resin bonding systems are expanding into high-humidity applications across Southeast Asia's tropical belt. Japanese commercial builders are specifying these grades for exterior sheathing at accelerating rates. The technology is compressing urea-formaldehyde market share in segments where JIS A 5908 durability requirements apply.
China's GB/T 4897 revisions are mandating stricter structural wood panel testing protocols for commercial projects. The SAMR compliance framework is elevating certified mill capacity while excluding uncured imports. Indonesian developers are responding by pre-qualifying suppliers with demonstrated phenolic resin track records.
Contractor purchasing is fragmenting across state-led housing programs while modular builders consolidate volume. Site-based procurement in Vietnam and Thailand is yielding to factory-direct panel scheduling. The shift is most visible in Indonesia's Java-Bali corridor where prefabricated clusters now specify OSB substrates in bulk tender structures.
Asia-Pacific Oriented Strand Board Market Segmentation
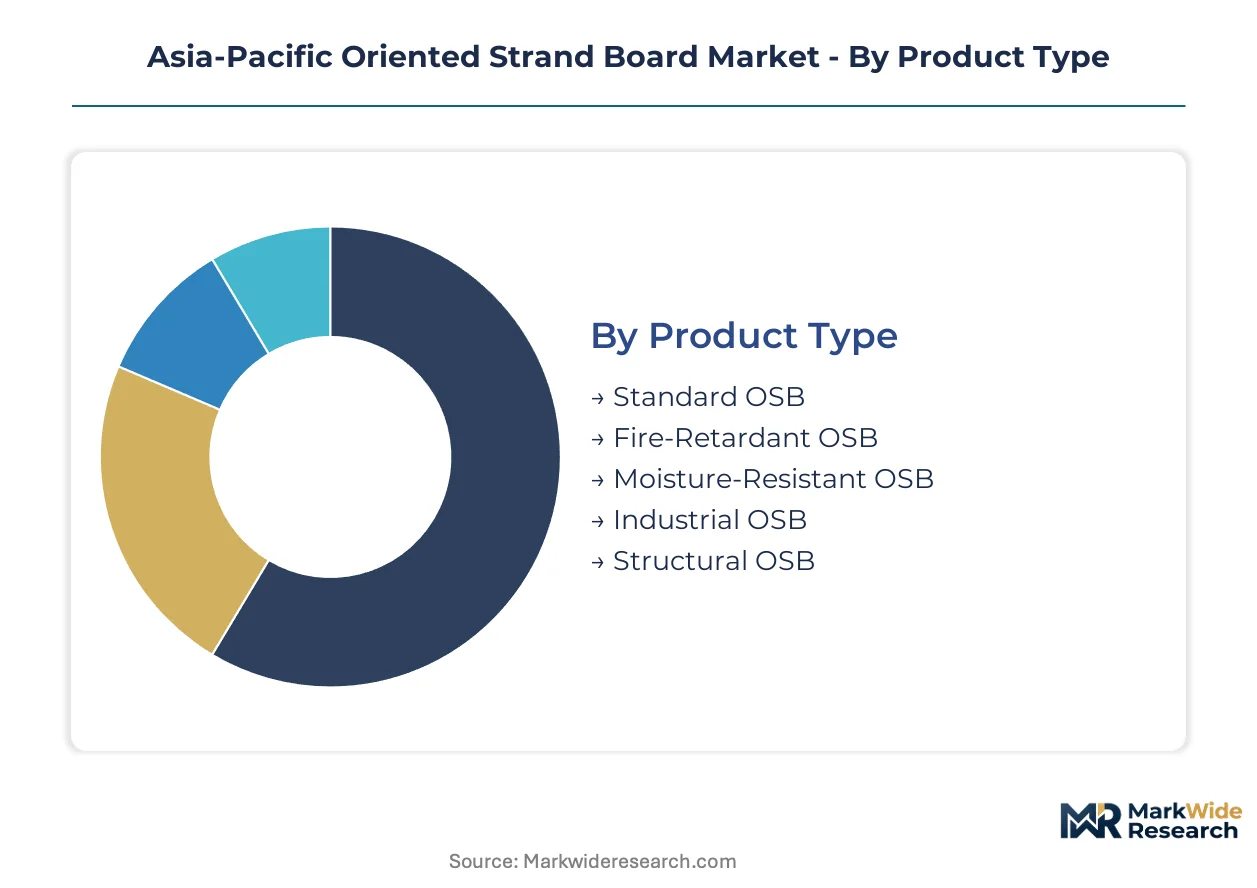
OSB demand fragments across performance tiers that align with specific building code triggers and climate exposure. Resin chemistry and density ratings determine which segments capture volume in Southeast Asia's humid construction corridors versus Australia's fire-prone zones.
Product Type:
Supply concentration favors mills with phenolic resin capacity that can pivot between standard and moisture-resistant grades as China's SAMR tightens emission limits.
- Standard OSB:Cross-oriented wood strands bonded with urea-formaldehyde adhesives serve interior wall sheathing in climate-controlled environments. Indonesian residential developers in the Java-Bali corridor specify this grade for cost-sensitive housing blocks where humidity exposure is limited.
- Moisture-Resistant OSB:Phenolic resin bonding systems achieve density ratings above 640 kg/m³ for exterior sheathing applications. Japanese commercial builders under METI's JIS A 5908 standards are specifying these grades for wall systems facing monsoon exposure.
- Fire-Retardant OSB:Intumescent-treated panels meet Australia's NCC bushfire attack level ratings for multi-story commercial builds in Sydney and Melbourne.
- Industrial OSB:Lower-density panels serve non-structural packaging and crating applications across Thailand's manufacturing export zones.
- Structural OSB:High-MOR panels exceeding 3,800 psi anchor floor substrates in Vietnam's prefabricated housing clusters.
Structural OSB absorbs the bulk of installed capacity; moisture-resistant grades are expanding most quickly as tropical climate specifications tighten.
Application:
Cost tier differentiation separates commodity sheathing from engineered systems that command specification premiums in commercial framing.
- Wall Sheathing:OSB panels replace plywood in residential framing systems where dimensional stability and nail-holding strength matter. Indonesia's state-led housing programs are consolidating procurement around this application in prefabricated building clusters.
- Floor Substrate:Tongue-and-groove edge profiles create seamless load-bearing surfaces for modular home builders in Thailand and Vietnam. Factory-direct scheduling is compressing traditional site-based plywood installation cycles.
- Roof Decking:Structural panels with enhanced span ratings serve commercial builds under Japan's snow load requirements.
- Packaging:Industrial-grade OSB replaces hardwood crates for machinery exports from China's coastal manufacturing zones.
- Furniture Manufacturing:Sanded OSB substrates enter flat-pack furniture production for Southeast Asian export markets.
Wall sheathing dominates procurement volumes; floor substrates are climbing the fastest as modular construction scales.
End User:
Customer type determines volume scale and specification complexity, with factory-based builders consolidating purchasing power away from fragmented site contractors.
- Construction Contractors:Site-based procurement across Indonesia and Vietnam is yielding to bulk tender structures as state housing programs fragment awards across regional developers.
- Modular Home Builders:Factory-based construction channels in Thailand consolidate panel purchasing through direct mill relationships, bypassing traditional lumberyard distribution.
- Furniture Makers:Sanded panel demand concentrates in export-oriented manufacturing zones serving flat-pack retailers.
- Packaging Manufacturers:Industrial OSB consumption tracks machinery and electronics export volumes from China's Pearl River Delta.
Construction contractors still move the largest tonnage; modular home builders are gaining share fastest through consolidated factory procurement.
Distribution Channel:
Geography shapes channel efficiency, with coastal proximity to strand mills determining whether direct sales or intermediaries capture margin.
- Direct Sales:Mill-direct relationships serve modular builders and large contractors with scheduled panel deliveries synchronized to factory production cycles. Vietnam's prefabricated housing clusters leverage this channel for just-in-time substrate supply.
- Wholesalers:Regional distributors aggregate fragmented contractor demand across Indonesia's archipelago geography, absorbing inventory risk for smaller builders.
- Retail Lumberyards:Local stocking points serve repair and renovation contractors with immediate availability for small-batch orders.
- Online Platforms:Digital procurement channels are emerging for standardized grades in China's tier-two construction markets.
Direct sales capture the steepest expansion trajectory; wholesalers still anchor volume in geographically fragmented markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in prefabricated construction corridors where state housing programs and modular builder procurement are displacing traditional site-based panel sourcing. China's GB standards and Japan's JIS frameworks are pulling regional supply chains toward phenolic resin compliance. Indonesia's Java-Bali corridor anchors Southeast Asian volume absorption.
China
Commercial builders in the Yangtze River Delta and Pearl River Delta are specifying structural OSB for mid-rise residential frames. SAMR's GB/T 4897 revisions mandate stricter formaldehyde testing protocols that exclude uncured imports. Coastal manufacturing zones around Shanghai and Guangzhou are pre-qualifying suppliers with demonstrated phenolic resin track records.
Japan
Commercial framing systems in Tokyo and Osaka are absorbing moisture-resistant grades for exterior sheathing exposed to monsoon cycling. METI enforces JIS A 5908 standards governing panel density and adhesive durability. Kanto and Kansai construction corridors are consolidating procurement around certified mills with waterproof bonding capacity.
Indonesia
State-led housing programs in the Java-Bali corridor are fragmenting awards across regional developers while scaling prefabricated cluster construction. National building code revisions are incorporating engineered wood standards that will determine resin system eligibility. Surabaya and Bandung satellite cities are specifying OSB wall sheathing and floor substrates in bulk tender structures.
Vietnam
Modular home builders in Ho Chi Minh City and Hanoi are consolidating panel purchasing through direct mill relationships. Factory-based construction channels are compressing traditional lumberyard distribution cycles. Northern industrial zones around Hai Phong are anchoring just-in-time substrate supply for prefabricated housing clusters.
Australia
Multi-story commercial builds in Sydney and Melbourne are specifying fire-retardant grades under NCC-mandated bushfire attack level ratings. New South Wales and Victorian construction codes are tightening external wall system requirements for designated fire-prone zones. Coastal urban corridors are absorbing premium-positioned panels for high-density residential frames.
Asia-Pacific Oriented Strand Board Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue phenolic resin specialization and modular builder direct relationships. The vendor base stratifies across coastal timber access, resin technology leadership, and Pacific Rim distribution integration. Three archetypes dominate: integrated strand mill operators with captive timber supply, adhesive technology specialists with certification-tracked capacity, and regional distributors leveraging Central European production bases. Capacity expansion and strategic partnerships represent the dominant competitive moves as mills reposition for China's tightening emission standards.
Among North American timber-anchored producers, West Fraser Timber Co. Ltd. and Tolko Industries Ltd. occupy positions tied to coastal British Columbia strand supply. European-integrated operators including Kronospan and Egger Group exemplify phenolic resin capacity that feeds Pacific Rim distribution networks. Georgia-Pacific LLC sits within the adhesive technology tier, representing waterproof bonding systems aligned with Japan's JIS durability requirements.
| Leading Market Players |
|---|
| West Fraser Timber Co. Ltd. |
| Coilite |
| Egger Group |
| Nine Dragons Paper (Holdings) Limited |
| Georgia-Pacific LLC |
| Kronospan |
| Sonae Arauco |
| Tolko Industries Ltd. |
| SWISS KRONO Group |
| Others |
Value Chain & Pricing Dynamics
Phenolic resin input costs cascade through three distinct pricing tiers as waterproof adhesive systems displace legacy urea-formaldehyde binders across Asia-Pacific panel markets. Coastal British Columbia timber supply anchors premium structural-grade positioning while Southeast Asian mills absorb formulation transition costs in mid-tier segments.
Pricing Analysis
Volume concentrates in standard OSB grades where Indonesian residential developers drive procurement scale, while moisture-resistant and fire-retardant tiers capture margin premiums through JIS A 5908 and NCC certification requirements. Price differentiation separates phenolic-bonded panels meeting China's GB/T 4897 emission limits from uncertified imports facing SAMR exclusion. Cost compression in the standard tier intensifies as plywood substitution retains cost advantages in moderate-humidity Indonesian construction. Modular home builders in Thailand and Vietnam exhibit lowest price sensitivity through factory-direct mill relationships, while fragmented site-based contractors across Indonesia's archipelago geography remain most price-sensitive.
Supply Chain Analysis
Softwood strand supply rests on coastal British Columbia timber bases, Central European integrated mill networks, and emerging Southeast Asian plantation sources. Raw material dependencies center on phenol-formaldehyde resin precursors, oriented strand processing equipment, and kiln-drying energy inputs. Single-source vulnerability concentrates in Pacific shipping lanes connecting British Columbia export terminals to Asian import channels. Distribution runs through direct mill relationships for modular builders, regional wholesalers aggregating fragmented Indonesian demand, and retail lumberyards serving renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific OSB market sits in a technology-transition phase as phenolic resin bonding systems replace urea-formaldehyde across structural panel applications. Waterproof adhesive chemistry is displacing legacy binders as the dominant competitive differentiator.
For Market Incumbents: Anchor coastal British Columbia timber access through long-term harvest agreements while accelerating phenolic resin capacity certification for China's SAMR compliance. Defend against Central European integrated mills by deepening backward integration into strand processing and pre-qualifying for Indonesia's national building code revisions. Prioritize direct sales channel control with modular builders in Vietnam and Thailand where factory procurement is consolidating.
For New Entrants and Emerging Players: Begin with fire-retardant OSB specialization for Australia's NCC-mandated bushfire attack level ratings, where premium positioning and limited certified supply create penetrable white space. Target Sydney and Melbourne multi-story commercial builds where specification premiums offset scale disadvantages. Pursue joint venture structures with established phenolic resin technology holders to bypass GB/T 4897 certification timelines.
For Investors and Strategic Acquirers: Indonesia's national building code revision incorporating engineered wood standards is the leading indicator that phenolic resin certification capacity will command acquisition premiums. Position for five-to-ten-year viability by targeting mid-scale mills with demonstrated waterproof bonding track records and coastal logistics access. Monitor SAMR import exclusion enforcement as the signal for regional supply chain restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Phenolic Resin Capacity Expansion | GB/T 4897 compliance unlocks China's Yangtze and Pearl River Delta commercial construction channels. |
| Direct Mill Relationships with Modular Builders | Factory-based procurement in Thailand and Vietnam compresses traditional lumberyard distribution cycles. |
| Fire-Retardant Certification Investment | NCC bushfire attack level ratings enable premium positioning in Sydney and Melbourne high-density builds. |
| Coastal Timber Supply Agreements | British Columbia strand access secures structural-grade panel flows against Pacific shipping disruptions. |
| JIS A 5908 Compliance Certification | METI durability standards open Tokyo and Osaka exterior sheathing specifications to moisture-resistant grades. |
Study Parameters
Document review covered customs and trade flow databases, national building code revision filings, and mill certification records, complemented by interviews with resin technology specialists, procurement directors at modular home builders, distribution channel managers, and regulatory compliance officers. Secondary validation drew from SAMR GB standard publications, METI JIS framework documentation, and Australian NCC amendment registers. Bottom-up volume estimates from mill capacity and utilization rates were triangulated against top-down construction spending allocation models.
Cross-referencing historical panel demand elasticities with forward-looking construction pipeline data anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, application function, end-user procurement scale, and distribution channel structure. CAGRs were derived from trend extrapolation moderated by regulatory inflection points. Forecast inputs incorporated phenolic resin adoption curves, prefabricated construction penetration rates, and national building code implementation timelines.
Raw material cost volatility, shipping lane disruptions, and regulatory enforcement intensity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about SAMR certification continuity, JIS standard stability, and Indonesian code revision adoption speed. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Acoustical Ceiling Market
Building & Construction Materials
Asphalt Shingles Market
Building & Construction Materials
North America Steel Roofing Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Tile Backer Boards Market
Building & Construction Materials
Travertine Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Global Convertible Roof System Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market