
 North America Concrete Superplasticizer Market | 2026-2036
North America Concrete Superplasticizer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concrete Superplasticizer Market Intelligence
Market Dynamics
US Gulf Coast capacity expansion is rewriting supply availability for polycarboxylate ether superplasticizers across North America. BASF SE leverages its integrated petrochemicals footprint to sustain cost-advantaged production of high-performance admixtures. Sika AG anchors its position through specialized distribution networks serving ready-mix concrete producers. GCP Applied Technologies Inc. competes on technology leadership in rheology-modifying formulations for infrastructure applications.
Product Landscape
Concrete superplasticizers are high-range water-reducing admixtures, typically formulated from polycarboxylate ether polymers or sulfonated naphthalene condensates, that enable flowable concrete at low water-to-cement ratios without segregation. Their primary industrial purpose is to achieve specified compressive strength and durability targets while maintaining workability in demanding placement conditions. Polycarboxylate ether formulations command premium positioning due to superior slump retention and tailored molecular architecture for high-performance concrete. Self-consolidating concrete applications represent the fastest-growing demand segment as complex formwork designs proliferate in commercial construction.
Regulatory Environment
ASTM C494 standards govern chemical admixture performance classification across US jurisdictions, while CSA A266.1 requirements shape product qualification in Canadian provinces. The US EPA's construction and demolition debris regulations indirectly steer specification toward durable concrete mixes requiring advanced superplasticizer chemistry. Stakeholders must monitor state-level Buy America provisions for federally funded infrastructure, as domestic content rules increasingly influence admixture sourcing decisions for public works contractors.
Market Dynamics
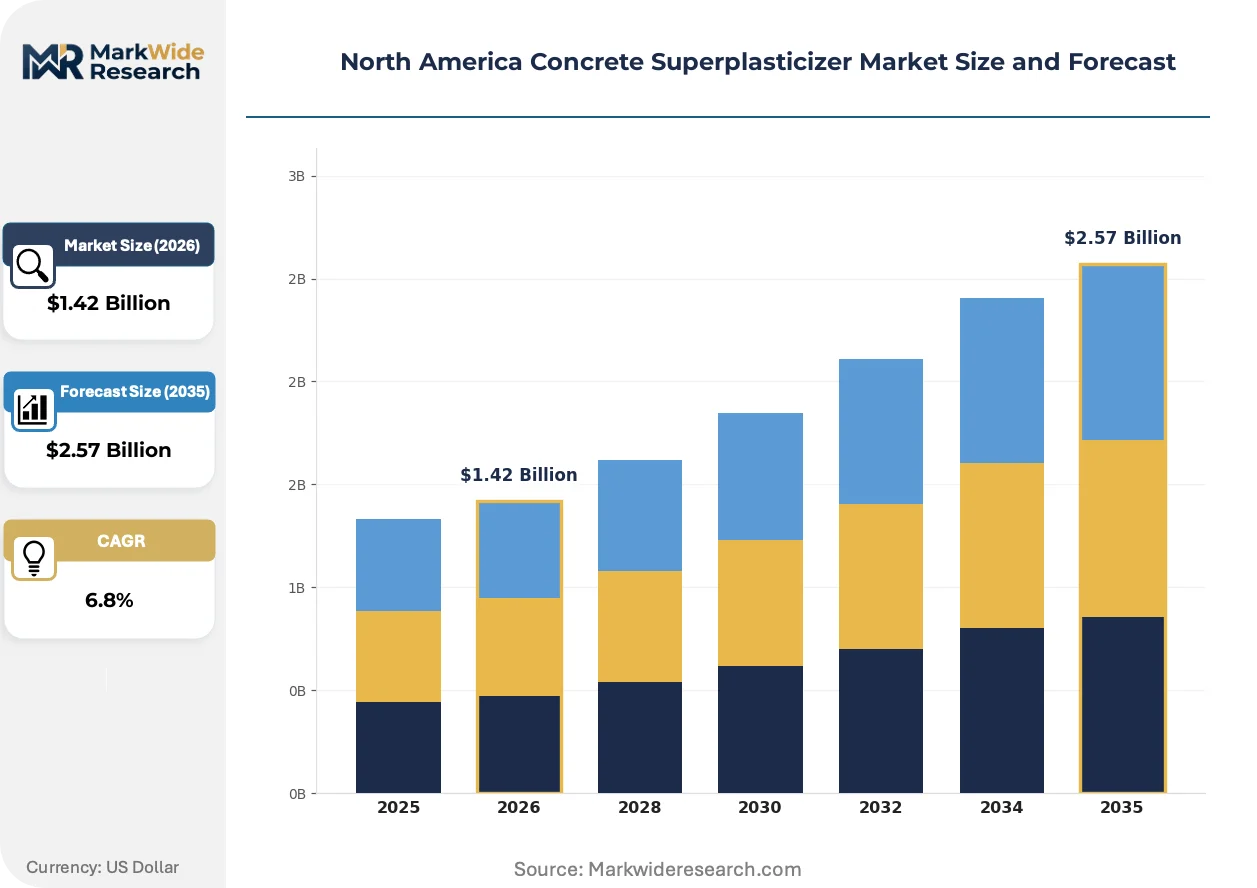
The US Gulf Coast's polycarboxylate ether production cluster is consolidating supply leverage, as integrated petrochemical complexes convert ethylene oxide derivatives into high-performance admixtures at scale advantages unreachable by distributed blending operations.
Growth Catalysts
- Infrastructure rehabilitation mandates:Federal bridge and highway repair programs across the United States are specifying high-performance concrete mixes requiring advanced superplasticizer chemistry to achieve extended service life targets.
- Self-consolidating concrete specification:Complex architectural formwork in commercial construction is displacing conventional placement methods, creating specification pull for slump-retaining polycarboxylate ether formulations.
- EPA durability standards:Evolving construction material regulations are compressing water-to-cement ratio tolerances, forcing specification upgrades toward high-range water reducers.
Market Restraints
- Ethylene oxide feedstock concentration:Gulf Coast petrochemical corridor disruptions propagate rapidly through polycarboxylate ether supply chains, creating single-point vulnerability.
- Technical compatibility limits:Polycarboxylate ether chemistry exhibits sensitivity to cement alkalinity variations, restricting reliable performance across diverse regional cement sources.
- Sulfonated naphthalene substitution pressure:Cost-sensitive ready-mix segments in price-competitive markets revert to legacy condensate chemistry despite performance tradeoffs.
Strategic Opportunities
- Canadian infrastructure stimulus:Federal transit and water treatment commitments under the Canada Infrastructure Bank are accelerating specification migration toward high-performance admixtures in Ontario and British Columbia.
- 3D-printed concrete construction:Layered deposition robotics require rheology-tailored superplasticizer systems with precise thixotropic control, opening formulation specialization white space.
- Buy America compliance services:Domestic content verification for federally funded projects creates advisory and certification revenue streams beyond commodity admixture sales.
Industry Challenges
- Admixture compatibility testing capacity:Cement source variability across North American markets strains quality assurance laboratories, extending project qualification timelines.
- Batch plant integration complexity:Automated dosing system retrofits for polycarboxylate ether polymers require capital deployment and operator retraining at fragmented ready-mix operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concrete Superplasticizer Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarboxylate Ether, Melamine, Naphthalene, Lignosulfonate Application: Ready-Mix Concrete, Precast Concrete, Self-Consolidating Concrete, High-Performance Concrete Distribution Channel: Direct Sales, Online Sales, Wholesalers, Retail Stores End User: Residential, Commercial, Infrastructure, Industrial |
| Companies Covered | Fosroc, Inc., The Euclid Chemical Company, Sika AG, Evonik Industries AG, Arkema, BASF SE, GCP Applied Technologies Inc., Kao Corporation, MAPEI S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concrete Superplasticizer Market Strategic Shifts & Innovations
Formulation science is converging with digital concrete monitoring, creating demand for admixtures that communicate placement parameters in real time. Molecular architecture customization is compressing the gap between laboratory performance and field reliability.
Polycarboxylate ether polymers with grafted side-chain density variations are hybridizing slump retention and viscosity-modifying functions into single-admixture systems. Infrastructure contractors facing tight placement windows are specifying these dual-function chemistries to reduce jobsite complexity. The technology is hybridizing formerly separate product categories, compressing revenue pools for standalone viscosity modifiers.
ASTM C494 Type F and G classification updates are tightening performance verification protocols for high-range water reducers. The revised standards are forcing reformulation of legacy polycarboxylate ether products to demonstrate extended slump retention under standardized test conditions. Precast concrete producers in the US Southeast are responding by consolidating supplier relationships toward laboratories with certified ASTM testing capabilities.
Specification authority is migrating from ready-mix producers to engineering firms and owner-agencies with centralized mix design control. Large infrastructure general contractors are deploying proprietary concrete performance specifications that override traditional ACI 318 defaults, compressing admixture selection to pre-approved supplier lists. The shift is most visible in Texas and California megaprojects where design-build delivery concentrates procurement decision-making.
North America Concrete Superplasticizer Market Segmentation
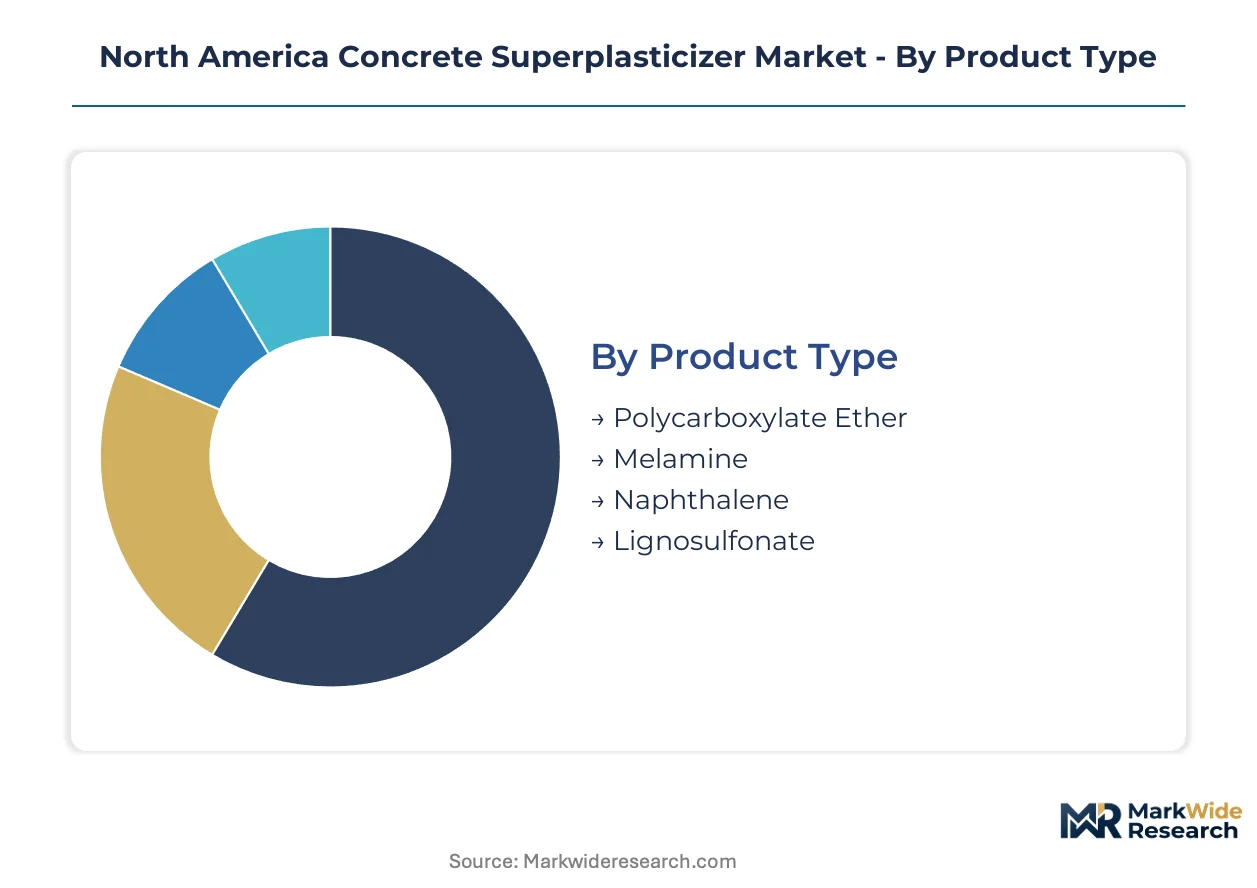
Concrete superplasticizer procurement patterns diverge sharply across formulation chemistry, placement method, and project scale. Specification authority migrates differently through each segmentation axis, creating distinct competitive arenas for admixture suppliers.
Product Type:
After-sales service intensity escalates with formulation complexity, as polycarboxylate ether systems require cement compatibility testing and batch plant calibration support that legacy chemistries do not.
- Polycarboxylate Ether:Molecular architecture with grafted side chains enables slump retention exceeding two hours and water reduction above 30%. Demand concentrates in Texas and California megaprojects where design-build contractors specify proprietary performance criteria. EPA durability standards compressing water-to-cement ratios force specification upgrades from older chemistries.
- Naphthalene:Sulfonated condensate chemistry delivers cost-effective water reduction for standard ready-mix applications with less sensitivity to cement alkalinity variation. Cost-sensitive producers in price-competitive Midwest markets revert to this legacy technology despite performance tradeoffs against polycarboxylate ether systems.
- Melamine:Formaldehyde-based superplasticizer retains niche specification in precast concrete where rapid early strength development overrides extended slump retention requirements.
- Lignosulfonate:Byproduct of wood pulping processes serves as low-cost water reducer in non-critical residential flatwork with minimal technical service requirements.
Polycarboxylate ether holds the largest share; momentum sits with high-performance concrete specification migration.
Application:
Placement method determines dosing precision requirements and drives supplier selection toward laboratories with certified ASTM C494 testing capabilities.
- Self-Consolidating Concrete:Flowable mixes achieving 650mm+ spread without segregation demand polycarboxylate ether with tailored viscosity-modifying side chains. Complex architectural formwork in Toronto and Vancouver commercial towers proliferates specification for slump-retaining formulations that reduce jobsite labor.
- Ready-Mix Concrete:Volume-driven segment serving residential foundations and standard commercial slabs prioritizes cost efficiency over extended performance windows. Gulf Coast petrochemical corridor supply concentration enables competitive pricing for high-volume contractors.
- Precast Concrete:Controlled factory environments permit precise admixture dosing for rapid form turnover and consistent surface finish quality.
- High-Performance Concrete:Federal bridge rehabilitation programs specify 100-year service life targets requiring low permeability achieved through advanced water reducer chemistry.
Ready-mix concrete dominates volume; self-consolidating concrete is climbing the fastest as complex formwork proliferates.
Distribution Channel:
Channel selection reflects customer scale and technical support requirements, with large infrastructure contractors consolidating procurement through direct manufacturer relationships.
- Direct Sales:Technical specification support and cement compatibility testing bundled with bulk supply contracts. Major ready-mix producers in the US Southeast and Ontario maintain dedicated technical service agreements.
- Wholesalers:Regional distribution networks serve fragmented contractors requiring smaller batch quantities with standard lead times.
- Online Sales:Emerging channel for documented small-project procurement with transparent pricing and specification sheets.
- Retail Stores:Limited to lignosulfonate and basic naphthalene products for residential contractor spot purchases.
Direct sales commands premium specification; online channels are gaining share fastest among mid-tier contractors.
End User:
Customer type segmentation separates specification complexity, infrastructure durability mandates, and price sensitivity thresholds.
- Infrastructure:Federal and state transportation agencies specify ASTM C494 Type F and G high-range water reducers for bridge decks and highway repair. Buy America provisions steer sourcing toward domestic polycarboxylate ether production.
- Commercial:Architectural concrete and high-rise construction drive self-consolidating concrete specification with rheology-tailored admixture systems.
- Residential:Foundation and flatwork applications prioritize cost minimization over extended performance characteristics.
- Industrial:Manufacturing facility slabs and containment structures specify chemical-resistant concrete with specialized admixture packages.
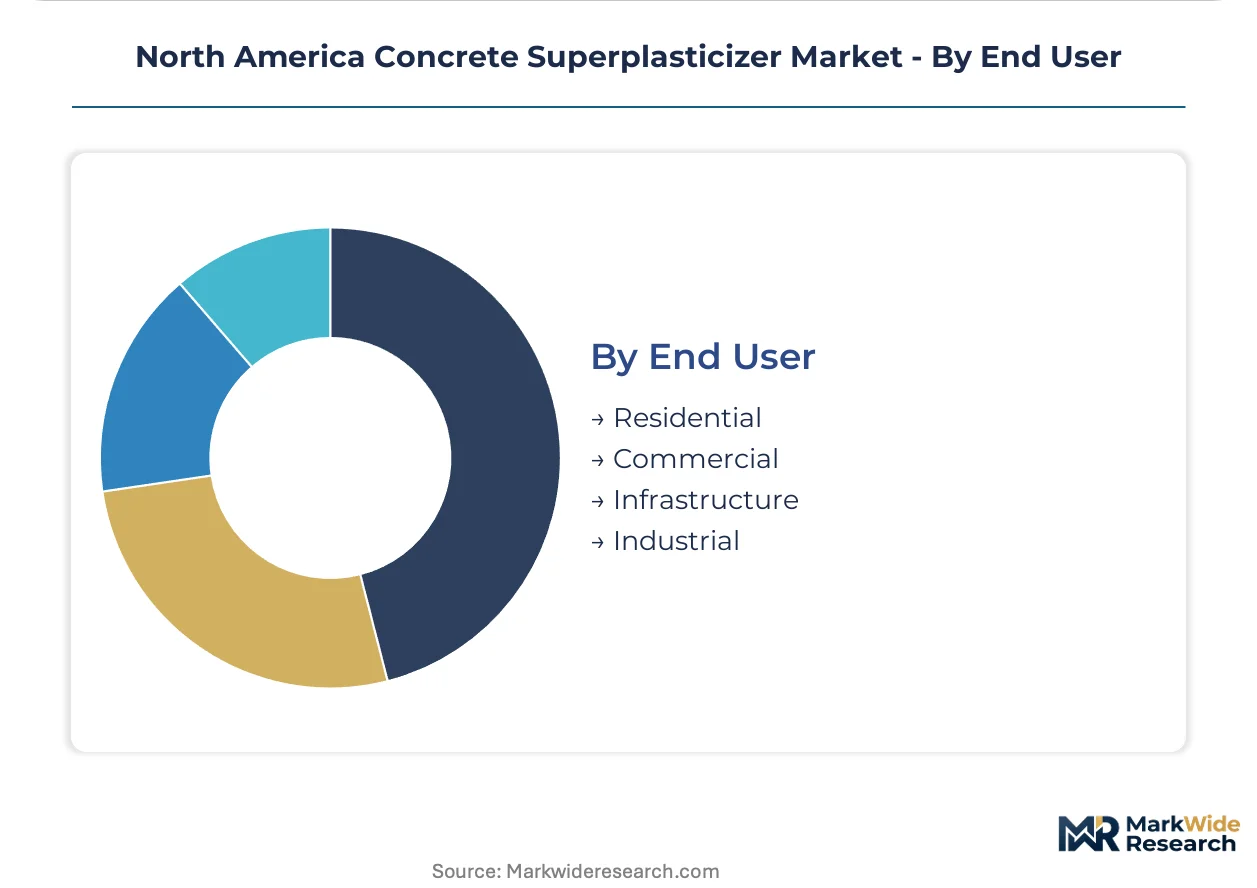
Infrastructure holds the largest share; commercial construction shows steepest expansion trajectory as urban density intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA durability standards anchor specification authority across the United States, while provincial infrastructure programs in Canada and industrial corridor development in Mexico reshape procurement geography for polycarboxylate ether admixtures.
United States
Federal bridge rehabilitation programs and highway repair mandates drive specification migration toward high-performance concrete mixes. The EPA's evolving construction material durability standards compress water-to-cement ratio tolerances, forcing upgrades to advanced superplasticizer chemistry. The US Gulf Coast petrochemical corridor concentrates polycarboxylate ether production capacity, with integrated ethylene oxide derivative operations supplying admixture manufacturers at scale advantages.
Canada
Canada Infrastructure Bank commitments for transit and water treatment accelerate high-performance admixture specification in Ontario and British Columbia. CSA A266.1 requirements shape product qualification protocols across Canadian provinces, creating compliance barriers for non-certified suppliers. Toronto and Vancouver commercial towers proliferate self-consolidating concrete demand for complex architectural formwork applications.
Mexico
Industrial facility construction and manufacturing sector expansion generate steady demand for chemical-resistant concrete admixtures. Federal infrastructure commitments under the National Infrastructure Program specify durability targets requiring imported polycarboxylate ether formulations. The Bajío Region automotive manufacturing cluster drives specification for high-strength concrete in facility slabs and containment structures.
North America Concrete Superplasticizer Market Key Industry Players
Capability concentration sits with integrated petrochemical players possessing captive ethylene oxide derivative supply; scale advantage sits with specialized admixture manufacturers operating distributed technical service networks. The market structures around three tiers: multinational chemical conglomerates with backward integration into polymer feedstocks, regional admixture specialists with certified testing laboratories, and commodity blenders competing on price-sensitive ready-mix segments. Dominant competitive moves include Gulf Coast capacity expansion for polycarboxylate ether production and strategic consolidation of distribution networks serving design-build infrastructure contractors.
Among European-headquartered chemical conglomerates, BASF SE and Evonik Industries AG occupy positions anchored by integrated petrochemicals footprints that sustain cost-advantaged polymer production. Sika AG exemplifies the specialized admixture archetype, with distribution networks concentrated around technical service capabilities for ready-mix concrete producers. These three companies represent the capability-scale spectrum: integrated feedstock control versus specialized formulation expertise versus technical service intensity.
| Leading Market Players |
|---|
| Fosroc, Inc. |
| The Euclid Chemical Company |
| Sika AG |
| Evonik Industries AG |
| Arkema |
| BASF SE |
| GCP Applied Technologies Inc. |
| Kao Corporation |
| MAPEI S.p.A. |
| Others |
Cost & Logistics Intelligence
Ethylene oxide feedstock concentration along the US Gulf Coast determines both pricing tier spreads and supply chain shape, as integrated petrochemical complexes wield cost advantages that distributed blending operations cannot match while cement alkalinity sensitivity constrains reliable performance across diverse regional cement sources.
Pricing Analysis
Texas and California megaprojects command premium pricing for polycarboxylate ether formulations with tailored molecular architecture, while cost-sensitive Midwest ready-mix producers revert to sulfonated naphthalene condensates despite performance tradeoffs. Price differentiation rests on certification level—ASTM C494 Type F and G compliance—and volume scale, with bulk supply contracts bundling technical service support. Cost compression in standard ready-mix segments is intensifying because Gulf Coast petrochemical corridor capacity expansion enables competitive pricing for high-volume contractors. Infrastructure contractors facing tight placement windows show least price sensitivity, whereas residential flatwork applications prioritize economy over extended performance characteristics.
Supply Chain Analysis
Integrated petrochemical manufacturers along the US Gulf Coast hold captive ethylene oxide derivative capacity, converting feedstock into polycarboxylate ether polymers at scale advantages unreachable by commodity blenders. Raw material dependencies center on ethylene oxide derivatives, sulfonated naphthalene intermediates, and formaldehyde-based melamine precursors. Single-source vulnerability propagates rapidly through polycarboxylate ether supply chains when Gulf Coast disruptions occur, as no alternative production cluster matches the integrated cost structure. Distribution runs through direct sales channels for major ready-mix producers with dedicated technical service agreements, while regional wholesalers serve fragmented contractors requiring smaller batch quantities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sulfonated naphthalene substitution pressure represents the core substitution threat that polycarboxylate ether incumbents must navigate, as cost-sensitive ready-mix segments revert to legacy chemistry despite inferior slump retention and water reduction performance.
For Market Incumbents: Build certification moats around ASTM C494 Type F and G testing capabilities, locking in pre-approved supplier status with infrastructure general contractors deploying proprietary concrete performance specifications. Consolidate supplier relationships with precast concrete producers in the US Southeast who demand certified laboratory capabilities. Capacity addition in the Canadian market—specifically Ontario and British Columbia—captures Canada Infrastructure Bank transit and water treatment commitments before regional specialists entrench.
For New Entrants and Emerging Players: Establish a beachhead in 3D-printed concrete construction, where layered deposition robotics require rheology-tailored superplasticizer systems with precise thixotropic control and no entrenched supplier relationships exist. Target the Canadian infrastructure stimulus corridor, where federal transit commitments accelerate specification migration toward high-performance admixtures. Lead with Buy America compliance advisory services, creating certification revenue streams that bypass commodity admixture margin compression.
For Investors and Strategic Acquirers: EPA durability standard evolution reshapes the acquisition landscape by compressing water-to-cement ratio tolerances and forcing specification upgrades toward high-range water reducers. Long-term viability favors integrated petrochemical players with captive ethylene oxide derivative supply over distributed commodity blenders. The signal to watch is state-level Buy America provision enforcement intensity, as domestic content verification creates structural advantages for US Gulf Coast production assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide Derivatives | Gulf Coast petrochemical corridor integration secures cost-advantaged polycarboxylate ether feedstock supply. |
| ASTM C494 Testing Laboratory Certification | Certified capabilities lock in pre-approved supplier status with infrastructure design-build contractors. |
| Canadian Distribution Network Expansion | Ontario and British Columbia infrastructure stimulus accelerates high-performance admixture specification migration. |
| Buy America Compliance Service Launch | Domestic content verification creates advisory revenue beyond commodity admixture sales. |
| 3D-Printed Concrete Formulation Development | Thixotropic control specialization opens white space in layered deposition robotics applications. |
Research Approach
A spread of perspectives from admixture plant managers, ready-mix concrete procurement leads, infrastructure contractor technical directors, and cement compatibility testing laboratory heads converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, American Concrete Institute technical bulletins, EPA construction material durability guidance documents, and SEC 10-K filings of listed chemical conglomerates. Bottom-up volume estimates from individual production facility outputs and top-down demand assessments from infrastructure project pipelines were triangulated to establish market sizing.
Demand-supply balance dynamics across the analysis window anchored the forecast framework, with segmentation dimensions spanning formulation chemistry grade tier, placement method application, project scale end-use, and regional production hub. CAGRs were derived from modeled annual volume trajectories adjusted for specification migration rates and infrastructure spending patterns. Key inputs included federal bridge rehabilitation program commitments, commercial construction formwork complexity indices, and polycarboxylate ether production capacity utilization rates along the Gulf Coast corridor.
Stress conditions across ethylene oxide feedstock price volatility, cement source alkalinity variation, and EPA durability standard implementation timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure stimulus continuation and specification authority migration toward engineering firms. Quarterly review of federal infrastructure appropriations, state-level Buy America enforcement actions, and ASTM C494 standard revision timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Vegetal Concrete Market
Building & Construction Materials
Decorative Concrete Market
Building & Construction Materials
Air Barrier Market
Building & Construction Materials
South Korea Aluminum Door and Window Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Global Aggregates Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Limestone Aggregates Market
Building & Construction Materials
Technical Insulation Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Asia-Pacific Ceramic Sanitary Ware Market
Building & Construction Materials
Waterstop Market
Building & Construction Materials
Insulated Wall Panels Market
Building & Construction Materials
Epoxy Grout Market