
 Rubber Expansion Joints Market | 2026-2036
Rubber Expansion Joints Market Size, Share, and Industry Trends Forecast 2026-2036
Rubber Expansion Joints Market Outlook
Fluoroelastomer compounds is repositioning product economics in high-temperature chemical service, displacing standard EPDM formulations in sulfuric acid and hydrocarbon transfer lines. Garlock Sealing Technologies leverages captive polymer compounding to sustain margin control across severe-service specifications. ContiTech AG anchors European supply through integrated hose-and-joint manufacturing at its Hannover complex. EagleBurgmann Expansion Joint Solutions specializes in nuclear-qualified expansion joints, occupying a defensible niche in power generation retrofit programs.
Rubber expansion joints are flexible elastomeric connectors, typically reinforced with synthetic fabric plies and steel wire rings, designed to absorb thermal expansion, vibration, and misalignment in piping systems operating from minus 40 to 200 degrees Celsius. Their primary industrial purpose is protecting pumps, valves, and fixed piping from mechanical stress in fluid handling infrastructure. Single sphere configurations dominate volume in HVAC and water treatment applications where moderate pressure ratings and cost sensitivity define procurement. Double sphere designs command premium positioning in marine and oil & gas verticals due to superior angular movement absorption and fatigue resistance under cyclic loading.
EPA New Source Performance Standards and REACH chemical compliance frameworks are tightening permissible elastomer leachate thresholds, forcing compound reformulation and third-party certification investments. The EU F-Gas Regulation and associated MEE emissions protocols in China are indirectly shaping demand by accelerating heat exchanger and cooling system replacements that cascade into joint procurement cycles. Stakeholders must monitor evolving polymer substitution economics and pre-qualification testing burdens across divergent regional approval pathways.
Market Dynamics
EPDM-to-fluoroelastomer material substitution is restructuring competitive advantage in high-temperature chemical service, forcing compounders to recalibrate margin models around severe-service certification tiers rather than volume throughput.
Growth Catalysts
- EPA New Source Performance Standards:Tighter emissions protocols for chemical processing infrastructure are accelerating replacement cycles in sulfuric acid transfer lines. Petrochemical operators face mandatory joint upgrades to meet elastomer leachate thresholds.
- Power generation retrofit programs:Nuclear-qualified expansion joint demand is concentrating in Southeast Asia thermal facilities managing thermal cycling stress. Procurement of flexible piping connectors is expanding across regional capacity additions.
- India municipal water treatment:Accelerating infrastructure retrofits and petrochemical capacity additions are compressing joint replacement cycles. State-level treatment plant modernization is driving double-digit volume concentration in this geography.
Market Restraints
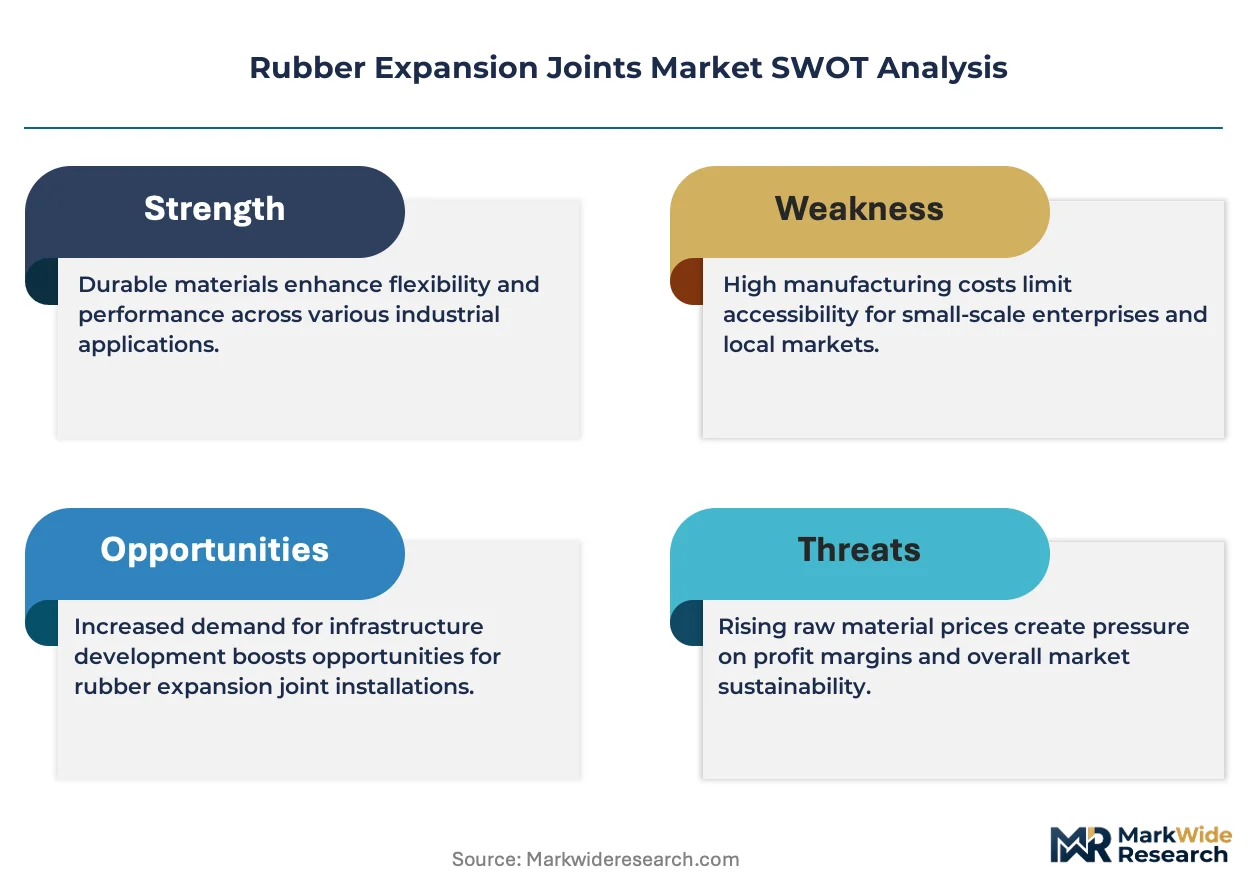
- Raw material volatility:Fluoroelastomer resin prices fluctuate with fluoropolymer feedstock availability, squeezing compounders unable to secure captive polymer supply. EPDM natural rubber substitution offers limited relief in severe-service applications.
- Supply concentration risk:European integrated hose-and-joint manufacturing anchors regional supply through Hannover-complex production. Disruption risks cascade through fabric ply and steel wire ring sourcing networks.
- REACH certification friction:Third-party elastomer leachate testing and reformulation investments extend product qualification timelines. Chemical compliance frameworks impose documentation burdens that favor incumbents with established certification portfolios.
Strategic Opportunities
- Hydrogen economy infrastructure:Emerging hydrogen pipeline and fueling station construction creates demand for cryogenic-compatible expansion joint materials. Material qualification for minus 40 degree Celsius service opens premium specification tiers.
- Carbon capture retrofit wave:Heat exchanger and cooling system replacements under EU F-Gas Regulation and China MEE protocols cascade into joint procurement cycles. Amine handling lines require fluoroelastomer formulations resistant to chemical degradation.
- Digital twin integration:Predictive maintenance platforms are converging with sensor-embedded joint designs to enable condition-based replacement scheduling. Industrial IoT adoption in water treatment verticals creates service revenue attachment opportunities.
Industry Challenges
- Polymer compounding expertise scarcity:Qualified formulators capable of severe-service compound development command premium compensation. Talent pipelines struggle to match demand for fluoroelastomer-EPDM hybrid formulations.
- Legacy system integration complexity:Retrofit installations in aging chemical processing plants require custom angular movement calculations. Dimensional mismatch between existing piping and standardized joint geometries extends field engineering timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rubber Expansion Joints Market |
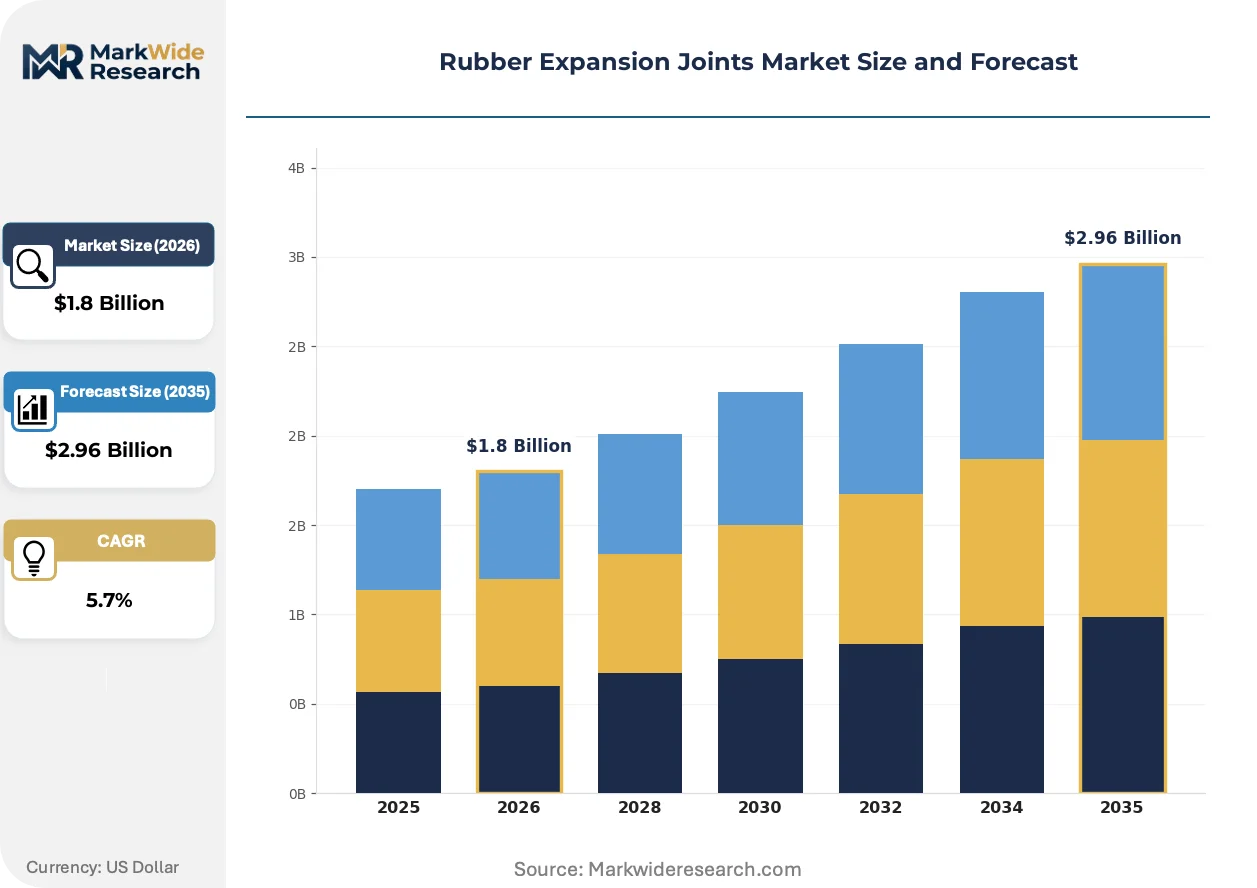
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single Sphere, Double Sphere, Universal, Conical Application: Piping Systems, Ventilation, Chemical Plants, Power Generation Industry Vertical: Oil & Gas, Water Treatment, HVAC, Marine Size: Small, Medium, Large, Custom |
| Companies Covered | Garlock Sealing Technologies, Eaton Corporation, ContiTech AG, Belman A/S, CRP Industrial, EagleBurgmann Expansion Joint Solutions, Flexider Group, TOZEN Group, Proco Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rubber Expansion Joints Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine product architecture, with digital instrumentation and predictive service models emerging as parallel innovation vectors.
Multi-layer fluoroelastomer-EPDM hybrid compounds are decentralizing the traditional single-material specification hierarchy in chemical processing infrastructure. Refinery operators and sulfuric acid producers are adopting these formulations at accelerating pace to bridge cost-performance gaps. The technology is decentralizing procurement authority from central engineering teams to site-level reliability engineers who specify by operational severity rather than capital project budget.
REACH chemical compliance frameworks and EPA emissions protocols are tightening permissible elastomer leachate thresholds across divergent regional approval pathways. Compound reformulation investments and third-party certification burdens are compressing margin structures for non-integrated manufacturers. Chemical processing and power generation verticals are responding by consolidating supplier relationships around pre-qualified severe-service portfolios.
Specification-driven procurement consolidation is compressing vendor panels in municipal water treatment and petrochemical end-uses. Engineering-procurement-construction firms are displacing fragmented distributor networks as primary specification gatekeepers. India and Southeast Asia project markets exhibit the most pronounced channel concentration, with integrated solution providers capturing joint procurement bundled within larger piping system contracts.
Rubber Expansion Joints Market Segmentation
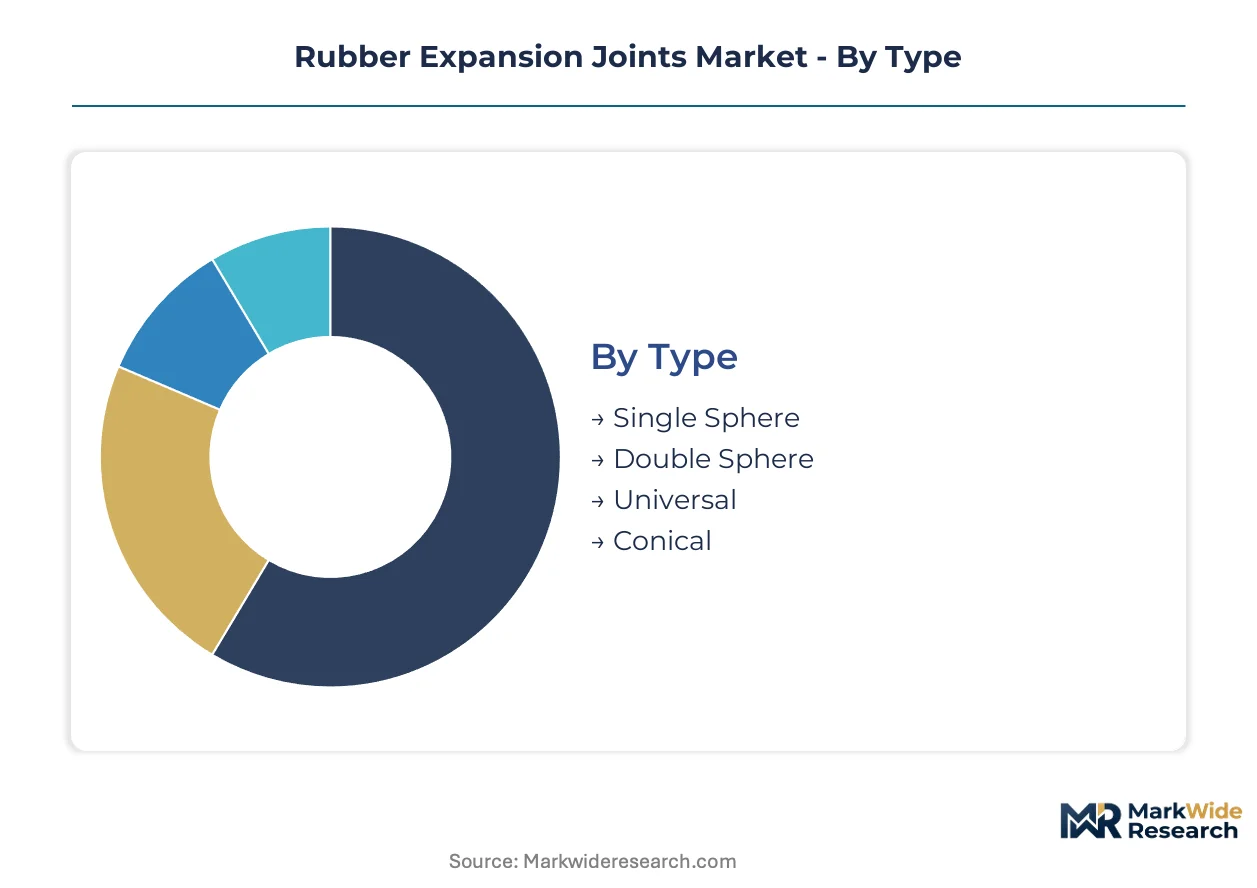
Rubber expansion joint specifications diverge sharply based on thermal cycling severity and angular movement requirements. Procurement patterns cluster around installation complexity, with standalone replacements dominating maintenance budgets while embedded system integrations capture new construction flows.
Type:
Integration depth separates single sphere units—typically procured as standalone maintenance items—from universal and conical designs embedded in complex piping arrays requiring field-engineered fitment.
- Single Sphere:These units incorporate synthetic fabric plies and steel wire rings within an elastomeric body rated for moderate pressure service. Demand concentrates in India municipal water treatment retrofits where cost sensitivity and standardized flange dimensions dominate procurement specifications. State-level plant modernization programs compress replacement cycles for these volume configurations.
- Double Sphere:Dual-architecture designs deliver superior angular movement absorption through tandem elastomeric chambers separated by a reinforcing collar. Marine and oil & gas verticals in Southeast Asia specify these for cyclic loading environments where fatigue resistance justifies premium positioning. Offshore platform piping retrofits drive specification authority toward reliability engineers rather than central procurement.
- Universal:Multi-plane movement capability suits these units for embedded installation in aging chemical processing infrastructure where legacy dimensional constraints require custom angular calculations.
- Conical:Tapered geometry accommodates misalignment in space-constrained ventilation and exhaust systems where straight-run piping is impractical.
Volume placements concentrate in Single Sphere; the faster expansion belongs to Double Sphere.
Application:
Cost tier differentiation separates commodity piping system replacements from premium specifications in chemical and power generation environments where severe-service certification commands pricing power.
- Piping Systems:The foundational application category spans HVAC, water distribution, and industrial process lines with standardized pressure-temperature ratings. India and Southeast Asia infrastructure investments channel volume through distributor networks serving maintenance-repair-operations procurement.
- Ventilation:Lower pressure specifications and ambient temperature service define this tier, with EPDM formulations dominating where chemical resistance requirements are minimal.
- Chemical Plants:Fluoroelastomer-EPDM hybrid compounds are gaining specification share in sulfuric acid and hydrocarbon transfer lines. EPA emissions protocols and REACH leachate thresholds force compound reformulation investments that favor integrated manufacturers with captive polymer compounding.
- Power Generation:Nuclear-qualified expansion joints occupy a defensible niche in thermal facility retrofit programs. Southeast Asia capacity additions concentrate procurement of flexible connectors engineered for thermal cycling stress management.
Standardized Piping Systems capture the highest unit volumes; Chemical Plants demonstrate the steepest expansion trajectory as regulatory compliance accelerates replacement cycles.
Industry Vertical:
Customer type segmentation reveals divergent procurement authority patterns, with engineering-procurement-construction firms displacing distributors in integrated project markets while maintenance verticals retain fragmented sourcing.
- Oil & Gas:Severe-service specifications dominate this vertical, with fluoroelastomer formulations resistant to amine degradation in carbon capture retrofits. EU F-Gas Regulation and China MEE protocols cascade joint procurement through heat exchanger replacement cycles.
- Water Treatment:Municipal retrofits in India compress replacement cycles for single sphere configurations. State-level infrastructure programs concentrate volume in integrated solution providers bundling joints within larger piping system contracts.
- HVAC:Building automation integration and moderate pressure ratings define this commercial construction vertical.
- Marine:Double sphere designs command specification authority for fatigue resistance under cyclic loading in offshore and shipboard applications.
Water Treatment absorbs the greatest unit placements; Oil & Gas climbs the fastest on carbon capture and hydrogen economy infrastructure development.
Size:
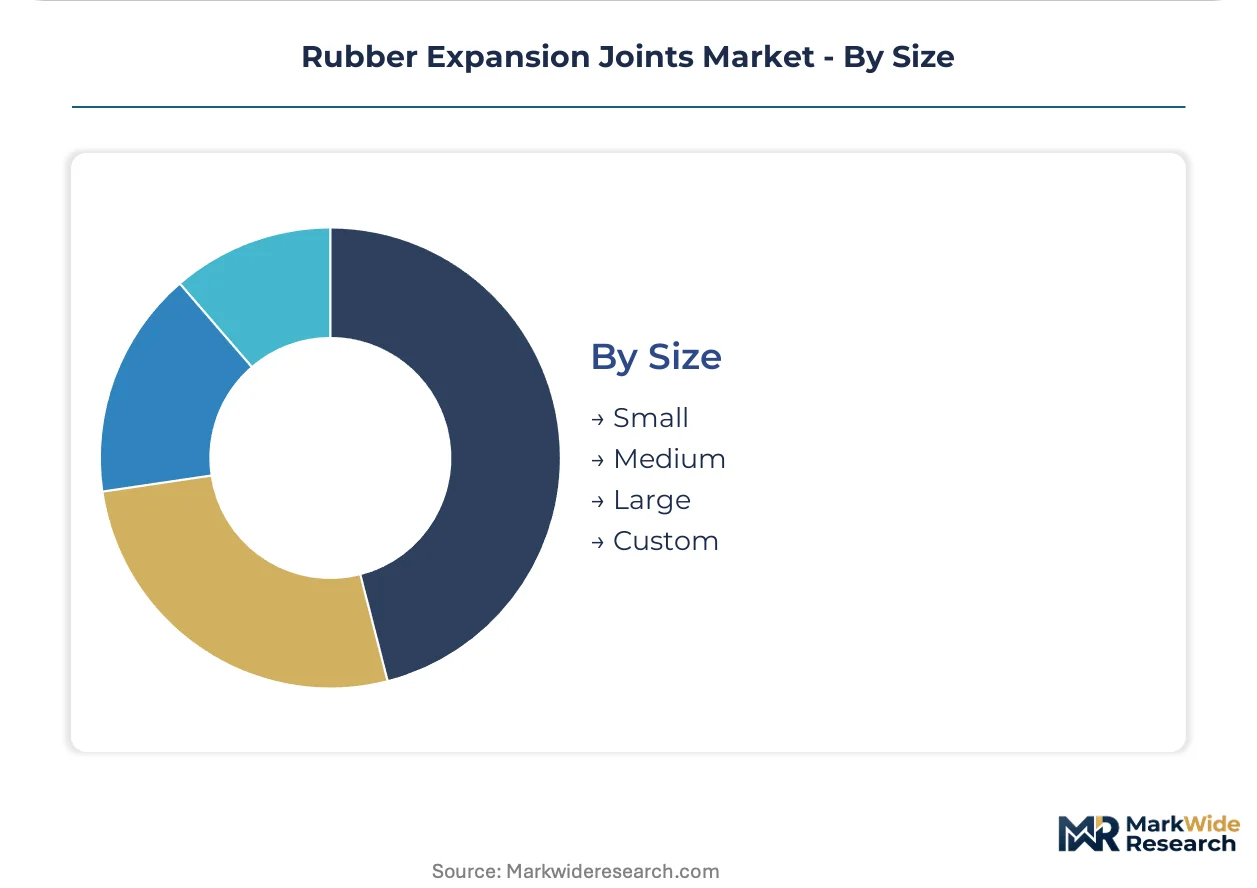
Supply concentration patterns differentiate standardized small and medium units from large and custom segments requiring application engineering and extended qualification timelines.
- Small:Dimensional standardization enables distributor inventory models and rapid replacement procurement in HVAC and light industrial maintenance.
- Medium:This tier bridges standardized catalog offerings and engineered solutions, capturing volume in municipal water treatment and commercial building systems.
- Large:Custom fabrication and extended lead times characterize these units for power generation and chemical processing infrastructure. ContiTech AG's Hannover complex anchors European supply through integrated hose-and-joint manufacturing.
- Custom:Field measurement and angular movement calculations extend engineering timelines for aging chemical plant retrofits where legacy piping geometry defies standardization.
Medium sizes dominate current placements; Custom configurations are gaining share fastest as infrastructure age and regulatory retrofit requirements intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates procurement volume for rubber expansion joints through municipal water treatment retrofits and petrochemical capacity additions. Southeast Asia power generation facilities are expanding flexible piping connector procurement for thermal cycle management. Regulatory divergence across EPA, REACH, and MEE frameworks is fragmentating certification requirements by geography.
United States
EPA New Source Performance Standards are accelerating replacement cycles in sulfuric acid transfer lines across Texas and Louisiana chemical corridors. Petrochemical operators face mandatory joint upgrades to meet elastomer leachate thresholds. Houston-area refineries are consolidating supplier relationships around pre-qualified severe-service portfolios.
Germany
REACH chemical compliance frameworks are tightening permissible elastomer leachate thresholds for chemical processing infrastructure. The EU F-Gas Regulation is cascading joint procurement through heat exchanger replacement cycles. ContiTech AG's Hannover complex anchors European supply through integrated hose-and-joint manufacturing.
India
State-level water treatment plant modernization programs are compressing replacement cycles for single sphere configurations. BIS certification requirements are extending product qualification timelines for municipal infrastructure tenders. Gujarat and Maharashtra petrochemical clusters are driving double-digit volume concentration through capacity additions.
China
MEE emissions protocols are indirectly shaping demand by accelerating cooling system replacements that cascade into joint procurement cycles. Yangtze River Delta chemical processors are adopting fluoroelastomer-EPDM hybrid compounds for amine handling lines. Shanghai-area infrastructure investments channel volume through engineering-procurement-construction firms.
Japan
METI industrial efficiency standards are driving thermal facility retrofit programs requiring nuclear-qualified expansion joints. Kansai region power generators are specifying flexible connectors engineered for thermal cycling stress management. Osaka-based engineering firms are displacing distributor networks as primary specification gatekeepers.
Rubber Expansion Joints Market Competitive Environment
Capacity expansion dominates the current landscape as compounders recalibrate margin models around severe-service certification tiers. The vendor base stratifies across integrated polymer compounders, specialized expansion joint fabricators, and diversified sealing solution providers. Three archetypes define competitive positioning: captive compounders controlling resin supply, project-integrated solution providers bundling joints within piping contracts, and severe-service specialists occupying nuclear-qualified niches. M&A activity and geographic expansion represent the dominant competitive vectors as stakeholders pursue regional certification portfolios.
Among diversified industrial conglomerates, Eaton Corporation and ContiTech AG exemplify scale-driven positions with integrated manufacturing footprints. Garlock Sealing Technologies occupies a specialist tier focused on captive polymer compounding for severe-service specifications. EagleBurgmann Expansion Joint Solutions represents the nuclear-qualified niche, anchoring defensible positioning in power generation retrofit programs. These three entities collectively illustrate how supply-side capabilities map to divergent certification requirements across EPA, REACH, and MEE regulatory jurisdictions.
| Leading Market Players |
|---|
| Garlock Sealing Technologies |
| Eaton Corporation |
| ContiTech AG |
| Belman A/S |
| CRP Industrial |
| EagleBurgmann Expansion Joint Solutions |
| Flexider Group |
| TOZEN Group |
| Proco Products |
| Others |
Value Chain & Pricing Dynamics
Fluoroelastomer-EPDM hybrid compound transitions are simultaneously elevating certification-driven cost structures and concentrating procurement authority around captive polymer compounders with in-house resin supply. This material shift compresses margin structures for non-integrated manufacturers while rewarding compounders who control upstream polymer formulation.
Pricing Analysis
Volume placements concentrate in standardized single sphere configurations where per-unit transactional pricing dominates municipal water treatment procurement in India. Three-tier pricing structure across severe-service premium, standard EPDM, and economy ventilation tiers differentiates by certification grade and captive compounding capability. Cost compression in standard EPDM tiers is intensifying because Indian state-level tenders prioritize lowest compliant bid. Municipal procurement teams exhibit highest price sensitivity; nuclear-qualified power generation specifications demonstrate lowest.
Supply Chain Analysis
Fluoroelastomer resin supply rests on German and Japanese specialty chemical producers with limited alternative sourcing for severe-service grades. Synthetic fabric ply and steel wire ring inputs draw from Chinese and Indian textile and metalworking clusters. Single-source vulnerability in fluoropolymer feedstock creates cascading disruption risk for compounders lacking captive supply. Distribution runs through engineering-procurement-construction firms displacing fragmented distributor networks in India and Southeast Asia project markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as REACH and EPA certification burdens force sub-scale compounders toward exit or acquisition by integrated manufacturers with established severe-service portfolios.
For Market Incumbents: Anchor defensible positioning through captive polymer compounding investments that lock in margin control across fluoroelastomer-EPDM hybrid formulations. Pursue backward integration into fabric ply manufacturing to reduce dependency on Chinese textile suppliers. Nuclear-qualified certification portfolios and pre-approved supplier status with EPC firms in India and Southeast Asia constitute the priority defensive levers against emerging integrated solution providers. For New Entrants and Emerging Players: The premium-to-economy price-point gap in chemical plant applications creates white-space opportunity for mid-tier hybrid compound specialists. Target municipal water treatment retrofits in Indian states with compressed replacement cycles where distributor relationships remain penetrable. Amine handling line specifications for carbon capture retrofits offer the most accessible entry vector through fluoroelastomer formulation partnerships with established polymer suppliers. For Investors and Strategic Acquirers: Re-rating potential sits with captive compounders possessing severe-service certification portfolios given accelerating EPA and REACH compliance timelines. Long-term viability over the coming decade favors integrated manufacturers with Hannover-complex scale production footprints and established EPC channel relationships. Watch fluoroelastomer resin price volatility as the inflection signal for margin compression among non-integrated compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | Captive resin supply insulates margin structures from fluoropolymer feedstock volatility. |
| Severe-Service Certification Investment | EPA and REACH pre-qualification opens premium specification tiers in chemical processing. |
| EPC Channel Partnership Development | Engineering-procurement-construction relationships displace distributor networks in India project markets. |
| Hydrogen Economy Material Qualification | Cryogenic-compatible formulations capture emerging pipeline and fueling station construction demand. |
| Digital Twin Integration Development | Sensor-embedded joint designs enable predictive maintenance service revenue attachment. |
Study Parameters
Independent corroboration across plant engineers at power generation facilities, procurement leads at Indian municipal water authorities, technical directors at petrochemical operators, and aftermarket service heads at sealing solution distributors underwrites the qualitative findings. Secondary validation draws from EPA emissions protocol filings, REACH certification databases, EPC contract award records, and customs trade data for elastomer compound imports. Bottom-up volume estimates from application-level replacement cycles triangulate against top-down industry spend analysis.
Comparable-period anchoring to historical replacement cycle data from thermal facility retrofit programs and municipal infrastructure investment waves structures the projection horizon. Segmentation modeling spans joint type, application severity, industry vertical procurement authority, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand curves incorporating fluoroelastomer substitution economics and certification timeline compression. Hydrogen pipeline construction forecasts and carbon capture retrofit pipelines constitute industry-specific demand inputs.
Inputs from EPC contract databases and state-level tender announcements were available through the study window; gaps in proprietary compound formulation cost structures introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding regulatory enforcement continuity and resin supply chain stability. A small set of triggers—fluoroelastomer price spikes, REACH threshold tightening, and Indian BIS certification delays—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Japan Cross Laminated Timber (CLT) Market
Building & Construction Materials
Glass Railing System Market
Building & Construction Materials
Ceiling Tiles Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
US Windows Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Asia-Pacific Construction Adhesives Market
Building & Construction Materials
Global Builder Hardware Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Mechanically Fastened Cross-Laminated Timber Market
Building & Construction Materials
Plastic Decking Market
Building & Construction Materials
North America Particle Board Market
Building & Construction Materials
Fiber Cement Rainscreen Panels Market
Building & Construction Materials
Building Vibration Isolation Market