
 Ceiling Cassettes Market | 2026-2036
Ceiling Cassettes Market Size, Share, and Industry Trends Forecast 2026-2036
Ceiling Cassettes Market Outlook
Buyer concentration in the commercial real estate sector is pivoting toward large-scale facility management firms and multinational retail chains that standardize HVAC specifications across portfolios. Daikin Industries leverages its captive compressor manufacturing to control cost structures in premium four-way cassette lines. Mitsubishi Electric sustains technology leadership through proprietary inverter-driven compressor platforms. Carrier Global competes on scale by anchoring its position in North American retrofit channels through distributor-exclusive service networks.
A ceiling cassette is a recessed indoor air handling unit designed for suspended ceiling installation, typically housing a centrifugal fan, heat exchanger coil, and multi-directional air discharge louvers in a compact rectangular chassis measuring 600mm by 600mm to match standard modular tile grids. Its primary commercial purpose is to deliver conditioned air across large open-plan spaces while preserving usable floor area and architectural aesthetics. The four-way cassette category dominates value pools in hospitality and conference applications where uniform air distribution is non-negotiable, while smart system control technology represents the fastest-expanding segment as building automation protocols displace manual thermostats in new commercial construction. Retrofit installation types remain structurally constrained by ceiling void depth limitations in legacy buildings, concentrating margin capture in new-build and full-gut-renovation projects.
The EU Ecodesign Directive and F-Gas Regulation shape refrigerant selection and minimum seasonal efficiency thresholds for products sold across Europe, while the U.S. Department of Energy enforces regional efficiency standards that vary by climate zone and directly determine product eligibility for federal tax incentives under the Inflation Reduction Act. India's Bureau of Energy Efficiency mandates star-labeling for packaged air conditioners, including cassette configurations, creating a compliance gateway for market access in one of the fastest-expanding construction economies. Stakeholders must monitor refrigerant transition timelines and evolving regional efficiency benchmarks to align R&D roadmaps with tightening certification requirements.
Market Dynamics
Refrigerant transition timelines under the EU F-Gas Regulation and comparable efficiency mandates are compressing product development cycles, forcing manufacturers to redesign heat exchanger architectures and compressor platforms simultaneously rather than sequentially.
Growth Catalysts
- EU Ecodesign Directive:Minimum seasonal efficiency thresholds are eliminating sub-par units from distribution channels, redirecting procurement budgets toward certified four-way systems in German and French commercial construction.
- Infrastructure build-out:Tier-two Indian cities are accelerating hospitality and retail deployments as domestic capital flows into mixed-use developments requiring concealed climate control.
- Smart building protocols:BACnet and Modbus integration is displacing standalone thermostats in new Southeast Asian office towers, embedding cassettes within centralized automation frameworks.
Market Restraints
- Copper and aluminum volatility:Heat exchanger coil costs fluctuate with London Metal Exchange pricing, compressing margin visibility for manufacturers without captive metal hedging.
- Ceiling void depth:Legacy European and North American buildings constructed before 1990 lack the 250mm minimum plenum space required for standard cassette chassis, structurally excluding retrofit penetration.
- Split-system substitution:Wall-mounted ductless units from Chinese manufacturers compete on installed cost in price-sensitive Southeast Asian residential-adjacent commercial segments.
Strategic Opportunities
- India's Bureau of Energy Efficiency star-labeling:Compliance gateways for packaged air conditioners create first-mover positioning for manufacturers achieving four-star ratings ahead of 2026 enforcement tightening.
- Healthcare ventilation:Hospital outpatient wings and diagnostic centers in Brazil and Mexico are specifying cassettes with HEPA-grade filtration modules as permanent infrastructure rather than temporary pandemic response.
- Direct-to-facility-manager digital channels:Large-scale property management platforms in Australia are consolidating HVAC specification authority, enabling bypass of traditional distributor networks for standardized portfolio rollouts.
Industry Challenges
- Refrigerant handling certification:Technician licensing requirements for R-32 and low-GWP alternatives are tightening across multiple jurisdictions, constraining installation capacity during peak construction seasons.
- Legacy building management system integration:Proprietary control protocols from 1990s-era automation vendors resist standard API connectivity, requiring custom middleware development for smart cassette deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceiling Cassettes Market |
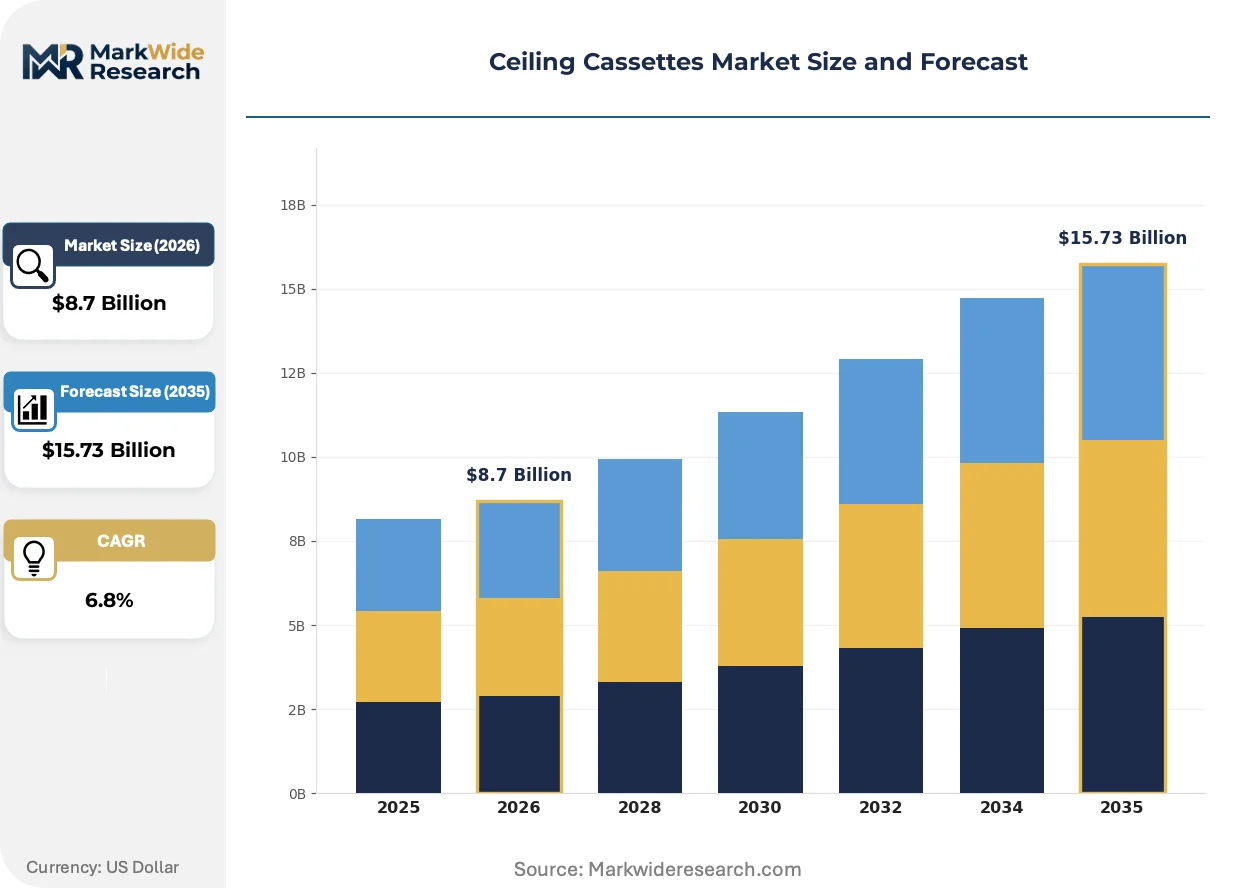
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1-Way Cassette, 2-Way Cassette, 3-Way Cassette, 4-Way Cassette End User: Residential, Commercial, Industrial, Hospitality Installation Type: New Installation, Retrofit, Replacement, Upgrade Control Technology: Manual, Remote Control, Smart System, Centralized Control |
| Companies Covered | Daikin Industries, Ltd., Mitsubishi Electric Corporation, LG Electronics Inc., Samsung Electronics Co., Ltd., Carrier Global Corporation, Panasonic Corporation, Fujitsu General Limited, Gree Electric Appliances Inc., Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceiling Cassettes Market Strategic Shifts
Climate-control hardware is converging with building intelligence layers, transforming cassettes from passive terminal units into data-generating nodes within energy optimization networks.
Variable refrigerant flow sensors paired with AI-driven damper control are rewriting how airflow balancing operates in open-plan environments. Facility managers in Singapore and Dubai are deploying these systems in headquarters relocations where thermal zoning precision affects lease valuations. The technology is rewriting the traditional split between HVAC mechanical contractors and controls specialists, compressing two procurement categories into single-source specifications.
The EU F-Gas Regulation's phasedown schedule is accelerating refrigerant transitions from R-410A to R-32 and HFO blends across European manufacturing footprints. Compressor platforms must be validated for flammability handling and pressure envelope compatibility, extending product development timelines by 18-24 months. Commercial office developers in Germany and the Netherlands are responding by front-loading procurement decisions to lock in compliant equipment availability ahead of 2027 supply constraints.
Consolidated procurement by multinational retail chains is concentrating specification authority at headquarters level rather than regional facilities teams. Standardized HVAC templates across hundreds of locations are displacing site-by-site engineering discretion in new store construction programs. This concentration is most visible in quick-service restaurant and big-box retail rollouts across India and Southeast Asia, where parent companies mandate uniform cassette configurations to simplify maintenance training and spare parts inventory.
Ceiling Cassettes Market Segmentation
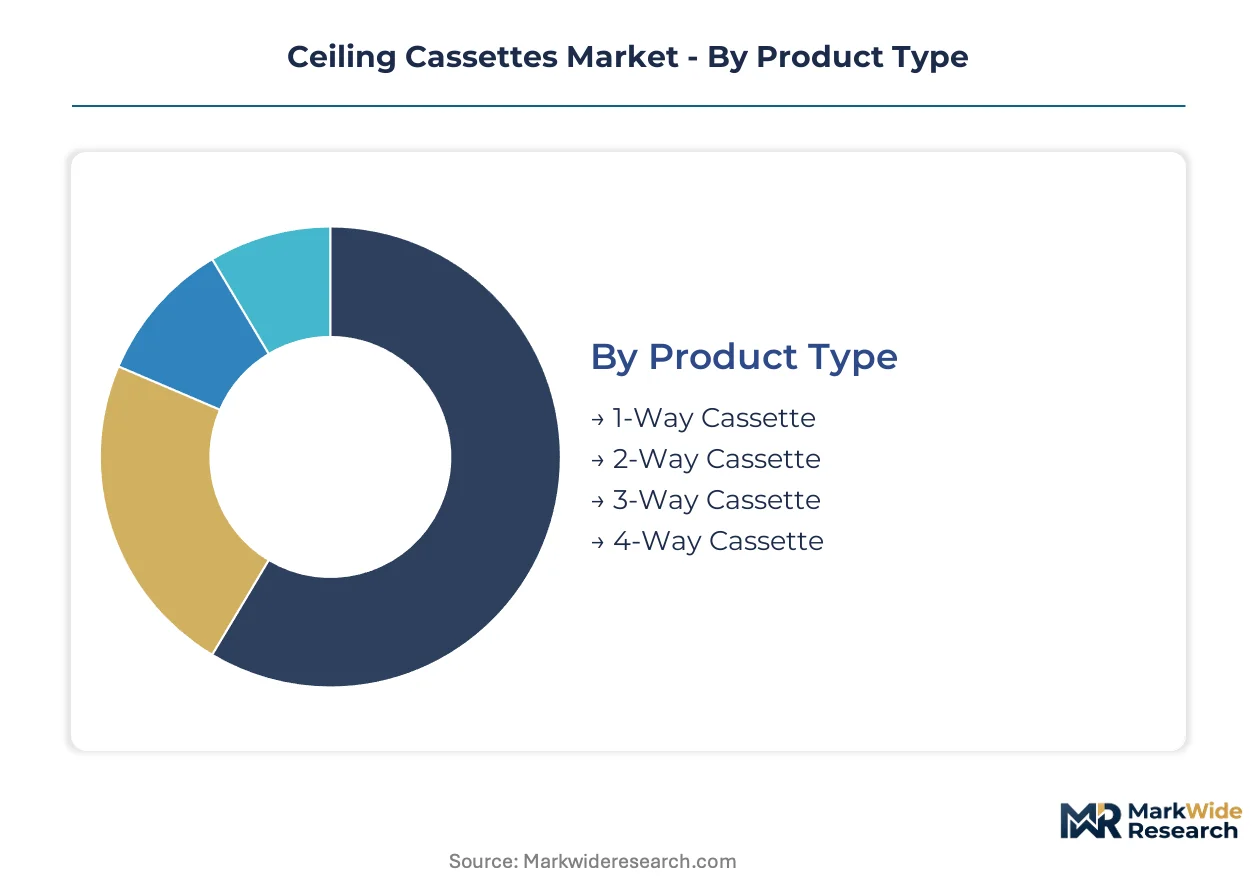
Ceiling cassette procurement decisions pivot on airflow geometry, building lifecycle stage, and automation integration depth. Specification authority increasingly rests with facility managers who standardize across portfolios rather than project engineers optimizing single installations.
Product Type:
Upgrade cycles favor units that deliver superior air distribution without ceiling grid modifications, compressing replacement timelines in premium commercial segments.
- 4-Way Cassette:Delivers conditioned air through four independently adjustable discharge louvers arranged around a central chassis, enabling uniform temperature distribution across irregular floor plates. Demand concentrates in Indian hospitality developments and Southeast Asian conference facilities where architectural flexibility commands lease premiums. EU Ecodesign Directive efficiency thresholds are eliminating non-compliant units from German and French specification lists.
- 1-Way Cassette:Single-direction discharge suits perimeter zones and corridor applications where linear airflow patterns align with building geometry. Japanese commercial retrofits specify these units where ceiling void depth restricts larger chassis.
- 2-Way Cassette:Dual-opposing discharge louvers serve narrow open-plan layouts common in Brazilian and Mexican retail banking branches.
- 3-Way Cassette:Tri-directional configurations occupy niche positions in L-shaped floor plans and angular atrium spaces.
Volume placements concentrate in 4-way configurations; the faster expansion belongs to 2-way units as cost-conscious Southeast Asian retail chains standardize on simpler geometries.
End User:
Customer procurement scale determines specification complexity, with multinational portfolios driving standardization that eliminates site-by-site engineering discretion.
- Commercial:Encompasses office towers, retail banking, and co-working spaces where lease valuations depend on thermal comfort metrics. Tier-two Indian cities are accelerating mixed-use developments requiring concealed climate control systems. Australia's large-scale facility management platforms are consolidating HVAC authority at portfolio level.
- Hospitality:Hotels and conference centers demand four-way airflow uniformity to prevent guest complaints about thermal stratification. Southeast Asian commercial office developers are expanding adoption of premium cassette lines in flagship properties.
- Residential:High-end apartments and serviced residences specify compact cassettes for aesthetic integration with suspended ceiling designs.
- Industrial:Manufacturing floor applications favor robust chassis designs tolerating dust load and vibration exposure.
Commercial segment captures the dominant placement volume; hospitality is climbing the fastest as India's infrastructure build-out accelerates.
Installation Type:
Building age distribution across target geographies creates divergent opportunity windows for new-build versus renovation channels.
- New Installation:Full-gut construction enables optimal ceiling void engineering for standard 250mm chassis depths. German and Dutch developers are front-loading procurement to secure F-Gas-compliant equipment availability.
- Retrofit:Legacy European and North American buildings constructed before 1990 lack minimum plenum space, structurally constraining penetration. Singapore and Dubai headquarters relocations are driving replacement demand in premium commercial segments.
- Replacement:End-of-life swaps in existing ceiling grids favor dimensionally identical units to minimize tenant disruption.
- Upgrade:Performance enhancement installations pair new cassettes with smart control retrofits in buildings with adequate infrastructure.
New installation commands the dominant share; upgrade activity is expanding most quickly as building automation protocol integration displaces manual thermostats.
Control Technology:
Intelligence layer integration is compressing procurement timelines as facility managers demand single-source accountability for mechanical and controls performance.
- Smart System:BACnet and Modbus integration embeds cassettes within centralized energy optimization networks, generating operational data for predictive maintenance. Variable refrigerant flow sensors paired with AI-driven damper control are rewriting airflow balancing in Singapore and Dubai headquarters projects.
- Centralized Control:Building management system integration serves large single-tenant properties with dedicated engineering staff.
- Remote Control:Infrared and RF handheld units persist in smaller commercial installations without automation infrastructure.
- Manual:Thermostat-only control is retreating to budget-constrained residential-adjacent segments.
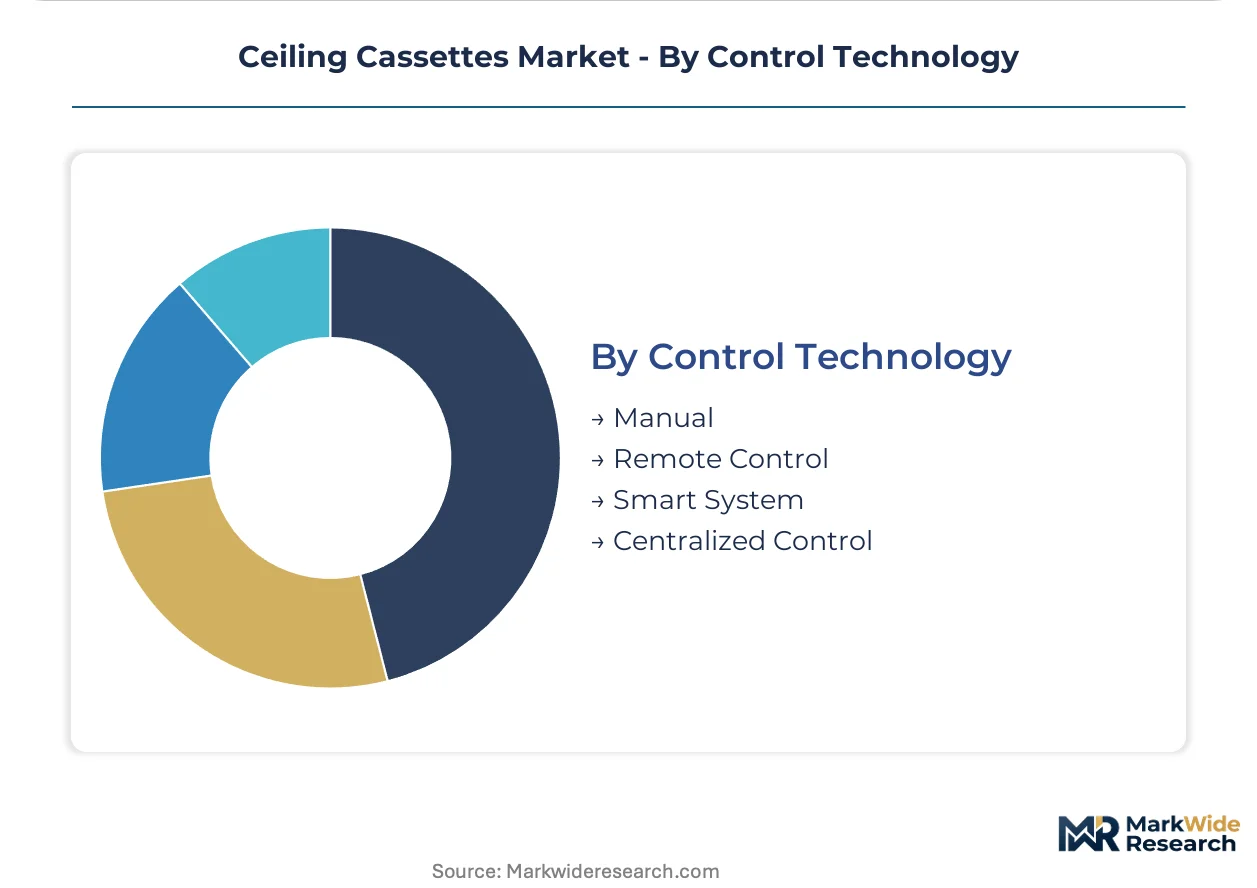
Smart system configurations are gaining share fastest; manual control persists only where capital constraints override efficiency priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in India, where infrastructure build-out in tier-two cities accelerates hospitality and retail deployments. Southeast Asian commercial office developers expand four-way airflow adoption. European efficiency mandates reshape certification requirements.
India
Tier-two cities accelerate mixed-use developments requiring concealed climate control systems. The Bureau of Energy Efficiency mandates star-labeling for packaged air conditioners, creating compliance gateways for market access. Mumbai and Bangalore clusters drive premium cassette specifications in flagship hospitality properties.
Germany
Commercial office developers front-load procurement decisions to lock in F-Gas-compliant equipment availability. The EU Ecodesign Directive eliminates sub-par units from distribution channels, redirecting budgets toward certified four-way systems. Frankfurt and Munich construction markets specify premium cassette lines in new-build commercial towers.
United States
Regional efficiency standards vary by climate zone and determine product eligibility for federal tax incentives under the Inflation Reduction Act. The Department of Energy enforces these thresholds through certification programs. Retrofit channels concentrate in distributor-exclusive service networks across major metropolitan construction corridors.
Singapore
Headquarters relocations drive replacement demand in premium commercial segments with thermal zoning precision affecting lease valuations. BACnet and Modbus integration displaces standalone thermostats in new office towers. The CBD and Marina Bay clusters embed cassettes within centralized automation frameworks.
United Arab Emirates
Dubai facility managers deploy variable refrigerant flow sensors paired with AI-driven damper control in flagship properties. Smart building protocols compress procurement timelines as controls and mechanical categories merge. Downtown Dubai and Business Bay districts standardize on four-way configurations for uniform air distribution.
Ceiling Cassettes Market Competitive Environment
Japanese producers anchor one tier; South Korean and Chinese specialists hold cost-competitive positions in volume segments. The vendor base organizes around three strategic archetypes: integrated compressor manufacturers controlling upstream cost structures, inverter technology specialists, and scale-driven distributors anchoring retrofit channels. Capacity expansion and captive supply of critical components represent dominant competitive moves.
Within the integrated manufacturing tier, Daikin Industries and Mitsubishi Electric exemplify archetypes of upstream control and technology leadership respectively. LG Electronics occupies a position bridging premium specification and volume scale. Carrier Global anchors the North American retrofit channel through service network density. Gree Electric Appliances sits within the cost-optimized volume tier serving price-sensitive segments.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Mitsubishi Electric Corporation |
| LG Electronics Inc. |
| Samsung Electronics Co., Ltd. |
| Carrier Global Corporation |
| Panasonic Corporation |
| Fujitsu General Limited |
| Gree Electric Appliances Inc. |
| Johnson Controls International plc |
| Others |
Value Chain & Pricing Dynamics
Copper and aluminum coil costs feed directly from London Metal Exchange volatility into manufacturer margin structures, compressing visibility for producers lacking captive metal hedging while forcing three-tier pricing stratification across premium inverter-driven platforms, standard efficiency-certified units, and economy configurations serving price-sensitive Southeast Asian retail chains.
Pricing Analysis
Volume placements concentrate in economy-tier standard chassis configurations while margin capture clusters in premium four-way systems with smart control integration. Price differentiation rests on EU Ecodesign certification status and inverter technology tier, with German and French procurement budgets redirecting toward certified four-way lines. Pricing pressure stems from Chinese wall-mounted ductless substitution in Southeast Asian residential-adjacent commercial segments. Facility management platforms in Australia exhibit lowest price sensitivity as they standardize across portfolios, while independent retail banking branches in Brazil and Mexico remain most cost-constrained.
Supply Chain Analysis
Freight cost fluctuations from Asia-Pacific manufacturing hubs to European distribution centers are compressing landed cost predictability for non-integrated manufacturers. Production concentrates in Japan, South Korea, and China, with compressor platforms and heat exchanger coils drawing from captive foundries or specialized component suppliers. Single-source vulnerability sits with R-32 refrigerant handling certification bottlenecks constraining installation capacity. Distribution runs through distributor-exclusive service networks in North American retrofit channels and direct-to-facility-manager digital platforms in Australian commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where R-32 refrigerant handling certification bottlenecks prop pricing power for qualified installation networks and compressor-validated manufacturers.
For Market Incumbents: Anticipate F-Gas Regulation phasedown acceleration by locking in R-32 and low-GWP alternative compressor platform validation ahead of competitor timelines. Defensive consolidation through captive heat exchanger coil manufacturing insulates margin structures from London Metal Exchange volatility. Channel control investments in facility management platform relationships secure specification authority bypassing traditional distributor networks. For New Entrants and Emerging Players: Facility management platforms consolidating HVAC specification authority in Australia represent the most penetrable channel archetype. White-space targets concentrate in tier-two Indian city mixed-use developments requiring Bureau of Energy Efficiency four-star compliance ahead of enforcement tightening. Healthcare ventilation modules with HEPA-grade filtration for Brazilian and Mexican outpatient wings offer specialized entry positioning. Go-to-market execution should anchor on direct digital engagement with property management platforms rather than distributor network buildout. For Investors and Strategic Acquirers: Front-loaded procurement decisions by German and Dutch developers locking in F-Gas-compliant equipment availability are the leading indicator that compressor-validated manufacturing capacity commands scarcity premiums. Long-term viability over the projection horizon favors integrated producers with captive component supply and certified refrigerant handling networks. Acquisition target archetypes include regional specialists with Bureau of Energy Efficiency star-labeling achievements in India and smart control protocol integration capabilities in Southeast Asia. Watch for technician licensing requirement tightening across multiple jurisdictions as the inflection signal constraining effective supply expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Validation | R-32 and low-GWP compressor certification extends development timelines 18-24 months for EU F-Gas compliance. |
| Captive Heat Exchanger Manufacturing | Backward integration into copper and aluminum coil production insulates margins from London Metal Exchange volatility. |
| Smart Control Protocol Integration | BACnet and Modbus embedding transforms cassettes into data-generating nodes within building automation networks. |
| Facility Management Platform Partnership | Direct digital channels bypass traditional distributor networks for standardized portfolio rollouts in Australia. |
| Bureau of Energy Efficiency Certification Investment | Four-star rating achievement ahead of 2026 enforcement tightening creates compliance gateway for Indian market access. |
Study Parameters
Document review covered regulatory filings from the EU Ecodesign Directive and F-Gas Regulation, Bureau of Energy Efficiency star-labeling databases, and Inflation Reduction Act tax incentive eligibility frameworks, complemented by interviews with HVAC procurement directors at multinational retail chains, compressor platform engineering leads, facility management platform technology officers, and commercial real estate developers across Southeast Asian markets. Secondary validation drew from customs and trade flow data, SEC 10-K disclosures from listed manufacturers, and building automation protocol standard documentation. Bottom-up unit placement estimates triangulated against top-down construction spend allocation models.
Cross-referencing historical efficiency standard adoption curves against expert panel input on refrigerant transition timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include airflow geometry configuration, building lifecycle stage, automation integration depth, and regional regulatory cluster. CAGRs were derived from compound growth trajectory analysis of certified product placement volumes. Industry-specific forecast inputs incorporated Bureau of Energy Efficiency enforcement tightening schedules and F-Gas Regulation phasedown milestones.
Caveats apply where refrigerant transition timeline acceleration or technician licensing requirement tightening could materially shift the outlook for installation capacity and effective supply availability. Forecasts reflect assumptions on metal price stabilization and construction permit issuance continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Europe Air to Water Heat Pump Market
HVAC Equipment
Industrial Electric Boiler Market
HVAC Equipment
Germany Heat Pump Market
HVAC Equipment
North America Residential Heat Pump Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Louver Dampers Market
HVAC Equipment
Steam Heat Exchanger Market
HVAC Equipment
Commercial RAC PD Compressor Market
HVAC Equipment
Industrial Boiler Market
HVAC Equipment
Brazed Plate Heat Exchangers Market
HVAC Equipment
Residential Furnaces Market
HVAC Equipment
North America Air to Water Heat Pump Market
HVAC Equipment
Heating Radiator Market
HVAC Equipment
China HVAC Field Device Market
HVAC Equipment
Duct Fans Market
HVAC Equipment
Field-Erected Cooling Tower Market