
 Global Tubular Heating Elements Market | 2026-2036
Global Tubular Heating Elements Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tubular Heating Elements Market Outlook
Advanced ceramic-coating integration is rewriting durability benchmarks for high-temperature tubular elements. Watlow Electric Manufacturing Company leverages its vertical manufacturing footprint across North American facilities to control alloy sourcing costs. NIBE anchors its competitive position through deep specialization in energy-efficient residential heating systems across Scandinavian markets. Chromalox, Inc. dominates the industrial process segment with engineered solutions for chemical and petrochemical end users.
Tubular heating elements are metal-sheathed resistance heaters constructed with a helical nickel-chromium wire coil embedded in magnesium oxide insulation, typically operating between 300°C and 850°C surface temperatures depending on alloy selection. Electric tubular configurations lead the product type landscape due to precise temperature control and compatibility with renewable electricity sources, while gas tubular alternatives retain share in legacy industrial boiler retrofits where infrastructure constraints persist. Stainless steel and Incoloy material grades capture the majority of margin pools, as corrosion resistance specifications tighten across food processing and pharmaceutical applications.
The EU Ecodesign Directive and REACH chemical compliance frameworks are elevating material traceability requirements for European suppliers, while China's GB standards and NMPA-equivalent pressure equipment codes govern import access into Asian manufacturing hubs. The US EPA and OSHA jointly influence industrial heater deployment through emissions thresholds and workplace thermal safety protocols. Stakeholders must monitor alloy price volatility and certification harmonization gaps between regional testing regimes to secure long-term supply contracts.
Market Dynamics
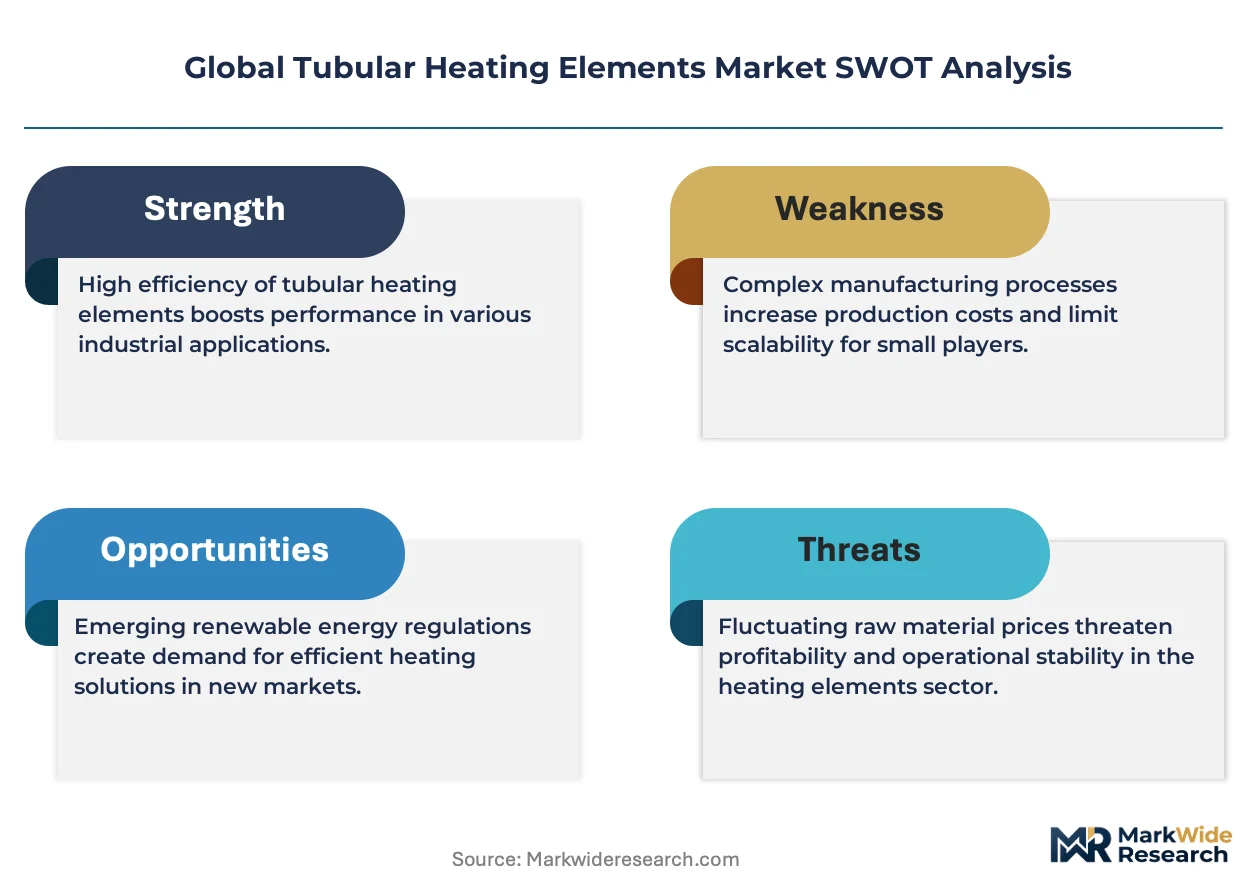
Energy efficiency mandates across industrialized economies are compressing replacement cycles for legacy heating equipment while forcing alloy specification upgrades that fragment supplier qualification pools.
Growth Catalysts
- EU Ecodesign Directive:Minimum performance standards for heating equipment are accelerating equipment replacement schedules across German and Italian food processing lines.
- China's eastern manufacturing corridor:Process heating upgrades dominate capital expenditure as chemical and pharmaceutical facilities modernize thermal systems.
- Stainless steel alloy advances:Enhanced corrosion resistance specifications are expanding addressable market share in pharmaceutical clean-in-place applications.
Market Restraints
- Nickel price volatility:Nickel-chromium wire coil input costs swing with Indonesian and Philippine ore export policies, compressing margin predictability for mid-tier fabricators.
- REACH chemical compliance:Material traceability requirements for European suppliers add documentation overhead that disadvantages smaller heating element manufacturers.
- Gas infrastructure lock-in:Legacy industrial boiler retrofits retain gas tubular alternatives where pipeline constraints block electrical grid upgrades.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO regulatory alignment with EU GMP standards is opening import pathways for certified European and US heating element suppliers.
- Renewable electricity integration:Electric tubular configurations gain preference as industrial buyers pair process heat with captive solar and wind generation assets.
- Advanced ceramic-coating convergence:Ceramic insulation technologies combined with magnesium oxide formulations are extending service intervals in high-temperature chemical processing.
Industry Challenges
- Alloy metallurgy expertise scarcity:Specialized knowledge of Incoloy and superalloy performance under thermal cycling is concentrated among aging engineering workforces in Germany and Japan.
- Multi-jurisdiction certification timelines:Harmonization gaps between EU pressure equipment codes, China's GB standards, and US OSHA thermal safety protocols delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tubular Heating Elements Market |
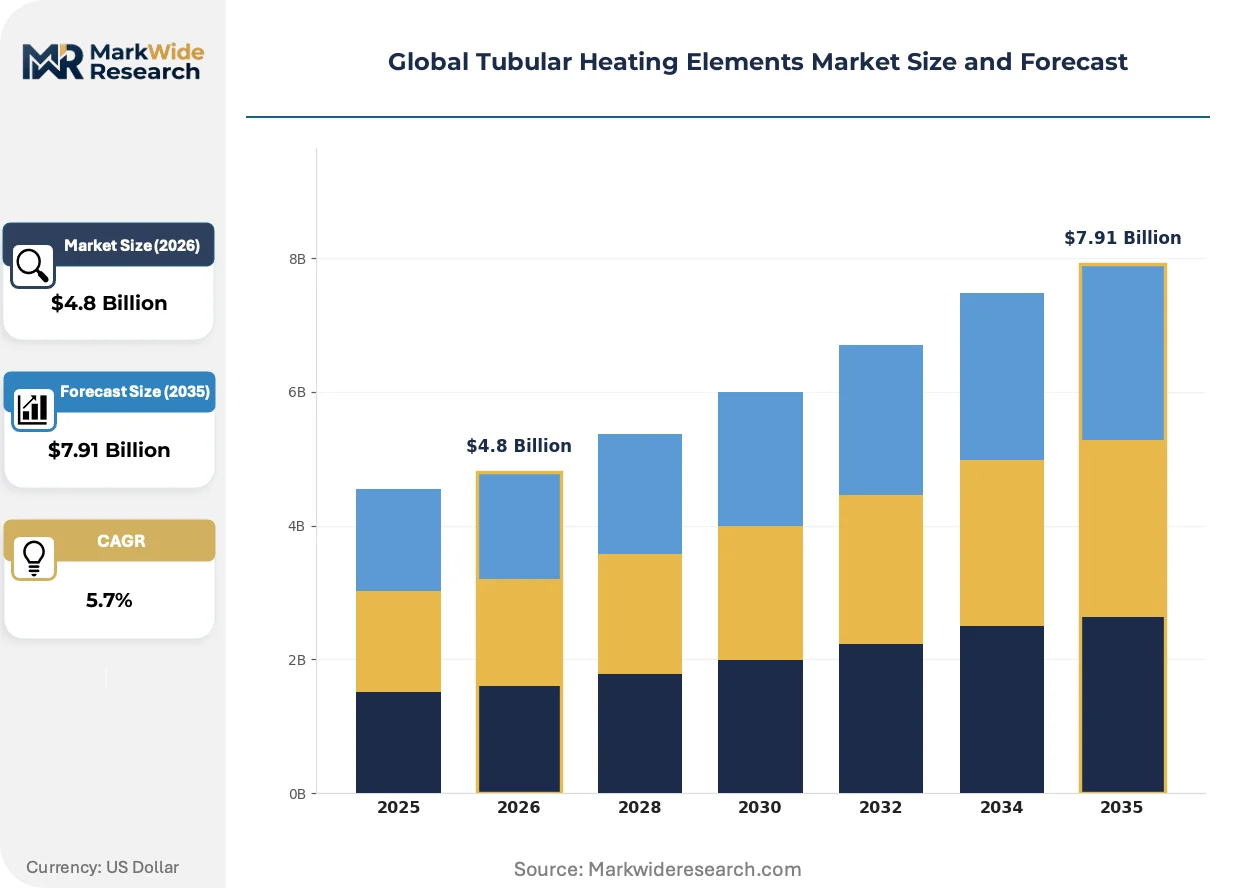
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tubular, Gas Tubular, Oil Tubular, Water Tubular End User: Residential, Commercial, Industrial, Food Processing Application: Heating Systems, Process Heating, Laboratory Equipment, HVAC Systems Material: Stainless Steel, Incoloy, Copper, Silicon Carbide |
| Companies Covered | Thermon Group Holdings, Inc., NIBE, Watlow Electric Manufacturing Company, Tempco Electric Heater Corporation, Durex Industries, Chromalox, Inc., Omega Engineering, Inc., Zoppas Industries, Backer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tubular Heating Elements Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance benchmarks across industrial process heating, with durability and traceability emerging as non-negotiable selection criteria.
Ceramic-coating integration is migrating from niche aerospace applications into mainstream chemical processing equipment. BASF and Dow chemical facilities in Louisiana and Texas are piloting these surfaces for catalytic reactor heating. The technology is migrating from premium price tiers into mid-volume contract manufacturing as coating deposition costs fall below 15% of total element price.
REACH chemical compliance frameworks are elevating material traceability requirements for European suppliers. ECHA substance of very high concern listings now cover multiple magnesium oxide impurities, forcing smelter audits back to raw ore sources. Food processing equipment OEMs in Denmark and the Netherlands are responding by consolidating supplier panels to pre-qualified alloy mills with certified chain-of-custody documentation.
Industrial buyers are unbundling after-sales service from equipment procurement, contracting thermal performance guarantees separately from hardware supply. German automotive parts manufacturers and Japanese semiconductor fabricators lead this pattern, engaging third-party metrology firms for calibration and predictive maintenance. The shift is most visible in precision temperature control applications where ISO 17025-accredited validation carries insurance and liability weight.
Global Tubular Heating Elements Market Segmentation
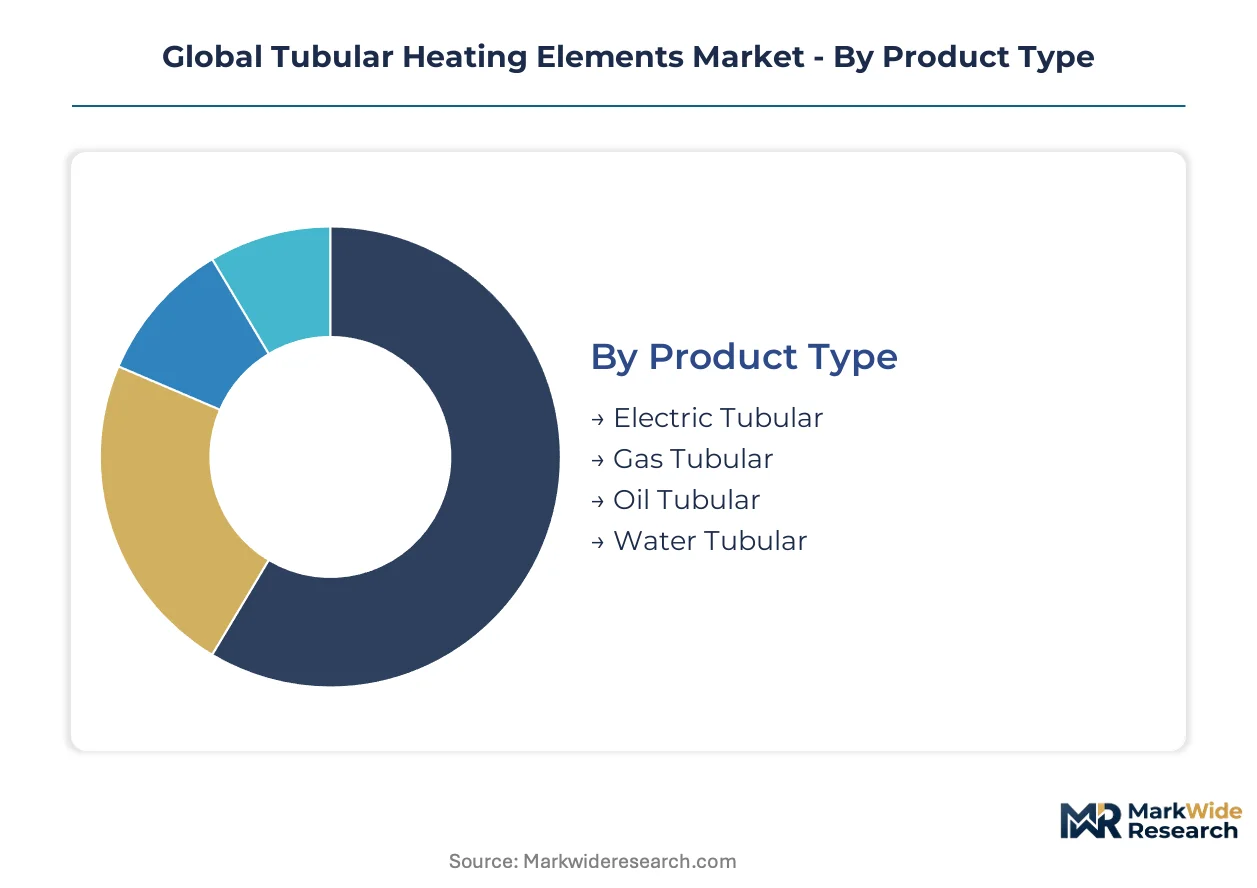
Segmentation in the tubular heating elements market reveals how alloy selection, energy source, and end-use thermal requirements fragment procurement patterns. Buyers optimize for corrosion resistance, temperature precision, or fuel infrastructure compatibility depending on application context.
Product Type:
Mature electric configurations dominate installed base volumes while alternative fuel formats retain pockets of legacy demand.
- Electric Tubular:Metal-sheathed resistance heaters with nickel-chromium coils embedded in magnesium oxide insulation deliver surface temperatures between 300°C and 850°C. German automotive parts manufacturers and Japanese semiconductor fabricators specify these for precise temperature control paired with captive renewable generation assets.
- Gas Tubular:Combustion-based heating elements integrated into legacy boiler architectures where pipeline infrastructure blocks electrical grid upgrades. Louisiana and Texas chemical facilities retain these for catalytic reactor heating where retrofit economics favor fuel continuity over efficiency gains.
- Oil Tubular:Fuel-oil fired elements serving remote industrial sites lacking grid connectivity or natural gas pipeline access.
- Water Tubular:Hydronic heating configurations for residential and commercial boiler systems requiring fluid-based heat distribution.
Electric Tubular handles the majority of throughput; Gas Tubular is the fastest mover on share as renewable integration accelerates specification shifts.
End User:
Cost tier stratification separates premium-specification industrial buyers from price-sensitive residential segments.
- Industrial:Process heating for chemical, petrochemical, and pharmaceutical manufacturing where ISO 17025-accredited thermal validation carries insurance weight. BASF and Dow facilities in Louisiana and Texas pilot ceramic-coated surfaces for catalytic reactor applications.
- Food Processing:Stainless steel and Incoloy configurations for clean-in-place equipment meeting FDA and EFSA corrosion resistance mandates. Danish and Dutch OEMs consolidate supplier panels to pre-qualified alloy mills with certified chain-of-custody documentation.
- Commercial:Mid-scale thermal systems for hospitality, healthcare, and institutional buildings balancing efficiency with capital constraints.
- Residential:Standardized heating elements for domestic water heaters and space heating where NIBE anchors competitive position through Scandinavian energy-efficient system specialization.
Industrial commands the premium tier on margin per unit; Food Processing is climbing the fastest as EU Ecodesign Directive replacement cycles compress.
Application:
Volume concentration tracks toward process heating while laboratory precision segments extract value through calibration services.
- Process Heating:Industrial thermal management for chemical reactions, material treatment, and manufacturing workflows. China's eastern manufacturing corridor dominates capital expenditure as pharmaceutical facilities modernize thermal systems.
- Laboratory Equipment:Precision temperature control for analytical instruments and research apparatus where German automotive parts manufacturers unbundle after-sales service from hardware procurement.
- Heating Systems:General-purpose thermal generation for building services and industrial infrastructure.
- HVAC Systems:Climate control integration for commercial and institutional air handling units.
Process Heating anchors volume demand; Laboratory Equipment shows steepest expansion trajectory as third-party metrology contracts proliferate.
Material:
Supply concentration among specialty alloy mills creates qualification bottlenecks for corrosion-critical specifications.
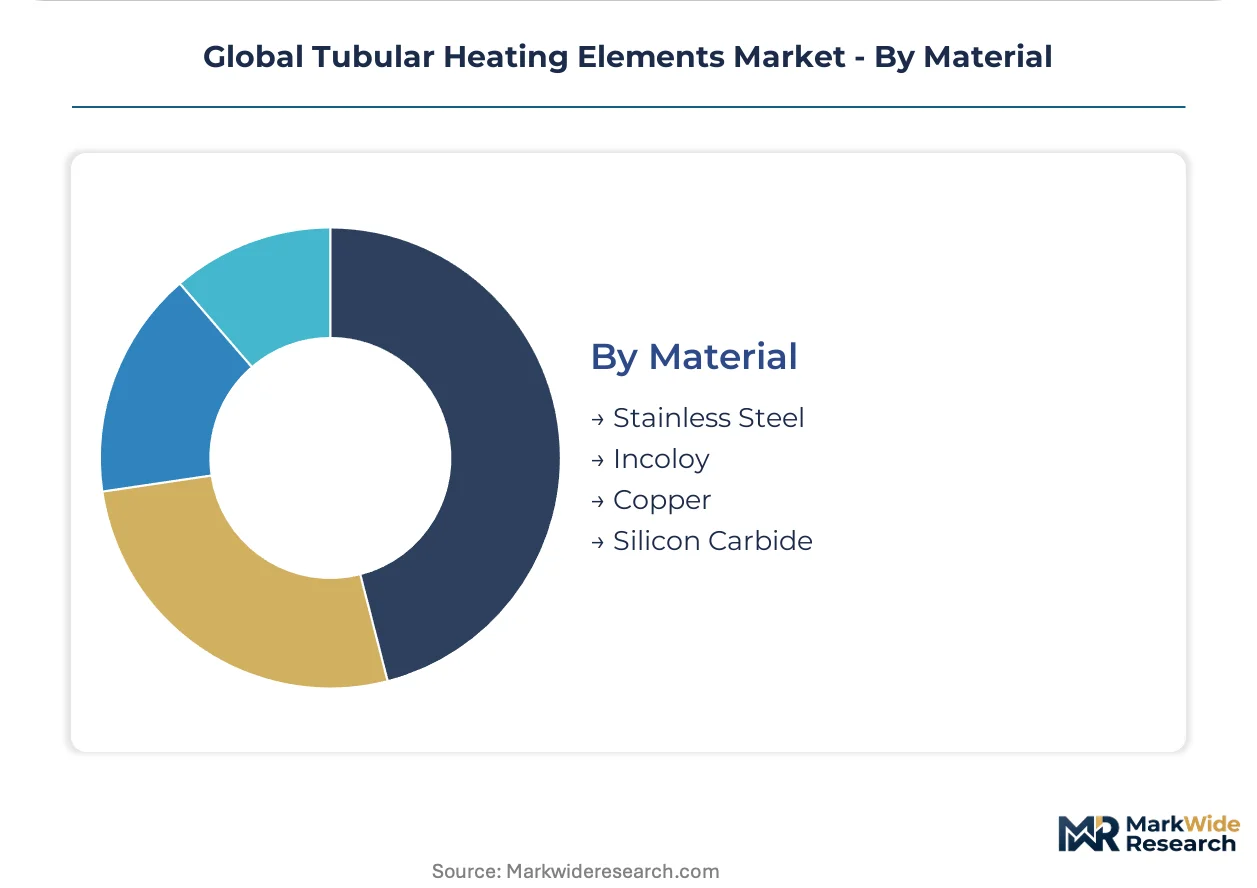
- Stainless Steel:Austenitic grades 304 and 316L dominate food processing and pharmaceutical applications where ECHA substance of very high concern listings now cover multiple magnesium oxide impurities. REACH compliance forces smelter audits back to raw ore sources.
- Incoloy:Nickel-iron-chromium superalloys for high-temperature chemical processing where thermal cycling resistance extends service intervals. Specialized metallurgy expertise concentrates among aging engineering workforces in Germany and Japan.
- Copper:High thermal conductivity elements for water heating and low-temperature applications where cost efficiency outweighs corrosion concerns.
- Silicon Carbide:Ceramic-based heating elements for extreme temperature environments beyond metal alloy limits.
Stainless Steel captures the widest qualification base; Incoloy is gaining share fastest as temperature and corrosion specifications tighten across process industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive parts manufacturers and Japanese semiconductor fabricators concentrate premium-tier procurement. Chinese pharmaceutical facilities in the eastern manufacturing corridor drive volume expansion. US chemical processors in Louisiana and Texas anchor North American demand for high-temperature configurations.
United States
BASF and Dow chemical facilities in Louisiana and Texas pilot ceramic-coated tubular elements for catalytic reactor heating. EPA emissions thresholds and OSHA thermal safety protocols govern industrial heater deployment. Process heating upgrades dominate capital expenditure as petrochemical facilities modernize thermal systems.
Germany
Industrial food processing lines expand orders for stainless steel tubular heaters as EU Ecodesign Directive replacement cycles compress. REACH chemical compliance frameworks elevate material traceability requirements for European suppliers. Automotive parts manufacturers in Baden-Württemberg unbundle after-sales service from hardware procurement.
China
Pharmaceutical facilities in the eastern manufacturing corridor modernize thermal systems with process heating upgrades. GB standards and NMPA-equivalent pressure equipment codes govern import access into Asian manufacturing hubs. Chemical and pharmaceutical capital expenditure concentrates in the Yangtze River Delta region.
Japan
Semiconductor fabricators specify electric tubular configurations for precise temperature control paired with captive renewable generation. METI industrial efficiency programs accelerate equipment replacement schedules. Specialized metallurgy expertise concentrates among aging engineering workforces in the Kansai and Chubu regions.
India
CDSCO regulatory alignment with EU GMP standards opens import pathways for certified European and US heating element suppliers. Pharmaceutical manufacturing expansion drives specification upgrades for corrosion-resistant alloys. Maharashtra and Gujarat host the majority of contract manufacturing facility investments.
Global Tubular Heating Elements Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered qualification pools. The vendor base separates into scale-driven manufacturers with captive alloy sourcing, application-engineering specialists with ISO 17025-accredited validation capabilities, and regional fabricators serving price-sensitive replacement markets. Strategic moves concentrate on backward integration into specialty alloy supply and third-party metrology partnerships for thermal performance guarantees.
Among North American manufacturers, Watlow Electric Manufacturing Company and Chromalox, Inc. exemplify the application-engineering specialist archetype with vertical manufacturing footprints. NIBE anchors the energy-efficient residential systems segment through Scandinavian market specialization. Thermon Group Holdings, Inc. occupies a position within industrial process heating alongside Tempco Electric Heater Corporation and Durex Industries, while Zoppas Industries and Backer Group represent European fabrication scale. Omega Engineering, Inc. sits within the precision instrumentation tier.
| Leading Market Players |
|---|
| Thermon Group Holdings, Inc. |
| NIBE |
| Watlow Electric Manufacturing Company |
| Tempco Electric Heater Corporation |
| Durex Industries |
| Chromalox, Inc. |
| Omega Engineering, Inc. |
| Zoppas Industries |
| Backer Group |
| Others |
Value Chain & Pricing Dynamics
Nickel price volatility from Indonesian and Philippine ore export policies compresses margin predictability for mid-tier fabricators while simultaneously widening spreads between premium alloy-certified suppliers and commodity-grade competitors. This raw material instability forces procurement officers toward long-term offtake contracts with indexed pricing clauses, fragmenting the supplier base into qualified mills with traceable chain-of-custody documentation versus unqualified regional fabricators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange nickel indexation dominate procurement agreements for Incoloy and stainless steel tubular elements. Price differentiation hinges on ISO 17025-accredited thermal validation tiers and captive renewable energy pairing for electric configurations. Cost compression in standard-grade stainless steel segments is intensifying because REACH compliance documentation overhead disadvantages smaller manufacturers. Food processing OEMs in Denmark and the Netherlands show least price sensitivity due to liability insurance requirements, while residential boiler replacement markets exhibit highest sensitivity to alloy surcharges.
Supply Chain Analysis
Export-control restrictions on superalloy metallurgy expertise limit technology transfer from German and Japanese engineering workforces to emerging manufacturing hubs. Supply concentration centers on German specialty alloy mills, Japanese precision wire coil producers, and Chinese magnesium oxide insulation processors. Raw material flows draw from Indonesian nickel laterite mines, Philippine chromite operations, and Australian magnesite deposits. Single-source vulnerability concentrates in helical nickel-chromium wire coil fabrication where thermal cycling expertise has atrophied. Distribution runs through OEM direct procurement for industrial process heating and distributor networks for aftermarket residential replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Tubular Heating Elements Market sits at an inflection where ceramic-coating integration and EU Ecodesign Directive replacement cycles are simultaneously elevating performance benchmarks and compressing supplier qualification timelines.
For Market Incumbents: Entrench metallurgy expertise through apprenticeship programs targeting German and Japanese engineering workforces nearing retirement. Secure backward integration into specialty alloy supply through equity stakes in Indonesian nickel processing assets. Defend against emerging ceramic-coating specialists by accelerating pilot partnerships with BASF and Dow chemical facilities.
For New Entrants and Emerging Players: Establish a beachhead in India's pharmaceutical manufacturing expansion where CDSCO regulatory alignment with EU GMP standards opens import pathways without incumbent relationships. Target corrosion-resistant Incoloy specifications for clean-in-place equipment where Danish and Dutch OEMs are consolidating supplier panels. Pursue third-party metrology partnerships for ISO 17025-accredited thermal performance guarantees as the primary go-to-market angle.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors application-engineering specialists with captive alloy sourcing and accredited validation capabilities. Long-term viability hinges on regulatory compliance infrastructure rather than commodity fabrication scale. Monitor nickel price volatility trajectory and EU REACH substance of very high concern listing expansions as primary signals for margin compression timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Processing | Captive supply from Indonesian laterite mines insulates margin from ore export policy swings. |
| Ceramic-Coating Technology Licensing | BASF and Dow pilot programs validate deposition cost thresholds below 15% of element price. |
| ISO 17025 Accreditation Investment | German automotive parts manufacturers unbundle metrology contracts carrying insurance liability weight. |
| EU REACH Compliance Infrastructure | ECHA substance of very high concern listings now cover multiple magnesium oxide impurities requiring smelter audits. |
| Renewable Energy Pairing Partnerships | Japanese semiconductor fabricators specify electric tubular configurations with captive solar and wind generation assets. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings from heating element manufacturers, customs trade data for nickel alloy imports, and EU ECHA regulatory databases. Plant engineers at BASF and Dow facilities, procurement leads at Danish food processing OEMs, and aftermarket service heads at German automotive parts manufacturers provided operational validation. Technical R&D directors at specialty alloy mills and channel partners in the Yangtze River Delta distribution corridor contributed supply-side perspectives. Bottom-up demand modeling from end-use capital expenditure announcements triangulates against top-down market sizing from trade association production statistics.
Forecast inputs incorporate product type segmentation across electric, gas, oil, and water tubular configurations alongside material grade tiers and application-specific thermal precision requirements. End-use industry splits for chemical processing, pharmaceutical manufacturing, food processing, and residential heating systems anchor volume projections. CAGRs derive from regression analysis of historical replacement cycle data against regulatory mandate implementation timelines. Nickel price trajectory assumptions and EU Ecodesign Directive compliance cost curves inform margin evolution across the projection horizon.
Sensitivities concentrate around Indonesian and Philippine ore export policy shifts, EU REACH substance of very high concern listing expansions, and ceramic-coating deposition cost reduction trajectories. Forecasts reflect documented assumptions regarding alloy price volatility ranges and certification harmonization timeline estimates. Material shifts in nickel-chromium wire coil supply concentration or breakthrough ceramic insulation formulations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Industrial Chiller Market
HVAC Equipment
Variable Refrigerant Flow (VRF) System Market
HVAC Equipment
China Residential Heat Pump Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
Italy Commercial HVAC Market
HVAC Equipment
Europe HVAC Equipment Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Centrifugal Blower Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Commercial Water Heater Market
HVAC Equipment
Welded Spiral Heat Exchangers Market