
 Global Concrete Block and Brick Manufacturing Market | 2026-2036
Global Concrete Block and Brick Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Concrete Block and Brick Manufacturing Market Foresight
Project finance tied to green building certification is fragmenting competitive access across the Global Concrete Block and Brick Manufacturing Market. CRH plc leverages captive limestone reserves across the United States and Ireland to sustain margin stability on bulk concrete blocks. Wienerberger AG anchors its position through specialized clay brick firing technology that dominates heritage restoration segments in Germany and Austria. China National Building Material Company controls distribution depth across provincial hubs, extending reach into infrastructure tenders that smaller producers cannot finance.
Concrete block and brick manufacturing encompasses the mechanical forming, curing, and finishing of cementitious or fired clay units used for load-bearing walls, facades, and structural infill, with compressive strengths typically ranging from 7.5 MPa for lightweight blocks to over 50 MPa for engineered structural masonry. The process employs hydraulic pressing, extrusion, or kiln firing to achieve dimensional tolerances within ±2 mm for modular construction compatibility. Autoclaved aerated concrete leads product type growth due to its thermal insulation coefficient of 0.16 W/mK, which reduces HVAC loads in residential construction. Clay bricks occupy mature, brand-sensitive replacement cycles in European renovation markets where heritage codes preserve traditional fired products. Dry-pressed technology dominates high-volume infrastructure contracts where surface finish uniformity matters less than unit cost.
EPA construction material sourcing guidelines and China's MEE dual carbon enforcement are tightening emissions thresholds for kiln operations and cement content, pushing manufacturers toward alternative binders and waste-heat recovery systems. The EU Green Deal's embodied carbon benchmarks for building materials are reshaping import competitiveness for Middle Eastern and Asian producers seeking European project qualification. Stakeholders must monitor how national building codes integrate lifecycle carbon accounting into public procurement scoring, as this will determine which manufacturing technologies and regional supply bases capture the next wave of institutional construction volume.
Market Dynamics
Carbon accounting integration into public procurement scoring is bifurcating manufacturer competitiveness, favoring those with verified lifecycle data while marginalizing regional suppliers lacking certification infrastructure.
Growth Catalysts
- India's affordable housing mandate:Central government schemes targeting low-income urban settlements drive standardized block procurement at scale, compressing delivery timelines for domestic producers.
- Fly ash utilization mandates:EPA emissions frameworks and China's MEE enforcement classify coal combustion residues as preferred raw inputs, redirecting waste streams into cementitious binders.
- Autoclaved aerated concrete thermal performance:Its insulation coefficient of 0.16 W/mK satisfies stringent building envelope codes in Nordic and German residential construction, displacing conventional dense blocks.
Market Restraints
- Cement clinker cost volatility:Energy-intensive kiln operations expose margins to natural gas and electricity price swings, particularly acute for producers in Germany and Italy.
- Clay brick supply concentration:Heritage-grade firing capacity clusters in Austria and Bavaria, creating bottleneck risk for restoration-grade materials across Central European projects.
- Cross-laminated timber substitution:Engineered wood products penetrate mid-rise residential frames in Austria and Switzerland, eroding structural block specification share.
Strategic Opportunities
- Brazil's northern corridor infrastructure:Port and logistics expansion around Belém and São Luís creates demand for high-volume, lower-specification blocks with localized supply advantages.
- Waste-heat recovery retrofits:Kiln exhaust capture systems qualify manufacturers for EU Green Deal embodied carbon benchmarks, unlocking public tender access.
- Direct-to-contractor digital platforms:B2B procurement portals bypass traditional distributor markups, enabling price transparency for mid-sized construction firms in Poland and Czech Republic.
Industry Challenges
- Lifecycle assessment certification timelines:EPD verification processes extend 8-14 months, delaying qualification for green building projects with fixed completion deadlines.
- Automation retrofit capex requirements:Robotic handling and vision-based quality control systems demand capital outlays that strain family-owned kiln operations in Southern Europe.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Concrete Block and Brick Manufacturing Market |
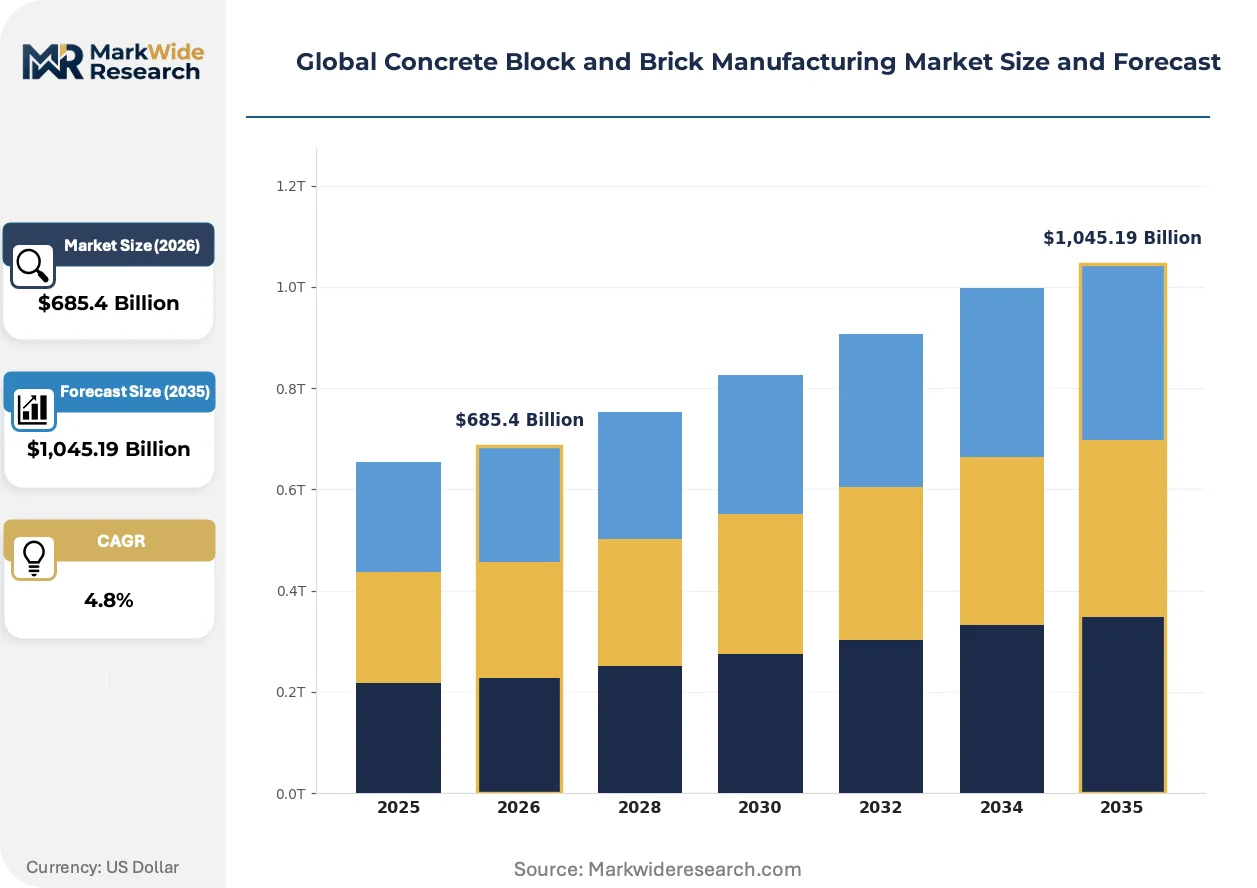
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $1,045.19 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concrete Blocks, Clay Bricks, Fly Ash Bricks, Sand Lime Bricks, Calcium Silicate Blocks, Autoclaved Aerated Concrete Manufacturing Technology: Dry-Pressed, Wire-Cut, Molding, Extrusion, Autoclaving, Hand Molding Building Application: Residential Construction, Commercial Construction, Infrastructure Projects, Institutional Buildings, Warehouses, Landscaping End User Industry: Contractors, Real Estate Developers, Government Agencies, Construction Companies, Infrastructure Firms, Housing Authorities |
| Companies Covered | Wienerberger AG, Boral Limited, CRH plc, China National Building Material Company, Xella Group, Heidelberg Materials, UltraTech Cement, General Shale, CEMEX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Concrete Block and Brick Manufacturing Market Shifts & Advancements
Electrification of thermal processes and alternative binder chemistry are compressing the carbon intensity of masonry production, while procurement digitization reconfigures how specifications reach factory floors.
Geopolymer binders derived from industrial aluminosilicate waste are rendering obsolete Portland cement dependence in precast block manufacturing. Infrastructure contractors in the Netherlands and Denmark specify these materials for marine exposure applications. The shift collapses clinker import exposure while introducing new supply chain dependencies on fly ash and slag quality consistency.
The EU Green Deal's embodied carbon benchmarks for building materials are tightening import qualification thresholds. Middle Eastern producers seeking European project access must document kiln fuel sources and transport emissions. German and Austrian heritage restoration specialists now prioritize domestic clay brick supply to satisfy lifecycle scoring requirements.
Contractor consortiums are consolidating purchasing power through centralized procurement platforms. Mid-sized builders in Poland and Hungary aggregate volume to negotiate direct factory pricing, bypassing traditional regional distributors. This channel compression concentrates order flow with manufacturers offering real-time inventory visibility and flexible batch sizing.
Global Concrete Block and Brick Manufacturing Market Segmentation
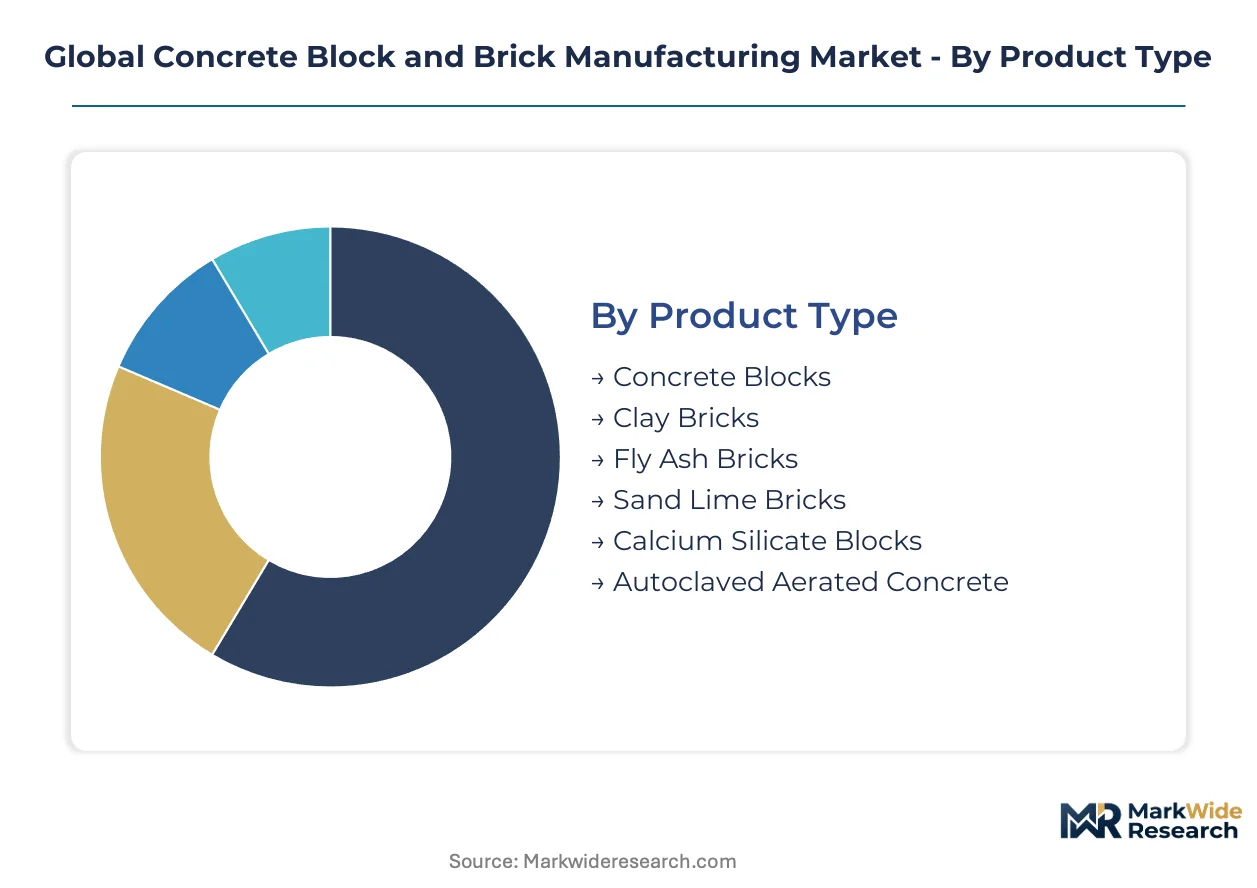
Product differentiation across the Global Concrete Block and Brick Manufacturing Market determines thermal performance specifications, structural load ratings, and regulatory compliance pathways. Manufacturers align production configurations with distinct construction verticals ranging from mass housing to heritage restoration.
Product Type:
Use-case spectrum spans lightweight thermal insulation systems through high-compressive structural units serving load-bearing and non-load-bearing applications.
- Concrete Blocks:Dense cementitious units manufactured through hydraulic pressing achieve compressive strengths from 7.5 MPa to over 50 MPa for structural masonry. India's affordable housing mandate and China's urban renewal corridors absorb rising volumes as standardized procurement compresses delivery timelines for domestic producers.
- Autoclaved Aerated Concrete:Cellular concrete formed through autoclave curing delivers thermal insulation coefficients of 0.16 W/mK, reducing HVAC loads in Nordic and German residential construction where stringent building envelope codes apply.
- Clay Bricks:Fired clay units dominate heritage-sensitive replacement cycles in European renovation markets governed by preservation codes.
- Fly Ash Bricks:Coal combustion residue binders satisfy EPA emissions frameworks and China's MEE enforcement classifying waste streams as preferred raw inputs.
- Sand Lime Bricks:Calcium silicate bonded units serve facades requiring precise dimensional tolerances within ±2 mm.
- Calcium Silicate Blocks:Hydrated lime-silica compositions provide fire resistance ratings for commercial compartmentalization.
Established volume favors concrete blocks; emerging adoption favors autoclaved aerated concrete.
Manufacturing Technology:
Cost tier stratification separates capital-intensive automated systems from labor-dependent traditional methods.
- Dry-Pressed:High-pressure compaction without moisture addition dominates infrastructure contracts where surface finish uniformity matters less than unit cost. Brazil's northern corridor port expansion around Belém and São Luís generates demand for high-volume, lower-specification blocks.
- Extrusion:Continuous clay forming through die profiles enables rapid output of modular units with consistent density. Heritage-grade firing capacity clusters in Austria and Bavaria, creating bottleneck risk for restoration-grade materials across Central European projects.
- Autoclaving:Steam-cured cellular concrete production achieves precise density control for thermal performance specifications.
- Wire-Cut:Slab slicing methods produce textured surfaces for aesthetic masonry applications.
- Molding:Form-based casting accommodates complex geometries for specialized architectural elements.
- Hand Molding:Artisanal techniques persist for heritage matching in conservation-designated districts.
Automation investments concentrate in dry-pressing; craft preservation sustains hand molding.
Building Application:
Application intensity varies by construction cycle durability and regulatory scrutiny levels.
- Residential Construction:Multi-unit housing programs across India, China, and Brazil absorb standardized block procurement at scale. India's central government schemes targeting low-income urban settlements compress delivery timelines.
- Infrastructure Projects:Transport and utility construction demands high-compressive units for buried and exposed structural applications.
- Commercial Construction:Office and retail developments prioritize rapid assembly systems with dimensional precision.
- Institutional Buildings:Schools and healthcare facilities require enhanced fire resistance and acoustic insulation ratings.
- Warehouses:Large-span structures utilize load-bearing masonry for cost-efficient envelope construction.
- Landscaping:Non-structural paving and retaining applications specify lower-grade aesthetic units.
Volume concentration sits with residential construction; specification value concentrates in infrastructure.
End User Industry:
Customer type determines procurement scale, certification requirements, and payment cycle structures.
- Contractors:Mid-sized builders in Poland and Hungary aggregate volume through centralized procurement platforms, negotiating direct factory pricing and bypassing traditional regional distributors. Digital B2B portals enable real-time inventory visibility.
- Government Agencies:Public procurement scoring integrates lifecycle carbon accounting, favoring manufacturers with verified EPD data while marginalizing regional suppliers lacking certification infrastructure.
- Real Estate Developers:Private housing projects prioritize cost optimization through standardized block specifications.
- Construction Companies:Integrated firms maintain captive supply relationships for schedule certainty.
- Infrastructure Firms:Transport and utility specialists demand durability certifications for exposed applications.
- Housing Authorities:Social housing programs mandate affordability compliance with thermal performance minimums.
Consolidated purchasing power favors contractor platforms; compliance complexity favors government agency specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor consortiums and government housing agencies concentrate procurement power in India, China, Germany, Brazil, and the United States, where construction volume and regulatory stringency create divergent competitive conditions for block and brick manufacturers.
India
Affordable housing mandates under the Pradhan Mantri Awas Yojana drive standardized concrete block procurement at scale, compressing delivery timelines for domestic producers. BIS certification requirements for masonry units tighten quality thresholds for fly ash brick manufacturers. Gujarat and Maharashtra industrial clusters host expanding production capacity to serve Mumbai-Ahmedabad corridor urbanization.
China
Urban renewal corridors in tier-two cities absorb rising volumes of autoclaved aerated concrete for residential envelope construction. MEE dual carbon enforcement redirects kiln operations toward waste-heat recovery systems and alternative binders. Shandong and Hebei provincial hubs concentrate manufacturing capacity to capture infrastructure tender flows.
Germany
Heritage restoration cycles sustain demand for traditional fired clay bricks governed by preservation codes in Bavaria and North Rhine-Westphalia. EU Green Deal embodied carbon benchmarks reshape import qualification thresholds for project access. Baden-Württemberg firing capacity clusters serve Stuttgart and Munich renovation markets.
Brazil
Northern corridor port expansion around Belém and São Luís generates demand for high-volume, lower-specification concrete blocks with localized supply advantages. Federal infrastructure programs prioritize cost-efficient masonry for logistics and transport construction. São Paulo state manufacturers extend distribution reach into Amazon basin development zones.
United States
Residential construction across Sun Belt metros absorbs bulk concrete block volumes for single-family and multi-unit housing. EPA construction material sourcing guidelines tighten emissions thresholds for kiln operations and cement content. Texas and Florida production clusters leverage captive limestone reserves and distribution depth to serve Gulf Coast and Southeast markets.
Global Concrete Block and Brick Manufacturing Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into scale-driven bulk suppliers, heritage-grade firing specialists, and regional procurement platforms. Three archetypes dominate: integrated building materials conglomerates with captive raw material reserves; clay brick specialists preserving traditional firing craft for restoration markets; and state-linked producers controlling provincial distribution networks. Competitive moves concentrate on waste-heat recovery retrofits for carbon certification and direct-to-contractor digital procurement bypassing distributor markups.
Among European heritage specialists, Wienerberger AG exemplifies the firing-technology archetype serving conservation-code markets. CRH plc represents the integrated conglomerate model with raw material reserve control. China National Building Material Company anchors the state-linked platform archetype with provincial hub distribution depth.
| Leading Market Players |
|---|
| Wienerberger AG |
| Boral Limited |
| CRH plc |
| China National Building Material Company |
| Xella Group |
| Heidelberg Materials |
| UltraTech Cement |
| General Shale |
| CEMEX |
| Others |
Supply & Pricing Matrix
The Shanghai-Rotterdam maritime corridor's freight cost volatility transmits directly into landed price spreads for autoclaved aerated concrete imports, concentrating supply leverage with domestic producers in India and China while forcing European buyers toward premium-certified local kilns.
Pricing Analysis
Cost-plus contracts indexed to cement clinker and natural gas benchmarks dominate bulk infrastructure procurement, with price differentiation resting on BIS certification grade and volume scale. Premium heritage-grade clay bricks from Bavarian firing clusters command substantial markups over standard concrete blocks. Pricing pressure stems from energy cost compression in German and Italian kiln operations. Government housing authorities exhibit highest price sensitivity; heritage restoration contractors show lowest.
Supply Chain Analysis
Upstream feedstock sourcing draws from limestone deposits in the United States and Ireland, fly ash streams from Chinese and Indian coal power generation, and high-purity clay reserves in Austria and Bavaria. Cement clinker, industrial aluminosilicate waste, and firing fuel constitute critical input dependencies. Single-source vulnerability concentrates in heritage-grade clay supply from Central European firing clusters. Distribution runs through provincial hub networks controlled by state-linked producers and direct-to-contractor digital platforms bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as India's affordable housing mandate and China's urban renewal corridors accelerate standardized block procurement ahead of full carbon accounting integration into public tender scoring.
For Market Incumbents: Entrench position through waste-heat recovery retrofits qualifying for EU Green Deal embodied carbon benchmarks, and deepen captive limestone reserve control across Texas and Florida production clusters. Cross-laminated timber substitution in Austrian and Swiss mid-rise residential frames threatens structural block specification share. Certification investment in EPD verification infrastructure unlocks green building project access. For New Entrants and Emerging Players: Brazil's northern corridor port and logistics expansion around Belém and São Luís represents the most penetrable entry point for high-volume, lower-specification concrete block supply. Fly ash brick manufacturing under EPA emissions frameworks offers second white-space avenue. Direct-to-contractor digital platforms provide the essential go-to-market angle for bypassing entrenched distributor markups. For Investors and Strategic Acquirers: Regional procurement platforms with real-time inventory visibility and flexible batch sizing capabilities present the most attractive acquisition target archetype for medium-term consolidation plays. Long-term viability hinges on carbon certification infrastructure deployment across the analysis window. Monitor integration of lifecycle carbon accounting into public procurement scoring as the critical inflection indicator for competitive access fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Waste-Heat Recovery Retrofit | Qualifies manufacturers for EU Green Deal benchmarks and unlocks public tender access in Germany. |
| Backward Integration into Limestone Reserves | CRH plc's captive supply across United States and Ireland sustains margin stability on bulk concrete blocks. |
| Direct-to-Contractor Digital Platform Launch | Mid-sized Polish and Czech builders aggregate volume to negotiate factory pricing bypassing distributors. |
| Geopolymer Binder Transition | Dutch and Danish infrastructure contractors specify industrial aluminosilicate waste binders for marine exposure applications. |
| Provincial Hub Distribution Expansion | China National Building Material Company extends reach into infrastructure tenders smaller producers cannot finance. |
Research Methodology
A standing panel of plant operations managers, procurement leads at infrastructure contractors, kiln technology specialists, and government housing agency specification officers provided ongoing calibration throughout the study. Primary interview findings combined with secondary validation from EPA construction material sourcing guidelines, China's MEE enforcement documentation, EU Green Deal embodied carbon benchmark publications, and BIS certification requirement databases. Bottom-up capacity and demand modeling triangulated against top-down macro construction spend projections.
Scenario-bracketing around cement clinker cost volatility, natural gas price swings, and carbon accounting integration timelines bounded the analytical envelope across the projection horizon. Segmentation dimensions modeled encompass product type, manufacturing technology, building application, and end user industry alongside regional regulatory cluster intensity. CAGRs derived from volume-demand elasticity analysis and capacity expansion pipeline tracking, with specific inputs including India's Pradhan Mantri Awas Yojana procurement timelines and China's tier-two city urban renewal corridor spend patterns.
Stress conditions across energy input costs, EPD certification approval delays, and cross-laminated timber substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement consistency and infrastructure program continuity. Cross-checking against national construction spend surveys and provincial tender award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Middle-East and Africa Industrial Flooring Market
Building & Construction Materials
Door and Window Hardware Market
Building & Construction Materials
Fiberglass Light Poles Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
North America Steel Rebar Market
Building & Construction Materials
Fire-Retardant Treated Wood Market
Building & Construction Materials
Engineered Wood Market
Building & Construction Materials
USA and Canada Fence Screen Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
Magnesium Oxide Boards Market
Building & Construction Materials
Tile Grout Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Asia-Pacific Gypsum Board Market
Building & Construction Materials
Door Hardware Market
Building & Construction Materials
Basalt Fiber Reinforced Polymer BFRP Market