
 Acoustic Doors Market | 2026-2036
Acoustic Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Acoustic Doors Market Outlook
European steel door fabrication is shifting toward certified acoustic cores as building codes tighten. ASSA ABLOY leverages its multi-brand architecture to dominate specification channels across Scandinavia and Central Europe. Hörmann Group anchors its position through captive supply of mineral wool cores and in-house pressing lines. Dormakaba Group differentiates via integrated access-control hardware paired with tested acoustic assemblies.
Acoustic doors are engineered barriers designed to attenuate airborne sound transmission, typically achieving Sound Transmission Class ratings from STC 35 to STC 55 through multi-layer construction incorporating mass-loaded barriers, viscoelastic damping compounds, and sealed perimeter gasketing. Their primary purpose is to isolate noise-sensitive zones in commercial, industrial, and cultural facilities where speech privacy, equipment containment, or recording fidelity is mandatory. Hinged doors still occupy the largest specification share due to retrofit compatibility and established hardware ecosystems, while sliding variants are gaining fastest in healthcare and broadcast studios where floor-space optimization dictates selection. Composite materials are displacing solid wood in premium tiers as manufacturers seek lighter weight with equivalent mass-law performance.
The EPA's Noise Control Act and OSHA occupational exposure limits shape industrial demand by mandating hearing conservation programs above 85 dBA, directly specifying acoustic enclosure doors. Germany's EnEV and the EU's Construction Products Regulation enforce declared sound reduction indices, forcing third-party testing and CE marking for market access. Stakeholders must monitor evolving green building certifications that now weight acoustic comfort alongside energy metrics, recalibrating material choices and certification investments.
Market Dynamics
Building code stringency across developed markets is compressing specification timelines while forcing manufacturers to pre-certify assemblies before bidding. This regulatory ratchet is concentrating procurement power among testing-capable suppliers and accelerating obsolescence of uncertified product lines.
Growth Catalysts
- Healthcare construction mandates:Hospital expansion in the United States and Germany is specifying STC 50+ assemblies for patient privacy zones. Medicare facility guidelines now explicitly reference acoustic performance in reimbursement eligibility.
- EnEV sound insulation benchmarks:Germany's updated Energy Saving Ordinance mandates stricter sound reduction indices in new commercial buildings, forcing retrofit upgrades and new-build specification of certified acoustic cores.
- Mineral wool core technology:Captive in-house production of engineered mineral wool is enabling manufacturers to guarantee batch-to-batch acoustic consistency while compressing lead times for custom STC ratings.
Market Restraints
- Steel sheet input volatility:Cold-rolled steel pricing fluctuations directly compress door fabrication margins, with European mills exercising quarterly price adjustment clauses that transfer risk downstream.
- Testing laboratory concentration:Third-party STC certification capacity concentrates in Germany and the United States, creating bottlenecks for Asian manufacturers seeking CE marking or UL listing.
- Mass-law performance ceiling:Solid-core wood alternatives face inherent weight constraints above STC 52, limiting specification in broadcast studios and orchestral facilities demanding STC 55+ isolation.
Strategic Opportunities
- Modular healthcare construction:Prefabricated patient room pods in the United States require factory-installed acoustic door sets, creating specification channels outside traditional construction bidding.
- Integrated access control convergence:Pairing acoustic assemblies with biometric readers and electronic locking hardware addresses security-audio bundling demand in data centers and financial trading floors.
- EU Green Deal building renovation wave:Deep retrofit mandates for commercial stock create replacement demand for outdated entrance assemblies, with acoustic performance now weighted alongside thermal metrics in public tender scoring.
Industry Challenges
- Acoustic testing technician scarcity:Qualified laboratory personnel for STC/ISO 140 measurement protocols command premium wages, constraining certification throughput and extending product launch timelines.
- Legacy frame compatibility:Retrofit acoustic door installation requires field modification of existing steel or timber frames, complicating warranty coverage and installer certification requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acoustic Doors Market |
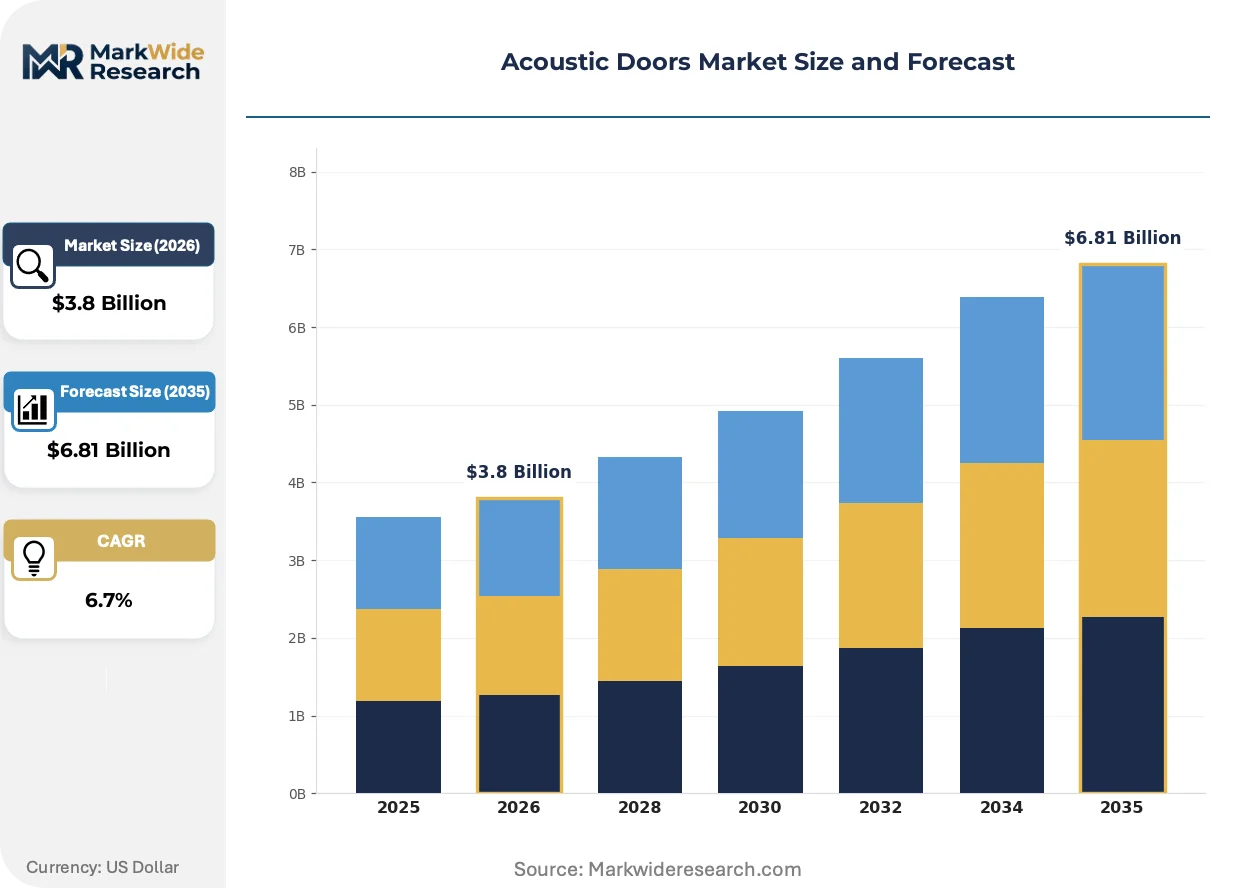
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hinged Doors, Sliding Doors, Bi-Fold Doors, Acoustic Windows End User: Residential, Commercial, Industrial, Educational Material: Wood, Metal, Glass, Composite Application: Studios, Theaters, Offices, Laboratories |
| Companies Covered | ASSA ABLOY, Dormakaba Group, Hörmann Group, JELD-WEN, Inc., Masonite, IAC Acoustics, Clark Door, Lindner Group, Krieger Specialty Products LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acoustic Doors Market Strategic Shifts
Digital fabrication and automated core assembly are compressing the traditional trade-off between custom acoustic performance and production scale. Manufacturers are reconfiguring plant layouts to accommodate shorter runs without sacrificing tested consistency.
Machine-guided pressing and robotic core placement is automating the assembly of multi-layer acoustic door constructions. Broadcast studio contractors in Los Angeles and Nashville are specifying these digitally verified assemblies to eliminate field acoustic failures. The technology is automating quality assurance steps previously requiring manual inspection, reducing per-unit testing overhead by consolidating verification at the production line.
REACH chemical restrictions on legacy flame retardants are forcing reformulation of intumescent seals and viscoelastic damping compounds used in high-STC assemblies. German manufacturers are accelerating substitution timelines to maintain CE marking validity under updated safety data sheet requirements. Fire-rated acoustic door exports from Asia-Pacific face compliance recertification costs that compress margin structures for standard-grade product lines.
Specification bundling is consolidating procurement authority among architectural firms with in-house acoustic modeling capability. Large healthcare and performing arts projects in the United States are bypassing distributor networks to negotiate direct with certified manufacturers. This channel compression is most visible in hospital construction, where design-build contracts assign acoustic performance liability to single-source envelope contractors rather than fragmented specialty suppliers.
Acoustic Doors Market Segmentation
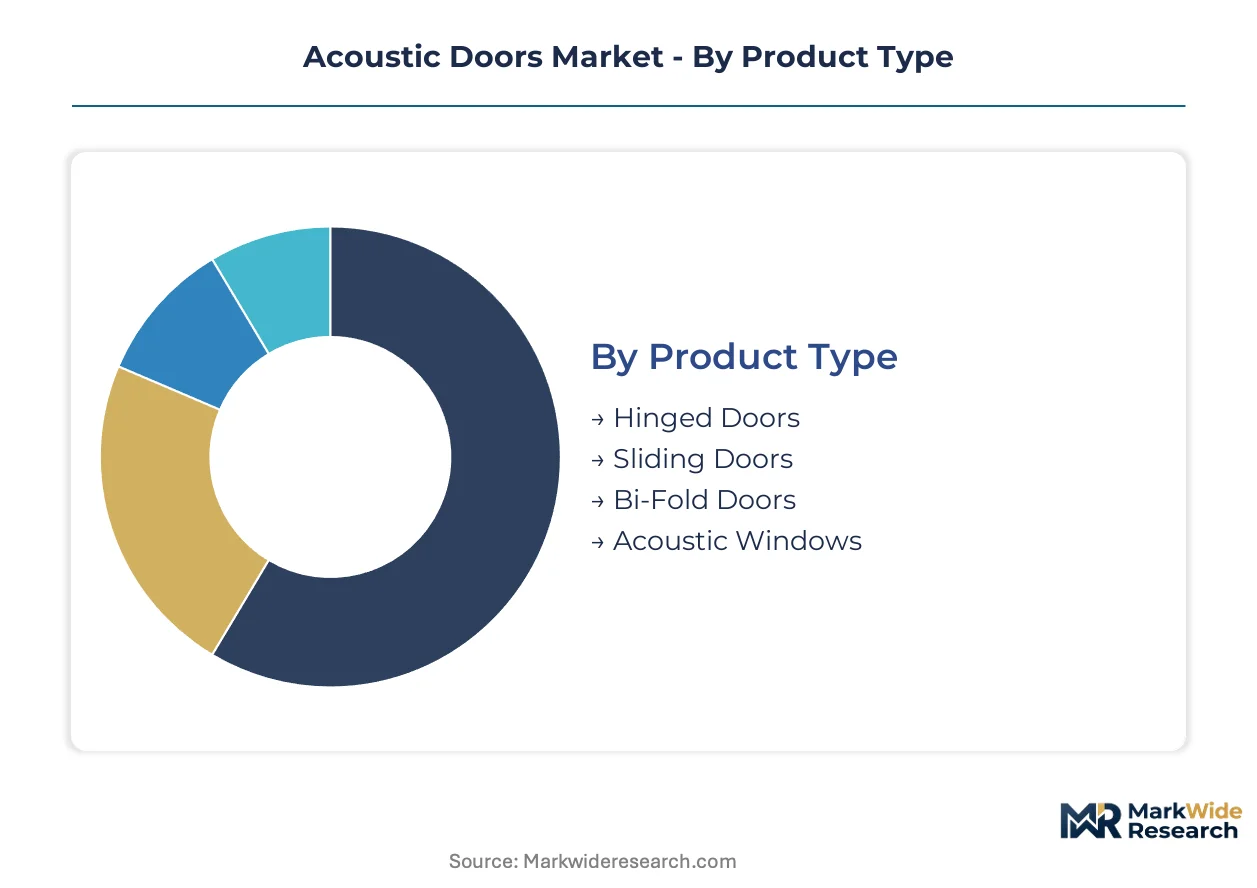
Acoustic door procurement divides sharply between retrofit replacement cycles and new-build specification channels. Material choices and operating configurations determine which manufacturers capture hospital, studio, and commercial contracts.
Product Type:
Hinged assemblies dominate volume shipments while sliding configurations command premium pricing in space-constrained installations.
- Hinged Doors:Single or double-leaf assemblies with perimeter compression seals and multi-point locking hardware. Hospital expansion in the United States and Germany specifies these for patient room privacy zones where Medicare guidelines mandate STC 50+ performance.
- Sliding Doors:Top-hung or floor-guided systems eliminating swing radius requirements. Broadcast studios in Los Angeles and Nashville favor these for control room isolation where floor-space optimization dictates selection.
- Bi-Fold Doors:Concertina configurations for wide apertures in flexible performance venues.
- Acoustic Windows:Fixed or operable glazed assemblies paired with door systems for visual monitoring.
Today's leader: Hinged Doors. Tomorrow's challenger: Sliding Doors.
End User:
Commercial specifications concentrate procurement authority among design-build contractors while residential demand fragments across individual renovation decisions.
- Commercial:Office towers, hospitality, and retail complexes specifying STC 35-45 entrance assemblies. Germany's EnEV mandates drive replacement demand in existing commercial stock.
- Industrial:Manufacturing facilities and power plants requiring OSHA-compliant hearing conservation enclosures above 85 dBA exposure thresholds.
- Residential:Home theaters and urban infill projects seeking privacy from external noise sources.
- Educational:University lecture halls and K-12 music rooms with limited acoustic isolation budgets.
Commercial specifications anchor current revenue. Industrial retrofits show steepest expansion trajectory under tightening occupational exposure regulations.
Material:
Weight-performance tradeoffs separate premium tiers from standard-grade procurement.
- Metal:Steel or aluminum frames with mineral wool cores achieving STC 45-55 ratings. Cold-rolled steel input volatility compresses fabrication margins.
- Composite:Engineered laminates displacing solid wood in premium tiers by delivering equivalent mass-law performance at reduced weight.
- Wood:Solid-core timber alternatives facing inherent constraints above STC 52.
- Glass:Laminated or insulated glazing for visual transparency in administrative and healthcare corridors.
Metal captures specification share in institutional projects. Composite materials gain fastest in broadcast and orchestral facilities demanding high isolation at manageable weight.
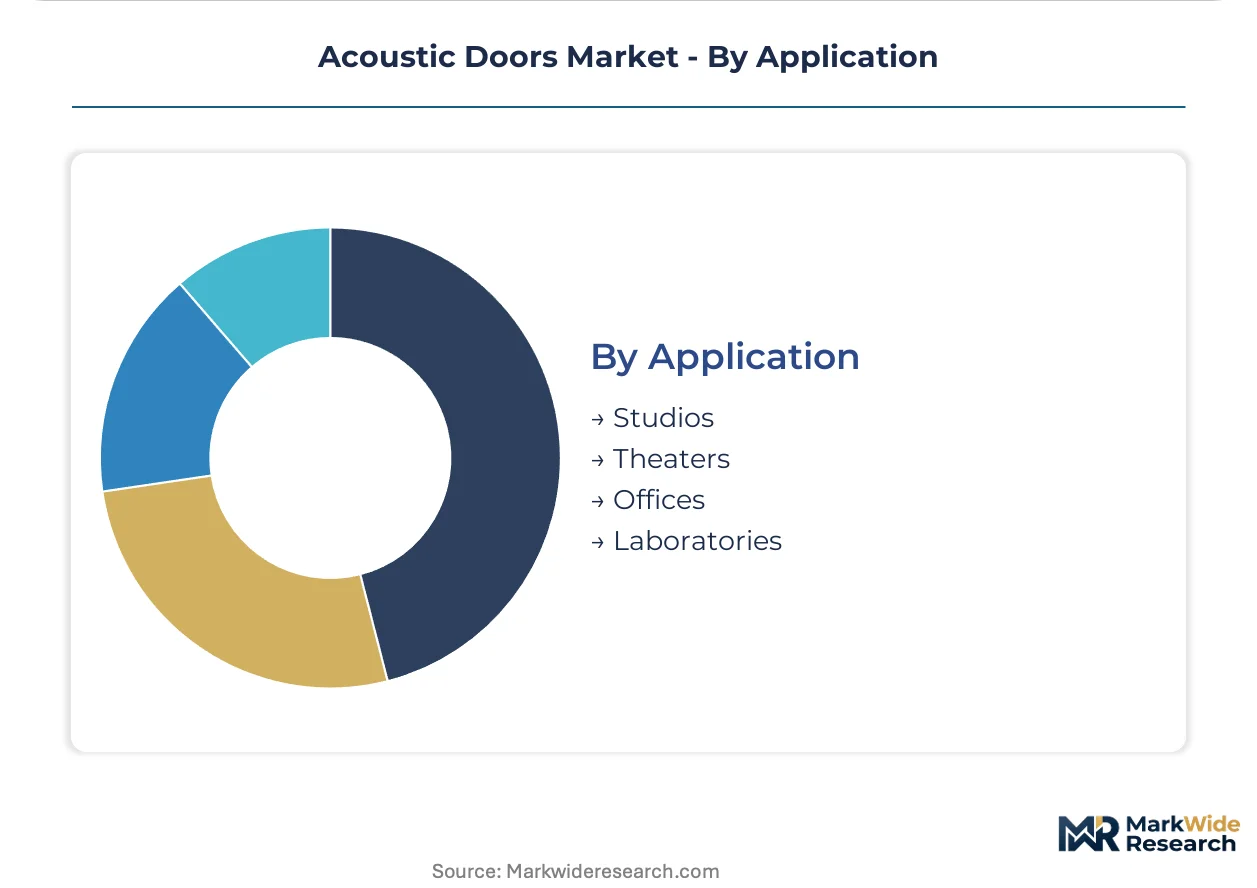
Application:
Performance thresholds vary dramatically between speech privacy and full-spectrum isolation requirements.
- Studios:Recording and broadcast facilities demanding STC 55+ isolation for critical listening environments.
- Theaters:Performance venues requiring variable acoustic separation between backstage and audience zones.
- Offices:Conference rooms and executive suites seeking speech privacy at moderate STC 40-45 ratings.
- Laboratories:Research facilities containing equipment noise while maintaining cleanroom pressure differentials.
Studios set the performance ceiling that drives material innovation. Laboratories represent the fastest-climbing application as pharmaceutical and semiconductor construction accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany enforces stricter sound insulation benchmarks than the United States, yet both markets concentrate procurement among certified manufacturers capable of pre-tested STC assemblies.
United States
Hospital construction in Nashville and Los Angeles specifies STC 50+ hinged assemblies for patient privacy zones. Medicare facility guidelines now tie reimbursement eligibility to acoustic performance metrics. OSHA mandates hearing conservation programs above 85 dBA, driving industrial procurement of acoustic enclosure doors across manufacturing belts.
Germany
The updated Energy Saving Ordinance mandates elevated sound reduction indices in new commercial buildings and retrofits. CE marking under the Construction Products Regulation forces third-party testing of mineral wool core assemblies. Fabrication clusters in North Rhine-Westphalia concentrate captive production of engineered cores for batch-to-batch consistency.
United Kingdom
Broadcast studio construction in London and Manchester demands STC 55+ sliding configurations for control room isolation. Building Regulations Part E enforces minimum airborne sound insulation for residential and commercial conversions. Specialist contractors in the Southeast bypass distributor networks to negotiate direct with certified manufacturers.
China
Pharmaceutical and semiconductor facility construction accelerates demand for cleanroom-compatible acoustic assemblies. GB standards for building acoustics are tightening enforcement in first-tier cities. Industrial clusters in the Yangtze River Delta scale automated core pressing lines to compress lead times for custom STC ratings.
Japan
Urban infill projects in Tokyo and Osaka specify lightweight composite doors achieving equivalent mass-law performance at reduced weight. METI promotes building energy efficiency standards that now weight acoustic comfort alongside thermal metrics. Prefabricated construction methods in Kanto require factory-installed acoustic door sets.
Acoustic Doors Market Competitive Environment
European producers anchor the premium tier through captive mineral wool core supply and in-house pressing lines; Asian fabricators compete on scale for standard-grade commercial specifications. The vendor base concentrates among testing-capable suppliers with established CE marking and UL listing credentials. Three archetypes dominate: diversified building hardware conglomerates, specialized acoustic enclosure fabricators, and vertically integrated door manufacturers. Competitive moves center on automated core assembly investments and direct specification channel development with architectural firms.
Among European-based building hardware groups, ASSA ABLOY, Hörmann Group, and Dormakaba Group exemplify the diversified conglomerate archetype. ASSA ABLOY leverages multi-brand architecture across Scandinavian and Central European specification channels. Hörmann Group anchors its position through captive supply of mineral wool cores. Dormakaba Group occupies a position emphasizing integrated access-control hardware paired with tested acoustic assemblies.
| Leading Market Players |
|---|
| ASSA ABLOY |
| Dormakaba Group |
| Hörmann Group |
| JELD-WEN, Inc. |
| Masonite |
| IAC Acoustics |
| Clark Door |
| Lindner Group |
| Krieger Specialty Products LLC |
| Others |
Value Chain & Pricing Dynamics
Hospital procurement committees and design-build contractors in the United States and Germany concentrate purchasing power around certified STC-rated assemblies, enforcing a performance-tiered pricing model where third-party testing credentials command substantial premiums over uncertified alternatives.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for standard-grade metal acoustic doors. Three-tier pricing structure across premium, standard, and economy levels separates STC 55+ broadcast studio assemblies from STC 35-45 commercial entrance units. Cold-rolled steel input volatility compresses margins most acutely in the economy tier. Industrial buyers under OSHA mandate pressure exhibit highest price sensitivity; orchestral facilities demanding STC 55+ isolation show least.
Supply Chain Analysis
Mineral wool core supply rests on captive production clusters in Germany's North Rhine-Westphalia, China's Jiangsu province, and Japan's Kanto region. Cold-rolled steel sheet, engineered mineral wool, and intumescent seal compounds constitute critical input dependencies. Single-source vulnerability concentrates in third-party STC certification capacity located in Germany and the United States. Distribution runs through architectural specification channels and direct contracting with design-build envelope contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where Germany's updated Energy Saving Ordinance and Medicare facility guidelines in the United States continuously ratchet performance baselines and replacement demand.
For Market Incumbents: Deploy automated core assembly investments to compress custom-order lead times without sacrificing batch-to-batch acoustic consistency. Defensive moves center on locking specification channels through pre-certified assembly libraries and securing captive mineral wool supply against input volatility. The threat of REACH chemical restrictions on legacy flame retardants demands accelerated reformulation of intumescent seals and damping compounds. For New Entrants and Emerging Players: Digital fabrication platforms offer a technology-first wedge into the modular healthcare construction segment where prefabricated patient room pods require factory-installed acoustic door sets. White-space targets include cleanroom-compatible acoustic assemblies for pharmaceutical and semiconductor facilities in China, and lightweight composite doors for urban infill projects in Japan. A specification-direct go-to-market angle bypasses distributor networks to capture design-build contracts. For Investors and Strategic Acquirers: Building hardware conglomerates are the most active acquirer in this space, seeking testing-capable suppliers with established CE marking and UL listing credentials. Long-term viability hinges on regulatory certification moats rather than manufacturing scale alone. The acquisition target archetype is vertically integrated fabricators with in-house mineral wool core production. Watch for REACH enforcement acceleration in Europe as an inflection indicator for reformulation cost burdens.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Core Assembly Investment | Machine-guided pressing enables shorter custom runs while maintaining STC consistency for broadcast studio contractors. |
| Captive Mineral Wool Production | In-house engineered core supply guarantees batch-to-batch acoustic performance and compresses lead times. |
| Specification Channel Direct Access | Bypassing distributor networks captures hospital construction contracts where design-build liability consolidates. |
| REACH-Compliant Seal Reformulation | Substituting legacy flame retardants maintains CE marking validity under updated safety data requirements. |
| Integrated Access Control Pairing | Biometric reader bundling addresses security-audio convergence demand in data centers and trading floors. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged acoustic testing laboratory technicians, hospital procurement managers, broadcast studio contractors, architectural specification writers, and door fabrication plant managers. Secondary validation drew from OSHA enforcement databases, CE marking registries, Medicare facility guideline documents, and German EnEV regulatory filings. Bottom-up volume builds and top-down market sizing triangulated to convergence.
Historical reference periods anchored the projection horizon to observed regulatory implementation timelines and construction cycle patterns. The analytical framework modeled segmentation across product type, material composition, STC performance tier, end-use vertical, and regional regulatory cluster. CAGRs derived from regression against construction spending indices and regulatory mandate adoption curves. Forecast inputs incorporated mineral wool capacity expansion schedules and third-party testing laboratory throughput constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH chemical restriction timelines and steel input volatility. Assumptions reflect documented regulatory trajectories and disclosed capacity investments. A small set of named triggers—German EnEV enforcement intensity, Medicare acoustic reimbursement rule finalization, and Chinese GB standard tightening—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
US Residential and Commercial Roofing Materials Market
Building & Construction Materials
Composite Insulated Panels Market
Building & Construction Materials
Household Mosaic Tiles Market
Building & Construction Materials
India Particle Board Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Exterior Sheathing Market
Building & Construction Materials
Spray Foam Market
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
Clean Room Panels Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Elevated Water Storage Tanks Market
Building & Construction Materials
Door System Market
Building & Construction Materials
Europe AAC Blocks and Panels Market