
 Global Roofing Market | 2026-2036
Global Roofing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Roofing Market Outlook
Green bond financing and sustainability-linked project finance is rewriting competitive access for roofing contractors and material suppliers. Owens Corning leverages its vertically integrated fiberglass supply chain to control input costs across North American markets. GAF Materials Corporation anchors its position through dense distributor networks and contractor loyalty programs. Wienerberger AG dominates clay and concrete tile production across Central and Eastern European markets.
Roofing encompasses the design, fabrication, and installation of protective weatherproofing layers for buildings, typically incorporating membranes, shingles, tiles, or metal panels with specified fire-resistance ratings and thermal insulation values. Its primary purpose is to shield structural interiors from precipitation, solar radiation, and temperature extremes while contributing to building envelope energy performance. Asphalt shingles occupy the largest installed base in North American residential markets due to low first-cost and established contractor familiarity. Metal roofing represents the fastest-expanding material category as standing-seam and stone-coated steel systems gain traction in commercial and high-wind zones. Tile and slate segments concentrate margin pools in premium replacement cycles and heritage restoration projects where longevity commands price premiums.
The EPA Energy Star program and California Title 24 building codes drive cool-roof specifications that favor reflective coatings and light-colored membranes. REACH and RoHS frameworks in Europe restrict hazardous substance content in polymer-modified bitumen and adhesive formulations. The EU Green Deal's renovation wave targets are accelerating deep retrofit demand across aging building stocks. Stakeholders must monitor how evolving carbon-border adjustments and embodied-carbon disclosure rules reshape material sourcing decisions and supplier qualification criteria.
Market Dynamics
The EU F-Gas Regulation and parallel refrigerant-phaseout mandates are compressing polymer-modified bitumen supply chains while accelerating mineral wool and bio-based membrane substitution curves across European retrofit programs.
Growth Catalysts
- Deep Retrofit Mandates:The EU Green Deal's renovation wave targets are triggering whole-building envelope replacements in Germany, Poland, and Italy, pulling demand for high-R-value insulated roofing systems.
- Cool-Roof Codes:California Title 24 and EPA Energy Star specifications are mandating solar reflectance index thresholds that favor TPO membranes and reflective coatings in commercial re-roofing cycles.
- Metal Panel Technology:Standing-seam and stone-coated steel systems are capturing share in Florida and Texas high-wind zones where insurance underwriters now require enhanced uplift resistance ratings.
Market Restraints
- Bitumen Input Volatility:Crude oil price swings directly transmit to SBS-modified asphalt shingle margins, constraining pricing flexibility for mid-tier residential contractors.
- Clay Tile Concentration:Wienerberger AG and select Italian producers control 70% of European clay tile kiln capacity, creating supply bottlenecks during peak Mediterranean construction seasons.
- Fluorinated Polymer Restrictions:REACH Annex XVII limitations on PFAS content are forcing reformulation of premium single-ply membranes, extending product recertification timelines.
Strategic Opportunities
- Indian Urban Renewal:Smart Cities Mission funding in Mumbai, Bangalore, and Hyderabad is creating specification pathways for pre-engineered metal roofing in commercial and institutional verticals.
- Solar-Integrated Systems:Building-integrated photovoltaics convergence with standing-seam metal is opening new revenue pools for contractors capable of electrical interconnection work.
- Green Bond Finance:Sustainability-linked project finance vehicles are expanding contract ticket sizes for deep retrofit bundles that combine insulation, membrane, and daylighting upgrades.
Industry Challenges
- Installer Certification Gaps:Manufacturer-specific warranty programs for TPO and PVC membranes require trained applicator networks that remain thin outside major US metropolitan corridors.
- Embodied Carbon Accounting:Upstream suppliers struggle to provide verified EPDs for polymer-modified bitumen and adhesive formulations demanded by CSRD-aligned procurement teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Roofing Market |
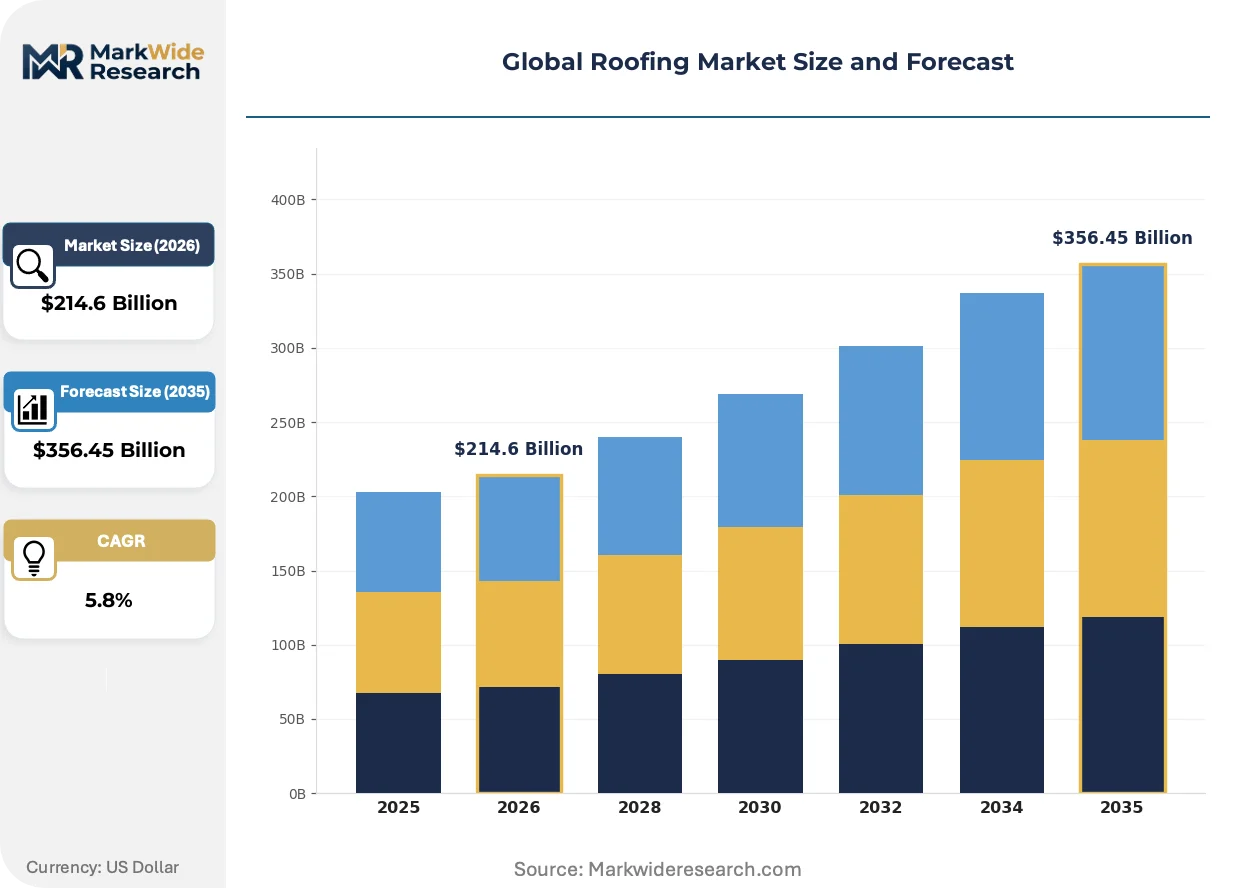
| Market Size in 2026 | $214.6 Billion |
| Market Size in 2035 | $356.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Asphalt Shingles, Metal, Tile, Slate Installation Method: Roof Replacement, New Construction, Retrofit, Repair End User: Residential, Commercial, Industrial, Institutional Sales Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | GAF Materials Corporation, Owens Corning, CertainTeed Corporation, Carlisle Companies Incorporated, IKO Industries Ltd., TAMKO Building Products LLC, Atlas Roofing Corporation, Johns Manville, Wienerberger AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Roofing Market Strategic Shifts
Digital specification tools and drone-based roof assessment platforms are compressing traditional design-bid-build timelines while shifting technical authority from field contractors to centralized engineering teams.
Building information modeling is virtualizing the traditional roof specification process. Large commercial developers and institutional owners now require 3D envelope models with embedded thermal bridging calculations before final membrane selection. This shift is compressing contractor influence over material choices while elevating manufacturer technical service teams into direct buyer relationships.
The EU F-Gas Regulation's phasedown schedule is forcing refrigerant-dependent spray polyurethane foam contractors toward water-blown and hydrocarbon-blown alternatives. Equipment retrofit costs and applicator retraining requirements are slowing adoption curves in Eastern European markets where legacy HFC systems remain economically entrenched despite regulatory deadlines.
Facility managers are consolidating roofing spend under national service agreements with single-source accountability. Third-party technical due diligence firms are displacing traditional bid-leveling by general contractors in US healthcare and retail verticals. This pattern concentrates volume with manufacturers capable of multi-site warranty administration and predictive maintenance analytics.
Global Roofing Market Segmentation
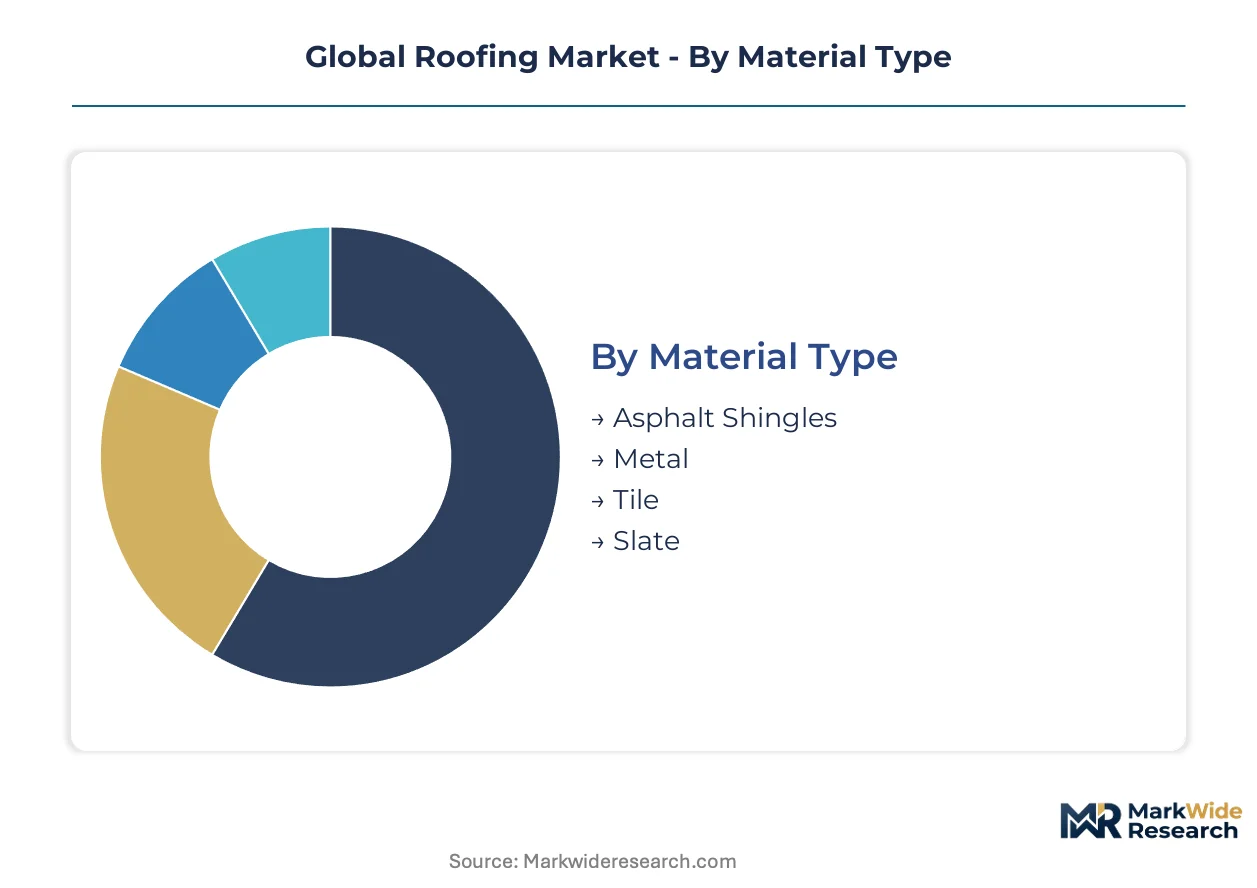
Material selection in roofing determines lifecycle cost, thermal performance, and regulatory compliance across divergent climate zones and building codes. Segmentation reveals how specification authority is migrating from contractors to building owners and institutional procurement teams.
Material Type:
The use-case spectrum spans from cost-sensitive residential re-roofing to century-scale heritage restoration where material longevity dominates capital planning.
- Asphalt Shingles:Fiberglass-reinforced asphalt laminates with ceramic granule surfacing dominate North American residential replacement cycles. Demand concentrates in United States suburban markets where contractor familiarity and low first-cost sustain specification inertia despite shorter service lives than alternatives.
- Metal:Standing-seam aluminum and steel panels with PVDF coatings deliver 40-60 year lifespans and Class A fire ratings. Adoption is accelerating in Florida and Texas coastal zones where insurance underwriters mandate enhanced wind uplift resistance.
- Tile:Clay and concrete interlocking units provide thermal mass and Mediterranean architectural compatibility. Italian and Spanish producers anchor European supply for heritage restoration projects.
- Slate:Natural metamorphic stone from Welsh and Vermont quarries commands premium positioning in institutional and luxury residential segments where century-scale durability justifies elevated installed costs.
The dominant share belongs to Asphalt Shingles, while Metal is closing the gap fastest.
Installation Method:
Volume distribution tracks building stock age, energy retrofit policy intensity, and new construction cyclicality across major economies.
- Roof Replacement:Removal of degraded membrane or shingle systems and installation of complete new assemblies. Germany and Poland are seeing elevated activity from EU Green Deal renovation wave targeting building envelope performance.
- New Construction:Primary installation on structures where roofing integrates with framing and insulation sequencing. United States multifamily housing starts and Indian commercial development are pulling membrane and metal panel specifications.
- Retrofit:Overlay or tear-off upgrades integrating insulation, air sealing, and cool-roof surfaces without full structural intervention. California Title 24 compliance mandates are concentrating demand in commercial building stocks.
- Repair:Localized remediation of storm damage, membrane punctures, or flashing failures. Weather volatility in United States Midwest and Southeast is expanding service contract volumes.
Replacement commands the largest installed base, though Retrofit is expanding most quickly as energy codes tighten.
End User:
Customer sophistication varies from price-sensitive homeowners to institutional owners with lifecycle cost modeling and sustainability mandates.
- Residential:Single-family and multifamily owners prioritizing curb appeal, warranty length, and insurance discounts. United States demand favors asphalt shingles; Australian and Mediterranean markets prefer tile.
- Commercial:Office, retail, and hospitality developers with flat-roof membrane specifications and national service agreement requirements. TPO and EPDM dominate low-slope applications.
- Industrial:Manufacturing and logistics facilities requiring corrosion-resistant metal panels and daylighting integration. Pre-engineered building systems specify standing-seam profiles.
- Institutional:Healthcare, education, and government owners with extended hold periods and EPD-driven procurement. Cool-roof and solar-ready specifications are standard.
Residential absorbs the highest unit volumes, yet Institutional is driving specification complexity fastest.
Sales Channel:
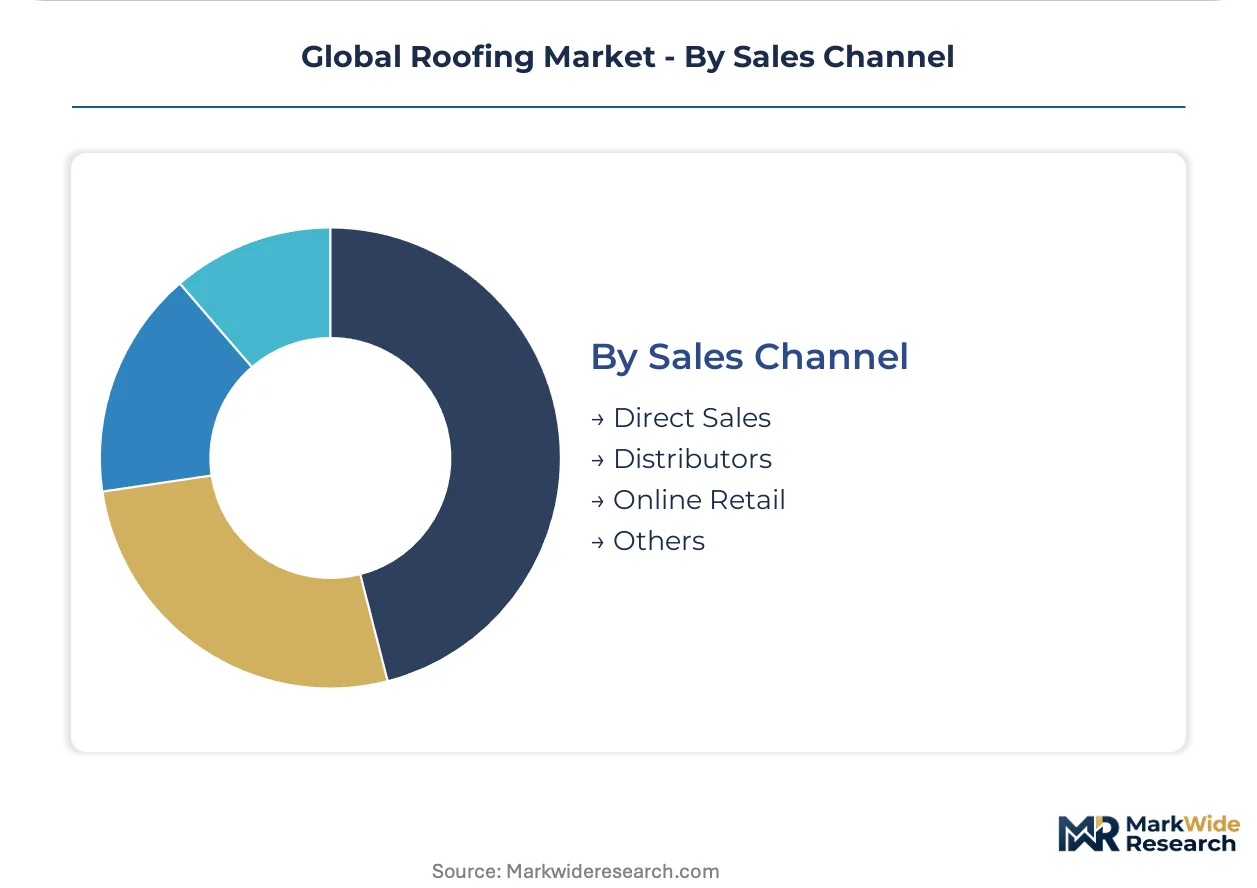
Channel structure reflects contractor loyalty programs, just-in-time logistics requirements, and the technical service intensity of membrane systems.
- Direct Sales:Manufacturer-to-contractor relationships for large commercial projects requiring engineered specifications and warranty administration. Major membrane producers maintain direct specification teams.
- Distributors:Regional and national networks stocking shingle, metal, and accessory inventories with local delivery and credit terms. United States two-step distribution remains dominant for residential asphalt products.
- Online Retail:E-commerce platforms for accessory products, tools, and small-quantity specialty materials. Growth is constrained by freight costs for bulky products and contractor preference for physical inspection.
- Others:Home center retail, cooperative buying groups, and manufacturer-owned retail locations serving specific geographies or customer segments.
Distributors retain the structural advantage in residential volume, while Direct Sales is gaining share in commercial specification control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal renovation wave incentives and California Title 24 cool-roof mandates are redirecting specification authority toward institutional procurement teams across major economies. National building code harmonization is compressing contractor discretion while elevating manufacturer technical service intensity.
United States
Insurance underwriters in Florida and Texas now mandate enhanced wind uplift ratings, accelerating standing-seam metal specifications in coastal zones. EPA Energy Star and California Title 24 drive reflective membrane demand in commercial re-roofing cycles. Houston and Miami metropolitan clusters concentrate contractor networks for high-performance installations.
Germany
The EU Green Deal's building renovation targets are triggering whole-envelope replacements in aging housing stocks across North Rhine-Westphalia and Bavaria. The national building energy ordinance (GEG) tightens thermal performance thresholds for roof assemblies. Berlin and Munich districts are seeing elevated specification activity for mineral wool insulated systems.
China
Dual carbon goals and urban renewal programs in tier-one cities are pulling demand for pre-engineered metal roofing in commercial verticals. The Ministry of Ecology and Environment enforces stricter VOC limits on adhesive and coating formulations. Yangtze River Delta manufacturing clusters around Shanghai supply membrane components for domestic retrofit programs.
India
Smart Cities Mission funding in Mumbai, Bangalore, and Hyderabad is creating specification pathways for metal roofing in institutional and commercial buildings. Bureau of Indian Standards certification requirements are tightening for fire-resistant membrane imports. Gujarat and Maharashtra industrial corridors concentrate domestic tile and metal panel fabrication capacity.
Poland
EU cohesion fund allocations for building efficiency are accelerating deep retrofit demand in Krakow and Warsaw residential districts. The national clean air program restricts solid fuel heating, indirectly elevating roof insulation specifications. Silesian and Lodz voivodeships concentrate renovation contractor networks serving aging multifamily housing stocks.
Global Roofing Market Competitive Environment
On the supply side, the industry is moderately consolidated with tiered specialization across material categories. Large-scale shingle and membrane producers dominate North American residential volume through distributor networks, while European clay tile and premium slate segments concentrate around heritage-region kiln operations. Three archetypes define competitive positioning: vertically integrated fiberglass suppliers controlling input costs, distributor-anchored brands leveraging contractor loyalty programs, and regional specialists in heritage restoration materials. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers seeking to secure mineral wool and bio-based membrane supply chains ahead of regulatory phaseouts.
Within the North American shingle and membrane tier, GAF Materials Corporation and Owens Corning exemplify scale-driven positioning through captive supply chain control and national distribution density. European clay and concrete tile concentration centers on Wienerberger AG, which anchors Central and Eastern European supply through regional kiln networks. These three entities represent distinct strategic archetypes: distributor-anchored volume leadership, vertically integrated input cost management, and regional heritage-material specialization.
| Leading Market Players |
|---|
| GAF Materials Corporation |
| Owens Corning |
| CertainTeed Corporation |
| Carlisle Companies Incorporated |
| IKO Industries Ltd. |
| TAMKO Building Products LLC |
| Atlas Roofing Corporation |
| Johns Manville |
| Wienerberger AG |
| Others |
Value Chain & Pricing Dynamics
Bitumen input volatility from crude oil price swings determines both pricing tier spreads and supply chain shape across the roofing industry. Cost compression in SBS-modified asphalt shingle tiers intensifies when petroleum feedstock indices spike, forcing mid-tier residential contractors toward economy-grade laminates or alternative material substitutions.
Pricing Analysis
Certification level creates the primary spread across roofing material tiers, with UL-listed Class A fire-rated systems and ASTM D3462-compliant fiberglass laminates commanding premiums over unrated economy grades. Three-tier pricing structure across premium, standard, and economy levels separates heritage-grade slate and standing-seam metal from commodity asphalt shingles. Pricing pressure stems from polymer-modified bitumen reformulation costs under REACH Annex XVII PFAS restrictions. Residential homeowners exhibit highest price sensitivity, while institutional procurement teams with lifecycle cost mandates tolerate elevated first costs for extended warranty coverage.
Supply Chain Analysis
Export-control regimes on fluorinated polymer precursors limit premium single-ply membrane flows from select European and Asian manufacturing hubs. Geographic supply concentration centers on China for stone-coated steel substrates, the United States for fiberglass mat production, and Germany for mineral wool insulation. Raw material dependencies span petroleum-derived bitumen, soda-lime glass fiber, and clay feedstock from specific quarry regions. Single-source vulnerability threatens TPO membrane availability during peak construction seasons. Distribution runs through two-step regional networks for residential shingles and direct manufacturer-to-contractor channels for commercial membrane specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital specification platforms and building information modeling interoperability are transforming roofing procurement into a platform-economics inflection, with centralized engineering teams displacing traditional contractor authority over material selection.
For Market Incumbents: Harden warranty administration capabilities against emerging solar-integrated system competitors who bundle electrical interconnection services. Consolidate applicator certification networks for TPO and PVC membranes to defend specification control in commercial verticals. Backward integration into mineral wool insulation production secures supply ahead of EU F-Gas Regulation-driven substitution curves.
For New Entrants and Emerging Players: Mid-market commercial buildings in Indian Smart Cities Mission corridors represent the most penetrable entry point for pre-engineered metal roofing specifications. Drone-based roof assessment platforms and predictive maintenance analytics offer service-revenue differentiation against established material suppliers. Partner with national facility management firms to bypass entrenched distributor relationships in United States healthcare and retail verticals.
For Investors and Strategic Acquirers: EU Green Deal renovation wave targets reshape the acquisition landscape toward deep-retrofit capability bundles combining insulation, membrane, and daylighting upgrades. Long-term viability hinges on embodied-carbon disclosure compliance and verified EPD availability across polymer-modified bitumen portfolios. Watch for carbon-border adjustment implementation as the inflection signal forcing supplier qualification criteria revisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Wool | Captive insulation supply secures margins under EU Green Deal thermal performance mandates. |
| Applicator Certification Network Expansion | Manufacturer-trained installer pools satisfy TPO warranty requirements in underserved metropolitan corridors. |
| Solar-Ready Standing-Seam System Launch | Building-integrated photovoltaic compatibility opens electrical contractor revenue pools. |
| Predictive Maintenance Analytics Platform | IoT-enabled roof monitoring supports national service agreement consolidation under facility managers. |
| Bio-Based Membrane Formulation Investment | Hydrocarbon-blown alternatives position ahead of HFC refrigerant phaseout deadlines. |
Study Parameters
Cross-validation between primary interviews with roofing contractors, membrane specification engineers, distributor procurement managers, and facility management directors anchors the qualitative findings. Secondary sources include customs and trade data on bitumen and fiberglass imports, SEC 10-K filings from listed building material producers, EPA Energy Star certification databases, and EU ECHA regulatory submission records. Bottom-up project pipeline analysis and top-down construction spending forecasts triangulate market sizing.
Calibration against historical replacement cycle data and new construction permit volumes informs the projection framework across the analysis window. Segmentation dimensions encompass material type, installation method, end-user vertical, and sales channel structure. CAGRs derive from fitted growth curves applied to disclosed manufacturer capacity expansions and national building code adoption timelines. Energy retrofit policy intensity and insurance underwriting requirement shifts serve as industry-specific forecast inputs.
Practitioners should monitor crude oil price volatility, REACH PFAS restriction enforcement, and carbon-border adjustment implementation for early signals. Forecasts reflect assumptions on regulatory timeline adherence and contractor network expansion rates. Material shifts in EU Green Deal funding allocation or California Title 24 code stringency would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Gypsum Board Market
Building & Construction Materials
Pipe Hanger Market
Building & Construction Materials
Precast Concrete Members Market
Building & Construction Materials
Poland Cement Market
Building & Construction Materials
Steel Rebar Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Timber Construction Connectors Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Branched Reinforced Fittings Market
Building & Construction Materials
Porcelain Tiles Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Italy Ceramic Tiles Market
Building & Construction Materials
GRC Conduit Fittings Market
Building & Construction Materials
Global Panelized and Modular Building System Market
Building & Construction Materials
Soil Stabilization Market