
 Bronchitis Market | 2026-2036
Bronchitis Market Size, Share, and Industry Trends Forecast 2026-2036
Bronchitis Market Analysis
Digital biomarker integration into respiratory diagnostics is reconfiguring how bronchitis severity gets stratified before therapy selection. AstraZeneca leverages its inhaled corticosteroid portfolio to sustain leadership in chronic bronchitis maintenance. GlaxoSmithKline anchors its position through long-acting bronchodilator combinations that dominate hospital formularies. Novartis differentiates via biologic pathways for refractory eosinophilic bronchitis subtypes.
Bronchitis denotes inflammation of the bronchial tubes, typically involving mucosal edema, increased goblet cell secretion, and airflow obstruction measurable by forced expiratory volume in one second. The condition serves clinical and commercial purposes across acute infection management, chronic obstructive pulmonary disease exacerbation prevention, and occupational respiratory disability assessment. Bronchodilators and corticosteroids command the largest current revenue pools given their entrenched reimbursement status across hospital and outpatient settings, while inhalation administration routes attract disproportionate R&D investment due to superior local lung targeting and reduced systemic adverse effects compared with oral or injectable alternatives.
FDA pharmacovigilance mandates and EMA Good Manufacturing Practice standards govern active pharmaceutical ingredient purity, inhaler device bioequivalence, and post-market respiratory adverse event reporting across developed markets. WHO Essential Medicines List inclusion criteria shape national procurement priorities and generic substitution policies in lower-income health systems. Stakeholders must monitor evolving EPA air quality standards and their downstream impact on bronchitis incidence trajectories, alongside CMS and national payer decisions on digital therapeutics reimbursement for remote respiratory monitoring.
Market Dynamics
FDA pharmacovigilance tightening and EMA Good Manufacturing Practice standards are compressing respiratory drug approval timelines while forcing manufacturers toward digital biomarker integration for pre-therapy patient stratification.
Growth Catalysts
- EPA Air Quality Enforcement:Stricter particulate matter standards in the United States elevate pollution-linked bronchitis incidence and expand addressable patient populations for maintenance therapies.
- Japan's Super-Aged Society:METI-directed healthcare infrastructure investments prioritize chronic respiratory disease management as hospital-based acute care programs scale bronchitis protocols.
- Digital Biomarker Platforms:Remote respiratory monitoring technologies enable severity-based therapy selection before hospital admission, reducing emergency department burden.
Market Restraints
- Active Pharmaceutical Input Concentration:Corticosteroid and bronchodilator API production clusters in India and China create supply vulnerability during export restriction episodes.
- Inhaler Device Bioequivalence Costs:FDA and EMA requirements for demonstrating equivalent lung deposition between reference and generic products extend development timelines and capital requirements.
- Oral Antibiotic Substitution:Acute bacterial bronchitis treatment faces pressure from cheap generic azithromycin and amoxicillin-clavulanate prescriptions in outpatient settings.
Strategic Opportunities
- Germany's E-Health Act Implementation:Digital therapeutics reimbursement pathways open for remote respiratory monitoring applications in statutory health insurance coverage.
- Biologic-Refractory Subtyping:Eosinophil-guided patient segmentation creates addressable niches for targeted monoclonal antibody development beyond standard corticosteroid maintenance.
- WHO Essential Medicines Procurement:National tender systems in lower-income health systems favor inhalation generic substitution, creating volume scale for device-agnostic API suppliers.
Industry Challenges
- Respiratory Formulation Talent Scarcity:Inhalation product development requires specialized expertise in particle engineering and device mechanics that outpaces current training pipeline output.
- Post-Market Surveillance Burden:FDA adverse event reporting mandates for respiratory products demand dedicated pharmacovigilance infrastructure that strains mid-tier manufacturer resources.
- Legacy Nebulizer System Integration:Hospital formularies maintain entrenched compressor-nebulizer protocols that resist rapid substitution by mesh or soft-mist alternatives despite superior deposition profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bronchitis Market |
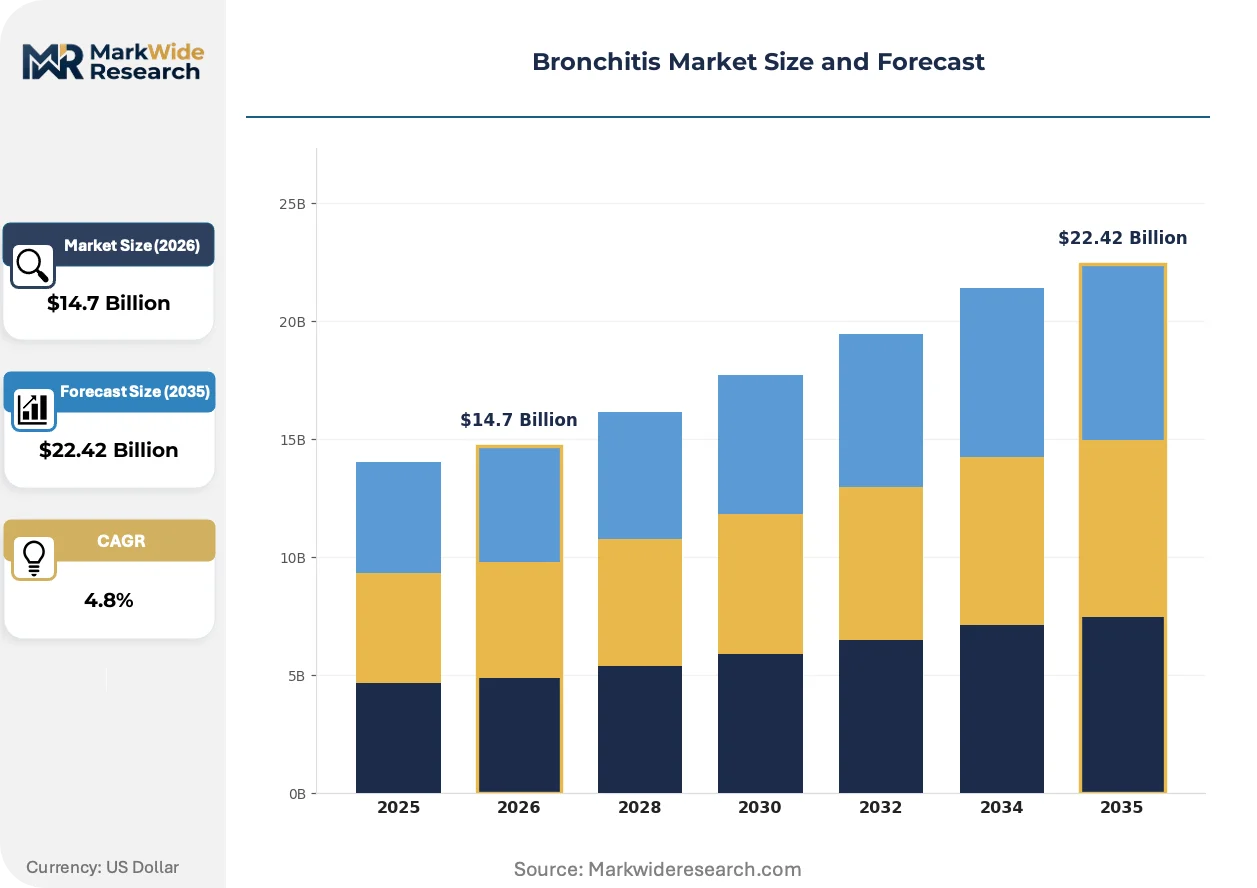
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bronchodilators, Corticosteroids, Antidepressants, Antibiotics End User: Hospitals, Outpatient Clinics, Home Care, Diagnostic Labs Administration Route: Inhalation, Oral, Injectable, Transdermal Severity Level: Mild, Moderate, Severe, Chronic |
| Companies Covered | AstraZeneca, GlaxoSmithKline, Novartis AG, Pfizer Inc., Sanofi, Boehringer Ingelheim, Dr. Reddy's Laboratories Ltd., Melinta Therapeutics, Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bronchitis Market Emerging Trajectories
Respiratory diagnostics are pivoting from symptom-based assessment toward molecular and digital stratification, compressing the gap between diagnosis and targeted therapy initiation while reshaping how pharmaceutical portfolios align with patient subtypes.
Smart inhalers with embedded sensors and Bluetooth connectivity are rendering obsolete manual adherence monitoring and physician-reported outcome measures in chronic bronchitis management. Hospital systems in Germany and Japan are deploying these devices at scale for maintenance therapy oversight. The technology is rendering obsolete traditional pharmacy benefit management approaches that lacked real-world usage data.
EMA's Medical Device Regulation and FDA's digital health software guidance are converging to create dual-jurisdiction compliance requirements for connected inhaler platforms. Manufacturers must now satisfy both notified body CE marking and FDA 510(k) software validation for integrated drug-device combinations. European hospital procurement tenders increasingly specify MDR-certified connected devices, forcing portfolio reconfiguration for suppliers lacking EU authorized representatives.
Specialized respiratory clinics are consolidating previously dispersed bronchitis care into dedicated airway centers that bundle diagnosis, therapy initiation, and remote monitoring under single reimbursement episodes. This model displaces fragmented pulmonologist-primary care handoffs in the United States and Japan. Germany's Diagnosis-Related Group system is adapting to accommodate these bundled payment structures for complex chronic respiratory cases.
Bronchitis Market Segmentation
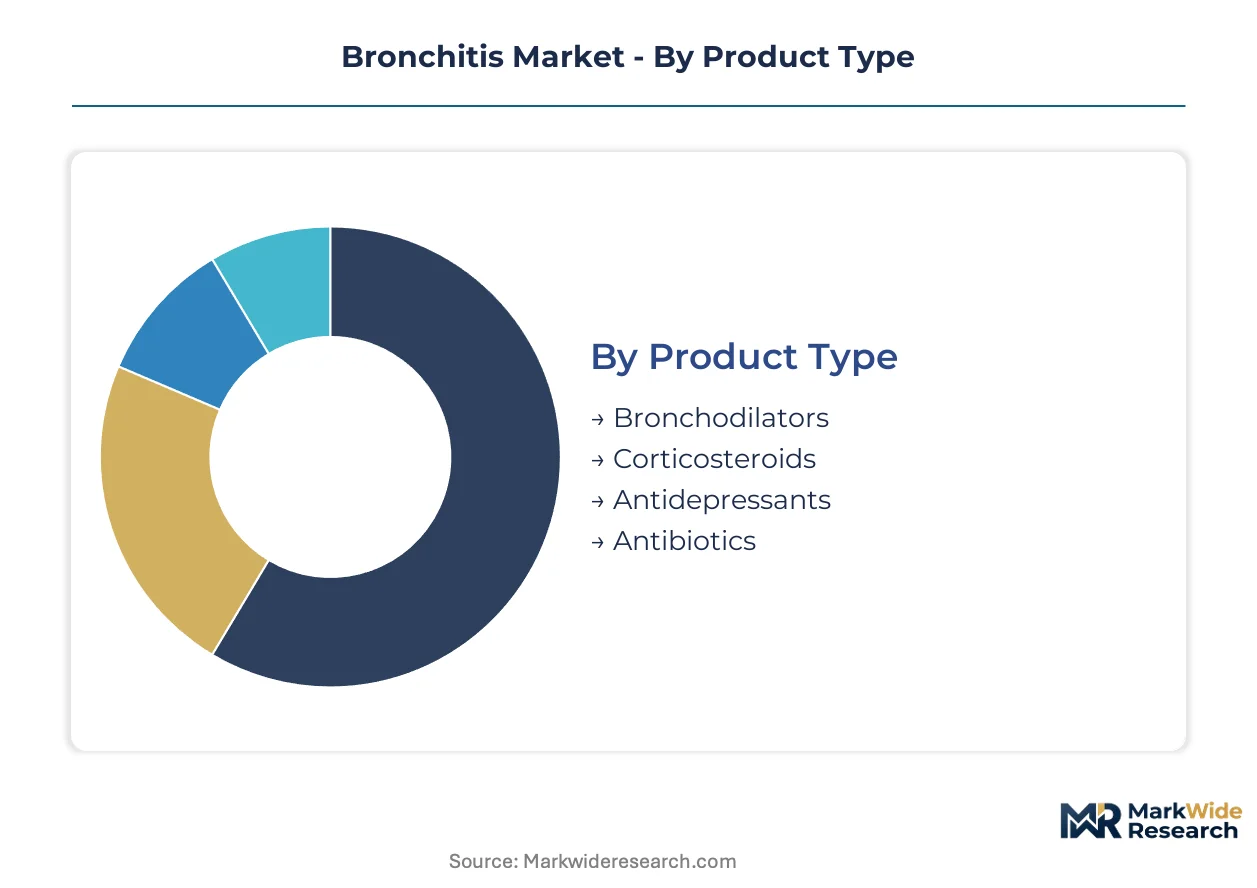
Segmentation in the bronchitis market determines reimbursement pathways, device selection, and pharmacovigilance intensity. Product type and administration route segments carry the steepest R&D investment cycles, while severity stratification governs therapy escalation protocols across hospital and outpatient settings.
Product Type:
Bronchodilators and corticosteroids turn inventory fastest due to chronic maintenance prescriptions, whereas antibiotics cycle more slowly around acute exacerbation seasons.
- Bronchodilators:Beta-agonist and anticholinergic formulations relax airway smooth muscle through cyclic AMP modulation or muscarinic receptor antagonism. Demand concentrates in United States hospital formularies where long-acting combinations dominate maintenance protocols for chronic bronchitis patients. FDA bioequivalence requirements for generic substitutions extend development timelines for new molecular entities.
- Corticosteroids:Inhaled glucocorticoids suppress airway inflammation via NF-kappaB pathway inhibition and cytokine transcription reduction. Germany's statutory health insurance system favors these for moderate-to-severe cases under Diagnosis-Related Group reimbursement structures. EMA Good Manufacturing Practice standards for active pharmaceutical ingredient purity create compliance barriers for Indian and Chinese API suppliers.
- Antidepressants:Tricyclic and SSRI classes address cough hypersensitivity syndromes refractory to standard bronchodilator therapy.
- Antibiotics:Macrolide and fluoroquinolone prescriptions target acute bacterial exacerbations with narrow therapeutic indices requiring renal monitoring.
Bronchodilators anchor the volume base while corticosteroids gain share at the steepest rate among maintenance therapies.
End User:
Cost tier stratification separates capital-intensive hospital systems from lean outpatient and home-based delivery models.
- Hospitals:Acute care programs manage severe exacerbations requiring nebulized bronchodilator delivery and continuous pulse oximetry monitoring. Japan's METI-directed infrastructure investments prioritize these facilities for chronic respiratory disease bundled payments.
- Outpatient Clinics:Primary care and pulmonology practices initiate step-therapy protocols with metered-dose inhalers before hospital referral. United States Medicare Part B reimbursement shapes prescribing patterns through physician-administered drug payment rates.
- Home Care:Remote respiratory monitoring platforms enable post-discharge adherence tracking and exacerbation early warning.
- Diagnostic Labs:Spirometry and fractional exhaled nitric oxide testing stratify severity before therapy selection in Germany's E-Health Act implementation zones.
Hospitals command the highest per-patient revenue while home care represents the most rapidly expanding addressable base.
Administration Route:
Volume concentration favors inhalation devices given superior lung deposition and reduced systemic exposure compared with systemic alternatives.
- Inhalation:Dry powder and soft-mist devices achieve 15-40% lung deposition versus 5-10% for pressurized metered-dose inhalers. Germany and Japan hospital procurement tenders increasingly specify connected inhalers with Bluetooth adherence monitoring under MDR certification requirements.
- Oral:Tablets and capsules serve acute bacterial bronchitis and corticosteroid burst protocols where patient dexterity limits inhaler technique.
- Injectable:Intravenous bronchodilators and corticosteroids reserve for intensive care unit admissions with respiratory failure.
- Transdermal:Patch delivery systems remain experimental for bronchodilator absorption through dermal vasculature.
Inhalation routes dominate prescription volume while injectable applications command premium pricing in critical care segments.
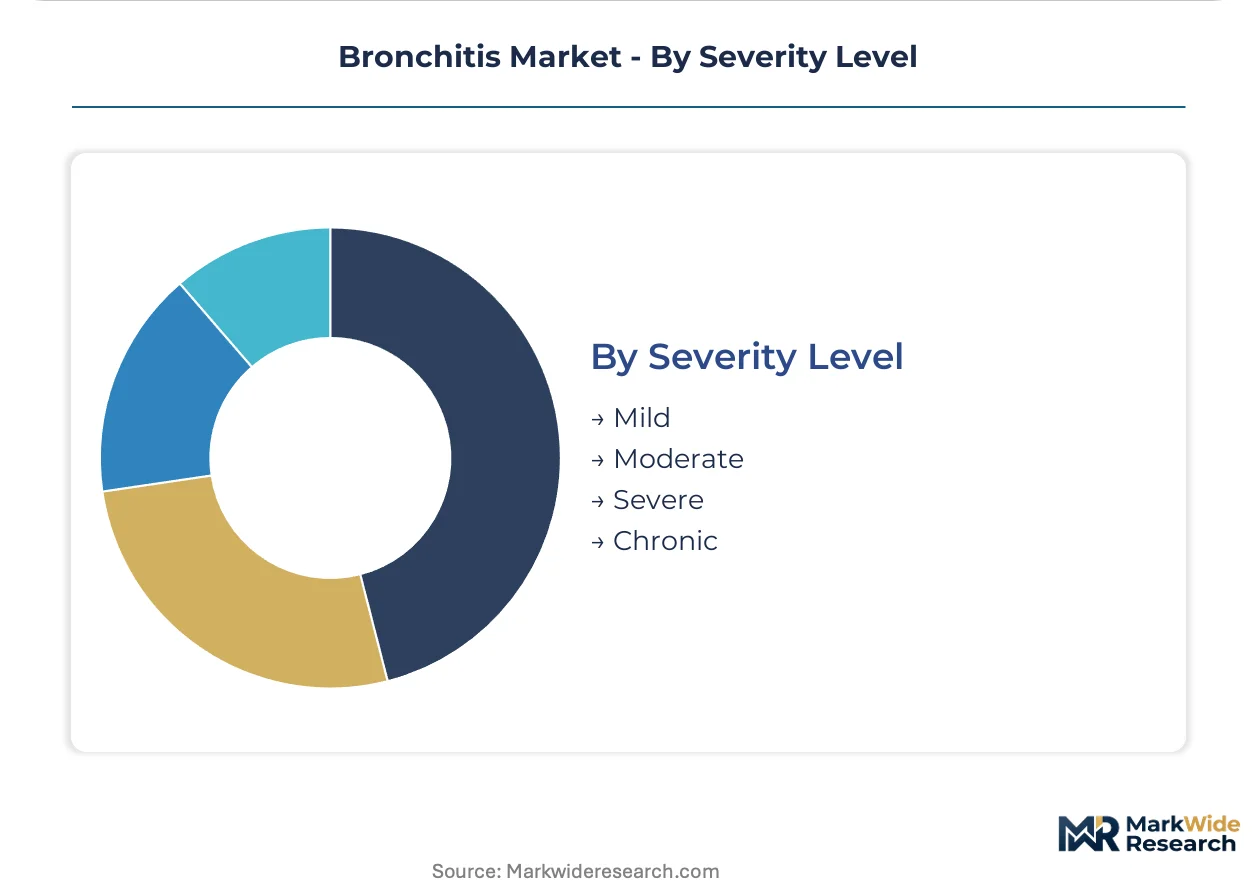
Severity Level:
Patient stratification by symptom burden and airflow obstruction magnitude determines therapy intensity and monitoring frequency.
- Mild:Intermittent symptoms with FEV1 above 80% predicted receive short-acting bronchodilator rescue therapy. United States primary care settings manage these cases through pharmacy benefit manager prior authorization pathways.
- Moderate:Daily symptoms and FEV1 50-80% predicted warrant long-acting bronchodilator maintenance with or without inhaled corticosteroid combination.
- Severe:FEV1 below 50% predicted with frequent exacerbations requires triple therapy and referral to specialized respiratory clinics in Japan's super-aged society care networks.
- Chronic:Persistent airflow obstruction with systemic inflammation markers qualifies for biologic pathway evaluation under eosinophil-guided subtyping protocols.
Moderate severity cases constitute the largest treated population while severe and chronic categories drive the most aggressive therapy escalation and specialty referral rates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement managers and respiratory clinic directors concentrate purchasing power in markets with aging demographics and stringent air quality enforcement. Buyers prioritize connected inhaler platforms and bundled reimbursement pathways over standalone pharmaceutical contracts.
United States
EPA particulate matter standards and Medicare Part B reimbursement structures drive demand for maintenance bronchodilator therapies. FDA pharmacovigilance mandates tighten post-market surveillance requirements for inhaled corticosteroid products. The Cleveland Clinic respiratory network and Mayo Clinic airway centers deploy smart inhaler adherence monitoring at scale.
Germany
Statutory health insurance Diagnosis-Related Group reimbursement favors step-therapy protocols with inhaled corticosteroid combinations. EMA Medical Device Regulation certification requirements shape hospital procurement tenders for connected inhaler platforms. The Rhine-Ruhr industrial corridor's specialized respiratory clinics consolidate previously fragmented pulmonologist-primary care handoffs.
Japan
METI-directed healthcare infrastructure investments prioritize chronic respiratory disease management in super-aged society care networks. PMDA inhaler device bioequivalence standards extend generic substitution timelines. Tokyo and Osaka hospital systems scale bronchitis acute care protocols with bundled payment structures for complex cases.
India
CDSCO active pharmaceutical ingredient purity standards and WHO Essential Medicines List procurement priorities shape national tender systems for generic bronchodilator substitution. The Hyderabad-Visakhapatnam API manufacturing belt supplies corticosteroid and bronchodilator inputs to domestic formulators and export markets.
United Kingdom
NHS England integrated care systems bundle respiratory diagnostics with therapy initiation under single reimbursement episodes. MHRA post-Brexit regulatory divergence from EMA creates dual compliance tracks for inhaler device manufacturers. The Manchester and Birmingham respiratory networks deploy remote monitoring platforms for post-discharge adherence tracking.
Bronchitis Market Vendor Landscape
Channel-controlling players compete with product-specialist players across hospital formulary placement and outpatient clinic prescribing influence. The market structure concentrates around three archetypes: integrated respiratory portfolio holders with device-drug combinations, API-to-formulation vertical specialists, and biologic pathway developers for refractory subtypes. Dominant competitive moves include strategic partnerships for digital biomarker integration and geographic licensing for inhaler device platforms.
Within the integrated portfolio tier, AstraZeneca and GlaxoSmithKline occupy positions as archetypal respiratory franchise holders with entrenched hospital formulary relationships. Novartis exemplifies the biologic specialization vector through eosinophil-guided patient segmentation approaches. Among European-origin conglomerates, Boehringer Ingelheim and Sanofi represent diversified pharmaceutical structures with respiratory maintenance portfolios.
| Leading Market Players |
|---|
| AstraZeneca |
| GlaxoSmithKline |
| Novartis AG |
| Pfizer Inc. |
| Sanofi |
| Boehringer Ingelheim |
| Dr. Reddy's Laboratories Ltd. |
| Melinta Therapeutics |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
The Mumbai-JNPT pharmaceutical freight corridor transmits API shipping cost volatility directly into corticosteroid and bronchodilator price differentiation across European and North American hospital procurement tiers. FDA bioequivalence certification requirements and EMA Medical Device Regulation compliance costs stratify inhaler device pricing into premium-connected, standard-mesh, and economy-nebulizer segments that mirror upstream API sourcing concentration.
Pricing Analysis
Cost-plus contracts with API indexation to Indian and Chinese corticosteroid feedstock benchmarks dominate long-term hospital formulary agreements. Price differentiation separates MDR-certified connected inhalers from standard dry-powder devices through Bluetooth adherence monitoring bundling and software validation tiers. Pricing pressure stems from WHO Essential Medicines List procurement favoring generic bronchodilator substitution in lower-income tenders. Outpatient primary care settings exhibit highest price sensitivity due to pharmacy benefit manager prior authorization pathways, while intensive care units demonstrate lowest sensitivity given emergency procurement protocols.
Supply Chain Analysis
Upstream beclomethasone and salmeterol feedstock production clusters in the Hyderabad-Visakhapatnam API belt and select Chinese pharmaceutical manufacturing zones. Corticosteroid active pharmaceutical ingredients, lactose carrier powders for dry-powder formulations, and propellant gases for metered-dose devices constitute critical input dependencies. Single-source vulnerability concentrates in Indian export restriction episodes that disrupted European hospital formularies during recent regulatory enforcement periods. Distribution runs through hospital group purchasing organizations in the United States, statutory health insurance tender systems in Germany, and METI-directed procurement platforms in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected inhaler platforms are reconfiguring bronchitis care into interoperable ecosystems where device adherence data, electronic health record integration, and remote monitoring reimbursement pathways determine competitive viability rather than standalone pharmaceutical efficacy alone.
For Market Incumbents: Insulate formulary position through captive API supply agreements with Indian manufacturers and accelerated MDR certification timelines for next-generation connected devices. Digital biomarker integration capabilities represent the critical defensive lever against biologic pathway specialists encroaching on severe chronic segments. FDA pharmacovigilance infrastructure investments strain mid-tier competitors and consolidate purchasing influence among vertically integrated respiratory portfolio holders. For New Entrants and Emerging Players: Biologic-refractory eosinophilic bronchitis subtypes in Japan's super-aged society care networks represent the most penetrable entry point for targeted monoclonal antibody development. Germany's E-Health Act digital therapeutics reimbursement pathways offer secondary white-space for remote respiratory monitoring software platforms. Go-to-market positioning should emphasize eosinophil-guided patient stratification protocols and specialized respiratory clinic partnerships over primary care channel competition. For Investors and Strategic Acquirers: Inhalation formulation specialists with particle engineering expertise and device mechanics capabilities command premium acquisition multiples given respiratory talent scarcity and extended FDA bioequivalence timelines. Long-term viability hinges on portfolio exposure to maintenance therapy chronicity rather than acute antibiotic substitution vulnerability. PMDA inhaler device bioequivalence standard harmonization with FDA pathways signals regulatory convergence that would accelerate generic substitution timelines and compress device-centric margin structures.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Biomarker Platform Integration | Remote respiratory monitoring enables severity-based therapy selection before hospital admission, reducing emergency department burden. |
| API Supply Agreement Diversification | Captive sourcing from Indian and Chinese manufacturers insulates against export restriction episodes and formulary disruption. |
| MDR Certification Acceleration | European hospital procurement tenders increasingly specify connected inhaler compliance, forcing portfolio reconfiguration for EU market access. |
| Eosinophil-Guided Patient Stratification | Biologic pathway development for refractory subtypes creates addressable niches beyond standard corticosteroid maintenance. |
| Specialized Respiratory Clinic Partnership | Bundled reimbursement structures in Japan and Germany consolidate previously fragmented pulmonologist-primary care handoffs. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with hospital formulary directors, respiratory clinic physicians, pharmaceutical regulatory affairs leads, and inhaler device procurement managers; and secondary validation through FDA pharmacovigilance filings, EMA Medical Device Regulation submissions, CMS Medicare Part B reimbursement databases, and WHO Essential Medicines List procurement records. Bottom-up patient population modeling and top-down pharmaceutical revenue triangulation anchored volume and value estimates.
Forecast inputs considered bronchodilator and corticosteroid product type segments, inhalation versus oral administration routes, and severity-stratified therapy escalation protocols across hospital, outpatient, and home care settings. CAGRs were derived from epidemiological incidence projections, reimbursement pathway expansion trajectories, and digital therapeutics adoption curves. EPA air quality standard enforcement timelines and METI-directed healthcare infrastructure investments shaped regional demand assumptions.
Practitioners should monitor FDA adverse event reporting mandate intensification, EMA GMP standard updates for API purity, and PMDA inhaler bioequivalence guideline revisions for early signals of regulatory-driven market restructuring. Quarterly review of hospital procurement tender specifications, connected inhaler MDR certification timelines, and Indian API export policy shifts is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Herpes Simplex Virus Treatment Market
Infectious Disease
Japanese Encephalitis Market
Infectious Disease
Typhoid Fever Vaccine Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Acute Vulvovaginal Candidiasis Treatment Market
Infectious Disease
Burkholderia Infections Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Italy Infectious Disease in-Vitro Diagnostics Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Chronic Hepatitis B (CHB) Market
Infectious Disease
Coxsackievirus Infections Treatment Market
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Retropharyngeal Abscess Market
Infectious Disease
Bacterial Conjunctivitis Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market