
 Global Nebulizers Market | 2026-2036
Global Nebulizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nebulizers Market Foresight
Consolidation among home care distributors is repositioning procurement leverage toward large respiratory equipment chains and away from fragmented clinic networks. PARI GmbH leverages German engineering standards to dominate European pediatric nebulizer segments. Omron Healthcare anchors Asian market access through localized manufacturing and pharmacy channel control. Koninklijke Philips competes on connected health platforms that integrate nebulizer therapy data with remote monitoring systems.
A nebulizer converts liquid medication into aerosol droplets for direct lung delivery, typically producing particles between one and five micrometers to optimize alveolar deposition. Jet nebulizers operate via compressed gas through a Venturi nozzle, while vibrating mesh systems employ a piezoelectric element to force medication through microscopic apertures, yielding higher respirable fractions with reduced waste. Mesh nebulizers capture the fastest-growing product category as patients prioritize silent, battery-operated portability over traditional pneumatic alternatives. Pneumatic technology retains volume leadership in institutional settings where cost sensitivity outweighs convenience premiums.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access barriers for manufacturers seeking dual-territory approval. ISO 27427 standards for nebulizing systems establish performance benchmarks that differentiate premium devices from unvalidated competitors. Stakeholders must monitor reimbursement code revisions by CMS and national health technology assessment bodies, as coverage determinations for home nebulization directly influence patient out-of-pocket decisions and manufacturer volume forecasts.
Market Dynamics
Portable mesh nebulizers are displacing pneumatic systems in home care settings, compressing replacement cycles and forcing manufacturers to reconfigure supply chains around battery chemistry and micro-pump sourcing rather than compressor fabrication.
Growth Catalysts
- EU MDR conformity pathways:Stricter post-market surveillance requirements for Class IIa respiratory devices are filtering out unvalidated competitors and concentrating demand among ISO 27427-certified manufacturers.
- COPD patient cohort expansion:Aging populations in Germany, Japan, and the United States are sustaining replacement demand for home nebulization equipment as chronic respiratory disease prevalence climbs.
- Connected health platforms:Integration of nebulizer therapy data with remote patient monitoring systems is expanding reimbursement eligibility under CMS remote therapeutic monitoring codes.
Market Restraints
- Piezoelectric element supply:Concentration of precision aperture mesh manufacturing in East Asian electronics clusters creates single-source vulnerability for vibrating mesh device producers.
- FDA 510(k) timeline compression:Respiratory device clearance backlogs are extending product launch windows by 8-14 months for dual-territory applicants.
- Dry powder inhaler substitution:DPI technology is capturing maintenance therapy prescriptions previously directed toward nebulized bronchodilators in stable COPD populations.
Strategic Opportunities
- Indian home care penetration:Underpenetrated rural respiratory therapy markets present white space for battery-operated mesh devices distributed through pharmacy chains.
- US IRA price negotiation spillover:Medicare drug pricing reforms are redirecting patient cost sensitivity toward durable medical equipment with transparent out-of-pocket structures.
- Telehealth-integrated adherence monitoring:Convergence of Bluetooth-enabled nebulizers with synchronous video consultation platforms is opening subscription-based service models.
Industry Challenges
- Biocompatibility validation:FDA extractables and leachables testing for polymer medication reservoirs is forcing reformulation of legacy device architectures.
- Cross-border warranty service:Fragmented service networks for portable devices are generating customer satisfaction gaps that erode brand equity in direct-to-consumer channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nebulizers Market |
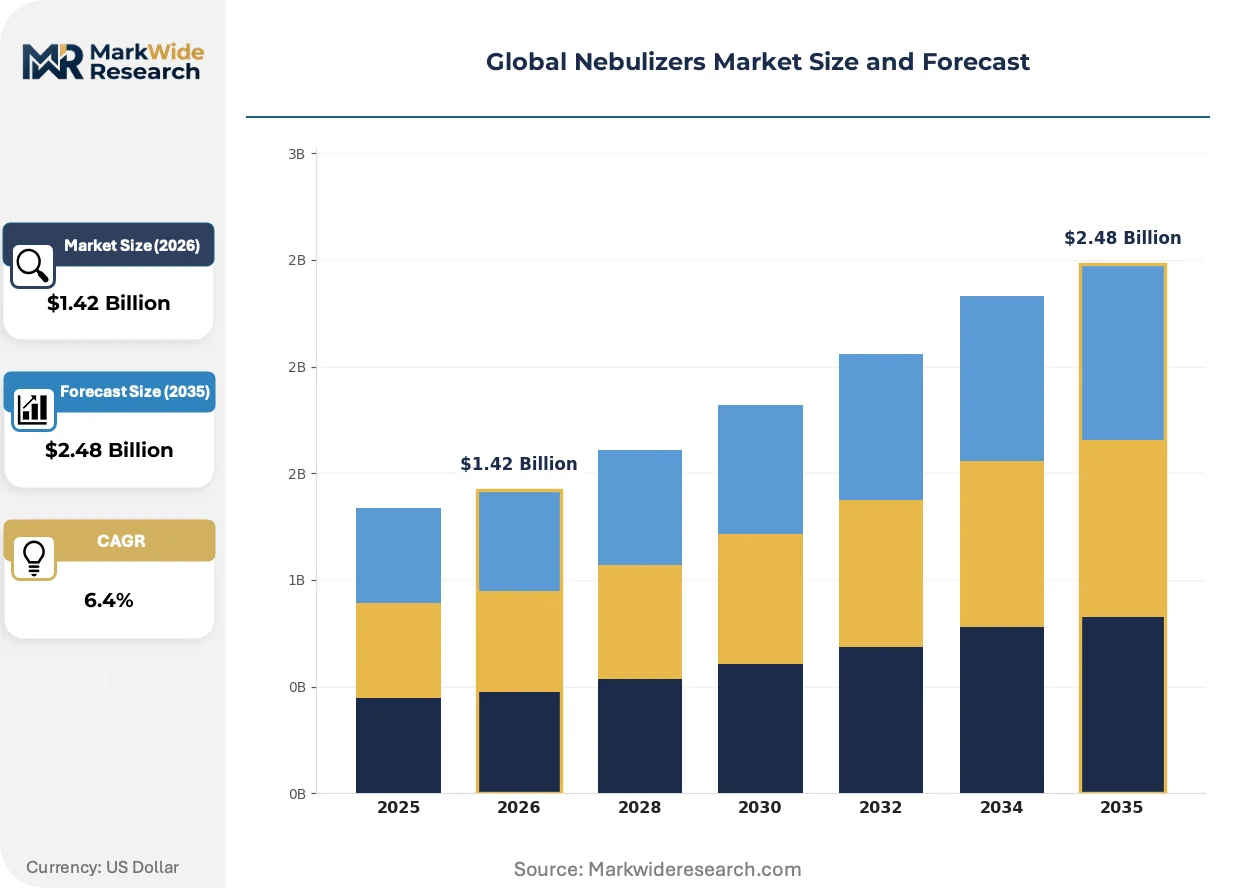
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Jet Nebulizers, Ultrasonic Nebulizers, Mesh Nebulizers, Breath-Actuated Nebulizers Technology: Pneumatic, Piezoelectric, Vibrating Mesh, Ultrasonic Wave Application: Asthma Management, Chronic Obstructive Pulmonary Disease, Cystic Fibrosis, Bronchitis Treatment End User: Home Care Patients, Pulmonary Clinics, Respiratory Therapy Centers, Long-Term Care Facilities |
| Companies Covered | Omron Healthcare, Koninklijke Philips, PARI GmbH, Drive DeVilbiss Healthcare, GE Healthcare, Allied Healthcare Products, Aerogen, GF Health Products, Trudell Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nebulizers Market Shifts & Advancements
Active materials science and regulatory digitization are compressing product development timelines while reshaping how respiratory therapy devices integrate into broader care delivery ecosystems.
Vibrating mesh technology is expanding into pediatric and geriatric home care segments where noise sensitivity and hand-strength limitations previously constrained pneumatic device adoption. Caregivers in Japan and Germany are prioritizing silent, single-button operation over treatment speed, compressing demand for compressor-based systems in these demographics. The shift is expanding addressable market boundaries beyond traditional COPD populations into asthma management and cystic fibrosis maintenance protocols.
EU MDR technical documentation requirements for nebulizing systems are forcing manufacturers to maintain electronic quality management systems with post-market clinical follow-up capabilities. The regulation is compressing competitive margins for mid-tier producers lacking in-house regulatory affairs infrastructure. German and Swiss manufacturers with established notified body relationships are capturing volume from competitors facing delayed conformity assessment timelines.
Pharmacy channel consolidation is compressing distributor count in United States and German markets, concentrating procurement leverage among three national respiratory equipment chains. Independent clinic networks are losing volume to centralized purchasing organizations with direct manufacturer relationships. The pattern is most visible in Medicare Advantage plan service territories where preferred supplier arrangements lock out fragmented regional distributors.
Global Nebulizers Market Segmentation
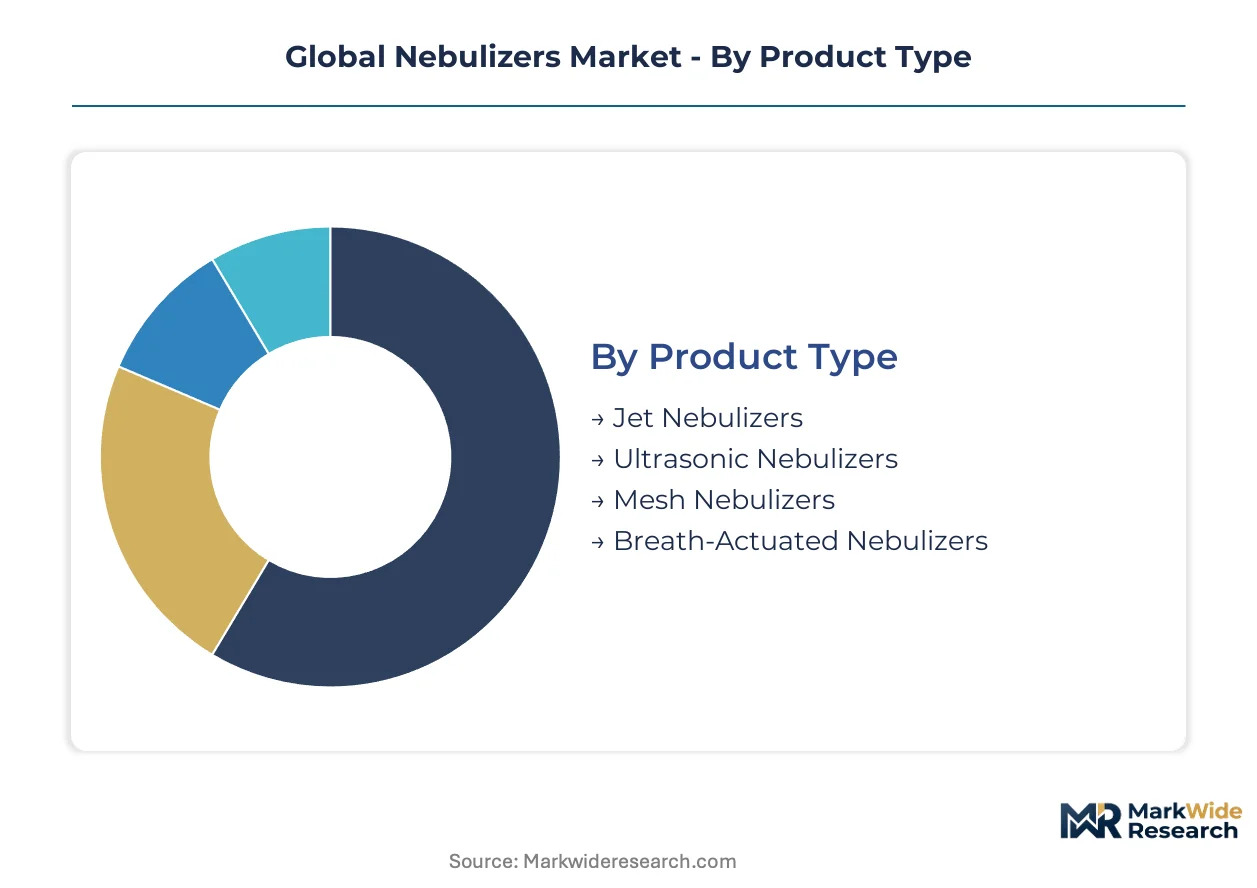
Nebulizer market segmentation reveals how device specifications align with distinct clinical requirements and care delivery settings. Technology choices, application contexts, and end-user capabilities collectively determine procurement patterns and manufacturer positioning strategies.
Product Type:
Device architecture defines aerosol generation mechanics, particle size distribution, and operational noise profiles.
- Jet Nebulizers:Compressed gas forced through a Venturi nozzle produces therapeutic aerosol from liquid medication. Institutional purchasing in the United States and Germany favors these systems for their durability and low per-unit cost in high-volume respiratory therapy centers.
- Mesh Nebulizers:Piezoelectric elements drive medication through precision apertures, yielding higher respirable fractions with near-silent operation. Japanese home care patients and pediatric caregivers prioritize these devices for nighttime administration and travel portability.
- Ultrasonic Nebulizers:High-frequency sound waves generate aerosol without mechanical compression. Long-term care facilities deploy these for patients requiring extended treatment sessions.
- Breath-Actuated Nebulizers:Inhalation-triggered delivery synchronizes aerosol release with patient breathing patterns. Pulmonary clinics prescribe these for coordinated bronchodilator therapy.
Jet nebulizers lead on scale; mesh nebulizers lead on momentum.
Technology:
Core energy conversion mechanisms differentiate performance benchmarks and regulatory validation pathways.
- Pneumatic:Compressed air or oxygen drives medication atomization through established mechanical principles. German engineering standards dominate manufacturing quality for these systems, with ISO 27427 certification serving as the procurement filter across European hospital networks.
- Vibrating Mesh:Micron-scale aperture plates oscillated by piezoelectric crystals generate consistent particle sizes with minimal residual volume. Battery chemistry innovations from South Korean suppliers enable the portable form factors gaining share in United States Medicare Advantage home care programs.
- Piezoelectric:Direct electrical-to-mechanical energy conversion without aperture plates. Japanese manufacturers integrate these elements into compact devices for asthma management in school-age populations.
- Ultrasonic Wave:Piezoelectric transducers generate high-frequency mechanical vibration in liquid reservoirs. These systems face FDA scrutiny over heat generation during extended cystic fibrosis treatment protocols.
Pneumatic technology anchors installed base; vibrating mesh commands expansion capital.
Application:
Disease-specific aerosol delivery requirements shape device selection across acute and maintenance therapy contexts.
- Chronic Obstructive Pulmonary Disease:Long-acting bronchodilator administration demands reliable daily nebulization. Aging patient cohorts in Germany and Japan sustain replacement cycles for home-deployed equipment.
- Asthma Management:Rescue medication delivery emphasizes rapid onset and patient-controlled dosing. Pediatric segments in the United States drive demand for silent, portable mesh alternatives to compressor-based systems.
- Cystic Fibrosis:Mucolytic and antibiotic aerosol therapy requires extended treatment durations. Specialized respiratory therapy centers in Switzerland and the Netherlands specify heated nebulizer systems for hypertonic saline delivery.
- Bronchitis Treatment:Acute symptom management favors disposable or single-patient-use devices. Pulmonary clinics in France prioritize contamination control through dedicated equipment assignment.
COPD applications concentrate volume; asthma management segments expand most quickly.
End User:
Care setting capabilities determine device complexity tolerance and support infrastructure requirements.
- Home Care Patients:Self-administered therapy demands intuitive operation and minimal maintenance. United States pharmacy chains and Japanese home medical equipment distributors compete on delivery speed and insurance pre-authorization support for these users.
- Pulmonary Clinics:Specialist-directed care enables prescription of feature-rich devices with adherence monitoring. German pulmonology practices integrate nebulizer data into electronic health records through connected health platforms.
- Respiratory Therapy Centers:High-throughput institutional use prioritizes device durability and rapid patient turnaround. These facilities in the United States negotiate volume purchasing agreements with national respiratory equipment chains.
- Long-Term Care Facilities:Staff-mediated administration requires robust construction and simplified cleaning protocols. Japanese geriatric care operators specify devices with single-button operation and visual completion indicators.
Home care patients represent addressable volume; pulmonary clinics concentrate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan present contrasting demand profiles for nebulizer equipment, with German institutional procurement favoring durable pneumatic systems while Japanese home care patients prioritize silent mesh portability for aging-in-place respiratory therapy.
United States
Medicare Advantage enrollment growth and remote therapeutic monitoring reimbursement codes are accelerating connected nebulizer deployment in home care settings. FDA 510(k) clearance timelines for respiratory devices now extend eight to fourteen months, compressing product launch windows for dual-territory applicants. Minnesota's medical device corridor hosts concentrated regulatory affairs expertise serving manufacturers navigating CMS coverage determinations.
Germany
Aging demographics and COPD prevalence sustain replacement cycles for home nebulization equipment across Bavaria and North Rhine-Westphalia. EU MDR conformity assessments for Class IIa respiratory devices filter demand toward ISO 27427-certified manufacturers with established notified body relationships. Stuttgart's precision engineering cluster supplies pneumatic compressor components to institutional purchasing networks.
Japan
Geriatric care operators specify single-button mesh devices with visual completion indicators for staff-mediated administration in long-term care facilities. METI standards for home medical equipment interoperability shape connected health platform development. Osaka's electronics manufacturing base produces piezoelectric elements for compact pediatric asthma management devices.
India
Underpenetrated rural respiratory therapy markets present expansion opportunities for battery-operated mesh devices distributed through pharmacy chains. CDSCO medical device registration requirements are tightening quality benchmarks for imported nebulizing systems. Gujarat's pharmaceutical manufacturing belt is developing localized assembly capacity for cost-optimized home care equipment.
Switzerland
Specialized respiratory therapy centers in Zurich and Geneva specify heated nebulizer systems for hypertonic saline delivery in cystic fibrosis protocols. Swissmedic post-market surveillance requirements align with EU MDR technical documentation standards. Basel's precision materials cluster supplies biocompatible polymer reservoirs meeting FDA extractables and leachables testing protocols.
Global Nebulizers Market Competitive Landscape
German engineering specialists anchor one tier; Japanese and American health technology conglomerates hold platform-scale positions. The vendor structure concentrates around three to five established respiratory equipment manufacturers with notified body relationships and pharmacy channel control, while mid-tier producers face margin compression from regulatory compliance costs. Two strategic archetypes dominate: precision aperture mesh technology developers and connected health platform integrators. Competitive dynamics center on M&A activity among home care distributors and strategic partnerships between device manufacturers and telehealth platform operators.
Within the precision engineering tier, PARI GmbH and Omron Healthcare exemplify divergent geographic specializations. PARI GmbH occupies a position reflecting German manufacturing standards in European pediatric segments. Omron Healthcare anchors Asian market access through localized production networks. Koninklijke Philips sits within the connected health platform archetype, integrating nebulizer therapy data with remote monitoring infrastructure. These three entities represent distinct competitive vectors: engineering-certified institutional supply, pharmacy-channel home care penetration, and digital health ecosystem integration.
| Leading Market Players |
|---|
| Omron Healthcare |
| Koninklijke Philips |
| PARI GmbH |
| Drive DeVilbiss Healthcare |
| GE Healthcare |
| Allied Healthcare Products |
| Aerogen |
| GF Health Products |
| Trudell Medical |
| Others |
Supply & Pricing Matrix
Piezoelectric element costs from South Korean suppliers cascade through three pricing tiers, with battery chemistry specifications and ISO 27427 certification grades separating premium mesh devices from economy pneumatic alternatives in procurement negotiations across German hospital networks and United States pharmacy chains.
Pricing Analysis
Capacity additions in China's precision electronics clusters are reshaping price floors for vibrating mesh components, compressing margins for mid-tier manufacturers lacking backward integration into aperture plate fabrication. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared connected devices from CE-marked alternatives and unvalidated imports. Pricing pressure stems from Medicare Advantage plan consolidation favoring transparent out-of-pocket structures over bundled device-and-service contracts. Home care patients exhibit highest price sensitivity, while pulmonary clinics concentrate premium pricing power through prescription-controlled device selection.
Supply Chain Analysis
ISO 27427 certification and FDA 510(k) clearance gating concentrate component sourcing among qualified tier-one suppliers in Germany, Japan, and South Korea. Piezoelectric crystals, biocompatible polymer reservoirs, and lithium-ion battery cells constitute critical input dependencies. Single-source vulnerability concentrates in East Asian precision aperture mesh manufacturing. Distribution runs through consolidated national respiratory equipment chains in the United States and pharmacy-controlled networks in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Nebulizers Market operates as a regulatory compounder where EU MDR conformity assessments and FDA 510(k) clearance timelines progressively filter competitive density toward ISO-certified incumbents with established notified body relationships.
For Market Incumbents: Deploy connected health platform integration to defend against dry powder inhaler substitution in maintenance COPD therapy. Deepen backward integration into piezoelectric element sourcing to offset East Asian supply concentration risk. Prioritize CE marking pathway acceleration ahead of EU MDR technical documentation deadlines to capture volume from delayed competitors. For New Entrants and Emerging Players: Launch via direct-to-consumer pharmacy channel partnerships in underpenetrated Indian rural markets where battery-operated mesh devices address accessibility gaps. Target pediatric asthma management segments in Japan where silent operation and single-button interfaces command caregiver willingness to pay premium pricing over established pneumatic alternatives. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier producers face margin compression from regulatory compliance infrastructure requirements. Five-to-ten year viability favors precision aperture mesh technology developers with captive manufacturing or exclusive supplier agreements over contract-assembled competitors. Watch FDA 510(k) clearance timeline deviations as inflection indicators for dual-territory market access bottlenecks.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR conformity assessments filter demand toward ISO 27427-certified manufacturers with notified body relationships. |
| Hospital System Partnership | German pulmonology practices integrate nebulizer data into electronic health records through connected health platforms. |
| Software Companion Development | Bluetooth-enabled adherence monitoring opens subscription-based service models with telehealth platform operators. |
| Reimbursement Strategy | CMS remote therapeutic monitoring codes expand connected nebulizer eligibility in Medicare Advantage home care programs. |
| Backward Integration | Captive piezoelectric element production mitigates single-source vulnerability from East Asian electronics clusters. |
Research Methodology
Bottom-up home care patient and pulmonary clinic modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and respiratory therapy center directors combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement code revisions, and hospital procurement contract registries. Triangulation between demand-side adoption metrics and supply-side production data ensures cross-verified volume estimates.
Historical trendline analysis across installed base replacement cycles and technology transition patterns informs projection mechanics over the analysis window. Segmentation dimensions encompass device architecture, energy conversion mechanism, disease application, and care setting capability, with regional regulatory cluster differentiation as an additional modeled layer. CAGR derivation rests on patient cohort expansion rates, reimbursement code adoption curves, and technology substitution elasticity estimates specific to respiratory therapy equipment.
Several conditions sit outside the modeled scope, including pandemic-driven demand spikes, abrupt tariff regime changes affecting East Asian electronics imports, and breakthrough dry powder inhaler formulations displacing nebulized maintenance therapy. Forecasts reflect documented assumptions regarding FDA clearance timeline normalization and EU MDR notified body capacity expansion. Deviation in piezoelectric element supply chain concentration or CMS reimbursement code revisions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Subcutaneous Implantable Defibrillator System Market
Medical Devices
Focused Ultrasound System Market
Medical Devices
USA Artificial Organs and Bionic Implants Market
Medical Devices
Peak Flow Meters Market
Medical Devices
US Contact Lenses Market
Medical Devices
North America Smart Medical Devices Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Airway Management Tubes Market
Medical Devices
High Volume Dispensing Systems Market
Medical Devices
Europe Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Adjustable Speed Vortex Mixer Market