
 Canada Minimally Invasive Surgery Devices Market | 2026-2036
Canada Minimally Invasive Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Minimally Invasive Surgery Devices Market Analysis
The capital-intensity gap between established manufacturers and emerging entrants is collapsing as robotic platform costs fall and leasing models proliferate. Medtronic PLC leverages its integrated surgical ecosystem to sustain installed-base loyalty across Canadian teaching hospitals. Stryker Corporation anchors its position through dedicated ambulatory surgical center partnerships in British Columbia and Alberta. Johnson & Johnson competes via specialized energy devices that integrate with third-party visualization systems.
Canada minimally invasive surgery devices encompass precision instruments, camera systems, and energy platforms engineered for procedures performed through incisions under two centimeters, utilizing high-definition visualization and advanced tissue manipulation to reduce patient trauma and accelerate recovery. Structural dynamics favor robotic surgery systems where capital deployment cycles and training infrastructure create sticky provider relationships, while electrosurgery technology leads procedural volume due to its ubiquity in laparoscopic suites across the country. Endoscopes represent a mature segment with replacement-driven demand, whereas ambulatory surgical centers emerge as the fastest-growing end-user channel as provincial health authorities push same-day procedures outside hospital settings.
Health Canada's Medical Devices Regulations govern pre-market licensing and post-market surveillance, while the Canadian Standards Association certifies electrical safety and biocompatibility parameters that shape product design requirements. Provincial health technology assessment bodies, notably Ontario's Health Quality Ontario and Quebec's Institut national d'excellence en santé et en services sociaux, determine reimbursement eligibility that directly conditions hospital procurement decisions. Stakeholders must monitor evolving provincial funding mechanisms for robotic surgery capital equipment and same-day surgical infrastructure to align portfolio investments with payer priorities.
Market Dynamics
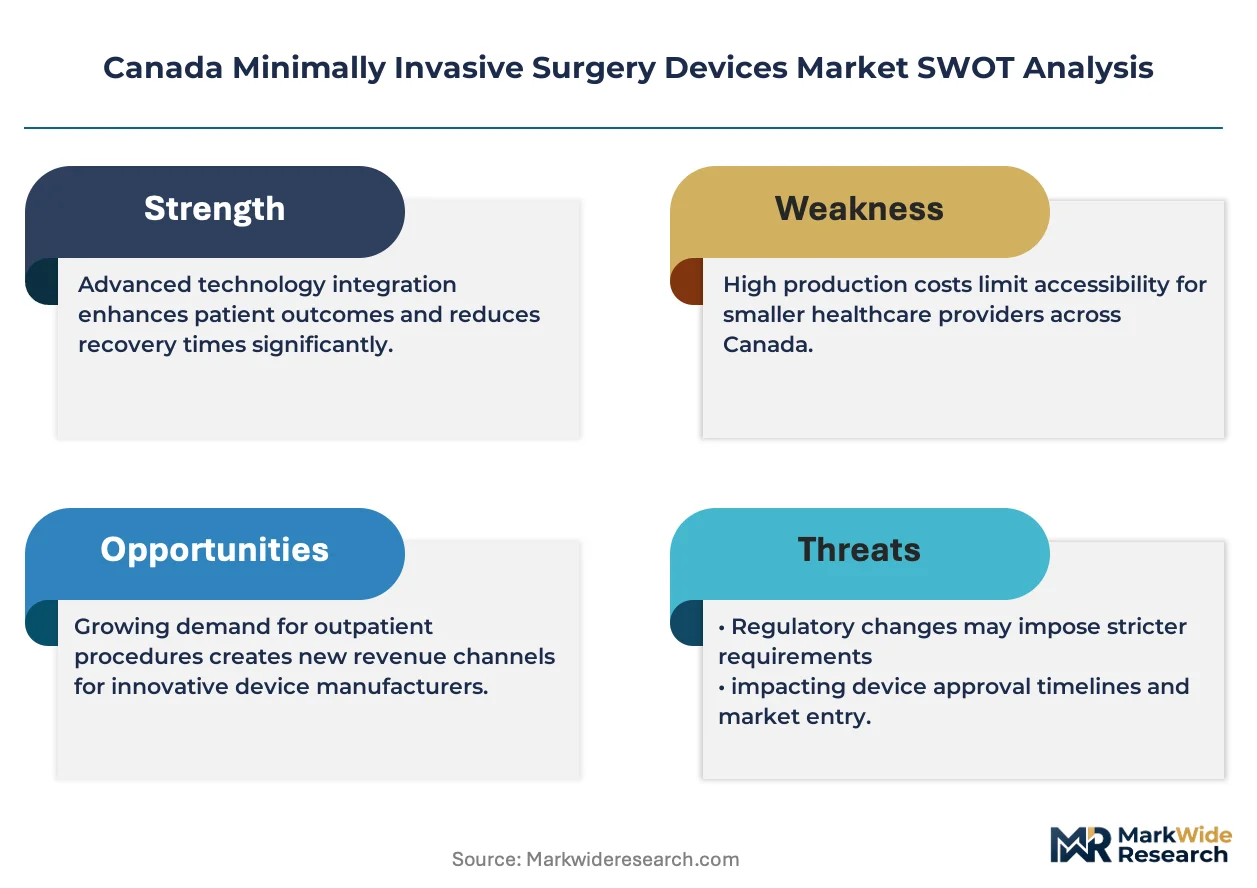
Health Canada's tightening Medical Devices Regulations are compressing product approval timelines while provincial health technology assessment bodies simultaneously constrain reimbursement eligibility, forcing manufacturers to synchronize regulatory and commercial strategies across multiple approval pathways.
Growth Catalysts
- Same-day surgical mandates:Provincial health authorities in Ontario and Quebec are directing cardiac and orthopedic procedures into ambulatory settings, expanding addressable demand for compact laparoscopic platforms.
- Robotic surgery training infrastructure:Teaching hospitals across Alberta and British Columbia are embedding simulation-based credentialing programs, accelerating surgeon adoption curves for computer-assisted platforms.
- Health Canada licensing harmonization:Streamlined pre-market review pathways for devices with prior FDA or CE marking are reducing time-to-revenue for established manufacturers.
Market Restraints
- Capital equipment concentration:Robotic surgery platforms require dedicated surgical suites and specialized maintenance contracts, limiting deployment to tertiary centers in Toronto, Montreal, and Vancouver.
- Supply chain input volatility:Precision optical components and surgical-grade alloys face sourcing constraints from concentrated Asian manufacturing clusters, pressuring instrument margins.
- Technical limitation in haptic feedback:Current robotic platforms lack tactile sensation transfer, restricting adoption in procedures requiring tissue palpation such as complex oncologic resections.
Strategic Opportunities
- Underpenetrated Atlantic provinces:Nova Scotia and New Brunswick maintain lower robotic surgery penetration rates than central Canada, presenting first-mover expansion potential for platform vendors.
- Regulatory tailwind from INESSS accelerated review:Quebec's health technology assessment body has implemented fast-track evaluation for devices reducing length-of-stay metrics, favoring minimally invasive innovations.
- Technology convergence of AI-assisted imaging:Integration of real-time computer vision with existing laparoscopic towers is creating upgrade pathways without full platform replacement.
Industry Challenges
- Surgeon credentialing bottlenecks:Royal College of Physicians and Surgeons of Canada proctorship requirements for robotic surgery create training queue backlogs at major academic centers.
- Legacy visualization system incompatibility:Hospital investments in proprietary camera and insufflator ecosystems from the 2010s resist interoperability with newer energy device platforms.
- Post-market surveillance compliance:Health Canada's mandatory adverse event reporting for Class III and IV devices demands dedicated regulatory affairs infrastructure that mid-tier manufacturers struggle to maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Minimally Invasive Surgery Devices Market |
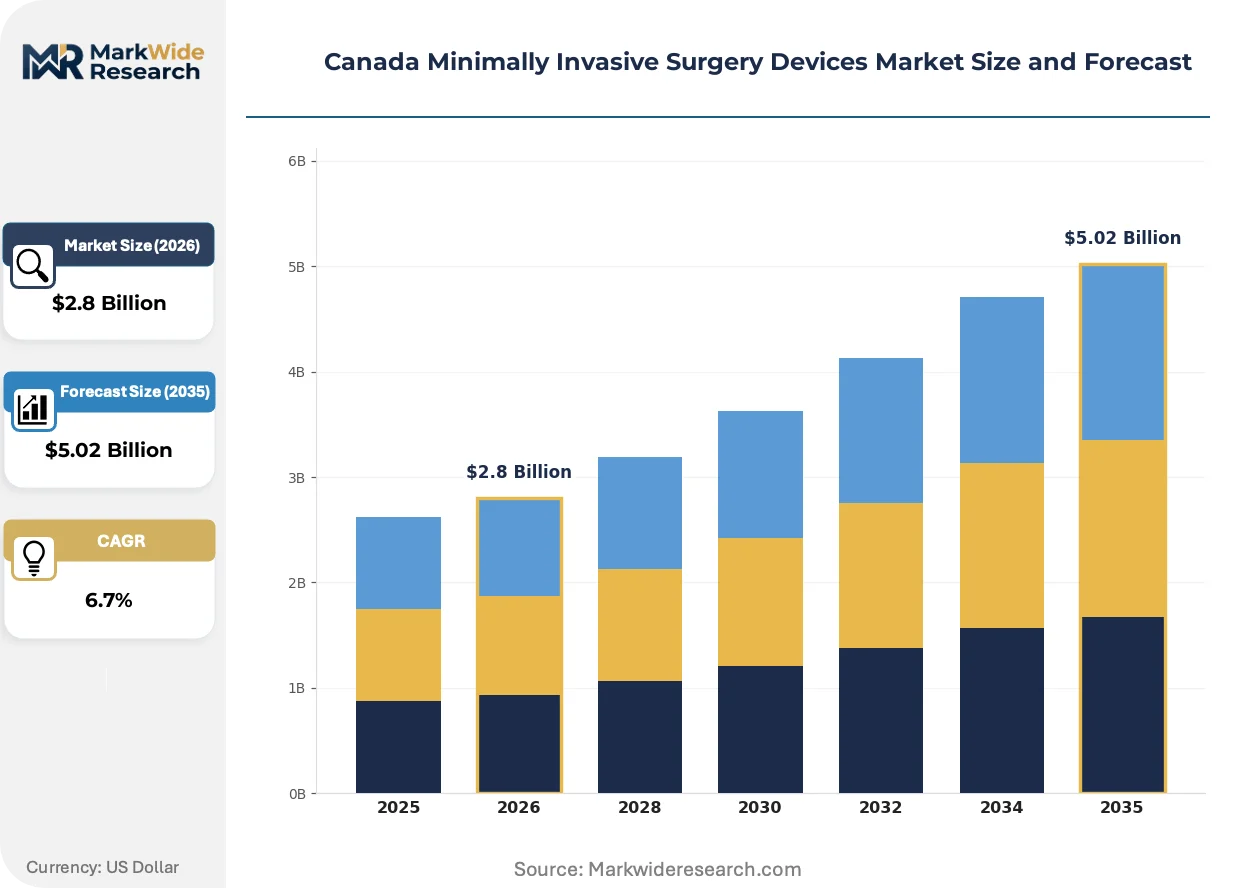
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laparoscopic Devices, Robotic Surgery Systems, Endoscopes, Surgical Instruments Technology: Laser Technology, Electrosurgery, Visualization Systems, Energy Devices End User: Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Research Institutions Application: Cardiothoracic Surgery, Orthopedic Surgery, Gastrointestinal Surgery, Urological Surgery |
| Companies Covered | CONMED Corporation, Johnson & Johnson, Olympus Corporation, Smith & Nephew, Stryker Corporation, Medtronic PLC, B. Braun SE, Zimmer Biomet Holdings, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Minimally Invasive Surgery Devices Market Emerging Trajectories
Single-port surgical platforms are compressing the physical footprint of minimally invasive procedures while artificial intelligence integration redefines intraoperative decision support, reshaping capital allocation priorities across Canadian hospital procurement cycles.
Advanced energy sealing devices incorporating bipolar and ultrasonic modalities are decomposing the traditional electrosurgery market structure. Community hospitals in Manitoba and Saskatchewan are adopting these hybrid platforms ahead of academic centers, attracted by reduced thermal spread and consolidated instrument trays. The technology is decomposing established vendor relationships by enabling cross-manufacturer compatibility with third-party visualization systems.
Health Canada's 2023 amendments to the Medical Devices Regulations introduced mandatory cybersecurity documentation for networked surgical platforms. Manufacturers must now submit threat assessment protocols and software update procedures as part of pre-market licensing submissions. Class III robotic systems face the steepest compliance burden, with several vendors extending Canadian launch timelines to satisfy these documentation requirements.
Hospital procurement committees are unbundling service contracts from capital equipment purchases, separating preventive maintenance from software licensing and training fees. This disaggregation is most pronounced in British Columbia's health authority purchasing consortia, where multi-hospital agreements now specify line-item pricing for each service component. Vendors accustomed to bundled recurring revenue models face margin compression as buyers benchmark service elements across competitive tenders.
Canada Minimally Invasive Surgery Devices Market Segmentation
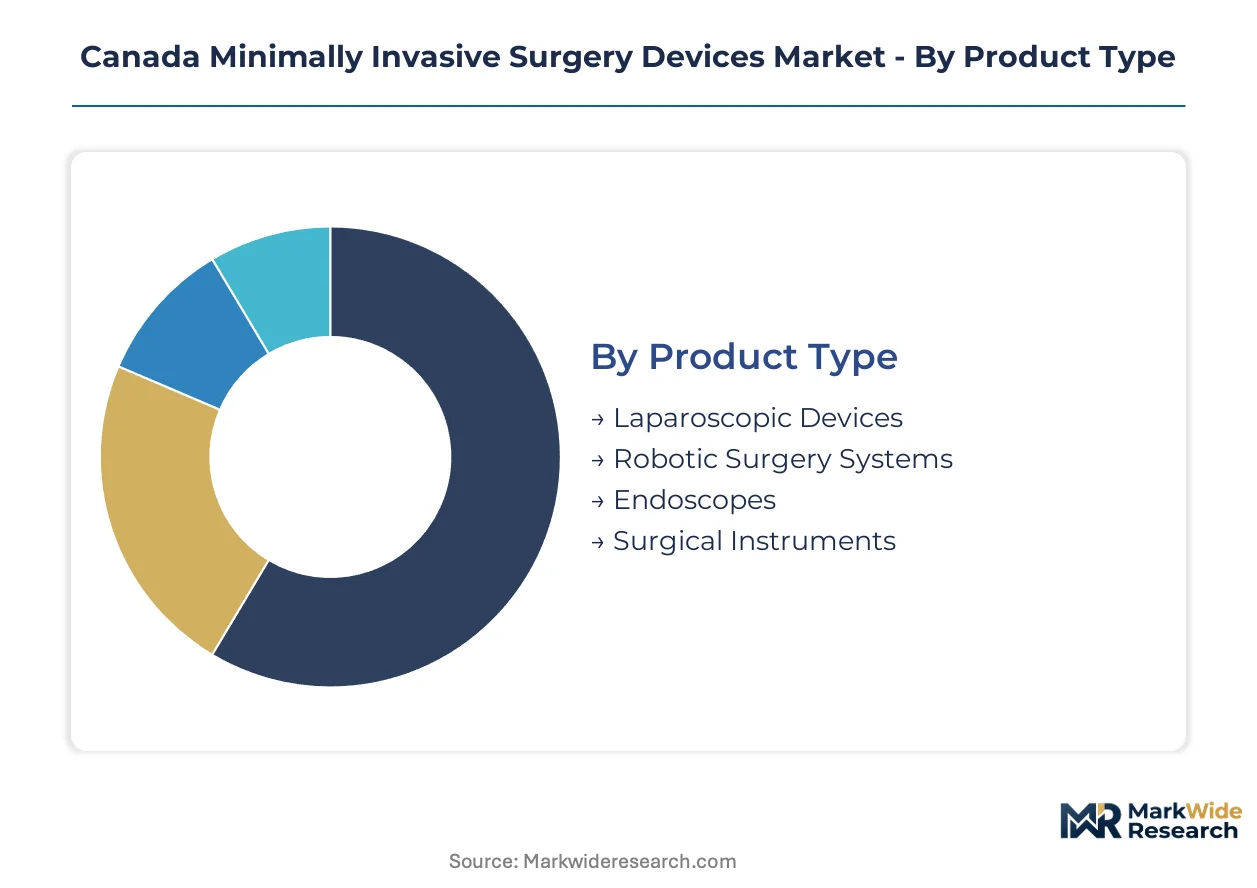
Segmentation reveals how procurement power fragments across Canadian healthcare infrastructure. Provincial funding mechanisms and facility-level capital cycles create distinct demand profiles that manufacturers must navigate simultaneously.
Product Type:
Margin pools concentrate in platforms requiring recurring consumables and service contracts rather than one-time instrument sales.
- Robotic Surgery Systems:Computer-assisted platforms integrate haptic interfaces, 3D visualization, and proprietary instrument ecosystems. Tertiary centers in Toronto and Vancouver deploy these for complex oncologic and cardiac procedures where length-of-stay reductions justify capital outlays. Health Canada's Class III licensing requirements extend approval timelines, entrenching incumbents with established regulatory infrastructure.
- Laparoscopic Devices:Trocars, insufflators, and hand instruments constitute the procedural backbone across Ontario's hospital networks. Demand concentrates in high-volume cholecystectomy and hernia repair programs where standardized instrument trays reduce per-case costs. Quebec's same-day surgery mandates are accelerating replacement cycles for aging tower systems.
- Endoscopes:Flexible and rigid optical systems for diagnostic and interventional procedures.
- Surgical Instruments:Graspers, scissors, and needle drivers for manual minimally invasive access.
Robotic Surgery Systems hold installed capacity. Laparoscopic Devices is rotating up the share rankings.
Technology:
Technology selection follows visualization infrastructure decisions made in previous capital cycles, locking facilities into compatible energy platforms.
- Energy Devices:Advanced sealing platforms combining bipolar and ultrasonic modalities reduce thermal spread and consolidate instrument counts. Community hospitals in Manitoba and Saskatchewan are adopting these ahead of academic centers, attracted by simplified sterilization workflows and cross-manufacturer compatibility.
- Visualization Systems:4K and 3D camera towers with integrated insufflation and smoke evacuation. British Columbia's health authority purchasing consortia are unbundling service contracts from capital purchases, pressuring vendor margins on multi-hospital agreements.
- Electrosurgery:Monopolar and bipolar current delivery for tissue cutting and coagulation.
- Laser Technology:Precision ablation systems for specialized urologic and ophthalmic applications.
Visualization Systems anchor procurement committees. Energy Devices is climbing the fastest as facilities prioritize consumable efficiency.
End User:
End-user channel dynamics reflect provincial pushes toward decentralized surgical delivery and capital constraint differentiation.
- Ambulatory Surgical Centers:Standalone facilities performing same-day cardiac and orthopedic procedures under Ontario and Quebec mandates. These centers favor compact laparoscopic platforms with reduced physical footprints and lower per-procedure overhead than hospital-based suites.
- Hospitals:Integrated delivery networks with robotic surgery programs, residency training infrastructure, and emergency backup capabilities. Academic centers in Alberta and British Columbia embed simulation-based credentialing that accelerates technology adoption curves.
- Specialty Clinics:Focused outpatient facilities for endoscopy and minor interventional procedures.
- Research Institutions:Teaching hospitals and university affiliates conducting clinical trials and device validation studies.
Hospitals retain capital deployment authority. Ambulatory Surgical Centers is expanding most quickly as provincial authorities redirect reimbursable volume.
Application:
Application demand correlates with demographic burden and provincial prioritization of wait-time reduction targets.
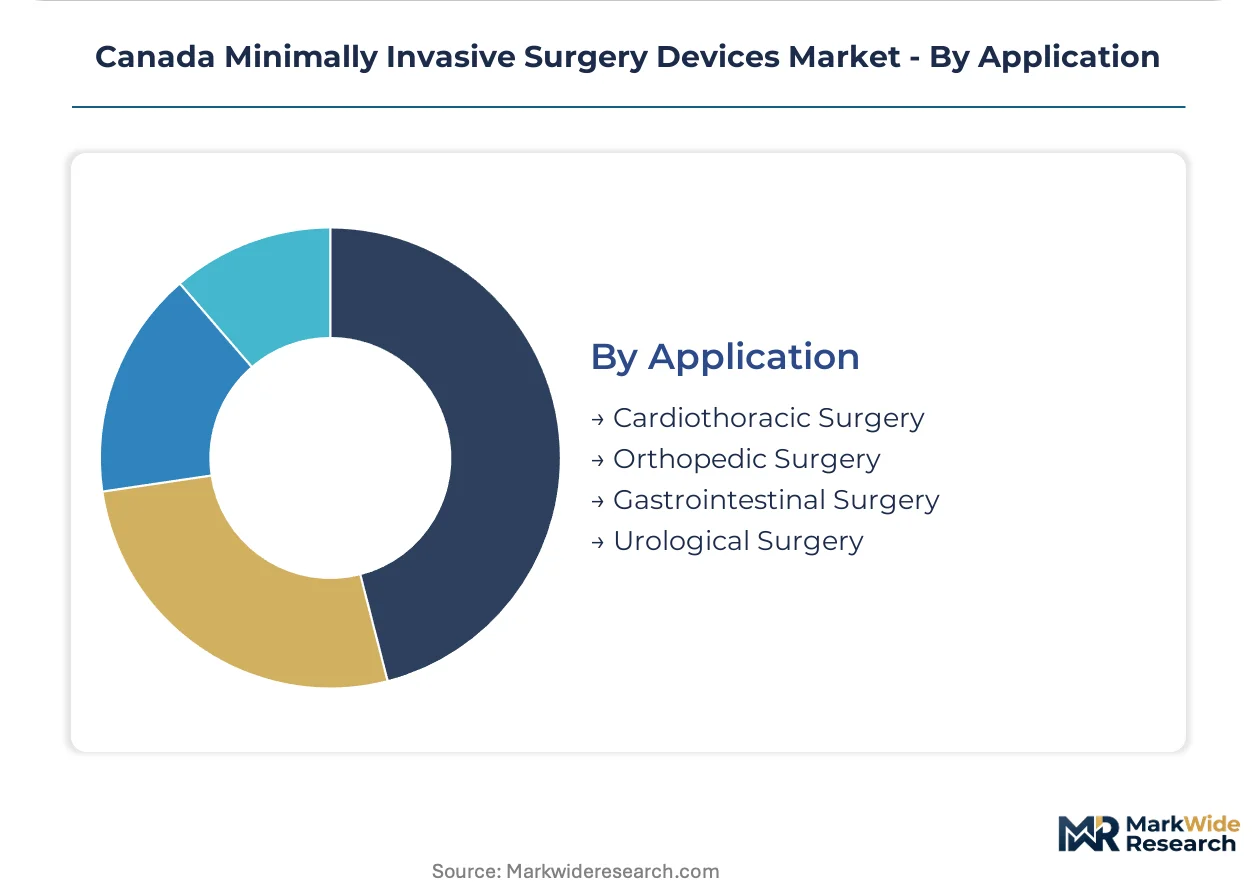
- Orthopedic Surgery:Arthroscopic and minimally invasive joint replacement procedures. Alberta's health authority has centralized complex hip and knee reconstructions to high-volume centers, consolidating demand for specialized instrument sets and navigation platforms.
- Cardiothoracic Surgery:Valve repair, coronary bypass, and lung resection through port access. Ontario's cardiac care networks are expanding minimally invasive mitral valve programs, driving demand for robotic thoracic platforms and specialized cannulation devices.
- Gastrointestinal Surgery:Colorectal resection, bariatric procedures, and foregut operations.
- Urological Surgery:Prostatectomy, nephrectomy, and stone disease management.
Cardiothoracic Surgery commands premium pricing. Orthopedic Surgery is gaining share fastest through volume concentration policies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Canadian provinces. Ontario and Quebec buyers prioritize technology integration and training infrastructure, accepting premium pricing for robotic platforms. Atlantic Canada and Prairie Provinces remain price-sensitive, favoring refurbished laparoscopic towers and leasing arrangements over capital purchases.
Ontario
Toronto's University Health Network and Sunnybrook Health Sciences Centre drive demand for da Vinci Xi systems and affiliated simulation labs. Health Quality Ontario's health technology assessment mandates evidence-based procurement, slowing adoption of unproven energy devices. The Greater Toronto Area concentrates robotic surgery volume, with Mississauga and Hamilton community hospitals now acquiring compact laparoscopic platforms for same-day orthopedic procedures.
Quebec
McGill University Health Centre and CHU de Québec anchor cardiothoracic robotic programs, with provincial cardiac care networks expanding minimally invasive mitral valve surgery. INESSS accelerated review pathways favor devices demonstrating length-of-stay reductions, compressing evaluation timelines for sealing platforms and 3D visualization systems. Montreal's medical device corridor hosts service hubs for major vendors, reducing maintenance response times for Class III robotic systems.
Alberta
Calgary's Foothills Medical Centre and Edmonton's Royal Alexandra Hospital embed simulation-based credentialing through the University of Calgary and University of Alberta surgical programs. Alberta Health Services centralized procurement for arthroscopic and joint replacement instruments, consolidating demand for specialized navigation platforms. The Calgary-Edmonton corridor attracts ambulatory surgical center investment as provincial authorities redirect reimbursable orthopedic volume outside hospital settings.
British Columbia
Vancouver Coastal Health and Fraser Health authority purchasing consortia unbundle service contracts from capital equipment, pressuring vendor margins through line-item benchmarking. Vancouver General Hospital maintains Western Canada's highest robotic surgery case volume for urologic and gynecologic procedures. Interior Health Authority facilities in Kelowna and Kamloops adopt hybrid energy platforms ahead of academic centers, attracted by simplified sterilization workflows.
Atlantic Canada
Halifax's QEII Health Sciences Centre represents the region's sole robotic surgery deployment, with New Brunswick and Newfoundland facilities reliant on laparoscopic and endoscopic platforms. Health Canada licensing timelines deter vendor investment in Atlantic service infrastructure, extending maintenance response times. Provincial health authorities in Nova Scotia prioritize same-day surgical mandates for cholecystectomy and hernia repair, expanding demand for compact laparoscopic towers with reduced physical footprints.
Canada Minimally Invasive Surgery Devices Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding installed-base loyalty through proprietary instrument ecosystems and training infrastructure. The middle tier competes on cross-manufacturer compatibility and unbundled service pricing. Strategic archetypes include full-stack platform vendors, modular energy device specialists, and visualization-agnostic instrument suppliers. Competitive moves center on ambulatory surgical center partnerships and provincial health authority purchasing consortia penetration.
Within the integrated platform tier, Medtronic PLC and Stryker Corporation anchor positions through teaching hospital relationships and dedicated service networks. Johnson & Johnson occupies a position bridging energy devices and surgical instrumentation, representing the modular specialist archetype. These three entities exemplify contrasting approaches to Health Canada's Medical Devices Regulations compliance, with varying emphasis on regulatory affairs infrastructure and post-market surveillance capabilities.
| Leading Market Players |
|---|
| CONMED Corporation |
| Johnson & Johnson |
| Olympus Corporation |
| Smith & Nephew |
| Stryker Corporation |
| Medtronic PLC |
| B. Braun SE |
| Zimmer Biomet Holdings |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Multi-year service bundling contracts lock in recurring revenue streams for robotic platform vendors while simultaneously insulating hospital buyers from volatile consumable pricing. These arrangements concentrate procurement leverage among provincial health authority purchasing consortia in British Columbia and Alberta, compressing margins on aftermarket components.
Pricing Analysis
Preventive maintenance and software licensing tiers generate lifetime value multiples exceeding initial capital equipment sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by training infrastructure inclusion and response-time guarantees. Cost compression in consumable instrument trays is intensifying because British Columbia's unbundled contracting mandates line-item benchmarking. Community hospitals in Manitoba exhibit highest price sensitivity, deferring to refurbished tower systems, while Toronto's academic centers accept premium positioning for simulation-integrated packages.
Supply Chain Analysis
Shanghai-Shenzhen precision optics corridors anchor surgical camera component sourcing, creating single-source vulnerability for 4K sensor arrays and fiber optic bundles. German and Japanese surgical-grade alloy foundries feed instrument manufacturing, with Taiwanese contract manufacturers assembling final device platforms. Tariff exposure runs through Health Canada's Medical Devices Regulations compliance documentation, extending lead times for Class III robotic systems. Distribution feeds from vendor-managed inventory hubs in Montreal and Toronto into hospital materials management departments and ambulatory surgical center consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around interoperability mandates as Health Canada's cybersecurity documentation requirements force open previously proprietary visualization ecosystems.
For Market Incumbents: Secure installed-base loyalty by embedding simulation-based training infrastructure within credentialing pipelines at Alberta and British Columbia teaching hospitals. Deepen backward integration into precision optical component sourcing to offset Asian supply concentration. Counter modular energy device specialists by accelerating cross-manufacturer compatibility certifications for legacy tower systems. For New Entrants and Emerging Players: Health Canada's streamlined pre-market review for FDA-CE harmonized devices offers fast-track access without duplicative clinical trials. Exploit underpenetrated Atlantic provinces where Nova Scotia and New Brunswick maintain minimal robotic surgery deployment. Pursue ambulatory surgical center partnerships in Ontario's same-day surgery corridors with compact laparoscopic platforms emphasizing reduced physical footprints. For Investors and Strategic Acquirers: Visualization-agnostic instrument suppliers with Health Canada regulatory infrastructure present acquisition targets positioned for interoperability tailwinds. Long-term viability hinges on software-defined platform transitions rather than capital equipment cycles. Monitor INESSS accelerated review queue depth as inflection signal for Quebec reimbursement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Licensing Harmonization | Reduces time-to-revenue for established manufacturers with FDA-CE predicate devices. |
| Simulation-Based Training Partnership | Accelerates surgeon credentialing throughput at Royal College-affiliated academic centers. |
| Ambulatory Surgical Center Alliance | Captures same-day procedure volume redirected from hospital settings under provincial mandates. |
| Cross-Manufacturer Compatibility Certification | Unlocks procurement committee access in unbundled British Columbia purchasing consortia. |
| Provincial GPO Contract Penetration | Consolidates demand capture through Ontario and Quebec health authority purchasing agreements. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Health Canada licensing databases, provincial health technology assessment publications, and hospital procurement records. Clinicians, biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs specialists at device manufacturers provided structured input. Bottom-up demand modeling triangulates against top-down expenditure analysis from provincial health authority budget disclosures.
Segmentation dimensions modeled encompass product type, technology platform, end-user channel, application specialty, and provincial regulatory cluster across the analysis window. CAGRs derive from installed base growth projections, replacement cycle acceleration, and same-day surgery policy implementation timelines. Forecast inputs incorporate Health Canada Class III approval velocity and INESSS evaluation queue dynamics.
Underlying assumptions cover stable provincial funding for robotic surgery capital equipment, with deviation risk concentrated in supply chain input volatility and credentialing bottleneck resolution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Breast Implants Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Centrifugation-Free Sperm Separation Systems Market
Medical Devices
Organoids Kits Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Europe Mobility Aids Market
Medical Devices
Medical Device Connectivity Market
Medical Devices
South America C-Arms Market
Medical Devices
Otoscope Devices Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Global Organs-On-Chips Market
Medical Devices
Asia-Pacific Electroencephalography Devices Market
Medical Devices
Bioimpedance Analyzers Market
Medical Devices
High Viscosity Bone Cement Market