
 TMJ Implants Market | 2026-2036
TMJ Implants Market Size, Share, and Industry Trends Forecast 2026-2036
TMJ Implants Market Outlook
Patient-matched titanium condylar systems is collapsing the gap between off-the-shelf stock implants and fully custom prosthetics, forcing manufacturers to elevate precision manufacturing capabilities. Zimmer Biomet leverages its orthopedic metals heritage to dominate craniofacial alloy supply chains. TMJ Concepts anchors North American production with vertically integrated CNC milling operations in California. Stryker competes through its established hospital contracting networks across major academic medical centers.
Temporomandibular joint implants are biocompatible prosthetic devices, typically machined from titanium alloy or cobalt-chromium with ultra-high molecular weight polyethylene bearing surfaces, designed to restore mandibular function and alleviate degenerative joint dysfunction. Condylar implants command the largest revenue share due to the anatomical complexity of mandibular head replacement and the premium pricing attached to patient-specific designs. Fossa implants represent the fastest-growing material segment as surgeons adopt all-polyethylene glenoid-style components for less invasive joint resurfacing. Research institutions increasingly drive demand for novel biocompatible alloys that reduce stress-shielding and improve osseointegration timelines.
FDA 510(k) premarket notification requirements govern US commercialization, while the EU Medical Device Regulation mandates notified body conformity assessment for CE marking across European markets. ISO 5832 standards for surgical implant materials establish baseline metallurgical and mechanical specifications that manufacturers must satisfy for multi-jurisdiction market access. Stakeholders must monitor evolving reimbursement codes for custom craniofacial devices as payor policies increasingly differentiate between stock and patient-matched implant categories.
Market Dynamics
Patient-matched manufacturing is collapsing the traditional trade-off between surgical precision and production economics, forcing implant fabricators to reconfigure capital deployment around additive and subtractive CNC workflows.
Growth Catalysts
- FDA 510(k) Pathway Streamlining:The FDA's premarket notification framework for custom craniofacial devices accelerates manufacturer entry timelines for patient-specific condylar systems.
- Titanium Alloy Biocompatibility:Osseointegration performance of Ti-6Al-4V ELI is displacing cobalt-chromium in mandibular head reconstructions across German university hospitals.
- Oral Surgery Center Consolidation:United States ambulatory surgical centers are aggregating procurement volume for complex joint reconstruction procedures.
Market Restraints
- Titanium Sponge Supply Concentration:Primary titanium feedstock production concentrates in Chinese sponge facilities, exposing fabricators to input cost volatility.
- EU MDR Conformity Assessment:The European Medical Device Regulation's notified body bottleneck extends CE marking timelines for novel bearing surface designs.
- Polyethylene Wear Debris Limitations:Ultra-high molecular weight polyethylene generates particulate concerns that constrain long-term implant durability claims.
Strategic Opportunities
- India's CDSCO Accelerated Pathways:India's pharmaceutical regulator is streamlining import licenses for custom craniofacial devices, opening subcontinent access.
- Additive Manufacturing Convergence:Electron beam melting combined with CNC finishing enables hollow-core condylar geometries previously impossible through milling alone.
- Direct-to-Hospital Digital Distribution:Patient-specific implant file transfer bypasses traditional distributor markups in academic medical center procurement.
Industry Challenges
- CAD/CAM Surgical Planning Integration:Preoperative virtual surgical planning requires interoperability with legacy PACS infrastructure that oral surgery centers struggle to reconcile.
- Biocompatibility Certification Timelines:ISO 5832-3 compliance documentation for novel titanium alloy variants extends preclinical validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TMJ Implants Market |
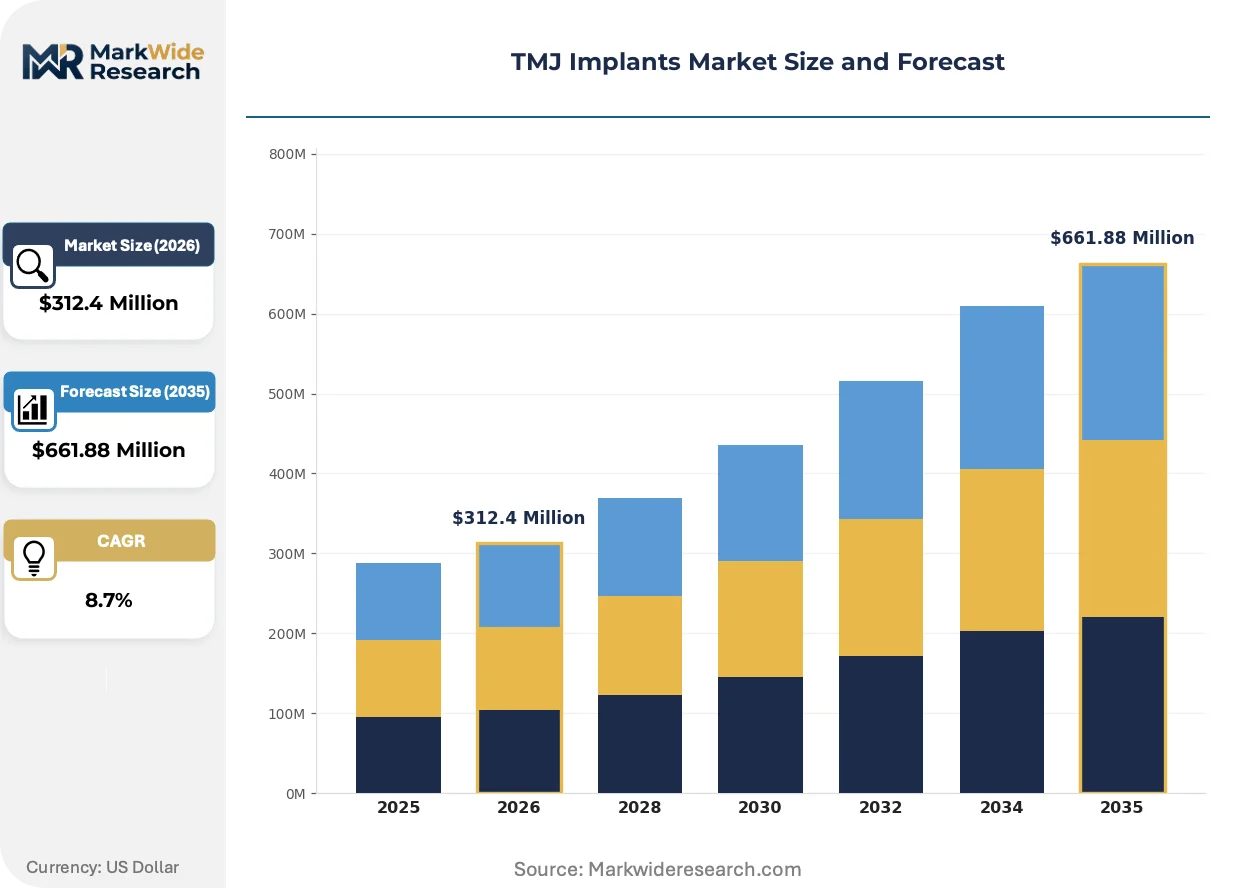
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condylar Implants, Fossa Implants, Fixed Reconstruction, Removable Reconstruction Material: Titanium, Polyethylene, Cobalt-Chromium, Biocompatible Alloys End User: Hospitals, Dental Clinics, Oral Surgery Centers, Research Institutions Application: Jaw Reconstruction, Pain Relief, Facial Aesthetic, Joint Stabilization |
| Companies Covered | Xilloc Medical, TMJ Concepts, Zimmer Biomet, DePuy Synthes, KLS Martin, Stryker, Ortho Baltic, Arthrex, Medtronic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TMJ Implants Market Strategic Shifts
Additive fabrication workflows are fragmenting the traditional monopoly of subtractive milling in patient-matched implant production, while regulatory frameworks on both sides of the Atlantic recalibrate around custom device categories.
Patient-specific titanium condylar implants fabricated through electron beam melting are decomposing the historical cost barrier between stock inventory and fully custom prosthetics. Oral surgery centers in the United States are adopting these workflows for complex mandibular reconstructions at accelerating pace. The technology is compressing lead times from six weeks to ten days, enabling same-surgery digital planning-to-implant sequences.
The European Union's Medical Device Regulation is reclassifying patient-matched craniofacial devices under stricter notified body oversight. Manufacturers must now demonstrate equivalence to predicate devices through expanded clinical data packages. Fossa implant categories face the steepest compliance burden, delaying CE marking for all-polyethylene glenoid-style components.
Academic medical centers are consolidating procurement decisions around integrated service contracts that bundle preoperative planning, implant fabrication, and postoperative monitoring. Traditional distributor networks are losing share to manufacturer-direct digital platforms in Germany and the United States. University hospitals in Heidelberg and Boston exemplify this purchasing concentration, negotiating multi-year sole-source agreements for titanium-based joint reconstruction systems.
TMJ Implants Market Segmentation
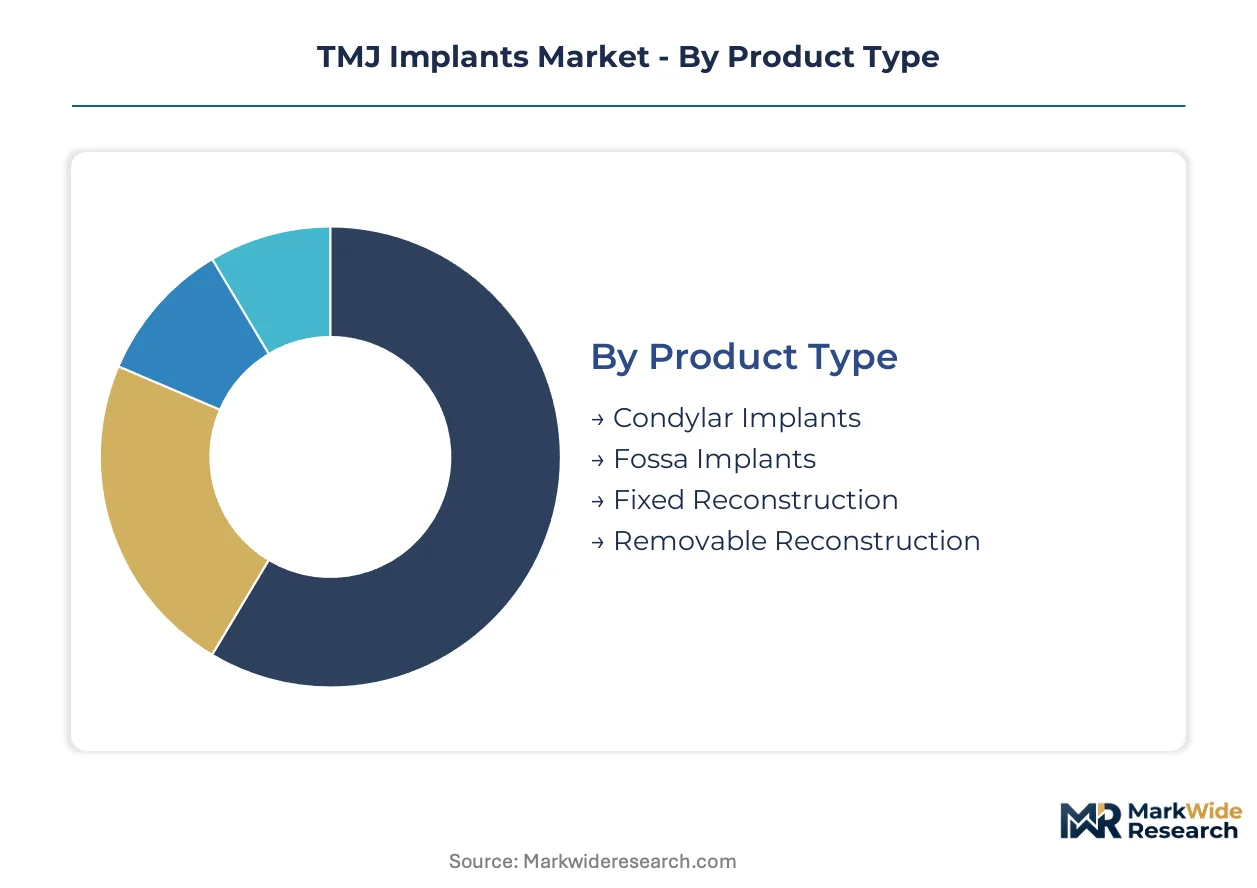
Patient-matched manufacturing workflows are fragmenting traditional procurement patterns across implant categories. Surgeons now select components based on digital planning compatibility rather than legacy supplier relationships.
Product Type:
Condylar systems face intensifying substitution pressure from additive-manufactured patient-specific alternatives that bypass stock inventory entirely.
- Condylar Implants:Titanium alloy mandibular head prostheses machined to patient-specific geometries via electron beam melting or five-axis CNC. German university hospitals concentrate demand for these systems as osseointegration timelines compress with improved surface topology.
- Fossa Implants:Glenoid-style components fabricated from ultra-high molecular weight polyethylene for joint resurfacing without condylar replacement. United States oral surgery centers adopt these for less invasive procedures where bone stock preservation matters.
- Fixed Reconstruction:Rigid integrated systems combining condylar and fossa elements in non-removable assemblies.
- Removable Reconstruction:Modular designs permitting postoperative adjustment or component exchange.
Condylar implants anchor the volume base while fossa implants gain share at the steepest rate.
Material:
Cost tier stratification separates premium titanium formulations from commodity-bearing surfaces in procurement contracts.
- Titanium:Ti-6Al-4V ELI alloy dominates mandibular reconstructions due to fatigue resistance and bone-bonding surface characteristics. Heidelberg and Boston academic centers specify this grade exclusively in multi-year supply agreements.
- Polyethylene:Cross-linked UHMWPE bearing surfaces enable low-friction articulation in fossa components. Wear debris concerns constrain long-term durability claims across European notified body submissions.
- Cobalt-Chromium:Legacy alloy retaining position in cost-sensitive procurement segments.
- Biocompatible Alloys:Experimental formulations targeting stress-shielding reduction.
Titanium commands the procurement premium while biocompatible alloys climb the fastest toward clinical validation.
End User:
Customer type determines service bundling requirements, with integrated planning-fabrication-monitoring packages displacing transactional implant sales.
- Hospitals:Academic medical centers in Germany and the United States consolidate procurement through sole-source agreements spanning preoperative planning to postoperative monitoring. These institutions drive adoption of patient-matched workflows.
- Oral Surgery Centers:Ambulatory facilities aggregate procedure volume for complex reconstructions. California and Massachusetts clusters lead United States penetration of same-surgery digital planning sequences.
- Dental Clinics:Limited to diagnostic referral and preliminary assessment.
- Research Institutions:Drive demand for novel alloy validation and bearing surface innovation.
Hospitals anchor the volume base while oral surgery centers expand capacity most aggressively.
Application:
Volume concentration in functional reconstruction creates margin pressure on aesthetic indications.
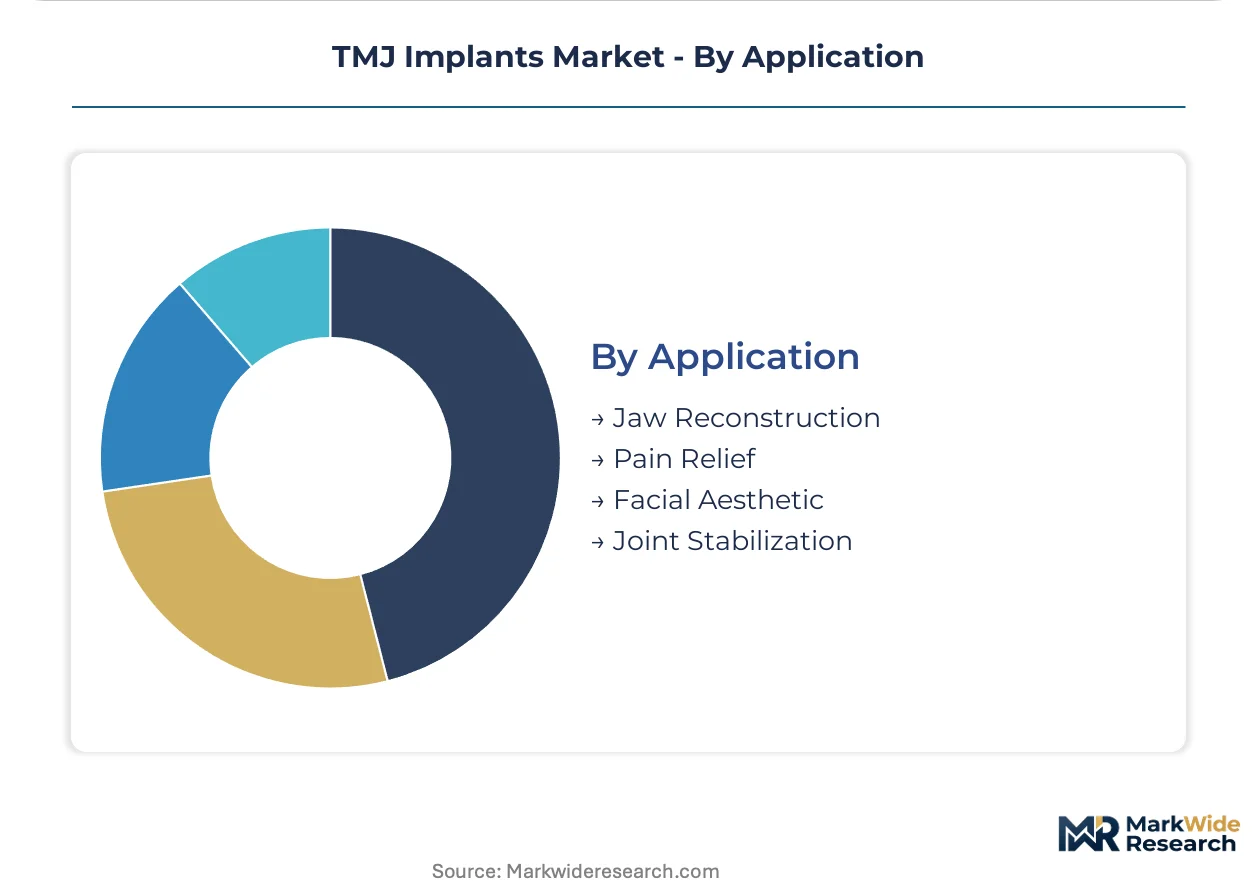
- Jaw Reconstruction:Post-traumatic and oncologic mandibular restoration following resection. German university hospitals specialize in complex cases requiring combined hard and soft tissue replacement.
- Pain Relief:Degenerative joint dysfunction interventions targeting functional restoration. United States ambulatory centers emphasize rapid return to oral function as outcome metric.
- Facial Aesthetic:Contour restoration with secondary functional benefits.
- Joint Stabilization:Hypermobility and subluxation management.
Jaw reconstruction anchors the volume base while pain relief applications expand most quickly into ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium sponge refining concentrates in Chinese industrial zones, yet mandibular implant fabrication clusters in Western medical device corridors where FDA and EU MDR compliance infrastructure already exists.
United States
Oral surgery centers in California and Massachusetts drive patient-matched condylar adoption through same-surgery digital planning sequences. FDA 510(k) premarket notification pathways accelerate manufacturer entry for custom craniofacial devices. The Greater Boston corridor anchors procurement consolidation through multi-year sole-source agreements spanning preoperative planning to postoperative monitoring.
Germany
University hospitals in Heidelberg and surrounding Baden-Württemberg specialize in complex oncologic mandibular reconstructions requiring combined hard and soft tissue replacement. EU MDR notified body conformity assessment reclassifies patient-matched devices under stricter oversight, extending CE marking timelines. The Heidelberg medical cluster specifies Ti-6Al-4V ELI alloy exclusively in titanium-based joint reconstruction procurement.
India
Subcontinent access opens through CDSCO accelerated import license pathways for custom craniofacial devices. The national pharmaceutical regulator streamlines documentation requirements for patient-specific condylar systems. Maharashtra and Karnataka medical device corridors develop domestic CNC finishing capacity to support regional fabrication.
Japan
PMDA marketing authorization requirements govern commercialization of mandibular head prostheses with distinct clinical data package expectations from Western regulators. METI industrial policy supports additive manufacturing adoption in precision medical devices. The Kanto region around Tokyo concentrates academic medical center demand for osseointegration-optimized surface topologies.
United Kingdom
Post-Brexit UKCA marking requirements run parallel to retained EU MDR standards for craniofacial implant categories. The MHRA maintains recognition routes for CE-marked devices during transitional periods. London and Southeast England academic centers negotiate integrated service contracts bundling planning, fabrication, and monitoring.
TMJ Implants Market Competitive Environment
Concentration sits with diversified orthopedic conglomerates possessing established hospital contracting networks and metals heritage. Three to four manufacturers anchor procurement decisions at major academic medical centers, while mid-scale specialists occupy patient-matched fabrication niches. Strategic archetypes divide between scale-driven full-line suppliers, vertically integrated custom fabricators, and regional precision machining houses. Competitive moves center on additive manufacturing capability acquisition and direct-to-hospital digital platform deployment.
Among North American fabricators, TMJ Concepts and Zimmer Biomet occupy distinct positioning within the custom-to-stock spectrum. Stryker represents the diversified orthopedic conglomerate archetype with established academic medical center relationships. The player set spans from California-based CNC milling operations to Midwestern hospital contracting networks, with European specialists like KLS Martin and Ortho Baltic anchoring continental production.
| Leading Market Players |
|---|
| Xilloc Medical |
| TMJ Concepts |
| Zimmer Biomet |
| DePuy Synthes |
| KLS Martin |
| Stryker |
| Ortho Baltic |
| Arthrex |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Ten-day lead times for patient-matched condylar implants compress the traditional six-week fabrication window, concentrating pricing power with California-based CNC operations and German university hospital procurement committees while eroding distributor markups through direct digital file transfer.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across patient-matched craniofacial devices. Premium-mid-economy pricing differentiation separates electron beam melted titanium condylar systems from CNC-milled stock alternatives and cobalt-chromium legacy options. Cost compression in standard-grade implants intensifies as oral surgery centers aggregate procurement volume through multi-year sole-source agreements. Academic medical centers exhibit the lowest price sensitivity due to bundled service contracts, while ambulatory surgical centers in California and Massachusetts negotiate hardest on per-unit implant costs.
Supply Chain Analysis
Titanium sponge refining in Chinese industrial zones creates raw material chokepoints for Western fabricators. Ti-6Al-4V ELI alloy feedstock and ultra-high molecular weight polyethylene bearing surfaces draw from concentrated Asian chemical processing corridors. Single-source vulnerability in titanium sponge exposes California milling operations to input cost volatility. Distribution runs through manufacturer-direct digital platforms that bypass traditional orthopedic distributor networks in Heidelberg and Boston academic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient-matched additive manufacturing is disrupting stock implant economics, with FDA 510(k) streamlining and EU MDR reclassification creating simultaneous opportunity and compliance burden across the forecast window.
For Market Incumbents: Secure additive manufacturing capability through electron beam melting acquisition or partnership, locking in the ten-day lead-time advantage that oral surgery centers now demand. Defend against mid-scale CNC specialists by anchoring multi-year sole-source agreements at Heidelberg and Boston academic medical centers before EU MDR compliance costs escalate. For New Entrants and Emerging Players: Differentiate on hollow-core condylar geometries enabled by combined additive-subtractive workflows that incumbent conglomerates have not yet deployed. Target India's CDSCO accelerated pathway for custom craniofacial devices, where import license streamlining opens subcontinent access before domestic fabrication capacity matures in Maharashtra and Karnataka. For Investors and Strategic Acquirers: Long-term, this sits as a precision manufacturing consolidation play because patient-matched workflows are collapsing the cost barrier between custom and stock implants. Watch for electron beam melting capability acquisition signals as the inflection indicator for valuation step-ups in mid-scale fabricators.| Strategic Initiative | Industry Significance |
|---|---|
| Additive Manufacturing Integration | Electron beam melting enables hollow-core geometries that compress lead times from six weeks to ten days. |
| Direct-to-Hospital Digital Platform | File transfer bypasses distributor markups and captures procurement decisions at Boston and Heidelberg academic centers. |
| FDA 510(k) Clearance Investment | Premarket notification streamlining accelerates entry timelines for patient-specific condylar systems. |
| EU MDR Notified Body Preparation | Expanded clinical data packages defend CE marking for reclassified patient-matched craniofacial devices. |
| Titanium Alloy Supply Anchoring | Upstream control over Ti-6Al-4V ELI feedstock mitigates Chinese sponge concentration risk. |
Study Parameters
Initial hypotheses were tested against primary input from oral and maxillofacial surgeons, hospital purchasing committee members, biomedical engineers at academic medical centers, and GPO contracts managers, then refined against FDA 510(k) filing databases, EU MDR notified body submission records, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up implant volume estimates triangulated against top-down market sizing from orthopedic device trade associations.
Variance decomposition across the projection horizon isolates volume drivers by product type, material grade, end-user facility category, and application indication. CAGRs derive from segmented growth rate modeling anchored to patient-matched adoption curves and oral surgery center capacity expansion. Forecast inputs incorporate electron beam melting penetration assumptions and EU MDR compliance timeline scenarios.
The analysis sits within stated boundaries; outcomes outside FDA 510(k) pathway stability, titanium sponge supply continuity, or EU MDR notified body capacity would require recalibration. Forecasts reflect documented assumptions regarding patient-matched manufacturing cost reduction trajectories and reimbursement code evolution for custom craniofacial categories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ophthalmic Ultrasound Devices Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Robotic Hair Transplant System Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Global Medical Radiation Shielding Market
Medical Devices
Automated Compounding Systems Market
Medical Devices
US Wearable Medical Devices Market
Medical Devices
Global Abdominal Surgical Robot Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
ECG Telemetry Devices Market
Medical Devices
Disposable EEG Electrode Market
Medical Devices
Thrombectomy System Market
Medical Devices
Global Wheelchair Market
Medical Devices
Germany Ophthalmic Devices Market