
 Global on-Body Injectors Market | 2026-2036
Global on-Body Injectors Market Size, Share, and Industry Trends Forecast 2026-2036
Global on-Body Injectors Market Foresight
Polymer-grade liquid silicone rubber is repositioning device housings away from rigid thermoplastics, cutting unit weight and improving skin-contact biocompatibility. Insulet Corporation leverages vertical integration in automated manufacturing to sustain cost leadership in patch injector volumes. Ypsomed anchors European supply through specialized pen injector platforms, while Tandem Diabetes Care competes on electromechanical precision in closed-loop insulin delivery systems.
On-body injectors are wearable drug delivery devices that administer therapeutic doses through subcutaneous infusion over extended periods, typically incorporating reservoirs, drive mechanisms, and adhesive interfaces rated for multi-day skin adhesion. Their primary purpose is to shift parenteral therapy from clinical settings to patient-controlled home administration. Patch injectors lead volume due to expanding biologics portfolios requiring large-volume subcutaneous delivery, while electromechanical delivery technology captures premium positioning through programmable dose titration. Home healthcare dominates end-user demand as payors prioritize reduced hospitalization costs, though ambulatory surgery centers are gaining traction for same-day infusion protocols.
FDA device classification rules and EU MDR conformity requirements are elevating validation burdens for gas-driven and microfluidic platforms, effectively filtering smaller entrants from commercialization pathways. ISO 11608 needle-based injection standards and REACH material compliance further shape component sourcing decisions across European and North American supply chains. Stakeholders must monitor evolving reimbursement codes for wearable infusion in Japan's Ministry of Health framework, as these determinations will set precedent for Asia-Pacific market entry economics.
Market Dynamics
Biologics manufacturers are consolidating wearable delivery partnerships around electromechanical platforms as chronic disease management shifts irreversibly toward patient-administered therapy, forcing component suppliers to validate against tightening FDA device classification and EU MDR conformity requirements.
Growth Catalysts
- Home healthcare reimbursement maturation:Payors in the United States, Germany, and Japan have established durable reimbursement codes for wearable infusion, redirecting chronic therapy volumes from clinical settings to patient-controlled administration.
- EU MDR electromechanical pathway clarity:The updated device classification framework has created predictable validation timelines for gas-driven and microfluidic platforms, reducing regulatory uncertainty for platform developers.
- Large-volume subcutaneous biologics expansion:Monoclonal antibody portfolios requiring extended-duration delivery are concentrating demand on patch injector architectures with multi-day adhesion ratings.
Market Restraints
- Polymer-grade liquid silicone rubber supply concentration:Medical-grade LSR compounding capacity clusters with a limited supplier base in Switzerland and Germany, exposing device housings to input cost volatility.
- ISO 11608 needle-based injection compliance burden:The standard's dimensional and performance requirements impose extended validation timelines, filtering smaller electromechanical entrants from commercialization.
- Gas-driven platform technical ceiling:Mechanical drive systems face hard limits on programmable dose titration precision, constraining their addressable market to fixed-dose biologics.
Strategic Opportunities
- Japan's Ministry of Health wearable infusion code expansion:Pending reimbursement determinations for closed-loop insulin delivery will establish precedent economics for Asia-Pacific market entry by electromechanical platform developers.
- Ambulatory surgery center same-day infusion protocols:These facilities are adopting on-body injectors for post-discharge therapy continuation, creating a channel distinct from traditional home healthcare distribution.
- Polymer-silicone hybrid skin-interface convergence:Advanced adhesive chemistries combined with breathable backing materials are enabling multi-day wear ratings previously unattainable with rigid thermoplastic housings.
Industry Challenges
- Electromechanical firmware validation talent scarcity:The intersection of embedded systems engineering and medical device quality assurance represents a constrained labor pool, extending development timelines for programmable dose platforms.
- REACH material compliance documentation burden:Component sourcing across European supply chains requires exhaustive substance-of-very-high-concern tracking, complicating multi-source procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global on-Body Injectors Market |
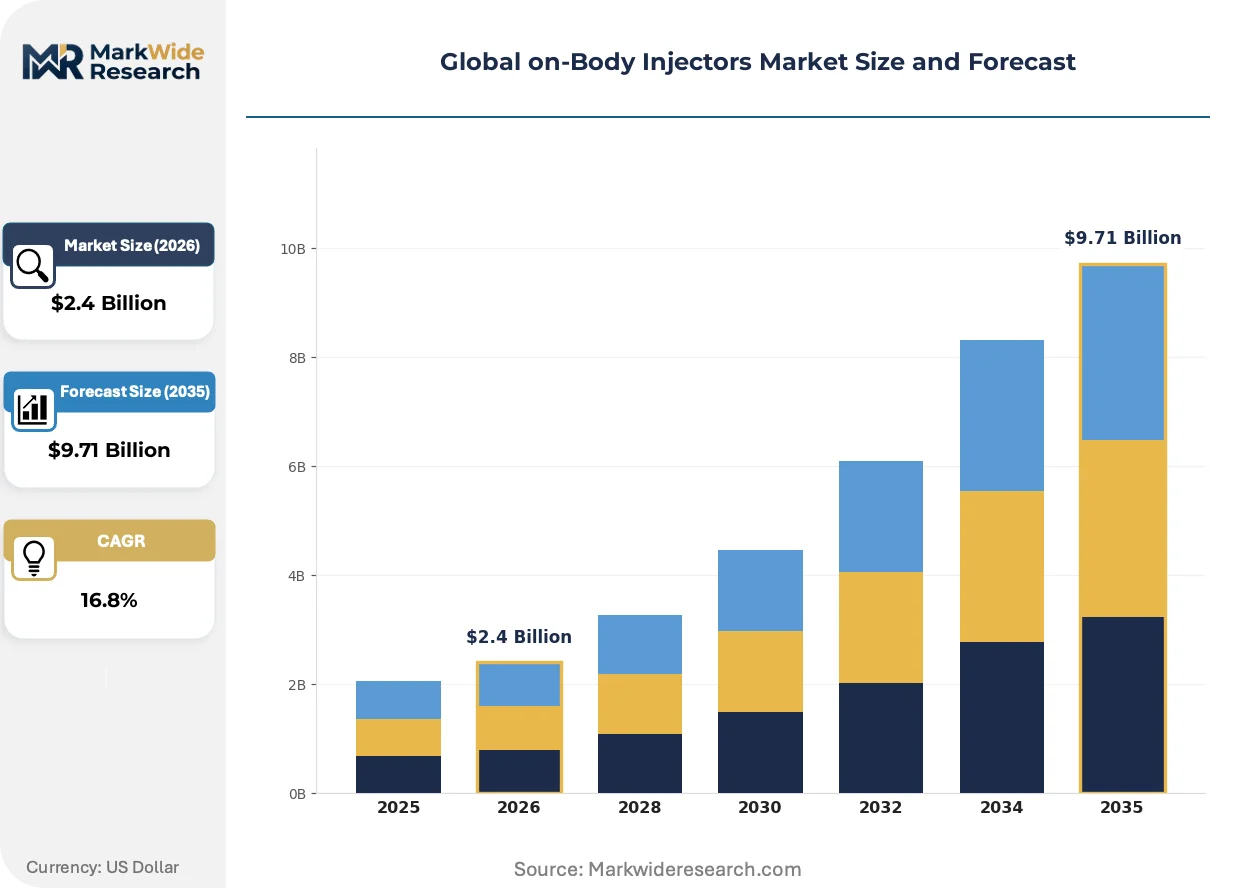
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $9.71 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Infusion Pumps, Patch Injectors, Pen Injectors, Automated Injectors Therapy Area: Diabetes Management, Hormone Therapy, Oncology Treatment, Immunotherapy, Pain Management End User: Home Healthcare, Specialty Clinics, Ambulatory Surgery Centers, Pharmacies Delivery Technology: Spring-Loaded, Electromechanical, Gas-Driven, Microfluidic |
| Companies Covered | Medtronic, Insulet Corporation, Amgen, Becton Dickinson, AbbVie, Johnson & Johnson, Ypsomed, West Pharmaceutical Services, Tandem Diabetes Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global on-Body Injectors Market Shifts & Advancements
Electromechanical precision architectures are compressing competitive differentiation around firmware-enabled dose titration, while material science advances in skin-contact polymers are redefining adhesion performance benchmarks across the device category.
Closed-loop insulin delivery systems are decentralizing chronic diabetes management from endocrinology clinics to patient-controlled environments. Adolescent and adult Type 1 diabetes populations in the United States and Germany are migrating rapidly from multiple daily injection regimens. This technology is decentralizing monitoring and therapeutic adjustment authority, compressing the traditional clinical intermediary role.
EU MDR device classification updates for electromechanical drug delivery platforms are elevating third-party notified body involvement in conformity assessment. Manufacturers now face mandatory clinical evidence requirements for programmable dose systems that were previously self-certified. European patch injector developers are responding by consolidating validation partnerships with established notified bodies in Germany and the Netherlands.
Hospital procurement committees are unbundling device acquisition from pharmaceutical contracting, forcing standalone economic justification for wearable delivery platforms. This pattern is most visible in United States integrated delivery networks, where pharmacy and medical device sourcing functions have separated. Device manufacturers must now demonstrate total cost-of-therapy reduction independent of drug volume commitments.
Global on-Body Injectors Market Segmentation
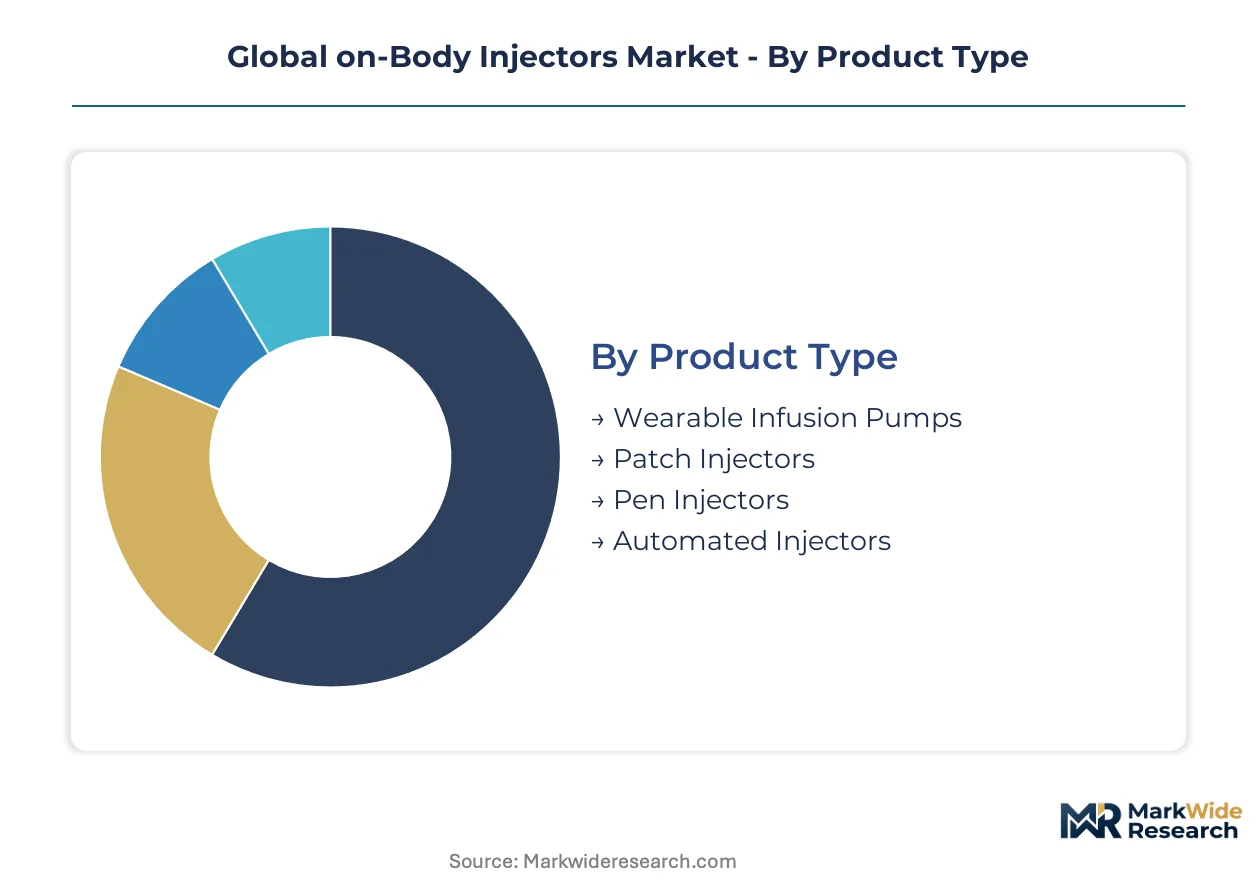
Device architectures and therapy applications segment the on-body injector landscape into distinct commercial battlegrounds. Each category carries divergent regulatory burdens and margin profiles that reshape competitive positioning across the forecast horizon.
Product Type:
FDA Class II and EU MDR Class IIa certifications dominate wearable infusion pumps and electromechanical patch injectors, while pen injectors navigate lighter self-certification pathways under ISO 11608.
- Patch Injectors:Adhesive-backed reservoir systems with multi-day skin adhesion ratings. Demand concentrates in the United States for large-volume monoclonal antibody delivery, constrained by polymer-grade liquid silicone rubber supply concentration in Switzerland and Germany.
- Wearable Infusion Pumps:Programmable electromechanical platforms with continuous subcutaneous delivery capability. Germany and Japan drive procurement volumes as closed-loop insulin delivery systems displace multiple daily injection regimens in Type 1 diabetes populations.
- Pen Injectors:Manual-dose cylindrical devices for intermittent hormone and insulin administration. Ypsomed anchors European supply through specialized manufacturing platforms.
- Automated Injectors:Pre-programmed single-use devices with electronic dose confirmation. Ambulatory surgery centers in the United States adopt these for same-day infusion protocols.
Leading the category by volume: Patch Injectors. Growing fastest: Wearable Infusion Pumps.
Therapy Area:
Reimbursement code maturity varies sharply across indications, with diabetes and oncology commanding established pathways while immunotherapy navigates evolving prior authorization frameworks.
- Diabetes Management:Closed-loop insulin delivery systems with real-time glucose-responsive dosing. The United States and Germany concentrate demand as patient populations migrate from endocrinology clinics to home-controlled environments.
- Oncology Treatment:Extended-duration subcutaneous biologics delivery for supportive care agents. Patch injector architectures with multi-day adhesion ratings capture preference for neutropenia and chemotherapy-induced nausea protocols.
- Hormone Therapy:Intermittent dosing regimens for endocrine disorders. Pen injector formats dominate due to lower unit cost and simplified patient training requirements.
- Immunotherapy:Checkpoint inhibitor and monoclonal antibody delivery for autoimmune conditions. EU MDR clinical evidence requirements for programmable dose systems filter smaller platform developers.
- Pain Management:Continuous local anesthetic infusion for post-surgical recovery. Ambulatory surgery centers represent the primary channel as unbundled procurement separates device acquisition from pharmaceutical contracting.
Highest reimbursement density: Diabetes Management. Steepest expansion trajectory: Immunotherapy.
End User:
Procurement authority fragmentation distinguishes institutional buyers from patient-direct channels, with integrated delivery networks unbundling pharmacy and medical device sourcing functions.
- Home Healthcare:Patient-controlled administration with third-party reimbursement support. The United States, Germany, and Japan anchor volume through durable wearable infusion codes.
- Ambulatory Surgery Centers:Same-day infusion protocols with post-discharge therapy continuation. These facilities gain traction as payors prioritize reduced hospitalization costs.
- Specialty Clinics:Endocrinology and oncology centers with in-house infusion capabilities. Prescribing authority concentrates device selection influence.
- Pharmacies:Retail distribution with patient training and adherence monitoring services. European markets favor this channel for pen injector formats.
Channel commanding largest volume: Home Healthcare. Expanding most quickly: Ambulatory Surgery Centers.
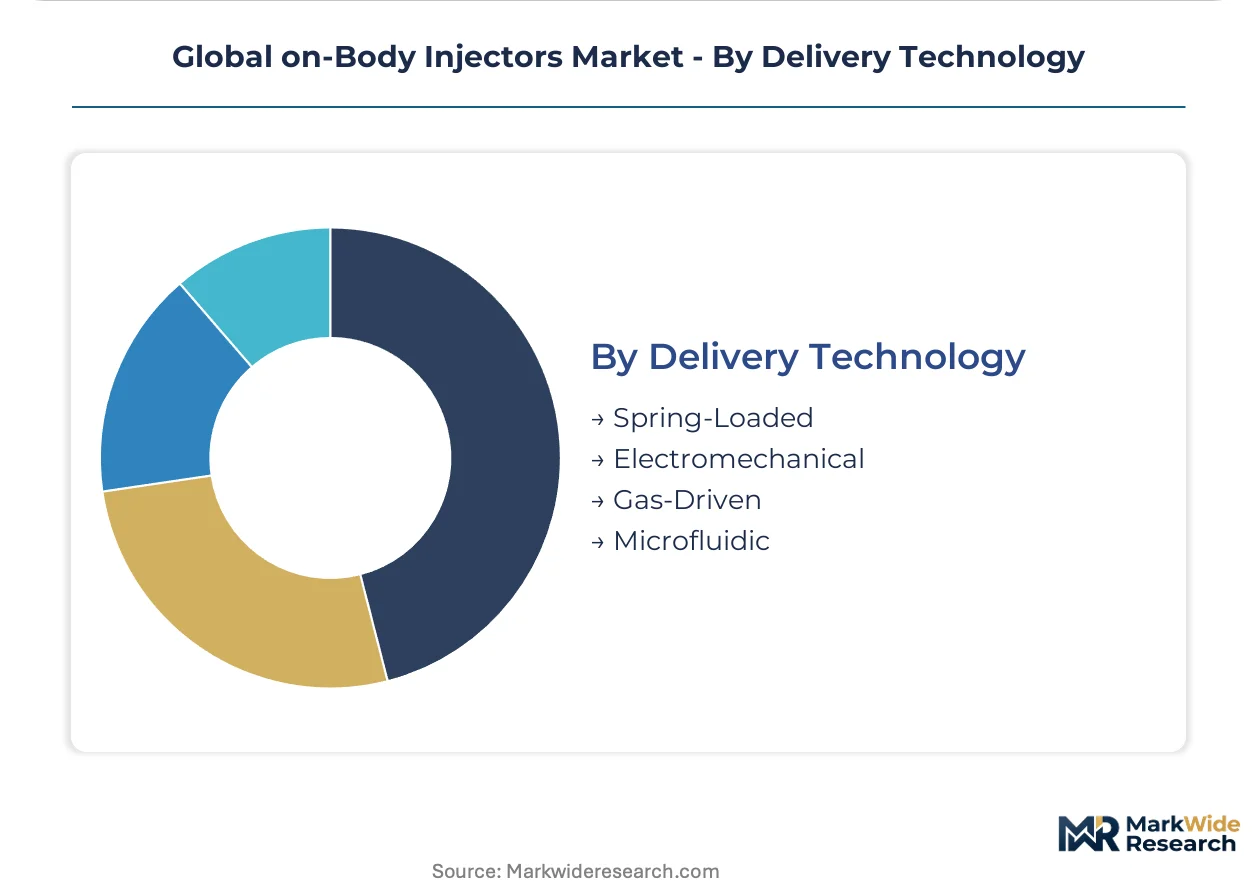
Delivery Technology:
Precision differentiation separates programmable platforms from mechanical alternatives, with firmware-enabled dose titration capturing premium positioning against fixed-dose gas-driven systems.
- Electromechanical:Motor-driven piston systems with programmable dose titration and Bluetooth connectivity. Firmware validation talent scarcity extends development timelines for platform developers.
- Spring-Loaded:Mechanical energy storage with fixed-dose delivery upon trigger activation. Lower unit cost sustains volume in price-sensitive hormone therapy segments.
- Gas-Driven:Compressed gas propellant systems for constant-rate infusion. Technical ceilings on programmable precision constrain addressable market to fixed-dose biologics.
- Microfluidic:Channel-based fluid manipulation with precise flow control. EU MDR conformity requirements elevate third-party notified body involvement, consolidating validation partnerships with German and Dutch assessors.
Technology capturing premium positioning: Electromechanical. Gaining share fastest: Microfluidic.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Shenzhen and Singapore concentrate electromechanical component sourcing for Asian device assembly. Swiss and German medical-grade polymer compounding clusters anchor European supply security. Reimbursement code maturity in the United States, Germany, and Japan determines commercialization sequencing across the forecast horizon.
United States
Integrated delivery networks in Texas and California unbundle pharmacy from device procurement, forcing standalone economic justification. FDA Class II device classification updates for programmable dose systems extend validation timelines for electromechanical entrants. The Greater Boston corridor concentrates closed-loop insulin delivery development alongside venture capital availability.
Germany
Notified bodies in Munich and Berlin consolidate EU MDR conformity assessment partnerships for microfluidic platform developers. REACH material compliance documentation requirements complicate multi-source procurement strategies for polymer-grade liquid silicone rubber. The Baden-Württemberg medical technology cluster anchors pen injector manufacturing specialization.
Japan
PMDA reimbursement determinations for wearable infusion in Type 1 diabetes management establish precedent economics for Asia-Pacific market entry. METI industrial policy supports domestic electromechanical precision manufacturing capacity expansion. The Kanto region around Tokyo concentrates adolescent diabetes population migration from clinic-based to home-controlled therapy administration.
Switzerland
Medical-grade LSR compounding capacity clusters in Basel and Zurich expose device housing supply to input cost volatility. Swissmedic device classification alignment with EU MDR reduces dual-track validation burden for export-oriented manufacturers. The Lake Geneva corridor anchors specialized adhesive chemistry development for multi-day skin adhesion ratings.
United Kingdom
NHS procurement frameworks for home-based biologics delivery concentrate demand assessment in the Midlands and Southeast England. MHRA post-Brexit regulatory divergence from EU MDR creates parallel conformity pathway complexity for platform developers. The Oxford-Cambridge arc concentrates microfluidic research translation into commercial drug delivery applications.
Global on-Body Injectors Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with electromechanical precision platforms consolidating around firmware-enabled differentiation while mechanical alternatives fragment across price-sensitive hormone therapy volumes. Three archetypes dominate: vertically integrated device-drug combination developers, specialized component suppliers with captive polymer compounding, and contract manufacturing organizations with FDA-registered sterile assembly lines. M&A activity concentrates on adhesive technology assets and electromechanical firmware talent pools, while capacity expansion targets automated liquid silicone rubber molding for multi-day adhesion ratings.
Among North American electromechanical developers, Insulet Corporation and Tandem Diabetes Care occupy positions in closed-loop insulin delivery, with the former exemplifying vertical integration into automated manufacturing and the latter representing precision dosing firmware specialization. Ypsomed anchors European pen injector supply through Switzerland-based manufacturing concentration. These three entities represent distinct competitive vectors: scale-driven cost leadership, electromechanical precision premium positioning, and regional supply security specialization.
| Leading Market Players |
|---|
| Medtronic |
| Insulet Corporation |
| Amgen |
| Becton Dickinson |
| AbbVie |
| Johnson & Johnson |
| Ypsomed |
| West Pharmaceutical Services |
| Tandem Diabetes Care |
| Others |
Supply & Pricing Matrix
Integrated delivery networks in the United States and Germany concentrate procurement authority for on-body injectors, anchoring contract-based long-term offtake agreements that tie unit pricing to multi-year volume commitments and FDA Class II validation status.
Pricing Analysis
Short lead-time premiums of fifteen to thirty percent apply to polymer-grade liquid silicone rubber compounding orders from Swiss and German suppliers, while spot inventory discounts emerge for standard-grade thermoplastic housings. Pricing stratifies across premium, standard, and economy tiers based on electromechanical firmware certification level and multi-day adhesion rating performance. Cost compression in spring-loaded mechanical platforms is intensifying because Asian contract manufacturers are expanding automated molding capacity. Ambulatory surgery centers exhibit highest price sensitivity due to unbundled procurement separating device acquisition from pharmaceutical contracting, while closed-loop insulin delivery systems in diabetes management show lowest sensitivity given reimbursement code maturity.
Supply Chain Analysis
Freight costs for medical-grade liquid silicone rubber from Switzerland and Germany to Asian assembly hubs have elevated landed costs for device housings, compressing margins on patch injector volumes. Supply concentrates in Switzerland for LSR compounding, Germany for electromechanical precision components, and China for automated molding and final assembly. Raw material dependencies span polymer-grade silicone, stainless steel cannula stock, and lithium-polymer power cells. Single-source vulnerability in Swiss LSR compounding capacity exposes device manufacturers to input cost volatility. Distribution runs through integrated delivery networks in the United States, specialized medical distributors in Germany, and direct hospital procurement in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EU MDR conformity requirement elevation is filtering smaller electromechanical platform developers from commercialization pathways, forcing weaker players toward exit or acquisition.
For Market Incumbents: To counter firmware validation talent scarcity extending development timelines, secure captive electromechanical engineering capacity through targeted acquisition of embedded systems specialists in the Greater Boston corridor. Deepen backward integration into automated liquid silicone rubber molding to insulate patch injector margins from Swiss and German supply concentration.
For New Entrants and Emerging Players: Direct-to-clinic digital channels for patient training and adherence monitoring bypass traditional distributor markups in European pen injector segments. Target pain management applications in United States ambulatory surgery centers as the most penetrable white-space, where unbundled procurement creates standalone economic justification windows. Prioritize microfluidic platform development with notified body pre-submission pathways in Germany and the Netherlands to compress validation timelines.
For Investors and Strategic Acquirers: The window for entry favors adhesive technology assets and electromechanical firmware talent pools over mechanical platform manufacturers facing technical ceilings. Long-term viability centers on programmable dose titration capabilities with multi-day skin adhesion ratings. Monitor Japan's Ministry of Health reimbursement determinations for closed-loop insulin delivery as the inflection signal establishing Asia-Pacific precedent economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Consolidation | EU MDR Class IIa certification timelines compress through German and Dutch assessor relationships. |
| Automated LSR Molding Capacity Expansion | Captive polymer-grade silicone processing insulates patch injector margins from Basel supply volatility. |
| Firmware Validation Talent Acquisition | Embedded systems engineering scarcity in medical device quality assurance extends development timelines. |
| Reimbursement Strategy Investment | Japan PMDA wearable infusion code expansion establishes Asia-Pacific market entry economics. |
| Ambulatory Surgery Center Channel Development | Same-day infusion protocol adoption creates distribution distinct from traditional home healthcare. |
Research Methodology
Multi-period observation of FDA Class II submission volumes, EU MDR notified body appointment patterns, and Japan PMDA reimbursement code determinations anchored the trend analysis, supplemented by interviews with biomedical engineers at integrated delivery networks, regulatory affairs leads at electromechanical platform developers, GPO contracts managers, and formulary directors at German sickness funds. Secondary validation drew from FDA 510(k) filings, EMA device classification guidance, ClinicalTrials.gov intervention records, and CMS Medicare durable medical equipment claims data. Bottom-up patient population modeling and top-down pharmaceutical manufacturer revenue allocation triangulated market sizing.
The input-output matrix structured demand forecasting across device architecture, therapy area, end-user channel, and delivery technology dimensions throughout the forecast period. CAGRs derived from regression analysis of historical reimbursement code expansion rates and biologics portfolio pipeline data. Electromechanical precision platform adoption curves and polymer-grade liquid silicone rubber supply elasticity informed scenario-weighted projections.
The model holds under stable FDA and EU MDR classification frameworks; deviation in notified body capacity constraints or Japan reimbursement determination delays would shift commercialization sequencing assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
US Nebulizer Market
Medical Devices
Peripheral Vascular Guide Wire Market
Medical Devices
Life Science Microscopy Devices Market
Medical Devices
Europe Otoscope Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Cranial Implants Treatment Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Tinnitus Maskers Market
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
Argentina Respiratory Devices Market
Medical Devices
Pipette Controllers Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Global Keratometers Market
Medical Devices
Airway Management Market