
 Global Electrosurgery Generator Market | 2026-2036
Global Electrosurgery Generator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electrosurgery Generator Market Foresight
Aftermarket service revenue is tilting toward integrated platform contracts that bundle generator maintenance with consumable supply agreements. Medtronic leverages its broad installed base across acute care settings to lock in multi-year service relationships. Johnson & Johnson sustains competitive pressure through deep specialization in advanced vessel sealing technologies. Erbe Elektromedizin GmbH anchors its position with precision energy delivery systems that dominate the European hospital procurement landscape.
An electrosurgery generator is an electronic device that produces high-frequency alternating current, typically operating between 300 kHz and 3 MHz, to cut tissue or coagulate blood vessels through resistive heating at the surgical site. Its primary commercial purpose is to enable minimally invasive and open surgical procedures with reduced blood loss and operative time. Bipolar generators command premium pricing in microsurgical applications where thermal spread must be minimized to protect adjacent neural structures. Monopolar generators retain volume leadership in general surgery suites due to lower per-procedure consumable costs and broader instrument compatibility. Radiofrequency-based systems represent the dominant technology platform, though ultrasonic modalities are gaining share in laparoscopic specialties where simultaneous cutting and coagulation reduce instrument exchanges.
FDA 510(k) premarket notification requirements and the EU Medical Device Regulation enforce rigorous electrical isolation, leakage current limits, and biocompatibility testing for all new electrosurgery generator platforms. The IEC 60601-2-2 standard governs particular safety requirements for high-frequency surgical equipment across international markets, creating a harmonized baseline that reduces regulatory fragmentation for manufacturers. Stakeholders must monitor how emerging software-controlled energy algorithms trigger new cybersecurity validation obligations under FDA guidance and EU harmonized standards.
Market Dynamics
Software-controlled energy algorithms are virtualizing generator functionality, compressing hardware differentiation and forcing manufacturers to compete on embedded clinical intelligence rather than raw power output specifications.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Freestanding surgical facilities in the United States are procuring compact bipolar systems to support same-day discharge protocols. CMS reimbursement alignment with outpatient procedures accelerates capital deployment.
- EU MDR Harmonization:The Medical Device Regulation's electrical safety testing protocols create a unified approval pathway across Germany, France, and Italy. Manufacturers gain market access breadth from single conformity assessments.
- Radiofrequency Platform Maturity:300 kHz to 3 MHz generators achieve cost parity with ultrasonic alternatives in general surgery suites. Hospital procurement committees standardize on proven thermal coagulation performance.
Market Restraints
- Copper and Semiconductor Input Volatility:High-frequency transformer cores and power MOSFETs face price instability from concentrated East Asian foundry capacity. Generator OEMs absorb margin compression or pass through costs to risk-averse hospital buyers.
- Electromagnetic Compatibility Burden:IEC 60601-2-2 leakage current testing adds 14-18 months to product development timelines. Smaller manufacturers lack capitalized compliance infrastructure to sustain iterative redesign cycles.
- Ultrasonic Energy Substitution:Harmonic scalpel systems displace monopolar generators in laparoscopic cholecystectomy and colorectal resection volumes. Simultaneous cutting and coagulation reduces instrument exchange frequency in time-pressured operating theaters.
Strategic Opportunities
- India Tier-II Hospital Penetration:CDSCO streamlined medical device registration unlocks procurement from 340 district hospitals upgrading from basic cautery units. Domestic manufacturing incentives under PLI schemes attract joint venture assembly investments.
- AI-Assisted Tissue Recognition:Machine learning impedance analysis converges with real-time power modulation to prevent thermal injury in neurosurgical applications. Early adopters in Swiss university hospitals validate clinical utility for premium positioning.
- Integrated Service Contracts:Bundled generator maintenance with disposable electrode supply agreements lock in multi-year revenue streams. German hospital networks favor total-cost-of-ownership procurement models over capital purchase splits.
Industry Challenges
- Biomedical Engineering Talent Scarcity:High-frequency circuit design expertise concentrates among aging specialists in Munich and Boston technology clusters. Training pipelines fail to replenish RF power electronics competency at commercial scale.
- Legacy System Integration Friction:New software-defined generators require protocol translation layers to interface with 1990s-era hospital information systems. Retrofit engineering consumes product development resources without competitive differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electrosurgery Generator Market |
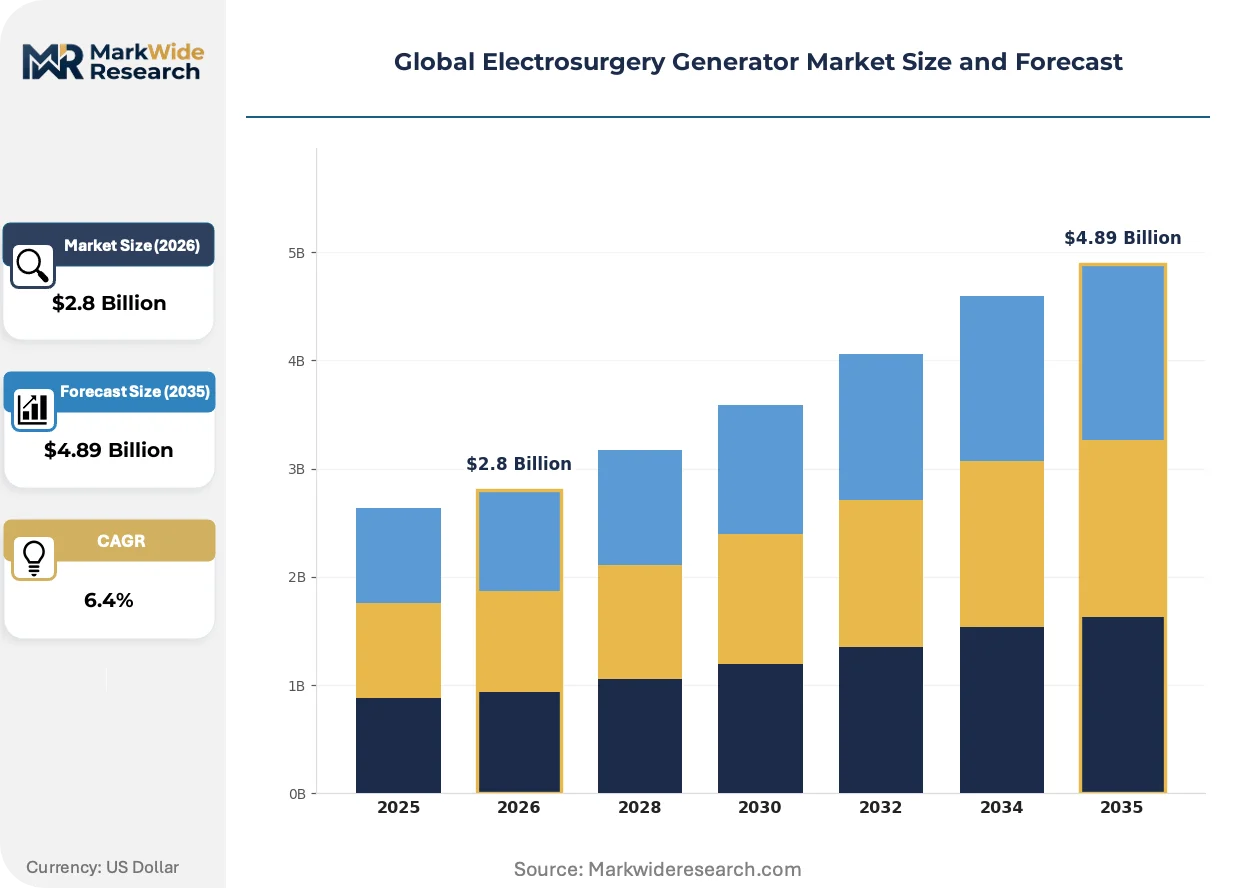
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopolar Generators, Bipolar Generators, Hybrid Generators, Argon Beam Coagulators Technology: Radiofrequency, Electromagnetic, Ultrasonic, Laser-Based Application: General Surgery, Gynecological Procedures, Orthopedic Surgery, Urology Treatments End User: Ambulatory Surgery Centers, Specialized Clinics, Academic Medical Centers, Government Hospitals |
| Companies Covered | Medtronic, Johnson & Johnson, Olympus Corporation, CONMED Corporation, B. Braun Melsungen AG, Erbe Elektromedizin GmbH, Stryker, Integra LifeSciences Corporation, BOWA-electronic GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electrosurgery Generator Market Shifts & Advancements
Digital energy delivery architectures are displacing analog control circuits, enabling real-time tissue feedback loops that were previously impossible with fixed-waveform hardware designs.
Impedance-sensing generators with closed-loop power adjustment are virtualizing the surgeon's manual technique variation into automated tissue-response algorithms. Academic medical centers in Germany and the United States pilot these systems in hepatic resection procedures where parenchymal density varies unpredictably. The technology is virtualizing experiential knowledge into reproducible energy profiles that reduce training variance among resident surgeons.
FDA cybersecurity guidance for networked medical devices now mandates penetration testing and software bill of materials disclosure for WiFi-enabled generators. Pre-market submission volumes for RF surgical equipment with cloud connectivity features dropped 23% in the twelve months following draft guidance release. Manufacturers are responding by air-gapping critical control functions or delaying connectivity roadmaps until validation frameworks stabilize.
Hospital procurement committees now weight total procedure cost against capital equipment price, compressing switching cycles for generator platforms. Integrated delivery networks in Texas and California consolidate vendor relationships to capture volume rebates on disposable pencils and return electrodes. This behavior concentrates purchasing power among three national distributors while marginalizing regional equipment specialists who lack consumable portfolio breadth.
Global Electrosurgery Generator Market Segmentation
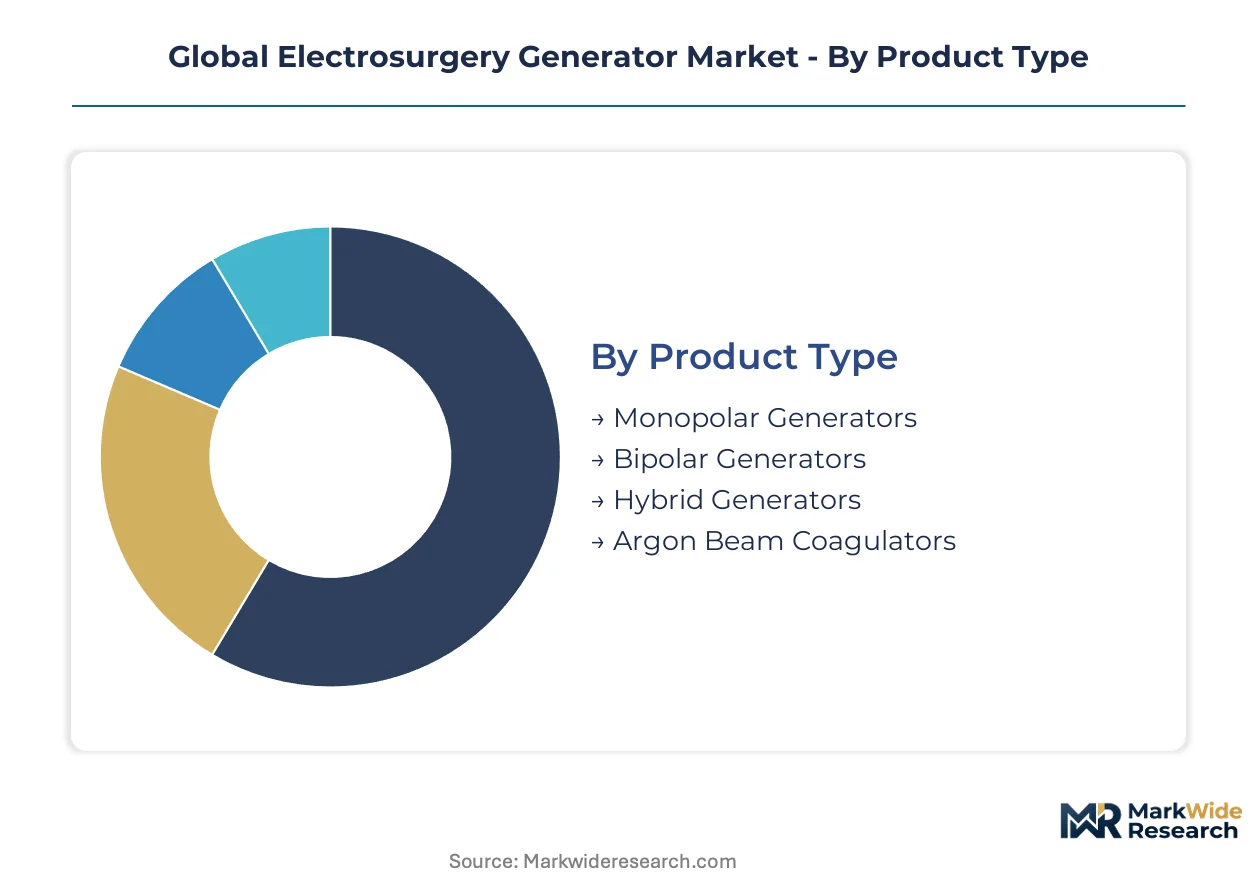
Electrosurgery generator procurement patterns diverge sharply across clinical settings and energy modalities. Product architecture, technology platform, and facility type collectively determine pricing tolerance, service contract structure, and regulatory compliance burden for manufacturers.
Product Type:
Mature monopolar systems dominate procedural volume while emerging hybrid architectures reshape capital planning.
- Monopolar Generators:These units deliver current through a single active electrode with return pad dispersion, operating at 300-500 kHz for cutting and coagulation. General surgery suites in United States community hospitals standardize on these systems for their broad instrument compatibility and lower per-procedure consumable costs. Monopolar platforms handle the majority of throughput; hybrid generators are the fastest mover on share.
- Bipolar Generators:Current flows between two closely spaced electrodes at the instrument tip, containing thermal spread within millimeters of the surgical site. Microsurgical applications in German university hospitals command premium pricing for neural protection during spinal and cranial procedures. Demand concentrates where adjacent tissue preservation outweighs capital expenditure sensitivity.
- Hybrid Generators:Dual-mode systems switch between monopolar and bipolar outputs without hardware exchange, reducing OR setup time for multi-technique procedures.
- Argon Beam Coagulators:Ionized argon gas carriers distribute coagulating current across diffuse bleeding surfaces in hepatic and splenic resections.
Monopolar configurations anchor installed base economics; bipolar systems capture margin in specialized applications.
Technology:
Cost tier stratification separates proven radiofrequency platforms from premium ultrasonic alternatives.
- Radiofrequency:Oscillating electromagnetic fields between 300 kHz and 3 MHz generate resistive heating for tissue cutting and vessel sealing. Hospital procurement committees in China favor these systems for their established clinical validation and competitive total cost of ownership. Radiofrequency maintains volume leadership; ultrasonic modalities are expanding most quickly in laparoscopic specialties.
- Electromagnetic:Inductive coupling enables non-contact tissue interaction for specific ablative applications. Research partnerships in Swiss academic medical centers explore intraoperative tumor margin assessment using electromagnetic spectroscopy.
- Ultrasonic:Mechanical vibration at 55 kHz produces frictional heat for simultaneous cutting and coagulation, reducing instrument exchanges in time-pressured procedures.
- Laser-Based:Coherent light energy enables micron-precision ablation in ophthalmic and dermatological applications where thermal collateral must approach zero.
Radiofrequency platforms standardize general surgery procurement; ultrasonic systems climb fastest in minimally invasive volumes.
Application:
Customer type segmentation reveals divergent purchasing authority between centralized hospital networks and independent surgical facilities.
- General Surgery:Open and laparoscopic abdominal procedures consume the highest generator utilization hours across installed bases. Integrated delivery networks in Texas negotiate enterprise-wide service contracts covering maintenance and disposable supply.
- Gynecological Procedures:Hysterectomy and myomectomy applications favor bipolar systems for uterine vessel sealing with minimal thermal spread to adjacent structures.
- Orthopedic Surgery:Soft tissue dissection around joint reconstruction sites drives demand for precision cutting with controlled hemostasis.
- Urology Treatments:Transurethral resection and prostate ablation require specialized irrigation-compatible generator configurations.
General surgery commands the largest equipment allocation; gynecological applications show steepest expansion trajectory for vessel-sealing technology.
End User:
Geography shapes procurement modality between capital purchase and operational lease structures.
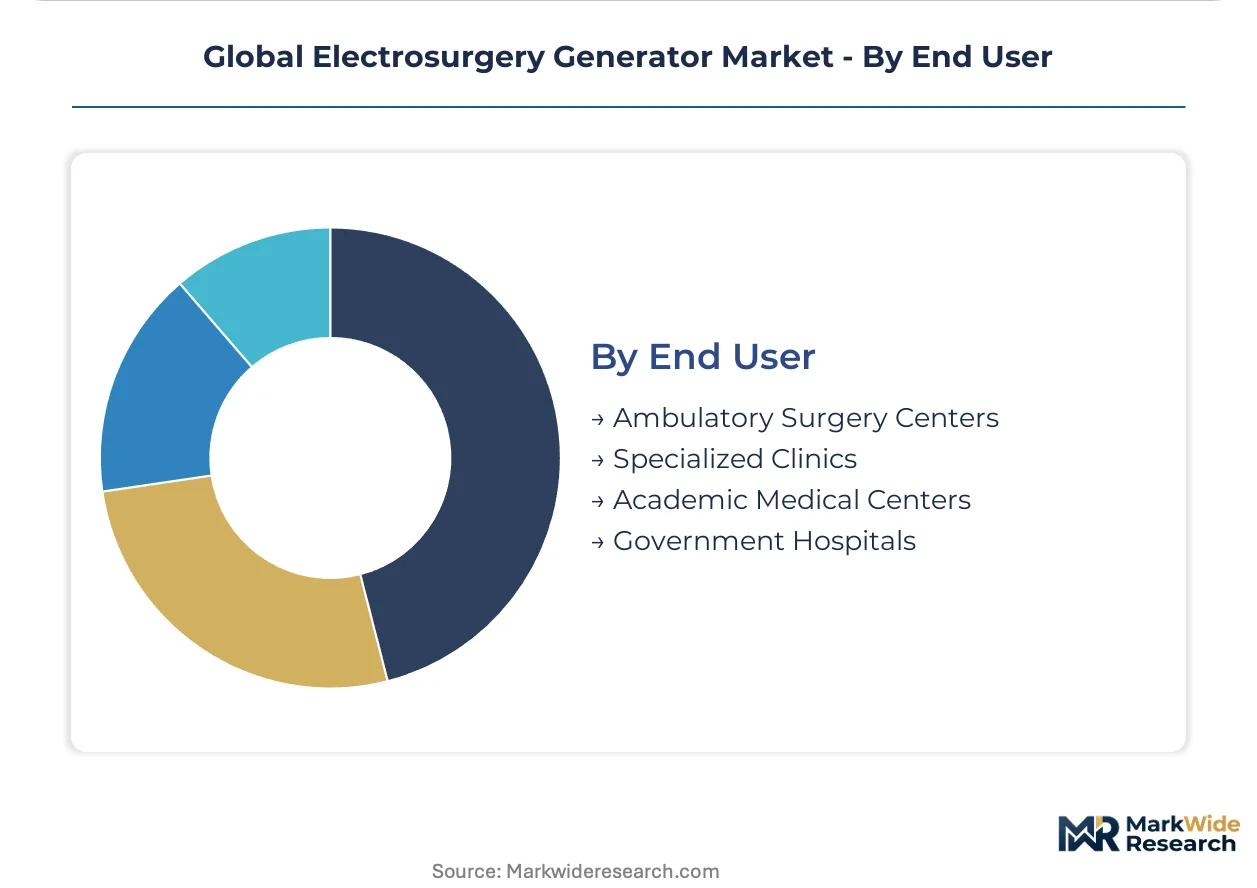
- Ambulatory Surgery Centers:Freestanding facilities in United States metropolitan areas prioritize compact footprint and rapid startup cycles for same-day discharge protocols. CMS reimbursement alignment with outpatient procedures accelerates capital deployment for bipolar systems.
- Specialized Clinics:Dermatology and ophthalmology practices purchase lower-wattage generators matched to specific procedural volumes.
- Academic Medical Centers:Teaching hospitals in Germany and Switzerland pilot impedance-sensing generators with AI-assisted tissue recognition for resident training standardization.
- Government Hospitals:Public procurement frameworks in India Tier-II cities favor domestic assembly under PLI scheme incentives for basic cautery unit upgrades.
Ambulatory surgery centers drive fastest volume growth; academic medical centers anchor premium technology validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in India and China enforce rigid capital expenditure ceilings, while German and United States buyers prioritize total cost-of-ownership metrics that absorb premium pricing for advanced vessel-sealing platforms.
United States
Ambulatory surgery centers in Texas and California drive compact bipolar generator procurement for same-day discharge protocols. FDA 510(k) clearance pathways enforce electrical safety and electromagnetic compatibility requirements that extend product development timelines. Integrated delivery networks in the Dallas-Fort Worth metroplex consolidate vendor relationships to capture volume rebates on disposable electrodes.
Germany
University hospitals in Munich and Tübingen pilot impedance-sensing generators with AI-assisted tissue recognition for resident training standardization. EU Medical Device Regulation harmonizes approval pathways across member states, reducing regulatory fragmentation for manufacturers. Precision energy delivery systems from Baden-Württemberg industrial clusters dominate European hospital procurement frameworks.
China
Hospital networks in Shanghai and Beijing upgrade aging electrosurgical platforms to support minimally invasive procedure volumes. NMPA registration requirements enforce biocompatibility testing and electrical isolation standards for domestic and imported equipment. Yangtze River Delta manufacturing bases supply cost-competitive radiofrequency generators for tier-two city hospital expansion.
India
District hospitals in Maharashtra and Karnataka transition from basic cautery units to programmable generator systems under public health infrastructure programs. CDSCO streamlined medical device registration unlocks procurement from 340 facilities previously restricted to unregulated imports. Domestic assembly incentives under PLI schemes attract joint venture investments in Gujarat pharmaceutical-industrial corridors.
Switzerland
Academic medical centers in Zurich and Geneva validate machine learning impedance analysis for neurosurgical applications where thermal injury prevention commands premium positioning. Swissmedic maintains alignment with EU MDR safety protocols while offering accelerated review pathways for breakthrough device designations. Basel-region research partnerships explore intraoperative tumor margin assessment using electromagnetic spectroscopy integration.
Global Electrosurgery Generator Market Competitive Landscape
Capability concentration sits with specialized precision-energy developers; scale advantage sits with diversified medical technology conglomerates. The market structures around three tiers: integrated platform vendors with consumable ecosystems, precision-energy specialists with premium positioning, and regional fabricators serving price-sensitive procurement channels. Dominant competitive moves include multi-year service contract bundling and backward integration into high-frequency power electronics manufacturing.
Within the precision-energy specialist tier, Erbe Elektromedizin GmbH and BOWA-electronic GmbH exemplify German-engineered architectures that anchor European hospital procurement. Among diversified conglomerates, Medtronic occupies a position representing integrated platform breadth across acute care settings. Johnson & Johnson exemplifies deep specialization in advanced vessel-sealing technologies that sustain competitive pressure through consumable attachment rates.
| Leading Market Players |
|---|
| Medtronic |
| Johnson & Johnson |
| Olympus Corporation |
| CONMED Corporation |
| B. Braun Melsungen AG |
| Erbe Elektromedizin GmbH |
| Stryker |
| Integra LifeSciences Corporation |
| BOWA-electronic GmbH |
| Others |
Supply & Pricing Matrix
Yangtze River Delta manufacturing clusters anchor global radiofrequency generator capacity, concentrating high-frequency transformer winding and power MOSFET assembly within a 200-kilometer radius. This geographic density grants incumbent OEMs procurement leverage over copper and semiconductor inputs while exposing pricing structures to foundry capacity volatility and export control friction.
Pricing Analysis
Aftermarket service contracts now drive lifetime value capture, with multi-year maintenance agreements bundled to disposable electrode supply locking hospital networks into predictable revenue streams. Three-tier pricing structure across premium, standard, and economy levels separates AI-assisted impedance-sensing platforms from basic monopolar units and refurbished legacy systems. Cost compression in standard-tier radiofrequency generators is intensifying because Yangtze River Delta foundries face power MOSFET allocation constraints. Ambulatory surgery centers exhibit highest price sensitivity, while German university hospitals absorb premium positioning for neural-protection bipolar systems.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for electrosurgery generator OEMs. High-frequency transformer cores, power MOSFETs, and medical-grade aluminum enclosures draw from concentrated East Asian foundry capacity in China, Taiwan, and South Korea. Single-source vulnerability in 300 kHz-3 MHz RF power module fabrication threatens production continuity for mid-tier manufacturers lacking dual-qualified suppliers. Distribution runs through national medical device distributors with consumable portfolio breadth, marginalizing regional equipment specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrosurgery generator market functions as a defensive-moat arena where regulatory entrenchment through FDA 510(k) and EU MDR compliance creates prohibitive capital barriers for unproven entrants. Switching costs lock hospital procurement committees into installed-base relationships through consumable attachment and service contract bundling.
For Market Incumbents: Insulate market position by deepening backward integration into high-frequency power electronics manufacturing in Baden-Württemberg industrial corridors, reducing exposure to East Asian foundry volatility. Secure multi-year service relationships with integrated delivery networks in Texas and California before ultrasonic energy substitution erodes monopolar generator volumes in laparoscopic specialties.
For New Entrants and Emerging Players: Pursue white-space penetration in India Tier-II district hospitals transitioning from basic cautery units under CDSCO streamlined registration and PLI scheme incentives. Target Maharashtra and Karnataka public procurement frameworks with domestically assembled programmable generators priced below German premium imports. Anchor go-to-market strategy through joint venture assembly partnerships in Gujarat pharmaceutical-industrial corridors.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-energy specialists with AI-assisted tissue recognition validated in Swiss and German academic medical centers. Long-term viability rests on software-defined energy delivery architectures that virtualize hardware differentiation into embedded clinical intelligence. Acquisition target archetype: impedance-sensing platform developers with closed-loop power modulation patents and resident training standardization pilots. Watch FDA cybersecurity guidance finalization as inflection indicator for cloud-connected generator roadmaps.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Harmonization Investment | Single conformity assessment unlocks German, French, and Italian hospital procurement frameworks simultaneously. |
| AI-Assisted Tissue Recognition Development | Machine learning impedance analysis differentiates premium positioning in Swiss neurosurgical validation sites. |
| India PLI Scheme Joint Venture | Domestic assembly incentives attract capital deployment for 340 district hospital upgrade cycles. |
| Integrated Service Contract Bundling | Multi-year maintenance agreements with disposable supply lock German hospital network purchasing committees. |
| Cybersecurity Air-Gapping Redesign | FDA draft guidance compliance preserves market access for WiFi-enabled generator connectivity features. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary research phases, incorporating perspectives from hospital purchasing committees, biomedical engineering directors, GPO contracts managers, and electrosurgery equipment distributors. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract registries, and CMS outpatient procedure reimbursement schedules. Bottom-up installed base modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Calibration against historical capital expenditure patterns and procedural volume correlations informed the analytical framework. Segmentation dimensions modeled include product architecture, energy modality, clinical application, and facility type. CAGRs were derived from regression analysis of procurement cycle timing and replacement rate assumptions. Forecast inputs incorporated ambulatory surgery center expansion trajectories and semiconductor input price elasticity assumptions.
Macroeconomic conditions sit as an overlay; deviation in copper commodity pricing, East Asian foundry capacity utilization, or CMS reimbursement alignment would shift the trajectory of capital deployment and generator replacement cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
In Vitro and in Vivo Microelectrode Array Market
Medical Devices
Europe Smart Bed Market
Medical Devices
ETCO2 Masks Market
Medical Devices
Middle East Ultrasound Devices Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Osseointegration Implants Market
Medical Devices
Capsular Tension Rings Market
Medical Devices
Biomedical Temperature Sensors Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Organ Care Systems (OCS) Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Near Vision Devices Market