
 Levofloxacin Lactate Injection Market | 2026-2036
Levofloxacin Lactate Injection Market Size, Share, and Industry Trends Forecast 2026-2036
Levofloxacin Lactate Injection Market Insights
CE marking under the EU Medical Device Regulation is reorganizing which manufacturers can serve European hospital buyers with sterile injectable antibiotics. Aurobindo Pharma leverages backward integration into active pharmaceutical ingredient production to control cost positions across vial and ampoule formats. Teva Pharmaceutical Industries anchors its position through generic portfolio breadth and established intravenous supply contracts with hospital group purchasing organizations. Sandoz International GmbH differentiates via biosimilar-adjacent manufacturing discipline and European regulatory dossier depth.
Levofloxacin lactate injection is a sterile aqueous solution of the S-enantiomer of ofloxacin complexed with lactic acid, typically formulated at concentrations between 5 mg/mL and 25 mg/mL for intravenous administration, functioning as a broad-spectrum bactericidal agent against Gram-positive and Gram-negative pathogens in acute bacterial infections. The product type landscape shows vials dominating hospital procurement due to dosing flexibility, while pre-filled syringes gain traction in outpatient care settings where medication error reduction carries premium value. Application segmentation reveals antibacterial treatment as the mature revenue base, with surgical procedures representing the fastest-growing indication as peri-prophylaxis protocols expand in orthopedic and abdominal surgery.
The US FDA's boxed warning requirements for fluoroquinolone tendon and neuropathy risks shape prescribing thresholds and product liability exposure for all market participants. China's NMPA enforces Good Manufacturing Practice certification for sterile injectable production lines, filtering domestic supply to hospitals through centralized volume-based procurement. India's CDSCO mandates bioequivalence documentation for generic levofloxacin lactate formulations entering public health programs. Stakeholders must monitor how antimicrobial resistance surveillance data from WHO and national health agencies redirect hospital formulary decisions away from broad-spectrum fluoroquinolones toward targeted therapy alternatives.
Market Dynamics
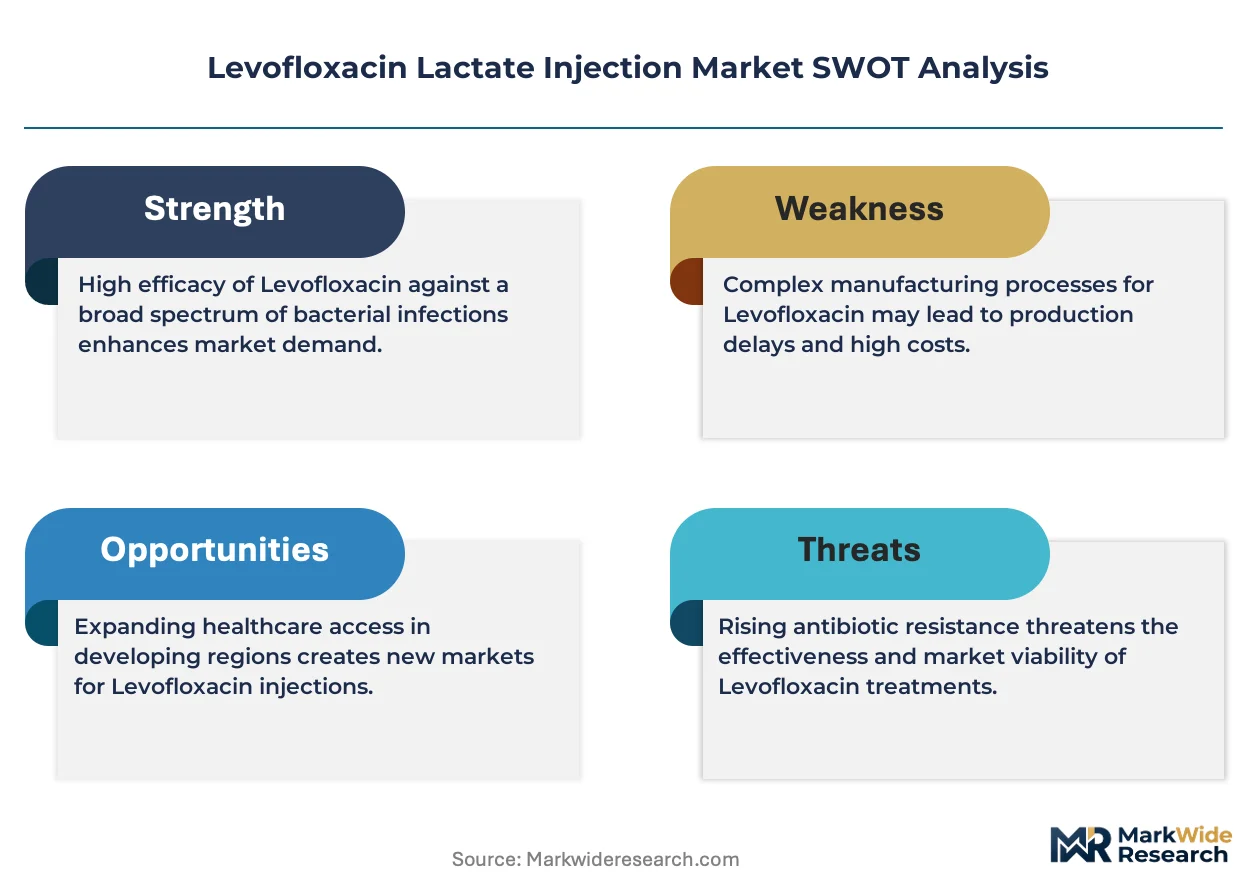
Centralized hospital procurement systems are compressing margins for injectable fluoroquinolone manufacturers while antimicrobial stewardship programs tighten formulary access, forcing suppliers to demonstrate clinical differentiation beyond cost.
Growth Catalysts
- Perioperative prophylaxis protocols:Orthopedic and abdominal surgery departments in Chinese tier-one hospitals are expanding levofloxacin lactate use for infection prevention, driving volume through standardized surgical bundles.
- India's CDSCO bioequivalence mandates:Generic injectable qualification requirements for public health programs are filtering out substandard suppliers and consolidating procurement toward documented manufacturers.
- Pre-filled syringe technology:Outpatient infusion centers and ambulatory surgery facilities are adopting unit-dose formats to reduce medication errors and nursing preparation time.
Market Restraints
- Active pharmaceutical ingredient concentration:China-based API suppliers control upstream levofloxacin base production, exposing finished dose manufacturers to input cost volatility and supply allocation decisions.
- FDA boxed warning scope:Tendon rupture and peripheral neuropathy risk disclosures have elevated prescribing thresholds in US hospital formularies, restricting automatic substitution privileges.
- Antimicrobial resistance surveillance:WHO and national health agency data are redirecting hospital antibiotic committees toward narrower-spectrum alternatives for routine empiric therapy.
Strategic Opportunities
- Centralized volume-based procurement in China:Domestic manufacturers with NMPA GMP-certified sterile lines can secure multi-year hospital supply contracts through provincial tendering consortia.
- CE marking under EU MDR:European hospital buyers face supplier consolidation as legacy dossiers expire, creating entry windows for manufacturers with updated technical documentation and notified body certification.
- Biosimilar-adjacent manufacturing discipline:Companies with sterile injectable capabilities developed for biologics can leverage quality systems and aseptic processing expertise to differentiate in commodity antibiotic segments.
Industry Challenges
- Aseptic processing qualification:Sterile injectable production lines require sustained media fill validation and environmental monitoring compliance, consuming technical resources and extending facility approval timelines.
- Legacy intravenous contract renegotiation:Hospital group purchasing organizations are unbundling historical fluoroquinolone supply agreements and introducing competitive rebidding cycles that compress contract duration and price predictability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Levofloxacin Lactate Injection Market |
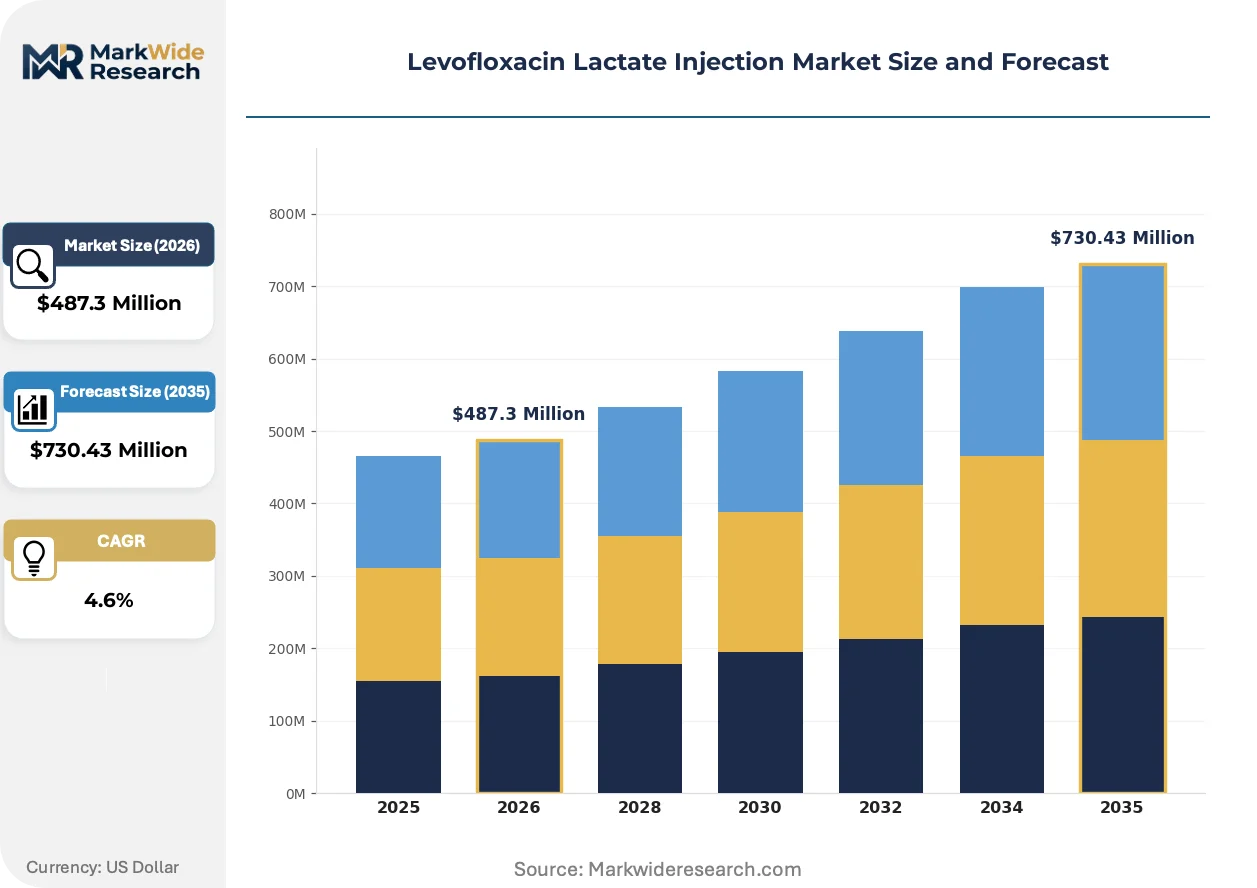
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $730.43 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Pre-filled Syringes, Bulk Solution Application: Antibacterial Treatment, Hospital Use, Outpatient Care, Surgical Procedures Delivery Mode: Intravenous, Intramuscular, Subcutaneous, Oral End User: Hospitals, Clinics, Home Healthcare, Pharmacies |
| Companies Covered | Harbin Pharmaceutical Group, Shanghai Huazhong Pharmaceutical, Aurobindo Pharma, Sandoz International GmbH, Teva Pharmaceutical Industries, Lupin Limited, Dr. Reddy's Laboratories, Zydus Lifesciences, Cipla, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Levofloxacin Lactate Injection Market Trends and Innovations
Injectable antibiotic manufacturing is undergoing process intensification as regulatory scrutiny tightens and hospital buyers demand supply chain transparency from API source to patient administration.
Continuous manufacturing technology for sterile injectable production is decomposing traditional batch-based processing economics. European and North American contract manufacturers are piloting integrated flow chemistry and aseptic filling lines to reduce hold times and contamination risk. This technology is decomposing the historical cost advantage of large-scale batch facilities by enabling smaller, flexible output with equivalent unit economics.
EU MDR Article 117 requirements for drug-device combination products are forcing manufacturers of pre-filled syringe formats to integrate quality management systems across pharmaceutical and medical device standards. Notified bodies are demanding expanded clinical evidence for primary container closure integrity. Sterile injectable suppliers with European regulatory dossier depth are capturing hospital procurement decisions as competitors face documentation gaps.
Hospital pharmacy committees are consolidating antibiotic formularies around stewardship metrics rather than acquisition cost alone. US health systems are tying physician prescribing privileges to indication-specific approval pathways, replacing automatic therapeutic substitution. This behavioral shift is most visible in academic medical centers where infectious disease pharmacists now control peri-prophylaxis protocol design and post-operative infection surveillance reporting.
Levofloxacin Lactate Injection Market Segmentation
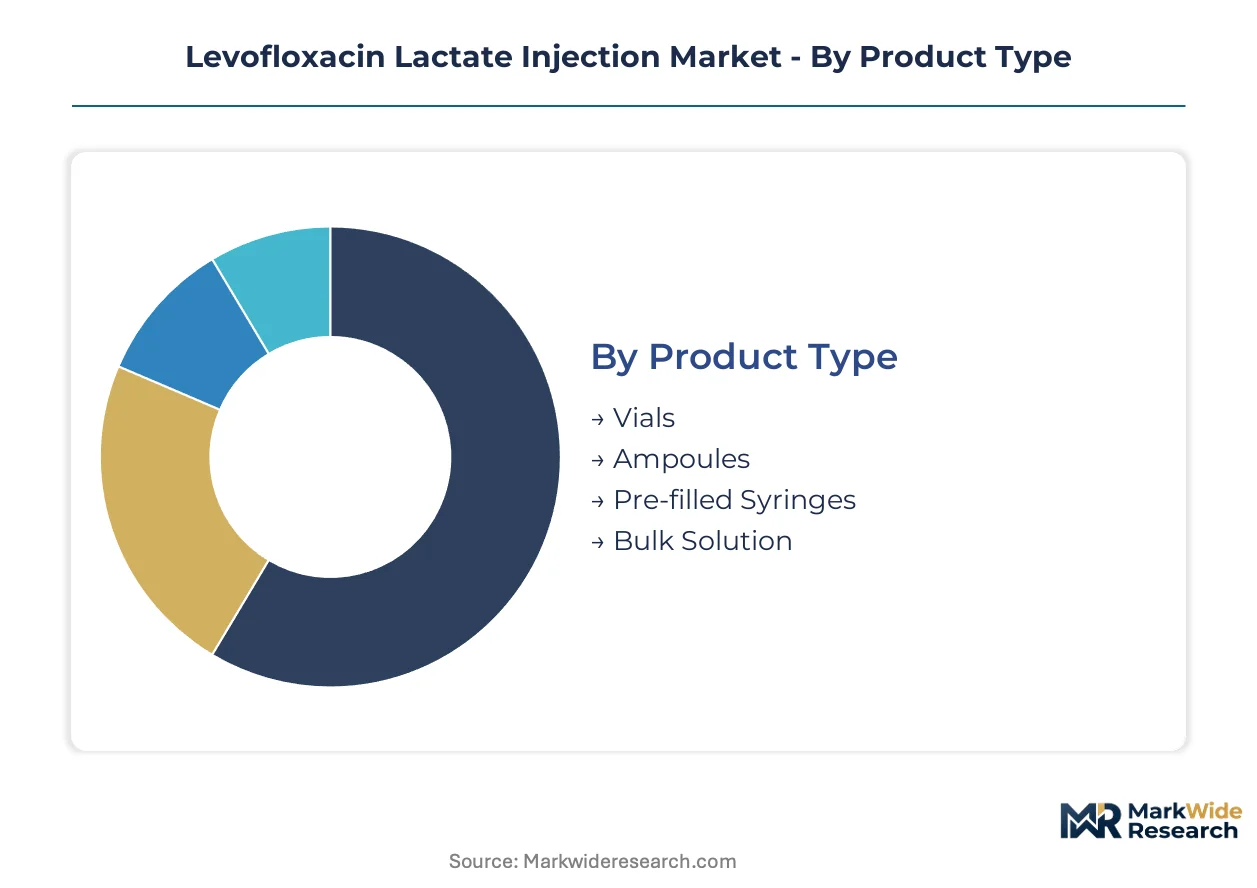
Injectable fluoroquinolone procurement varies sharply by container format and care setting, with hospital formulary committees applying distinct technical specifications to each category. Regulatory packaging requirements and medication safety protocols create divergent margin structures across the four segmentation dimensions.
Product Type:
FDA container closure integrity guidelines and EU MDR Article 117 compliance requirements differentiate which formats qualify for institutional procurement contracts.
- Vials:Multi-dose glass containers with rubber stoppers and aluminum seals allow flexible dosing across weight-based protocols. Chinese tier-one hospitals source vials through centralized volume-based procurement, with NMPA GMP certification filtering supplier pools to domestic manufacturers with validated sterile lines.
- Pre-filled Syringes:Unit-dose presentations integrate drug and delivery device, requiring combined pharmaceutical and medical device quality systems. Outpatient infusion centers in the United States adopt this format to reduce nursing preparation time and medication error liability under Joint Commission patient safety standards.
- Ampoules:Single-use glass containers scored for clean break, common in emergency department and field medicine settings where immediate access outweighs multi-dose efficiency.
- Bulk Solution:Large-volume parenteral bags for pharmacy compounding operations, supplying hospital central admixture services with standardized antibiotic stock for individualized patient dosing.
Established volume favors vials; emerging adoption favors pre-filled syringes.
Application:
Clinical indication drives reimbursement coding and antimicrobial stewardship committee oversight intensity.
- Surgical Procedures:Perioperative prophylaxis protocols in orthopedic and abdominal surgery represent the steepest expansion trajectory as bundled payment models incentivize infection rate reduction. Chinese provincial health commissions standardize surgical antibiotic bundles, concentrating procurement through tier-one hospital networks.
- Antibacterial Treatment:Empiric and definitive therapy for respiratory, urinary, and skin structure infections constitutes the mature revenue base, with FDA boxed warning restrictions elevating prescribing thresholds in US hospital formularies.
- Hospital Use:Inpatient administration across medical and surgical wards, subject to formulary restriction and therapeutic substitution protocols managed by infectious disease pharmacists.
- Outpatient Care:Ambulatory infusion center and home health administration, requiring stability data supporting extended dwell time and patient self-management education.
Revenue concentration rests with antibacterial treatment; protocol expansion drives surgical procedures.
Delivery Mode:
Bioavailability requirements and vascular access considerations shape route selection across acute and chronic care settings.
- Intravenous:Direct vascular administration achieves rapid therapeutic levels in septic patients, with central line-associated bloodstream infection prevention protocols governing catheter maintenance in US intensive care units.
- Intramuscular:Depot absorption for patients without reliable venous access, common in resource-limited settings and emergency department step-down care.
- Subcutaneous:Alternative parenteral route for extended outpatient therapy, requiring formulation adjustment to reduce tissue irritation.
- Oral:Bioequivalent tablet and liquid formulations for step-down therapy, with CDSCO bioequivalence documentation required for Indian public health program inclusion.
Acute care dependency centers on intravenous; transition protocols elevate oral step-down.
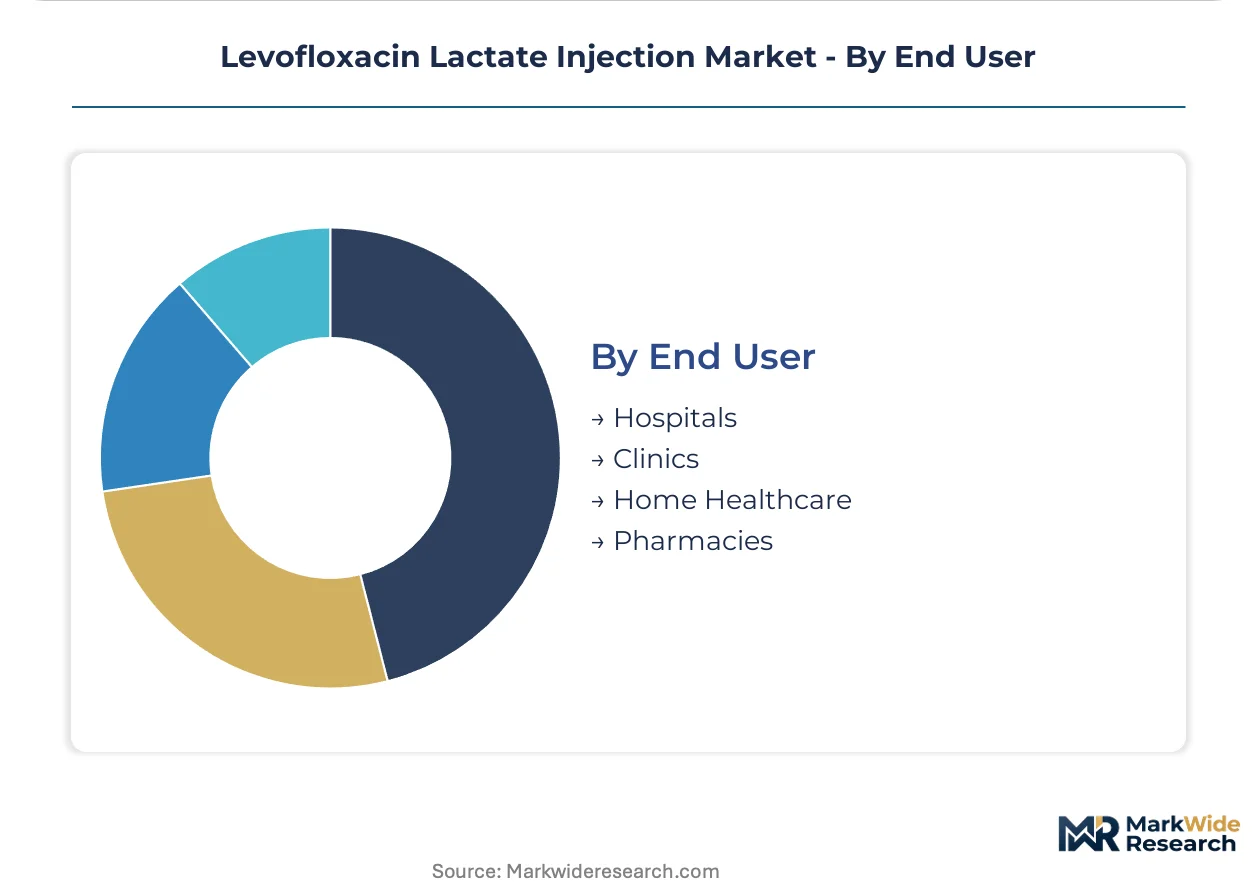
End User:
Purchasing authority and reimbursement mechanism create distinct customer archetypes with divergent price sensitivity and technical requirements.
- Hospitals:Integrated delivery networks and academic medical centers with group purchasing organization contracts, antimicrobial stewardship committees, and value-based care accountability. China's centralized procurement schemes consolidate hospital purchasing through provincial tendering consortia.
- Clinics:Outpatient procedure centers and urgent care facilities with limited formulary autonomy, dependent on hospital system supply agreements or wholesale distribution.
- Home Healthcare:Infusion nursing services and patient self-administration programs, requiring patient education materials and stability data for ambient temperature transport.
- Pharmacies:Retail and specialty pharmacy dispensing for outpatient parenteral antimicrobial therapy, with US 340B program pricing affecting acquisition cost for eligible entities.
Procurement scale concentrates in hospitals; service expansion characterizes home healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement authorities in China, the United States, and India concentrate the majority of injectable fluoroquinolone demand through centralized purchasing schemes and antimicrobial stewardship protocols. European buyers under EU MDR compliance deadlines are consolidating supplier relationships toward notified body-certified manufacturers. Emerging volume growth tracks surgical bundle standardization in tier-one hospital networks across Asia-Pacific markets.
China
Provincial volume-based procurement consortia in Jiangsu and Guangdong are consolidating hospital antibiotic purchasing toward domestic manufacturers with NMPA GMP-certified sterile lines. The National Healthcare Security Administration's centralized tendering schemes filter supplier pools through quality-tier assessments. Shanghai and Beijing tier-one hospitals anchor demand concentration as surgical infection prevention protocols expand across orthopedic and abdominal service lines.
United States
Academic medical centers and integrated delivery networks are tightening fluoroquinolone formulary access through infectious disease pharmacist oversight of peri-prophylaxis protocols. FDA boxed warning requirements for tendon and neuropathy risks elevate prescribing thresholds and reshape group purchasing organization contract negotiations. The Boston and New York hospital clusters demonstrate concentrated stewardship program implementation with automated therapeutic substitution restrictions.
India
CDSCO bioequivalence mandates for generic injectable antibiotics are filtering public health program procurement toward documented manufacturers with validated sterile production. Maharashtra and Gujarat pharmaceutical manufacturing zones supply domestic hospital demand while serving export markets under WHO prequalification pathways. Central government hospital procurement schemes prioritize cost containment alongside quality certification compliance.
Germany
EU MDR Article 117 compliance deadlines are reorganizing hospital buyer relationships toward manufacturers with updated technical documentation and notified body certification. The Rhine-Ruhr and Bavarian hospital networks concentrate demand for pre-filled syringe formats under medication safety protocols. Federal Institute for Drugs and Medical Devices enforcement of drug-device combination standards is accelerating supplier consolidation.
Japan
PMDA quality management system requirements for sterile injectable production are shaping procurement relationships between university hospitals and domestic manufacturers. The Kanto and Kansai metropolitan hospital clusters drive demand for high-purity formulations with extended stability data. Ministry of Health, Labour and Welfare antimicrobial stewardship guidelines are redirecting perioperative prophylaxis protocols toward documented clinical outcomes.
Levofloxacin Lactate Injection Market Competitive Landscape
Player mix skews toward vertically integrated pharmaceutical conglomerates with captive API production and sterile manufacturing infrastructure. Market structure concentrates around three strategic tiers: multinational generic houses with global regulatory dossier depth, regional champions serving domestic procurement schemes, and contract manufacturers with aseptic processing specialization. Competitive dynamics center on backward integration into levofloxacin base production and CE marking attainment under EU MDR timelines.
Among multinational generic houses, Aurobindo Pharma, Teva Pharmaceutical Industries, and Sandoz International GmbH exemplify divergent strategic positioning. Aurobindo Pharma represents the backward-integrated archetype with captive API supply chains controlling cost positions across container formats. Teva Pharmaceutical Industries anchors the portfolio-breadth model through established intravenous supply contracts with hospital group purchasing organizations. Sandoz International GmbH occupies the European regulatory specialization tier, leveraging biosimilar-adjacent manufacturing discipline and notified body relationship depth to capture procurement decisions as legacy dossiers expire.
| Leading Market Players |
|---|
| Harbin Pharmaceutical Group |
| Shanghai Huazhong Pharmaceutical |
| Aurobindo Pharma |
| Sandoz International GmbH |
| Teva Pharmaceutical Industries |
| Lupin Limited |
| Dr. Reddy's Laboratories |
| Zydus Lifesciences |
| Cipla |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts with Chinese tier-one hospitals lock in multi-year supply access and price visibility through provincial volume-based procurement schemes, compressing margin flexibility for manufacturers while securing sterile line utilization rates.
Pricing Analysis
Cost-plus contracts with API indexation to levofloxacin base commodity markets dominate hospital procurement negotiations. Three-tier pricing structure across NMPA GMP-certified premium, standard CDSCO-documented, and economy non-certified tiers separates manufacturers by regulatory dossier depth. Pricing pressure stems from centralized tendering consortia unbundling historical supply agreements. Academic medical centers exhibit lowest price sensitivity due to stewardship protocol requirements, while outpatient clinics face acute cost compression.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Ningbo port congestion periodically disrupt API-to-finished-dose workflows for European and North American manufacturers. Supply concentrates in China for levofloxacin base production, India for generic formulation, and Germany for pre-filled syringe device integration. Finished dose manufacturing draws from lactic acid complexing agents, borosilicate glass containers, and rubber closure components. Single-source vulnerability in Chinese API supply creates exposure to export license suspensions. Distribution runs through hospital group purchasing organizations and provincial tendering consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Perioperative prophylaxis protocol expansion in Chinese tier-one hospitals signals early-cycle penetration growth for sterile injectable antibiotics, with surgical bundle standardization creating embedded demand visibility.
For Market Incumbents: Shield formulary positions by securing NMPA GMP certification renewals ahead of EU MDR Article 117 compliance deadlines. Backward integration into levofloxacin base production insulates against API allocation decisions by Chinese suppliers. Pre-filled syringe capacity expansion captures outpatient medication safety premiums. For New Entrants and Emerging Players: Lead with CE marking attainment under EU MDR timelines to capture hospital procurement decisions as legacy dossiers expire. White-space exists in Indian public health program supply following CDSCO bioequivalence mandate enforcement. Target ambulatory surgery center pre-filled syringe adoption with unit-dose medication error reduction value propositions. For Investors and Strategic Acquirers: Sterile injectable contract manufacturers with aseptic processing specialization represent the priority acquisition archetype. Long-term viability hinges on antimicrobial stewardship program resilience versus narrow-spectrum substitution. Monitor WHO resistance surveillance data redirection as the inflection signal for fluoroquinolone formulary access contraction.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA GMP Certification Renewal | Qualifies manufacturers for China's provincial volume-based procurement hospital contracts. |
| CE Marking Pathway Completion | Enables European hospital access as EU MDR Article 117 deadlines force supplier consolidation. |
| Backward Integration into API | Captures levofloxacin base supply control insulating against Chinese export allocation volatility. |
| Pre-filled Syringe Manufacturing Scale-Up | Addresses outpatient infusion center demand for Joint Commission medication safety compliance. |
| Hospital System Partnership | Secures antimicrobial stewardship committee endorsement for peri-prophylaxis protocol inclusion. |
Research Methodology
A spread of perspectives from hospital procurement managers, infectious disease pharmacists, regulatory affairs leads, and sterile manufacturing executives converged on the working assumptions. Primary interviews combined with secondary validation against FDA filings, NMPA GMP certification databases, EMA submissions, and hospital formulary records. Bottom-up volume modeling triangulated against top-down market sizing across the analysis window.
Segmentation dimensions modeled include container format, clinical indication, delivery mode, and end-user purchasing authority. CAGRs derived from weighted average of historical trajectory and adoption curve projections. Forecast inputs incorporated antimicrobial stewardship program penetration rates and surgical bundle protocol expansion timelines.
The analysis sits within stated boundaries; outcomes outside sustained NMPA enforcement, EU MDR implementation timelines, or WHO resistance surveillance redirection would require recalibration. Model assumptions reflect current regulatory frameworks and hospital procurement structures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Famotidine Market
Pharmaceuticals
Bacterial Vaginosis Treatment Market
Pharmaceuticals
Homocystinuria Therapeutics Market
Pharmaceuticals
Europe Insulin Drugs and Glucagon-Like Peptide 1 (GLP-1) Receptor Agonist Market
Pharmaceuticals
Global Local Anesthesia Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Norovirus Treatment Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Europe Adenomyosis Drugs Market
Pharmaceuticals
Influenza Antiviral Market
Pharmaceuticals
Europe FMD Vaccine Market
Pharmaceuticals
Gastrointestinal OTC Drugs Market
Pharmaceuticals
Etomidate Market
Pharmaceuticals
Cervical Cancer Vaccine Market
Pharmaceuticals
Intravenous Pegloticase Market