
 Global Automated Dispensing Machines Market | 2026-2036
Global Automated Dispensing Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automated Dispensing Machines Market Analysis
Aftermarket service revenue is narrowing as a margin pool as hardware commoditization pressures original equipment manufacturers. Omnicell Inc. extends its service footprint through software-enabled remote diagnostics. Becton Dickinson and Company anchors its position with deep integration into hospital enterprise resource planning systems. Baxter International Inc. leverages its infusion therapy installed base to cross-sell automated dispensing units.
Automated dispensing machines are electromechanical systems that store, count, and distribute pharmaceuticals through barcode verification, weight-sensing drawers, and robotic retrieval mechanisms, primarily serving to eliminate manual dispensing errors in high-volume medication environments. Prescription dispensing machines lead product type revenue due to chronic disease prescription volumes, while IoT-enabled machines represent the fastest-expanding technology segment as cloud-connected inventory management reduces stockout incidents. Point-of-care machines occupy a mature niche with slower replacement cycles but stable margins from intensive care unit installations.
The FDA enforces 21 CFR Part 11 electronic record requirements that shape machine software validation costs, while the EU MDR imposes clinical evidence standards on devices with patient interface functions. Japan's PMDA maintains distinct pharmaceutical handling certifications that complicate direct product transfers from Western manufacturers. Stakeholders must monitor evolving interoperability mandates between dispensing systems and electronic health record platforms.
Market Dynamics
Hospital pharmacy consolidation is compressing vendor margins while forcing automated dispensing suppliers to embed software layers that lock in enterprise clients through electronic health record interoperability mandates.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization requirements for track-and-trace compliance are compelling acute care facilities to upgrade legacy dispensing infrastructure with barcode-verified units.
- Robotic retrieval mechanisms:Weight-sensing drawer systems combined with automated counting are eliminating manual verification steps in high-volume chemotherapy and emergency medication environments.
- Japan:Hospital consolidation into regional medical clusters is driving centralized pharmacy investments with multi-site inventory visibility requirements.
Market Restraints
- Stainless steel and precision motor costs:Input price volatility for electromechanical components is squeezing hardware margins for mid-tier equipment manufacturers.
- German component suppliers:Concentration of servo motor and sensor production in Baden-Württemberg creates geographic supply risk for non-integrated vendors.
- EU MDR clinical evidence standards:Patient interface functions now require expanded documentation, extending certification timelines by twelve to eighteen months for new machine introductions.
Strategic Opportunities
- India:Private hospital chains in Maharashtra and Karnataka are deploying first-generation automated dispensing with CDSCO medical device registration creating a compliance moat for early entrants.
- Cloud-connected inventory management:IoT-enabled machines with predictive stockout algorithms are penetrating long-term care facilities previously served by manual cart-fill systems.
- Remote diagnostics channels:Software-enabled service models are unbundling maintenance contracts from hardware sales, creating recurring revenue streams in installed base expansion.
Industry Challenges
- Biomedical technician certification:Shortage of technicians qualified for electromechanical and pharmaceutical handling dual certification is extending deployment timelines in community hospital settings.
- Legacy EHR integration:HL7 FHIR interoperability mandates are forcing expensive middleware development for machines installed before 2020, complicating upgrade economics for budget-constrained facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automated Dispensing Machines Market |
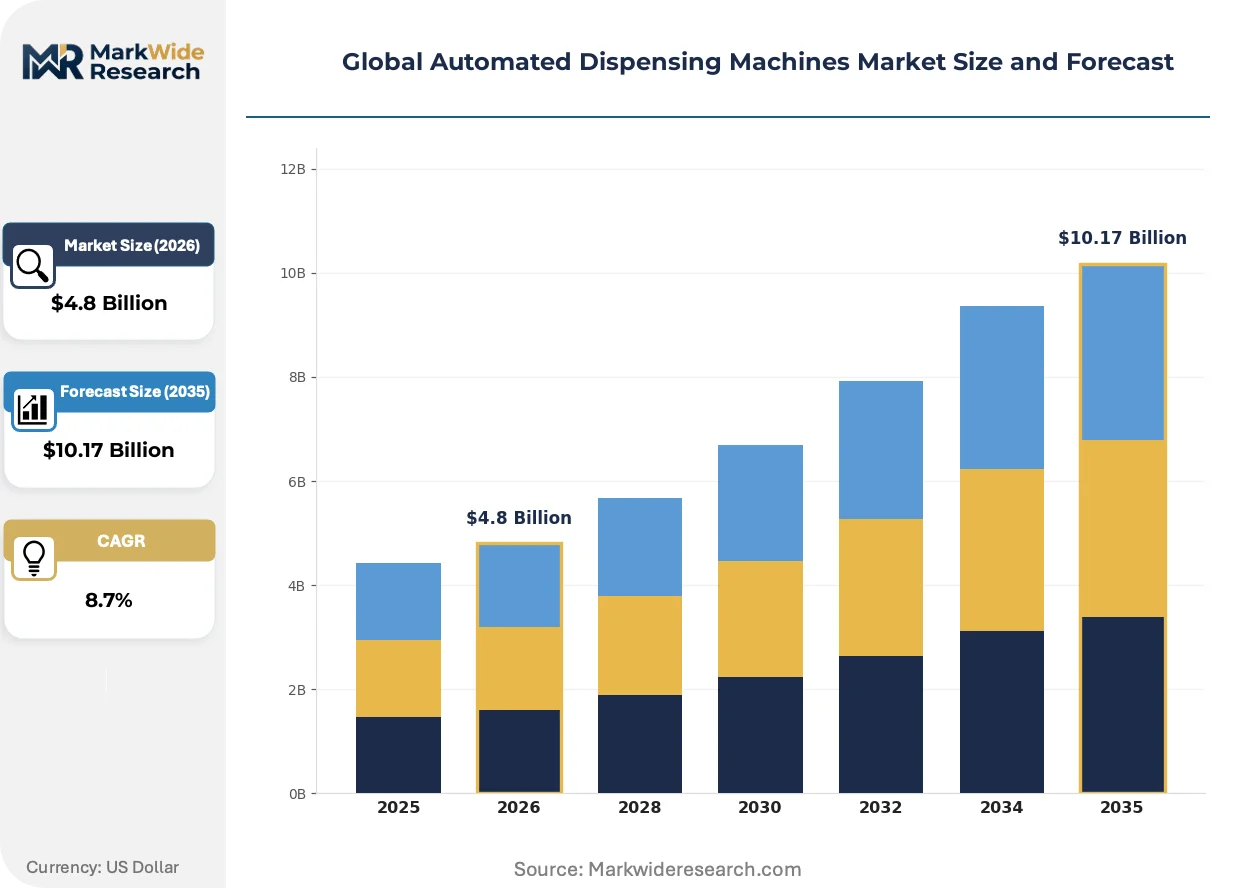
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vending Machines, Prescription Dispensing Machines, Point-of-Care Machines, Cashless Payment Machines End User: Hospitals, Pharmacies, Retail Stores, Clinics Technology: IoT-Enabled Machines, RFID-Based Machines, Manual Machines, Smart Systems Deployment: Indoor, Outdoor, Mobile, Fixed Locations |
| Companies Covered | B Braun Melsungen AG, ScriptPro LLC, Omnicell Inc., ARxIUM Inc., Yuyama Co Ltd, Becton Dickinson and Company, Swisslog Holding Limited, Willach Pharmacy Solutions, Baxter International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automated Dispensing Machines Market Emerging Trajectories
Machine intelligence is migrating from back-end inventory tracking to point-of-care decision support, compressing the traditional separation between dispensing hardware and clinical software layers.
Computer vision verification is hybridizing with barcode scanning in next-generation dispensing cabinets. These systems perform pill-level image recognition for dose validation. Academic medical centers in the United States are piloting installations in oncology satellite pharmacies. The technology is hybridizing quality assurance workflows by embedding visual inspection directly into retrieval sequences, reducing pharmacist verification bottlenecks during high-acuity shifts.
Japan's PMDA revised its pharmaceutical handling equipment certification framework in 2023, requiring thermal stability documentation for climate-controlled storage modules. Domestic manufacturers have accelerated R&D investment in temperature-logging sensor arrays. Export-oriented suppliers from Switzerland and Germany are establishing local testing partnerships to satisfy distinct documentation requirements, fragmenting previously standardized product platforms.
Long-term care procurement is consolidating purchasing authority into regional pharmacy service corporations, displacing individual facility capital budgets. These entities negotiate enterprise-wide equipment leases with remote monitoring service bundles. The shift is most visible in Germany's Pflegekassen reimbursement zones, where centralized dispensing is reducing per-bed medication administration labor costs across multi-site operator networks.
Global Automated Dispensing Machines Market Segmentation
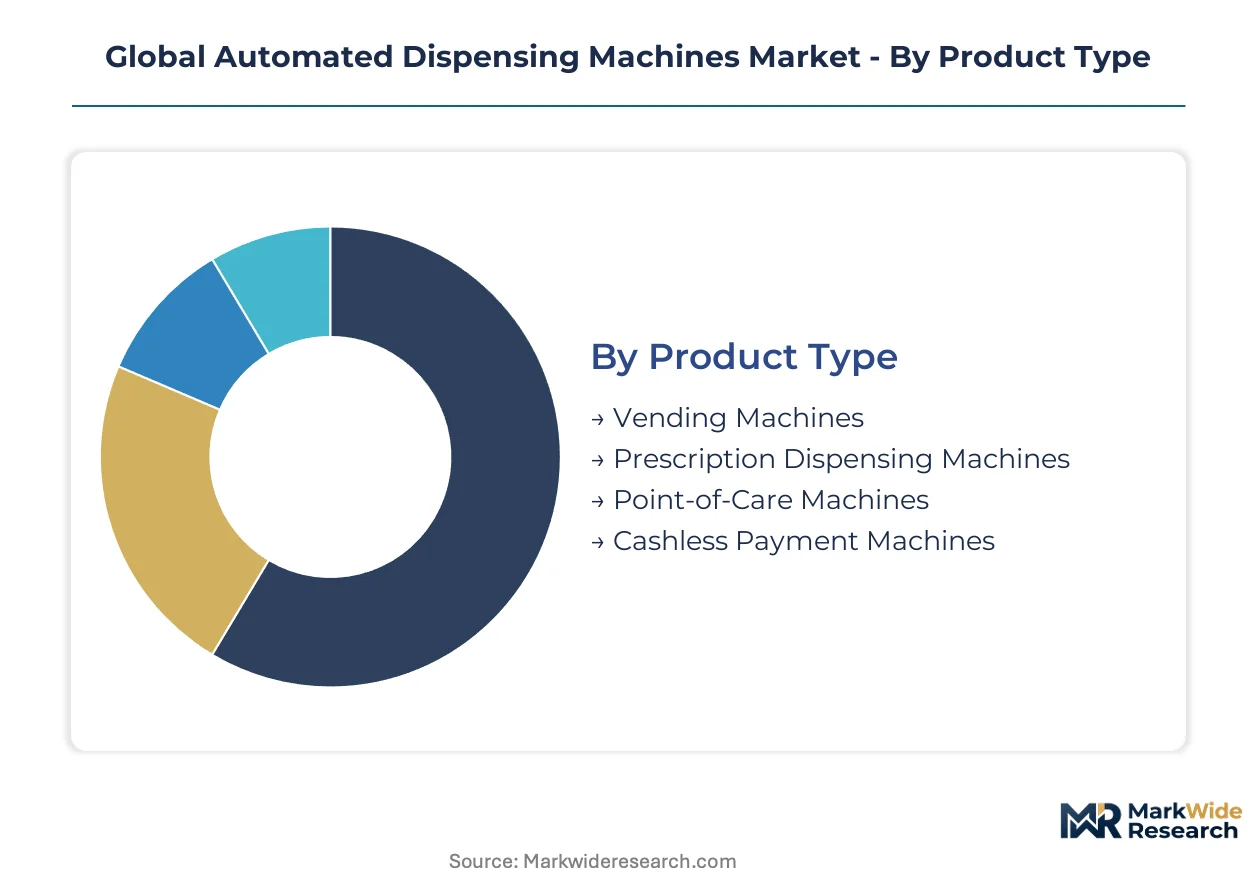
Segmentation in automated dispensing machines reveals distinct value capture patterns across hardware configurations, care settings, and connectivity architectures. Each dimension carries specific regulatory footprints and margin structures that shape vendor positioning strategies.
Product Type:
Use-case spectrum spans high-acuity clinical environments through consumer-facing retail automation, with electromechanical complexity and software integration depth varying dramatically across the range.
- Prescription Dispensing Machines:These systems integrate barcode verification, weight-sensing drawers, and robotic retrieval mechanisms for high-volume pharmaceutical distribution. Demand concentrates in hospital pharmacies across the United States and Germany, driven by FDA Drug Supply Chain Security Act serialization mandates and health system consolidation into centralized fulfillment models.
- Point-of-Care Machines:Compact units designed for intensive care unit and emergency department deployment with immediate access protocols. Installations cluster in Japan's regional medical clusters, where PMDA pharmaceutical handling certifications and multi-site inventory visibility requirements sustain replacement cycles despite mature market conditions.
- Vending Machines:Consumer-facing units for over-the-counter products and wellness categories. Retail pharmacy chains in Germany's Pflegekassen reimbursement zones deploy these for after-hours access.
- Cashless Payment Machines:Integrated payment terminals enabling card and mobile transactions. Urban clinic networks in Maharashtra and Karnataka adopt these alongside first-generation automated dispensing infrastructure.
Established volume favors Prescription Dispensing Machines; emerging adoption favors Point-of-Care Machines.
End User:
Customer type determines procurement authority structure, with enterprise-level purchasing displacing individual facility capital budgets across developed markets.
- Hospitals:Acute care facilities with enterprise resource planning integration requirements and 21 CFR Part 11 electronic record compliance obligations. Consolidated health systems in the United States negotiate multi-site equipment leases with remote monitoring service bundles.
- Pharmacies:Centralized fulfillment operations serving long-term care networks. Germany's regional pharmacy service corporations drive this segment through enterprise-wide procurement.
- Clinics:Outpatient settings with limited biomedical technician availability. CDSCO medical device registration in India creates compliance barriers for early entrants.
- Retail Stores:Non-clinical environments with lower regulatory burden but higher price sensitivity. Margins compress due to hardware commoditization pressures.
Procurement concentration favors Hospitals; regulatory pathway clarity favors Pharmacies.
Technology:
Connectivity architecture separates legacy installed base from next-generation platforms, with cloud integration creating recurring revenue opportunities distinct from hardware margins.
- IoT-Enabled Machines:Cloud-connected systems with predictive stockout algorithms and remote diagnostics capabilities. Long-term care facilities previously served by manual cart-fill systems represent expanding demand in Germany and Japan.
- Smart Systems:Integrated platforms combining computer vision verification with barcode scanning for pill-level image recognition. Academic medical centers in the United States pilot these in oncology satellite pharmacies.
- RFID-Based Machines:Track-and-trace infrastructure for inventory management without full cloud connectivity. Serves budget-constrained community hospitals.
- Manual Machines:Basic electromechanical units without network integration. Replacement cycles accelerate as HL7 FHIR interoperability mandates force middleware investments.
Cloud-connected platforms are expanding most quickly; electromechanical-only units face displacement pressure.
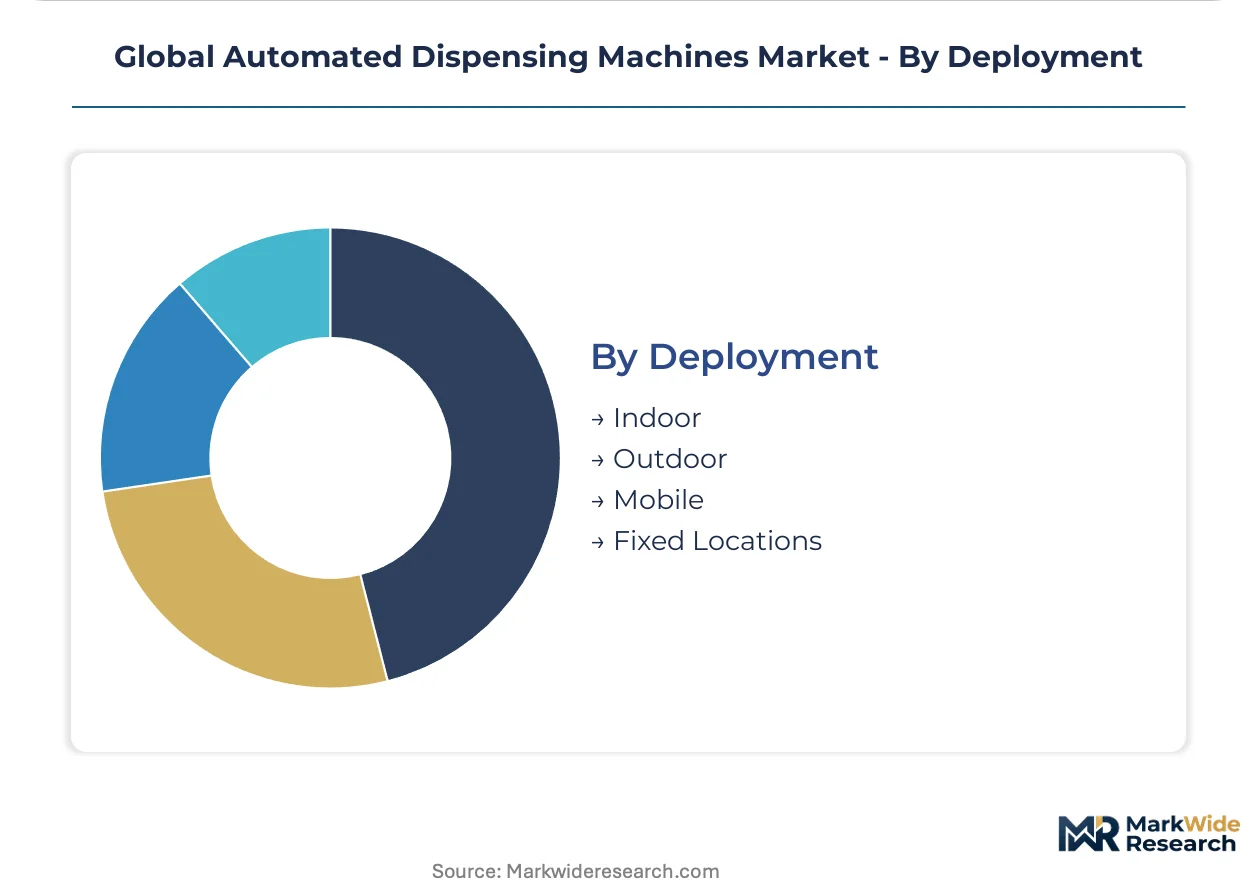
Deployment:
Physical installation mode reflects care delivery location strategy and environmental protection requirements for pharmaceutical stability.
- Indoor:Climate-controlled environments with thermal stability documentation for storage modules. Japan's PMDA 2023 framework revision accelerated R&D investment in temperature-logging sensor arrays.
- Fixed Locations:Permanent installation with deep electronic health record integration. Hospital pharmacy consolidation favors this deployment mode.
- Mobile:Transportable units for emergency response and temporary clinical facilities. Servo motor and sensor supply concentration in Baden-Württemberg creates geographic risk for non-integrated vendors.
- Outdoor:Weather-hardened enclosures for remote access points. Limited adoption due to pharmaceutical handling certification complexity.
Climate-controlled indoor deployment dominates value capture; mobile configurations address supply chain resilience requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German hospital systems absorb premium hardware costs for regulatory compliance, while Indian private chains prioritize entry-level units with software-enabled service bundles to manage capital constraints.
United States
Health system consolidation into regional networks drives enterprise-wide equipment leases with remote monitoring service bundles. FDA enforcement of 21 CFR Part 11 electronic record requirements shapes software validation costs for new installations. Academic medical centers in Boston and the Research Triangle pilot computer vision verification systems in oncology satellite pharmacies.
Germany
Pflegekassen reimbursement zones consolidate purchasing authority into regional pharmacy service corporations negotiating multi-site equipment contracts. EU MDR clinical evidence standards extend certification timelines for patient interface functions. Servo motor and sensor production concentrates in Baden-Württemberg, creating geographic supply risk for non-integrated vendors.
Japan
Hospital consolidation into regional medical clusters drives centralized pharmacy investments with multi-site inventory visibility requirements. PMDA revised its pharmaceutical handling equipment certification framework in 2023, requiring thermal stability documentation for climate-controlled storage modules. Domestic manufacturers in the Kanto region accelerated R&D investment in temperature-logging sensor arrays.
India
Private hospital chains in Maharashtra and Karnataka deploy first-generation automated dispensing with CDSCO medical device registration creating compliance barriers for late entrants. Biomedical technician shortages extend deployment timelines in community hospital settings. Mumbai and Bangalore clusters see concentrated procurement from enterprise pharmacy operators.
Switzerland
Export-oriented suppliers establish local testing partnerships to satisfy Japan's distinct PMDA documentation requirements, fragmenting previously standardized product platforms. Swissmedic maintains alignment with EU MDR standards while preserving national notification procedures for pharmaceutical handling devices. Basel and Zurich host specialized testing facilities serving cross-border certification needs.
Global Automated Dispensing Machines Market Vendor Landscape
Capability concentration sits with integrated system architects; scale advantage sits with diversified healthcare conglomerates. The vendor base separates into three tiers: full-stack platform providers, component-specialized fabricators, and regional service integrators. Strategic moves center on software-enabled remote diagnostics unbundling and electronic health record interoperability mandates that lock in enterprise clients.
Among diversified medical technology conglomerates, Becton Dickinson and Company and Baxter International Inc. occupy positions anchoring hardware sales through deep enterprise resource planning integration and cross-selling from adjacent installed bases. Omnicell Inc. represents the platform-specialist archetype with software-enabled service footprint expansion. Yuyama Co Ltd and Willach Pharmacy Solutions exemplify regional specialists with concentrated geographic presence.
| Leading Market Players |
|---|
| B Braun Melsungen AG |
| ScriptPro LLC |
| Omnicell Inc. |
| ARxIUM Inc. |
| Yuyama Co Ltd |
| Becton Dickinson and Company |
| Swisslog Holding Limited |
| Willach Pharmacy Solutions |
| Baxter International Inc. |
| Others |
Supply Flow & Price Mechanics
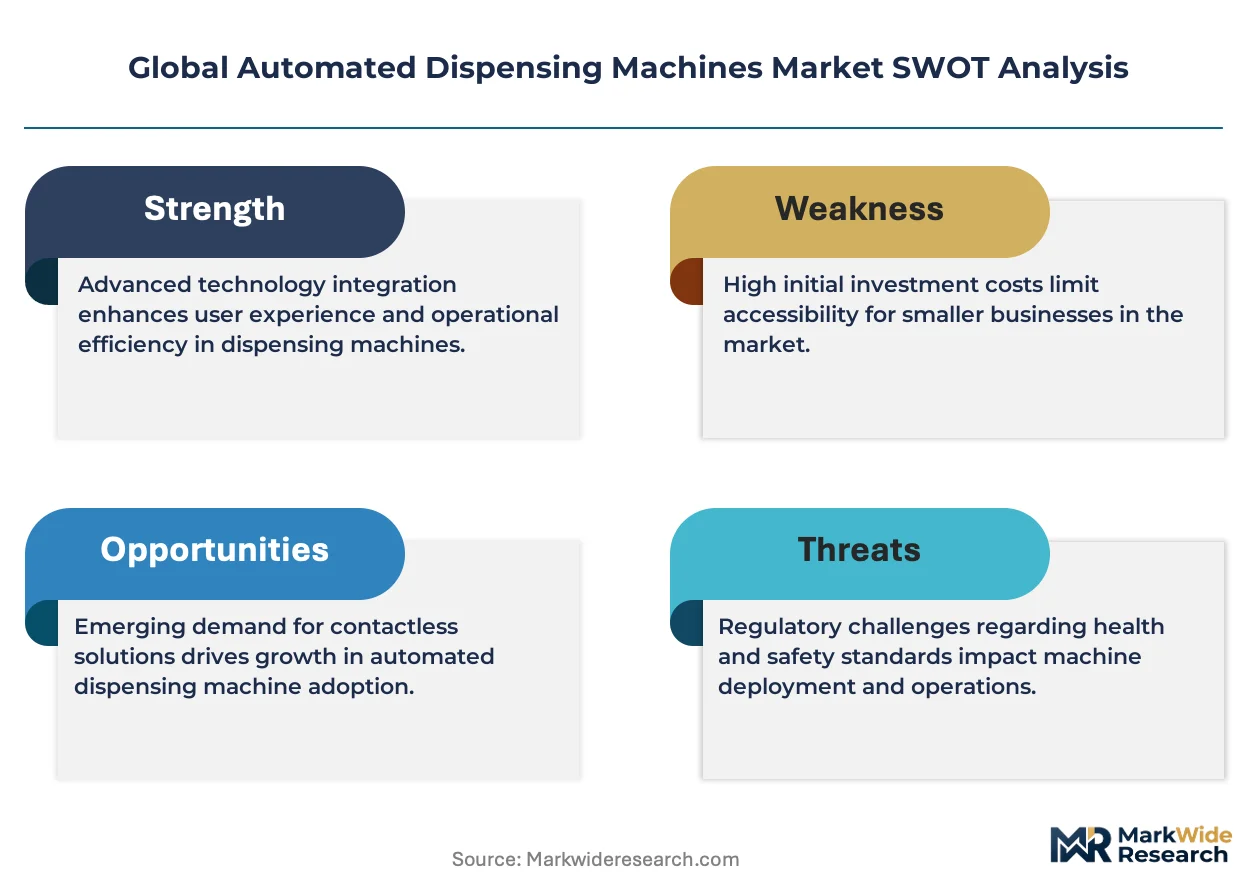
Undercapacity in precision servo motor fabrication across Baden-Württemberg is compressing component availability for mid-tier equipment manufacturers, forcing hardware vendors toward software-enabled service bundling to defend margin structures against input cost volatility.
Pricing Analysis
Long-term equipment lease contracts with remote monitoring service bundles dominate hospital procurement in consolidated United States health systems, while spot purchasing persists in Indian private hospital chains facing capital constraints. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated units with 21 CFR Part 11 compliance from CE-marked systems and basic electromechanical configurations. Cost compression in standard-tier hardware is intensifying because stainless steel and precision motor input volatility squeezes fabricator margins. Community hospitals with limited biomedical technician availability exhibit highest price sensitivity; academic medical centers with enterprise resource planning integration requirements absorb premium positioning.
Supply Chain Analysis
Contract manufacturing for electromechanical assemblies concentrates in Germany, Japan, and Switzerland, with Swisslog Holding and domestic Japanese fabricators controlling climate-controlled storage module production. Precision servo motors, weight-sensing drawer sensors, and barcode verification optics draw from specialized component suppliers anchored in Baden-Württemberg and the Kanto region. Single-source vulnerability in German servo motor production creates geographic concentration risk for non-integrated vendors lacking captive supply arrangements. Distribution runs through hospital group purchasing organizations in the United States, regional pharmacy service corporations in Germany, and enterprise pharmacy operators in Maharashtra and Karnataka.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of biomedical technicians holding dual electromechanical and pharmaceutical handling certification is constraining deployment velocity, creating competitive advantage for vendors who can compress installation complexity or embed remote diagnostics capabilities.
For Market Incumbents: Build software-enabled service moats through HL7 FHIR interoperability mandates that lock enterprise clients into electronic health record-integrated platforms. Incumbents should deepen backward integration into precision motor supply to offset Baden-Württemberg concentration risk, while accelerating computer vision verification R&D to defend against emerging smart system specialists. Cloud-connected inventory management represents the critical lever for recurring revenue unbundling from hardware commoditization pressures. For New Entrants and Emerging Players: Mid-market community hospitals in India's Maharashtra and Karnataka clusters represent the most penetrable entry point, where CDSCO medical device registration creates compliance barriers for late movers and biomedical technician shortages extend deployment timelines for established vendors. Long-term care facilities in Germany's Pflegekassen zones previously served by manual cart-fill systems offer secondary white-space, with IoT-enabled predictive stockout algorithms as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across IoT-enabled machine platforms requiring cloud infrastructure investment and thermal stability documentation for PMDA compliance. Platform-specialist archetypes with software-enabled remote diagnostics footprints offer superior long-term viability compared to hardware-commoditized fabricators. The signal to watch is hospital pharmacy consolidation velocity into regional networks, which accelerates enterprise lease contracting and displaces spot purchasing channels.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Enabled Remote Diagnostics Development | Unbundles maintenance contracts from hardware sales, creating recurring revenue streams in installed base expansion. |
| HL7 FHIR Interoperability Certification Investment | Locks enterprise health system clients through electronic health record integration mandates. |
| Backward Integration into Precision Motor Supply | Reduces geographic concentration risk from Baden-Württemberg servo motor suppliers. |
| Computer Vision Verification Platform Launch | Hybridizes quality assurance workflows in oncology satellite pharmacies at academic medical centers. |
| PMDA Local Testing Partnership Establishment | Satisfies Japan's distinct pharmaceutical handling certification requirements for climate-controlled storage modules. |
Methodological Framework
The analysis maps prescription dispensing machines, point-of-care units, IoT-enabled platforms, and smart systems with computer vision, each validated through hospital pharmacy directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists at device manufacturers. Primary interviews with these stakeholders combined with secondary validation against FDA 510(k) filings, PMDA pharmaceutical handling equipment certifications, EU MDR technical documentation, and hospital procurement databases. Bottom-up unit deployment tracking and top-down health system capital expenditure analysis provided triangulation across data sources.
Assumptions held fixed include regulatory enforcement timelines for 21 CFR Part 11 and EU MDR clinical evidence standards, while variables included hospital consolidation velocity and biomedical technician certification pipeline expansion. The projection horizon spans hardware replacement cycles, software upgrade adoption curves, and regional pharmacy service corporation formation across the United States, Germany, and Japan. Segmentation dimensions modeled encompass product type, end user procurement authority structure, connectivity architecture, and deployment mode. CAGRs derived from installed base expansion rates, ASP erosion trajectories, and service revenue mix shifts, with forecast inputs including chronic disease prescription volume growth and serialization mandate compliance deadlines.
Practitioners should monitor FDA Drug Supply Chain Security Act enforcement intensity, PMDA certification framework revisions, and servo motor supply availability from Baden-Württemberg for early signals requiring forecast revision. Quarterly review of hospital consolidation announcements, GPO contract awards, and CDSCO medical device registration timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Midline Catheters Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
Bionic Devices Market
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Global Capnography Market
Medical Devices
Global Robotic Flight Simulator Surgery Market
Medical Devices
Electric Handpiece Market
Medical Devices
Surgical Devices Market
Medical Devices
ETCO2 Masks Market
Medical Devices
United States Implantable Medical Devices Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Capsulorhexis Forceps Market
Medical Devices
Neurodiagnostic and Monitoring Devices Market