
 Pulse Lavage Market | 2026-2036
Pulse Lavage Market Size, Share, and Industry Trends Forecast 2026-2036
Pulse Lavage Market Intelligence
The gap between reusable and disposable pulse lavage architectures is narrowing as sterilization economics and infection control protocols collide. Mölnlycke Health Care AB leverages its wound care heritage to anchor premium disposable positioning across European surgical centers. Medtronic plc sustains R&D intensity in battery-operated platforms that compete on operating room mobility. Stryker Corporation dominates orthopedic procedure bundles by integrating pulse lavage into its surgical workflow ecosystems.
Pulse lavage is a powered irrigation system that delivers pulsatile saline or antibiotic solution at controlled pressures, typically 10-15 psi, to debride wounds and clean bone surfaces during surgical procedures. The technology serves primarily to reduce bacterial load and remove debris from tissue beds before closure or implantation. Disposable product configurations command the largest revenue share due to infection prevention mandates, while battery operated systems represent the fastest-expanding segment as ambulatory facilities prioritize cordless maneuverability. Pulsatile flow technology leads clinical preference for orthopedic applications, whereas ultrasonic irrigation captures margin pools in specialized wound care settings.
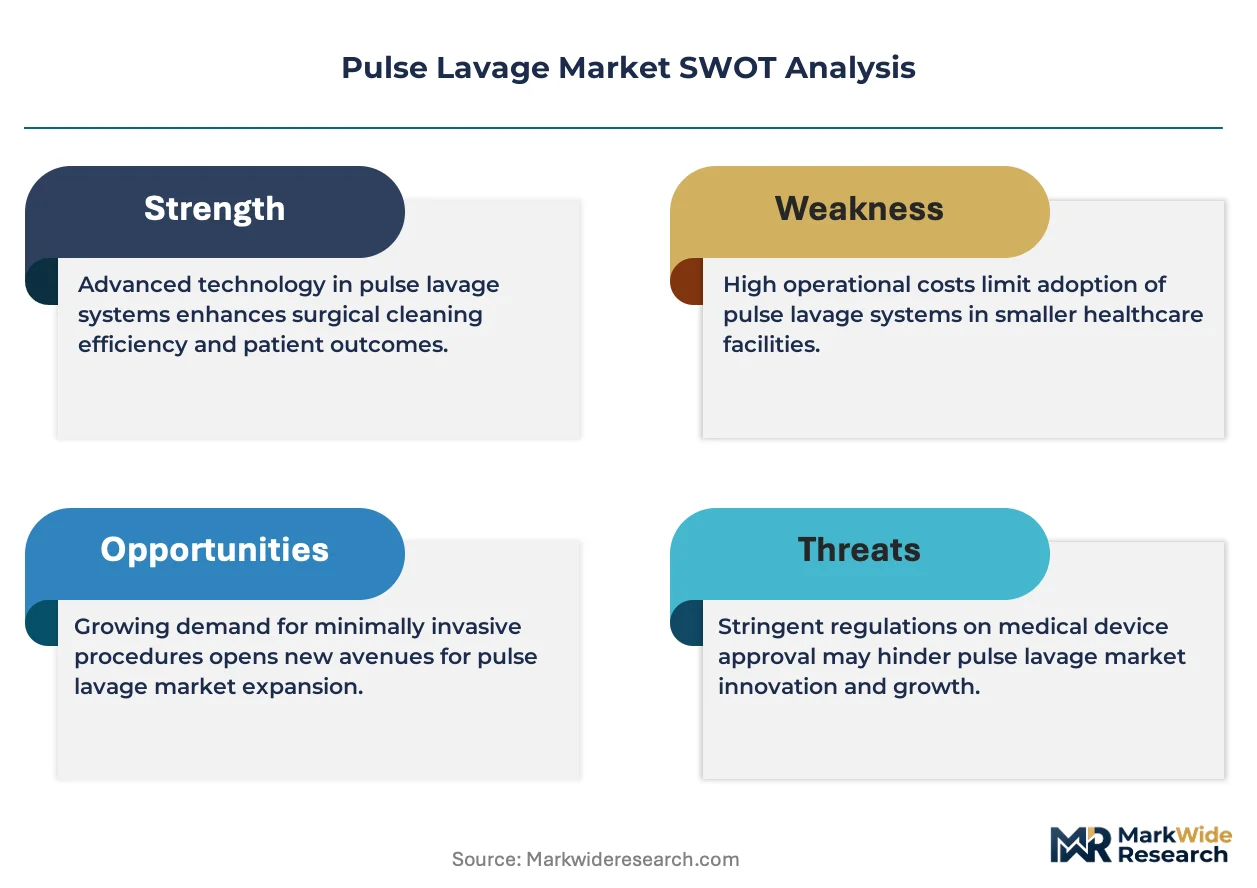
The FDA classifies pulse lavage devices as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for powered surgical instruments under its expanded scope. ISO 13485 quality management certification shapes supplier qualification for original equipment manufacturers seeking hospital system contracts. Stakeholders must monitor reimbursement coding revisions for surgical irrigation procedures, as these directly influence capital allocation decisions by ambulatory surgery center administrators.
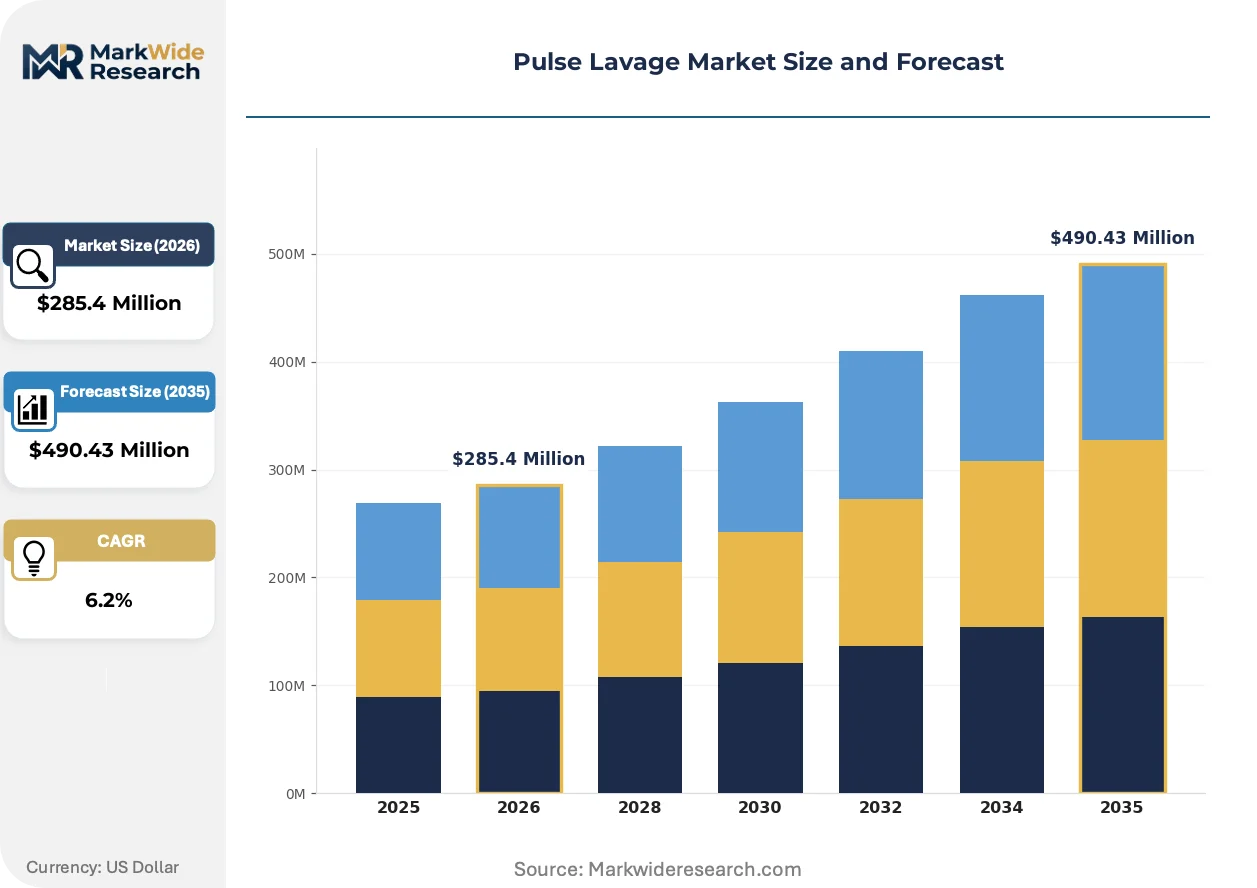
Market Dynamics
The FDA's 510(k) clearance pathway for powered surgical instruments is tightening evidentiary standards, forcing manufacturers to generate additional clinical data for pulse lavage systems while ambulatory surgical centers accelerate their shift toward battery-operated platforms.
Growth Catalysts
- EU MDR compliance deadlines:Stricter clinical evidence requirements under the Medical Device Regulation are favoring established manufacturers with robust quality management systems, consolidating procurement toward ISO 13485-certified suppliers.
- Orthopedic procedure volume:Rising joint replacement surgeries in aging populations across Germany, the United States, and Japan are expanding the addressable patient base for pulsatile irrigation systems.
- Battery chemistry advances:Lithium-ion cell energy density improvements are enabling cordless pulse lavage platforms that match wired systems in pressure output and runtime.
Market Restraints
- Single-use consumable costs:Disposable pulse lavage tips and tubing sets carry per-procedure costs that strain reimbursement-constrained ambulatory surgery center budgets.
- Supply concentration in precision motors:Miniature brushless DC motor production clusters in East Asia create vulnerability for battery-operated system manufacturers.
- Ultrasonic irrigation substitution:Specialized wound care applications are partially migrating to ultrasonic debridement systems that reduce soft tissue trauma.
Strategic Opportunities
- Outpatient migration in the United States:CMS reimbursement shifts toward site-neutral payment are incentivizing joint replacement procedures in ambulatory settings that favor portable pulse lavage.
- Antibiotic solution integration:Convergence of pulsatile delivery systems with topical antimicrobial formulations is opening premium positioning in infection-prone trauma cases.
- Direct-to-facility distribution:Bypassing traditional distributor markups through manufacturer-owned logistics networks is capturing margin in high-volume hospital systems.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 series evaluations for novel materials in disposable tips extend product development cycles by months.
- OR integration complexity:Pulse lavage systems must interface with existing suction and fluid management infrastructure, requiring customized mounting solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pulse Lavage Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $490.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Operated, Corded, Disposable, Reusable, Portable Application: Orthopedic Surgery, Wound Care, Dental Procedures, Dermatology, Plastic Surgery End User: Specialty Clinics, Surgical Centers, Dental Offices, Ambulatory Care Facilities, Rehabilitation Institutes Technology: Ultrasonic Irrigation, Pulsatile Flow, Sonic Jetting, Hydrotherapy, Vacuum Assisted |
| Companies Covered | Mölnlycke Health Care AB, Medtronic plc, Stryker Corporation, Judd Medical Ltd., De Soutter Medical Ltd., Zimmer Biomet Holdings, Inc., MicroAire Surgical Instruments LLC, Premier Surgical Ltd., Smith & Nephew plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pulse Lavage Market Strategic Shifts & Innovations
Active reshaping of the pulse lavage landscape centers on three vectors: hybrid power architectures, regulatory data requirements, and procurement model compression in outpatient settings.
Pulsatile-continuous flow hybridization is hybridizing irrigation modalities by combining high-pressure pulse phases with sustained low-pressure delivery. Orthopedic surgeons in high-volume joint replacement centers are piloting these dual-mode systems to reduce operative time while maintaining debridement efficacy. The structural consequence is compression of the standalone continuous-flow irrigation segment as hybrid platforms capture share across procedure types.
EU MDR Article 10 clinical evaluation requirements are mandating post-market surveillance data collection for Class IIa powered surgical instruments. Manufacturers must now maintain systematic literature reviews and PMCF studies, raising compliance costs that disproportionately burden smaller device firms. German notified bodies are experiencing backlog delays, stretching certification timelines for new pulse lavage submissions.
Ambulatory surgery center administrators are consolidating vendor relationships through capital-plus-consumable bundled contracts. Traditional equipment-only purchasing is giving way to multi-year agreements that lock in disposable supply commitments. This behavioral shift is most pronounced in United States metropolitan markets where ASC chains operate 10-plus facilities and wield procurement leverage.
Pulse Lavage Market Segmentation
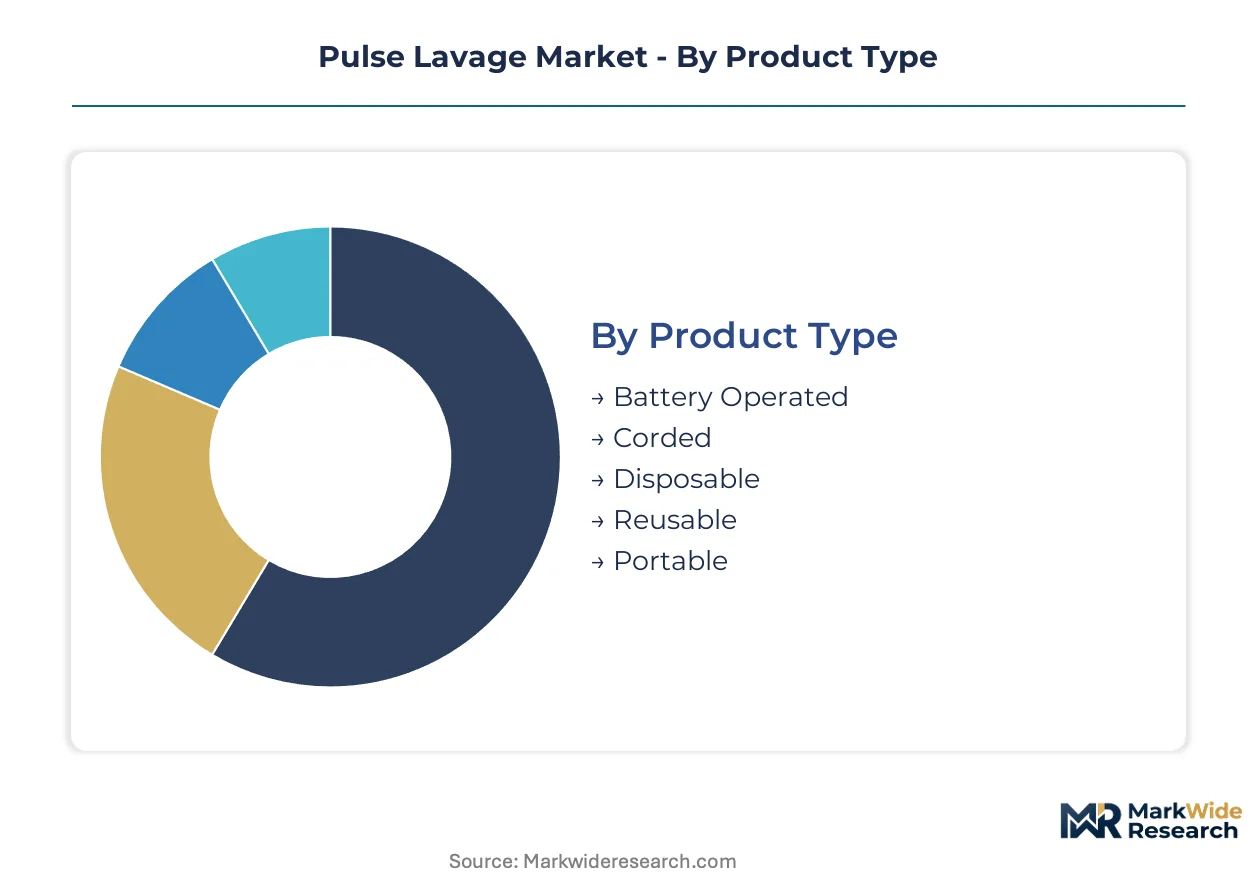
Pulse lavage segmentation reflects the collision between infection control mandates and mobility requirements in modern surgical environments. Product architecture choices directly determine facility capital allocation and per-procedure economics across orthopedic and wound care settings.
Product Type:
Use-case spectrum spans from high-volume hospital suites requiring continuous power to ambulatory sites prioritizing cordless maneuverability.
- Battery Operated:Lithium-ion powered platforms deliver 10-15 psi pulsatile output without tethering to wall suction. Ambulatory surgery centers in Germany and the United States are standardizing these systems as joint replacement procedures migrate outpatient.
- Disposable:Single-use tubing sets and handpieces eliminate cross-contamination risk between patients. Hospital systems with strict infection prevention protocols in Japan and the United States absorb higher per-procedure costs to avoid sterilization liability.
- Corded:Mains-powered units maintain consistent pressure output for extended orthopedic cases requiring sustained irrigation.
- Reusable:Autoclavable handpieces and cannulas reduce consumable spend for high-volume trauma centers with in-house sterilization infrastructure.
- Portable:Compact wheeled units bridge stationary and mobile requirements for multi-procedure surgical suites.
The dominant share belongs to Disposable configurations, while Battery Operated systems are closing the gap fastest.
Application:
Clinical settings range from sterile orthopedic theaters to outpatient wound clinics with varying sterility requirements.
- Orthopedic Surgery:Total joint arthroplasty and fracture fixation demand high-pressure debridement of bone surfaces before implantation. German hospital networks and United States academic medical centers drive procurement volume for pulsatile systems integrated into surgical workflows.
- Wound Care:Chronic ulcer management and trauma debridement require adjustable pressure settings to preserve viable tissue. Specialized clinics in Japan and rehabilitation institutes across Germany are expanding adoption of gentler irrigation modalities.
- Dental Procedures:Implant site preparation and periodontal surgery utilize lower-pressure irrigation systems.
- Dermatology:Mohs surgery and lesion excision employ precise fluid delivery for tissue bed cleaning.
- Plastic Surgery:Aesthetic and reconstructive procedures integrate irrigation into suction-assisted lipectomy and tissue transfer protocols.
Orthopedic Surgery commands the largest installed base, though Wound Care applications are expanding most quickly into community settings.
End User:
Facility type determines capital intensity, consumable commitment scale, and regulatory compliance burden.
- Surgical Centers:Ambulatory facilities performing same-day joint replacement prioritize battery-operated platforms with minimal infrastructure requirements. United States metropolitan markets with multi-facility chains leverage volume purchasing for bundled equipment-consumable contracts.
- Specialty Clinics:Orthopedic-focused practices concentrate procedure volume and standardize on single-vendor ecosystems. German outpatient clinics upgrading debridement capabilities favor disposable configurations to minimize sterilization overhead.
- Ambulatory Care Facilities:Hospital-affiliated same-day surgery units balance mobility with integration into central sterile supply chains.
- Rehabilitation Institutes:Long-term wound management programs utilize lower-pressure hydrotherapy systems for chronic patient populations.
- Dental Offices:Private practices select compact units with reduced pressure ranges appropriate for oral cavity procedures.
Surgical Centers capture the dominant procurement volume, while Specialty Clinics are gaining share fastest through vertical integration with orthopedic group practices.
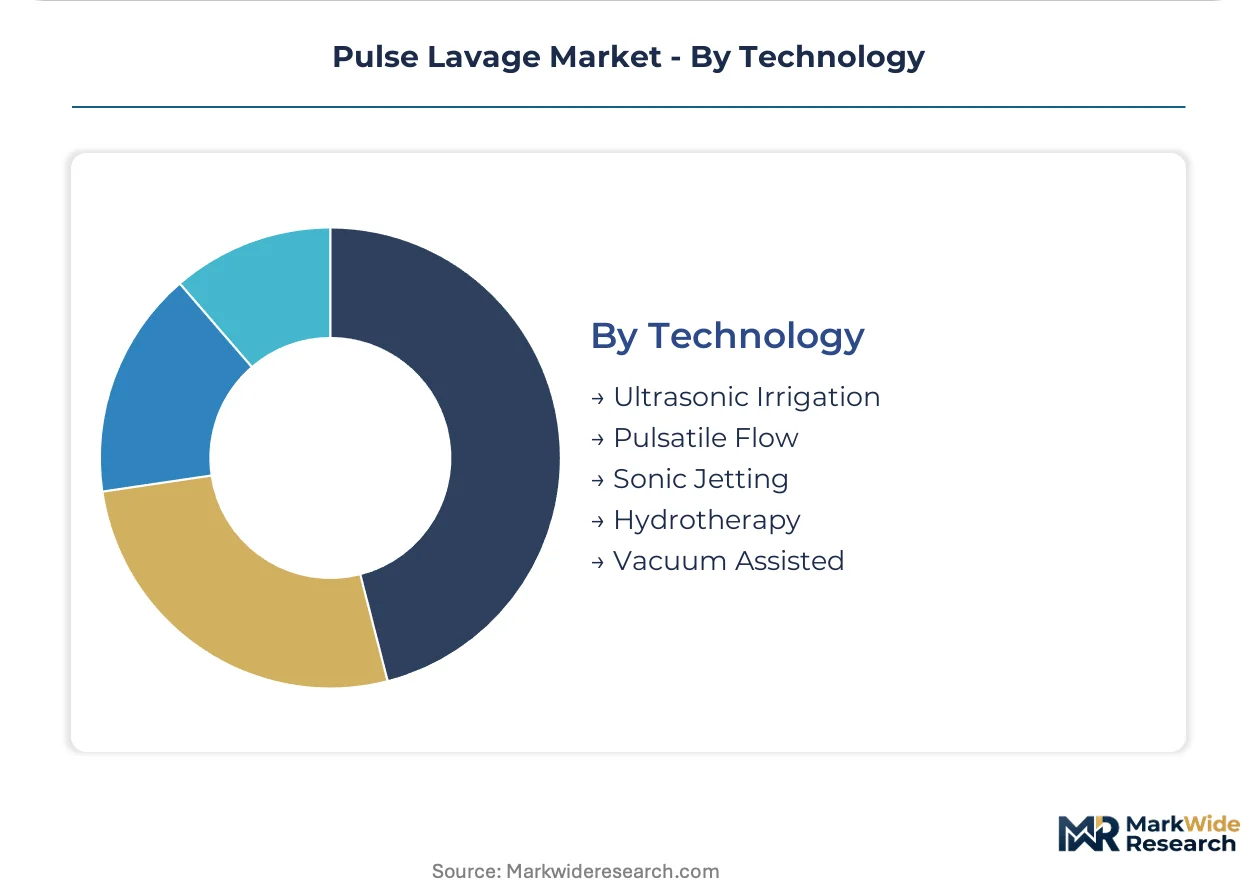
Technology:
Mechanism of fluid delivery differentiates tissue impact profiles and clinical indications.
- Pulsatile Flow:Cyclic high-pressure bursts at 10-15 psi dislodge debris and reduce bacterial load in bone and soft tissue. Orthopedic surgeons in the United States and Germany prefer this modality for joint replacement preparation due to established efficacy data.
- Ultrasonic Irrigation:High-frequency acoustic energy generates cavitation bubbles for gentle debridement with minimal soft tissue trauma. Japanese wound care specialists and German dermatology clinics adopt this technology for chronic ulcer management where tissue preservation is paramount.
- Sonic Jetting:Continuous high-velocity streams target localized contamination in dental and plastic surgery applications.
- Hydrotherapy:Low-pressure sustained flow suits rehabilitation settings with extended treatment protocols.
- Vacuum Assisted:Combined irrigation-suction systems manage fluid balance in confined surgical fields.
Pulsatile Flow retains the dominant clinical position, though Ultrasonic Irrigation is climbing the fastest as wound care applications expand beyond traditional surgical settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in pulse lavage systems tilt toward import dependency in emerging surgical markets while established manufacturing clusters in Germany and the United States supply regional demand hubs. Export intensity concentrates where precision motor fabrication and sterilization infrastructure overlap.
United States
Ambulatory surgery center chains in Texas and Florida are driving procurement volume for battery-operated platforms as joint replacement procedures migrate outpatient. FDA 510(k) clearance timelines for powered surgical instruments are extending, forcing manufacturers to submit additional clinical evidence. The Minneapolis medical device corridor anchors domestic production capacity for orthopedic irrigation systems.
Germany
Hospital networks in Bavaria and North Rhine-Westphalia are standardizing disposable pulse lavage configurations to eliminate sterilization liability. EU MDR Article 10 clinical evaluation requirements are stretching certification timelines through notified body backlogs. The Tuttlingen surgical instrument cluster supplies precision handpiece manufacturing for European distribution.
Japan
Academic medical centers in Tokyo and Osaka prefer pulsatile flow systems for total joint arthroplasty protocols. PMDA premarket approval pathways for Class II powered surgical devices emphasize biocompatibility documentation under ISO 10993 standards. The Kobe medical technology corridor hosts specialized wound care device assembly operations.
China
Tier-one hospitals in Shanghai and Beijing are upgrading debridement capabilities for trauma centers handling high-volume fracture cases. NMPA registration requirements for powered surgical instruments are converging with international standards through the Medical Device Administrative Measures. The Suzhou industrial park concentrates foreign-invested manufacturing for export-oriented surgical device production.
United Kingdom
NHS procurement frameworks are consolidating pulse lavage supply through multi-year equipment-plus-consumable contracts. MHRA post-Brexit regulatory autonomy is maintaining alignment with EU MDR technical standards for powered surgical instruments. The Cambridge medical technology cluster supports R&D partnerships between device manufacturers and academic orthopedic research units.
Pulse Lavage Market Key Industry Players
On the supply side, the industry is moderately consolidated with tiered positioning across premium disposable, integrated orthopedic ecosystems, and specialized wound care vectors. Strategic archetypes include surgical workflow integrators, infection control specialists, and ambulatory mobility enablers. Competitive moves center on bundled contracting structures and backward integration into precision motor supply chains.
Within the premium disposable tier, Mölnlycke Health Care AB exemplifies infection prevention positioning drawn from wound care heritage. Medtronic plc and Stryker Corporation anchor the integrated ecosystem archetype, with the latter representing surgical workflow bundling across orthopedic procedure sets. These three entities occupy positions that reflect distinct strategic bets on sterilization economics versus capital equipment intensity.
| Leading Market Players |
|---|
| Mölnlycke Health Care AB |
| Medtronic plc |
| Stryker Corporation |
| Judd Medical Ltd. |
| De Soutter Medical Ltd. |
| Zimmer Biomet Holdings, Inc. |
| MicroAire Surgical Instruments LLC |
| Premier Surgical Ltd. |
| Smith & Nephew plc |
| Others |
Cost & Logistics Intelligence
Precision brushless DC motor fabrication clusters in East Asia capture disproportionate upstream margin, forcing battery-operated pulse lavage OEMs to absorb cost volatility or push pricing pressure downstream to ambulatory surgery centers already constrained by site-neutral reimbursement.
Pricing Analysis
Ambulatory surgery center administrators anchor contract-based consumable bundling that locks multi-year disposable commitments against capital equipment discounts. Pricing stratifies across premium ISO 13485-certified configurations, standard FDA 510(k)-cleared systems, and economy-tier reusable architectures for high-volume trauma centers. Cost compression in battery-operated segments is intensifying because lithium-ion cell supply bottlenecks squeeze component margins. Price sensitivity peaks among independent ASC chains with fewer than five facilities, while integrated hospital systems wield volume leverage for steeper bundled discounts.
Supply Chain Analysis
Contract manufacturing for precision handpiece assembly concentrates in the Tuttlingen surgical instrument cluster, with secondary capacity in the Minneapolis medical device corridor and Suzhou industrial park. Production draws from Japanese lithium-ion cell suppliers, German precision motor windings, and Chinese polymer tubing extrusion. Single-source vulnerability in miniature DC motor controllers creates exposure to East Asian logistics chokepoints. Distribution runs through manufacturer-direct logistics networks for high-volume hospital systems, with traditional distributor markups persisting in fragmented outpatient clinic segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where FDA 510(k) clearance timelines and EU MDR Article 10 clinical evidence requirements create switching costs that cement incumbent positions against emerging challengers.
For Market Incumbents: Insulate market position by deepening backward integration into precision motor supply chains through captive production or long-term offtake agreements with German and Japanese suppliers. Fortify bundled contracting structures with multi-facility ASC chains to lock consumable streams before site-neutral reimbursement fully compresses capital equipment margins. Prioritize ISO 10993 biocompatibility pre-certification for novel disposable materials to accelerate product development cycles against ultrasonic irrigation substitutes.
For New Entrants and Emerging Players: Mid-market wound care clinics in Japan and rehabilitation institutes across Germany represent the most penetrable entry point, as these segments prioritize tissue-preserving ultrasonic modalities where regulatory barriers sit lower than orthopedic pulsatile systems. Battery chemistry innovation for extended runtime without pressure degradation offers a technical wedge against established corded platforms. Direct-to-facility distribution bypassing traditional GPO channels captures margin in independent specialty clinics with standardized debridement protocols.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed surgical instrument specialists holding ISO 13485 certification but lacking integrated consumable ecosystems. Long-term viability across the analysis window hinges on convergence with topical antimicrobial formulation delivery, positioning antibiotic-integrated platforms for premium trauma case capture. Monitor FDA 510(k) clearance backlog durations as an inflection signal—accelerating timelines would lower entrant barriers and compress incumbent pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Article 10 Compliance Investment | Clinical evaluation documentation satisfies notified body requirements for Class IIa powered surgical instruments in German markets. |
| Antibiotic Solution Integration Partnership | Co-development with topical antimicrobial formulators opens premium positioning in infection-prone orthopedic trauma procedures. |
| Direct-to-Facility Distribution Buildout | Manufacturer-owned logistics networks bypass distributor markups in high-volume United States hospital systems. |
| Battery Chemistry R&D Expansion | Lithium-ion energy density improvements enable cordless platforms matching wired systems in pressure output and runtime. |
| Hospital System Bundled Contracting | Multi-year equipment-plus-consumable agreements lock procurement relationships with metropolitan ASC chains operating 10-plus facilities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) premarket notification databases, EU MDR notified body certification records, hospital procurement contract filings, and orthopedic procedure volume registries. Interviews with biomedical engineers, GPO contracts managers, ASC administrators, and regulatory affairs specialists at powered surgical instrument manufacturers informed demand-side and supply-side assumptions. Bottom-up sizing of installed base and consumable throughput triangulates against top-down expenditure flows from Medicare claims data and private payer reimbursement schedules.
Forecast inputs span product architecture migration from corded to battery-operated platforms, infection control protocol evolution affecting disposable versus reusable adoption, and orthopedic procedure volume shifts between inpatient and ambulatory settings. Segmentation modeling covers power source configuration, sterility class, clinical application, and facility type across regional regulatory clusters. CAGRs derive from procedure volume elasticity to demographic aging, technology substitution curves, and reimbursement rate compression scenarios without year-specific anchors.
Macroeconomic conditions sit as an overlay; deviation in CMS reimbursement policy, lithium commodity pricing, or East Asian trade flows would shift the trajectory. Forecasts embed assumptions regarding EU MDR notified body capacity constraints and FDA evidentiary standard evolution. Quarterly review of 510(k) clearance velocity, ASC joint replacement migration rates, and precision motor supplier lead times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veterinary Respiratory Ventilators Market
Medical Devices
Intravascular Warming Systems Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
Minimally Invasive Spine Technologies Market
Medical Devices
North America Insulin Delivery Devices Market
Medical Devices
Wireless Neurostimulator Market
Medical Devices
Argentina Aesthetic Devices Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Skull Clamp Market
Medical Devices
Supraglottic Device Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Japan Electric Wheelchair Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
North America 3D Printing in Healthcare Market