
 Ultrasonic Medical Nebulizer Market | 2026-2036
Ultrasonic Medical Nebulizer Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Medical Nebulizer Market Insights
Asset-light leasing models for home-use nebulizer fleets is tilting competitive dynamics toward operators with balance-sheet flexibility rather than pure manufacturers. OMRON Healthcare leverages its established distribution in Asia-Pacific to sustain recurring revenue from consumable mesh components. Koninklijke Philips N.V. anchors its position through integrated respiratory care platforms that bundle nebulization with diagnostic monitoring. Drive Medical competes on price-accessible tabletop units for long-term care facilities.
An ultrasonic medical nebulizer generates therapeutic aerosols via piezoelectric crystal vibration at frequencies typically between 1–3 MHz, producing particle sizes of 1–5 micrometers optimized for lower respiratory tract deposition. The device serves primarily to deliver bronchodilators, corticosteroids, and antibiotics to patients with obstructive or infectious pulmonary conditions. Portable nebulizers dominate volume as lithium-ion battery miniaturization enables ambulatory therapy, while vibrating mesh technology captures premium pricing through superior drug delivery efficiency and reduced residual waste. Home care leads end-user demand structurally, though ambulatory surgical centers represent the fastest-growing adoption site as same-day procedures expand.
The FDA regulates ultrasonic nebulizers as Class II medical devices under 21 CFR 890.5050, requiring 510(k) premarket notification for substantial equivalence to legally marketed predicates. The EU Medical Device Regulation (MDR) imposes stricter clinical evidence and post-market surveillance obligations through notified body conformity assessment. China's NMPA implements domestic testing protocols under GB standards that foreign manufacturers must navigate for market access. Stakeholders must monitor reimbursement code revisions by CMS and parallel European health technology assessment bodies, as coverage determinations increasingly tie device qualification to demonstrated adherence metrics and patient-reported outcome data.
Market Dynamics
Asset-light leasing models for home-use nebulizer fleets are restructuring competitive dynamics toward operators with balance-sheet flexibility rather than pure manufacturers, compressing traditional ownership economics.
Growth Catalysts
- Home care migration:Patients with chronic obstructive pulmonary disease are relocating respiratory therapy from hospitals to residential settings, expanding addressable device demand.
- FDA 510(k) pathway efficiency:The premarket notification framework for substantial equivalence accelerates product development timelines in the United States compared to de novo routes.
- Vibrating mesh miniaturization:Piezoelectric crystal advances at 1–3 MHz frequencies enable portable lithium-ion systems with superior drug delivery efficiency.
Market Restraints
- Input cost volatility:Rare earth elements for piezoelectric crystals face price instability from concentrated Chinese supply chains.
- Technical residual waste:Conventional ultrasonic designs retain 10–15% medication volume, limiting cost-effectiveness against mesh alternatives.
- Regulatory friction:EU MDR clinical evidence requirements impose extended conformity assessment timelines through notified bodies.
Strategic Opportunities
- Ambulatory surgical centers:Same-day procedure expansion creates fastest-growing adoption site for pre-operative bronchodilator delivery.
- Integrated respiratory platforms:Convergence of nebulization with diagnostic monitoring enables bundled reimbursement positioning.
- Consumable mesh components:Recurring revenue from replacement parts sustains margin structures beyond initial device sales.
Industry Challenges
- Biocompatibility certification timelines:ISO 10993 testing protocols for patient-contact materials extend product launch schedules.
- Legacy system integration:Hospital electronic health record compatibility requirements complicate connectivity feature deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Medical Nebulizer Market |
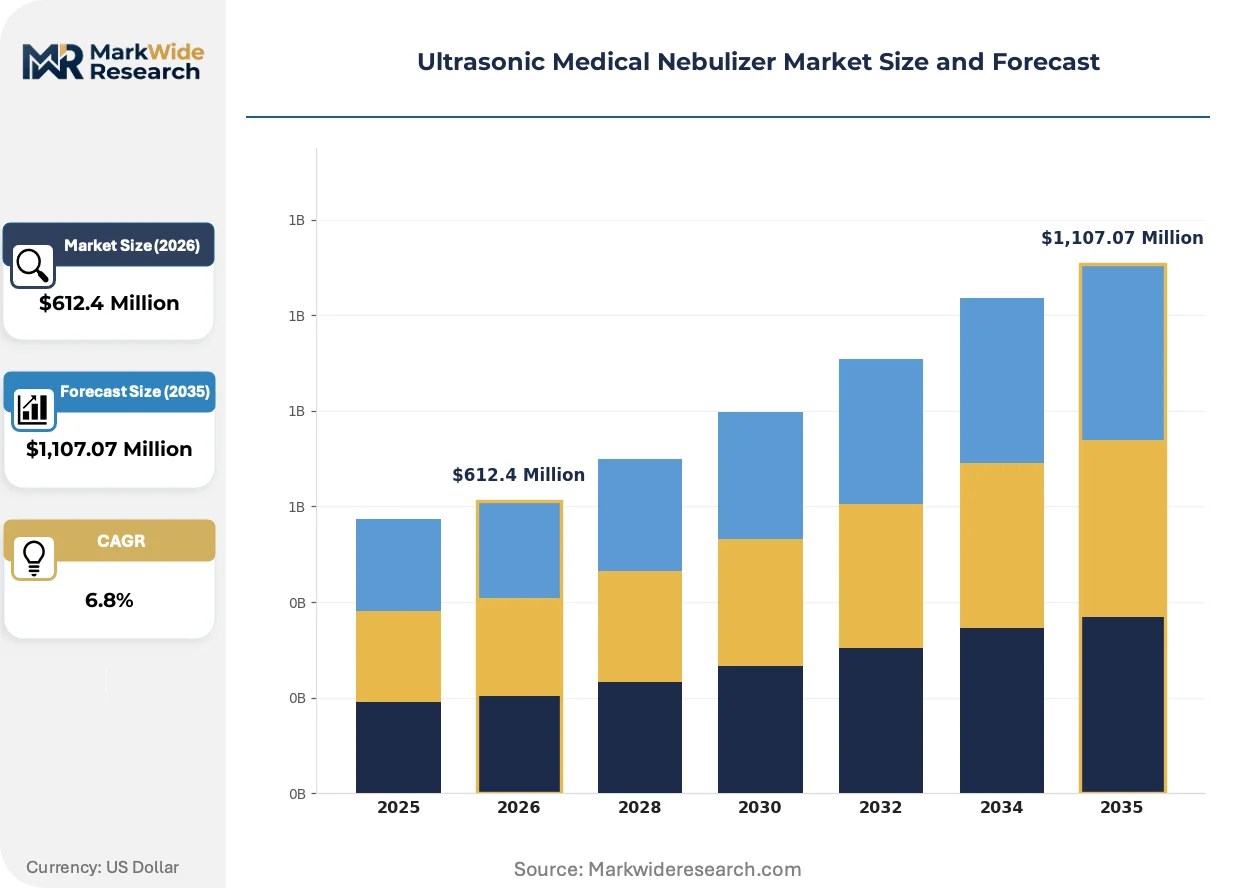
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,107.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Nebulizers, Tabletop Nebulizers, Pediatric Nebulizers, Smart Nebulizers Technology: Ultrasonic Technology, Mesh Technology, Jet Technology, Vibrating Mesh Technology End User: Hospitals, Home Care, Clinics, Ambulatory Surgical Centers Application: Asthma Treatment, COPD Management, Cystic Fibrosis Care, Postoperative Care |
| Companies Covered | Koninklijke Philips N.V., OMRON Healthcare, Inc., Drive Medical, Invacare Corporation, Agilent Technologies, Inc., AireHealth, Inspired Medical, Mercury Medical, Besmed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Medical Nebulizer Market Trends and Innovations
Connectivity architectures and reimbursement metric alignment are actively restructuring how ultrasonic nebulizer value is captured and measured across care settings.
Smart inhalation sensors embedded in mesh nebulizer housings is digitizing dose-tracking capabilities for adherence verification. Pulmonology clinics in Germany and Japan are piloting these systems for corticosteroid compliance monitoring. The technology is digitizing pharmaceutical reimbursement models by generating patient-reported outcome data required by CMS and parallel European health technology assessment bodies.
EU MDR post-market surveillance obligations now mandate systematic clinical follow-up for Class IIa respiratory devices. Manufacturers must maintain vigilance systems with notified body oversight that exceed previous Medical Device Directive requirements. Ambulatory care segments face compressed response timelines for adverse event reporting, forcing operational restructuring of quality management systems.
Hospital procurement departments are consolidating vendor relationships through integrated respiratory care contracts that bundle nebulization with oxygen therapy and diagnostic equipment. Group purchasing organizations are displacing individual facility negotiations in the United States and Western Europe. This concentration is most visible in integrated delivery networks seeking single-source accountability for respiratory outcomes.
Ultrasonic Medical Nebulizer Market Segmentation
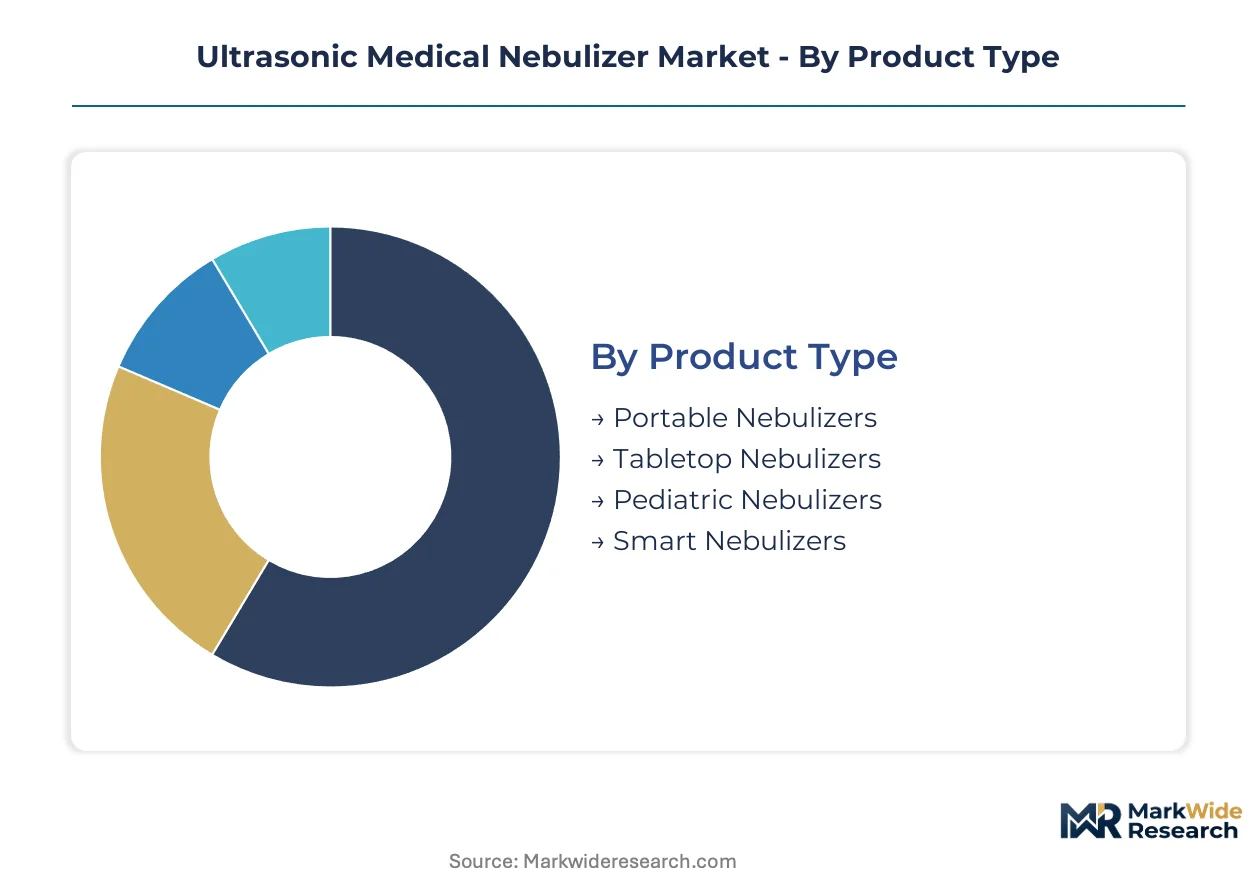
Ultrasonic medical nebulizers serve distinct patient workflows ranging from acute hospital interventions to chronic home management. Segmentation reveals how device specifications, technology choices, and care settings create divergent margin profiles and regulatory pathways across the value chain.
Product Type:
The use-case spectrum spans ambulatory patients requiring pocket-sized mobility to institutional settings demanding continuous-duty reliability.
- Portable Nebulizers:Lithium-ion battery systems weighing under 500 grams enable therapy during work commutes and travel. Demand concentrates in Japan and Germany where aging populations prioritize outpatient COPD management without facility dependency.
- Tabletop Nebulizers:Mains-powered units with 6–10 ml medication chambers serve stationary home environments and long-term care facilities. China's expanding home care reimbursement drives volume here as families establish dedicated therapy stations.
- Pediatric Nebulizers:Animal-shaped housings with reduced noise profiles address compliance challenges in children under 12.
- Smart Nebulizers:Bluetooth-enabled dose tracking with smartphone connectivity supports adherence monitoring for value-based contracts.
The dominant share belongs to Portable Nebulizers, while Smart Nebulizers are closing the gap fastest.
Technology:
Cost tier differentiation separates premium efficiency systems from legacy pressure-driven alternatives.
- Ultrasonic Technology:Piezoelectric crystal vibration at 1–3 MHz frequencies produces 1–5 micrometer particles optimized for lower respiratory deposition. Hospitals in the United States favor these systems for bronchodilator delivery in emergency departments.
- Mesh Technology:Perforated membranes with 3,000–7,000 apertures generate consistent aerosol plumes with under 5% residual waste. Home care settings in France and South Korea adopt these for corticosteroid regimens where medication economy matters.
- Jet Technology:Compressed air systems with higher noise output and larger particle sizes retain niche use in price-sensitive institutional procurement.
- Vibrating Mesh Technology:Active aperture control enables breath-synchronized delivery with programmable dose limits.
Mesh Technology commands the premium tier by margin, though Vibrating Mesh Technology is expanding most quickly through integrated diagnostic bundles.
End User:
Volume concentration follows reimbursement migration from inpatient facilities toward residential and same-day settings.
- Hospitals:Acute care departments require rapid-acting bronchodilator delivery for status asthmaticus and post-extubation management. CMS reimbursement codes in the United States support capital equipment acquisition through procedural bundling.
- Home Care:Chronic disease patients perform 2–4 daily treatments outside supervised settings. China's government health initiatives specifically target home-based respiratory therapy expansion in tier-2 and tier-3 cities.
- Clinics:Pulmonology practices maintain nebulizer fleets for same-day exacerbation management.
- Ambulatory Surgical Centers:Pre-operative bronchodilator protocols for reactive airway patients create procedural demand.
Home Care holds the dominant share, while Ambulatory Surgical Centers are gaining share fastest through same-day procedure proliferation.
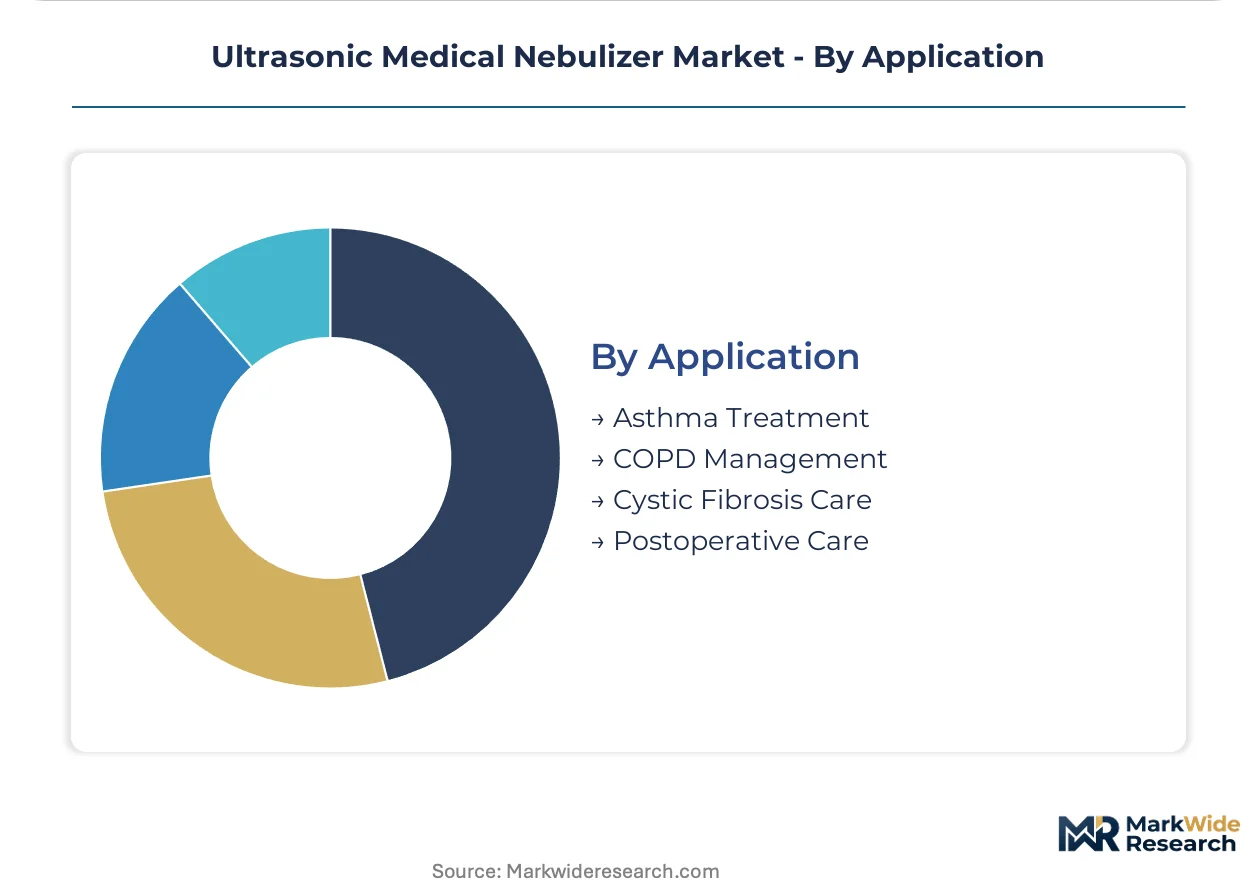
Application:
Patient population severity and therapy duration create divergent device performance requirements and replacement cycles.
- Asthma Treatment:Intermittent rescue therapy and daily controller regimens require rapid onset and consistent particle size distribution. Pediatric demand in India and Brazil concentrates here given high prevalence rates and expanding diagnosis access.
- COPD Management:Progressive disease necessitates escalating nebulization frequency from quarterly exacerbations to continuous therapy. Germany's disease management programs and Japan's long-term care insurance system structure reimbursement around documented adherence.
- Cystic Fibrosis Care:High-frequency antibiotic and mucolytic delivery demands corrosion-resistant materials and rigorous cleaning protocols.
- Postoperative Care:Short-duration bronchodilator prophylaxis following thoracic and abdominal procedures.
COPD Management represents the largest addressable population, while Cystic Fibrosis Care shows the steepest expansion trajectory through specialty pharmacy integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor established manufacturing bases in Asia-Pacific supplying North American and European demand, with China running substantial trade surpluses in nebulizer systems while the United States remains a net importer of advanced mesh technology.
United States
FDA 510(k) clearance pathways accelerate commercialization timelines for substantial equivalence claims. Home care reimbursement through CMS procedural bundling expands addressable demand beyond hospital procurement. Minneapolis and Boston medical device clusters concentrate R&D activity for connected respiratory platforms.
China
NMPA domestic testing protocols under GB standards create market access requirements for foreign manufacturers. Government health initiatives target tier-2 and tier-3 cities for home-based respiratory therapy expansion. Shenzhen and Shanghai manufacturing hubs scale production for both domestic consumption and export markets.
Germany
Disease management programs structure reimbursement around documented nebulizer adherence metrics. EU MDR notified body conformity assessment extends clinical evidence requirements for Class IIa respiratory devices. Munich and Hamburg pulmonology clinics pilot smart inhalation sensor systems for corticosteroid compliance monitoring.
Japan
Long-term care insurance systems reimburse escalating nebulization frequency for progressive COPD patients. METI standards coordination supports miniaturization of lithium-ion battery systems for ambulatory therapy. Tokyo and Osaka medical device clusters advance piezoelectric crystal integration for portable units.
France
ANSM post-market surveillance obligations mandate systematic clinical follow-up for connected nebulizer deployments. Health technology assessment bodies tie device qualification to patient-reported outcome data generation. Lyon and Paris hospital procurement departments consolidate vendor relationships through integrated respiratory care contracts.
Ultrasonic Medical Nebulizer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying piezoelectric crystals and perforated membranes to multiple OEMs. The vendor base stratifies across three tiers: multinational health technology conglomerates with respiratory care portfolios, mid-scale device manufacturers competing on price-accessible units, and specialized component fabricators capturing recurring revenue from replacement parts. Two dominant competitive moves are reshaping positioning: strategic partnerships between nebulizer manufacturers and pharmaceutical companies for co-developed drug-device combinations, and geographic expansion through regional distribution licensing to bypass direct regulatory registration burdens.
Among diversified health technology conglomerates, Koninklijke Philips N.V. and OMRON Healthcare, Inc. exemplify platform integrators anchoring integrated respiratory care ecosystems. Drive Medical occupies a position within the mid-tier price-competitive segment, representing manufacturers focused on accessible tabletop configurations for institutional procurement. These three entities illustrate the archetype spectrum from premium bundled systems to standardized volume units.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| OMRON Healthcare, Inc. |
| Drive Medical |
| Invacare Corporation |
| Agilent Technologies, Inc. |
| AireHealth |
| Inspired Medical |
| Mercury Medical |
| Besmed |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Shenzhen contract manufacturing clusters is compressing component margins for piezoelectric crystal assemblies and forcing suppliers toward volume-tier pricing concessions to maintain utilization rates. This utilization pressure cascades into buyer leverage for both mesh membrane OEMs and finished device assemblers, restructuring negotiation dynamics across the ultrasonic nebulizer value chain.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing structure across premium vibrating mesh, standard ultrasonic, and economy jet technology tiers. Price differentiation rests on FDA 510(k) certification status and residual waste specifications, with mesh systems commanding premiums for sub-5% medication loss rates. Cost compression in the economy tier is intensifying because Chinese domestic brands are expanding export quotas. Home care patients demonstrate highest price sensitivity, while hospital procurement committees prioritize total cost of ownership over unit acquisition cost.
Supply Chain Analysis
Flex, Jabil, and regional EMS providers in Dongguan hold dominant contract manufacturing capacity for portable nebulizer final assembly. Geographic supply concentration centers on China for piezoelectric crystals, Japan for precision-perforated mesh membranes, and South Korea for lithium-ion battery cells. Raw material dependencies draw from rare earth element concentrates, medical-grade polymers, and semiconductor-grade silicon. Single-source vulnerability in Chinese rare earth processing creates structural exposure. Distribution runs through hospital group purchasing organizations in the United States and specialized respiratory device distributors in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as home care reimbursement expansion creates niches for specialized connectivity features and pediatric form factors that incumbent platform integrators underserve. The demand-side shift toward ambulatory surgical center procurement is disaggregating volume concentration previously held by hospital systems.
For Market Incumbents: Pre-empt mesh technology commoditization by locking exclusive supply agreements with Japanese membrane fabricators and accelerating CE marking for connected nebulizer systems under EU MDR. Defend against emerging Asian OEMs by embedding diagnostic sensors that create switching costs through EHR integration investments. For New Entrants and Emerging Players: Build out white-space positions in pediatric nebulizer segments where noise reduction and compliance gamification remain underserved by existing portfolios. Target tier-2 Chinese cities where government health initiatives are expanding home care infrastructure faster than multinational distribution networks can penetrate. Pursue pharmaceutical co-development partnerships for drug-device combination products that bypass direct device pricing competition. For Investors and Strategic Acquirers: Capital is best deployed toward component specialists with captive piezoelectric crystal or mesh membrane capabilities that supply multiple competing OEMs. Long-term viability hinges on recurring revenue from consumable replacement parts rather than device hardware margins. Watch FDA 510(k) clearance backlogs as an inflection signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates US commercialization timelines for substantial equivalence claims against predicate devices. |
| CE Marking Pathway | Unlocks EU market access under MDR notified body conformity assessment for Class IIa respiratory devices. |
| Hospital System Partnership | Secures preferred vendor status through integrated respiratory care contracts bundling nebulization with oxygen therapy. |
| Software Companion Development | Enables adherence tracking for value-based reimbursement contracts with CMS and European HTA bodies. |
| Reimbursement Strategy | Aligns device qualification with procedural bundling codes that support capital equipment acquisition. |
Research Methodology
The analysis maps portable, tabletop, pediatric, and smart nebulizer sub-sectors, each validated through biomedical engineers, hospital purchasing committee members, GPO contracts managers, and respiratory therapy department heads. Primary interviews with device manufacturers and pharmaceutical formulation specialists were cross-referenced against FDA 510(k) filings, NMPA registration databases, EU MDR notified body certificates, and CMS reimbursement code revisions. Bottom-up unit demand estimates and top-down market sizing were triangulated for convergence.
Fixed assumptions across the analysis window include stable lithium-ion battery cost curves, continued FDA reliance on 510(k) substantial equivalence pathways, and sustained CMS procedural bundling for home care respiratory therapy. Segmentation dimensions modeled encompass product mobility class, aerosol generation technology, end-user care setting, and target patient population severity. CAGRs were derived from logistic diffusion curves fitted to historical adoption patterns and adjusted for reimbursement policy inflections in China and Germany.
Stress conditions across rare earth supply disruptions, EU MDR audit backlogs, and CMS code unbundling scenarios were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions and acknowledge that NMPA domestic testing protocol changes or sudden FDA de novo reclassification could materially revise trajectory. Quarterly review of FDA 510(k) clearance velocity, EU notified body capacity utilization, and Chinese tier-2 city reimbursement expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Vaccine Delivery Devices Market
Medical Devices
Human Enhancement Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Intraocular Lens (IOL) Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Electrical Stimulation Devices (Esds) Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Minimally Invasive Neurosurgery Devices Market
Medical Devices
Contact Thermometer Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Intravenous Stopcock Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Asia-Pacific Antimicrobial Coating for Medical Devices Market
Medical Devices
Ehealth Devices Market
Medical Devices
Asia-Pacific Manual Resuscitators Market
Medical Devices
Chemotherapy Infusion Pumps Market