
 Asthma and COPD Drugs Market | 2026-2036
Asthma and COPD Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asthma and COPD Drugs Market Analysis
Single-source API procurement for corticosteroid formulations is rebalancing toward qualified secondary suppliers as manufacturers mitigate geopolitical risk. GlaxoSmithKline plc anchors respiratory combination therapy development through sustained R&D investment across its inhaled portfolio. AstraZeneca plc leverages biologic specialization to differentiate in severe eosinophilic asthma segments where standard bronchodilators underperform. Boehringer Ingelheim GmbH dominates nebulized anticholinergic supply through manufacturing scale and established hospital formularies.
Asthma and COPD drugs comprise pharmacological agents formulated as bronchodilators, anti-inflammatory compounds, and biologic modifiers, typically delivered via pressurized metered-dose inhalers, dry powder devices, or nebulization systems with particle size distributions optimized for lower respiratory tract deposition, designed to reduce exacerbation frequency and improve forced expiratory volume in chronic obstructive pulmonary disease and reversible airway obstruction. Corticosteroid and beta agonist combinations occupy the deepest margin pools due to chronic maintenance requirements and patent-protected device formulations, while leukotriene modifiers face commoditization from generic tablet competition. Inhaler delivery modes command premium positioning against nebulizers and tablets owing to direct lung targeting and payer preference for outpatient management, though injectable biologics represent the fastest-growing modality in severe phenotype subsets.
FDA bioequivalence standards for orally inhaled products and EMA's MDR device classification requirements shape formulation development costs and generic substitution timelines, while China's NMPA accelerated review pathways for innovative respiratory biologics are redirecting clinical trial investment toward that regulator. The EU F-Gas Regulation constrains propellant choices for metered-dose inhalers, forcing manufacturers toward hydrofluoroalkane alternatives or dry powder transitions. Stakeholders must monitor how evolving pharmacovigilance requirements for long-acting muscarinic antagonists affect labeling and reimbursement across major prescribing markets.
Market Dynamics
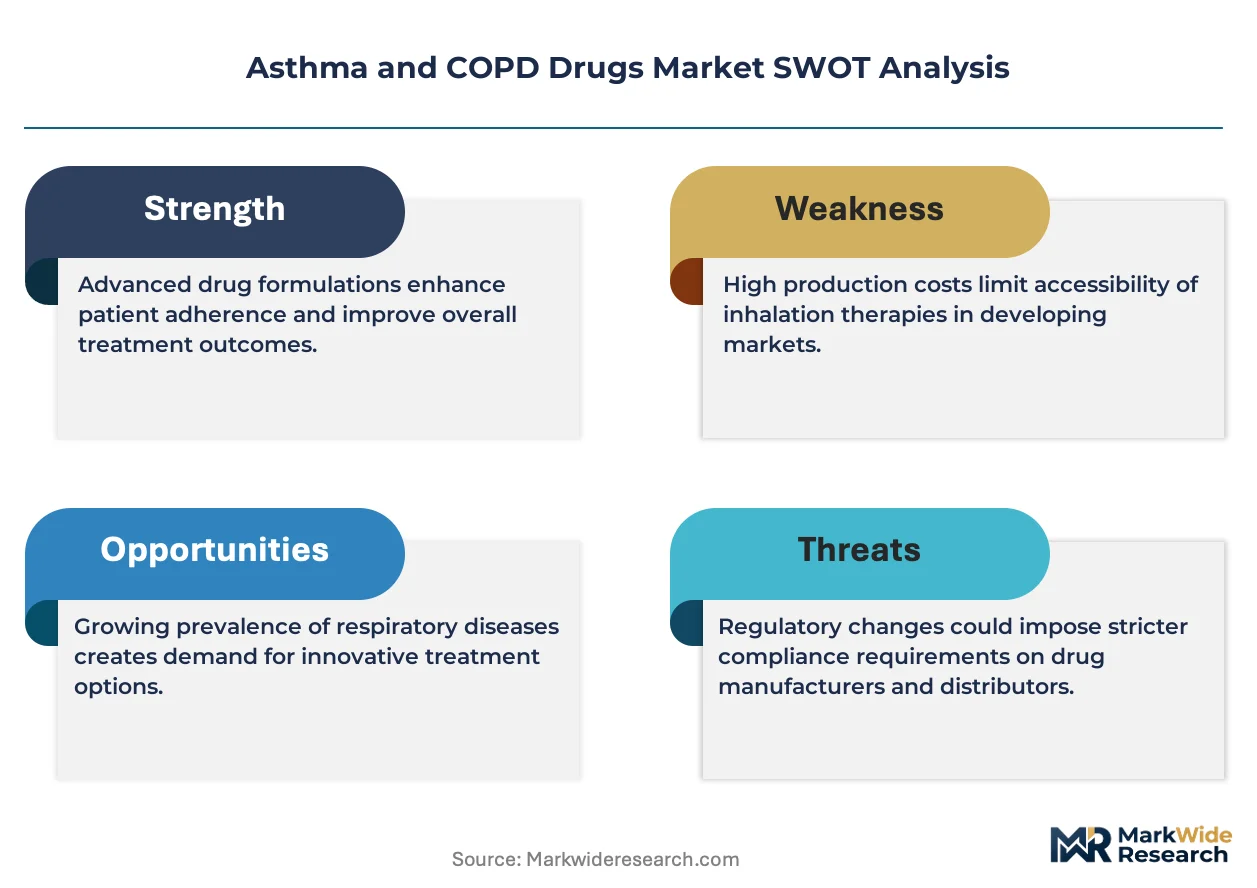
Hospital procurement consolidation around readmission-reduction protocols is redirecting formulary decisions toward combination inhalers with proven exacerbation-prevention data, compressing margins for single-mechanism bronchodilators.
Growth Catalysts
- Biologic reimbursement expansion:China's NMPA accelerated review pathways for respiratory biologics are redirecting clinical trial investment toward severe eosinophilic asthma segments.
- EMA MDR device classification:Stricter inhaler device standards are raising barriers to commoditized generics, protecting formulation-device combination patents.
- Centralized procurement reforms:National Health Commission reimbursement expansion in China is concentrating demand for biologic asthma therapies under volume-based purchasing.
Market Restraints
- Propellant transition costs:EU F-Gas Regulation constraints on hydrofluorocarbon propellants are forcing metered-dose inhaler manufacturers toward hydrofluoroalkane alternatives or dry powder transitions.
- API supply concentration:Single-source corticosteroid active pharmaceutical ingredient procurement from Indian contract manufacturers creates geopolitical exposure for European and North American formulators.
- Generic bioequivalence barriers:FDA updated standards for dry powder inhaler equivalence extend generic substitution timelines, limiting price competition in the United States.
Strategic Opportunities
- Home nebulization systems:Post-acute care discharge protocols in Germany and the United Kingdom are creating demand for connected nebulizer devices with adherence monitoring.
- Digital inhaler sensors:Bluetooth-enabled dose counters paired with maintenance therapies are opening reimbursement pathways under remote patient monitoring codes.
- Severe phenotype biologics:Anti-IL5 and anti-IgE monoclonal antibodies represent underpenetrated segments where standard bronchodilator maintenance fails.
Industry Challenges
- Inhaler engineering talent scarcity:Particle size distribution optimization for lower respiratory tract deposition requires specialized aerosol science expertise concentrated in limited academic programs.
- Legacy device platform integration:Electronic dose recording systems must interface with hospital electronic health record architectures that lack standardized respiratory medication data fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asthma and COPD Drugs Market |
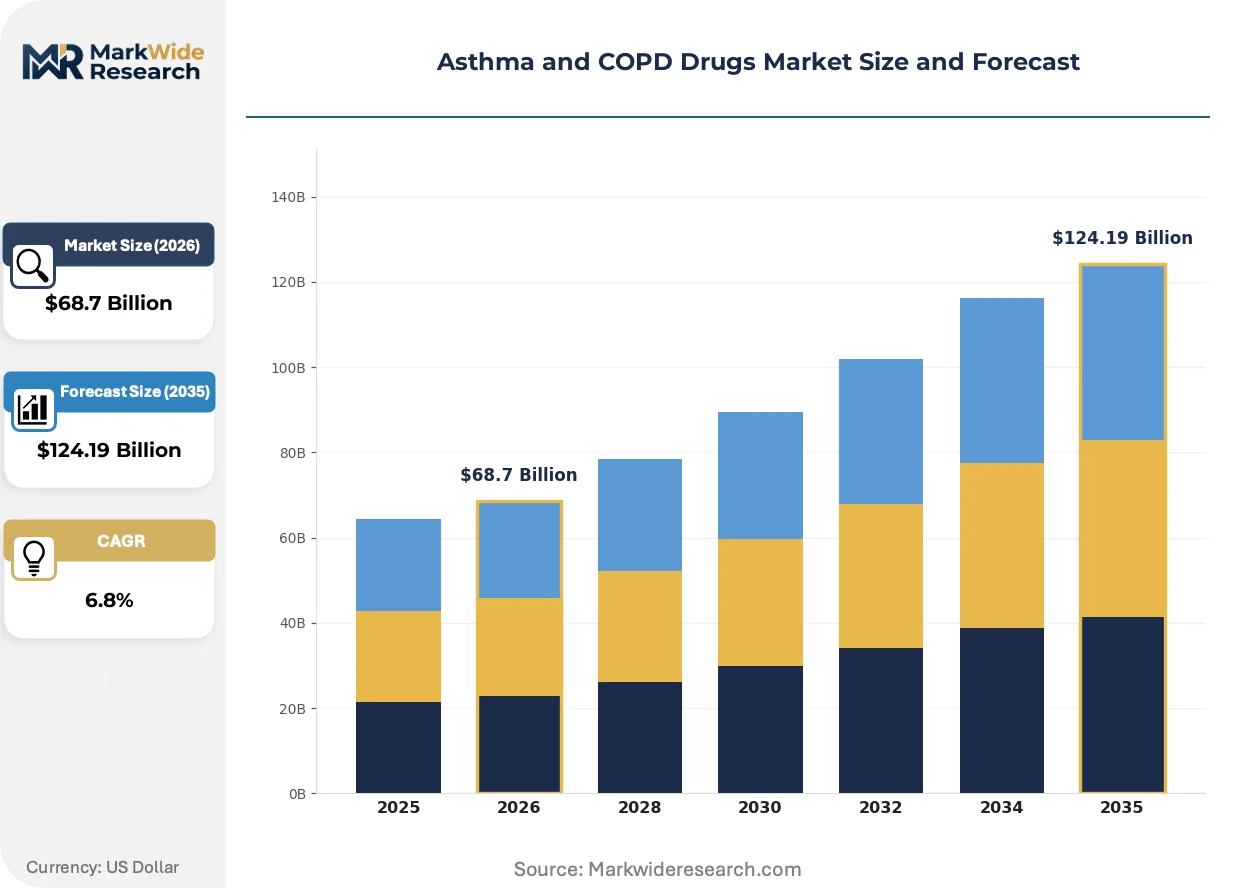
| Market Size in 2026 | $68.7 Billion |
| Market Size in 2035 | $124.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beta Agonists, Corticosteroids, Leukotriene Modifiers, Anticholinergics Delivery Mode: Inhalers, Nebulizers, Tablets, Injectables End User: Hospitals, Clinics, Home Care, Pharmacies Treatment Stage: Acute, Chronic, Maintenance, Preventative |
| Companies Covered | GlaxoSmithKline plc, AstraZeneca plc, Novartis AG, Boehringer Ingelheim GmbH, Teva Pharmaceutical Industries Ltd, Merck & Co. Inc, Pfizer Inc., Sanofi, F. Hoffmann-La Roche Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asthma and COPD Drugs Market Emerging Trajectories
Connected inhaler ecosystems and biologic specialization are fragmenting the traditional bronchodilator maintenance model, creating parallel premium and commodity supply tiers.
Smart inhaler technology with embedded sensors and cellular connectivity is decentralizing adherence monitoring from clinical sites to patient homes. Pulmonology practices in the United States and Netherlands are deploying these devices to reduce exacerbation-driven emergency department visits. The shift is compressing the traditional reliance on self-reported symptom diaries and enabling real-time intervention protocols.
EU F-Gas Regulation phase-down mandates are accelerating propellant chemistry transitions across European metered-dose inhaler portfolios. Manufacturers face reformulation costs and stability testing requirements that extend development timelines by eighteen to twenty-four months. Dry powder inhaler platforms are gaining share as hydrofluoroalkane alternatives remain supply-constrained.
Hospital procurement committees are consolidating vendor relationships around bundled combination therapy contracts that include device replacement and patient education services. Traditional wholesale distribution through retail pharmacy channels is losing share to direct-to-health-system logistics in the United States and United Kingdom. This concentration is most visible in integrated delivery networks managing Medicaid and Medicare populations.
Asthma and COPD Drugs Market Segmentation
Respiratory drug segmentation reveals divergent margin structures across delivery technologies and treatment intensities. Formulation-device combinations command premium positioning against commoditized oral generics, while biologic injectables are carving distinct reimbursement tiers in severe phenotype management.
Product Type:
Mechanism of action determines both clinical positioning and procurement economics, with combination formulations capturing the deepest margin pools through chronic maintenance requirements.
- Beta Agonists:Short-acting formulations provide rapid bronchodilation for acute rescue scenarios, while long-acting variants anchor maintenance protocols in COPD and persistent asthma. Hospital formularies in Germany and the United States are consolidating procurement around single-inhaler triple therapy combinations that embed LABA molecules with corticosteroids and anticholinergics, compressing standalone LABA volumes.
- Corticosteroids:Inhaled corticosteroids remain the cornerstone of anti-inflammatory maintenance, with particle size distribution engineering determining lower respiratory tract deposition efficiency. China's National Health Commission has expanded reimbursement for high-potency ICS formulations under centralized procurement reforms, redirecting volume toward fluticasone and budesonide derivatives with demonstrated exacerbation-reduction data.
- Leukotriene Modifiers:Oral montelukast and zafirlukast tablets face commoditization from generic competition across North American and European retail pharmacy channels.
- Anticholinergics:Long-acting muscarinic antagonists dominate COPD maintenance through once-daily dosing convenience and proven mortality benefit in combination regimens.
Mature deployment sits with Corticosteroids. Newer deployment is concentrated in Anticholinergics as triple-therapy formulations gain hospital formulary preference.
Delivery Mode:
Device technology stratifies the market into direct-lung targeting systems versus systemic administration routes, with reimbursement codes increasingly favoring adherence-monitoring capabilities.
- Inhalers:Pressurized metered-dose and dry powder devices command premium positioning through particle engineering optimized for alveolar deposition. The EU F-Gas Regulation is forcing propellant transitions across European MDI portfolios, while Bluetooth-enabled dose counters are opening remote patient monitoring reimbursement pathways in the United States and Netherlands.
- Nebulizers:Jet and mesh nebulization systems serve acute exacerbation management and pediatric or geriatric populations with coordination limitations. Post-acute care discharge protocols in Germany and the United Kingdom are creating demand for connected home nebulizers with cellular adherence reporting.
- Tablets:Oral leukotriene modifiers and methylxanthines occupy commodity tiers with thin margins and high generic substitution rates.
- Injectables:Subcutaneous monoclonal antibodies targeting IL-5, IL-4/13, and IgE pathways represent the steepest expansion trajectory in severe eosinophilic and allergic asthma phenotypes where standard bronchodilator maintenance fails.
Volume leadership belongs to Inhalers. Value growth is accelerating fastest in Injectables as biologic penetration deepens in treatment-resistant segments.
End User:
Procurement authority is shifting from retail pharmacy networks toward integrated health systems managing total cost of care for chronic respiratory populations.
- Hospitals:Inpatient and emergency department settings drive acute exacerbation management with nebulized bronchodilators and systemic corticosteroids. Integrated delivery networks in the United States are bundling device replacement and patient education services into combination therapy contracts, bypassing traditional wholesale distribution.
- Clinics:Pulmonology and allergy specialist practices prescribe biologic injectables and conduct phenotype testing to identify anti-IL5 and anti-IgE candidates.
- Home Care:Discharge planning departments are deploying connected inhaler and nebulizer ecosystems to reduce readmission penalties.
- Pharmacies:Retail channels retain rescue inhaler and generic oral medication dispensing, though margin compression from centralized procurement is redirecting volume toward health-system owned specialty pharmacies.
Established volume concentrates in Hospitals. Emerging deployment is shifting toward Home Care as remote monitoring technologies mature.
Treatment Stage:
Clinical guidelines stratify pharmacological intervention by symptom severity and exacerbation history, creating distinct procurement rhythms across acute rescue and chronic maintenance scenarios.
- Acute:Short-acting beta agonists and systemic corticosteroids address exacerbation rescue with immediate bronchodilation and inflammation suppression. Emergency department protocols in the United Kingdom and Australia are standardizing SABA-first approaches with ipratropium bromide add-on for severe presentations.
- Chronic:Daily controller therapy with inhaled corticosteroids or combination ICS/LABA formulations reduces long-term airway remodeling risk. Japan's Ministry of Health, Labour and Welfare has expanded reimbursement for high-dose ICS/LABA maintenance in severe asthma phenotypes.
- Maintenance:Long-acting bronchodilator combinations with or without inhaled corticosteroids form the backbone of COPD and persistent asthma management.
- Preventative:Pre-exposure prophylaxis with leukotriene modifiers or allergen immunotherapy targets trigger avoidance in allergic asthma subtypes.
Revenue depth lies in Maintenance. Biologic eligibility screening is expanding fastest in Chronic stage management of severe phenotypes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient synthesis for corticosteroid formulations clusters in Gujarat and Maharashtra, where Indian contract manufacturers supply European and North American formulators. This concentration creates geopolitical exposure that Western procurement committees now mitigate through qualified secondary supplier qualification.
United States
Hospital procurement consolidation around readmission-reduction protocols redirects formulary decisions toward combination inhalers with proven exacerbation-prevention data. FDA updated bioequivalence standards for generic dry powder inhalers extend substitution timelines and protect formulation-device combination patents. Integrated delivery networks in Texas and California bundle device replacement services into direct contracts, bypassing traditional wholesale distribution.
Germany
Post-acute care discharge protocols create demand for connected home nebulizers with cellular adherence reporting in Bavaria and North Rhine-Westphalia. EU F-Gas Regulation phase-down mandates accelerate propellant chemistry transitions across metered-dose inhaler portfolios, forcing eighteen to twenty-four month reformulation timelines. Pulmonology practices in Berlin deploy Bluetooth-enabled dose counters under remote patient monitoring reimbursement codes.
China
National Health Commission centralized procurement reforms expand reimbursement for biologic asthma therapies, redirecting clinical trial investment toward NMPA accelerated review pathways. Yangtze River Delta pharmaceutical clusters scale corticosteroid active pharmaceutical ingredient production for domestic formulation. Shanghai and Suzhou manufacturing bases supply fluticasone and budesonide derivatives to health systems prioritizing exacerbation-reduction data.
United Kingdom
Emergency department protocols standardize short-acting beta agonist-first approaches with ipratropium bromide add-on for severe presentations in London and Manchester health systems. EMA MDR device classification requirements raise barriers to commoditized generics, protecting patented inhaler platforms. Midlands manufacturing facilities face EU F-Gas Regulation compliance costs that compress margins on legacy hydrofluorocarbon propellant formulations.
Japan
Ministry of Health, Labour and Welfare reimbursement expansion for high-dose ICS/LABA maintenance in severe asthma phenotypes drives demand in Tokyo and Osaka metropolitan areas. Kanto region biopharma clusters develop particle size distribution engineering for lower respiratory tract deposition optimization. PMDA review timelines for innovative respiratory biologics attract multinational clinical trial investment away from slower Western regulatory pathways.
Asthma and COPD Drugs Market Vendor Landscape
Portfolio diversification dominates the current landscape as incumbents balance legacy bronchodilator maintenance against biologic specialization. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with integrated device-formulation capabilities, mid-scale biologic specialists targeting severe phenotype subsets, and regional generic manufacturers facing FDA and EMA bioequivalence barriers. Strategic archetypes include combination therapy platform holders, biologic monoclonal antibody developers, and connected device ecosystem integrators. M&A activity and technology licensing partnerships represent the primary competitive vectors as firms acquire aerosol science expertise and digital health capabilities.
Among UK-based pharmaceutical conglomerates, GlaxoSmithKline plc and AstraZeneca plc occupy positions spanning combination inhaler platforms and biologic specialization. Swiss-originated Novartis AG exemplifies the biologic-centric archetype through its respiratory monoclonal antibody positioning. German family-held Boehringer Ingelheim GmbH represents the nebulized anticholinergic and long-acting muscarinic antagonist manufacturing scale tier. Israeli-headquartered Teva Pharmaceutical Industries Ltd. sits within the generic complex formulation segment facing extended FDA equivalence timelines. These five entities collectively illustrate the competitive tension between patented device-formulation combinations and commoditized oral alternatives.
| Leading Market Players |
|---|
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Novartis AG |
| Boehringer Ingelheim GmbH |
| Teva Pharmaceutical Industries Ltd |
| Merck & Co. Inc |
| Pfizer Inc. |
| Sanofi |
| F. Hoffmann-La Roche Ltd |
| Others |
Supply Flow & Price Mechanics
Hydrofluoroalkane propellant transitions across European metered-dose inhaler portfolios are simultaneously elevating reformulation costs and redrawing API procurement geography. This dual pressure compresses margins on legacy hydrofluorocarbon formulations while rewarding manufacturers with captive supply relationships or dry powder platforms.
Pricing Analysis
Device replacement and patient education bundling separates hospital system contracts from unbundled retail pharmacy transactions. Three-tier pricing structure across patented combination inhalers, authorized generics, and commodity oral tablets reflects formulation complexity and reimbursement code differentiation. Cost compression in the leukotriene modifier tier intensifies because Indian and Chinese API oversupply erodes tablet margins. Retail pharmacy channels exhibit highest price sensitivity, while integrated delivery networks prioritize total cost-of-care outcomes over per-unit acquisition cost.
Supply Chain Analysis
Regional distribution centers in Gujarat and Maharashtra anchor corticosteroid API supply to European and North American formulators. Active pharmaceutical ingredient synthesis draws from Indian contract manufacturing clusters, with secondary qualification programs underway in Portugal and Singapore. Single-source concentration creates tariff exposure and geopolitical vulnerability. Distribution runs through direct-to-health-system logistics in the United States and United Kingdom, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market favors consolidation plays as FDA bioequivalence barriers and EMA MDR device requirements force subscale generic manufacturers toward exit or acquisition.
For Market Incumbents: Anticipate accelerated formulary consolidation by securing long-term device replacement contracts with integrated delivery networks. Biologic specialization in severe eosinophilic asthma segments protects against bronchodilator commoditization. Backward integration into particle engineering capabilities in Kanto and Yangtze River Delta clusters reduces API supply risk. For New Entrants and Emerging Players: Pulmonology practices in Germany and the Netherlands present partnership-ready entry points for connected inhaler ecosystems with remote patient monitoring reimbursement. Home nebulization systems with cellular adherence reporting represent the most penetrable white space. Target post-acute care discharge protocols as the initial go-to-market anchor. For Investors and Strategic Acquirers: Re-rating potential sits with aerosol science specialists given EU F-Gas Regulation-driven platform transitions. Five-to-ten-year viability favors firms with dual dry powder and hydrofluoroalkane capabilities plus digital health integration. Monitor NMPA accelerated review pathway approvals as the inflection signal for China clinical trial investment redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA MDR device classification compliance protects patented inhaler platforms from generic substitution. |
| Manufacturing Scale-Up | Dry powder inhaler capacity expansion in Shanghai and Suzhou captures EU F-Gas transition demand. |
| Hospital System Partnership | Bundled combination therapy contracts with Texas and California integrated delivery networks bypass wholesale channels. |
| Software Companion Development | Bluetooth-enabled dose counters open remote patient monitoring reimbursement codes in the Netherlands. |
| Reimbursement Strategy | NMPA accelerated review pathway positioning redirects clinical trial investment toward severe asthma biologics. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with drug development executives, formulary directors, hospital procurement managers, and payer access specialists cross-validated quantitative assumptions. FDA 510(k) filings, EMA marketing authorization applications, ClinicalTrials.gov records, and China NMPA registration databases supplied segmentation inputs. Bottom-up patient population modeling and top-down pharmaceutical market sizing reconciled through iterative triangulation.
Data-stream reconciliation across prescription audit databases, hospital procurement systems, and national reimbursement registries informed the analytical framework. Segmentation dimensions spanned mechanism of action, delivery mode, end user channel, and regional regulatory cluster. CAGRs derived from treatment intensity projections, biologic penetration curves, and device technology transition rates across the modeling period. Exacerbation frequency reduction data and real-world adherence metrics informed demand elasticity assumptions.
Several conditions sit outside the modeled scope, including pipeline phase transitions, patent litigation outcomes, and raw material price volatility. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement expansion trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Respiratory Care
Middle East and Africa Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Aspirin Exacerbated Respiratory Disease Market
Respiratory Care
Acute Lung Injury Market
Respiratory Care
Bronchopulmonary Dysplasia Treatment Market
Respiratory Care
Chronic Refractory Cough Treatment Market
Respiratory Care
Respiratory Measurement Devices Market
Respiratory Care
Lung Management Products Market
Respiratory Care
Lung Injury Market
Respiratory Care
Emphysema Market
Respiratory Care
Healthcare-Associated Pneumonia Market
Respiratory Care
Upper Respiratory Tract Infection Treatment Market
Respiratory Care
Ventilator-Associated Pneumonia (VAP) Market
Respiratory Care
Global Medical Ventilator Market
Respiratory Care
Budesonide Inhaler Market
Respiratory Care
North America Acute Respiratory Distress Syndrome (ARDS) Market
Respiratory Care
Asia-Pacific Acute Respiratory Distress Syndrome (ARDS) Market