
 US Intrauterine Devices Market | 2026-2036
US Intrauterine Devices Market Size, Share, and Industry Trends Forecast 2026-2036
US Intrauterine Devices Market Analysis
Specialty gynecology clinics and telehealth prescribing is reshaping how patients access long-acting contraception across the United States. Bayer leverages its established Mirena franchise to sustain brand loyalty among OB-GYN practices nationwide. CooperSurgical anchors the non-hormonal segment through Paragard's copper-based positioning, while AbbVie competes via its Allergan legacy portfolio in the hormonal IUD space.
An intrauterine device is a small, T-shaped contraceptive implant inserted into the uterus, typically measuring 32 millimeters horizontally and containing either levonorgestrel-releasing polymer or copper wire wound around a plastic stem to prevent fertilization through localized spermicidal or inflammatory effects. Hormonal IUDs dominate commercial volume due to extended duration labels and reduced bleeding profiles that drive patient satisfaction. Copper IUDs occupy a distinct niche among women seeking non-hormonal options, while family planning centers represent the fastest-growing end-user channel as Title X funding shifts toward community-based delivery.
FDA premarket notification and PMA pathways govern device approval, while state-level Medicaid expansion under CMS authority determines reimbursement breadth for insertion procedures. The Affordable Care Act's contraceptive mandate shapes insurer coverage obligations, though religious exemption litigation creates access variability across employer plans. Stakeholders must monitor state legislature movements on scope-of-practice laws, as nurse practitioner insertion authority expands access in underserved counties.
Market Dynamics
Medicaid expansion under the Affordable Care Act has fundamentally altered patient access patterns for long-acting reversible contraception across federally qualified health centers and community clinics.
Growth Catalysts
- Affordable Care Act Contraceptive Mandate:Employer-sponsored and marketplace plans must cover FDA-approved contraceptive methods without cost-sharing, eliminating upfront barriers for insured patients.
- Nurse Practitioner Scope Expansion:State-level scope-of-practice laws in Texas, California, and Florida now permit advanced practice providers to perform insertions, extending reach into physician-desert counties.
- Copper IUD Demand Resurgence:Patient preference for non-hormonal options drives volume in family planning centers and telehealth-prescribed delivery models.
Market Restraints
- Religious Exemption Litigation:Employer-based coverage gaps under Burwell v. Hobby Lobby create access variability across state insurance markets.
- Single-Source Copper Supply Concentration:Paragard's manufacturing depends on specialized copper wire suppliers with limited secondary sourcing options.
- Insertion Procedure Reimbursement Compression:CMS physician fee schedule updates lag procedural complexity, squeezing clinic margins on placement services.
Strategic Opportunities
- Telehealth-to-Insertion Pipeline:Virtual prescribing platforms in Texas and Florida coordinate with local clinics for same-day placement, reducing patient dropout between consultation and procedure.
- Title X Funding Reallocation:Federal family planning grants shifting toward community-based delivery create procurement volume for independent reproductive health centers.
- Extended-Duration Hormonal Formulations:Eight-year label extensions for levonorgestrel-releasing systems compress replacement cycles and lifetime patient acquisition costs.
Industry Challenges
- Specialized Insertion Training Bottlenecks:Competency certification for nurse practitioners and physician assistants requires supervised procedural hours that exceed clinic staffing capacity in rural markets.
- FDA PMA Pathway Timelines:Premarket approval for novel frame geometries or drug-eluting polymers extends development cycles, delaying competitive entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Intrauterine Devices Market |
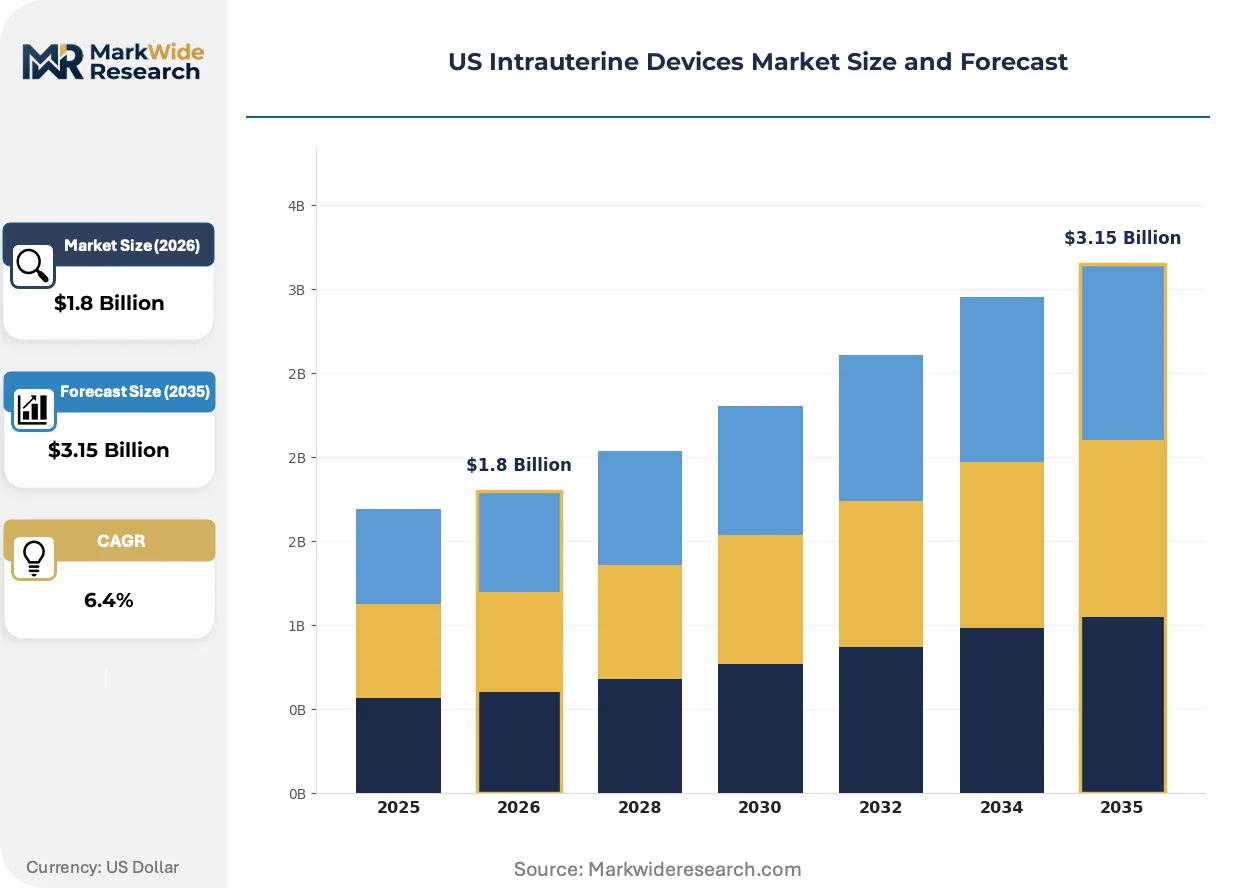
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hormonal IUD, Copper IUD, LNG IUD, Non-Hormonal IUD End User: Hospitals, Clinics, Healthcare Providers, Family Planning Centers Mode of Action: Hormonal Release, Copper-based Mechanism, Non-Hormonal, Multi-Mechanism Patient Demographics: Women of Reproductive Age, Adolescents, Postpartum Women, Nulliparous Women |
| Companies Covered | Bayer, AbbVie, CooperSurgical, Medicines360, Sebela Pharmaceuticals, DKT, Merck & Co, Teva Pharmaceutical Industries, Hologic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Intrauterine Devices Market Emerging Trajectories
Digital health infrastructure is compressing the gap between patient awareness and procedural access, while regulatory frameworks and reimbursement models adapt to decentralized care delivery.
Electronic health record integration is digitizing patient eligibility screening and prior authorization workflows for IUD placement. Federally qualified health centers in California and Texas deploy automated benefits verification that flags zero-cost-sharing status before scheduling. This compression of administrative friction reduces same-day cancellation rates and improves clinic throughput metrics.
State Medicaid programs under CMS authority are expanding carve-out reimbursement for insertion-only visits separate from annual wellness exams. This policy shift enables standalone billing for contraceptive counseling and placement, increasing provider willingness to offer same-day service. Texas Medicaid's 2023 benefit expansion most visibly demonstrates this structural adaptation.
Direct-to-patient pharmacy fulfillment is displacing traditional clinic-based device procurement in urban markets. Telehealth platforms in Florida coordinate with specialty pharmacies for pre-positioned device delivery to insertion sites, eliminating inventory carrying costs for smaller practices. This channel innovation concentrates in metropolitan counties with dense provider networks and same-day scheduling capacity.
US Intrauterine Devices Market Segmentation
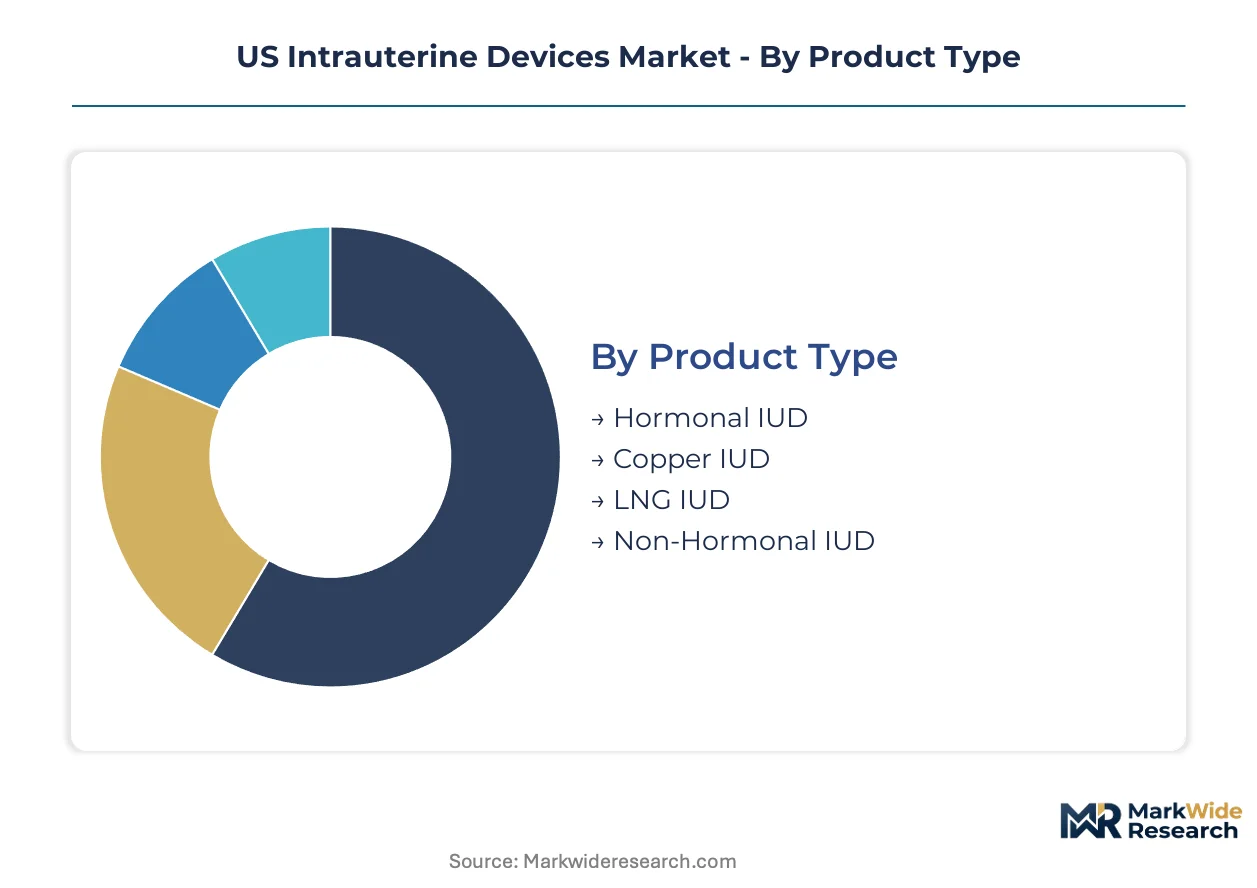
IUD market segmentation reveals how product chemistry, clinical setting, biological mechanism, and patient life stage each shape procurement patterns and reimbursement pathways across the United States. Understanding these intersecting dimensions clarifies why hormonal systems dominate commercial volume while copper alternatives sustain distinct positioning.
Product Type:
After-sales intensity varies sharply across product categories, with hormonal systems requiring ongoing clinical monitoring for side effect management and replacement scheduling.
- Hormonal IUD:Levonorgestrel-releasing polymer systems deliver localized progestin over multi-year intervals. Demand concentrates in Texas and California OB-GYN practices where extended duration labels reduce patient churn and drive predictable replacement revenue.
- Copper IUD:Plastic T-frame wound with copper wire generates localized inflammatory response for spermicidal effect. Family planning centers in Florida and federally qualified health centers across Medicaid expansion states favor this non-hormonal option for patients with contraindications to progestin.
- LNG IUD:Lower-dose levonorgestrel formulations target specific bleeding profile preferences.
- Non-Hormonal IUD:Alternative frame materials and inert compositions serve niche patient segments with dual hormone sensitivities.
Hormonal IUD holds the largest share; momentum sits with copper IUD as patient preference for non-hormonal contraception climbs the fastest.
End User:
Procurement scale and reimbursement complexity separate institutional buyers, with cost tier determining whether facilities carry inventory or rely on just-in-time specialty pharmacy fulfillment.
- Hospitals:Large health systems negotiate enterprise contracts covering insertion kits, devices, and emergency stock. California hospital networks leverage volume commitments for preferred pricing on levonorgestrel systems.
- Clinics:Independent gynecology practices and multi-specialty groups represent the volume midpoint. Texas independent clinics face margin pressure from CMS fee schedule compression on insertion procedures.
- Healthcare Providers:Individual physician practices and nurse practitioner-led sites drive fragmented demand.
- Family Planning Centers:Title X-funded community sites in Florida and expansion states experience steepest expansion trajectory as federal grants shift toward decentralized delivery.
Hospitals dominate procurement volume; family planning centers gain share fastest as policy reallocation accelerates.
Mode of Action:
Biological mechanism dictates FDA pathway, with PMA requirements for drug-device combinations creating higher regulatory barriers than 510(k) routes for inert systems.
- Hormonal Release:Diffusion-controlled levonorgestrel elution thickens cervical mucus and thins endometrial lining. OB-GYN practices in California favor these systems for patients seeking amenorrhea.
- Copper-based Mechanism:Ion release generates sterile inflammatory environment toxic to sperm. Medicaid expansion states show concentrated demand where cost sensitivity intersects with long-acting preference.
- Non-Hormonal:Physical barrier and ph effects without exogenous hormone delivery.
- Multi-Mechanism:Combined drug-eluting and physical action approaches in development pipelines.
Hormonal release commands installed base; copper-based mechanism expands most quickly amid hormone-free preference trends.
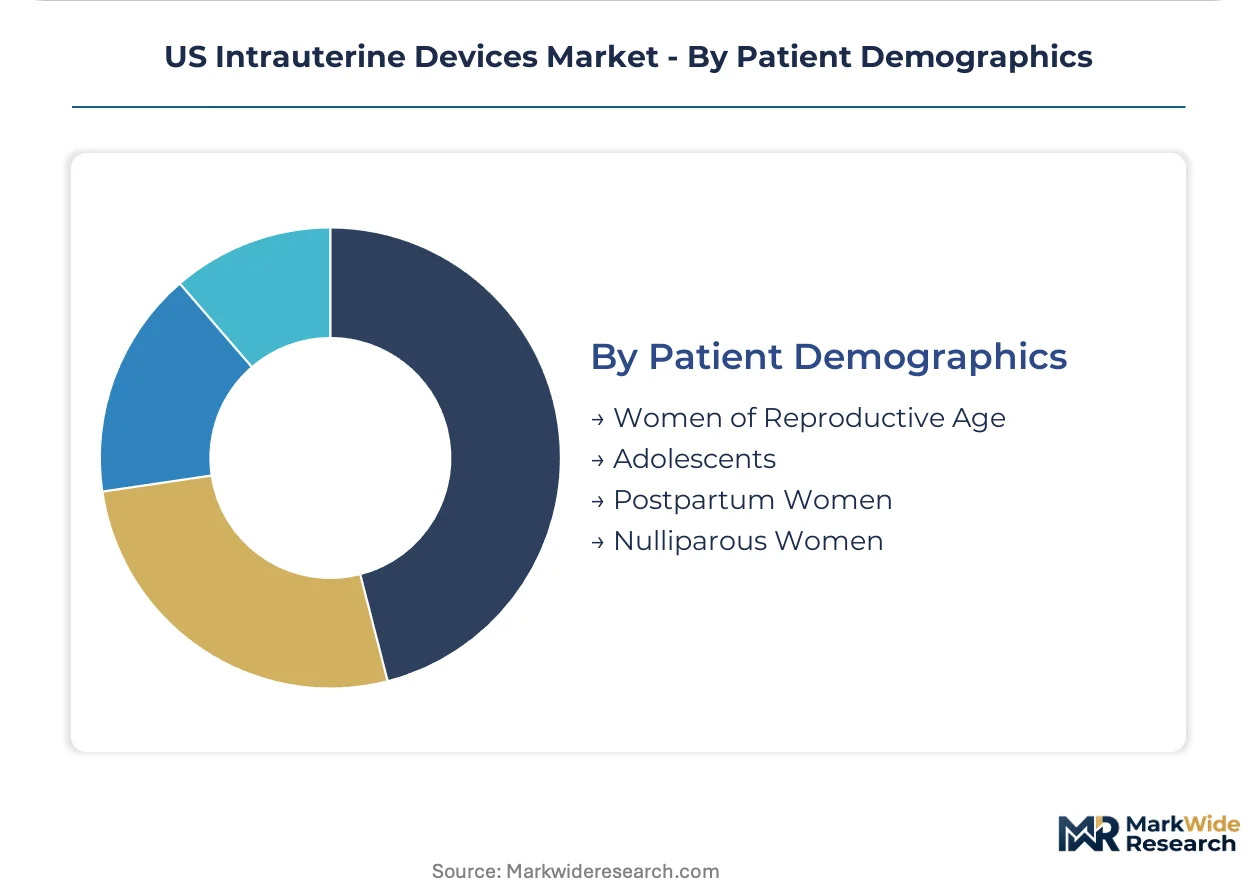
Patient Demographics:
Clinical indication and reimbursement eligibility vary across life stages, with postpartum placement qualifying for distinct billing codes that affect provider economics.
- Women of Reproductive Age:Core demographic spanning 15-49 years drives baseline demand. Texas and Florida Medicaid programs target this cohort with zero-cost-sharing mandates under ACA provisions.
- Postpartum Women:Immediate post-delivery insertion captures patients before return to fertility. Hospital systems in California leverage separate reimbursement codes for postpartum placement within 72 hours of delivery.
- Adolescents:Pediatric gynecology and school-based health centers serve this segment.
- Nulliparous Women:First-time contraceptive users without prior pregnancy require counseling-intensive selection support.
Women of reproductive age anchor volume; postpartum women show steepest utilization growth as immediate placement protocols spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA PMA pathways and state Medicaid authority under CMS govern device access across sub-regional markets. Texas, California, and Florida concentrate procurement volume where reproductive-age population density intersects with policy-driven reimbursement expansion.
Texas
Medicaid expansion limitations concentrate demand in federally qualified health centers and Title X clinics serving uninsured populations. State scope-of-practice laws permit nurse practitioner insertion authority, extending procedural access into rural counties beyond OB-GYN concentration. Houston and Dallas-Fort Worth anchor hospital system procurement for postpartum placement protocols.
California
Medi-Cal expansion and zero-cost-sharing mandates drive volume across community clinic networks and large health systems. Automated EHR benefits verification reduces administrative friction for same-day scheduling in Los Angeles and San Francisco Bay Area facilities. State-level carve-out reimbursement for standalone insertion visits separates contraceptive counseling from annual wellness billing.
Florida
Telehealth-prescribing platforms coordinate with specialty pharmacies for pre-positioned device delivery, eliminating inventory costs for independent practices. Miami-Dade and Broward County family planning centers experience steepest volume growth as federal Title X grants shift toward decentralized delivery models. State Medicaid managed care plans vary in prior authorization requirements across county lines.
Southeast (Georgia/North Carolina)
Hospital system consolidation in Atlanta and Charlotte creates enterprise procurement leverage for levonorgestrel system contracts. State Medicaid programs without expansion limit uninsured access to sliding-fee clinic networks. OB-GYN practice acquisition by private equity platforms concentrates insertion volume in metropolitan corridors.
Midwest (Illinois/Ohio/Michigan)
Chicago and Detroit health systems leverage volume commitments for preferred pricing on hormonal IUD portfolios. State-level contraceptive equity laws mandate coverage without cost-sharing in employer-sponsored plans. Rural clinic closures concentrate procedural capacity in tertiary hospital centers, extending patient travel distances for placement services.
US Intrauterine Devices Market Vendor Landscape
Pharmaceutical conglomerates and specialized women's health device manufacturers split the market across hormonal and non-hormonal product categories. The vendor base concentrates around three archetypes: diversified pharma majors with legacy contraceptive franchises, dedicated gynecological device specialists, and nonprofit/generic entrants targeting cost-sensitive channels. Consolidation pressure favors scale players with established OB-GYN sales infrastructure. Competitive moves center on extended-duration label extensions and telehealth partnership networks for virtual-to-procedural patient flow.
Within the pharmaceutical-major tier, Bayer and AbbVie occupy positions anchored by established hormonal IUD portfolios, while CooperSurgical exemplifies the device-specialist archetype through copper-based non-hormonal positioning. These three entities represent divergent strategic bets: pharma conglomerates leverage integrated sales forces across women's health portfolios, whereas CooperSurgical concentrates gynecological procedure equipment and contraceptive devices within a focused operational structure. Medicines360 and Sebela Pharmaceuticals sit within the access-oriented tier, targeting federally qualified health centers and international procurement channels with cost-optimized supply models.
| Leading Market Players |
|---|
| Bayer |
| AbbVie |
| CooperSurgical |
| Medicines360 |
| Sebela Pharmaceuticals |
| DKT |
| Merck & Co |
| Teva Pharmaceutical Industries |
| Hologic |
| Others |
Supply Flow & Price Mechanics
Specialized copper wire suppliers in Germany and Japan anchor upstream concentration for non-hormonal IUD manufacturing, concentrating margin capture in the polymer-drug combination tier where levonorgestrel-eluting systems command premium positioning. This upstream dependency on refined metal feedstock and pharmaceutical-grade polymers shapes how procurement teams at federally qualified health centers negotiate volume contracts against hospital system enterprise agreements.
Pricing Analysis
Geographic price spreads between Texas Medicaid reimbursement rates and California commercial payer schedules exceed the cost differential for device procurement alone. Three-tier pricing structure across premium hormonal, standard copper, and economy generic levels stratifies procurement channels, with FDA PMA certification tier and volume scale driving price differentiation. Cost compression in the copper IUD segment is intensifying because single-source supply limits competitive bidding. Family planning centers exhibit highest price sensitivity due to Title X grant constraints, while integrated hospital systems leverage enterprise commitments for least-sensitive tier access.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for independent gynecology practices purchasing through specialty pharmacy intermediaries. Manufacturing concentration rests on Germany, Japan, and the United States for pharmaceutical-grade polymers, copper wire drawing, and sterile packaging components. Raw material dependencies include levonorgestrel API, high-purity copper rod, and ethylene vinyl acetate copolymer. Single-source vulnerability for copper wire feedstock creates supply chain risk given limited secondary qualification pathways. Distribution runs through manufacturer-direct hospital contracts, specialty pharmacy fulfillment, and GPO-aggregated clinic purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US IUD market is entering a cyclical recovery phase as Medicaid expansion waves and ACA contraceptive mandate enforcement restore patient access volumes that contracted during prior policy uncertainty.
For Market Incumbents: Build regulatory data moats through extended-duration label supplements that compress replacement cycles and lock in patient lifetime value. Pursue backward integration into polymer resin production to defend margin position against commodity volatility. Secure nurse practitioner training certification partnerships to preempt emerging telehealth platforms from capturing insertion volume in rural Texas and Florida counties. For New Entrants and Emerging Players: Federally qualified health centers in non-expansion states represent the most penetrable entry point for cost-optimized copper IUD alternatives. Direct-to-patient pharmacy fulfillment models in metropolitan Florida bypass incumbent sales force infrastructure. Pursue FDA 510(k) pathway positioning for inert frame geometries to accelerate market entry beneath PMA timeline barriers. For Investors and Strategic Acquirers: Capital is best deployed toward device-specialist platforms with concentrated gynecological procedure portfolios rather than diversified pharma conglomerates where contraceptive franchises compete for R&D allocation. Long-term viability hinges on telehealth integration capabilities and state-level scope-of-practice regulatory positioning. Watch for inflection in nurse practitioner insertion authority legislation across southeastern states as signal for access expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Extended-Duration Label Extension | FDA approval for eight-year hormonal release compresses patient replacement cycles and lifetime acquisition costs. |
| Telehealth-to-Insertion Partnership | Virtual prescribing platforms in Texas coordinate same-day placement with local clinics to reduce patient dropout. |
| Nurse Practitioner Training Certification | Competency programs expand procedural access into physician-desert counties under state scope-of-practice laws. |
| Specialty Pharmacy Fulfillment Integration | Pre-positioned device delivery eliminates inventory carrying costs for independent Florida practices. |
| Title X Funding Alignment | Federal grant reallocation toward community-based delivery creates procurement volume for independent reproductive health centers. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across the analysis, including OB-GYN physicians, nurse practitioner clinic directors, hospital purchasing committee members, GPO contracts managers, and specialty pharmacy procurement leads. Primary interview findings were validated against secondary sources comprising FDA PMA and 510(k) filings, CMS Medicare reimbursement databases, state Medicaid formulary documents, and Title X funding allocation records. Bottom-up volume estimates from clinic-level insertion data were triangulated against top-down manufacturer shipment figures.
Calibration against historical insertion volume trends and reimbursement policy implementation timelines anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry, end-user facility type, biological mechanism, and patient life stage, with regional Medicaid expansion status as an additional cross-cutting variable. CAGRs were derived from fitted growth curves applied to policy-driven access expansion scenarios, incorporating FDA approval pathway timelines and state-level scope-of-practice legislative trajectories as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in federal health care funding allocations, state Medicaid matching rates, or contraceptive mandate litigation outcomes would shift the trajectory. Forecasts reflect documented assumptions about policy continuity and reimbursement stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
North America Single-Use Medical Device Reprocessing Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Low Flux Single-Use Dialyzers Market
Medical Devices
Injectable Drug Delivery Market
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Asia Pacific Portable X-Ray Devices Market
Medical Devices
Artificial Respirator Market
Medical Devices
Vascular Guidewires Market
Medical Devices
Artificial Disc Replacement Market
Medical Devices
Gastric Bands Market
Medical Devices
Middle East and Africa Medical Devices Market
Medical Devices
Manual Wheelchair Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Eye Drop Dispenser Market
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Global Medical Injection Molding Market