
 Marine Fender Market | 2026-2036
Marine Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Fender Market Analysis
Container terminal operations is shifting toward deeper-draft berths capable of handling vessels exceeding 24,000 TEU. Trelleborg Marine & Infrastructure leverages its integrated fender-to-bollard systems to dominate Northern European retrofit cycles. Yokohama Rubber Company anchors Asian supply through captive rubber compounding facilities in Japan and Thailand. JIER Marine competes aggressively on pneumatic fender tenders across Belt and Road port financings.
Marine fenders are energy-absorption devices installed along quay walls and vessel hulls to prevent structural damage during berthing, typically manufactured from reinforced rubber compounds or closed-cell foam cores with outer elastomer skins rated for reaction forces exceeding 1,000 kN. Pneumatic fenders lead port operations applications due to their deflection resilience and ease of relocation, while composite fenders capture margin pools in offshore structures where corrosion resistance and low maintenance justify premium positioning. Foam fenders sustain growth in temporary installations and emergency response fleets where rapid deployment outweighs per-unit cost.
ISO 17357 governs pneumatic fender dimensional tolerances and pressure testing protocols, while PIANC guidelines shape fender selection criteria for specific vessel classes and berthing velocities. The EU Green Deal's port electrification mandates indirectly tighten fender specifications as shore-power infrastructure alters vessel approach patterns and mooring loads. Stakeholders must monitor how IMO decarbonization timelines reshape vessel dimensions, draft requirements, and consequently fender energy-absorption specifications across major port redevelopment cycles.
Market Dynamics
Container terminal operators are deepening berths to accommodate ultra-large vessels exceeding 24,000 TEU, forcing simultaneous upgrades to fender energy-absorption ratings and reaction force specifications across port redevelopment cycles.
Growth Catalysts
- IMO Emission Guidelines:The International Maritime Organization's revised vessel emission standards are accelerating port infrastructure modernization in Vietnam, Indonesia, and the Philippines as manufacturing supply chains relocate from China.
- Pneumatic Fender Relocation Ease:Port operators favor pneumatic fenders for their deflection resilience and rapid repositioning capabilities during vessel traffic surges at expanding Southeast Asian terminals.
- Thailand Rubber Supply:Captive rubber compounding facilities in Japan and Thailand anchor Asian supply security, reducing raw material transit times for regional fender fabrication.
Market Restraints
- Natural Rubber Price Volatility:Reinforced rubber compound formulations remain exposed to fluctuating natural rubber futures, compressing margin predictability for pneumatic fender manufacturers.
- ISO 17357 Compliance Burden:Dimensional tolerance and pressure testing protocols add certification overhead, extending product development timelines for new market entrants.
- Foam Core Substitution:Closed-cell foam fenders are capturing temporary installation contracts where rapid deployment outweighs per-unit cost premiums, pressuring rubber fender pricing.
Strategic Opportunities
- EU Green Deal Port Electrification:Shore-power infrastructure mandates are altering vessel approach patterns, creating demand for fenders rated to modified mooring load profiles at Northern European retrofit sites.
- Offshore Composite Fenders:Corrosion-resistant elastomer-skinned foam cores are penetrating offshore structures where maintenance access constraints justify premium positioning.
- Belt and Road Port Financings:Pneumatic fender tenders tied to infrastructure lending are opening procurement channels at emerging terminals across Indian Ocean littoral states.
Industry Challenges
- PIANC Guideline Interpretation Variance:Fender selection criteria for specific vessel classes and berthing velocities lack uniform implementation, complicating cross-port specification standardization.
- Legacy Quay Wall Retrofit Integration:Existing port structures require custom mounting adaptations for modern high-reaction fenders, inflating engineering costs and project timelines.
- Composite Material Certification Delays:Novel foam-core and elastomer formulations face extended approval cycles under evolving ISO and classification society protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Fender Market |
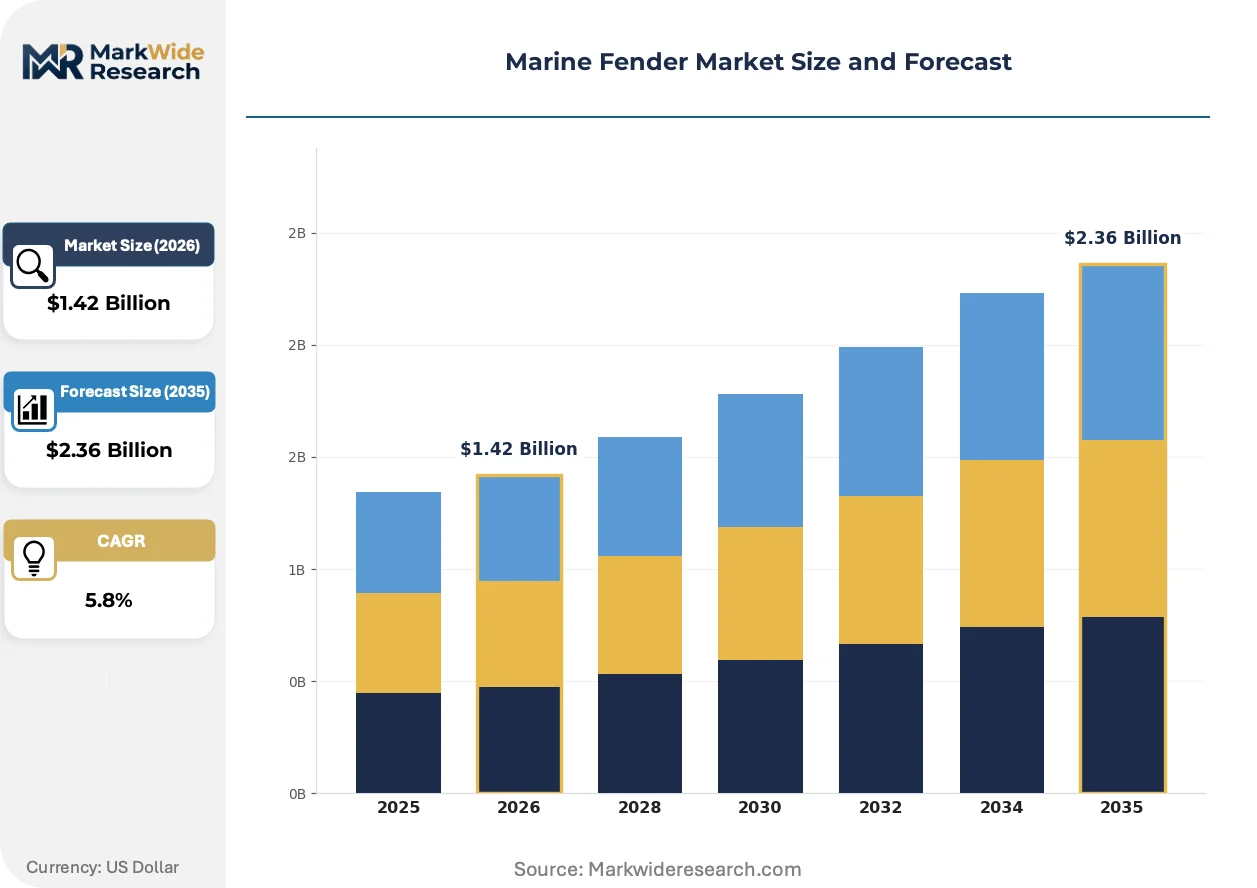
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inflatable Fenders, Foam Fenders, Pneumatic Fenders, Composite Fenders Application: Port Operations, Ship Docking, Offshore Structures, Boat Mooring Material: Rubber, Polyurethane, Nylon, PVC Installation: Permanent Installation, Temporary Installation, Floating Configuration, Fixed Configuration |
| Companies Covered | Shibata Fender Company, Hutchinson, Trelleborg Marine & Infrastructure, James Fisher Fendercare, Marine Fenders International, Yokohama Rubber Company, Sumitomo Rubber, JIER Marine, Bridgestone, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Fender Market Emerging Trajectories
Marine fender technology is bifurcating between high-performance permanent installations and rapidly deployable temporary systems, with material science and regulatory pressure reshaping competitive positioning across both segments.
Smart fender monitoring systems using embedded pressure sensors and wireless telemetry are electrifying predictive maintenance protocols at automated container terminals. Port operators in Rotterdam and Singapore are piloting real-time deflection monitoring to optimize vessel approach velocities. This capability is compressing insurance premium differentials between Tier-1 and standard fender installations by quantifying actual energy absorption performance.
The EU Green Deal's port electrification mandates are tightening fender specifications as shore-power infrastructure alters traditional vessel mooring dynamics. Northern European terminal operators must recalculate reaction force requirements to account for modified vessel positioning during cold-ironing operations. Composite fender manufacturers with corrosion-resistant formulations are capturing specification upgrades at Hamburg and Antwerp retrofit projects.
Terminal operators are consolidating procurement through integrated fender-to-bollard system contracts rather than component-level purchasing. This bundling is displacing standalone fender vendors at major port authority tenders across Southeast Asia. The shift is most visible in Vietnam and Indonesia, where state-owned terminal operators prioritize single-source accountability for berthing safety systems.
Marine Fender Market Segmentation
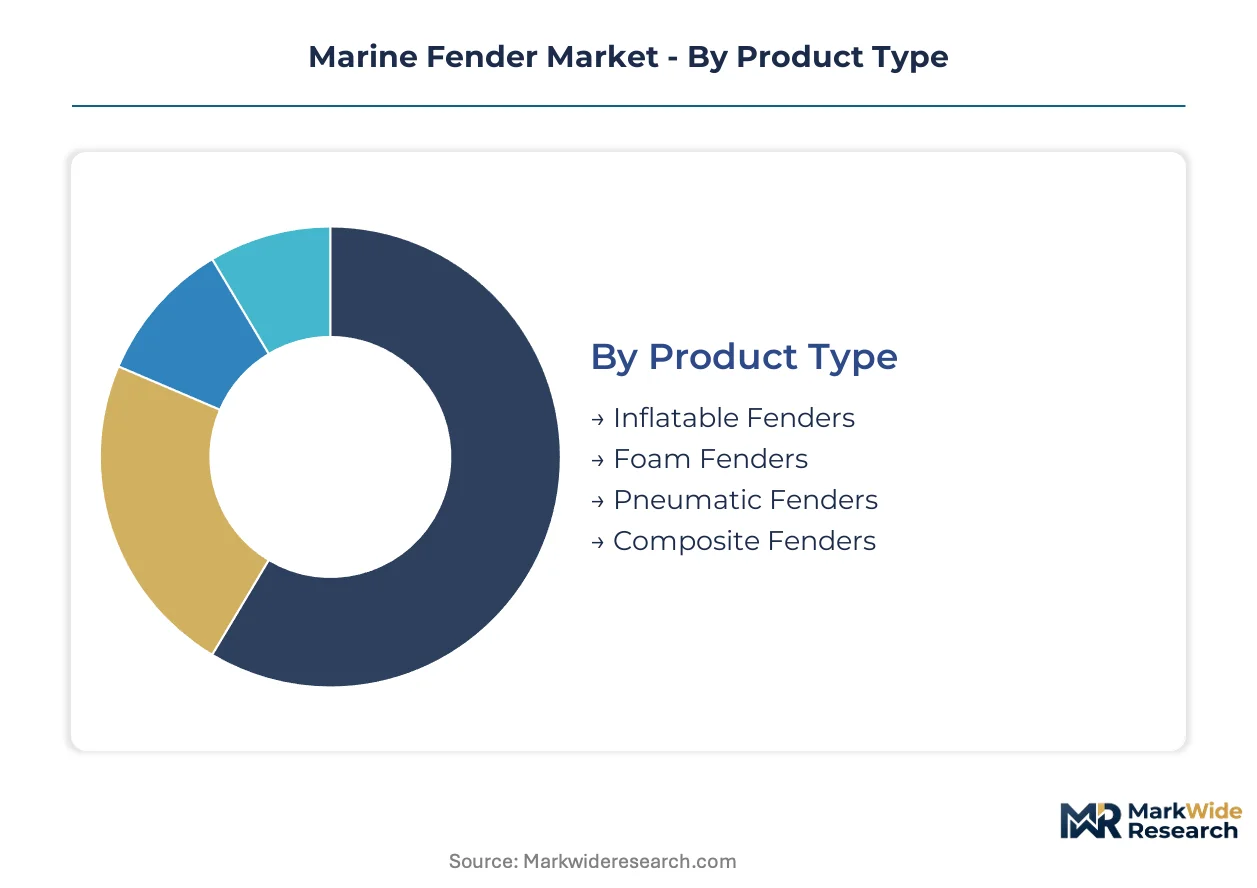
Marine fender segmentation reveals distinct capital intensity profiles across product categories, with pneumatic and composite systems demanding higher upfront engineering investment than foam alternatives. Port operators and offshore developers select fender types based on berthing frequency, vessel class, and maintenance access constraints.
Product Type:
Pneumatic and composite fenders require the heaviest capital deployment due to reinforced rubber compounding infrastructure and corrosion-resistant elastomer formulation R&D.
- Pneumatic Fenders:Air-filled rubber chambers with reinforced tire-cord layers withstand reaction forces exceeding 1,000 kN at container terminals. Demand concentrates in Vietnam, Indonesia, and the Philippines as manufacturing supply chains relocate from China and deepen draft berths for ultra-large vessels.
- Composite Fenders:Closed-cell foam cores with outer elastomer skins deliver corrosion resistance for offshore structures where maintenance access constraints justify premium positioning against rubber alternatives.
- Inflatable Fenders:Lightweight PVC or nylon construction suits recreational boat mooring and emergency response fleets requiring rapid deployment capabilities.
- Foam Fenders:Solid closed-cell polyethylene cores absorb impact through compression rather than air displacement, capturing temporary installation contracts where deployment speed outweighs per-unit cost.
Most installed capacity flows through pneumatic fenders at commercial container terminals. Expansion is steepest in composite fenders as offshore wind installations multiply across the North Sea and East Asian littoral zones.
Application:
Port operations absorb the majority of fender procurement volume, though offshore structures command the highest per-unit pricing due to environmental exposure severity.
- Port Operations:Quay wall installations at container terminals require energy-absorption ratings scaled to vessel class and berthing velocity per PIANC guidelines. Operators in Rotterdam and Singapore pilot smart monitoring systems with embedded pressure sensors.
- Offshore Structures:Oil platforms and wind turbine foundations demand corrosion-resistant fender systems rated for continuous wave action and limited maintenance windows.
- Ship Docking:Vessel-mounted fenders protect hull integrity during alongside transfers and lightering operations in open water conditions.
- Boat Mooring:Marina and yacht club installations prioritize aesthetic integration and low-maintenance materials over maximum energy absorption.
Port operations account for the dominant share of fender installations by unit volume. Offshore structures are climbing fastest as floating wind platforms enter commercial deployment.
Material:
Rubber compounds dominate material procurement by tonnage, though polyurethane gains specification share in environments requiring UV stability and chemical resistance.
- Rubber:Natural and synthetic rubber blends reinforced with tire-cord or steel-wire matrices deliver the deflection resilience required for pneumatic fender applications at major container terminals.
- Polyurethane:Cast elastomer formulations resist hydrocarbon exposure and ultraviolet degradation, penetrating offshore specifications where maintenance intervals must extend beyond rubber alternatives.
- Nylon:High-tensile strength textile reinforcement layers provide structural integrity for inflatable fender skins in recreational and emergency applications.
- PVC:Thermoplastic construction offers cost-efficient fabrication for low-duty cycle installations where energy absorption requirements remain modest.
Rubber formulations carry the heaviest installed base across commercial marine applications. Polyurethane is gaining specification fastest at North Sea offshore platforms exposed to aggressive salt spray and hydrocarbon contact.
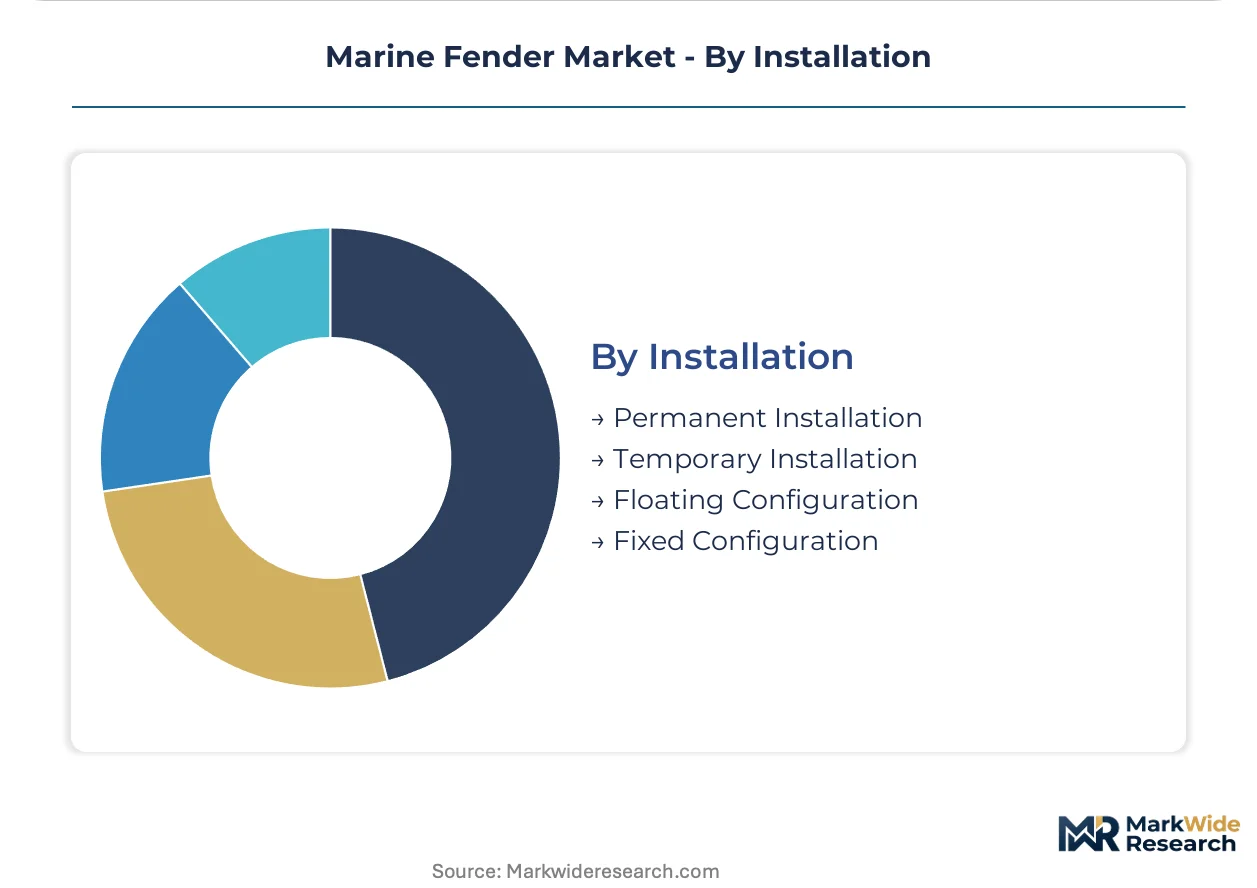
Installation:
Permanent installations lock capital into quay wall infrastructure for decades, while temporary configurations enable operational flexibility at expanding terminals managing vessel traffic surges.
- Permanent Installation:Bolted or chained fender systems integrated into concrete quay walls deliver design-life performance exceeding twenty years at major container terminals.
- Temporary Installation:Rapidly deployable floating or suspended fenders support emergency response, seasonal traffic peaks, and construction-phase vessel protection.
- Floating Configuration:Mooring-line suspended fenders adjust to tidal variation and vessel freeboard differences without fixed mounting infrastructure.
- Fixed Configuration:Rigidly mounted fender panels maintain precise energy-absorption geometry for automated berthing systems at high-throughput terminals.
Permanent installations represent the largest cumulative capital commitment across port infrastructure. Temporary configurations are expanding most quickly at Southeast Asian terminals managing Belt and Road construction phases and traffic volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward Southeast Asian ports where environmental compliance costs remain below Northern European benchmarks. Port authorities in Vietnam, Indonesia, and the Philippines are deepening berths to capture container traffic migrating from Chinese terminals. IMO emission guidelines are accelerating this infrastructure buildout as vessel operators seek compliant refueling hubs.
Vietnam
Container terminal operators at Cai Mep and Lach Huyen are expanding berthing capacity for ultra-large vessels exceeding 24,000 TEU. The country's Ministry of Transport has streamlined port development permits under the National Master Plan for Seaport Development. Manufacturing supply chains relocating from China are concentrating at Hai Phong and Ba Ria-Vung Tau, driving synchronized fender procurement for new quay walls.
Indonesia
State-owned terminal operator Pelindo is retrofitting Jakarta and Surabaya ports with deeper-draft infrastructure. The Indonesian Maritime Security Agency enforces updated vessel approach protocols aligned with IMO safety standards. Kalibaru Terminal expansion in East Java exemplifies integrated fender-to-bollard system procurement favoring single-source contractors.
Philippines
Manila International Container Terminal and Subic Bay Freeport are modernizing berths to accommodate post-Panamax vessel classes. The Philippine Ports Authority mandates PIANC-compliant fender specifications for all public terminal upgrades. Cebu and Davao port clusters are emerging as secondary hubs where temporary fender installations support construction-phase vessel protection.
Thailand
Captive rubber compounding facilities in Rayong and Map Ta Phut anchor regional supply security for pneumatic fender fabrication. Thailand's Board of Investment offers tax incentives for port infrastructure equipment manufacturing under its targeted industry promotion scheme. Laem Chabang Port Phase III expansion is specifying high-reaction fenders for automated berthing systems.
Netherlands
Rotterdam terminal operators are piloting smart fender monitoring with embedded pressure sensors and wireless telemetry. The EU Green Deal's port electrification mandates are tightening fender specifications as shore-power infrastructure alters vessel mooring dynamics. Maasvlakte 2 redevelopment is recalculating reaction force requirements for cold-ironing operations.
Marine Fender Market Vendor Landscape
Integrated system bundling dominates the current landscape as terminal operators consolidate procurement through fender-to-bollard contracts rather than component-level purchasing. The vendor base organizes around three strategic archetypes: European engineering conglomerates with captive rubber technology, Asian rubber specialists leveraging vertical supply control, and regional fabricators competing on pneumatic fender tenders. Capacity expansion and geographic licensing represent the primary competitive moves, with manufacturers establishing compounding facilities near Southeast Asian demand clusters.
Among Japanese rubber conglomerates, Yokohama Rubber Company and Sumitomo Rubber exemplify the integrated-materials archetype through captive compounding infrastructure. Trelleborg Marine & Infrastructure anchors the European engineering tier with system-level contracting capabilities. JIER Marine occupies a position within the project-finance specialist segment, particularly visible across Belt and Road port procurement channels.
| Leading Market Players |
|---|
| Shibata Fender Company |
| Hutchinson |
| Trelleborg Marine & Infrastructure |
| James Fisher Fendercare |
| Marine Fenders International |
| Yokohama Rubber Company |
| Sumitomo Rubber |
| JIER Marine |
| Bridgestone |
| Others |
Supply Flow & Price Mechanics
Family-owned rubber specialists in Thailand and Japan anchor supply-side discipline through captive compounding infrastructure, translating upstream material control into pricing power at pneumatic fender tenders across Southeast Asian port expansions.
Pricing Analysis
Distributor margins at project-finance channels absorb 12-18 points before terminal operators see landed quotes. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17357-certified systems from uncertified regional fabricators. Cost compression in economy-tier pneumatic fenders is intensifying because foam-core substitutes capture temporary installation contracts. State-owned terminal operators in Vietnam and Indonesia exhibit lowest price sensitivity, prioritizing single-source accountability over component-level savings.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Pelindo and the Philippine Ports Authority, bypassing distributor markups for integrated fender-to-bollard system contracts. Raw material sourcing draws from Thailand's natural rubber belt, Japan's synthetic compounding facilities, and South Korea's tire-cord reinforcement supply. Distribution runs through Rotterdam and Singapore hub terminals for Northern European and Southeast Asian retrofit cycles respectively. Single-source vulnerability concentrates in natural rubber futures exposure, with reinforced compound formulations tethered to volatile commodity exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: manufacturing supply chains relocating from China face stricter environmental compliance costs than greenfield developments in Vietnam, Indonesia, and the Philippines.
For Market Incumbents: Extend captive rubber compounding capacity into Vietnam and Indonesia to defend margin position against JIER Marine's aggressive Belt and Road tendering. Secure PIANC guideline interpretation partnerships with port authorities before specification standardization hardens. ISO 17357 certification investment represents the critical lever for displacing uncertified regional fabricators at state-owned terminal tenders. For New Entrants and Emerging Players: Temporary installation contractors at Cebu and Davao construction-phase port clusters present an underserved buyer archetype with rapid deployment requirements and lower certification barriers. Foam fender specifications for emergency response fleets offer the most penetrable segment given compressed procurement cycles. A go-to-market angle anchored to rental-service models rather than capital sales unlocks working-capital-constrained regional operators. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap composite fender specialists with corrosion-resistant formulations for North Sea offshore wind platforms. Long-term viability across the analysis window hinges on EU Green Deal port electrification mandates reshaping mooring load specifications. The signal to watch is classification society approval velocity for novel elastomer-skinned foam cores at Hamburg and Antwerp retrofit sites.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Captive supply of reinforced tire-cord layers secures margin control against natural rubber futures volatility. |
| Smart Fender Monitoring System Launch | Embedded pressure sensors at Rotterdam and Singapore terminals compress insurance premium differentials through quantified performance. |
| Composite Formulation Certification Pathway | Novel foam-core elastomer approvals under evolving ISO protocols unlock offshore wind platform specifications. |
| Integrated Fender-to-Bollard Contracting | Single-source procurement consolidation at Kalibaru Terminal displaces standalone component vendors. |
| Southeast Asian Manufacturing Footprint | Rayong and Map Ta Phut facilities reduce raw material transit times for Vietnam and Indonesia demand clusters. |
Methodological Framework
Multiple input streams — technical discussions with port authority procurement directors, regulatory consultations with IMO safety committee members, and operational interviews with terminal engineering managers — were reconciled against customs trade data, PIANC guideline documentation, and SEC filings from listed rubber conglomerates. Bottom-up triangulation across pneumatic fender tender databases and top-down validation through port infrastructure investment tracking anchored volume estimates.
Data-stream reconciliation applied across product type, application, material, installation configuration, and regional regulatory cluster dimensions. CAGRs were derived from berth-deepening project pipelines and vessel class migration curves. Forecast inputs incorporated IMO decarbonization timeline impacts on draft requirements and shore-power infrastructure alterations to mooring load profiles.
Underlying measurement precision varies by segment; pneumatic fender installations at major container terminals carry tighter precision than temporary foam fender deployments at emerging secondary hubs. Forecasts reflect assumptions around natural rubber price stability and Belt and Road financing continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Transport Refrigeration Unit Market
Marine
Hybrid Fishing Boats Market
Marine
North Sea Offshore Support Vessels Market
Marine
Flap Rudder Market
Marine
Marine Chartplotter Market
Marine
North America Naval Vessels Market
Marine
Marine Shackle Market
Marine
Unmanned Marine Vehicles Market
Marine
Sliding Fender Market
Marine
Marine Suspension Seat Bases Market
Marine
Ship/Boat Keel Market
Marine
Europe ROV Market
Marine
Boat Ladder Market
Marine
Boat Console Market
Marine
Global Marine Gearbox Market
Marine
Marine Salvage Services Market