
 Asia-Pacific Offshore Support Vessels Market | 2026-2036
Asia-Pacific Offshore Support Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Offshore Support Vessels Market Outlook
Modular vessel configurations with swappable mission packages is recalibrating how charterers match hulls to contract duration and task scope. Solstad Offshore ASA leverages its North Sea-hardened fleet management systems to compete for long-term Asia-Pacific charters. Tidewater Inc. anchors its regional presence through established port relationships in Southeast Asian logistics hubs. Keppel Corporation dominates newbuild contracting with yard capacity that extends from Singapore into Batam.
Offshore support vessels are purpose-built marine craft typically ranging from 50 to 150 meters in length, designed to transport personnel, supplies, and heavy equipment to fixed and floating offshore installations. Their diesel-electric or hybrid propulsion systems deliver station-keeping precision measured by dynamic positioning class notation for operations in sea states up to significant wave heights of five meters. Anchor handling tug supply vessels lead contract volume across the Asia-Pacific fleet due to persistent demand from legacy oil and gas mooring operations, while platform supply vessels attract premium day rates from offshore wind construction support. Deep water and ultra-deep water operation modes are gaining share as exploration moves off Australia's northwest shelf and into Myanmar's offshore concessions.
The Australian Maritime Safety Authority enforces stringent dynamic positioning operator certification that filters vessel eligibility for Bass Strait campaigns. Japan's METI coordinates with Nippon Kaiji Kyokai to align domestic vessel construction subsidies with decarbonization benchmarks including LNG dual-fuel readiness. China's MEE mandates exhaust gas cleaning system installations for vessels operating within twelve nautical miles of provincial coastlines. Stakeholders must weigh fleet renewal timing against emerging ammonia fuel pathway commitments and evolving charterer Scope 3 reporting obligations.
Market Dynamics
Japan's METI vessel construction subsidies tied to decarbonization benchmarks are compressing fleet renewal timelines across the Asia-Pacific basin. Charterers now face accelerated capital deployment decisions as dual-fuel readiness becomes a contractual gate.
Growth Catalysts
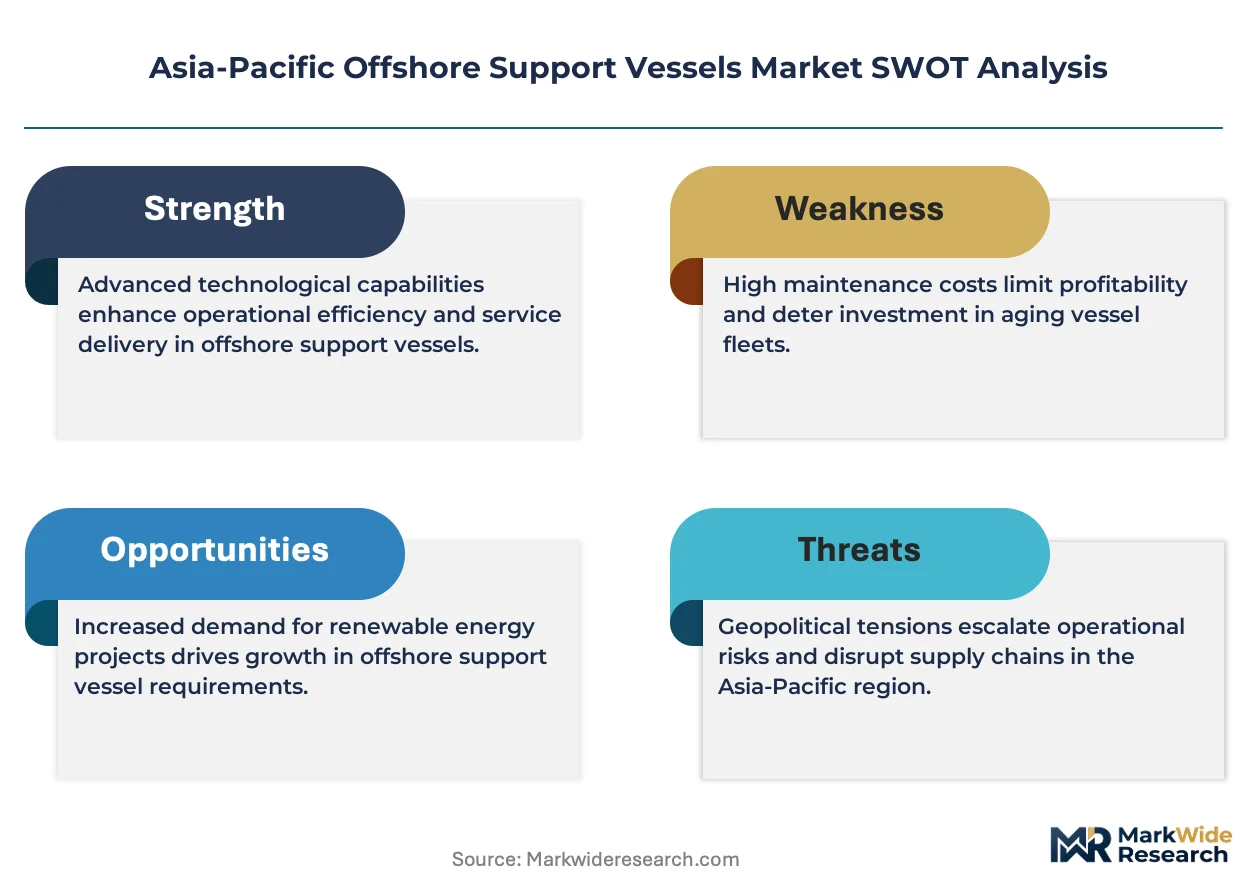
- Offshore wind installation demand:Australia's turbine installation campaigns in Bass Strait and the Gippsland offshore zone are absorbing anchor handling tug supply vessels at premium utilization rates.
- China's MEE coastal emissions mandate:Exhaust gas cleaning system requirements within twelve nautical miles of provincial coastlines are forcing fleet upgrades among Bohai Bay operators.
- Deep water exploration migration:Myanmar's offshore concessions and Australia's northwest shelf are pulling platform supply vessels into ultra-deep water operation modes.
Market Restraints
- Specialized steel plate supply concentration:High-tensile hull-grade steel sourcing narrows to a handful of Northeast Asian mills, exposing newbuild programs to input cost volatility.
- Dynamic positioning operator certification scarcity:Australia's Maritime Safety Authority maintains stringent eligibility filters that constrain vessel deployment for Bass Strait campaigns.
- LNG bunkering infrastructure gaps:Sparse fueling networks across Southeast Asian logistics hubs limit dual-fuel vessel operational range.
Strategic Opportunities
- Philippines offshore wind pipeline:The archipelago's nascent wind farm development represents underpenetrated demand for turbine installation and maintenance support.
- Ammonia fuel pathway readiness:Early mover advantage accrues to operators positioning hull designs for ammonia dual-fuel retrofit compatibility.
- Modular mission package standardization:Swappable deck equipment configurations enable charterers to span contract durations from single-well intervention through multi-year field support.
Industry Challenges
- DP operator certification pipeline:Training capacity for dynamic positioning officers lags vessel delivery schedules across Australian and Japanese flag registries.
- Scope 3 reporting integration:Charterer emissions accounting requirements demand real-time fuel consumption telemetry that legacy fleet management systems cannot deliver.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Offshore Support Vessels Market |
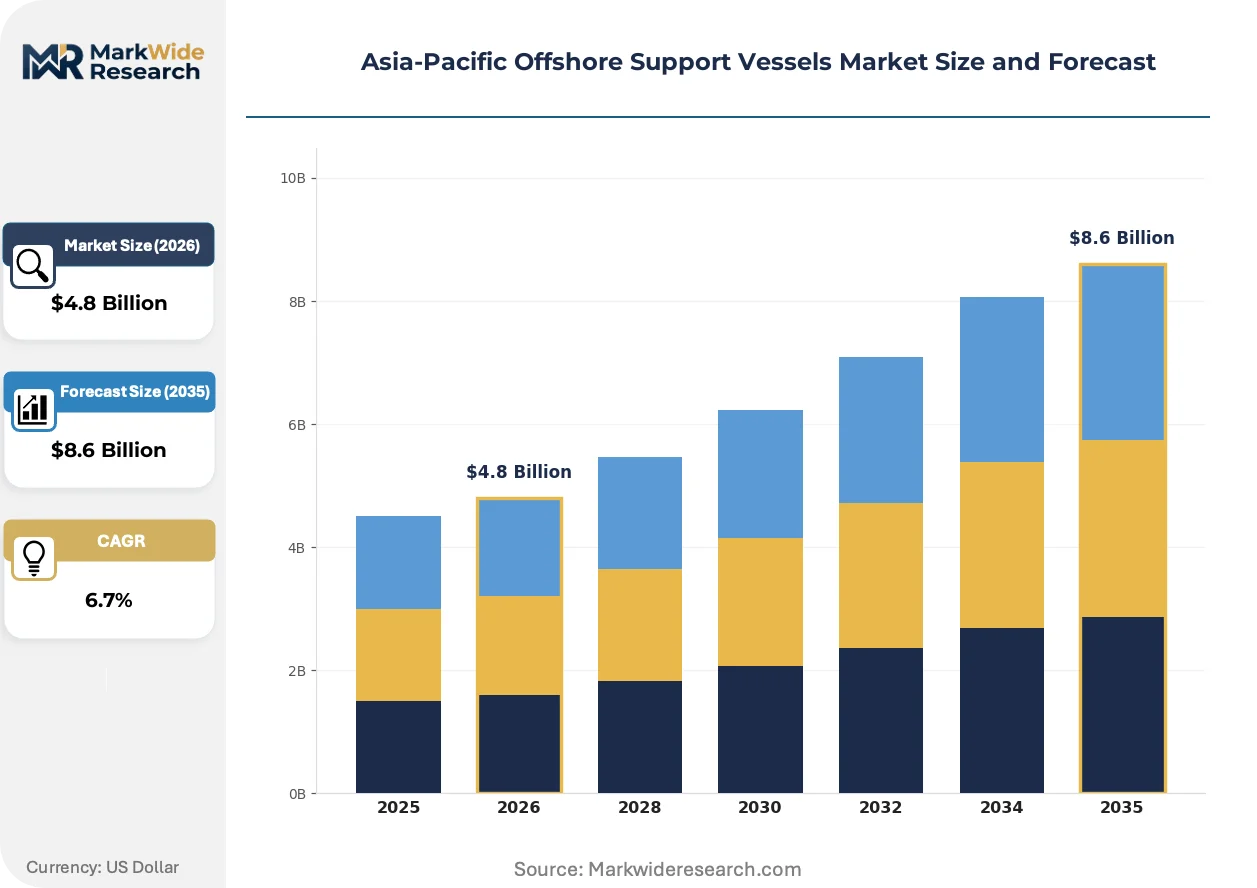
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: AHTS, PSV, OSV, DSV Operation Mode: Shallow Water, Deep Water, Ultra-Deep Water, Dynamic Positioning End User: Oil & Gas Companies, Renewable Energy, Government Agencies, Research Organizations Service Type: Logistics Support, Survey and Inspection, Emergency Response, Construction Support |
| Companies Covered | Solstad Offshore ASA, Damen Shipyards Group, Tidewater Inc., DOF ASA, Keppel Corporation, Seacor Marine Holdings Inc., Kawasaki Kisen Kaisha Ltd., Swire Pacific Offshore, PACC Offshore Services Holdings Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Offshore Support Vessels Market Strategic Shifts
Propulsion architecture decisions now lock in twenty-year operational economics as ammonia and methanol pathways mature alongside established LNG dual-fuel systems. Vessel designers must place bets on fuel chemistry before infrastructure clarity emerges.
Hybrid diesel-electric propulsion with battery peak shaving is overtaking conventional mechanical drivetrains in platform supply vessel newbuilds. Offshore wind developers in China and Australia specify this configuration for turbine installation support where station-keeping precision reduces weather downtime. The technology is compressing fuel consumption spreads between premium and standard vessel tiers.
Japan's METI coordinates with Nippon Kaiji Kyokai to align domestic construction subsidies with decarbonization benchmarks including LNG dual-fuel readiness. Shipyards in the Nagasaki and Kure clusters must certify hull designs against these standards to access public financing. Domestic operators face compressed renewal timelines as older tonnage loses subsidy eligibility.
Charterers now unbundle vessel provision from integrated marine services, contracting hulls on bareboat terms while retaining third-party crews and logistics management. Offshore wind construction consortia in Australia's Gippsland zone pioneered this model to optimize tax and liability structures. The shift fragments traditional integrated service providers and elevates specialized crew management firms.
Asia-Pacific Offshore Support Vessels Market Segmentation
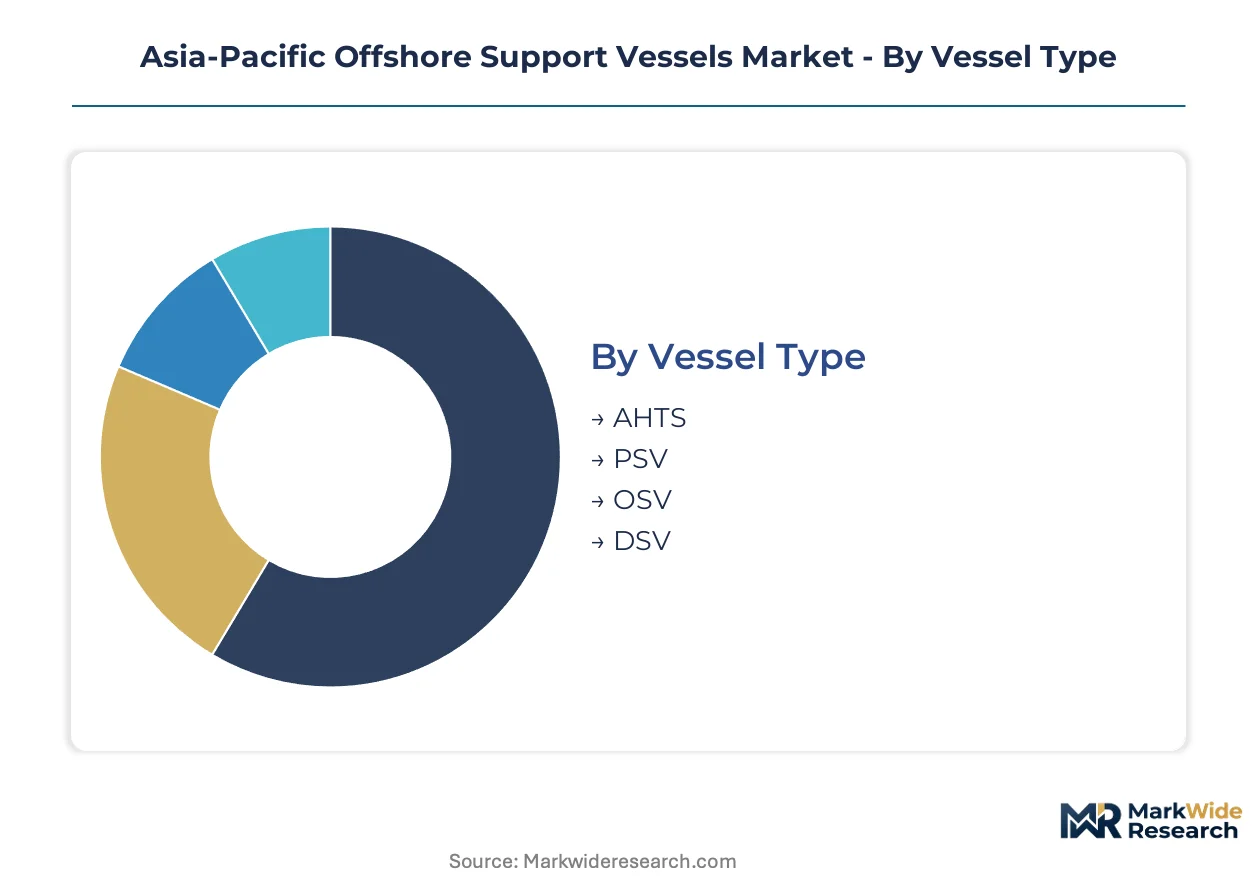
Vessel specialization in Asia-Pacific waters demands precise alignment between hull configuration and contract economics. Charterers segment fleets by water depth, mission duration, and regulatory exposure to optimize capital deployment across volatile energy markets.
Vessel Type:
Capital intensity peaks with dynamic positioning systems and specialized deck equipment, separating premium hulls from commodity tonnage.
- AHTS:Anchor handling tug supply vessels integrate winch systems rated above 400 tonnes bollard pull for mooring pre-lay and rig positioning. Australia's Bass Strait drilling campaigns absorb this fleet at sustained utilization, though China's Bohai Bay operators face compressed day rates from surplus regional tonnage.
- PSV:Platform supply vessels carry dry bulk, liquid mud, and methanol in segregated tank configurations. Offshore wind developers in Australia's Gippsland zone specify PSVs with hybrid propulsion for turbine component logistics, where station-keeping precision reduces weather downtime penalties.
- OSV:Multi-purpose offshore support vessels trade specification depth for chartering flexibility across contract durations.
- DSV:Dive support vessels command specialized saturation systems and hyperbaric chambers for subsea intervention work.
Most installed capacity flows through AHTS segments. Expansion is steepest in PSV configurations serving renewable energy logistics.
Operation Mode:
Water depth classification determines propulsion architecture, crew certification tiers, and insurance premia in stacked risk layers.
- Shallow Water:Conventional anchor-handling operations in depths below 500 feet utilize mechanical drivetrains without dynamic positioning redundancy. China's Pearl River Delta clusters concentrate this activity where state-backed majors maintain active drilling programs with lower specification hulls.
- Deep Water:Operations between 500 and 5,000 feet require DP-2 notation and dual-redundant power distribution. Myanmar's offshore concessions pull this fleet segment as exploration migrates from legacy shelf positions.
- Ultra-Deep Water:Australia's northwest shelf developments exceed 5,000 feet, demanding DP-3 systems with segregated machinery spaces and enhanced fire-fighting capacity.
- Dynamic Positioning:DP capability spans all depth tiers as a cross-cutting operational requirement rather than standalone classification.
Deep water operations absorb the majority of newbuild investment. Ultra-deep water configurations are gaining share fastest as frontier basins open.
End User:
Customer concentration varies by capital cycle timing, with renewable energy developers disrupting traditional oil and gas procurement patterns.
- Oil & Gas Companies:Integrated majors and national oil companies anchor term charter demand with three-to-five-year contracts. Japan's INPEX and Australia's Woodside Energy specify dual-fuel readiness in newbuild tenders to align with METI decarbonization benchmarks.
- Renewable Energy:Offshore wind farm developers in Australia and the Philippines drive spot market volatility during installation campaigns. Turbine installation support requires seasonal vessel stacking that conflicts with oil and gas drilling schedules.
- Government Agencies:Maritime safety and naval logistics operations generate stable but lower-margin demand.
- Research Organizations:Oceanographic survey missions utilize modified hulls with moonpool installations and A-frame deployments.
Oil and gas end users still command the largest contracted fleet. Renewable energy developers are expanding their share most aggressively.
Service Type:
Service unbundling is fragmenting integrated marine contractors, with charterers separating hull provision from crew management and logistics coordination.
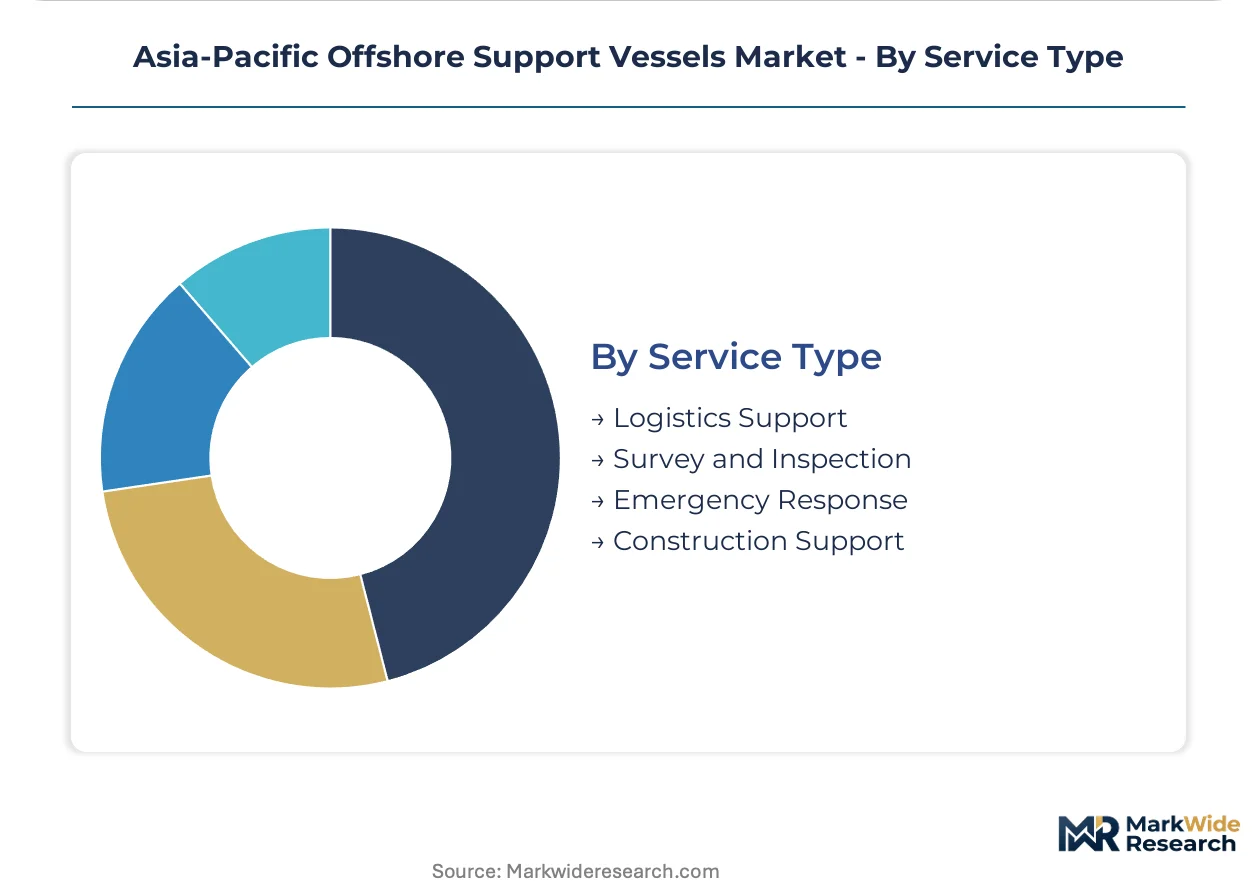
- Logistics Support:Personnel transport and supply chain coordination between shore bases and offshore installations. Australia's offshore wind construction consortia pioneered bareboat chartering models to optimize tax and liability structures while retaining third-party crew management.
- Construction Support:Heavy lift, cable lay, and foundation installation assistance. China's state-backed energy majors bundle this service with proprietary vessel fleets to control project timelines.
- Survey and Inspection:Subsea mapping, pipeline inspection, and structural integrity monitoring using ROV deployment systems.
- Emergency Response:Standby rescue and oil spill containment capabilities mandated by Australia's Maritime Safety Authority for Bass Strait operations.
Logistics support represents the largest service segment by vessel days. Construction support is climbing the fastest as offshore wind buildouts accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore support vessel operations in the Asia-Pacific trace their modern lineage to Singapore's emergence as a rig supply hub during the 1970s North Sea oil boom, with the city-state's shipyards later scaling fabrication capacity to serve Australia's Bass Strait and China's Bohai Bay developments.
China
State-backed energy majors in the Bohai Bay and Pearl River Delta clusters sustain the region's largest AHTS and PSV fleet deployment. The country's Ministry of Ecology and Environment mandates exhaust gas cleaning systems for vessels operating within twelve nautical miles of provincial coastlines. Dalian and Qingdao shipyards concentrate newbuild construction where dual-fuel LNG readiness has become a tender prerequisite.
Australia
Bass Strait drilling campaigns and Gippsland offshore wind installation absorb anchor handling tug supply vessels at sustained premium utilization. The Australian Maritime Safety Authority enforces stringent dynamic positioning operator certification that filters vessel eligibility for frontier basin work. Perth functions as the primary logistics coordination hub connecting northwest shelf ultra-deep water projects to Asian supply chains.
Japan
Domestic operators face compressed fleet renewal timelines as METI construction subsidies align with decarbonization benchmarks including LNG dual-fuel readiness. The updated Ship Safety Act tightens crew certification and environmental compliance standards for vessels serving INPEX and other integrated majors. Nagasaki and Kure shipyard clusters must certify hull designs against these standards to access public financing.
Singapore
The city-state's established port relationships anchor Southeast Asian logistics coordination for bareboat chartering models. Keppel Corporation dominates newbuild contracting with yard capacity extending from Singapore into Batam. The jurisdiction's regulatory framework supports vessel registration and crew management services that fragment traditional integrated marine contractors.
Myanmar
Offshore concession awards are pulling platform supply vessels into deep water and ultra-deep water operation modes as exploration migrates from legacy shelf positions. Sparse LNG bunkering infrastructure across adjacent Southeast Asian logistics hubs constrains dual-fuel vessel operational range. Yangon serves as the emerging coordination point for frontier basin campaigns.
Asia-Pacific Offshore Support Vessels Market Competitive Environment
Premium-margin players sit above commodity-margin players across vessel specification tiers, with dynamic positioning notation and dual-fuel readiness separating contract-winning hulls from surplus regional tonnage. The market structure concentrates around integrated fleet operators, specialized offshore wind logistics providers, and yard-affiliated vessel owners. Three archetypes dominate: North Sea-hardened fleet managers leveraging transferable operational systems, Southeast Asian port-network anchors controlling logistics access, and construction subsidy-dependent domestic Japanese operators. Competitive moves center on bareboat chartering model proliferation and ammonia fuel pathway positioning ahead of infrastructure clarity.
Within the integrated fleet management tier, Solstad Offshore ASA and Tidewater Inc. occupy positions shaped by transferable operational expertise from mature basins. Keppel Corporation anchors the yard-affiliated archetype with fabrication capacity extending across the Singapore-Batam corridor. These three entities exemplify how historical operational geography translates into Asia-Pacific contract access without requiring identical strategic postures.
| Leading Market Players |
|---|
| Solstad Offshore ASA |
| Damen Shipyards Group |
| Tidewater Inc. |
| DOF ASA |
| Keppel Corporation |
| Seacor Marine Holdings Inc. |
| Kawasaki Kisen Kaisha Ltd. |
| Swire Pacific Offshore |
| PACC Offshore Services Holdings Ltd. |
| Others |
Value Chain & Pricing Dynamics
DP-2 and DP-3 notation tiers separate premium hulls from commodity tonnage across Asia-Pacific charter markets, with this certification ladder manifesting in day rate spreads exceeding forty percent and procurement patterns that concentrate high-specification builds in Singapore-Batam corridor yards while surplus shallow-water capacity depresses pricing in China's Bohai Bay clusters.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs Asia-Pacific vessel charters, with DP-3 ultra-deep water hulls and LNG dual-fuel readiness commanding premium positioning against mechanical-drive shallow-water commodity tonnage. Price differentiation rests on dynamic positioning class notation and environmental compliance certification, with Australia's AMSA-mandated operator credentials filtering eligible vessels for Bass Strait work. Cost compression in shallow-water AHTS segments is intensifying because surplus regional tonnage from China's state-backed fleet expansion erodes day rate floors. Renewable energy developers exhibit highest price sensitivity during turbine installation campaigns, while oil majors accept premium rates for term charter certainty.
Supply Chain Analysis
Regional distribution centers in Singapore, Busan, and Yokohama anchor hub-and-spoke patterns for specialized marine equipment, with these nodes feeding fabrication yards across the Asia-Pacific basin. Geographic supply concentrates in South Korea, Japan, and China for high-tensile hull-grade steel plate, while Norway and the Netherlands anchor winch system and dynamic positioning component sourcing. Raw material dependencies include specialized steel alloys, marine-grade electronics, and LNG bunkering infrastructure components. Single-source vulnerability runs through Northeast Asian steel mill concentration for AH36 and DH36 grades. Distribution runs through Singapore-flagged vessel management hubs coordinating bareboat charter logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Asia-Pacific offshore support vessels hinges on fleet renewal timing that captures dual-fuel premium tiers before ammonia pathway clarity emerges, with early positioning against Japan's METI decarbonization benchmarks compressing competitor response windows.
For Market Incumbents: Hedge fleet obsolescence risk by accelerating ammonia-retrofit hull designs ahead of infrastructure clarity, while locking long-term bareboat charters with Australian offshore wind consortia to defend utilization against seasonal oil and gas drilling volatility. Backward integration into crew management capabilities counters the unbundling threat from specialized third-party operators. For New Entrants and Emerging Players: Enter via Philippines offshore wind logistics coordination, where nascent turbine installation demand and sparse established vessel relationships create white-space acquisition potential. Target modular mission package standardization as the most penetrable service layer, leveraging swappable deck equipment configurations to span contract durations without full fleet ownership overhead. For Investors and Strategic Acquirers: Asymmetric upside sits with yard-affiliated vessel owners controlling Singapore-Batam fabrication corridors, where capacity constraints and METI-aligned subsidy flows concentrate newbuild pricing power. Long-term viability favors operators with demonstrated DP-3 operational track records and established port relationships across Southeast Asian logistics hubs. Monitor ammonia bunkering infrastructure announcements in Japan and Australia as the critical inflection signal for fuel pathway commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Dual-Fuel Retrofit Readiness | Positions hull designs ahead of Japan's METI decarbonization benchmark evolution and emerging charterer Scope 3 requirements. |
| Bareboat Charter Model Expansion | Fragments traditional integrated marine contractors while elevating specialized crew management firms in Australia's Gippsland zone. |
| DP-3 Certification Investment | Unlocks Australia's northwest shelf ultra-deep water campaigns where AMSA filtering constrains eligible vessel supply. |
| Modular Mission Package Standardization | Enables charterers to span contract durations from single-well intervention through multi-year field support without hull switching. |
| Singapore-Batam Yard Capacity Lock | Secures newbuild slots against Keppel Corporation's dominant fabrication positioning for Asia-Pacific energy major tenders. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fleet managers at Solstad Offshore ASA and Tidewater Inc., chartering executives at INPEX and Woodside Energy, shipyard procurement leads at Keppel Corporation, and Australian Maritime Safety Authority certification officers with secondary validation through customs trade data, Lloyd's Register vessel databases, METI subsidy disclosure filings, and IEA offshore wind project tracking. Bottom-up vessel deployment tallies across Bohai Bay, Bass Strait, and Gippsland zones triangulated against top-down energy major capital expenditure disclosures.
Comparable-period anchoring linked historical utilization rates and day rate indices to forward projection assumptions across the analysis window, with segmentation modeling spanning vessel type, operation mode, end user, and service type dimensions. CAGRs derived from regression against offshore wind installation pipeline forecasts and oil and gas exploration licensing rounds, incorporating LNG dual-fuel penetration curves and ammonia pathway readiness indicators as industry-specific forecast inputs.
Inputs from Lloyd's Register and METI disclosure filings were available through the study window; gaps in real-time charter contract terms and undisclosed bareboat rate negotiations introduce uncertainty bands around utilization and pricing projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
Marine Asset Integrity Services Market
Marine
Boat Cleat Market
Marine
Marine Spreader Lights Market
Marine
Digital Nautical Charts Market
Marine
Europe Recreational Boating Market
Marine
Tele-Operated Marine Drone Market
Marine
Furnace Boats Market
Marine
Marine Propeller Market
Marine
GCC ROV Market
Marine
Steel Ship Plate Market
Marine
Fishing Vessel Market
Marine
Submarine Propulsion Systems Market
Marine
Sea Scooter Market
Marine
Marine Growth Removal Tool Market
Marine
Ballast Water Management Market