
 Europe Recreational Boating Market | 2026-2036
Europe Recreational Boating Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Recreational Boating Market Insights
Electric propulsion integration is narrowing the performance gap between conventional diesel systems and battery-hybrid alternatives across the sub-fifty-foot segment. Groupe Beneteau leverages its multi-brand architecture to cover entry-level through superyacht categories with distinct production footprints. Sunseeker International anchors its position in the performance motor yacht niche through deep customization capabilities at its Poole shipyard. Princess Yachts dominates the British flybridge segment with vertically controlled manufacturing from hull lamination to interior fit-out.
Europe recreational boating encompasses privately operated vessels designed for leisure navigation, typically spanning five to forty meters in length, constructed through resin-infusion or hand-layup fiberglass techniques with balsa-cored hull structures for stiffness-to-weight optimization. The sector serves discretionary consumers seeking marine-based recreation, coastal cruising, and competitive sailing. Motorboats lead volume shipments across Mediterranean markets where day-cruising culture prevails, while sailboats retain structural importance in Northern European waters where club racing traditions sustain demand. Yachts above twenty-four meters concentrate margin pools through bespoke commissioning cycles and extended after-sales service contracts. Fiberglass maintains manufacturing dominance due to mold-based economies of scale, though composites incorporating recycled content are gaining specification share among environmentally positioned builders.
The EU Green Deal and F-Gas Regulation constrain refrigerant choices in onboard climate systems while REACH compliance governs anti-fouling coating chemistries across member state waters. CE marking under the Recreational Craft Directive mandates exhaust emission thresholds and stability standards that shape product development pipelines for all manufacturers distributing within the single market. Stakeholders must monitor evolving battery safety certification protocols and shore-side charging infrastructure deployment timelines as electrification transitions from niche to mainstream specification across charter and private ownership channels.
Market Dynamics
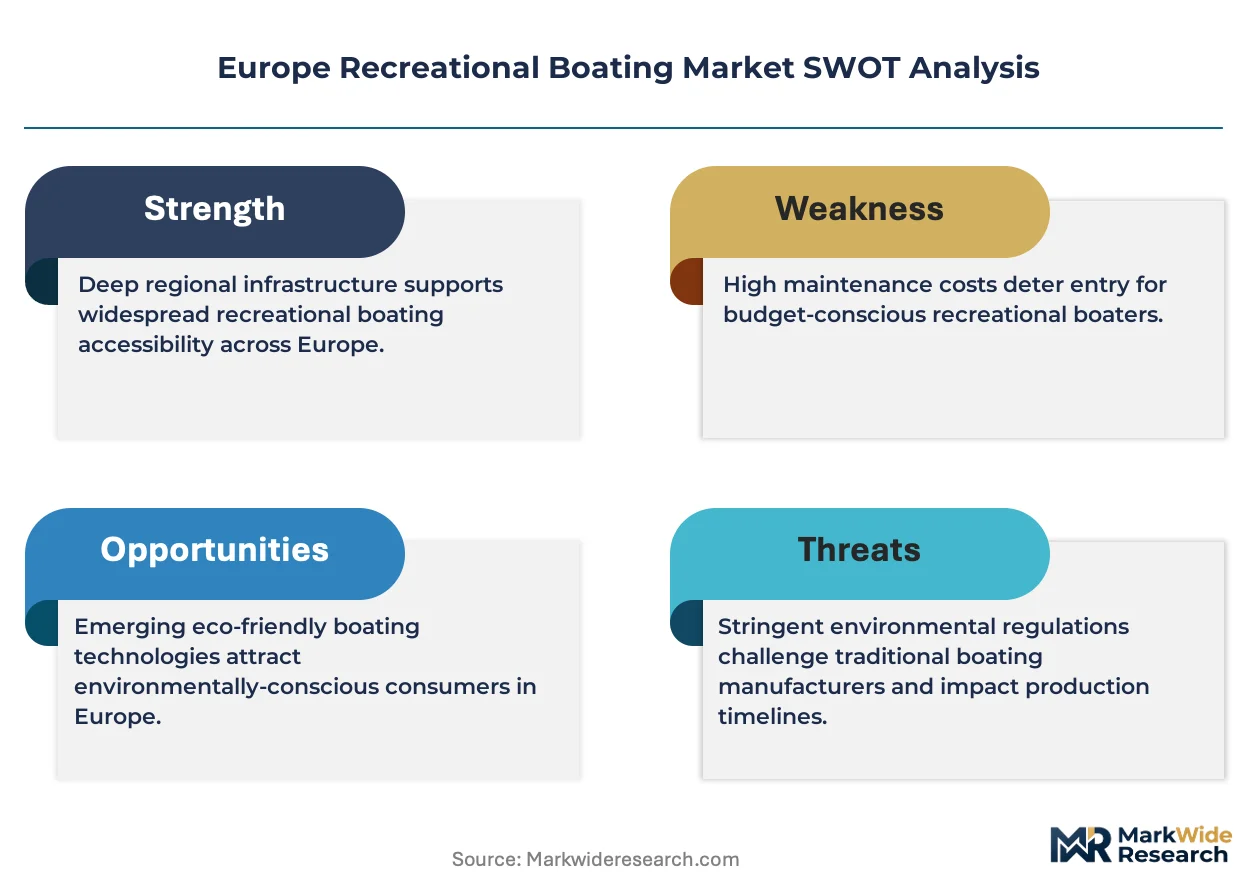
The EU Green Deal's decarbonization mandates are compressing product development cycles across European yards as builders retrofit diesel-dominant portfolios for electric-hybrid architectures. REACH compliance and F-Gas Regulation constraints now govern material selection and climate system design from hull lamination through commissioning.
Growth Catalysts
- EU Green Deal:Binding national decarbonization targets accelerate electric propulsion R&D subsidies and shore-side charging infrastructure deployment across Mediterranean charter networks.
- Marina infrastructure:French and Italian coastal municipalities are expanding berth capacity and deep-water access to accommodate larger motor yacht fleets.
- Resin-infusion automation:Computer-controlled lamination reduces volatile organic compound emissions while improving hull consistency for production builders.
Market Restraints
- Battery energy density:Lithium-ion pack weight limits cruising range for vessels above twelve meters, constraining electrification to day-boat segments.
- Carbon fiber supply:Prepreg availability concentrates among three European suppliers, exposing yards to input cost volatility and allocation rationing.
- REACH anti-fouling restrictions:Biocide-free coating alternatives require more frequent haul-out cycles, elevating lifetime operating costs for private owners.
Strategic Opportunities
- Eastern Adriatic coastlines:Croatian and Slovenian marina development lags Italian density, creating first-mover positioning for premium berth operators.
- Fractional ownership platforms:Digital booking systems are unbundling traditional charter models, lowering access barriers for occasional users.
- CE marking harmonization:Recreational Craft Directive standardization eases cross-border distribution for mid-size builders seeking German market entry.
Industry Challenges
- Composite lamination technicians:Skilled mold-makers and infusion specialists are retiring faster than vocational programs replenish supply.
- Battery safety certification:Evolving IEC standards for marine lithium systems delay type-approval timelines by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Recreational Boating Market |
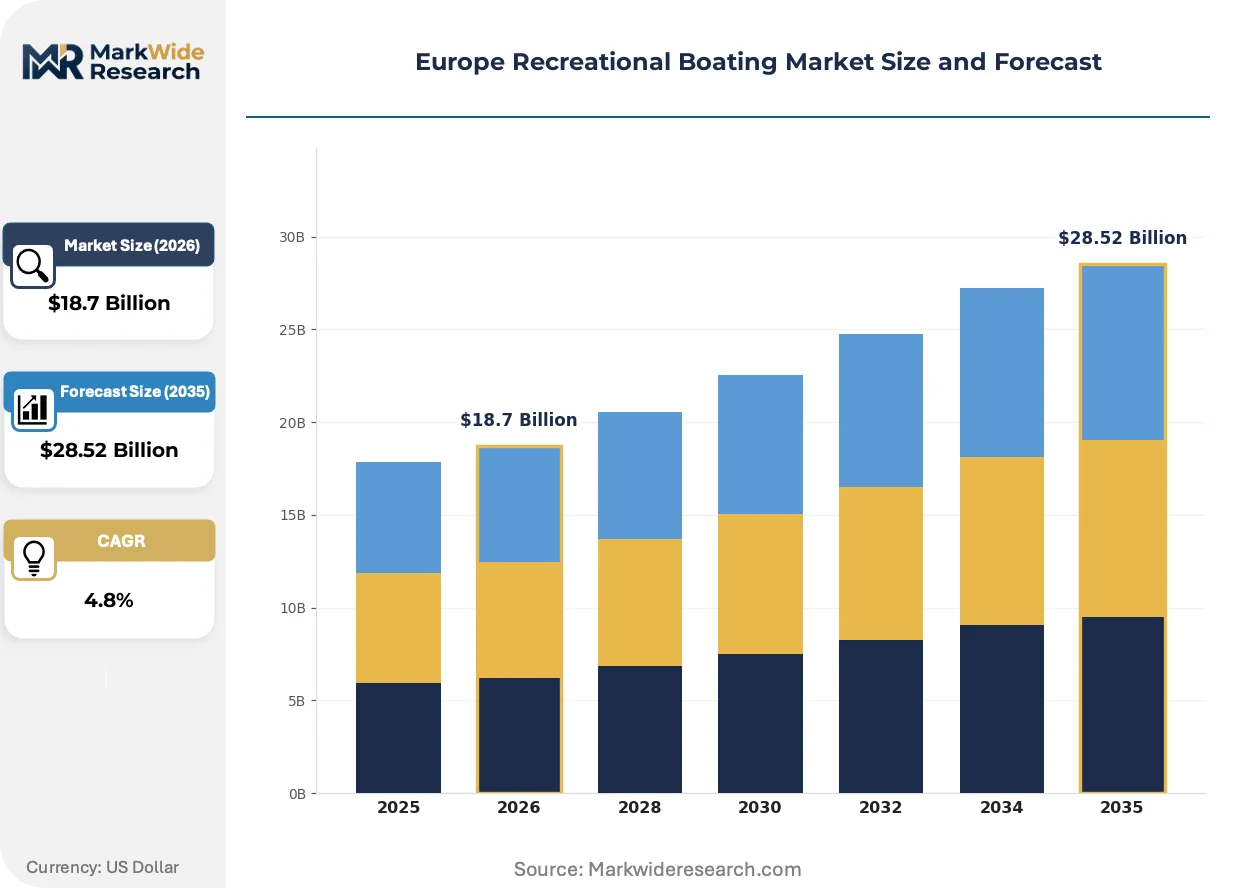
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Sailboats, Motorboats, Yachts, Personal Watercraft End User: Private Owners, Rental Operators, Tour Providers, Commercial Users Product Feature: Navigation Systems, Safety Equipment, Comfort Accessories, Entertainment Systems Material: Fiberglass, Aluminum, Wood, Composites |
| Companies Covered | Sunseeker International, Princess Yachts, Groupe Beneteau, HanseYachts AG, Lürssen, Ferretti Group, Sanlorenzo, Nimbus Group, Azimut-Benetti Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Recreational Boating Market Trends and Innovations
Electrification, sustainable materials substitution, and digitalized ownership models are restructuring how European yards design, build, and distribute recreational vessels. These shifts compress traditional specification cycles while opening new customer segments.
Hull construction is migrating from hand-layup fiberglass to vacuum-infused recycled-content composites. Northern European sailing yacht builders are adopting bio-based epoxy resins and flax fiber reinforcements to satisfy charter fleet sustainability procurement criteria. This materials transition is migrating from niche custom builders to mid-volume production lines as mold costs amortize across larger series.
F-Gas Regulation phase-down schedules are forcing refrigerant transitions in onboard HVAC systems. Hydrocarbon and CO2-based alternatives now dominate newbuild specifications, though retrofit compatibility constraints limit aftermarket penetration. Mediterranean motor yacht segments face the steepest compliance costs due to climate system scale and multi-zone complexity.
Ownership patterns among high-net-worth households are fragmenting toward shared-access models. Digital platforms now intermediate between vessel owners and occasional users, displacing traditional charter brokerage commissions. This behavioral shift concentrates in French and Italian coastal zones where berth scarcity elevates asset utilization premiums.
Europe Recreational Boating Market Segmentation
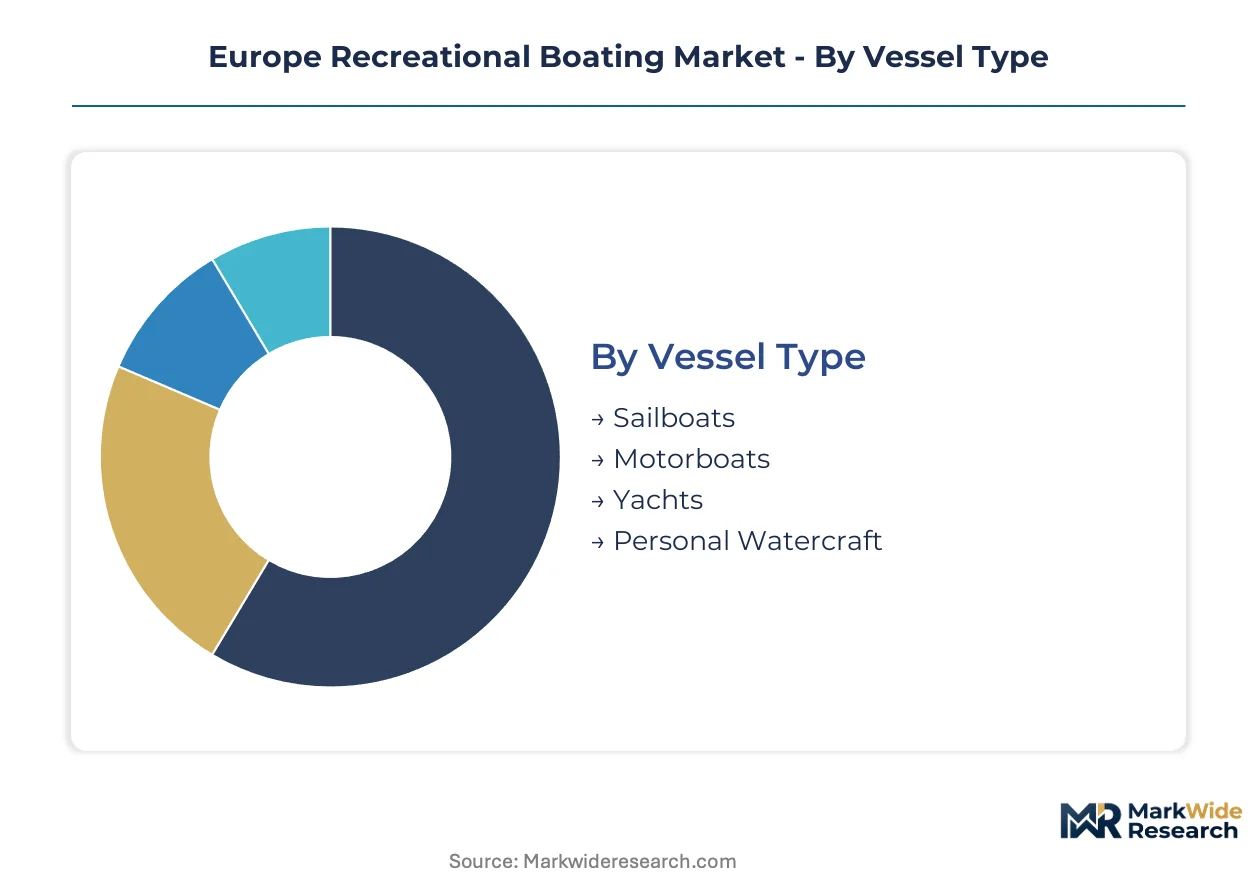
Vessel configuration and ownership models dictate radically different after-sales service intensities across the European recreational boating sector. Charter fleets demand continuous maintenance contracts while private owners concentrate spending on seasonal commissioning and refit cycles.
Vessel Type:
After-sales service intensity escalates dramatically with vessel complexity and operational duty cycles across European waters.
- Motorboats:Planing hull designs with sterndrive or outboard propulsion dominate Mediterranean day-cruising culture. French and Italian coastal municipalities expanding berth capacity drive fleet renewal among rental operators seeking fuel-efficient displacement hulls.
- Sailboats:Keel-stepped masts and rigging systems generate recurring inspection and replacement revenue for Northern European service yards. Club racing traditions in Germany and the Netherlands sustain demand for performance-oriented carbon mast specifications.
- Yachts:Bespoke commissioning cycles above twenty-four meters concentrate margin pools through extended warranty and crew training service contracts.
- Personal Watercraft:Compact jet-drive units serve beach rental concessions with rapid turnover and minimal technical support requirements.
Motorboats hold the largest share; momentum sits with yachts as superyacht berthing expands across Adriatic coastlines.
End User:
Procurement patterns diverge sharply between asset-heavy ownership and utilization-focused access models reshaping Mediterranean charter economics.
- Private Owners:Discretionary households in France, Italy, and Germany anchor premium vessel uptake through direct purchase or fractional equity structures. Marina infrastructure investment and high-net-worth household density support bespoke commissioning preferences.
- Rental Operators:Fleet managers prioritize standardized specifications enabling rapid turnaround and cross-vessel parts interchangeability. EU Green Deal subsidies for electric propulsion retrofitting accelerate capital replacement cycles across Croatian and Slovenian charter bases.
- Tour Providers:Coastal tourism operators expanding capacity across the Mediterranean require stable platform designs for passenger safety certification.
- Commercial Users:Fishing guide services and diving concessions select rugged aluminum hulls for professional durability in high-utilization regimes.
Private owners dominate absolute spending; rental operators are gaining share fastest as digital booking platforms consolidate fleet demand.
Product Feature:
Component lifecycle economics vary from capital-intensive navigation electronics to consumable safety inventory turnover.
- Navigation Systems:Multifunction displays integrating radar, AIS, and chart plotting command premium replacement cycles as cartography updates render older units obsolete.
- Safety Equipment:Inflatable liferaft servicing and EPIRB battery replacement generate mandatory recurring revenue for certified service stations.
- Comfort Accessories:F-Gas Regulation phase-down schedules force refrigerant transitions in climate systems, accelerating HVAC retrofit demand.
- Entertainment Systems:Audio-visual integration follows consumer electronics refresh rates, creating aftermarket upgrade opportunities for mid-life vessels.
Navigation systems capture the highest per-unit value; safety equipment delivers the most predictable recurring revenue streams.
Material:
Manufacturing cost structures and repair complexity differentiate hull material selection across production tiers.
- Fiberglass:Mold-based economies of scale sustain manufacturing dominance through resin-infusion automation reducing volatile organic compound emissions. REACH compliance governs gelcoat formulations across member state waters.
- Composites:Recycled-content laminates incorporating bio-based epoxy resins and flax fiber reinforcements gain specification share among environmentally positioned builders.
- Aluminum:Welded plate construction serves commercial and expedition yacht segments requiring impact resistance and polar code compliance.
- Wood:Cold-molded or traditional plank-on-frame techniques persist in heritage sailing yacht restoration and custom dayboat niches.
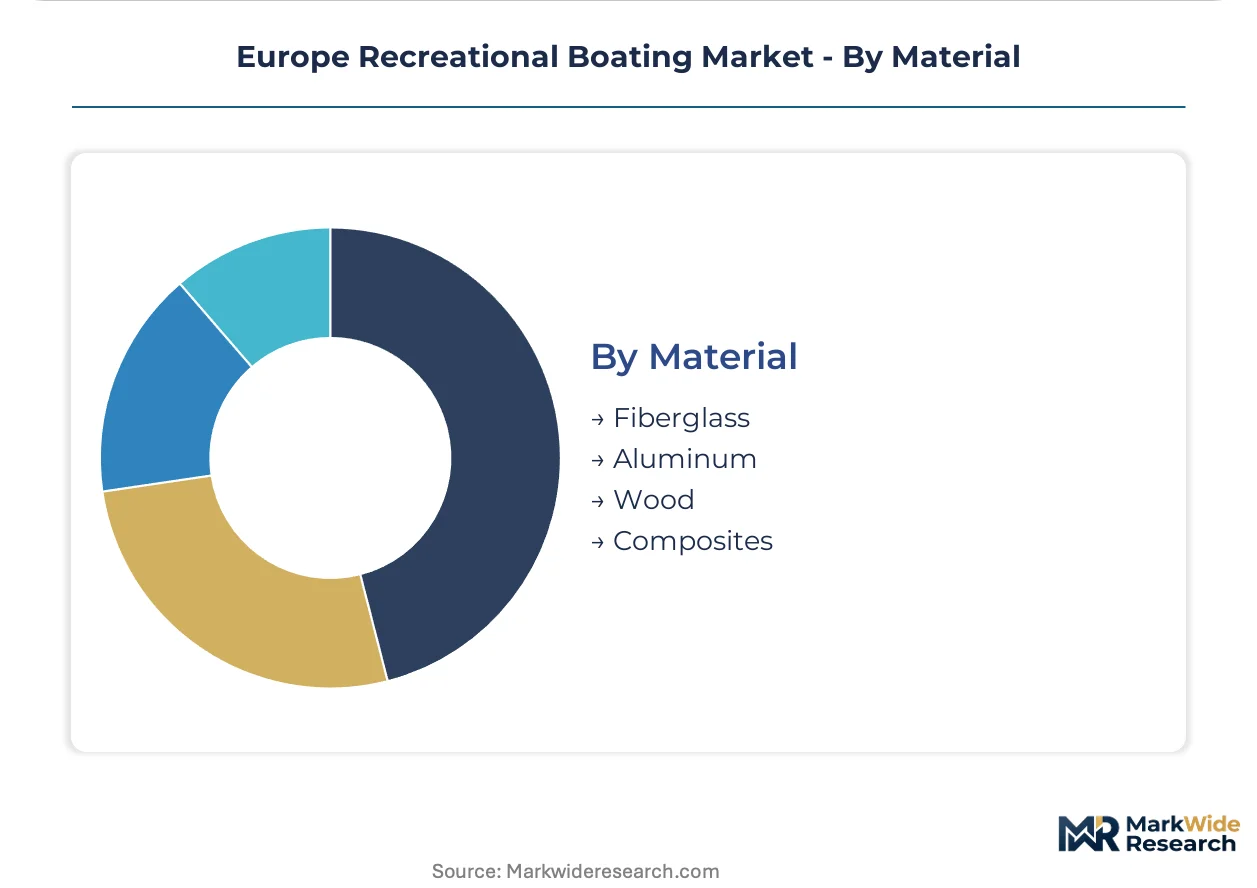
Fiberglass retains volume leadership; composites climb the fastest as charter fleet sustainability procurement criteria harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-net-worth households concentrate in coastal France, Italy, and Germany, driving premium vessel procurement through direct ownership and fractional equity structures. Marina infrastructure investment and EU Green Deal subsidy programs are accelerating fleet renewal across Mediterranean charter networks.
France
French coastal municipalities are expanding deep-water berth capacity along the Côte d'Azur to accommodate larger motor yacht fleets. The EU Green Deal's national decarbonization targets channel R&D subsidies toward electric propulsion development at yards clustered around La Rochelle and Vannes. Groupe Beneteau's multi-brand production footprint anchors manufacturing activity in the Pays de la Loire region.
Italy
Italian charter operators are retrofitting diesel-dominant fleets with battery-hybrid architectures to comply with tightening port emissions standards. REACH compliance governs anti-fouling coating specifications across Ligurian and Adriatic marinas, elevating biocide-free alternative adoption. The Ferretti Group and Azimut-Benetti Group concentrate superyacht commissioning activity between Viareggio and Savona.
Germany
German sailing yacht builders serve Northern European club racing demand through performance-oriented carbon mast specifications. The F-Gas Regulation constrains refrigerant choices in onboard climate systems, forcing HVAC transitions at yards in Bavaria and Lower Saxony. HanseYachts AG occupies a position within the mid-volume production segment centered on Greifswald.
United Kingdom
British flybridge motor yacht demand concentrates among discretionary households in the Southeast and Solent cruising grounds. CE marking under the Recreational Craft Directive harmonizes cross-border distribution standards, easing German and French market entry for Poole-based builders. Sunseeker International and Princess Yachts anchor performance and flybridge niche production along the Dorset coast.
Croatia
Croatian marina development lags Italian density, creating positioning opportunities for premium berth operators along the Eastern Adriatic. EU Green Deal subsidies for electric propulsion retrofitting accelerate capital replacement cycles at Split and Zadar charter bases. Nimbus Group exemplifies Scandinavian builders penetrating Adriatic markets through distributor partnerships.
Europe Recreational Boating Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around scale-driven production houses, bespoke commissioning yards, and mid-volume specialists with regional distribution footprints. Three archetypes dominate: multi-brand conglomerates covering entry-level through superyacht categories, vertically integrated British builders controlling manufacturing from lamination to fit-out, and Northern European sailing specialists serving club racing traditions. Competitive moves concentrate on portfolio diversification through brand acquisition and geographic expansion into underpenetrated Adriatic markets.
Among British flybridge and performance motor yacht fabricators, Sunseeker International, Princess Yachts, and Lürssen occupy positions spanning the sub-fifty-foot segment through superyacht commissioning. These entities exemplify archetypes ranging from deep-customization capabilities at single-shipyard operations to scale-driven production across multiple facilities. Groupe Beneteau and Ferretti Group represent multi-brand architectures that segment price-positioned offerings across distinct production footprints. Sanlorenzo anchors the bespoke commissioning tier where extended after-sales service contracts concentrate margin pools.
| Leading Market Players |
|---|
| Sunseeker International |
| Princess Yachts |
| Groupe Beneteau |
| HanseYachts AG |
| Lürssen |
| Ferretti Group |
| Sanlorenzo |
| Nimbus Group |
| Azimut-Benetti Group |
| Others |
Pricing and Supply Chain Analysis
Undercapacity at Croatian and Slovenian yards is compressing delivery timelines and elevating pricing power for Italian and French builders with available production slots. This utilization asymmetry rewards scale-driven manufacturers while forcing smaller yards toward cost-plus contracting with raw material indexation clauses.
Pricing Analysis
Cost-plus contracts with epoxy resin and carbon fiber prepreg indexation dominate bespoke commissioning above twenty-four meters. Three-tier pricing structure across premium, standard, and economy levels separates superyacht bespoke builds from semi-custom series production and entry-level fiberglass dayboats. Pricing pressure stems from lithium-ion battery pack cost volatility constraining electric-hybrid specification uptake. Rental operators in Mediterranean charter networks exhibit highest price sensitivity due to fleet standardization mandates, while private owners in the Côte d'Azur and Ligurian coast show lowest sensitivity to base vessel cost.
Supply Chain Analysis
Export-control regimes on advanced carbon fiber weaving technology limit prepreg flows from Germany, France, and the United Kingdom to non-EU yards. Hull lamination draws from Italian and French fiberglass mat suppliers, German epoxy resin formulators, and Spanish gelcoat producers. Single-source vulnerability concentrates in Toray Industries carbon fiber allocations for high-performance sailing yacht masts. Distribution runs through manufacturer-direct sales for superyacht commissioning and authorized dealer networks for production motorboats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across ownership models creates white-space opportunities as digital platforms disintermediate traditional charter brokerage. Electrification mandates and sustainable materials procurement criteria are spawning niche specialist positions.
For Market Incumbents: Harden after-sales service contract penetration to offset margin compression from electric propulsion R&D subsidies. Acquire distressed Croatian yards to secure Adriatic berth development rights. Consolidate mold-making technician training programs through vocational partnerships in Vannes and La Rochelle.
For New Entrants and Emerging Players: Mid-volume electric dayboat segments in German and Dutch club racing markets represent the most penetrable entry point. Target fractional ownership platform partnerships to bypass capital-intensive marina infrastructure requirements. Pursue bio-based epoxy resin certification to differentiate against incumbent fiberglass portfolios.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-hybrid propulsion integration. Five-to-ten-year viability favors vertically controlled British flybridge specialists with in-house lamination-through-fit-out capabilities. Monitor shore-side charging infrastructure deployment timelines across Mediterranean charter networks as electrification adoption inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Electric Propulsion R&D Partnership | EU Green Deal subsidies accelerate battery-hybrid architecture development at La Rochelle yards. |
| Adriatic Marina Infrastructure Expansion | Croatian berth development lags Italian density, creating first-mover positioning for premium operators. |
| Resin-Infusion Automation Investment | Computer-controlled lamination reduces volatile organic compound emissions while improving hull consistency. |
| Fractional Ownership Platform Launch | Digital booking systems unbundle traditional charter models, lowering access barriers for occasional users. |
| Bio-Based Composite Certification | Flax fiber and bio-epoxy specifications satisfy charter fleet sustainability procurement criteria in Northern Europe. |
Research Methodology
A spread of perspectives from production yard operations directors, marina infrastructure planners, charter fleet procurement managers, and marine battery system engineers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through CE marking certification databases, EU Green Deal subsidy disbursement records, and F-Gas Regulation compliance filings. Customs data on carbon fiber prepreg imports and recreational vessel registration statistics anchored bottom-up demand estimation against top-down macroeconomic consumption models.
Demand-supply balance dynamics across vessel type, propulsion architecture, and ownership model dimensions structured the analytical framework. Segmentation modeling incorporated hull material specifications, charter versus private utilization patterns, and regional regulatory cluster variations. CAGRs were derived from production capacity utilization trajectories and replacement cycle analysis. Forecast inputs included lithium-ion battery energy density improvement curves and shore-side charging infrastructure deployment schedules.
Practitioners should monitor REACH anti-fouling coating amendment timelines and IEC marine battery safety standard revision cycles for early signals. Forecasts reflect assumptions on EU Green Deal subsidy continuity and carbon fiber supply allocation stability. Material shifts in F-Gas Regulation phase-down schedules or Adriatic marina permitting velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Exhaust Systems Market
Marine
US Fish Finders Market
Marine
Global Foldable Inflatable Boats Market
Marine
Marine Propeller Market
Marine
Marine Suspension Seat Bases Market
Marine
Global Submarine Market
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Yacht Shell Doors Market
Marine
Ballast Water Management Market
Marine
Hydrogen Ships Market
Marine
Fishing Vessel Market
Marine
Integrated Bridge System for Ships Market
Marine
Marine Chronometers Market
Marine
Buoys and Beacon Market
Marine
Hydraulic Marine Cranes Market
Marine
Global Maritime Information Market