
 Shipbuilding Market | 2026-2036
Shipbuilding Market Size, Share, and Industry Trends Forecast 2026-2036
Shipbuilding Market Intelligence
The rising order book for complex vessels like LNG carriers and passenger ships is shifting the value concentration away from simpler bulk carriers. South Korean firms including Hanwha Ocean and Samsung Heavy Industries specialize in these high-value, technologically advanced vessels. In contrast, China State Shipbuilding Corporation (CSSC) dominates the high-volume segments, including tankers and container ships. Fincantieri sustains a strong position in the passenger ship segment, particularly for cruise liners.
Shipbuilding encompasses the design, construction, and outfitting of marine vessels for commercial, military, or specialized purposes. The process involves fabricating large hull sections from high-tensile steel, joining them through advanced welding techniques, and integrating complex propulsion and navigation systems. Within propulsion technology, hybrid systems and electric drives designed for shorter routes represent the fastest-growing categories. While steel remains the dominant construction material by tonnage, the use of composite materials is expanding in smaller, specialized naval and passenger vessels.
The International Maritime Organization's Energy Efficiency Existing Ship Index (EEXI) and Carbon Intensity Indicator (CII) are primary regulatory forces. Concurrently, classification societies such as DNV and Lloyd's Register enforce structural and safety standards that are essential for market access and insurance. Shipbuilders' strategic decisions must now balance the long-term investment in alternative fuel capabilities against near-term demand for conventional vessel designs.
Market Dynamics
The global shipbuilding industry is fundamentally shaped by regulatory pressure for decarbonization. Mandates from the International Maritime Organization and regional bodies like the European Union are compelling a transition toward vessels powered by alternative fuels, influencing newbuild orders and technology investment.
Growth Catalysts
- Offshore Energy Expansion:Demand from the offshore wind industry for specialized Wind Turbine Installation Vessels (WTIVs) and Service Operation Vessels (SOVs) is creating a high-value newbuild segment.
- Regulatory Mandates:The EU's Fit for 55 package and the IMO's 2030 and 2050 emissions targets are accelerating orders for ships capable of running on LNG, methanol, and ammonia.
- Fleet Renewal Cycles:An aging global fleet of bulk carriers and tankers necessitates replacement, creating a baseline of demand, with new orders specifying higher efficiency and lower emissions.
Market Restraints
- Input Cost Volatility:Fluctuations in the price of high-tensile steel, which constitutes a significant portion of a vessel's cost, create uncertainty in project bidding and can erode shipyard margins.
- Infrastructure Gaps:The limited availability of global bunkering infrastructure for new alternative fuels like green methanol or hydrogen deters shipowners from placing orders for single-fuel newbuilds.
- Yard Capacity Concentration:The consolidation of complex shipbuilding capabilities, particularly for LNG carriers, within a few large shipyards in South Korea and China creates production bottlenecks and limits buyer negotiation leverage.
Strategic Opportunities
- Autonomous Vessel Technology:The development of autonomous and remote-controlled vessels for maritime surveillance, hydrographic surveys, and short-sea cargo routes opens a new technological frontier for specialized shipbuilders.
- Floating Infrastructure:Emerging demand for non-traditional maritime assets, including floating nuclear power plants and large-scale carbon capture and storage (CCS) vessels, presents a significant opportunity.
- Arctic Shipping Routes:As polar ice recedes, the need for ice-class vessels, including LNG carriers and container ships designed for Arctic transit, creates a niche but high-value market segment.
Industry Challenges
- Skilled Labor Shortages:A persistent lack of certified welders and naval architects with expertise in dual-fuel propulsion systems and cryogenic containment for fuels like hydrogen constrains production capacity.
- High Capital Requirements:Upgrading and expanding drydock facilities to accommodate the construction of ultra-large container ships and Q-Max LNG carriers requires substantial capital investment, limiting market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shipbuilding Market |
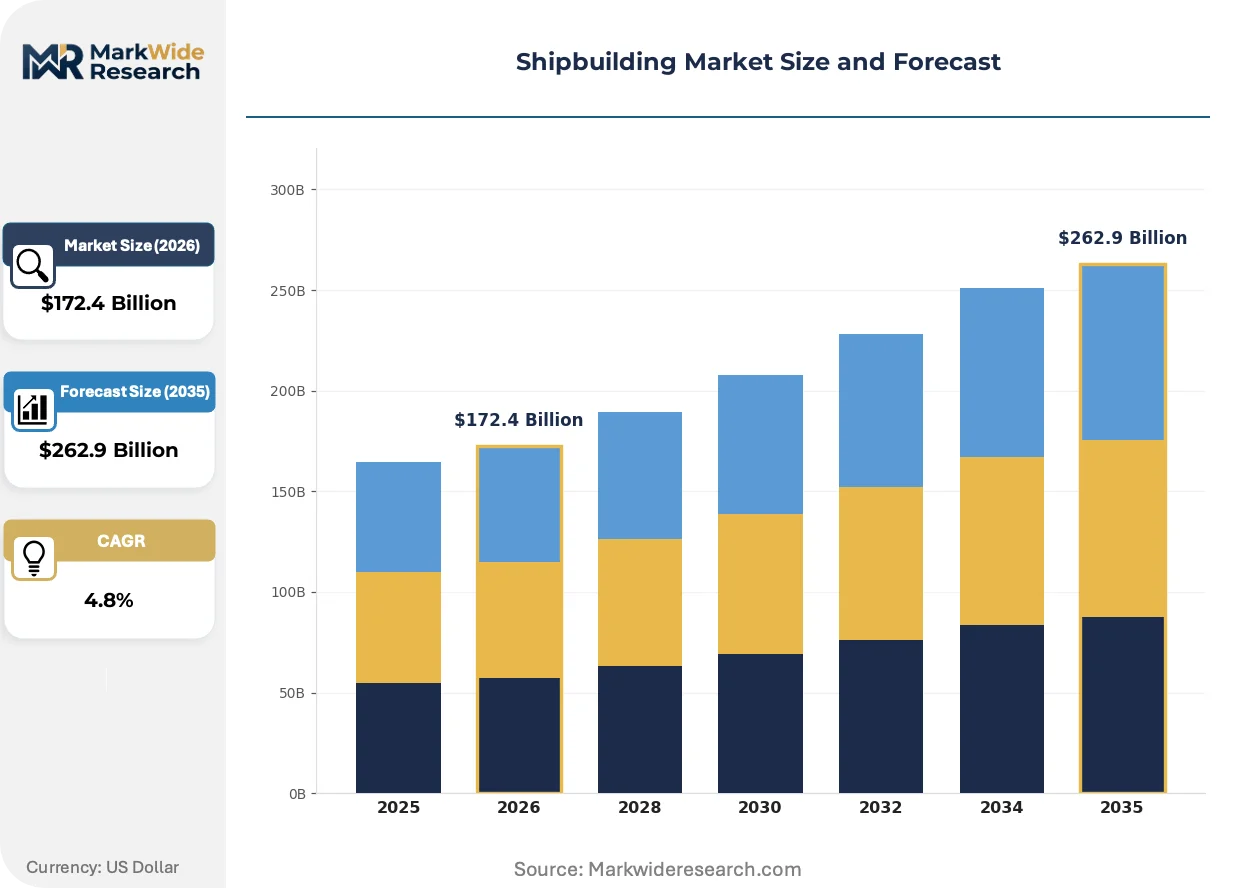
| Market Size in 2026 | $172.4 Billion |
| Market Size in 2035 | $262.9 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Container Ships, Bulk Carriers, Tankers, Passenger Ships, Offshore Vessels, Naval Ships Propulsion Technology: Diesel Engines, Gas Turbines, Electric Drives, Nuclear Propulsion, Hybrid Systems Construction Material: Steel, Aluminum, Composite Materials, High-Tensile Alloys Customer Type: Shipyards, Government Agencies, Private Fleet Owners, Offshore Contractors |
| Companies Covered | Hanwha Ocean, Imabari Shipbuilding, China State Shipbuilding Corporation (CSSC), Kawasaki Heavy Industries, Mitsubishi Heavy Industries, HD Hyundai Heavy Industries, Yangzijiang Shipbuilding, Fincantieri, Samsung Heavy Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shipbuilding Market Strategic Shifts & Innovations
Technological advancements are centered on improving vessel efficiency and enabling the use of zero-carbon fuels. Digitalization is transforming ship design and operation, while new materials offer pathways to lighter and more durable hull structures for specialized applications.
Digital twin technology provides a virtual, real-time replica of a physical vessel and its integrated systems. Fleet operators and naval forces are adopting this for predictive maintenance, performance simulation, and crew training. This innovation is unifying the design, construction, and operational phases of a ship's life into a cohesive, data-driven management process, reducing lifecycle costs.
The International Maritime Organization's Energy Efficiency Existing Ship Index (EEXI) and Carbon Intensity Indicator (CII) are primary regulatory drivers. These rules mandate technical and operational improvements to reduce the carbon footprint of the existing global fleet. The tanker and bulker segments are most affected, prompting widespread investment in retrofitting energy-saving devices and optimizing voyage planning.
A notable shift in contracting models involves the increasing use of long-term charter agreements tied to specific fuel efficiency and emissions performance metrics. This model is gaining traction over traditional spot market contracts, particularly for high-value newbuilds like LNG carriers and large container ships. This trend is most prominent among European and Asian shipping lines seeking to de-risk their investment in expensive, green-fueled vessels.
Shipbuilding Market Segmentation
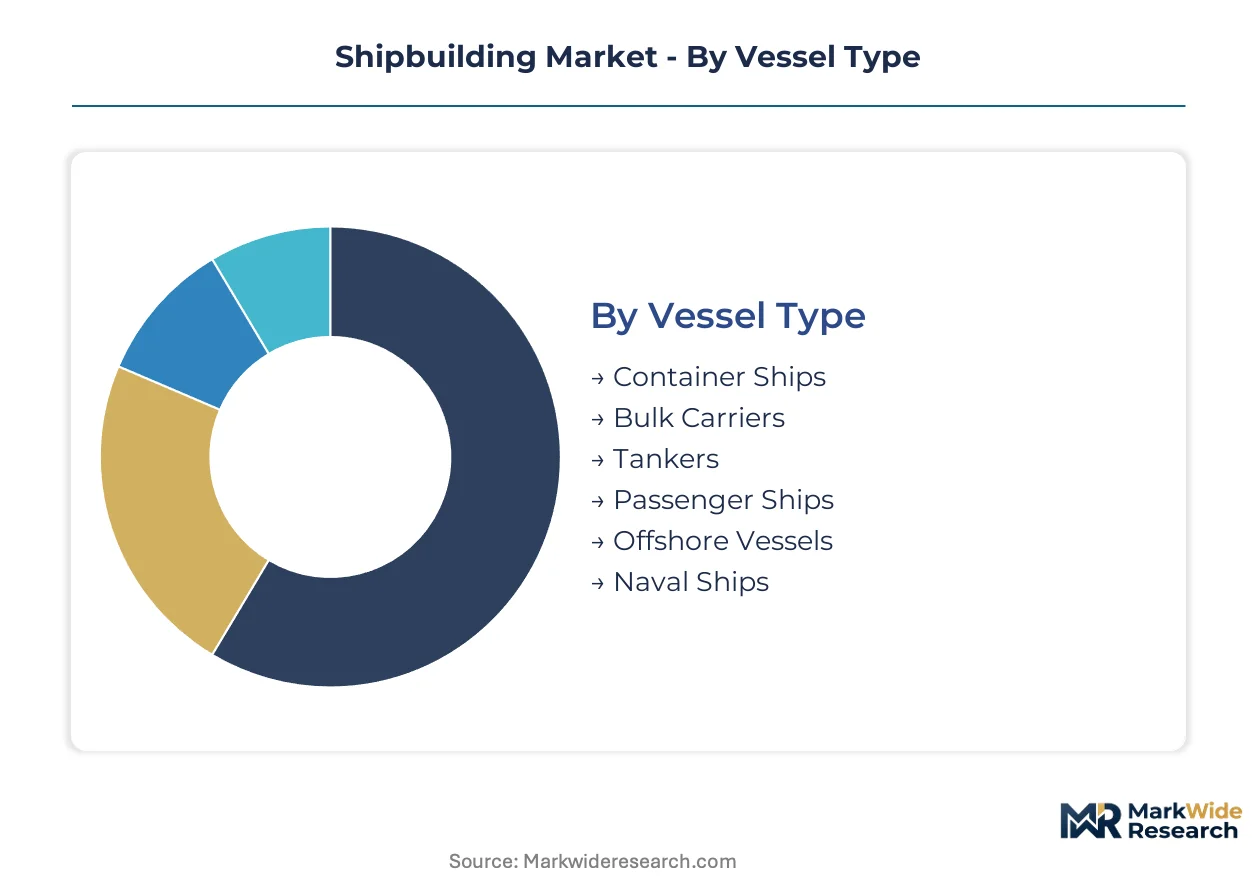
Shipbuilding market segmentation highlights diverse capital investments and specialized engineering required across different vessel types and operational needs. Understanding these distinctions reveals where technological innovation and regulatory pressures exert most influence on new orders. This analysis identifies key growth areas within the global industry.
Vessel Type:
The capital intensity of shipbuilding varies significantly across vessel types, with complex, high-value vessels demanding greater upfront investment in design and specialized construction.
- Passenger Ships:These vessels include cruise liners and ferries, designed for carrying large numbers of people with extensive onboard amenities and complex safety systems. Demand concentrates in Europe and Asia for luxury cruise newbuilds, driven by tourism rebound and lower-emission needs.
- Offshore Vessels:This category encompasses specialized ships like Wind Turbine Installation Vessels (WTIVs) and Service Operation Vessels (SOVs), essential for the burgeoning offshore wind sector. Demand concentrates in the North Sea and East Asia as countries expand renewable energy infrastructure.
- Container Ships:Large cargo vessels transporting standardized containers across global trade routes, primarily for Asian and European shipping lines.
- Bulk Carriers:Single-deck ships designed to transport unpackaged dry bulk commodities like grain, ore, and coal, serving global raw materials trade.
- Tankers:Vessels constructed for carrying liquid cargoes such as crude oil, petroleum products, chemicals, and LNG, crucial for global supply chains.
- Naval Ships:Military vessels including frigates, submarines, and aircraft carriers, built to stringent defense specifications for national security.
Most installed capacity flows through Bulk Carriers. Expansion is steepest in Offshore Vessels.
Propulsion Technology:
Propulsion technology segmentation highlights critical performance characteristics and environmental compliance drivers influencing vessel design and operational efficiency.
- Hybrid Systems:These systems combine internal combustion engines with electric motors and batteries, optimizing fuel consumption and reducing emissions. Demand accelerates in offshore support vessels and ferries, driven by emissions regulations and operational flexibility.
- Electric Drives:Electric propulsion systems use motors powered by batteries or generators, offering precise control, lower noise, and zero-emission capabilities for shorter voyages. Demand concentrates in harbor tugs, short-sea ferries, and specialized research vessels, supported by port electrification.
- Diesel Engines:Traditional internal combustion engines powering most commercial vessels, known for reliability and established bunkering infrastructure.
- Gas Turbines:High-power, compact engines primarily used in naval vessels and high-speed passenger craft.
- Nuclear Propulsion:Utilizes nuclear reactors for propulsion, exclusively employed in large naval vessels like aircraft carriers and submarines for extended endurance.
The dominant solution remains Diesel Engines. New investment prioritizes Hybrid Systems.
Construction Material:
The choice of construction material dictates a vessel's structural integrity, weight, and fabrication complexity, with supply concentration impacting material availability and cost.
- Steel:High-tensile steel remains the primary structural material for most commercial and naval vessels due to its strength, durability, and cost-effectiveness. Its demand is universal, driven by the need for robust hull sections.
- Composite Materials:These advanced materials, including fiberglass and carbon fiber reinforced polymers, offer high strength-to-weight ratios and design flexibility, reducing vessel weight. Their use expands in smaller naval vessels and specialized passenger craft.
- Aluminum:Lightweight and corrosion-resistant, aluminum is favored for high-speed craft, smaller passenger vessels, and superstructures.
- High-Tensile Alloys:Specialized steel alloys providing superior strength and toughness, used in critical structural areas of large vessels.
While Steel accounts for the bulk of volume, Composite Materials are gaining traction for their specialized advantages.
Customer Type:
Customer type segmentation reveals distinct procurement patterns and decision-making processes, reflecting varied operational requirements and long-term strategic objectives for vessel acquisition.
- Private Fleet Owners:This segment includes independent shipping companies, charter operators, and logistics firms that commission vessels for commercial cargo or passenger services. Their procurement decisions are influenced by market demand, freight rates, and regulatory compliance.
- Government Agencies:National defense ministries, coast guards, and scientific research institutions constitute this segment, procuring naval ships, patrol vessels, and specialized research platforms. Their purchasing is driven by strategic national interests and defense budgets.
- Shipyards:While primarily builders, shipyards can act as customers for specialized components, sub-assemblies, or vessel designs from other specialized yards.
- Offshore Contractors:Companies specializing in offshore oil & gas exploration, wind farm development, or subsea cable laying, requiring highly specialized support vessels.
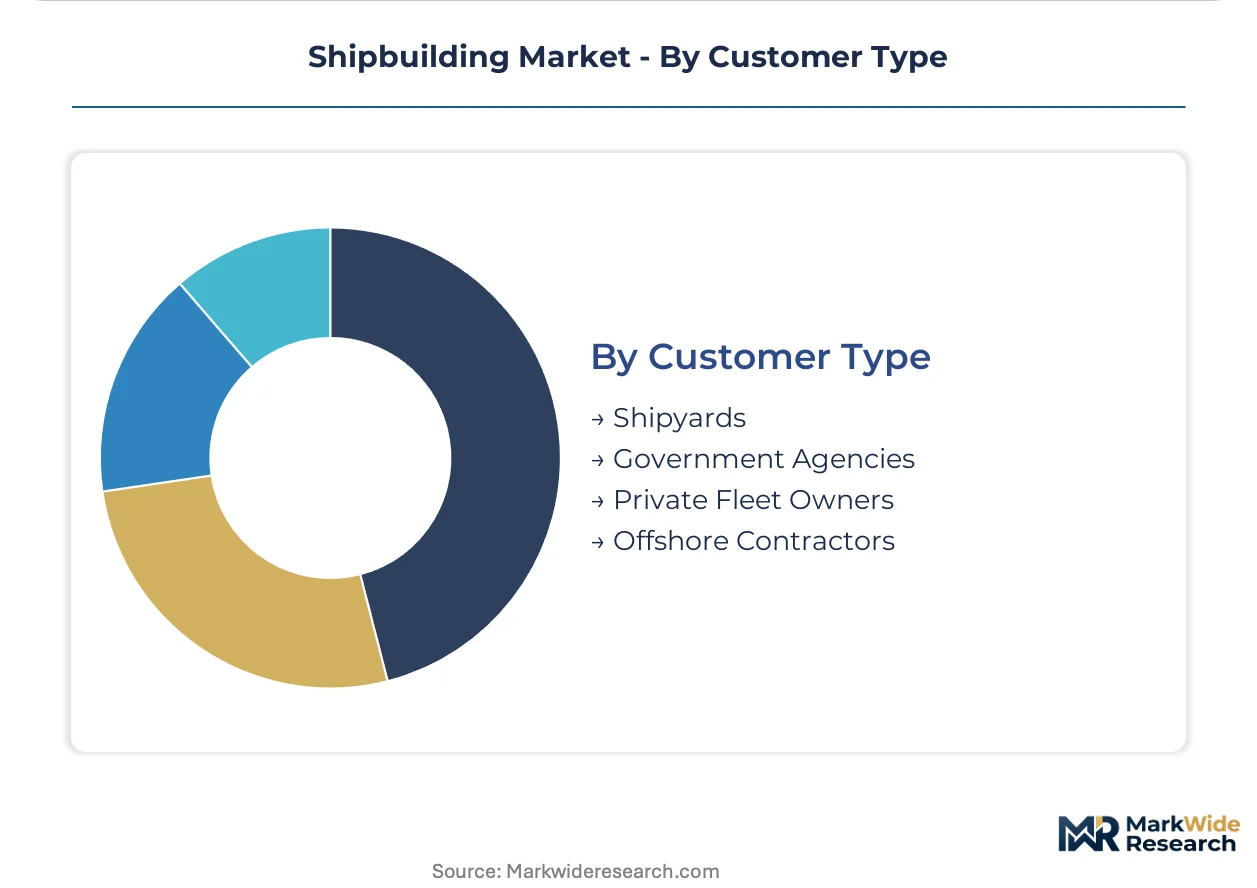
The largest volume of orders originates from Private Fleet Owners. The highest value contracts often reside with Government Agencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence across global regions significantly influences shipbuilding activity. Stricter environmental regulations in some areas drive demand for advanced, cleaner vessels, while other regions with less stringent oversight or lower labor costs attract conventional newbuild orders. Decarbonization mandates, particularly from the EU, create a regulatory arbitrage that shapes where new vessel construction occurs.
South Korea
Demand for high-value LNG carriers, advanced passenger ships, and complex naval vessels drives the South Korean market. National policies support extensive research and development in eco-friendly propulsion systems. The Busan and Ulsan regions host major shipyards like Hanwha Ocean and HD Hyundai Heavy Industries, specializing in technologically advanced newbuilds.
China
China's shipbuilding industry focuses on high-volume tankers, container ships, and bulk carriers, alongside growing offshore wind support vessels. The Ministry of Ecology and Environment's (MEE) dual carbon goals drive investment in green shipbuilding technologies. Shanghai and Dalian are key shipbuilding hubs, with China State Shipbuilding Corporation (CSSC) dominating diverse vessel types.
Germany
Germany concentrates on specialized naval vessels, high-tech research ships, and luxury yachts, including components for cruise ships. The EU's Fit for 55 package accelerates demand for low-emission designs and advanced vessel engineering. Rostock and Papenburg maintain specialized yards, focusing on advanced engineering and the high-value passenger vessel segments.
United States
The United States shipbuilding sector primarily serves military vessels, specialized research ships, and Jones Act-compliant domestic cargo vessels. Environmental Protection Agency (EPA) regulations influence domestic vessel emissions and design requirements. Pascagoula, Mississippi, and Newport News, Virginia, are critical for naval shipbuilding and repair activities.
Japan
Japanese shipbuilders focus on bulk carriers, car carriers, and increasingly, more efficient and environmentally compliant vessels. The Ministry of Economy, Trade and Industry (METI) promotes research and development into zero-emission fuels and autonomous shipping. Imabari and Nagasaki feature prominent shipyards, emphasizing technological innovation and quality construction.
Shipbuilding Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the shipbuilding market. The industry exhibits a tiered structure, with a few large players dominating high-volume and high-value segments. Global conglomerates, specialized builders, and regional players form the primary strategic archetypes. Technology licensing and strategic partnerships drive innovation, while capacity expansion addresses demand surges.
At the scale-driven end, China State Shipbuilding Corporation (CSSC) represents a state-owned enterprise with extensive capacity across diverse vessel types. Hanwha Ocean, a South Korean firm, exemplifies a specialist in high-value, technologically advanced vessels such as LNG carriers. Fincantieri, an Italian shipbuilding group, occupies a strong position in the passenger ship segment, particularly for cruise liners.
| Leading Market Players |
|---|
| Hanwha Ocean |
| Imabari Shipbuilding |
| China State Shipbuilding Corporation (CSSC) |
| Kawasaki Heavy Industries |
| Mitsubishi Heavy Industries |
| HD Hyundai Heavy Industries |
| Yangzijiang Shipbuilding |
| Fincantieri |
| Samsung Heavy Industries |
| Others |
Cost & Logistics Intelligence
The bifurcation between high-value, complex vessel construction and high-volume, standard vessel construction profoundly shapes pricing power and supply chain configurations. Specialized shipyards command premium pricing for technologically advanced newbuilds, while bulk orders face intense cost competition driven by scale-focused Asian yards.
Pricing Analysis
Direct-to-owner contracts dominate the shipbuilding market, reflecting the project-based nature of vessel construction. Pricing is largely determined by technological complexity, specific regulatory compliance requirements like IMO EEXI, and the level of customization requested. Pricing pressure stems from input cost volatility, particularly for high-tensile steel, and limited yard capacity for specialized vessels. Private fleet owners commissioning bulk carriers exhibit higher price sensitivity compared to government agencies procuring naval ships.
Supply Chain Analysis
Skilled labor shortages in key manufacturing geographies like South Korea and China represent a significant supply chain constraint. Supply concentration for most vessel types centers in South Korea, China, and Japan. Raw material dependencies include high-tensile steel and specialized propulsion components for alternative fuel systems. Single-source vulnerability for advanced cryogenic containment systems creates a structural risk. Distribution typically involves direct shipyard-to-owner delivery upon vessel completion.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shipbuilding market functions as a geographic-arbitrage play, where lower labor costs in some Asian nations contrast with stringent regulatory demands in European shipbuilding hubs. This divergence influences where different vessel types are constructed.
For Market Incumbents: Acquire specialized engineering firms focused on alternative fuel integration to enhance in-house R&D capabilities. Invest in upgrading drydock facilities to accommodate larger and more complex vessels, securing long-term contracts for high-tensile steel to mitigate input cost volatility. This strategy helps counter margin pressure from emerging alternative propulsion technologies.
For New Entrants and Emerging Players: Online design platforms and modular construction techniques offer a viable entry point. Target niche segments such as specialized research vessels or autonomous short-sea cargo routes, where smaller scale and rapid prototyping can differentiate offerings. Focus on developing innovative propulsion solutions for specific operational profiles, leveraging advanced composite materials for lighter structures.
For Investors and Strategic Acquirers: Consolidation pressure builds where capital requirements for new drydock facilities are substantial. Long-term viability remains strong for shipyards specializing in high-value, green-fueled vessels, driven by decarbonization mandates. Identify niche builders with expertise in composite materials or hybrid propulsion systems as prime acquisition targets. A key signal to watch is the increasing order book for floating infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Dual-Fuel Propulsion R&D | Ensures compliance with evolving emissions regulations and captures demand for eco-friendly vessels. |
| Expand Drydock Capacity for VLCCs | Addresses bottlenecks for ultra-large container ships and Q-Max LNG carriers, capturing high-value orders. |
| Secure Long-Term Steel Supply Contracts | Mitigates input cost volatility, stabilizing project bidding and protecting shipyard margins. |
| Develop Autonomous Vessel Prototypes | Positions firms for a new technological frontier in maritime surveillance and specialized cargo. |
| Form Strategic Partnerships for Bunkering | Overcomes infrastructure gaps for alternative fuels, de-risking newbuild investments for shipowners. |
Research Approach
Coverage spans East Asia, Europe, and North America, with primary inputs from each region. The analysis combines in-depth interviews with naval architects, shipyard executives, procurement managers, and classification society representatives. Secondary validation draws from IMO reports, national maritime authority publications, industry association data, and company financial statements, triangulating bottom-up and top-down insights.
The model details segmentation across vessel type, propulsion technology, construction material, and customer type, with an additional focus on operating region. Analytical frameworks integrate historical data with forward-looking projections over the projection horizon. CAGRs were derived through regression analysis and expert consensus, incorporating global trade volume projections and offshore wind investment forecasts.
The model assumes a particular technology adoption path; alternative pathways for ammonia or hydrogen propulsion would alter the outlook. Forecasts reflect assumptions regarding geopolitical stability and raw material price trends. Material deviation in rapid infrastructure buildout for new fuels warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Integrated All-Electric Propulsion System for Ships Market
Marine
Pneumatic Marine Fender Market
Marine
Global Submarine Market
Marine
Marine Diesel Engine Market
Marine
Europe Recreational Boating Market
Marine
Marine Base Steering Gear Market
Marine
Steel Ship Plate Market
Marine
Marine Interiors Market
Marine
Autonomous Ships Market
Marine
Hydrofoil Market
Marine
Marine Suspension Seat Bases Market
Marine
Deep-V Boat Market
Marine
Marine Fender Systems Market
Marine
Electric Outboard Engines Market
Marine
Marine VFD Market
Marine
Boat Steering Systems Market