
 India Automotive Pneumatic Actuators Market | 2026-2036
India Automotive Pneumatic Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
India Automotive Pneumatic Actuators Market Foresight
Buyer concentration among India's commercial vehicle OEMs is recalibrating procurement priorities toward localized pneumatic actuator sourcing. Continental AG leverages its Pune manufacturing base to supply double-acting actuators directly to domestic truck and bus assemblers. Robert Bosch GmbH sustains technology leadership through integrated valve-cylinder combinations tailored for engine control modules. Nucon Industries Pvt. Ltd. anchors its position as a cost-competitive indigenous supplier serving Tier-1 distributors across Tamil Nadu and Gujarat.
Automotive pneumatic actuators convert compressed air into linear or rotary mechanical motion through piston-driven cylinder assemblies, typically operating at 0.4–0.8 MPa working pressure to automate clutch engagement, gear shifting, and braking functions in commercial vehicles. Double-acting technology dominates volume shipments due to its bidirectional force output and reliability in heavy-duty engine control applications, while rotary variants capture premium positioning in power steering modules where angular positioning precision commands higher margins. Brake system applications attract the fastest growth trajectory as air-over-hydraulic configurations expand across medium and heavy commercial vehicle platforms.
BIS certification mandates under Automotive Industry Standard AIS-037 govern pneumatic component durability testing, while CMVR safety regulations enforce fail-safe actuator performance in brake and steering circuits. India's PLI scheme for automobile and auto component manufacturing incentivizes domestic capacity expansion for valve and cylinder producers meeting localization thresholds. Stakeholders must monitor proposed amendments to AIS-145 for electromagnetic compatibility as electrified pneumatic architectures enter prototype phases.
Market Dynamics
Commercial vehicle fleet operators in Maharashtra and Tamil Nadu are recalibrating procurement toward localized pneumatic actuator sourcing as BIS certification mandates under AIS-037 compress supplier qualification timelines and reshape vendor selection criteria across brake and suspension automation programs.
Growth Catalysts
- CMVR Safety Mandates:Tightening brake circuit fail-safe requirements under India's Central Motor Vehicles Rules are accelerating OEM demand for certified double-acting actuators in heavy commercial vehicle platforms.
- PLI Scheme Incentives:India's production-linked incentive scheme for auto component manufacturing rewards domestic valve and cylinder producers meeting localization thresholds, drawing fresh capacity investment toward Pune and Chennai manufacturing corridors.
- Air-over-Hydraulic Configurations:Medium and heavy commercial vehicle assemblers are expanding pneumatic brake system deployments as fleet operators prioritize maintenance simplicity and roadside serviceability over fully hydraulic alternatives.
Market Restraints
- Aluminum Alloy Input Volatility:Cylinder body manufacturing depends on primary aluminum price swings that compress margin predictability for domestic fabricators lacking long-term smelter contracts.
- Import Dependency for Precision Seals:Fluorocarbon elastomer seal supply concentrates among Japanese and German specialty chemical producers, exposing Indian actuator assemblers to currency and freight cost fluctuations.
- Electromechanical Substitution:Electric actuators are capturing gear-shifting applications in premium bus platforms where electronic control modules enable programmable shift mapping unavailable from pneumatic systems.
Strategic Opportunities
- Gujarat Automotive Corridor Expansion:Sanand and Halol manufacturing zones are attracting Tier-1 actuator distributors as commercial vehicle OEMs diversify supply origins beyond Maharashtra-Tamil Nadu concentration.
- Electrified Pneumatic Architectures:Prototype brake-by-wire systems integrating pneumatic backup circuits with electronic control units open development contracts for valve producers capable of electromagnetic compatibility certification.
- Aftermarket Channel Digitization:Fleet maintenance aggregators are creating direct procurement pathways for replacement actuators, disintermediating traditional distributor networks in long-haul trucking segments.
Industry Challenges
- AIS-145 Electromagnetic Compatibility Timeline:Proposed amendments to India's automotive electromagnetic standards are forcing pneumatic valve producers into costly testing protocol revisions without confirmed implementation dates.
- Multi-Species Inventory Complexity:OEM demand fragmentation across single-acting, double-acting, and rotary actuator variants strains working capital for mid-scale fabricators serving multiple truck and bus platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Automotive Pneumatic Actuators Market |
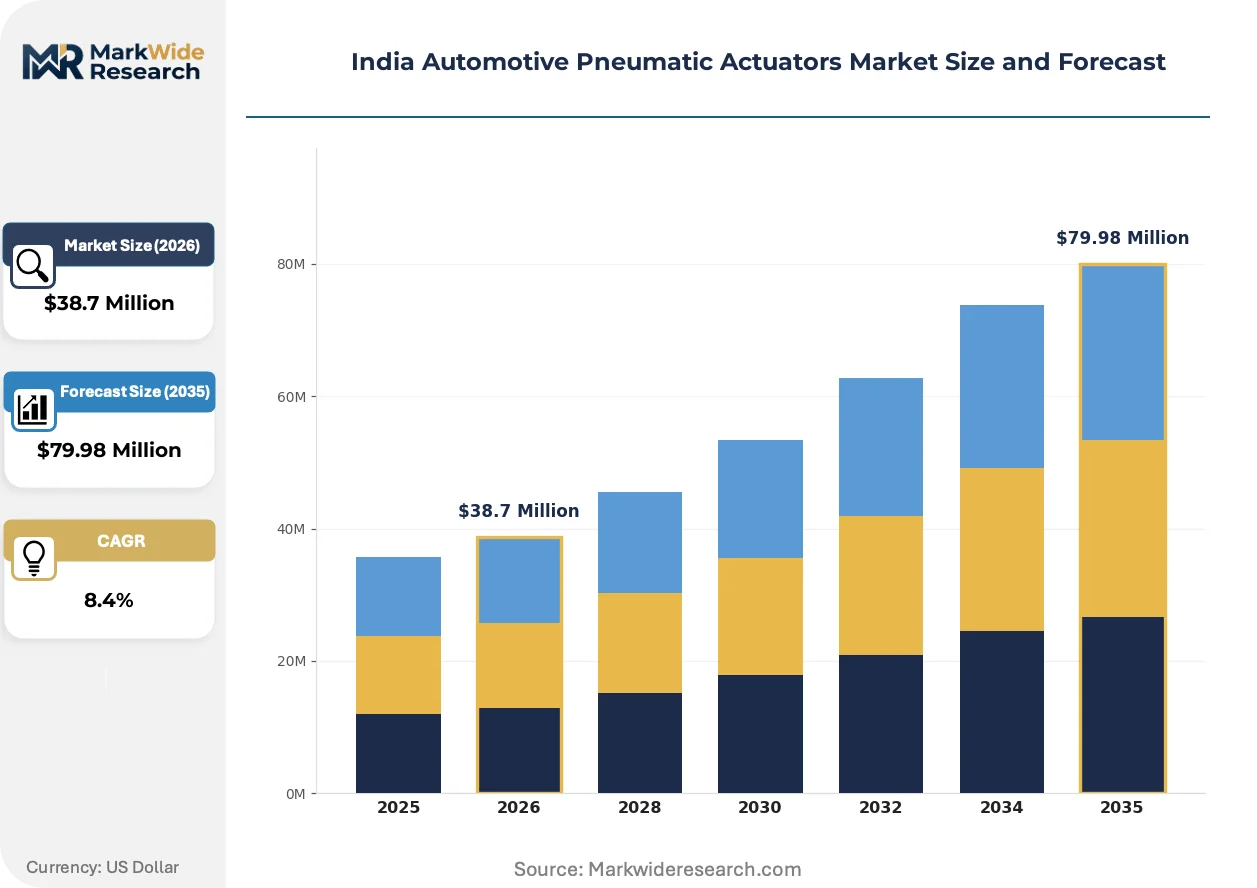
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Single-acting, Double-acting, Rodless, Rotary Application: Engine Control, Suspension Systems, Brake Systems, Power Steering End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Component: Valves, Cylinders, Regulators, Filters |
| Companies Covered | Denso Corporation, CTS Corporation, Continental AG, Nucon Industries Pvt. Ltd., Delphi Automotive PLC, Robert Bosch GmbH, Mitsubishi Electric Corporation, Hitachi, Ltd., ZF Friedrichshafen AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Automotive Pneumatic Actuators Market Shifts & Advancements
Technology convergence between electronic control modules and pneumatic actuation hardware is restructuring supplier capability requirements and procurement specifications across India's commercial vehicle manufacturing corridors.
Integrated valve-cylinder combinations are consolidating discrete pneumatic components into pre-tested subassemblies that reduce OEM assembly line complexity. Tier-1 suppliers serving engine control module manufacturers are adopting these compact units at accelerating rates. This consolidation is modularizing supplier tiers and compressing qualification timelines for new component entrants.
BIS certification protocols under AIS-037 are mandating accelerated durability testing cycles for pneumatic brake and steering circuit components. The Automotive Research Association of India is expanding test facility capacity to address application backlogs. Heavy commercial vehicle platforms face the tightest compliance deadlines as CMVR enforcement intensifies for air brake system reliability.
Fleet operators are unbundling actuator replacement decisions from OEM service contracts and sourcing directly through authorized distributor networks. Long-haul trucking companies operating across the Golden Quadrilateral corridor are driving this disintermediation. Tamil Nadu-based fleet aggregators are pioneering consolidated procurement platforms that aggregate volume across multiple operators for price leverage.
India Automotive Pneumatic Actuators Market Segmentation
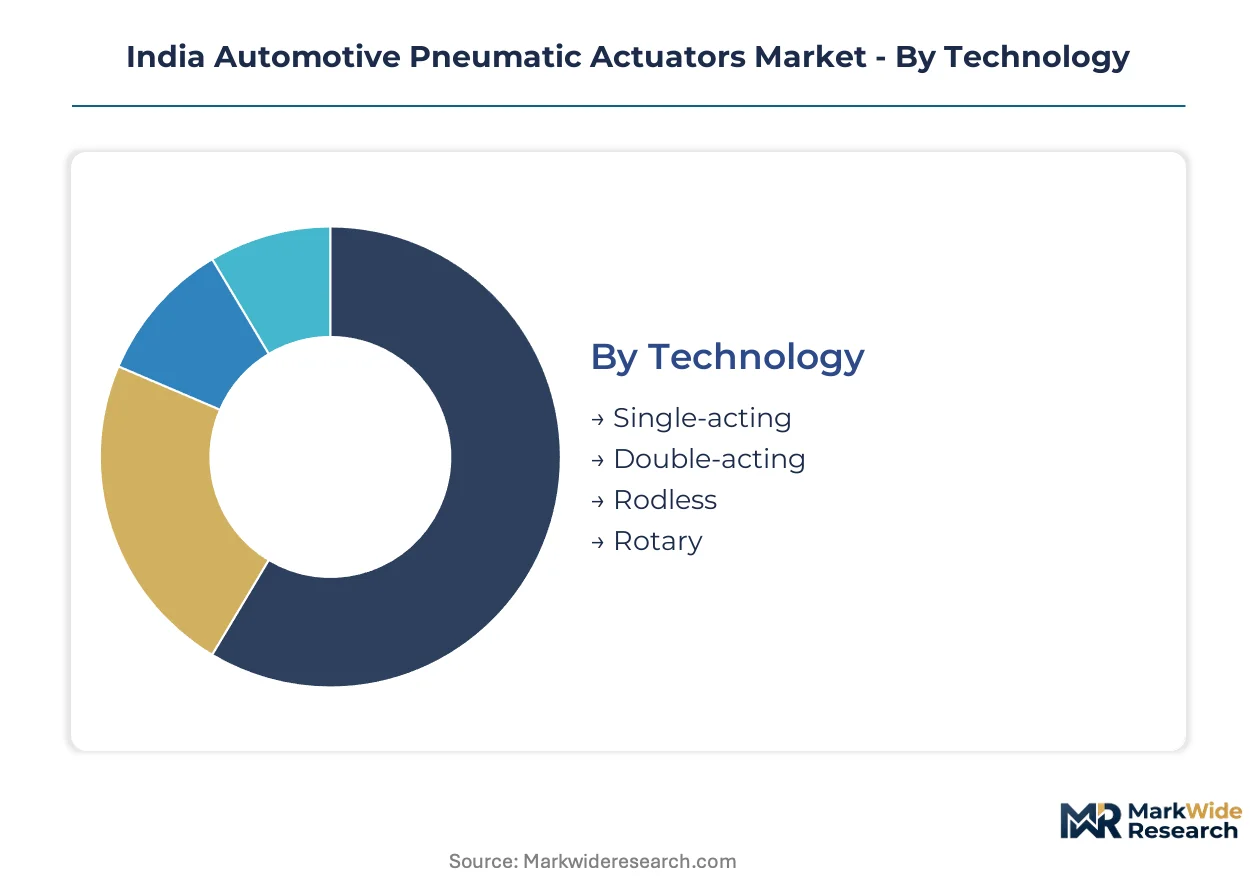
Pneumatic actuator procurement in India fragments across four structural dimensions. Technology and application segments command strategic attention from component suppliers navigating BIS certification mandates and CMVR compliance timelines.
Technology:
Supply concentration among double-acting and rotary variants shapes Tier-1 procurement negotiations with Pune and Chennai manufacturing clusters.
- Single-acting:Spring-return mechanisms deliver unidirectional force output for clutch automation in light commercial vehicles. Demand concentrates in Gujarat's Sanand belt where small-fleet operators prioritize cost minimization over bidirectional control precision.
- Double-acting:Compressed air drives piston motion in both directions, enabling precise force modulation for heavy-duty engine control modules. Maharashtra's truck and bus assemblers specify these actuators for brake and transmission automation, drawn by reliability under 0.4–0.8 MPa operating pressure.
- Rodless:Magnetically coupled or cable-driven designs eliminate piston rod protrusion, suiting space-constrained power steering installations. Tamil Nadu bus manufacturers trial these for articulated steering linkages.
- Rotary:Vane or rack-and-pinion configurations convert linear pressure into angular motion for steering column positioning. Premium bus platforms in Karnataka specify rotary variants where angular precision commands supplier qualification priority.
Today's leader: Double-acting. Tomorrow's challenger: Rotary.
Application:
Cost tier differentiation separates brake system investments from suspension automation programs across OEM budget allocations.
- Engine Control:Throttle and fuel injection modulation demands rapid response actuators with integrated position sensors. Double-acting cylinders dominate this segment as engine management system suppliers consolidate valve-cylinder combinations.
- Suspension Systems:Air spring leveling and ride height adjustment require sustained holding pressure without leakage. Fleet operators in Rajasthan's mining corridors specify these for load-adaptive heavy trucks.
- Brake Systems:Air-over-hydraulic configurations expand across medium and heavy commercial vehicle platforms. This application attracts the steepest expansion trajectory as CMVR enforcement intensifies for fail-safe circuit reliability.
- Power Steering:Rotary actuators assist steering rack positioning in premium bus chassis. Karnataka and Tamil Nadu assemblers source these for intercity coach platforms where electronic control modules enable programmable assist curves.
Current procurement priority: Brake Systems. Emerging specification focus: Power Steering.
End User:
Volume concentration among OEMs and Tier-1 suppliers determines production planning rhythms for cylinder and valve fabricators.
- OEMs:Tata Motors, Ashok Leyland, and Mahindra Truck and Bus specify certified actuators directly for in-house assembly. These customers enforce BIS compliance documentation and accelerated durability testing under AIS-037.
- Aftermarket Providers:Authorized distributors and fleet maintenance aggregators source replacement actuators for Golden Quadrilateral corridor operators. Channel digitization is disintermediating traditional distributor networks in long-haul segments.
- Vehicle Assemblers:Contract manufacturers and CKD assembly units procure pneumatic components for localized truck and bus production. Gujarat's Halol zone attracts these assemblers diversifying beyond Maharashtra-Tamil Nadu concentration.
- Tier-1 Suppliers:Bosch, Continental, and indigenous specialists like Nucon Industries integrate actuators into brake and engine control subassemblies. These suppliers qualify component vendors against OEM specification cascades.
Dominant procurement authority: Tier-1 Suppliers. Fastest channel evolution: Aftermarket Providers.
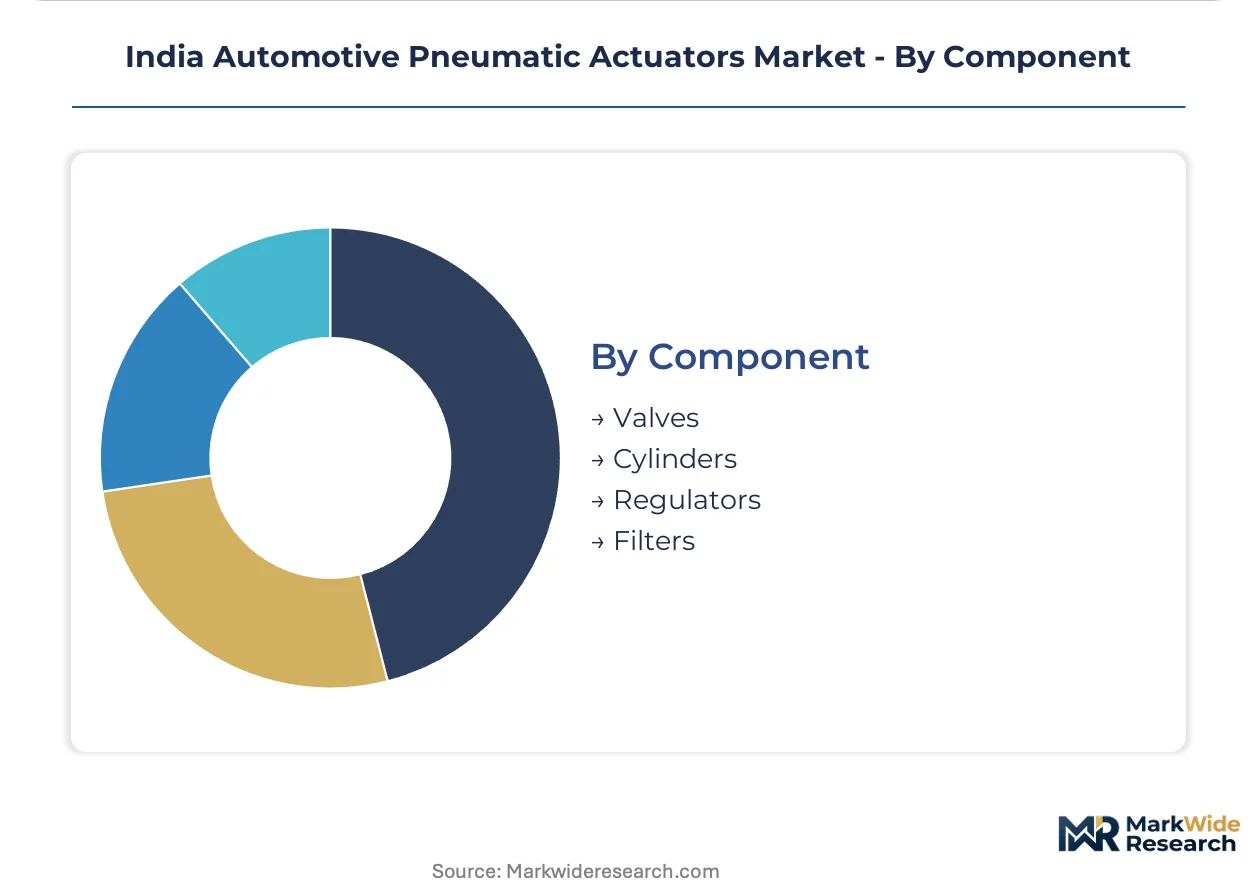
Component:
Margin structure varies sharply between precision seals and commodity cylinder bodies.
- Valves:Directional control and pressure regulation components manage airflow distribution across actuator circuits. Prototype electrified pneumatic architectures are opening development contracts for valve producers capable of electromagnetic compatibility certification.
- Cylinders:Aluminum alloy bodies house piston assemblies converting pressure to mechanical force. Primary aluminum price volatility compresses margin predictability for domestic fabricators lacking long-term smelter contracts.
- Regulators:Pressure-reducing and relieving devices maintain stable operating pressure despite supply fluctuations. These components face qualification pressure from proposed AIS-145 amendments for electromagnetic compatibility.
- Filters:Moisture and particulate removal units protect seal integrity in compressed air circuits. Fleet operators in humid coastal corridors specify enhanced filtration for brake system reliability.
Value concentration: Valves. Supply vulnerability: Cylinders.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands automotive pneumatic actuator technology exports while India accelerates domestic manufacturing capacity under production-linked incentive frameworks. Both markets illustrate divergent regional strategies—established precision engineering against emerging localization mandates.
Maharashtra
Pune's automotive manufacturing corridor hosts Tata Motors and Ashok Leyland assembly plants specifying double-acting actuators for heavy commercial vehicle brake systems. BIS certification requirements under AIS-037 compress supplier qualification timelines for domestic valve and cylinder producers. Fleet operators across the Mumbai-Nashik industrial belt prioritize localized sourcing to reduce procurement lead times.
Tamil Nadu
Chennai's Sriperumbudur belt attracts Tier-1 actuator distributors serving bus and truck OEMs with rotary variants for power steering applications. CMVR safety mandates enforce fail-safe performance standards in brake circuit components manufactured here. Nucon Industries anchors indigenous supply from this cluster to aftermarket channels across southern India.
Gujarat
Sanand and Halol manufacturing zones draw commercial vehicle assemblers diversifying supply origins beyond Maharashtra-Tamil Nadu concentration. The state's PLI scheme incentives reward valve and cylinder producers meeting localization thresholds for engine control modules. Small-fleet operators in Ahmedabad prioritize cost-minimized single-acting actuators for light commercial vehicle clutch automation.
Karnataka
Bengaluru's precision engineering base supports prototype development for electrified pneumatic architectures integrating electronic control units. Premium bus platforms in this state specify rotary actuators where angular positioning precision commands supplier qualification priority. Proposed AIS-145 amendments for electromagnetic compatibility force local valve producers into testing protocol revisions.
India Automotive Pneumatic Actuators Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across India's pneumatic actuator supply base. The market structure consolidates around three strategic tiers: multinational technology leaders with integrated valve-cylinder combinations, mid-scale indigenous fabricators serving regional OEMs, and emerging specialists targeting aftermarket digitization. Two dominant competitive moves define current positioning—capacity expansion toward Gujarat and Tamil Nadu manufacturing corridors, and strategic partnerships with fleet maintenance aggregators disintermediating traditional distribution.
Among Germany-based diversified automotive suppliers, Continental AG and Robert Bosch GmbH occupy positions exemplifying technology leadership through integrated subassembly architectures. These entities anchor the premium tier alongside Japan-based Denso Corporation, which represents precision engineering archetypes in engine control module supply. India-based Nucon Industries Pvt. Ltd. sits within the cost-competitive indigenous specialist tier, demonstrating how regional fabricators capture volume through Tier-1 distributor relationships across Tamil Nadu and Gujarat.
| Leading Market Players |
|---|
| Denso Corporation |
| CTS Corporation |
| Continental AG |
| Nucon Industries Pvt. Ltd. |
| Delphi Automotive PLC |
| Robert Bosch GmbH |
| Mitsubishi Electric Corporation |
| Hitachi, Ltd. |
| ZF Friedrichshafen AG |
| Others |
Supply & Pricing Matrix
Fleet operator consolidation across Maharashtra and Tamil Nadu is compressing procurement timelines for BIS-certified actuators, forcing valve and cylinder producers to absorb aluminum alloy volatility while maintaining price competitiveness against integrated Tier-1 imports.
Pricing Analysis
Capacity additions in Gujarat's Sanand and Halol corridors are reshaping price floors for single-acting and double-acting variants. Three-tier pricing structure across OEM-specified, Tier-1 integrated, and aftermarket replacement levels separates certification-grade products from commodity fabrications. Price differentiation hinges on BIS-AIS-037 compliance documentation and volume scale commitments from commercial vehicle assemblers. Cost compression in the indigenous fabricator tier is intensifying because primary aluminum contract insecurity erodes margin buffers against spot market swings. Small-fleet operators in Gujarat exhibit highest price sensitivity, while Tata Motors and Ashok Leyland procurement teams prioritize fail-safe reliability over unit cost.
Supply Chain Analysis
Remanufacturing flows for brake system actuators are emerging through Chennai-based aftermarket aggregators serving Golden Quadrilateral fleet operators. Manufacturing concentration rests on Germany, Japan, and domestic Indian production clusters for precision valve assemblies. Raw material dependencies draw from primary aluminum smelters, fluorocarbon elastomer seal producers, and precision-machined steel piston components. Single-source vulnerability concentrates in Japanese and German specialty chemical suppliers for high-temperature seals. Distribution runs through Tier-1 system integrators like Bosch and Continental, with direct procurement platforms disintermediating traditional distributor layers in long-haul segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's automotive pneumatic actuator market functions as a stable compounder underpinned by non-negotiable CMVR safety mandates that perpetually refresh replacement demand across commercial vehicle brake and engine control circuits.
For Market Incumbents: Anchor defensive positioning through backward integration into aluminum alloy cylinder body forging and captive fluorocarbon seal compound development. Electromechanical substitution in premium bus gear-shifting applications threatens pneumatic volume share; counter by accelerating integrated valve-cylinder combination R&D for electrified pneumatic backup architectures. Certification investment in AIS-145 electromagnetic compatibility testing protocols preserves OEM specification access as brake-by-wire prototypes advance. For New Entrants and Emerging Players: Enter via aftermarket channel digitization targeting long-haul trucking fleet aggregators across the Golden Quadrilateral corridor. Gujarat's Sanand belt offers the most penetrable geography given OEM diversification beyond Maharashtra-Tamil Nadu concentration. A direct procurement platform bypassing traditional Tier-2 distributor markups captures price-sensitive small-fleet operators seeking single-acting clutch automation actuators. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale indigenous fabricators possessing BIS certification infrastructure and untapped Gujarat manufacturing capacity. The five-to-ten year viability window favors suppliers capable of serving both OEM specification cascades and aftermarket replacement cycles. Acquisition targets should demonstrate proven AIS-037 durability testing relationships with ARAI facilities. Monitor PLI scheme localization threshold revisions as the critical inflection signal for domestic capacity valuation step-ups.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Gujarat Corridor | Sanand and Halol zones attract Tier-1 distributors diversifying beyond Maharashtra-Tamil Nadu concentration. |
| Backward Integration into Aluminum Forging | Captive cylinder body production insulates margin predictability against primary aluminum spot volatility. |
| AIS-145 Electromagnetic Compatibility Certification | Prototype brake-by-wire systems demand valve producers capable of electromagnetic resilience testing. |
| Aftermarket Channel Digitization | Fleet maintenance aggregators create direct procurement pathways disintermediating traditional distributor networks. |
| Integrated Valve-Cylinder Combination Development | Compact pre-tested subassemblies reduce OEM assembly complexity and compress qualification timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining structured discussions with Tier-1 supplier procurement teams, OEM platform engineers, aftermarket distributor operations heads, and ARAI certification specialists with secondary validation against vehicle production databases, BIS notification records, CMVR amendment dockets, and customs import data for precision seal categories. Bottom-up fabrication capacity surveys across Pune, Chennai, and Gujarat manufacturing clusters triangulated against top-down OEM procurement budget allocations.
Historical reference periods anchored volume and value trajectories to commercial vehicle production cycles and fleet replacement intervals across the analysis window. Segmentation dimensions modeled include technology variant, application circuit, end-user procurement authority, and component type. CAGRs were derived from regression analysis against vehicle platform deployment schedules and regulatory compliance deadline clustering. Industry-specific forecast inputs incorporated PLI scheme incentive disbursement timelines and proposed AIS-145 implementation uncertainty.
Inputs from ARAI testing facility records and Tier-1 supplier production schedules were available through the study window; gaps in aftermarket channel transaction data introduce uncertainty bands around replacement volume estimates. Forecasts reflect documented assumptions regarding CMVR enforcement intensity and aluminum alloy price corridor stability. Practitioners should monitor PLI scheme localization threshold adjustments and AIS-145 final notification dates for early signals of competitive positioning shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
North America Heat Shrink Tubing for Automotive Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Brake Rotor Market
Automotive Components
Europe Automotive Market
Automotive Components
Global Automotive Bumpers Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Global Automatic Lubrication System Market