
 Jack-Up Vessels Market | 2026-2036
Jack-Up Vessels Market Size, Share, and Industry Trends Forecast 2026-2036
Jack-Up Vessels Market Insights
Multi-source contracting for jack-up vessel capacity is broadening as offshore developers diversify fleet exposure across projects. Noble Corporation plc leverages its premium harsh-environment fleet to sustain dayrate competitiveness in the North Sea. Transocean Ltd anchors its position through high-specification units capable of operating in water depths exceeding 400 feet. Seadrill Limited differentiates via operational flexibility across both drilling and renewable installation contracts.
Jack-up vessels are self-elevating mobile offshore units with tubular or truss legs that penetrate the seabed to create a stable working platform above wave action, typically accommodating deck loads exceeding 5,000 tonnes and operating in water depths up to 150 meters. Their primary purpose spans offshore hydrocarbon drilling, wind turbine foundation installation, and subsea infrastructure maintenance. Independent leg configurations dominate harsh-environment markets where uneven seabed conditions demand precise leg penetration control, while wind turbine installation represents the fastest-growing application segment as turbine sizes escalate beyond 15 MW and require heavier lift capacity. Owner-operated structures retain margin pools in long-cycle offshore wind developments, though time charter arrangements are expanding among independent power producers seeking balance-sheet flexibility.
Classification societies including DNV and the American Bureau of Shipping enforce structural integrity standards for jack-up leg fatigue and spudcan design under IEC 61400-3-2 for offshore wind. The EU Green Deal and F-Gas Regulation constrain vessel power systems and refrigerant choices, while the US Coast Guard and EPA govern ballast water and emission compliance for units operating in federal waters. Stakeholders must monitor regulatory divergence between North Sea emission control areas and emerging Asian offshore wind zones when deploying cross-regional fleets.
Market Dynamics
Offshore wind turbine scaling beyond 15 MW is compressing fleet utilization rates as vessel lift capacity lags behind foundation mass requirements, forcing asset owners to reconfigure jack-up specifications mid-contract cycle.
Growth Catalysts
- EU Green Deal emission mandates:The EU Green Deal and F-Gas Regulation tighten marine construction standards, compelling fleet operators to retrofit power systems and accelerating replacement demand for compliant jack-up assets.
- North Sea offshore wind corridor:National targets in the United Kingdom, Germany, and Denmark concentrate turbine installation demand, creating sustained utilization pressure on premium harsh-environment vessels.
- Independent leg configuration advances:Precision spudcan penetration control systems enable operations on uneven seabed terrain, expanding addressable site geography for fixed-bottom wind foundations.
Market Restraints
- Steel plate input volatility:Jack-up leg fabrication depends on high-tensile steel grades subject to commodity price swings, compressing construction margin visibility for newbuild orders.
- Korean and Singaporean yard concentration:Specialist construction capacity for large offshore units clusters in East Asian shipyards, creating delivery queue risk during demand surges.
- Water depth technical ceiling:Conventional jack-up designs face structural limits near 150 meters, excluding deeper floating wind sites from addressable market scope.
Strategic Opportunities
- Floating wind foundation installation:Semi-submersible platform mating operations at portside assembly hubs create demand for hybrid jack-up vessels with enhanced deck load distribution.
- US Inflation Reduction Act offshore wind credits:Federal tax incentives accelerate Atlantic Coast lease development, opening new deployment corridors for EU-flagged vessels seeking contract diversification.
- Digital twin hull monitoring:Convergence of sensor telemetry and fatigue prediction algorithms enables condition-based maintenance, extending operational life beyond original classification timelines.
Industry Challenges
- Marine warranty surveyor capacity:DNV and ABS certification backlogs for modified leg structures delay project readiness, compressing revenue recognition windows.
- Specialized jacking system technicians:Shortage of engineers proficient in rack-and-pinion maintenance creates operational downtime risk during peak installation seasons.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Jack-Up Vessels Market |
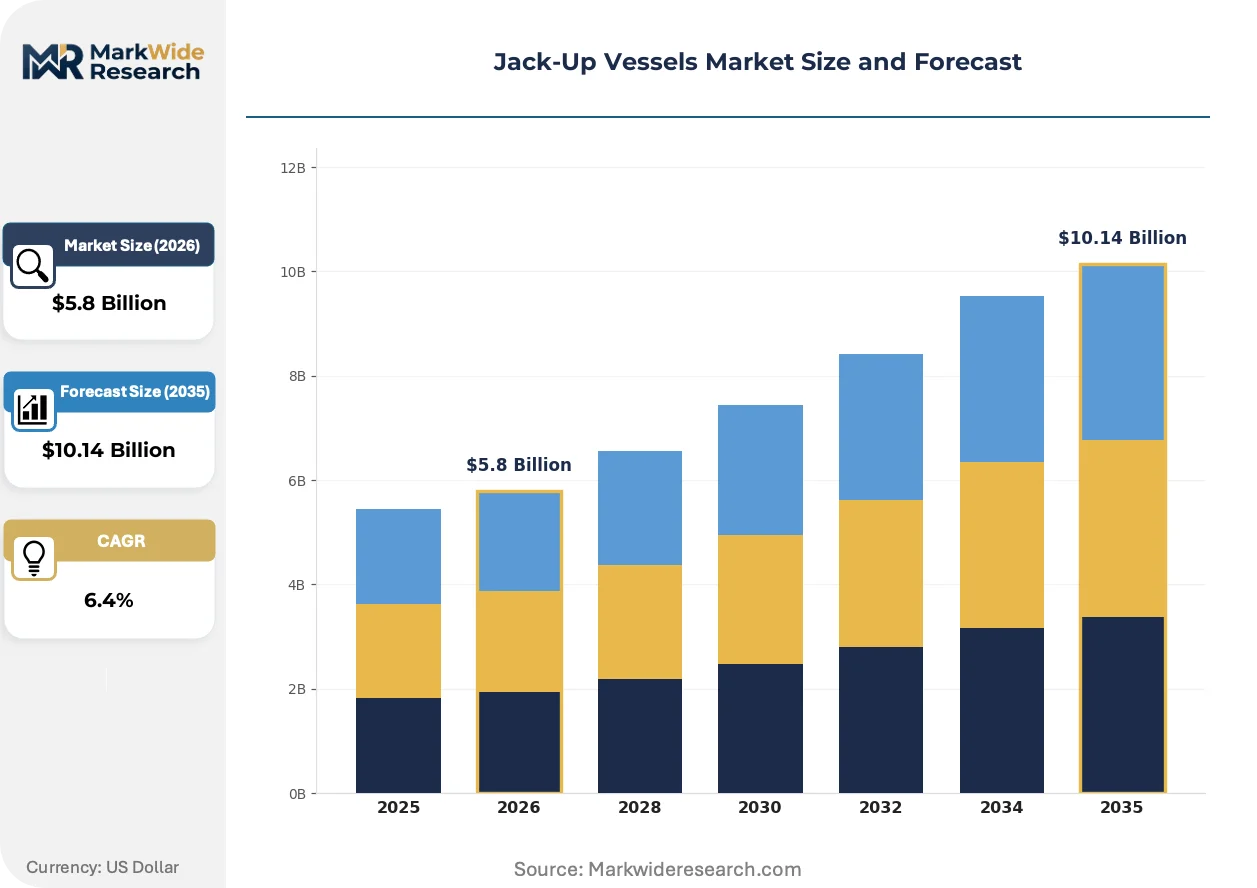
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vessel Type: Legged Jack-Up, Mat Supported, Independent Leg, Self-Elevating Application: Offshore Drilling, Wind Turbine Installation, Maintenance Services, Subsea Construction Ownership Type: Owner-Operated, Time Charter, Bareboat Charter, Spot Charter Jack-Up Leg Length: 90m, 120m, 150m, 180m, 210m |
| Companies Covered | Noble Corporation plc, Transocean Ltd, Seadrill Limited, Diamond Offshore Drilling Inc., Rowan Companies Inc., KCA DEUTAG Ltd., Maersk Drilling, ENSCO plc, COSL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Jack-Up Vessels Market Trends and Innovations
Battery-hybrid propulsion architectures and autonomous seabed positioning systems are redefining vessel operational economics, while procurement consolidation among offshore developers reshapes contract structuring.
Hybrid battery-diesel powertrains are electrifying auxiliary load management on next-generation jack-ups, cutting fuel consumption during transit and jacking operations. Offshore wind developers in the North Sea are specifying hybrid configurations for new charters, treating fuel efficiency as a tender scoring criterion. This electrification is compressing payback periods for retrofit investments and disadvantaging legacy diesel-only assets in competitive bidding.
The EU F-Gas Regulation and MRV monitoring requirements are forcing refrigerant system overhauls and exhaust treatment retrofits across the existing fleet. Vessel operators face compliance cost absorption or charter rate premiums to recover capital deployment. German and Danish project developers are now embedding emission performance clauses into multi-year contracts, shifting compliance risk to asset owners.
Power purchase agreement counterparties are consolidating procurement into multi-vessel framework agreements spanning multiple wind farm phases, displacing single-project spot charters. Independent power producers favor balance-sheet flexibility through time charter structures rather than equity stakes in vessel ownership. This concentration is most visible in United Kingdom Round 4 and Round 5 lease auctions, where developers pre-commit fleet capacity years ahead of construction start.
Jack-Up Vessels Market Segmentation
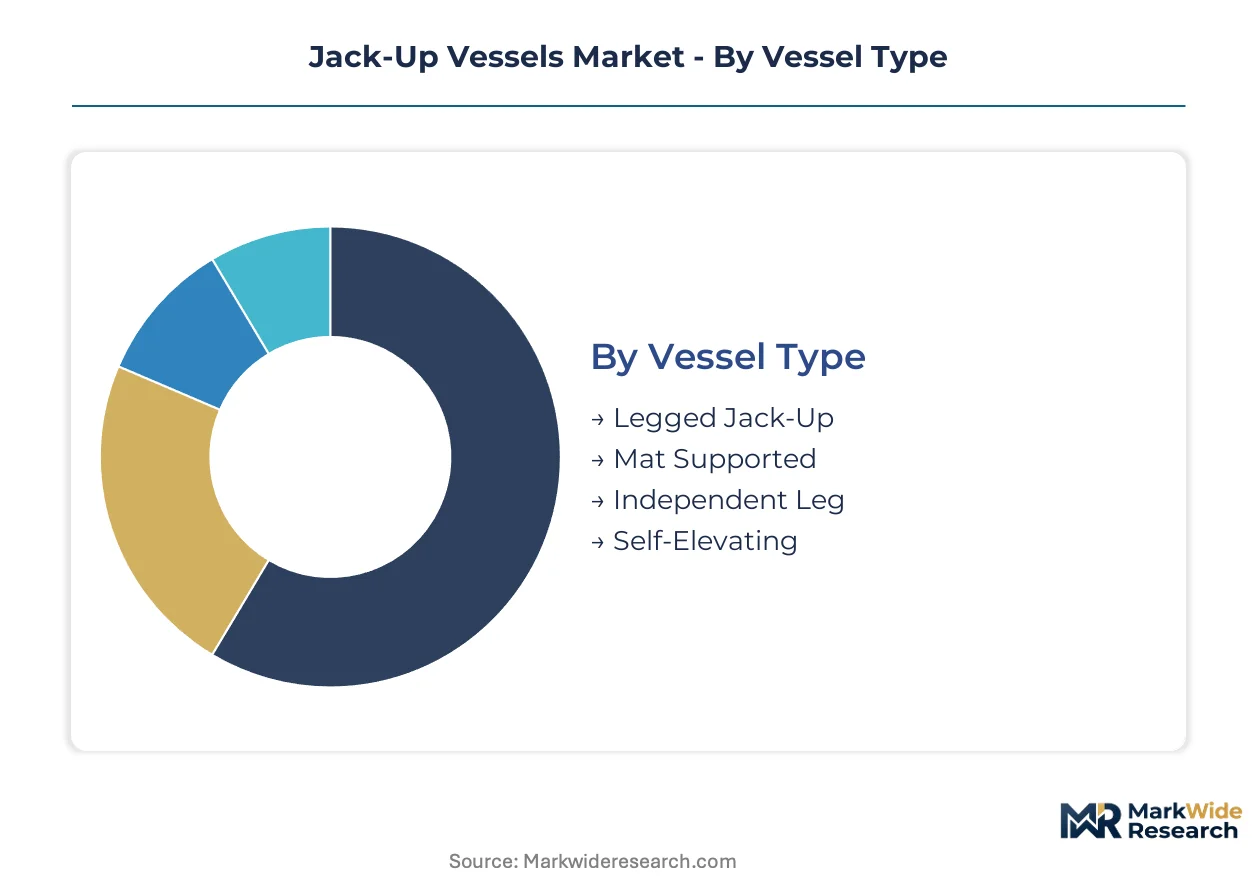
Jack-up vessel procurement patterns diverge sharply across operating models and technical specifications. Fleet configuration choices determine capital intensity, charter rate structures, and regulatory compliance pathways for offshore developers.
Vessel Type:
Buyers select hull-leg architectures based on seabed geology, water depth requirements, and harsh-environment exposure.
- Independent Leg:Tubular or truss leg configurations enable precise individual leg penetration control on uneven seabed terrain. North Sea wind farm developers specify these units for boulder-strewn glacial till conditions, paying premium dayrates for operational reliability where mat-supported designs risk structural failure.
- Legged Jack-Up:Conventional three- or four-leg platforms dominate established offshore drilling markets. Gulf of Mexico operators favor these assets for their proven jacking system reliability and extensive maintenance infrastructure across Texas and Louisiana port clusters.
- Mat Supported:Single large mat foundation distributes load across soft cohesive soils. Demand concentrates in US Gulf Coast marshland drilling where uniform seabed conditions permit deployment without individual leg penetration complexity.
- Self-Elevating:Integrated hull-leg systems optimize for rapid transit and positioning cycles. Asian offshore wind installation contractors specify these units for monopile foundation campaigns requiring frequent site relocation.
Volume sits with legged jack-up configurations; growth tilts toward independent leg architectures as offshore wind expands into geologically complex lease areas.
Application:
End-use economics determine vessel specification priorities, from drilling endurance to heavy-lift crane capacity.
- Wind Turbine Installation:Next-generation units carry 3,000-tonne-plus main cranes for 15 MW turbine component handling. United Kingdom Round 4 and Round 5 lease auctions are pre-committing fleet capacity years ahead, embedding multi-phase framework agreements that displace single-project spot charters.
- Offshore Drilling:Harsh-environment drilling units sustain dayrate premiums through winterized systems and dynamic positioning backup. Norwegian Continental Shelf operators maintain contracting preference for assets with 400-foot water depth capability and premium blowout preventer integration.
- Maintenance Services:Platform supply and accommodation support require lower capital intensity with emphasis on personnel transfer safety systems. North Sea asset integrity campaigns drive seasonal demand spikes during summer weather windows.
- Subsea Construction:Cable lay and pipeline intervention demand integrated deck space for flexible product storage. German Baltic Sea offshore wind export cable installation is expanding specialized vessel demand.
Revenue weighting favors offshore drilling; capacity expansion concentrates in wind turbine installation as foundation mass requirements escalate.
Ownership Type:
Capital structure preferences split between balance-sheet control and operational flexibility.
- Owner-Operated:Integrated vessel-owning developers capture full margin pools across multi-decade offshore wind project lifecycles. Ørsted and Equinor deploy this model for core North Sea assets where utilization visibility justifies capital deployment.
- Time Charter:Multi-year bareboat or fully crewed charters enable independent power producers to preserve balance-sheet capacity. Danish and German developers favor this structure for Round 4+ lease commitments, transferring residual value risk to vessel owners.
- Bareboat Charter:Unmanned vessel delivery with operator-provided crew and technical management. Specialist offshore contractors in Singapore and Dubai leverage this model for rapid fleet scaling without ownership concentration.
- Spot Charter:Single-voyage or single-project contracting for peak season capacity supplementation. Maintenance campaign peaks in the United Kingdom continental shelf absorb spot availability during July-September weather windows.
Contracting volume flows through time charter structures; strategic positioning tilts toward owner-operated models among integrated energy majors.
Jack-Up Leg Length:
Leg extension capability defines addressable water depth and site geography.
- 150m:Dominant specification for North Sea and Atlantic Coast offshore wind, accommodating 50-60 meter water depths with sufficient air gap for 15-meter wave conditions. German Bight and Dogger Bank developers specify this tier as standard.
- 120m:Cost-optimized configuration for shallow-water Baltic Sea and Irish Sea installations. Polish and Estonian lease areas with 30-40 meter depths favor this specification for capital efficiency.
- 90m:Legacy drilling asset specification now concentrated in Gulf of Mexico shelf operations. Brownfield platform maintenance and well intervention sustain residual demand.
- 180m:Extended reach for deeper Atlantic Coast and floating wind pre-installation sites. US Bureau of Ocean Energy Management lease areas off Massachusetts and New York are specifying this tier for future-proofing.
- 210m:Maximum extension category addressing frontier deepwater wind sites and harsh-environment drilling. Prototype units under construction for Norwegian and UK floating wind foundation pre-assembly operations.
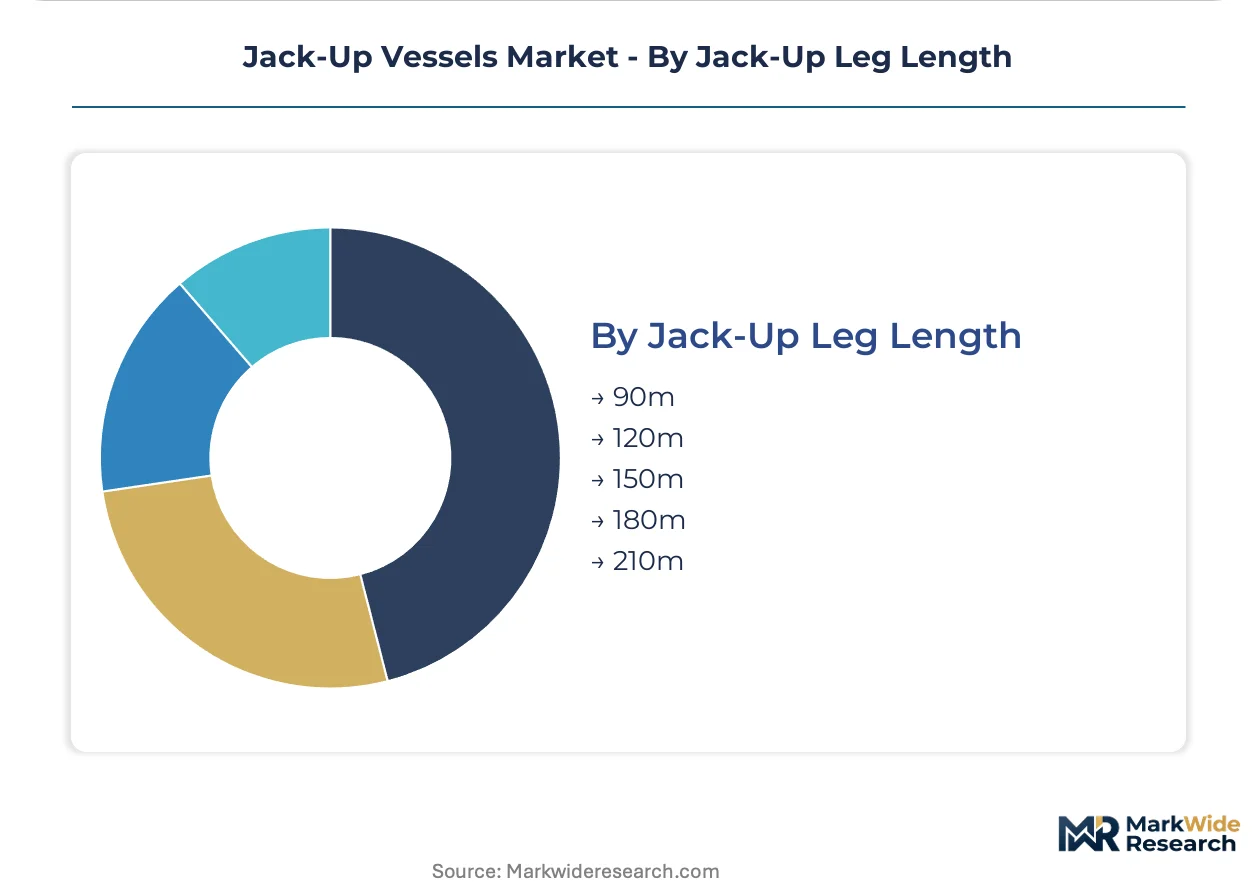
Fleet composition clusters at 150 meters; newbuild specification tilts toward 180-meter configurations as floating wind foundation installation creates hybrid operational requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Offshore wind installation demand concentrates in the North Sea corridor, where national renewable targets and seabed lease auctions are compressing vessel availability timelines across multiple jurisdictions.
United Kingdom
Dogger Bank and Round 4 lease developments are pre-committing jack-up capacity years ahead of construction starts. The UK Contracts for Difference scheme underpins revenue certainty for offshore wind developers, driving multi-vessel framework agreements. Port clusters at Hull and Great Yarmouth are expanding heavy-lift quayside infrastructure to accommodate 15 MW turbine component staging.
Germany
Baltic Sea and North Sea offshore wind targets through 2030 are absorbing premium harsh-environment vessel supply. The German Federal Maritime and Hydrographic Agency enforces strict spudcan penetration assessments for glacial till seabed conditions. Fabrication yards in Bremerhaven and Cuxhaven are retrofitting assembly halls for XXL monopile foundation production.
Denmark
Ørsted and Copenhagen Infrastructure Partners are contracting jack-up fleets across multi-phase wind farm portfolios. Danish Energy Agency permitting timelines for Kriegers Flak and subsequent lease areas are synchronizing vessel charter windows. Port of Esbjerg maintains its position as North Sea logistics hub with dedicated offshore wind marshalling areas.
United States
Bureau of Ocean Energy Management lease auctions off Massachusetts and New York are opening Atlantic Coast deployment corridors. The Inflation Reduction Act offshore wind tax credits are accelerating project financing commitments. New Bedford and Portsmouth marine terminals are upgrading crane capacity to receive European-flagged installation vessels.
China
Provincial offshore wind targets in Guangdong and Fujian are driving domestic jack-up construction programs. The Ministry of Natural Resources streamlines seabed use permits for fixed-bottom wind foundations in shallow coastal waters. Yantai and Qidao shipyards are delivering self-elevating units with integrated heavy-lift systems for 10 MW-plus turbine installation.
Jack-Up Vessels Market Competitive Landscape
Capacity expansion dominates the current landscape as fleet operators respond to offshore wind foundation mass escalation and compressed installation windows. The vendor base stratifies across integrated drilling contractors, pure-play renewable installation specialists, and Asian fabrication conglomerates. Three archetypes define positioning: premium harsh-environment drillers with winterized assets, hybrid operators bridging drilling and wind installation, and cost-optimized builders serving shallow-water Asian markets. Geographic expansion into Atlantic Coast lease areas and strategic partnerships for floating wind foundation mating operations represent the dominant competitive vectors.
Among premium-tier drilling contractors, Noble Corporation plc and Transocean Ltd occupy positions anchored by high-specification harsh-environment fleets, while Seadrill Limited exemplifies the hybrid archetype spanning both hydrocarbon and renewable contract streams. These entities represent contrasting strategic postures: the first two emphasize dayrate competitiveness through technical specification, while the third pursues operational flexibility across divergent end-market cycles. Their collective positioning illustrates how fleet configuration choices determine addressable contract pools in an environment where turbine scaling is compressing utilization rates for legacy assets.
| Leading Market Players |
|---|
| Noble Corporation plc |
| Transocean Ltd |
| Seadrill Limited |
| Diamond Offshore Drilling Inc. |
| Rowan Companies Inc. |
| KCA DEUTAG Ltd. |
| Maersk Drilling |
| ENSCO plc |
| COSL |
| Others |
Pricing and Supply Chain Analysis
High-tensile steel plate costs cascade from Korean and Singaporean fabrication yards through to charter rate structures, with premium harsh-environment vessels commanding substantial dayrate premiums over standard-leg configurations as commodity input volatility compresses construction margins.
Pricing Analysis
Volume concentrates in mid-tier time charter arrangements while margins pool in owner-operated premium assets. Pricing stratifies across premium harsh-environment specifications, standard independent-leg configurations, and economy mat-supported units, with differentiation driven by IEC 61400-3-2 certification tier and winterization grade. Cost compression in standard-tier construction is intensifying because steel plate commodity swings erode yard visibility. Independent power producers exhibit highest price sensitivity through bareboat structures, while integrated energy majors absorb premium tier premiums for utilization certainty.
Supply Chain Analysis
Direct-to-developer contracting channels handle framework agreement demand from Ørsted and Equinor, while spot charter brokers absorb seasonal peak supplementation. Geographic supply concentration centers on South Korea, Singapore, and China for hull fabrication, with Norway and the United Kingdom contributing specialized jacking system engineering. Raw material dependencies draw from high-tensile steel grades, rack-and-pinion drive components, and heavy-lift crane systems. Single-source vulnerability in East Asian yard capacity creates delivery queue risk during North Sea auction surges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The jack-up vessel market sits in a technology-transition phase as battery-hybrid propulsion architectures displace legacy diesel-only powertrains, compelling fleet operators to retrofit or face competitive exclusion.
For Market Incumbents: Deepen backward integration into high-tensile steel supply through captive offtake agreements with Korean mills, insulating construction margins from commodity volatility. Expand certification engineering teams to accelerate DNV and ABS backlog clearance, compressing revenue recognition delays that threaten utilization rates during peak installation windows. For New Entrants and Emerging Players: The gap between premium harsh-environment dayrates and economy Baltic Sea charter levels offers entry latitude for mid-tier independent-leg specifications. Target Polish and Estonian lease areas with 120-meter leg configurations, penetrating through time charter flexibility rather than equity ownership concentration. For Investors and Strategic Acquirers: German Federal Maritime and Hydrographic Agency spudcan assessment backlogs are the leading indicator that marine warranty surveyor capacity constraints will persist, favoring asset-light technical management platforms over heavy vessel ownership. Long-term viability hinges on exposure to floating wind foundation mating operations, with hybrid jack-up specifications representing the acquisition archetype best positioned for technology transition.| Strategic Initiative | Industry Significance |
|---|---|
| Battery-Hybrid Retrofit Program | EU F-Gas Regulation compliance secures charter eligibility in German and Danish waters. |
| Extended Leg Configuration Investment | 180-meter specifications access US Atlantic Coast floating wind pre-assembly sites. |
| Marine Warranty Surveyor Capacity Expansion | In-house DNV and ABS certification teams compress project readiness timelines. |
| Framework Agreement Consolidation | Multi-phase UK Round 4 and Round 5 commitments displace spot charter volatility. |
| Asian Fabrication Partnership | Yantai and Qidao yard alliances secure delivery slots during demand surges. |
Research Methodology
Multi-period observation of vessel dayrate movements, yard orderbook backlogs, and offshore wind lease auction timelines anchored the trend analysis, supplemented by interviews with fleet operations directors, marine warranty surveyors at DNV and ABS, offshore wind project developers, and EPC contractors. Secondary validation drew from Bureau of Ocean Energy Management lease records, EU Green Deal implementation directives, Korean and Singaporean customs trade data, and classification society technical bulletins. Bottom-up vessel supply modeling and top-down offshore wind capacity targets were triangulated to cross-check segment outputs.
The input-output matrix framed demand-side projections against supply-side yard capacity, with segmentation across vessel type, application, ownership structure, and leg length tier throughout the forecast period. CAGRs were derived from regression analysis of historical utilization rates against announced offshore wind pipeline capacity. Industry-specific forecast inputs included turbine scaling trajectories beyond 15 MW and spudcan penetration technology advancement curves.
Inputs from classification society technical committees and offshore developer procurement leads were available through the study window; gaps in forward yard orderbook visibility and unannounced turbine manufacturer specifications introduce uncertainty bands around capacity expansion timing. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity and steel plate price stabilization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Pneumatic Marine Fender Market
Marine
Boat Hook Market
Marine
Singapore Container Transshipment Market
Marine
Digital Nautical Charts Market
Marine
Marine VFD Market
Marine
Offshore Autonomous Underwater Vehicle (AUV) Market
Marine
Ship Rudders Market
Marine
Asia-Pacific Offshore Support Vessels Market
Marine
Rescue Boats Market
Marine
Offshore AUV and ROV Market
Marine
Marine Glass Market
Marine
Electric Outboard Engines Market
Marine
Integrated Bridge System for Ships Market
Marine
Ship Heat Exchanger Market