
 Marine Glass Market | 2026-2036
Marine Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Glass Market Foresight
The EU Green Deal is expanding compliance requirements for marine glazing across European shipyards. Sedak GmbH & Co. KG leverages its oversized lamination capacity to dominate superyacht contracts in Northern Europe. Diamond Sea Glaze anchors its position through specialized curved-glass engineering for expedition vessels. Glasshape competes aggressively in the retrofit segment across Australasian ports.
Marine glass encompasses tempered, laminated, coated, and bulletproof formulations engineered to withstand salt corrosion, pressure differentials, and impact trauma in maritime environments. Laminated glass incorporates interlayers of polyvinyl butyral or ionoplast polymers to maintain structural integrity upon fracture, a specification critical for windshield and hull applications where passenger safety intersects with watertight performance. The product type dimension shows laminated glass commanding the premium tier due to regulatory mandates for passenger vessel safety, while coated glass represents the fastest-growing category as thermal-control films reduce HVAC loads on commercial fleets. Application demand concentrates in windshields and windows where optical clarity standards from classification societies drive replacement cycles.
Classification societies including Lloyd's Register and DNV enforce structural glazing standards that determine market access for marine glass suppliers. The EU's F-Gas Regulation and REACH framework restrict certain coating chemistries, compelling manufacturers to reformulate low-emissivity layers. Stakeholders must monitor evolving IMO safety amendments and regional carbon-border adjustments that will reshape material specifications and supplier qualification timelines.
Market Dynamics
The EU Green Deal's vessel emissions mandates are compressing design cycles for marine glazing, forcing shipyards to prioritize lightweight laminated composites over conventional tempered glass to meet carbon-intensity targets.
Growth Catalysts
- EU F-Gas Regulation:Restrictions on high-global-warming-potential coating chemistries are accelerating reformulation of low-emissivity marine glass interlayers, creating replacement demand across European commercial fleets.
- Superyacht segment concentration:Italian and Dutch builders are expanding laminated safety glass orders for hull and superstructure applications, concentrating procurement in Northern European supply clusters.
- Ionoplast interlayer technology:Advanced polymer formulations deliver superior post-breakage structural retention for expedition vessels operating in polar pressure conditions.
Market Restraints
- Raw material volatility:Polyvinyl butyral resin supply concentrates among petrochemical producers in the US Gulf Coast and Northeast Asia, exposing laminators to feedstock price swings.
- Oversized capacity scarcity:Few European facilities possess autoclaves exceeding six meters in dimension, constraining superyacht windshield sourcing options to Germany and specialized Italian producers.
- REACH compliance friction:ECHA substance restrictions on certain adhesion promoters extend qualification timelines for new coating formulations by twelve to eighteen months.
Strategic Opportunities
- Expedition vessel retrofit:Polar cruise operators are replacing single-pane bridge glazing with thermally broken laminated units to meet DNV ice-class specifications.
- Carbon-border adjustment alignment:EU CBAM implementation on imported aluminum framing systems incentivizes regional sourcing of complete marine window assemblies.
- Electrochromic convergence:Integration of dynamic tinting films with laminated safety glass enables HVAC load reduction without sacrificing impact resistance ratings.
Industry Challenges
- Lloyd's Register certification bottlenecks:Backlogs in type-approval testing for novel curved-glass geometries delay superyacht delivery schedules by four to six months.
- Specialized laminator workforce scarcity:Vacuum-bag processing expertise for oversized marine panels concentrates among aging technicians in Hamburg and Venice production clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Glass Market |
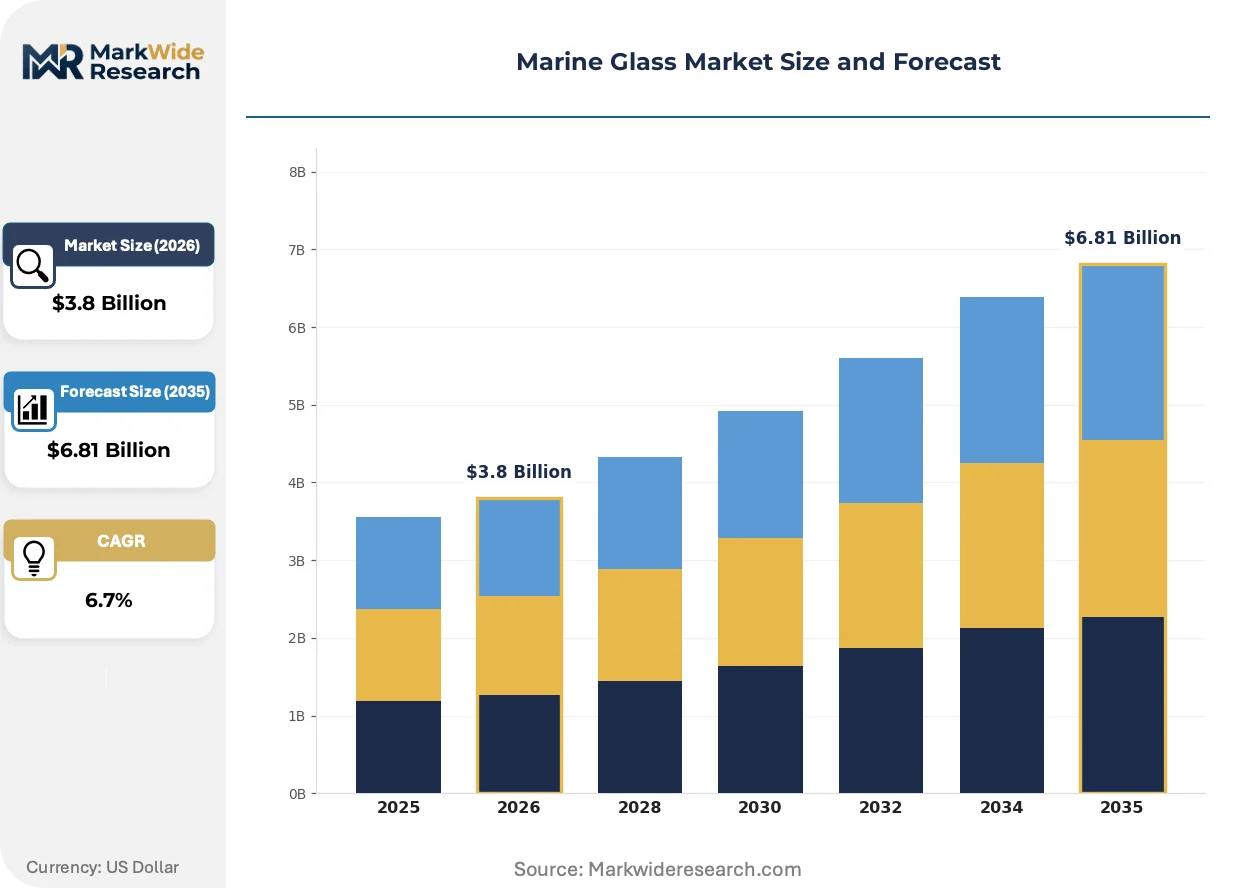
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Coated Glass, Bulletproof Glass Application: Windshields, Hulls, Windows, Decks End User: Commercial Vessels, Recreational Boats, Superyachts, Transportation Installation Type: Factory-installed, Retrofit, Custom-fit, Repair |
| Companies Covered | Marine Glass Specialties, Diamond Sea Glaze, Sedak GmbH & Co. KG, Vetrotech, Speedy Glass, Trend Marine, Garibaldi Glass, Glasshape, ProCurve Glass Design, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Glass Market Shifts & Advancements
Structural glazing specifications are fragmenting across vessel categories as classification societies tighten optical clarity standards while owners demand integrated thermal and ballistic performance from single-pane solutions.
Hybrid ionoplast-polyvinyl butyral interlayer systems are unifying post-breakage retention with acoustic damping for luxury yacht applications. Northern European superyacht builders specify these laminates for master suite glazing where privacy and safety codes intersect. The technology is compressing supplier qualification timelines by eliminating separate acoustic and structural testing protocols.
REACH framework amendments on per- and polyfluoroalkyl substances are compelling marine glass coaters to eliminate fluorinated water-repellent layers from exterior surfaces. German and Dutch yards now require suppliers to document alternative hydrophobic chemistries in technical files. Laminated windshields for North Sea offshore support vessels face the most acute reformulation pressure due to combined salt-spray and abrasion duty cycles.
Expedition cruise operators are unbundling glazing replacement from scheduled dry-dock maintenance, compressing procurement cycles for bridge and passenger-deck windows. Independent marine glass specialists in Hamburg, Rotterdam, and Singapore are capturing this work through mobile laminating units deployed at anchorage. The model is displacing yard-captive glazing contracts most visibly in the Antarctic and Arctic expedition segments where operational seasonality limits dry-dock access.
Marine Glass Market Segmentation
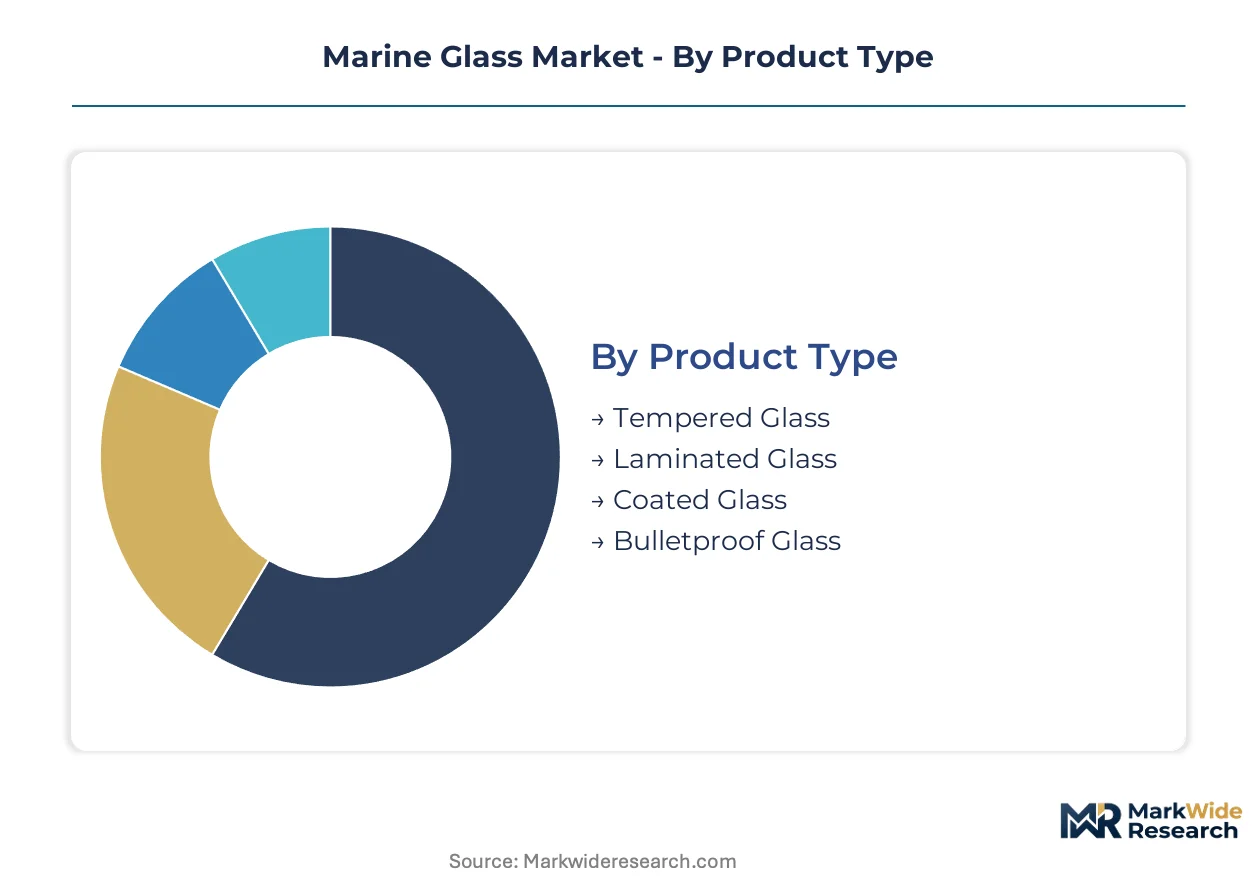
Marine glass procurement patterns diverge sharply across vessel categories, with classification society mandates and operational duty cycles dictating material specifications. Supply chain configuration varies by segment, concentrating high-value laminated production in Northern European autoclave clusters while commoditized tempered glass sources more broadly.
Product Type:
Supply concentration for advanced marine glazing tilts toward German and Italian laminators with oversized autoclave capacity, while commodity tempered glass sources from distributed float-glass processors.
- Laminated Glass:Polyvinyl butyral or ionoplast interlayers bond multiple glass plies to maintain structural integrity upon fracture. Superyacht builders in the Netherlands and Italy concentrate procurement of oversized laminated panels for hull and superstructure applications, driven by Lloyd's Register safety mandates for passenger vessel zones. Laminated glass absorbs the bulk of installed capacity; coated glass is expanding most quickly.
- Tempered Glass:Thermally strengthened monolithic panels offer cost-efficient impact resistance for non-structural marine applications. Commercial fishing fleets and inland waterway operators source tempered glazing from regional processors to minimize replacement logistics.
- Coated Glass:Low-emissivity and solar-control films reduce HVAC loads on commercial fleets. EU F-Gas Regulation restrictions on high-global-warming-potential chemistries are accelerating reformulation of coating interlayers.
- Bulletproof Glass:Multi-ply laminates with polycarbonate or glass-clad polycarbonate cores resist ballistic penetration for high-security vessel zones. Government and private security contractors specify these units for designated safe rooms and bridge protection.
Laminated glass absorbs the bulk of installed capacity; coated glass is expanding most quickly.
Application:
Application-specific demand correlates with vessel operational profiles, where bridge visibility requirements and passenger safety zones drive specification intensity.
- Windshields:Curved laminated assemblies with optical clarity certification from DNV and Lloyd's Register dominate bridge glazing for commercial and expedition vessels. Polar cruise operators are replacing single-pane units with thermally broken laminated configurations to meet ice-class specifications.
- Windows:Side-hull and superstructure glazing balances thermal performance with impact ratings. Passenger vessel operators face compressed replacement cycles due to classification society optical clarity standards.
- Hulls:Structural glazing for underwater viewing and specialized yacht applications requires pressure-rated laminated systems. Expedition vessel builders specify ionoplast interlayers for polar pressure conditions.
- Decks:Walkable glass panels with anti-slip surfaces and load-bearing certification serve luxury yacht and cruise ship amenity spaces. Surface treatments must resist salt corrosion and UV degradation simultaneously.
Windshields command premium pricing due to certification complexity; hull glazing is gaining share fastest among expedition vessel newbuilds.
End User:
End-user procurement patterns separate between scheduled newbuild programs and event-driven replacement demand, with superyacht and expedition segments showing highest specification intensity.
- Superyachts:Custom oversized laminated panels with integrated thermal and acoustic performance dominate this segment. Northern European builders concentrate orders with German and specialized Italian laminators possessing six-meter-plus autoclave capacity.
- Commercial Vessels:Ferry operators and offshore support fleets prioritize coated glass for HVAC load reduction under tightening EU emissions standards. Procurement runs through fleet maintenance contracts with regional glazing specialists.
- Recreational Boats:Production boatbuilders source standardized tempered and laminated configurations through distributor networks. Specification intensity remains lowest in this segment due to cost sensitivity.
- Transportation:Naval and government vessel programs require ballistic-rated and electromagnetic-shielding glass configurations. Security classification limits supplier qualification to cleared facilities.
Superyachts generate highest margin per square meter; commercial vessels represent largest volume throughput.
Installation Type:
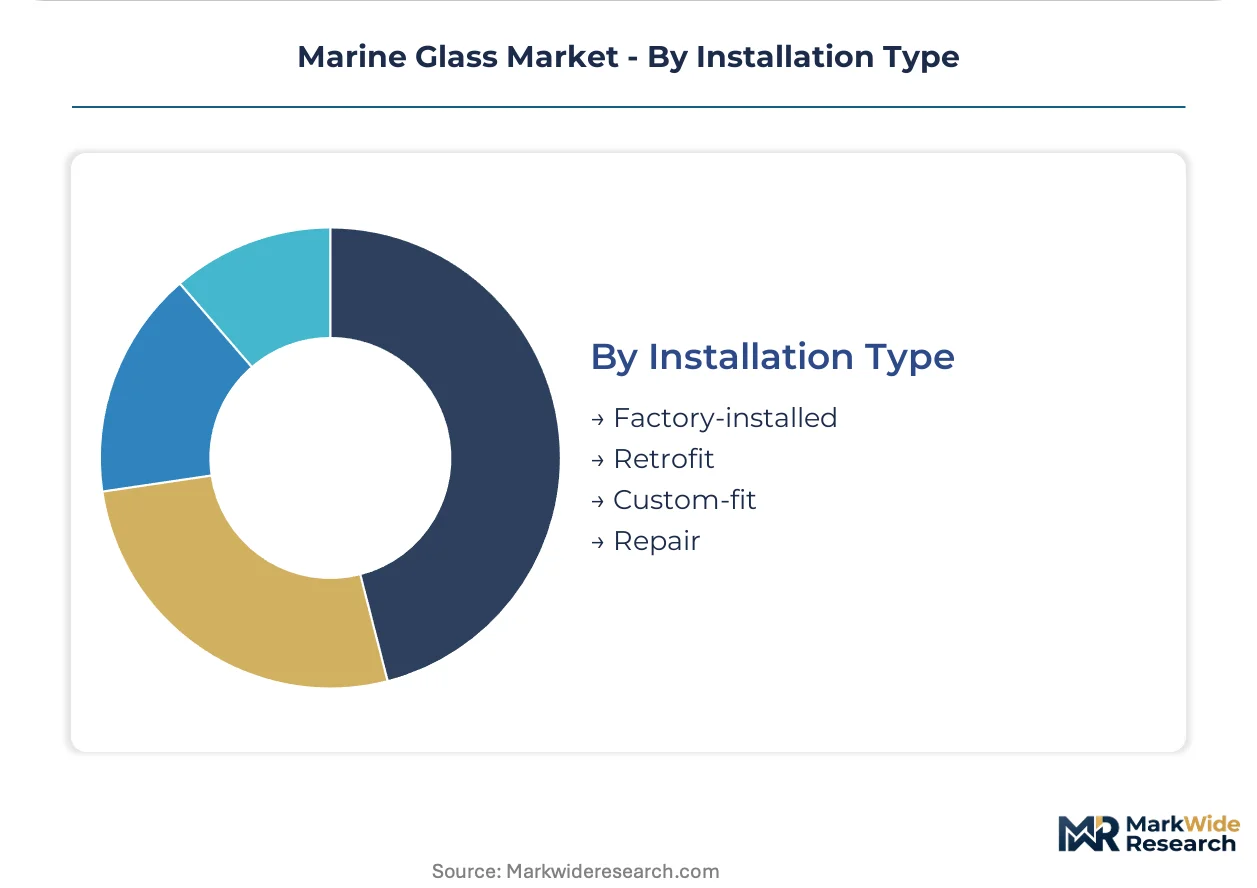
Installation modality determines supply chain touchpoints, with factory-installed glazing captive to yard relationships and retrofit/repair opening independent specialist channels.
- Factory-installed:Newbuild glazing integrates with hull construction schedules and classification society approval workflows. Superyacht yards in Germany, the Netherlands, and Italy maintain preferred supplier agreements with laminators possessing oversized capacity.
- Retrofit:Independent marine glass specialists in Hamburg, Rotterdam, and Singapore deploy mobile laminating units for at-anchor replacement. Antarctic and Arctic expedition operators favor this model due to dry-dock seasonality constraints.
- Custom-fit:One-off replacement for legacy vessels requires template-based fabrication and specialized installation protocols. Aging fleet demographics in European inland waterways sustain this segment.
- Repair:Crack remediation and interlayer delamination treatment extends service life for laminated units. Classification society survey requirements trigger repair versus replace decisions.
Factory-installed captures newbuild value; retrofit is climbing fastest as fleet age extends replacement cycles beyond scheduled maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European marine glass manufacturing through its northern German shipbuilding cluster, where oversized autoclave capacity serves superyacht and commercial vessel demand. The EU Green Deal's emissions mandates are compressing procurement cycles across Mediterranean and North Sea yards alike.
Germany
Superyacht builders in Hamburg and Bremen are expanding orders for laminated safety glass with ionoplast interlayers. The EU F-Gas Regulation restricts high-global-warming-potential coating chemistries, forcing reformulation of low-emissivity layers. Northern shipbuilding clusters concentrate procurement with laminators possessing six-meter-plus autoclave capacity.
Italy
Dutch and Italian superyacht yards are sourcing custom oversized panels for hull and superstructure applications. REACH compliance requirements from ECHA extend qualification timelines for new coating formulations by twelve to eighteen months. Venice production clusters retain specialized vacuum-bag processing expertise for curved marine glazing.
Netherlands
Expedition vessel operators are replacing single-pane bridge glazing with thermally broken laminated units to meet DNV ice-class specifications. The EU Green Deal tightens carbon-intensity targets for vessel manufacturing, pushing yards toward lighter glass composites. Rotterdam hosts independent marine glass specialists deploying mobile laminating units for at-anchor replacement.
United States
Commercial fishing fleets and inland waterway operators source tempered glazing from regional processors to minimize replacement logistics. Polyvinyl butyral resin supply concentrates among petrochemical producers in the US Gulf Coast, exposing laminators to feedstock price volatility. Coastal fabrication facilities serve retrofit demand across Pacific and Atlantic port networks.
Singapore
Antarctic and Arctic expedition operators favor mobile laminating models due to dry-dock seasonality constraints. Independent specialists capture unbundled glazing replacement work through units deployed at anchorage. Southeast Asian port infrastructure supports rapid turnaround for bridge and passenger-deck window procurement cycles.
Marine Glass Market Competitive Landscape
The competitive structure tilts toward specialized laminators with oversized autoclave capacity. Northern European yards maintain preferred supplier agreements with German and Italian fabricators possessing six-meter-plus dimension capability. Two archetypes dominate: premium-tier specialists in curved and ballistic-rated glazing, and scale-driven processors serving commercial fleet retrofit demand. Competitive moves concentrate on strategic partnerships with superyacht builders and geographic expansion through mobile laminating units.
Among European laminators, Sedak GmbH & Co. KG occupies a position exemplifying the oversized-capacity archetype, while Diamond Sea Glaze represents specialized curved-glass engineering for expedition vessels. Glasshape anchors the retrofit-specialist tier across Australasian ports. These three entities illustrate how supplier qualification timelines and autoclave scale create defensive positioning against commoditized tempered-glass processors.
| Leading Market Players |
|---|
| Marine Glass Specialties |
| Diamond Sea Glaze |
| Sedak GmbH & Co. KG |
| Vetrotech |
| Speedy Glass |
| Trend Marine |
| Garibaldi Glass |
| Glasshape |
| ProCurve Glass Design |
| Others |
Supply & Pricing Matrix
Polyvinyl butyral resin feedstock from US Gulf Coast petrochemical producers cascades through laminator pricing tiers, with oversized autoclave capacity in Hamburg and Venice commanding premium quotations for superyacht contracts while regional tempered-glass processors compete on logistics proximity for commercial fleet replacement cycles.
Pricing Analysis
Outcome-based pricing anchored to Lloyd's Register and DNV certification tiers dominates laminated marine glass procurement. Three-tier pricing structure across premium, standard, and economy levels separates ionoplast-interlayer expedition specifications from commodity PVB laminates and tempered replacements. Cost compression in the commercial vessel tier is intensifying because EU F-Gas Regulation reformulation expenses concentrate among smaller coaters lacking R&D scale. Recreational boatbuilders exhibit highest price sensitivity, while superyacht yards accept extended qualification timelines for curved-glass engineering.
Supply Chain Analysis
Freight costs for oversized laminated panels constrain sourcing radii around Northern European autoclave clusters in Germany, Italy, and the Netherlands. Raw material dependencies draw from Saudi petrochemical PVB resin, Belgian ionoplast polymer feedstock, and Chinese low-emissivity coating substrates. Single-source vulnerability concentrates in six-meter-plus autoclave capacity held by Sedak GmbH & Co. KG and select Italian laminators. Distribution runs through yard-captive channels for newbuild programs and independent mobile units for retrofit at Antarctic anchorage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Oversized autoclave scarcity props laminated glass pricing, with six-meter-plus capacity bottlenecks in Northern Europe limiting superyacht supply elasticity and sustaining incumbent margin structures.
For Market Incumbents: Anticipate mobile laminating specialists displacing yard-captive contracts in polar expedition segments, and respond by deploying proprietary at-anchorage units through Rotterdam and Singapore hubs to defend retrofit revenue streams. Accelerate REACH-compliant coating reformulation ahead of ECHA per- and polyfluoroalkyl substance amendments to compress twelve-to-eighteen-month qualification timelines for competitors. For New Entrants and Emerging Players: Electrochromic film integration with laminated safety glass offers a technology-first wedge into superyacht HVAC reduction specifications, where thermal-load engineering commands premium positioning. Target the Australasian retrofit segment where Glasshape's established presence leaves pricing gaps for independent specialists with mobile vacuum-bag processing capability. Lead with DNV ice-class bridge glazing certification to bypass Lloyd's Register backlog delays. For Investors and Strategic Acquirers: Backlogs in Lloyd's Register type-approval testing for novel curved-glass geometries is the leading indicator that certification-constrained laminators will capture sustained pricing power through superyacht delivery cycle compression. Position for five-to-ten-year holding periods around specialized curved-glass engineering capabilities with expedition vessel track records. Monitor ECHA substance restriction announcements as inflection signals for coating chemistry replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Mobile Laminating Unit Deployment | Captures unbundled Antarctic and Arctic expedition retrofit demand outside dry-dock seasonality constraints. |
| REACH-Compliant Coating Reformulation | Eliminates fluorinated water-repellent layers ahead of ECHA enforcement to secure German and Dutch yard technical approvals. |
| Ionoplast-PVB Hybrid Interlayer Development | Unifies structural retention with acoustic damping to compress Lloyd's Register testing protocols for luxury yacht suites. |
| Backward Integration into PVB Resin Sourcing | Reduces exposure to US Gulf Coast petrochemical price volatility through captive polymer supply arrangements. |
| Electrochromic Film Integration Partnership | Enables dynamic tinting without sacrificing impact resistance ratings for EU Green Deal HVAC load reduction mandates. |
Research Methodology
Multi-period observation of superyacht order flows, autoclave capacity utilization rates, and classification society certification backlogs anchored the trend analysis, supplemented by interviews with laminator operations directors, superyacht yard procurement managers, DNV surveyors, and mobile glazing unit technicians. Secondary validation drew from Lloyd's Register type-approval databases, ECHA substance restriction notifications, EU customs trade data for marine glass imports, and SEC filings of listed shipbuilding conglomerates. Bottom-up vessel demand modeling and top-down industry revenue estimates were triangulated for consistency.
Segment-weighting across product type, application, end user, and installation type dimensions shaped the analytical framework throughout the forecast period. CAGRs were derived from regression analysis against vessel order backlogs and replacement cycle compression indicators, with specific inputs including EU Green Deal carbon-intensity target implementation timelines and polar cruise operator fleet expansion announcements.
Several conditions sit outside the modeled scope, including unannounced ECHA substance restrictions beyond per- and polyfluoroalkyl substances, sudden Lloyd's Register or DNV regulatory amendments, and geopolitical disruptions to US Gulf Coast petrochemical supply. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Boat Ladder Market
Marine
Marine Fender Systems Market
Marine
Boat Steering Systems Market
Marine
Marine VFD Market
Marine
Boat Trolling Motor Market
Marine
Dynamic Positioning System Market
Marine
Shipbuilding Market
Marine
India Boat Davits Market
Marine
Fishing Vessel Market
Marine
Marine Salvage Services Market
Marine
LNG Bunkering Vessel Market
Marine
Sailboat Propellers Market
Marine
Marine Strip Market
Marine
Steel Ship Plate Market
Marine
Global Foldable Inflatable Boats Market
Marine
Global Maritime Information Market