
 South Africa Used Car Market | 2026-2036
South Africa Used Car Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Used Car Market Insights
Modular service bundling—combining warranty, financing, and inspection into single transaction packages—is broadening buyer choice across South Africa's used car ecosystem. WeBuyCars leverages its high-volume inspection infrastructure to sustain rapid inventory turnover. Motus anchors its competitive position through backward integration into captive finance and aftersales networks. AutoTrader South Africa competes by controlling digital discovery traffic and lead-generation economics.
A used car denotes a previously registered motor vehicle transferred through secondary ownership, typically evaluated by odometer reading, service history documentation, and structural integrity assessment against manufacturer specifications. The primary commercial purpose centers on providing affordable mobility access while capturing residual value from depreciated automotive assets. SUV and hatchback segments dominate volume flows, with SUVs commanding stronger margin pools due to family-buyer preference and higher average transaction values. Online platforms represent the fastest-growing sales channel, displacing traditional private sales as digital verification tools reduce information asymmetry between distant buyers and sellers.
South Africa's National Road Traffic Act, enforced by the Road Traffic Management Corporation, mandates roadworthiness certification for all transferred vehicles, directly filtering substandard inventory from formal channels. The National Credit Regulator governs instalment sale agreements and balloon finance structures, shaping how dealerships structure payment plans for subprime borrowers. Stakeholders must monitor enforcement intensity around odometer tampering penalties and evolving emissions testing protocols, as regulatory stringency will determine which inventory ages and fuel types retain market access.
Market Dynamics
Fleet renewal programs among ride-hailing operators are flooding South Africa's secondary market with late-model inventory, compressing price discovery cycles and forcing traditional dealers to accelerate digital transformation to match auction velocity.
Growth Catalysts
- Ride-hailing fleet rotation:Uber and Bolt operators are replacing vehicles every 3-4 years, injecting certified pre-owned stock with documented maintenance histories into wholesale channels.
- Road Traffic Act enforcement:The Road Traffic Management Corporation's stricter roadworthiness certification requirements are filtering substandard vehicles from formal resale, elevating buyer confidence in documented transactions.
- Digital verification tools:Blockchain-based service history logging and AI-powered damage assessment are reducing information asymmetry between distant buyers and sellers.
Market Restraints
- Import tariff exposure:High duties on replacement parts inflate repair costs for older vehicles, narrowing the economically viable age range for resale.
- Finance access stratification:National Credit Regulator caps on instalment sale agreements exclude deep subprime borrowers, capping addressable demand.
- Fuel type obsolescence risk:Pending emissions testing protocol expansions threaten diesel inventory values in urban centers.
Strategic Opportunities
- Eastern Cape penetration:Port Elizabeth and East London exhibit lower dealer density relative to population, creating whitespace for platform expansion.
- Subscription-to-ownership conversion:Short-term vehicle subscription pilots are building credit files and purchase intent among first-time buyers.
- Captive finance integration:Dealership groups with in-house lending capacity can structure balloon payment products the National Credit Regulator permits.
Industry Challenges
- Inspection technician scarcity:Certified vehicle assessor training programs have not scaled to match platform volume growth, creating quality control bottlenecks.
- Odometer fraud detection:Digital tampering methods outpace forensic verification capabilities, exposing dealers to liability and reputation damage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Used Car Market |
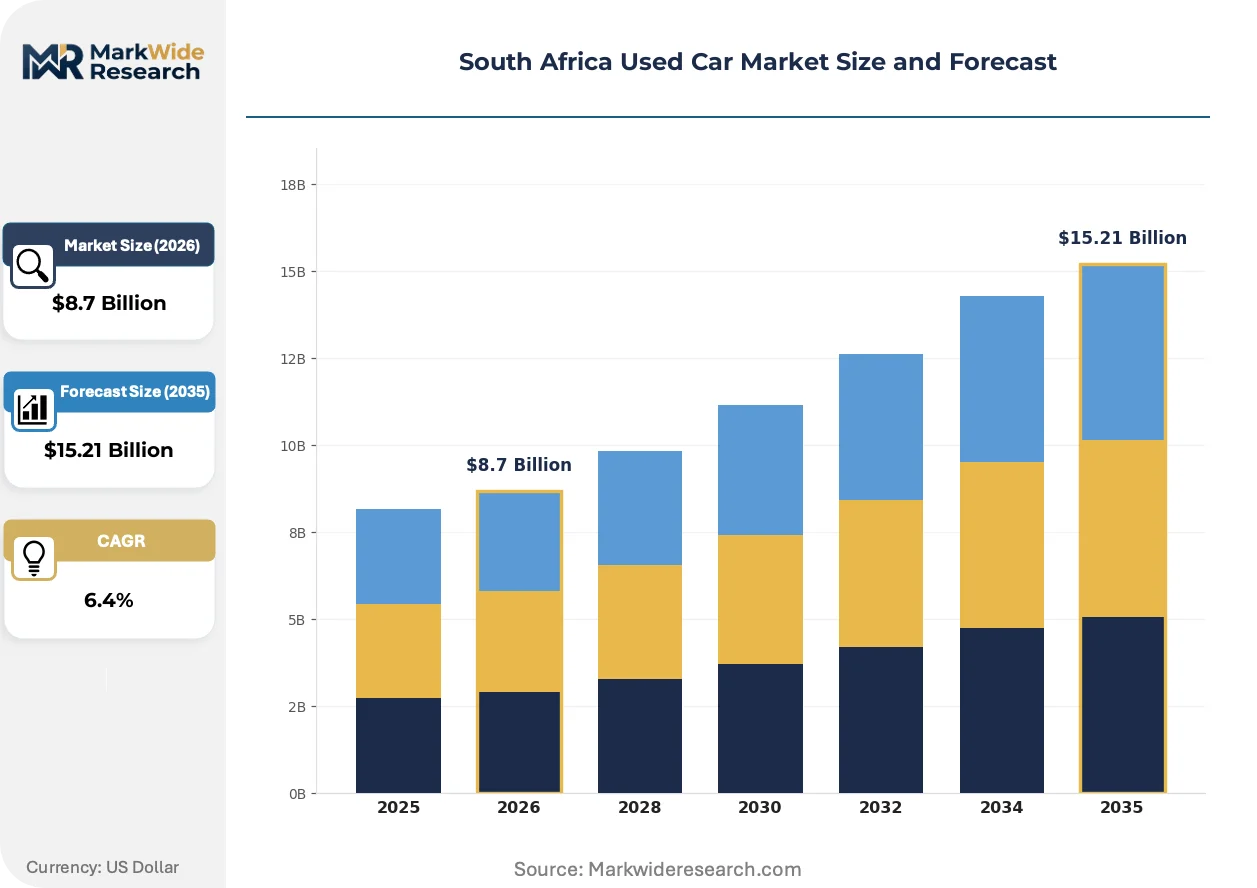
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, SUV, Hatchback, Coupe Fuel Type: Petrol, Diesel, Hybrid, Electric Age Category: 0-3 Years, 4-7 Years, 8-10 Years, Over 10 Years Sales Channel: Dealerships, Online Platforms, Private Sales, Auctions |
| Companies Covered | AutoTrader South Africa, WeBuyCars, Cars.co.za, Bidvest McCarthy, Motus, Barloworld Motor Retail, Avis Car Sales, Hertz Rent2Buy, InspectaCar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Used Car Market Trends and Innovations
Digital infrastructure is compressing transaction friction across South Africa's used car ecosystem, with verification technologies and financing modularization redefining how value moves between sellers and buyers.
Blockchain-based service history verification is decentralizing trust mechanisms that previously required physical inspection or dealer intermediation. Private sellers and distant buyers now transact directly through platforms that cryptographically validate maintenance records. This compression of verification costs is expanding the geographic radius of liquid markets beyond traditional auction clusters.
The National Road Traffic Act's roadworthiness certification mandate is tightening enforcement timelines and documentation standards. Workshops must now upload inspection results to centralized databases before transfer clearance. Gauteng-based wholesalers are investing in pre-certification inventory preparation to avoid transaction delays at transfer offices.
Buyers are unbundling the traditional dealership package, sourcing vehicles through discovery platforms while arranging finance and warranty separately. This disintermediation pressures full-service dealers to compete on component pricing rather than bundled convenience. The shift is most pronounced among digitally native purchasers in Johannesburg and Pretoria metropolitan areas.
South Africa Used Car Market Segmentation
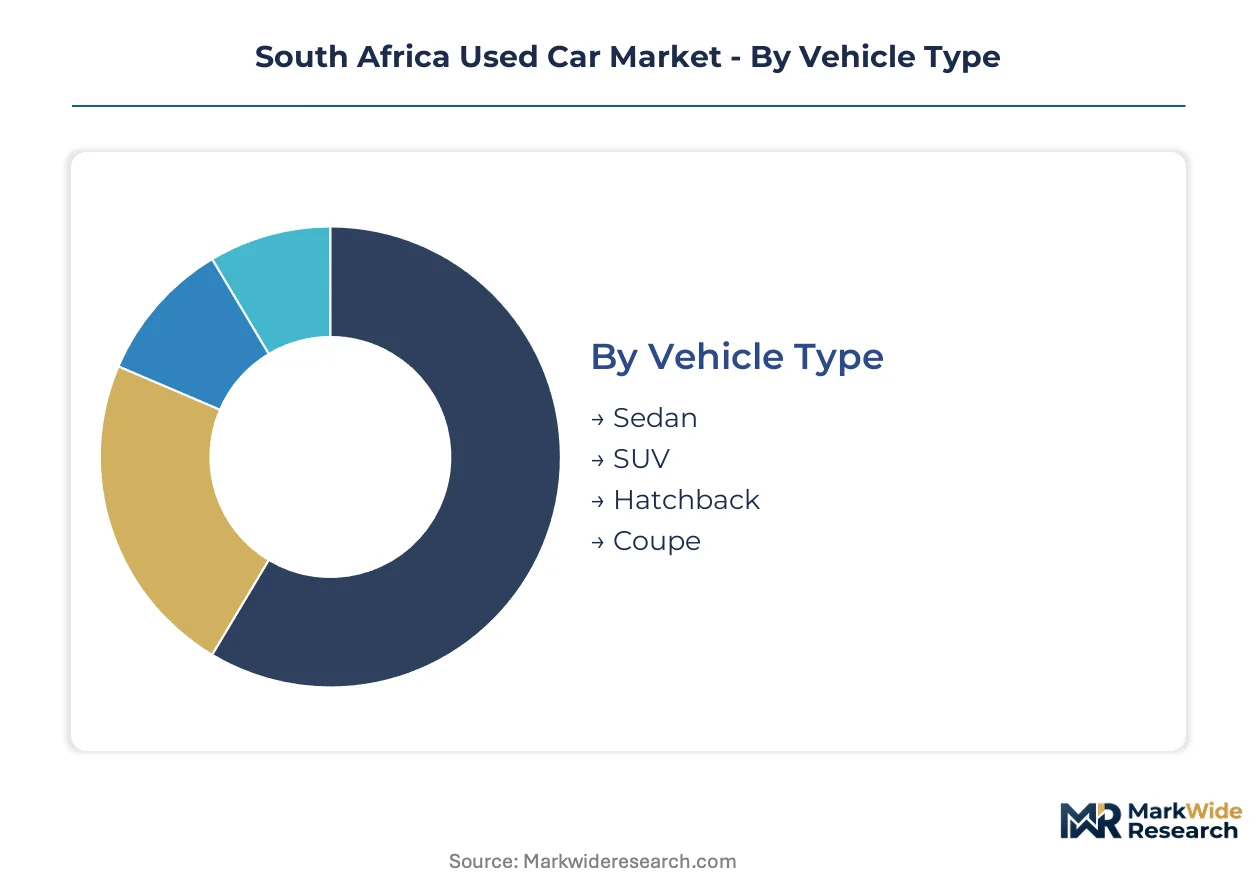
South Africa's used car market segments along four distinct dimensions that shape inventory sourcing, pricing power, and transaction velocity. Each category reflects different capital requirements, regulatory exposure, and buyer risk profiles that determine dealer strategy and platform economics.
Vehicle Type:
Capital intensity varies sharply across body styles, with SUVs requiring the highest floorplan financing and inspection infrastructure due to larger physical footprint and higher average transaction values.
- SUV:Body-on-frame and unibody configurations dominate family transportation demand. Dealers in Johannesburg and Pretoria concentrate inventory here to capture higher margins from suburban buyers prioritizing safety ratings and seating capacity. The segment absorbs disproportionate wholesale auction volume from fleet operators rotating ride-hailing vehicles.
- Hatchback:Compact three-door and five-door variants serve urban commuting and first-time buyer segments. Gauteng-based platforms move hatchbacks fastest due to parking constraints in dense metropolitan areas and fuel efficiency priorities among cost-conscious purchasers.
- Sedan:Three-box configurations retain corporate fleet heritage but face declining private demand as buyer preference shifts toward elevated driving positions.
- Coupe:Two-door performance and luxury variants occupy niche volume with specialized buyer pools and longer inventory holding periods.
Most installed capacity flows through SUV. Expansion is steepest in Hatchback.
Fuel Type:
Procurement patterns diverge based on regulatory exposure and total cost of ownership calculations across South Africa's uneven charging infrastructure and fuel price volatility.
- Petrol:Internal combustion engines with spark ignition dominate transaction volume due to lower purchase price and widespread service network coverage. Port Elizabeth and East London dealers source petrol inventory most aggressively given limited hybrid servicing capability in secondary metros.
- Diesel:Compression ignition engines command premium pricing in commercial and long-distance applications but face obsolescence risk from pending emissions testing protocol expansions in urban centers. The Road Traffic Management Corporation's evolving roadworthiness standards threaten residual values for older diesel stock.
- Hybrid:Parallel and series hybrid configurations bridge infrastructure gaps for buyers seeking efficiency without range anxiety.
- Electric:Battery electric vehicles remain thinly traded due to sparse charging networks and battery degradation uncertainty in secondary ownership.
Petrol holds the dominant transaction share. Hybrid is climbing the fastest as charging infrastructure gradually extends beyond Gauteng.
Age Category:
Inventory aging determines financing eligibility, warranty attach rates, and roadworthiness certification complexity under the National Road Traffic Act.
- 0-3 Years:Late-model vehicles with manufacturer warranty remainder and documented service histories. Ride-hailing fleet rotation injects concentrated supply into wholesale channels, compressing price discovery cycles for certified pre-owned programs.
- 4-7 Years:Depreciation-stabilized assets balancing affordability with feature content. Eastern Cape penetration strategies target this bracket for first-time buyers building credit files through subscription-to-ownership conversion pilots.
- 8-10 Years:Higher maintenance exposure and narrower finance access from National Credit Regulator constraints on instalment sale agreements for older collateral.
- Over 10 Years:Cash-transaction dominance with minimal formal financing penetration and elevated roadworthiness certification failure rates.
Transaction liquidity concentrates in 0-3 Years. Volume expansion is strongest in 4-7 Years as platform infrastructure penetrates secondary metros.
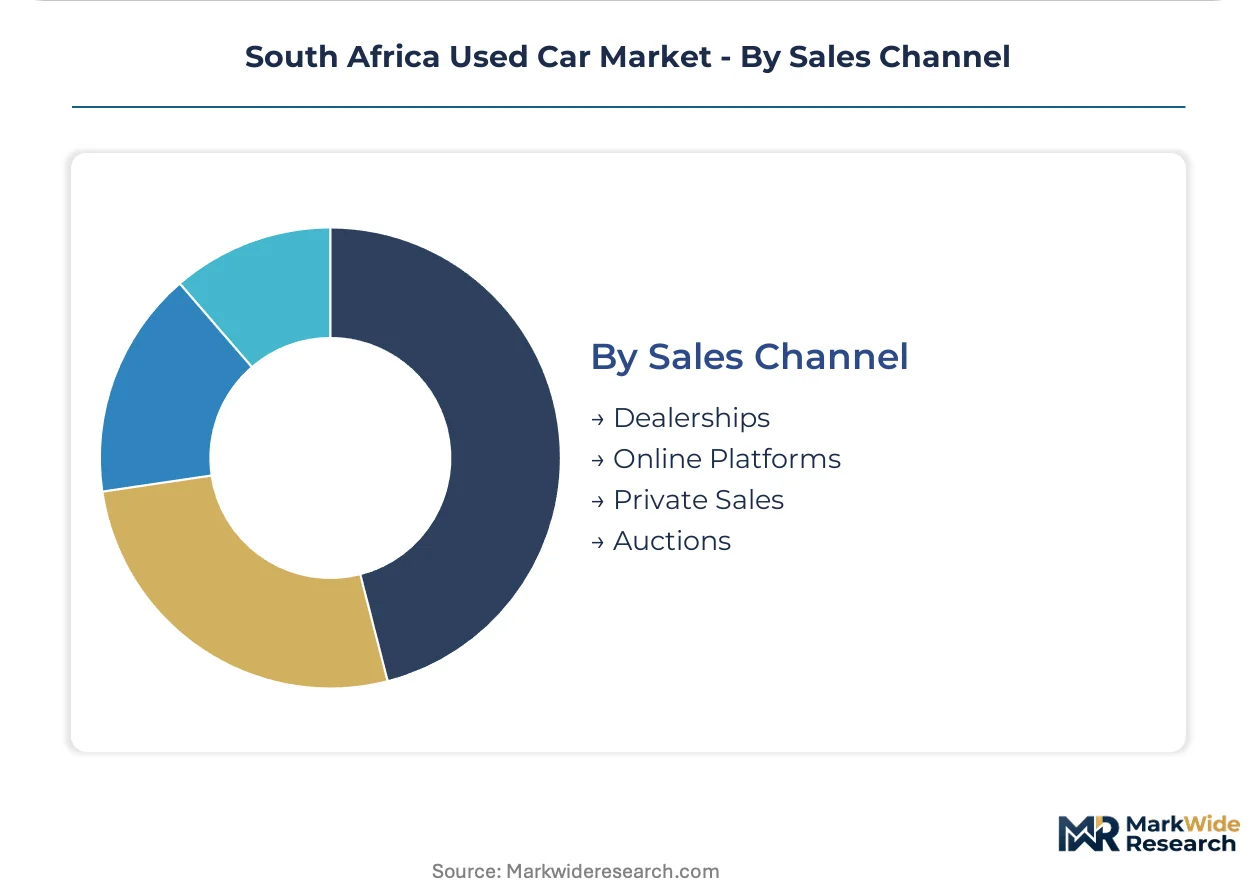
Sales Channel:
Channel selection dictates customer acquisition economics, inspection technology investment, and regulatory compliance burden around transfer documentation.
- Online Platforms:Digital discovery and transaction infrastructure with AI-powered damage assessment and blockchain-based service history verification. AutoTrader South Africa and WeBuyCars anchor this channel through lead-generation economics and high-volume inspection infrastructure.
- Dealerships:Full-service physical locations with captive finance integration and aftersales network attachment. Motus leverages backward integration into lending and service to defend margin position against platform disintermediation.
- Private Sales:Direct seller-to-buyer transactions with highest information asymmetry and odometer fraud exposure.
- Auctions:Wholesale velocity mechanisms concentrating in Johannesburg and Pretoria for fleet-dealer inventory transfer.
Dealerships retain the largest transaction share. Online Platforms are gaining share fastest as digital verification tools reduce distant-buyer risk perception.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's automotive retail infrastructure traces its formal structure to the post-1994 economic opening, when franchise dealer networks consolidated around Johannesburg and Pretoria to serve emerging middle-class vehicle demand. Gauteng's wholesale auction density remains the historical anchor of national price discovery.
Gauteng
Ride-hailing fleet rotation from Uber and Bolt operators injects late-model certified pre-owned stock into Johannesburg and Pretoria wholesale channels every 3-4 years. The Road Traffic Management Corporation's roadworthiness certification enforcement filters substandard inventory before transfer clearance at centralized licensing offices. Midrand and Centurion host the highest transaction velocity, with WeBuyCars and AutoTrader South Africa operating high-volume inspection infrastructure.
Western Cape
Subscription-to-ownership conversion pilots target first-time buyers in Cape Town's metropolitan area, building credit files for eventual vehicle purchase. National Credit Regulator caps on instalment sale agreements shape how dealerships structure balloon payment products for subprime borrowers. Stikland and Montague Gardens industrial zones concentrate refurbishment workshops preparing inventory for roadworthiness certification.
KwaZulu-Natal
Durban's port logistics position creates import exposure for replacement parts, inflating repair costs for older vehicles and narrowing economically viable resale age ranges. The National Road Traffic Act's evolving emissions testing protocols threaten diesel inventory values in the eThekwini metropolitan jurisdiction. Pinetown and Springfield host secondary wholesale activity serving coastal dealer networks.
Eastern Cape
Port Elizabeth and East London exhibit lower dealer density relative to population, creating whitespace for platform expansion into underserved markets. Petrol vehicle procurement dominates given limited hybrid servicing capability in these secondary metros. The province's manufacturing heritage around Uitenhage sustains technical labor pools for vehicle assessment and reconditioning.
Free State
Bloemfontein's central geographic position supports regional distribution logistics for inventory moving between coastal and inland markets. Cash-transaction dominance characterizes the over-10-years vehicle segment, with minimal formal financing penetration. The Mangaung metropolitan area serves as a consolidation point for auction-sourced stock entering smaller town markets.
South Africa Used Car Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and captive finance integration. The market structures around three distinct tiers: high-volume inspection platforms, full-service dealer groups with backward integration into lending, and digital discovery engines controlling lead-generation economics. Consolidation pressure runs through M&A activity among dealer groups and technology licensing partnerships between platforms and verification service providers.
Within the platform-centric tier, AutoTrader South Africa and WeBuyCars exemplify divergent approaches to transaction velocity—one controlling digital discovery traffic, the other leveraging high-volume inspection infrastructure for rapid inventory turnover. Motus occupies a position representing full-service dealer archetypes, anchoring competitive position through backward integration into captive finance and aftersales networks. These three entities collectively illustrate how certification depth, financing access, and digital reach define margin capture across the ecosystem.
| Leading Market Players |
|---|
| AutoTrader South Africa |
| WeBuyCars |
| Cars.co.za |
| Bidvest McCarthy |
| Motus |
| Barloworld Motor Retail |
| Avis Car Sales |
| Hertz Rent2Buy |
| InspectaCar |
| Others |
Pricing and Supply Chain Analysis
Certification-grade bifurcation between roadworthiness-verified inventory and uncertified private-sale vehicles manifests in parallel pricing ladders and sourcing strategies across South Africa's used car ecosystem. Premium-tier certified pre-owned stock commands financing eligibility and warranty attach rates that commodity-grade inventory cannot access, while supply chain investments concentrate in Gauteng's auction infrastructure where fleet rotation velocity determines inventory availability.
Pricing Analysis
Three-tier pricing structure across certified pre-owned, dealer-retail, and private-party transactions anchors South Africa's used car market. Price differentiation rests on roadworthiness certification status under the National Road Traffic Act and documented service history completeness. Cost compression in private-party channels is intensifying because digital platforms reduce information asymmetry, forcing traditional dealers to unbundle warranty and financing components. First-time buyers in Eastern Cape and Free State exhibit highest price sensitivity, while Gauteng-based fleet purchasers show lowest elasticity due to depreciation tax shield value.
Supply Chain Analysis
Freight costs from Durban's port inflate replacement part expenses for older vehicles, compressing economically viable resale age ranges across inland provinces. Inventory sourcing draws from Japan, South Korea, and domestic fleet rotation programs, with ride-hailing operator renewals feeding concentrated late-model supply into Johannesburg and Pretoria wholesale channels. Single-source vulnerability sits with WeBuyCars' inspection infrastructure dominance in Gauteng. Distribution runs through physical auction clusters in Midrand and Centurion, with digital platforms capturing growing downstream share via blockchain-verified remote transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's used car market offers margin expansion through certification infrastructure investment and captive finance integration, as regulatory enforcement filters substandard inventory and creates tiered pricing power for compliant operators.
For Market Incumbents: Acquire high-volume inspection infrastructure and certified assessor training programs to defend against platform disintermediation. Motus and Bidvest McCarthy should deepen backward integration into captive finance products permitted under National Credit Regulator guidelines, while accelerating blockchain-based service history verification to match WeBuyCars' transaction velocity. Road Traffic Management Corporation enforcement intensity on odometer fraud detection represents the critical regulatory threat requiring forensic capability investment. For New Entrants and Emerging Players: Launch via subscription-to-ownership conversion pilots targeting Eastern Cape's underpenetrated Port Elizabeth and East London markets. Whitespace exists in 4-7 year age category financing for first-time buyers excluded from traditional instalment sale agreements. Go-to-market positioning should emphasize petrol vehicle specialization given limited hybrid servicing capability in secondary metros, with balloon payment structures compliant with National Credit Regulator caps. For Investors and Strategic Acquirers: Asymmetric upside sits with platform-technology providers enabling remote verification and digital transaction infrastructure across the analysis window. Long-term viability favors entities combining inspection scale with finance integration, as disintermediation pressures pure discovery platforms. Monitor Road Traffic Management Corporation emissions testing protocol expansion timelines as the inflection signal for diesel inventory value exposure in urban centers.| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Service History Verification | Decentralizes trust mechanisms beyond physical inspection requirements, enabling distant buyer-seller transactions. |
| Captive Finance Integration | Allows balloon payment structuring under National Credit Regulator guidelines, defending margin against platform unbundling. |
| Certified Assessor Training Scale-Up | Addresses technician scarcity bottlenecks constraining WeBuyCars-tier inspection throughput expansion. |
| Eastern Cape Platform Expansion | Captures whitespace in Port Elizabeth and East London where dealer density lags population. |
| Pre-Certification Inventory Preparation | Avoids transaction delays at Gauteng licensing offices under tightened Road Traffic Act enforcement. |
Research Methodology
Multiple input streams — primary interviews with dealership operations directors, fleet procurement managers at ride-hailing operators, and Road Traffic Management Corporation enforcement officials; secondary validation through vehicle registration databases, auction transaction records, and National Credit Regulator filing disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder consultations encompassed wholesale auction operators, captive finance underwriters, and platform technology architects across Gauteng, Western Cape, and Eastern Cape provinces.
Data-stream reconciliation across the projection horizon applied segment-level modeling across vehicle type, fuel category, age bracket, and sales channel dimensions. CAGRs were derived from historical transaction velocity patterns and fleet rotation cycle analysis, with specific incorporation of ride-hailing operator replacement schedules and roadworthiness certification enforcement timelines as demand-side and supply-side forecast inputs respectively.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated emissions testing protocol adoption or National Credit Regulator instalment sale cap adjustments. Forecasts reflect documented assumptions regarding fleet rotation continuity and digital platform penetration rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Used Vehicles
United Arab Emirates Used Car Market
Used Vehicles
United States Used Car Market
Used Vehicles
Vietnam Used Car Market
Used Vehicles
Vintage Car Market
Used Vehicles
Singapore Used Car Market
Used Vehicles
Europe Used Car Market
Used Vehicles
South Korea Used Car Market
Used Vehicles
Brazil Used Car Market
Used Vehicles
Finland Used Car Market
Used Vehicles
Global Online Second-Hand Car Trading Service Market
Used Vehicles
Thailand Used Car Market
Used Vehicles
Spain Used Car Market
Used Vehicles
Japan Used Car Market
Used Vehicles
Malaysia Used Car Market
Used Vehicles
Italy Used Car Market
Used Vehicles
France Used Car Market