
 Asia-Pacific Marine Communication Systems Market | 2026-2036
Asia-Pacific Marine Communication Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Marine Communication Systems Market Outlook
Commercial shipping operator consolidation is expanding procurement leverage for integrated bridge systems. Furuno Electric Co., Ltd. anchors Japanese domestic supply through deep manufacturing scale in radar and VHF equipment. Kongsberg Maritime AS competes across the Nordic-Asia technology corridor with advanced integrated vessel control platforms. Icom Inc. specializes in portable and fixed-mount radio solutions for fishing and coastal patrol segments.
Asia-Pacific marine communication systems encompass shipboard equipment for voice, data, and distress signaling across radio frequency, satellite, and optical fiber channels, typically operating within ITU maritime frequency bands from 156 MHz to 162 MHz for VHF and L-band to Ku-band for satellite links. These systems enable collision avoidance, fleet coordination, and regulatory compliance across open-ocean and coastal waterways. Satellite communication commands premium positioning due to mandatory GMDSS requirements for distress alerting beyond coastal coverage zones. Radio frequency technology retains volume dominance across fishing vessels and coastal commercial fleets where cost sensitivity shapes procurement. Optical fiber backbones are penetrating newbuild cruise and offshore vessels as bandwidth demands for remote diagnostics and crew welfare connectivity intensify.
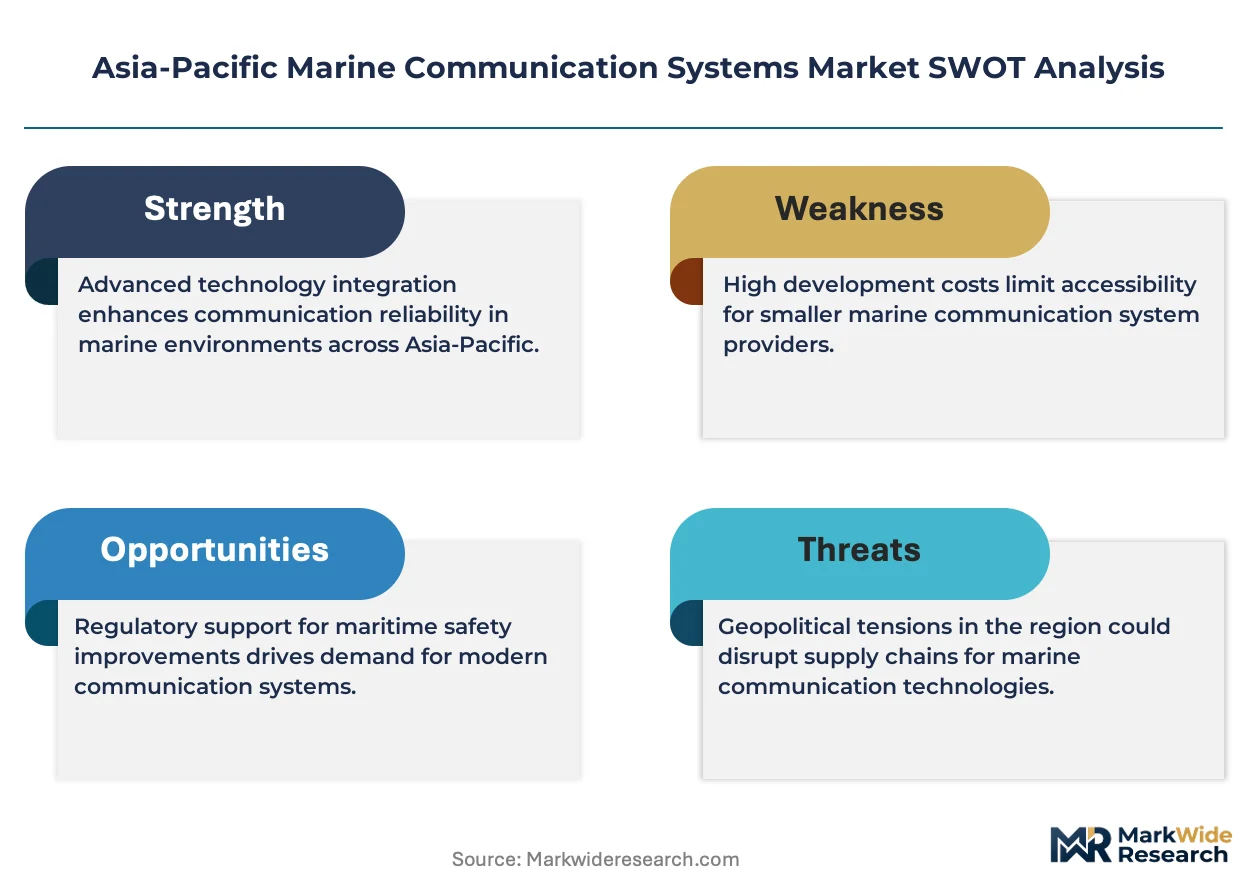
Japan's Ministry of Internal Affairs and Communications enforces radio equipment type certification that shapes product entry timelines for foreign manufacturers. South Korea's MFDS maritime safety standards and China's MIIT radio frequency allocation rules collectively determine equipment compatibility across the region's busiest shipping lanes. Australia's AMSA mandates GMDSS equipment carriage that drives recurring replacement demand across its coastal and offshore fleet. Stakeholders must monitor evolving spectrum reallocation decisions and flag-state harmonization pressures that will reshape product roadmaps and certification investments.
Market Dynamics
Japan's Ministry of Internal Affairs and Communications has tightened radio equipment type certification timelines, compressing product entry windows for foreign manufacturers and forcing accelerated R&D cycles across the Asia-Pacific marine communication supply base.
Growth Catalysts
- GMDSS Mandate Expansion:Australia's AMSA now requires distress alerting equipment carriage across extended offshore zones, driving replacement demand for satellite-linked safety systems in the coastal fleet.
- BeiDou Integration Requirements:China's MIIT radio frequency allocation rules mandate domestic satellite compatibility for all newbuild vessels, creating captive demand for dual-band communication terminals.
- Shipbuilding Cluster Concentration:South Korea's Ulsan and Geoje shipyards specify integrated bridge communication suites as standard, pulling through high-value equipment procurement at volume.
Market Restraints
- Semiconductor Input Volatility:RF component fabrication depends on specialized gallium nitride substrates concentrated in Taiwanese foundries, exposing lead times to geopolitical supply friction.
- Regulatory Fragmentation:Divergent certification pathways between Japan's MIC type approval and South Korea's MFDS maritime safety standards force redundant testing investments for pan-regional product lines.
- Ku-Band Subscription Costs:Monthly satellite bandwidth fees for fleet broadband exceed operational budgets of small-scale fishing cooperatives, capping addressable market penetration.
Strategic Opportunities
- Vietnam Coastal Patrol Modernization:Maritime law enforcement agencies are procuring portable VHF and satellite distress units under national security budget allocations, opening public-sector demand.
- Optical Fiber Convergence:Newbuild cruise vessels are integrating fiber backbones with RF distribution networks, enabling unified crew welfare and navigation data infrastructure.
- Indonesia Archipelago Coverage Gaps:The nation's 17,000-island geography creates persistent dead zones where low-earth-orbit satellite terminals address unmet connectivity needs for inter-island cargo fleets.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized microwave design expertise for maritime frequency bands concentrates in Japanese and South Korean defense contractors, constraining vendor expansion.
- Legacy Analog System Integration:Retrofitting digital GMDSS terminals onto aging coastal freighters requires custom interface development, extending deployment timelines and service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Marine Communication Systems Market |
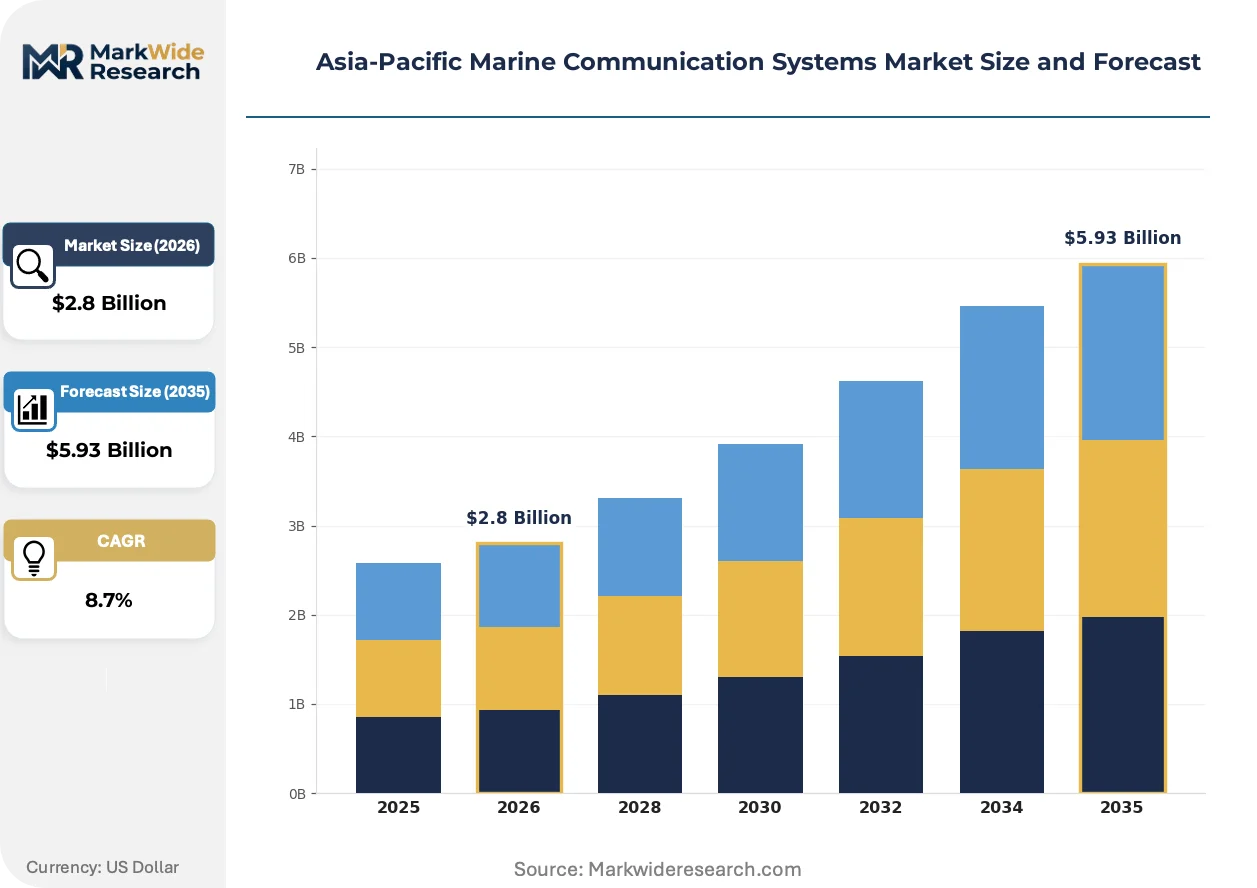
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cruise Control Systems, Navigation Systems, Satellite Communication, Vessel Tracking Systems Technology: Radio Frequency, Optical Fiber, Ethernet, Satellite Based Systems Application: Commercial Shipping, Recreational Boating, Fishing Vessels, Offshore Operations End User: Shipping Companies, Government Agencies, Fishing Industries, Marine Research Institutes |
| Companies Covered | Iridium Communications Inc., Icom Inc., Furuno Electric Co., Ltd., SAMYUNG, HAIYANG, Japan Radio Co., Ltd., Garmin Ltd., Kongsberg Maritime AS, Inmarsat Global Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Marine Communication Systems Market Strategic Shifts
Software-defined radio architectures are absorbing hardware functions across the Asia-Pacific marine communication stack, compressing equipment form factors while expanding frequency agility for multi-band compliance.
Software-defined radio is absorbing discrete component functions previously handled by dedicated VHF and HF transceivers, collapsing multiple hardware modules into reprogrammable chipsets. Japanese commercial fishing fleets and South Korean coast guard operators are adopting these platforms fastest, drawn by reduced spare parts inventory and over-the-air configuration updates. This convergence is absorbing maintenance revenue from traditional equipment service contracts, forcing manufacturers toward software subscription models.
China's MIIT BeiDou integration requirements are mandating dual-mode satellite compatibility in all certified marine terminals, effectively embedding domestic navigation infrastructure into regional communication standards. Foreign equipment suppliers must redesign RF front ends and protocol stacks to accommodate these specifications, adding six to nine months to product launch timelines. The shipbuilding export segment faces the steepest compliance burden, as Chinese-flagged newbuilds destined for international owners still require BeiDou capability.
Fleet operators are consolidating procurement authority at the holding-company level, bypassing traditional ship-manager intermediaries to negotiate directly with communication system integrators. This concentration is disintermediating regional distributors who previously captured margin on equipment resale and installation services. The pattern is most pronounced among Singapore-based container line headquarters, where integrated bridge system tenders now span fifty-vessel fleets rather than single-ship transactions.
Asia-Pacific Marine Communication Systems Market Segmentation
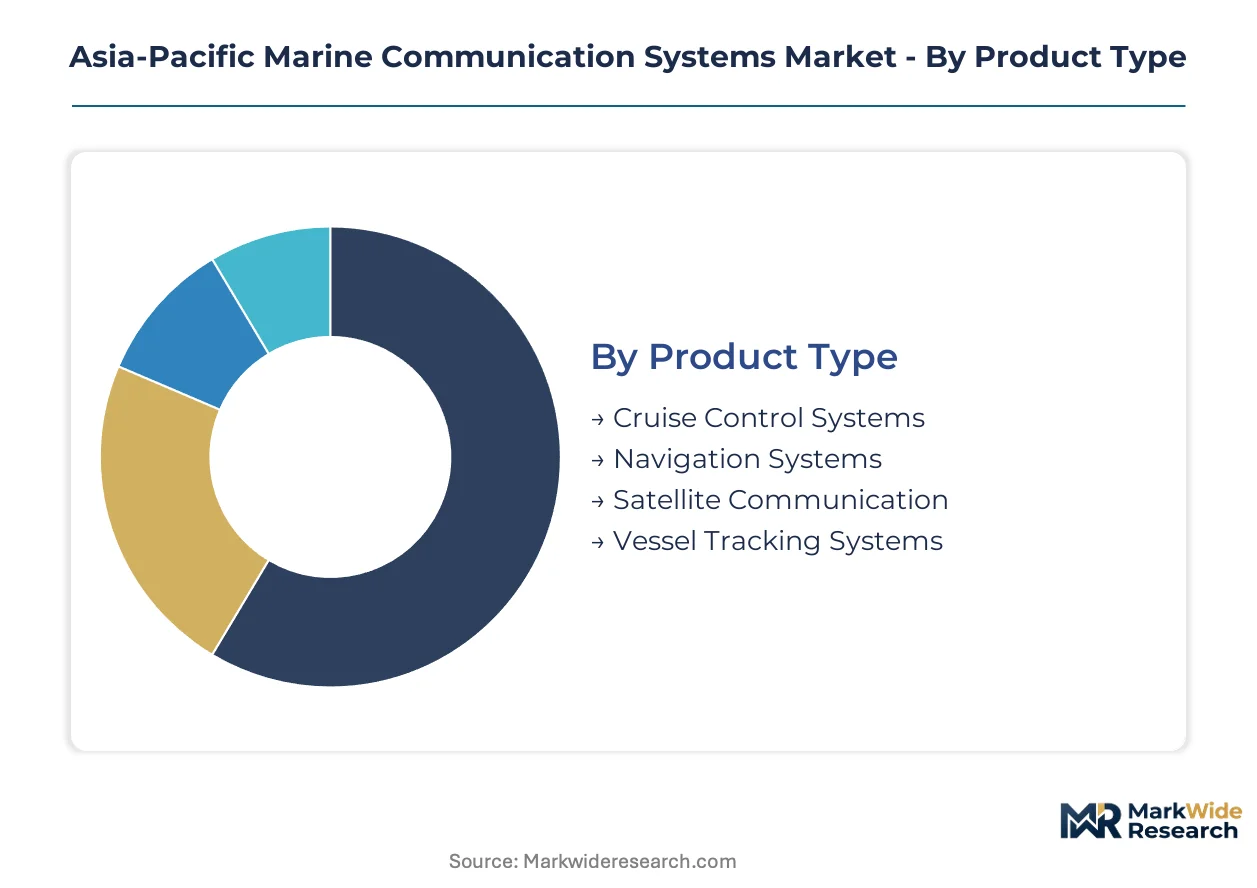
Marine communication procurement in Asia-Pacific fragments sharply across vessel categories and operational profiles. Buyers prioritize bandwidth density, regulatory compliance breadth, and integration complexity according to fleet scale and trading patterns.
Product Type:
Capital allocation splits between safety-mandated distress systems and discretionary connectivity upgrades.
- Navigation Systems:Integrated bridge platforms combining radar, ECDIS, and AIS transponders dominate newbuild specifications. South Korean shipyards at Ulsan and Geoje bundle these suites as standard, pulling through multi-million-dollar contracts per vessel.
- Satellite Communication:Dual-band L-band and Ku-band terminals enable fleet broadband and GMDSS distress alerting beyond coastal coverage. Australia's AMSA mandate expansion across extended offshore zones accelerates replacement cycles in the coastal fleet.
- Vessel Tracking Systems:AIS transponders and LRIT reporting hardware satisfy flag-state monitoring requirements.
- Cruise Control Systems:Autopilot and dynamic positioning interfaces integrate with communication backbones for coordinated fleet maneuvering.
Volume sits with Navigation Systems; growth tilts toward Satellite Communication.
Technology:
Signal propagation methods diverge by bandwidth requirements and electromagnetic environment constraints.
- Radio Frequency:VHF and HF transceivers operating in ITU maritime bands from 156 MHz to 162 MHz retain dominance across fishing and coastal commercial fleets. Japan's MIC type certification timelines compress product entry windows for foreign manufacturers.
- Satellite Based Systems:Geostationary and low-earth-orbit constellations address coverage gaps in Indonesia's 17,000-island archipelago. Monthly Ku-band subscription fees exceed operational budgets of small-scale fishing cooperatives, capping penetration.
- Optical Fiber:Backbone infrastructure penetrates newbuild cruise and offshore vessels as bandwidth demands intensify.
- Ethernet:IP-based distribution networks unify crew welfare and navigation data on unified LAN architectures.
Radio Frequency commands installed base; Optical Fiber climbs the fastest.
Application:
Operational risk profiles and regulatory exposure shape equipment specification intensity.
- Commercial Shipping:Container lines and bulk operators specify integrated bridge systems spanning fifty-vessel fleets. Singapore-based headquarters consolidate procurement authority, disintermediating regional distributors.
- Offshore Operations:Drillships and production platforms demand redundant communication paths for dynamic positioning safety. China's MIIT BeiDou integration requirements mandate dual-mode satellite compatibility, extending product launch timelines.
- Fishing Vessels:Cost-sensitive operators prioritize portable VHF and basic distress alerting.
- Recreational Boating:Yacht owners seek crew welfare connectivity and entertainment bandwidth.
Commercial Shipping anchors revenue concentration; Offshore Operations shows steepest expansion trajectory.
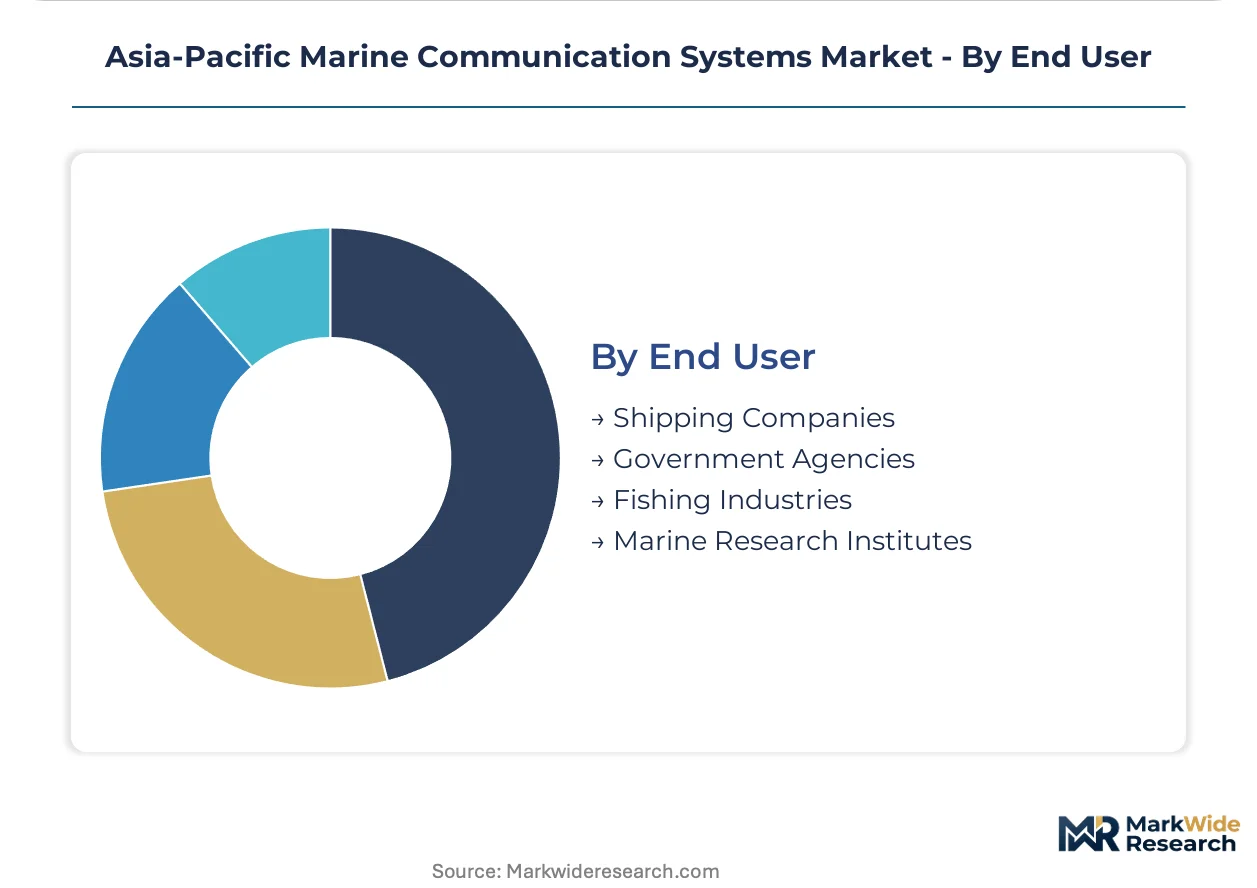
End User:
Budget authority and compliance urgency vary across public and private procurement channels.
- Shipping Companies:Fleet operators negotiate directly with system integrators, bypassing ship-manager intermediaries. Consolidated holding-company procurement expands leverage for volume discounts on integrated suites.
- Government Agencies:Vietnam's maritime law enforcement agencies procure portable VHF and satellite distress units under national security budget allocations. Public-sector tender processes extend sales cycles but offer multi-year contract visibility.
- Fishing Industries:Cooperative purchasing structures limit individual transaction scale.
- Marine Research Institutes:Scientific vessels require specialized data telemetry and remote sensor connectivity.
Shipping Companies dominate transaction volume; Government Agencies represent the fastest-growing procurement channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial shipping procurement concentrates in East Asian shipbuilding clusters, while Southeast Asian archipelagic geography drives specialized connectivity demand. Regulatory divergence across Japan, South Korea, and China fragments certification pathways and shapes equipment specification.
Japan
Domestic fishing fleets and coastal patrol operators sustain steady replacement demand for VHF and radar equipment. The Ministry of Internal Affairs and Communications enforces radio equipment type certification that compresses entry windows for foreign manufacturers. Tokyo and Osaka house concentrated electronics manufacturing that feeds component supply into regional marine communication assembly.
South Korea
Ulsan and Geoje shipyards specify integrated bridge communication suites as standard equipment on newbuild vessels. The MFDS maritime safety standards govern equipment compatibility across the coastal fleet and offshore operations. Busan port authority procurement drives recurring upgrades for pilotage and vessel traffic management infrastructure.
China
BeiDou integration requirements from MIIT mandate dual-mode satellite compatibility in all certified marine terminals for newbuild vessels. Yangtze River Delta shipyards face compliance burden for export vessels requiring both domestic and international navigation standards. Shanghai and Dalian clusters concentrate system integration capacity for integrated bridge platforms.
Australia
AMSA mandates GMDSS equipment carriage across extended offshore zones, accelerating replacement cycles in the coastal fleet. Perth and Fremantle serve offshore oil and gas operations demanding redundant communication paths for dynamic positioning safety. Darwin port modernization expands VTS and coastal monitoring infrastructure procurement.
Indonesia
The 17,000-island archipelago creates persistent coverage gaps where low-earth-orbit satellite terminals address unmet connectivity for inter-island cargo fleets. National maritime security budget allocations fund portable VHF and satellite distress units for law enforcement. Surabaya and Makassar anchor commercial shipping corridors with concentrated fleet coordination needs.
Asia-Pacific Marine Communication Systems Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and subscription service models. Market structure tilts toward consolidation at the integrated system level while component supply remains fragmented across specialized RF and satellite terminal vendors. Three archetypes dominate: Japanese electronics conglomerates with captive domestic distribution, Nordic-Asian system integrators targeting newbuild specifications, and satellite service operators leveraging constellation coverage advantages. Competitive moves center on certification pre-approval investments to compress regional entry timelines, and strategic partnerships with shipyard engineering departments to secure specification inclusion.
Within the Japanese domestic supply tier, Furuno Electric Co., Ltd. and Japan Radio Co., Ltd. anchor manufacturing scale for radar and VHF equipment. Kongsberg Maritime AS exemplifies the Nordic-Asia technology corridor approach with integrated vessel control platforms. Icom Inc. occupies a specialist position in portable and fixed-mount radio solutions. These named entities represent archetypal competitive positioning rather than exhaustive market coverage, with each exemplifying distinct geographic and technological segmentation strategies.
| Leading Market Players |
|---|
| Iridium Communications Inc. |
| Icom Inc. |
| Furuno Electric Co., Ltd. |
| SAMYUNG |
| HAIYANG |
| Japan Radio Co., Ltd. |
| Garmin Ltd. |
| Kongsberg Maritime AS |
| Inmarsat Global Limited |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between GMDSS-compliant integrated suites and basic VHF units splits Asia-Pacific marine communication procurement into parallel supply ecosystems. Premium-tier manufacturers capture margin through Japan's MIC type certification and South Korea's MFDS maritime safety standards, while commodity radio suppliers compete on gallium nitride substrate costs from Taiwanese foundries.
Pricing Analysis
Volume-margins concentrate at opposite ends of the equipment spectrum. Satellite communication terminals command premium positioning through mandatory GMDSS distress alerting requirements and Australia's AMSA mandate expansion, with price differentiation driven by dual-band L-band and Ku-band capability and BeiDou integration compliance. Pricing pressure intensifies in the VHF segment as gallium nitride RF component costs fluctuate with Taiwanese foundry capacity. Small-scale fishing cooperatives exhibit highest price sensitivity, while Singapore-based container lines demonstrate lowest sensitivity due to consolidated fleet procurement leverage.
Supply Chain Analysis
China's MIIT domestic-content requirements for BeiDou-compatible terminals are reshaping sourcing patterns for foreign equipment suppliers. Component fabrication draws from specialized gallium nitride substrate production in Taiwan, RF module assembly in Japan and South Korea, and final system integration at Yangtze River Delta and Ulsan shipbuilding clusters. Single-source vulnerability concentrates in Taiwanese gallium nitride foundries exposed to geopolitical supply friction. Distribution runs through shipyard engineering departments and direct holding-company procurement channels, disintermediating traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific marine communication systems are becoming a vertical-integration race, with manufacturers pursuing captive control over gallium nitride RF component supply to compress certification timelines and defend margin structures.
For Market Incumbents: Anticipate software-defined radio architectures displacing discrete hardware modules by accelerating in-house microwave design expertise acquisition. Defensive consolidation should prioritize backward integration into gallium nitride substrate sourcing to insulate against Taiwanese foundry volatility, while deepening shipyard engineering partnerships at Ulsan and Geoje to secure newbuild specification inclusion against Nordic-Asian system integrators. For New Entrants and Emerging Players: The price-point gap between premium integrated bridge suites and economy VHF units creates entry space for mid-tier software-defined platforms targeting Indonesia's inter-island cargo fleets and Vietnam's coastal patrol modernization programs. White-space concentration sits in low-earth-orbit satellite terminals addressing archipelago coverage gaps, with go-to-market traction through direct engagement with Singapore-based fleet operators consolidating procurement authority. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by Japanese electronics conglomerates seeking microwave design capability and Nordic-Asian system integrators pursuing Asia-Pacific newbuild specification share. Long-term viability favors targets with pre-approved certification across Japan's MIC type approval and South Korea's MFDS standards. The signal to monitor is BeiDou integration mandate expansion beyond Chinese-flagged vessels into international owner specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Radio Platform Development | Collapses discrete VHF and HF hardware into reprogrammable chipsets, reducing spare parts inventory for Japanese fishing fleets. |
| BeiDou Dual-Mode Certification Investment | Accelerates product entry timelines for Chinese newbuild specifications and export vessel compliance requirements. |
| Gallium Nitride Substrate Backward Integration | Captures RF component margin and insulates supply from Taiwanese foundry geopolitical exposure. |
| Shipyard Engineering Partnership Deepening | Secures integrated bridge suite inclusion at Ulsan and Geoje through collaborative newbuild specification design. |
| Low-Earth-Orbit Terminal Portfolio Expansion | Addresses Indonesia's 17,000-island coverage gaps and Vietnam's maritime law enforcement procurement. |
Study Parameters
Multi-period observation of shipyard newbuild specifications, regulatory certification timelines, and satellite constellation deployment anchored the trend analysis, supplemented by interviews with equipment procurement directors at Singapore-based container lines, shipyard engineering managers at Ulsan and Geoje, RF component specialists at Japanese defense contractors, and maritime safety regulators at Japan's MIC and South Korea's MFDS. Secondary validation incorporated customs trade data for marine communication equipment, SEC filings from listed satellite operators, ITU spectrum allocation records, and shipbuilding order databases. Bottom-up vessel fleet segmentation and top-down regional market sizing were triangulated against primary interview intelligence.
Input-output matrix modeling connected shipbuilding output forecasts, regulatory mandate implementation schedules, and satellite bandwidth pricing trajectories to equipment demand projections across the analysis window. Segmentation dimensions included product type, signal propagation technology, vessel application, and procurement channel authority. CAGRs were derived from regression analysis against historical replacement cycles and newbuild penetration rates, with sensitivity testing around gallium nitride supply constraints and spectrum reallocation decisions.
Underlying measurement precision varies by segment; satellite communication terminals and integrated bridge systems carry tighter precision than portable VHF units due to concentrated procurement visibility at holding-company level. Forecasts reflect assumptions regarding regulatory harmonization pressures, flag-state mandate expansion timelines, and constellation coverage deployment schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Navigation System Market
Marine
Hydrogen Ships Market
Marine
Marine Shackle Market
Marine
Boat Steering Systems Market
Marine
Boat Trolling Motor Market
Marine
Hybrid Fishing Boats Market
Marine
Offshore AUV and ROV Market
Marine
Marine AIS Monitoring System Market
Marine
Marine Auxiliary Engine Market
Marine
Military Marine Engine Market
Marine
Rigid Inflatable Boats (RIB) Market
Marine
Boat Ladder Market
Marine
Marine Diesel Engine Market
Marine
Global Submarine Market
Marine
Rescue Boats Market
Marine
China Controllable Pitch Marine Propeller Market