
 Automotive Rear Cross Traffic Alert System Market | 2026-2036
Automotive Rear Cross Traffic Alert System Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Rear Cross Traffic Alert System Market Analysis
ISO 26262 functional safety certification is rotating as the primary gatekeeper for component suppliers seeking OEM validation. Robert Bosch GmbH leverages its sensor fusion expertise to sustain dominance in integrated radar-camera modules. Continental AG anchors European supply relationships through localized production of ultrasonic and radar assemblies. Aptiv competes aggressively in North American programs with its scalable active system architectures.
Automotive rear cross traffic alert systems detect approaching vehicles from lateral directions during reversing maneuvers, typically employing 24 GHz or 77 GHz radar sensors with detection ranges of 20-30 meters and angular coverage exceeding 120 degrees. Their primary purpose is eliminating blind-spot collision risk in parking environments and driveway exits. Radar-based active systems command the largest installed base due to all-weather reliability and established cost curves, while integrated systems combining camera visual confirmation represent the fastest-expanding category as automakers consolidate ADAS compute platforms. OEM end users capture the dominant value share through factory-fit bundling with surround-view and automated parking packages.
NHTSA's ongoing rulemaking on rear visibility and rear automatic braking creates compliance-driven pull in the United States, while Euro NCAP's safety rating protocols directly incentivize rear cross traffic inclusion across European vehicle portfolios. Japan's Ministry of Land, Infrastructure, Transport and Tourism has incorporated similar rear-end collision avoidance expectations into domestic type approval guidelines. Stakeholders must monitor how software-defined vehicle architectures reshape sensor integration strategies and whether regional NCAP divergence creates certification fragmentation for global platform designs.
Market Dynamics
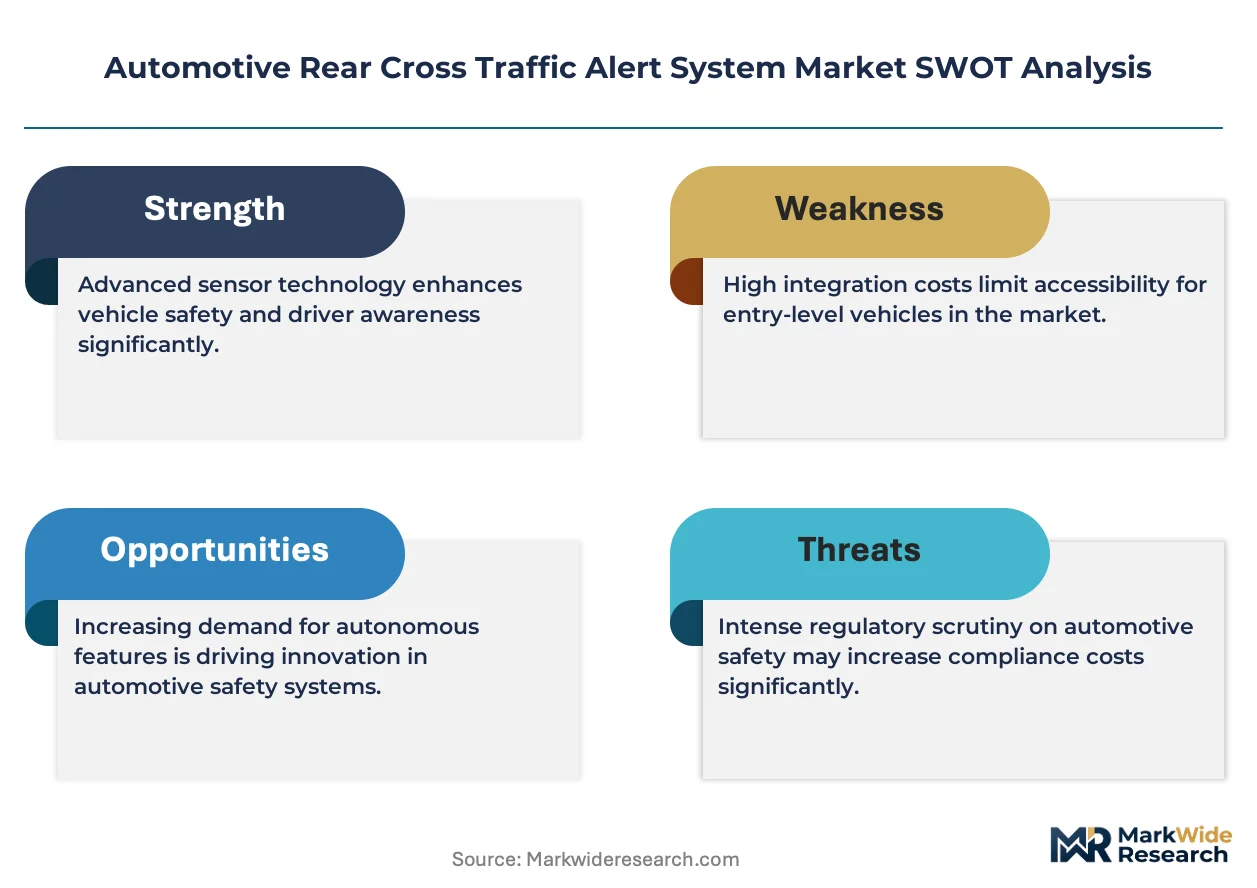
Euro NCAP's 2023 assessment protocol revisions now mandate rear cross traffic functionality for five-star safety ratings, forcing OEMs to accelerate factory-fit penetration across European vehicle portfolios and compressing aftermarket substitution windows.
Growth Catalysts
- Euro NCAP Rating Pressure:The European safety body's protocol changes eliminate top-tier ratings for vehicles lacking rear cross traffic capability, compelling luxury and mass-market OEMs to standardize these systems.
- Radar-Camera Sensor Fusion:Integration of 77 GHz radar with surround-view camera architectures reduces per-unit compute overhead while expanding detection reliability in adverse weather conditions.
- German Premium OEM Adoption:Mercedes-Benz, BMW, and Audi have expanded rear cross traffic alert to entry-level model variants, creating volume pull through tiered platform strategies.
Market Restraints
- Semiconductor Input Volatility:Radar MMIC and image signal processor shortages continue disrupting sensor module production schedules, particularly for 24 GHz legacy architectures.
- Supplier Concentration in Bavaria:Three German Tier-1 suppliers control approximately 60% of European radar assembly capacity, creating geographic vulnerability to regional logistics disruptions.
- Ultrasonic Substitution Threat:Low-cost parking assist systems using pure ultrasonic arrays compete for price-sensitive segments in emerging markets, limiting radar-based system expansion.
Strategic Opportunities
- India PLI Scheme Eligibility:Component localization for rear cross traffic sensors qualifies under India's automotive component production-linked incentive framework, reducing import duty exposure.
- Software-Defined Vehicle Convergence:Centralized ADAS compute platforms enable over-the-air feature activation, transforming hardware sales into recurring software revenue streams.
- NHTSA Rear Automatic Braking Mandate Trajectory:Pending US rulemaking on rear collision avoidance creates preemptive specification demand among Detroit Three OEMs preparing compliance pathways.
Industry Challenges
- ISO 26262 ASIL-D Certification Timeline:Functional safety validation for radar-fusion systems requires 18-24 month development cycles, constraining supplier response to sudden OEM specification changes.
- Legacy CAN Bus Integration Friction:Older vehicle architectures lack bandwidth for real-time rear cross traffic data streams, forcing expensive gateway module retrofits for model refreshes.
- Embedded Software Talent Scarcity:Shortages of functional safety engineers and radar signal processing specialists extend R&D timelines and inflate compensation costs across European development centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Rear Cross Traffic Alert System Market |
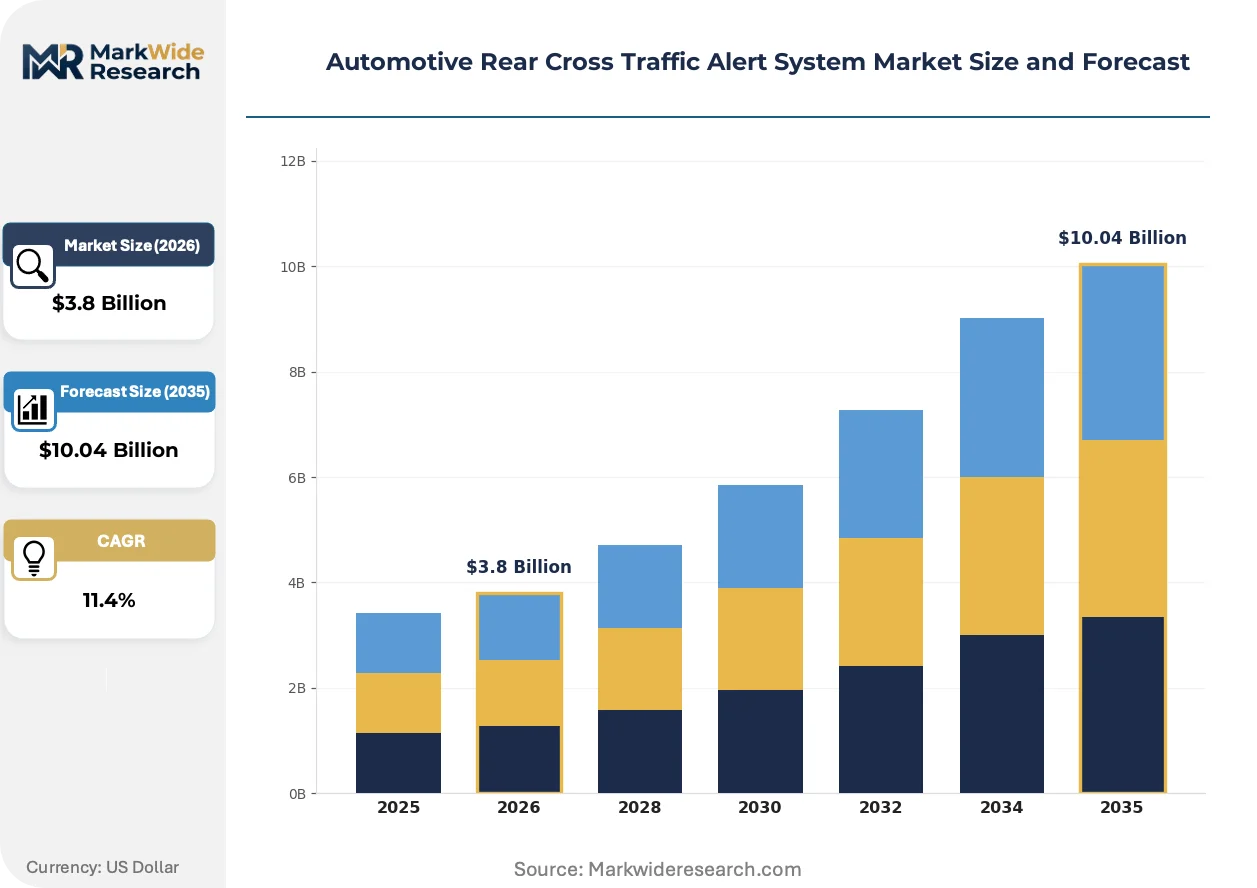
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Radar, Ultrasonic, Camera, Lidar End User: OEMs, Aftermarket Providers, Fleet Operators, Insurance Companies Technology: Active Systems, Passive Systems, Hybrid Systems, Integrated Systems Vehicle Type: SUV, Sedan, Hatchback, Pickup |
| Companies Covered | Aptiv, Magna International Inc., Robert Bosch GmbH, Infineon Technologies AG, Autoliv Inc., Continental AG, Valeo, ZF Friedrichshafen AG, DENSO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Rear Cross Traffic Alert System Market Emerging Trajectories
Rear cross traffic alert technology is consolidating around centralized perception stacks, with edge-based sensor processing giving way to domain controller architectures that pool computational resources across multiple ADAS functions.
4D imaging radar is displacing conventional 3D radar modules in premium vehicle programs, adding elevation measurement to range, azimuth, and Doppler data. Audi and BMW specification teams have adopted 4D radar for 2024 model year platforms, enabling single-sensor rear cross traffic detection without camera dependency. This displacement is compressing the addressable market for discrete ultrasonic parking sensors in the C-segment and above.
Japan's Ministry of Land, Infrastructure, Transport and Tourism has incorporated rear cross traffic performance expectations into amended safety regulations effective 2025, extending Euro NCAP's regulatory template to Asian type approval frameworks. Domestic OEMs Toyota and Honda are accelerating integration of standardized warning interfaces to satisfy homologation requirements without regional variant proliferation. The policy shift most affects kei-car manufacturers previously exempt from full ADAS mandates.
Fleet procurement of rear cross traffic systems is concentrating through leasing channel bundling rather than discrete option selection. Enterprise fleet managers at rental and corporate mobility providers negotiate ADAS package inclusion at fleet-wide scale, bypassing retail consumer choice architecture. This behavioral shift is most visible in Germany's commercial fleet segment, where operational liability reduction drives standardized safety specification across vehicle classes.
Automotive Rear Cross Traffic Alert System Market Segmentation
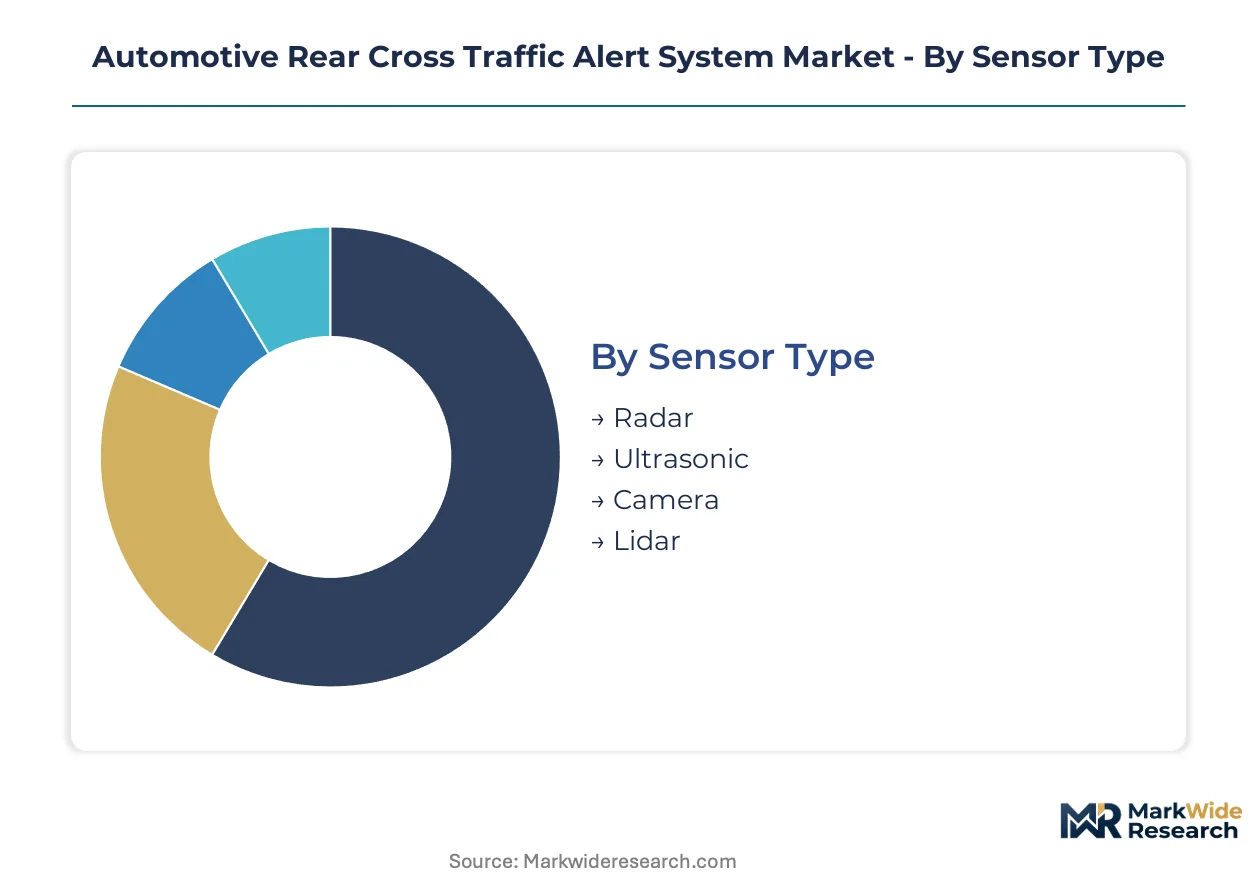
Rear cross traffic alert systems fragment across sensor modalities, integration architectures, and customer procurement patterns. Channel strategy varies sharply between factory-fit bundling and aftermarket retrofit paths. Understanding these segment boundaries clarifies where component suppliers compete versus where system integrators capture value.
Sensor Type:
Radar and ultrasonic modules flow predominantly through Tier-1 OEM supply contracts, while camera and lidar variants increasingly route through ADAS platform integrators consolidating multiple functions.
- Radar:77 GHz and 24 GHz modules dominate factory installations due to all-weather detection reliability and established automotive qualification pathways. German premium OEMs specify radar-first architectures for their volume model lines, compressing adoption timelines for competing sensor types.
- Ultrasonic:Lower-cost arrays serve price-sensitive vehicle segments and aftermarket parking assist retrofits. Indian and Southeast Asian OEMs favor ultrasonic for entry-level hatchbacks where radar unit economics prove prohibitive.
- Camera:Surround-view camera integration enables visual confirmation overlays, typically bundled with premium infotainment packages.
- Lidar:Solid-state units remain confined to luxury flagship programs and robotaxi development fleets.
By volume, radar leads. By growth pace, camera is expanding most quickly as automakers consolidate perception stacks.
End User:
Cost tier and procurement scale separate these customer groups more than functional requirements.
- OEMs:Factory-fit integration demands ISO 26262 ASIL-D certification and multi-year platform planning cycles. European and Japanese OEMs now specify rear cross traffic as standard equipment across model tiers to satisfy NCAP protocols.
- Fleet Operators:Enterprise leasing channels negotiate fleet-wide ADAS bundling to reduce liability exposure. German corporate mobility providers drive standardized specification across vehicle classes.
- Aftermarket Providers:Retrofit installations face bandwidth constraints on legacy CAN bus architectures, limiting addressable vehicles to recent model years.
- Insurance Companies:Usage-based policy incentives increasingly subsidize aftermarket system installation for high-risk driver segments.
OEMs command the dominant value share. Fleet procurement is climbing the fastest as operational liability frameworks tighten.
Technology:
Application criticality and weather tolerance determine which architectures OEMs specify for which vehicle positions.
- Active Systems:Radar-based detection with autonomous braking intervention commands the largest installed base. NHTSA's pending rear automatic braking mandate is accelerating specification among Detroit Three OEMs preparing compliance pathways.
- Integrated Systems:Fusion of radar, camera, and ultrasonic inputs onto centralized compute platforms represents the steepest expansion trajectory as automakers consolidate ADAS domain controllers.
- Hybrid Systems:Combinations of active warning with passive visual alerts serve mid-market segments balancing cost and functionality.
- Passive Systems:Warning-only configurations without braking intervention retain presence in emerging markets with limited regulatory pressure.
Active systems dominate current installations. Integrated architectures are gaining share fastest through platform consolidation.
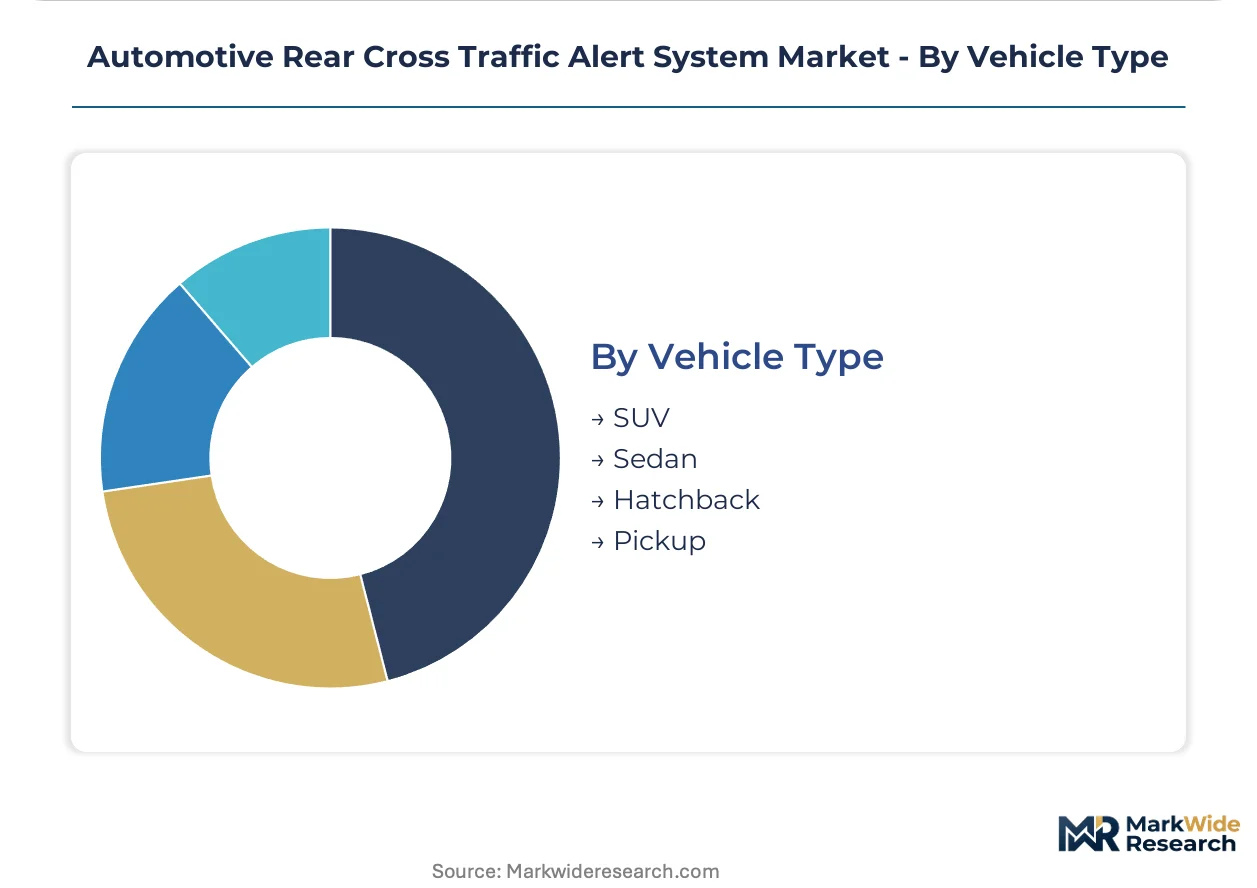
Vehicle Type:
Blind-spot geometry and reversing frequency shape system specification across body styles.
- SUV:Elevated ride height and larger rear blind spots drive highest penetration rates. American and Chinese OEMs specify standard equipment across compact, mid-size, and full-size SUV lineups.
- Sedan:Lower beltlines reduce absolute blind-spot volume but dense urban parking environments sustain demand. European volume manufacturers prioritize sedan fitment to maintain fleet-average safety ratings.
- Hatchback:Shorter rear overhangs and European market concentration create specification variation by price tier.
- Pickup:Commercial and personal-use dual-purpose applications drive adoption in North American markets.
SUVs lead by installation rate. Sedans dominate by absolute unit volume given global production scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium OEM procurement teams concentrate factory-fit specification decisions in Germany, Japan, and the United States, where regulatory pressure and fleet liability frameworks drive standardization across model tiers.
Germany
Mercedes-Benz, BMW, and Audi mandate rear cross traffic alert across entry-level variants to maintain Euro NCAP five-star eligibility. KBA type approval guidelines now incorporate rear collision avoidance performance benchmarks. Bavaria hosts three dominant Tier-1 radar assembly facilities supplying European OEM programs.
United States
Detroit Three OEMs accelerate specification ahead of anticipated NHTSA rear automatic braking mandates. Fleet leasing channels negotiate fleet-wide ADAS bundling to reduce operational liability exposure. Michigan-based engineering centers coordinate compliance pathway development for 2026 model year platforms.
Japan
Toyota and Honda integrate standardized warning interfaces to satisfy amended Ministry of Land, Infrastructure, Transport and Tourism safety regulations effective 2025. Kei-car manufacturers face expanded ADAS mandates previously exempt from full requirements. Nagoya-area supplier clusters adapt production lines for radar module volume scaling.
China
Domestic OEMs expand rear cross traffic fitment in mid-market SUVs to differentiate against European and Japanese competitors. MIIT guidelines encourage ADAS standardization without mandatory enforcement. Yangtze River Delta electronics manufacturing hubs localize radar MMIC sourcing to reduce import dependency.
India
Maruti Suzuki and Hyundai Motor India expand rear cross traffic availability in compact SUVs targeting urban parking environments. PLI scheme eligibility for sensor component localization attracts Tier-1 investment. Tamil Nadu automotive corridors host emerging radar module assembly operations serving domestic OEM programs.
Automotive Rear Cross Traffic Alert System Market Vendor Landscape
Player mix skews toward diversified automotive Tier-1 suppliers with established OEM validation pathways and multi-sensor integration capabilities. Three strategic archetypes dominate: radar-focused module specialists, camera-surround-view integrators, and full-stack ADAS platform providers. Competitive moves concentrate on sensor fusion patent licensing and centralized compute platform partnerships.
Within the diversified Tier-1 tier, Robert Bosch GmbH, Continental AG, and Aptiv occupy anchor positions representing integrated radar-camera fusion expertise, European supply relationship depth, and scalable North American program execution respectively. These firms exemplify the certification-heavy, long-cycle validation environment where ISO 26262 ASIL-D compliance serves as the primary competitive moat.
| Leading Market Players |
|---|
| Aptiv |
| Magna International Inc. |
| Robert Bosch GmbH |
| Infineon Technologies AG |
| Autoliv Inc. |
| Continental AG |
| Valeo |
| ZF Friedrichshafen AG |
| DENSO Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with radar MMIC foundries lock in supply access and stabilize unit pricing visibility for Tier-1 suppliers serving European OEM programs. These arrangements insulate procurement teams from spot-market volatility in semiconductor substrates while committing volume thresholds that shape factory utilization planning across German and Japanese assembly networks.
Pricing Analysis
Cost-plus contracts with silicon wafer indexation dominate radar module procurement, linking final unit prices to raw material input fluctuations. Three-tier pricing structure across ASIL-D certified premium, ASIL-B standard, and uncertified economy levels creates sharp differentiation based on functional safety grade and OEM validation depth. Pricing pressure stems from ultrasonic parking assist substitution in Indian and Southeast Asian entry-level vehicles. Fleet operators exhibit lowest price sensitivity due to liability-driven bundling mandates, while aftermarket retrofit channels face acute margin compression from legacy CAN bus integration costs.
Supply Chain Analysis
Inbound logistics costs from Asia-Pacific semiconductor fabrication centers through Rotterdam and Hamburg ports constrain margin recovery for European radar assembly operations. German, Chinese, and Japanese manufacturing clusters anchor global sensor module production, drawing from gallium arsenide substrates, RF printed circuit boards, and specialized automotive-grade plastics. Single-source vulnerability concentrates in 77 GHz radar MMIC fabrication, where two foundries control qualified automotive capacity. Distribution runs through OEM-directed Tier-1 supply contracts with sequenced just-in-time delivery to vehicle assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rear cross traffic alert systems face high-growth disruption from Euro NCAP's five-star mandate elimination for unequipped vehicles, compressing OEM adoption timelines and reshaping competitive positioning across sensor fusion architectures.
For Market Incumbents: Compound sensor fusion patent portfolios through targeted licensing of radar-camera integration IP to defend against pure-play camera perception entrants. Accelerate backward integration into 4D imaging radar semiconductor design to reduce MMIC foundry dependency and capture margin expansion from premium OEM specification shifts toward elevation-capable detection modules. For New Entrants and Emerging Players: ISO 26262 ASIL-B certification fast-track programs for mid-market Chinese and Indian OEMs offer the most penetrable entry vector, bypassing the 18-24 month validation timelines that protect incumbent supplier relationships. Target compact SUV platforms in India's Tamil Nadu automotive corridor through PLI scheme-eligible component localization partnerships, leveraging import duty advantages against established European Tier-1 pricing. For Investors and Strategic Acquirers: Capital is best deployed toward radar signal processing software specialists with embedded functional safety engineering capabilities, positioned for consolidation as centralized ADAS compute platforms displace edge-based sensor processing. Long-term viability hinges on software-defined vehicle architecture alignment rather than discrete hardware module supply. Monitor NHTSA rear automatic braking rulemaking trajectory as the critical regulatory inflection signal for North American specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| 4D Imaging Radar Platform Development | Audi and BMW specification adoption for 2024 model year platforms validates elevation-measurement technology. |
| Software-Defined Vehicle Compute Integration | Centralized ADAS domain controllers enable over-the-air feature activation transforming hardware into recurring software revenue. |
| India PLI Scheme Component Localization | Maruti Suzuki and Hyundai Motor India programs reduce import duty exposure for radar module assembly operations. |
| Euro NCAP Compliance Pathway Investment | Five-star rating dependency forces standardization across Mercedes-Benz, BMW, and Audi entry-level variants. |
| Rear Automatic Braking Mandate Preparation | NHTSA pending rulemaking accelerates Detroit Three OEM specification for 2026 model year platform compliance. |
Methodological Framework
Cross-validation between Tier-1 supplier procurement disclosures and OEM platform engineering documentation anchors the qualitative findings in this study. Primary interviews with radar module product managers, automotive functional safety engineers, and fleet leasing procurement directors combined with secondary validation from vehicle production databases, IHS Markit registration data, KBA type approval filings, and SEC automotive segment disclosures. Bottom-up sensor unit shipment estimates and top-down ADAS content per vehicle calculations establish convergent validity across the analysis.
Sensitivity analysis around radar MMIC foundry capacity assumptions and Euro NCAP protocol adoption timelines frames the projection uncertainty. The analytical framework models segmentation across sensor modality, vehicle class, OEM tier, and regional production cluster throughout the forecast period. CAGRs derive from fitted adoption curves calibrated to regulatory mandate effective dates and fleet liability framework evolution. Industry-specific inputs include NCAP rating incentive elasticity and software-defined vehicle architecture penetration assumptions.
Underlying assumptions cover sustained semiconductor substrate availability and stable Euro NCAP protocol enforcement, with deviation risk concentrated in radar MMIC supply disruption or regional NCAP divergence creating certification fragmentation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Airbag Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Automotive Passive Safety System Market
Automotive Safety and Security Systems
Automotive Inertial Systems Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market
Automotive Safety and Security Systems
Global Automotive Camera Cleaning System Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Forward Collision Warning System for Automotive Market
Automotive Safety and Security Systems
Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Europe Automotive Night Vision System Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Smart Airbag Coats Market
Automotive Safety and Security Systems
Highway Crash Cushion Market
Automotive Safety and Security Systems
Canada Automotive Adaptive Lighting System Market
Automotive Safety and Security Systems
Driver Assistance System Market
Automotive Safety and Security Systems
Global Automotive Lidar Sensor Market