
 Marine Chartplotter Market | 2026-2036
Marine Chartplotter Market Size, Share, and Industry Trends Forecast 2026-2036
Marine Chartplotter Market Outlook
Multi-source procurement for display panels and GNSS chipsets is shifting toward captive sourcing among tier-one marine electronics manufacturers. Garmin leverages its vertically integrated GPS engine development to control hardware-software synchronization across product lines. Furuno Electric anchors its competitive stance through deep specialization in commercial-grade sonar integration for deep-sea operations. Raymarine competes aggressively in the sailing yacht segment where wind-overlay chartplotting commands premium positioning.
A marine chartplotter combines electronic navigation data processing with geospatial chart display, typically integrating GPS positioning with raster or vector cartography at refresh rates exceeding 10 Hz for real-time vessel tracking. Its primary commercial purpose is collision avoidance and route optimization for vessels operating in confined or high-traffic waters. Integrated Systems command the largest revenue share as boat builders specify factory-installed bridge electronics packages to reduce aftermarket complexity. Networked Devices represent the fastest-growing product category, driven by NMEA 2000 protocol standardization that allows sonar, radar, and autopilot data to flow across a single backbone cable. Recreational Boaters generate the highest volume demand, though Fishing Charters sustain stronger per-unit pricing through professional-grade sonar and bathymetric mapping requirements.
The International Maritime Organization mandates ECDIS carriage requirements under SOLAS Chapter V, forcing commercial vessel operators to maintain certified chartplotting systems with type-approved hardware. The US Coast Guard enforces NVIC 01-16 compliance standards for electronic charting systems aboard inspected passenger vessels, directly shaping product development roadmaps for domestic manufacturers. Stakeholders must monitor evolving cybersecurity standards for connected bridge systems, as IEC 61162-460 network security protocols begin filtering down from commercial shipping into recreational product specifications.
Market Dynamics
ECDIS certification mandates under SOLAS Chapter V are compressing product development cycles and forcing hardware-software recertification investments across commercial vessel electronics portfolios.
Growth Catalysts
- IMO SOLAS Chapter V ECDIS Mandates:Commercial shipping operators must install type-approved electronic chart display systems, creating baseline demand for certified hardware across cargo fleets.
- NMEA 2000 Protocol Standardization:Unified data backbone architecture enables radar, sonar, and autopilot integration, reducing installation complexity for boat builders specifying factory electronics packages.
- Leisure Maritime Activity Concentration:Coastal state marina infrastructure expansion in Florida, California, and Texas sustains recreational boater demand for mid-range networked chartplotter systems.
Market Restraints
- Display Panel Supply Concentration:High-brightness marine-grade LCD sourcing clusters among East Asian panel fabricators, exposing tier-one manufacturers to single-source disruption risk.
- GNSS Chipset Cost Volatility:Multi-constellation receiver silicon pricing fluctuates with semiconductor foundry capacity allocation, pressuring hardware margin structures.
- Smartphone Navigation Substitution:Consumer-grade mobile applications with offline chart caching threaten entry-level dedicated chartplotter demand among casual day-boaters.
Strategic Opportunities
- Cybersecurity Protocol Migration:IEC 61162-460 network security standards filtering from commercial shipping into recreational specifications creates certified product differentiation potential.
- Fishing Charter Professionalization:Commercial-grade bathymetric mapping and CHIRP sonar integration commands per-unit pricing premiums in the charter vessel retrofit segment.
- Wind-Overlay Sailing Demand:Racing yacht and cruising sailboat operators require polar plot integration with real-time meteorological data feeds, opening specialized software module revenue.
Industry Challenges
- Type-Approval Certification Timelines:Hardware-software synchronization testing for US Coast Guard NVIC 01-16 compliance extends product launch windows by 8-14 months.
- Bridge System Integration Complexity:Legacy radar and autopilot architectures from disparate manufacturers resist seamless NMEA 2000 backbone connectivity without proprietary gateway investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marine Chartplotter Market |
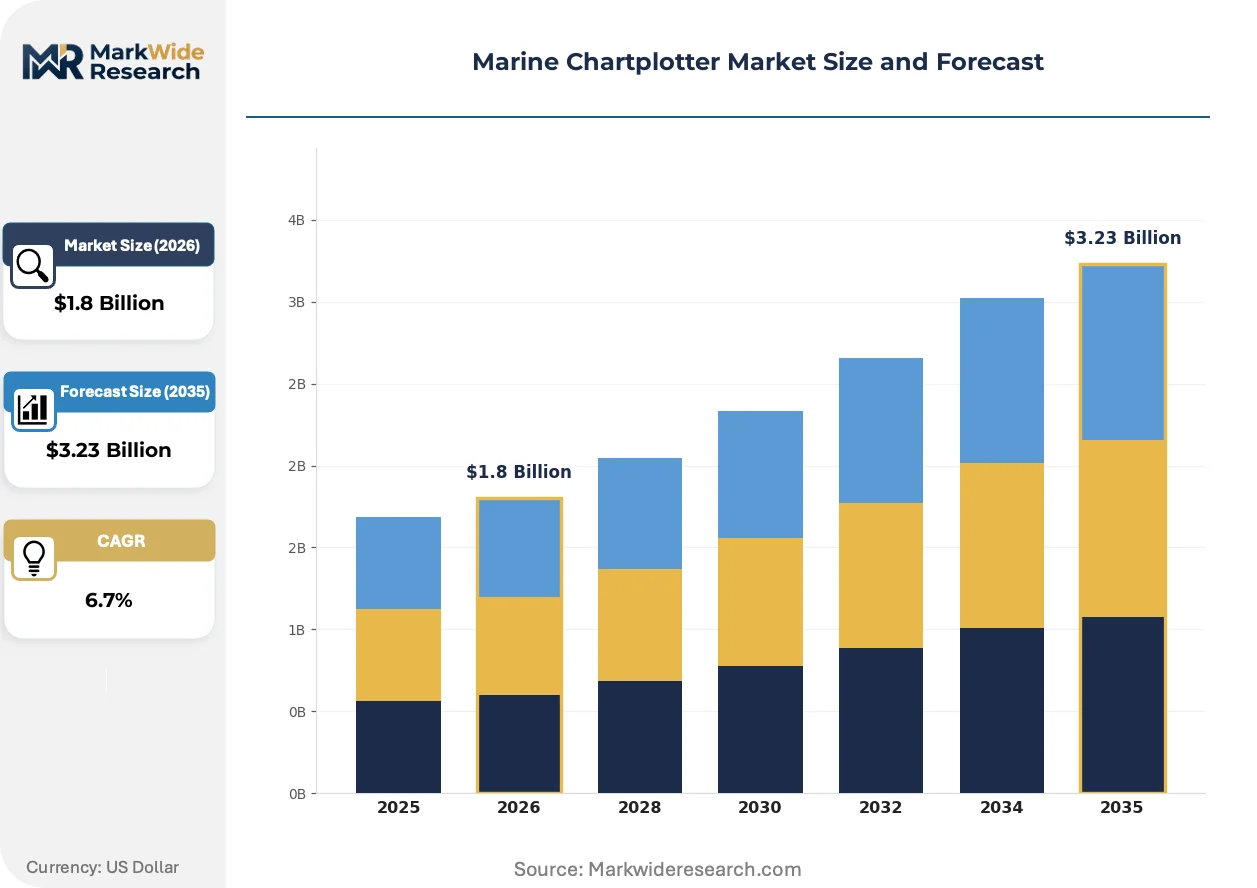
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Units, Integrated Systems, Networked Devices, Mobile Applications Technology: GPS, RADAR, Sonar, AIS End User: Commercial Vessels, Recreational Boaters, Fishing Charters, Research Institutions Installation Type: Fixed Mount, Portable, Flush Mount, Remote |
| Companies Covered | Furuno Electric, NKE, Garmin, FLIR Systems, Simrad, Navico, Navionics, Si-Tex Marine Electronics, Raymarine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marine Chartplotter Market Strategic Shifts
Real-time cloud chart updates and AI-assisted route optimization are compressing the functional gap between commercial ECDIS platforms and recreational chartplotters, reshaping product tier boundaries.
Cloud-based raster and vector chart synchronization is expanding into mid-range recreational units, enabling automatic notice-to-mariner updates without manual SD card replacement. Weekend cruisers and coastal anglers now expect hourly chart revision cycles previously reserved for commercial fleets. This capability is compressing aftermarket service revenue streams while shifting value toward subscription-based cartography licensing.
The US Coast Guard NVIC 01-16 enforcement framework is tightening electronic charting system compliance standards for inspected passenger vessels operating in domestic waters. Manufacturers must redesign hardware architectures to meet encrypted data logging and audit trail requirements. Domestic ferry operators and harbor cruise fleets represent the most affected segment, accelerating refresh cycles for bridge electronics packages.
Boat builder procurement teams are consolidating vendor relationships around single-source electronics packages that span chartplotting, radar, and autopilot functions. Direct OEM specification agreements are displacing traditional marine retail channels for new vessel sales. This concentration is most visible in Florida and Great Lakes manufacturing clusters where production volume justifies dedicated supplier engineering support.
Marine Chartplotter Market Segmentation
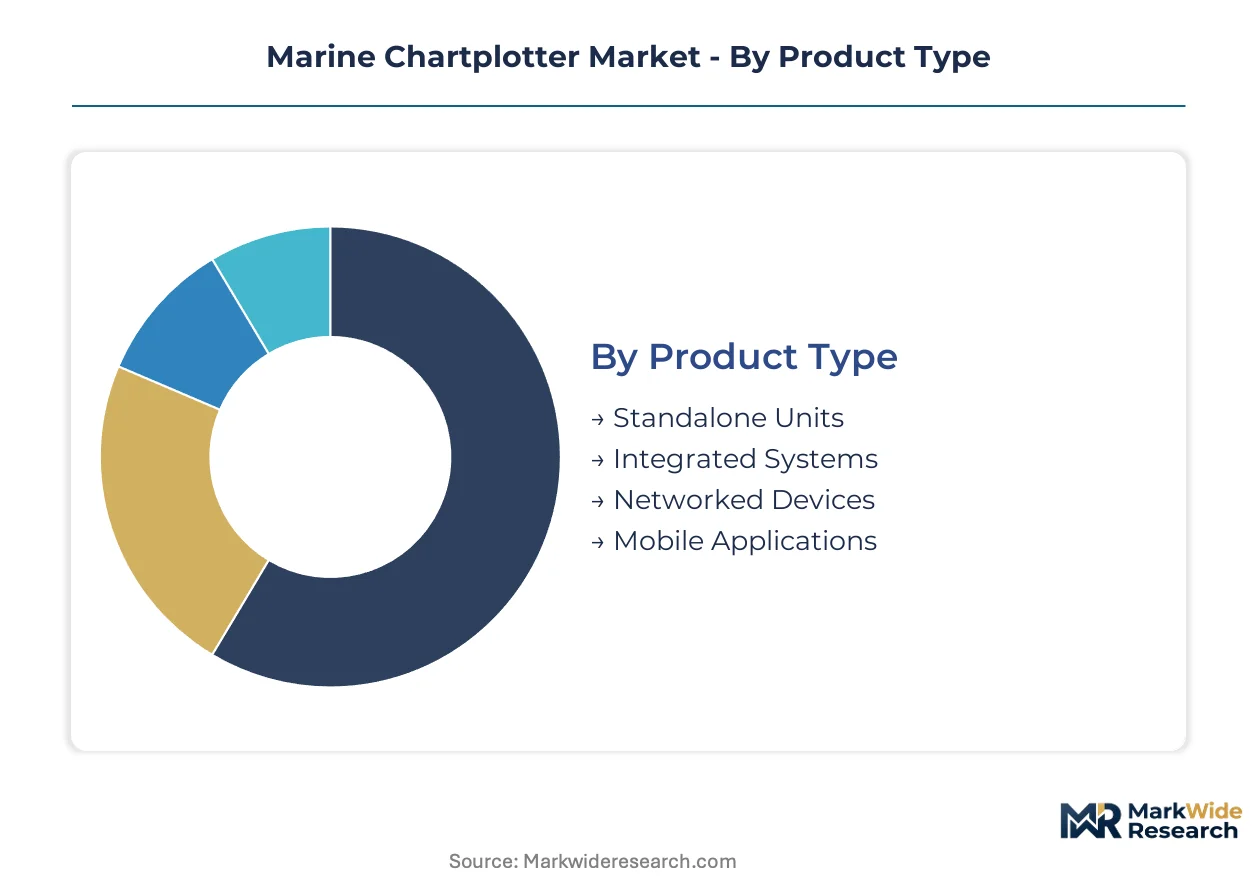
Marine chartplotter segmentation reveals how vessel type, technical architecture, and operational intensity shape purchasing specifications. Product configurations diverge sharply between factory-installed bridge packages and aftermarket retrofit solutions.
Product Type:
The customization-standardization spectrum runs from fully proprietary integrated bridge systems to open-architecture networked devices that accept third-party sensors.
- Integrated Systems:Factory-installed bridge electronics packages combine chartplotting, radar, and autopilot functions under unified hardware-software control. Boat builders in Florida, California, and Texas specify these systems to reduce commissioning complexity and warranty exposure. These configurations dominate new vessel production.
- Networked Devices:NMEA 2000 backbone-compatible units enable modular expansion with sonar, engine monitoring, and weather sensors. Recreational boaters retrofitting older vessels drive aftermarket demand. Expansion is steepest in this segment as protocol standardization lowers integration barriers.
- Standalone Units:Self-contained chartplotters with embedded GPS and cartography serve budget-conscious coastal anglers. Limited sensor expandability restricts appeal beyond entry-level day-boaters.
- Mobile Applications:Consumer-grade tablet and smartphone software with offline chart caching threatens dedicated hardware at the lowest price tier. Casual operators on inland lakes increasingly rely on these solutions.
Most installed capacity flows through Integrated Systems. Expansion is steepest in Networked Devices.
Technology:
Cost tier separation distinguishes professional-grade multi-sensor fusion from single-modality recreational units.
- GPS:Multi-constellation receivers integrating GPS, GLONASS, Galileo, and BeiDou signals deliver sub-meter positioning for collision avoidance. Commercial shipping operators require this redundancy for SOLAS Chapter V compliance. GNSS chipset cost volatility pressures margin structures across all product tiers.
- Sonar:CHIRP and broadband fishfinding systems with bathymetric mapping capabilities command pricing premiums in the charter vessel segment. Professional operators in the Gulf of Mexico and Pacific Northwest specify high-frequency transducers for bottom discrimination.
- RADAR:Solid-state pulse compression systems enable target tracking in reduced visibility. Integration complexity with legacy magnetron radars limits retrofit adoption outside commercial fleets.
- AIS:Automatic Identification System receivers display vessel traffic data for collision avoidance. IMO mandates drive carriage requirements on commercial vessels exceeding specified tonnage thresholds.
Volume concentrates in GPS-enabled configurations. Pricing power is strongest in Sonar-integrated platforms.
End User:
Application intensity separates continuous-operation commercial fleets from seasonal recreational use patterns.
- Commercial Vessels:Cargo ships, tankers, and passenger ferries operate under strict ECDIS carriage requirements with type-approved hardware-software combinations. US Coast Guard NVIC 01-16 compliance shapes domestic product specifications. Certification timelines extend procurement cycles significantly.
- Recreational Boaters:Weekend cruisers and coastal sailors generate the highest unit volumes through marine retail channels. Marina infrastructure expansion in coastal states sustains mid-range networked system demand. This segment shows the steepest volume trajectory as leisure maritime participation rises.
- Fishing Charters:Professional operators require commercial-grade sonar, bathymetric mapping, and route optimization for client success. Per-unit pricing exceeds recreational tiers by substantial margins.
- Research Institutions:Oceanographic vessels demand specialized data logging and scientific sensor integration. Limited volume restricts dedicated product development.
Revenue concentrates in Commercial Vessels. Volume expansion is fastest among Recreational Boaters.
Installation Type:
Customer type separation distinguishes OEM factory specifications from owner-operator retrofit preferences.
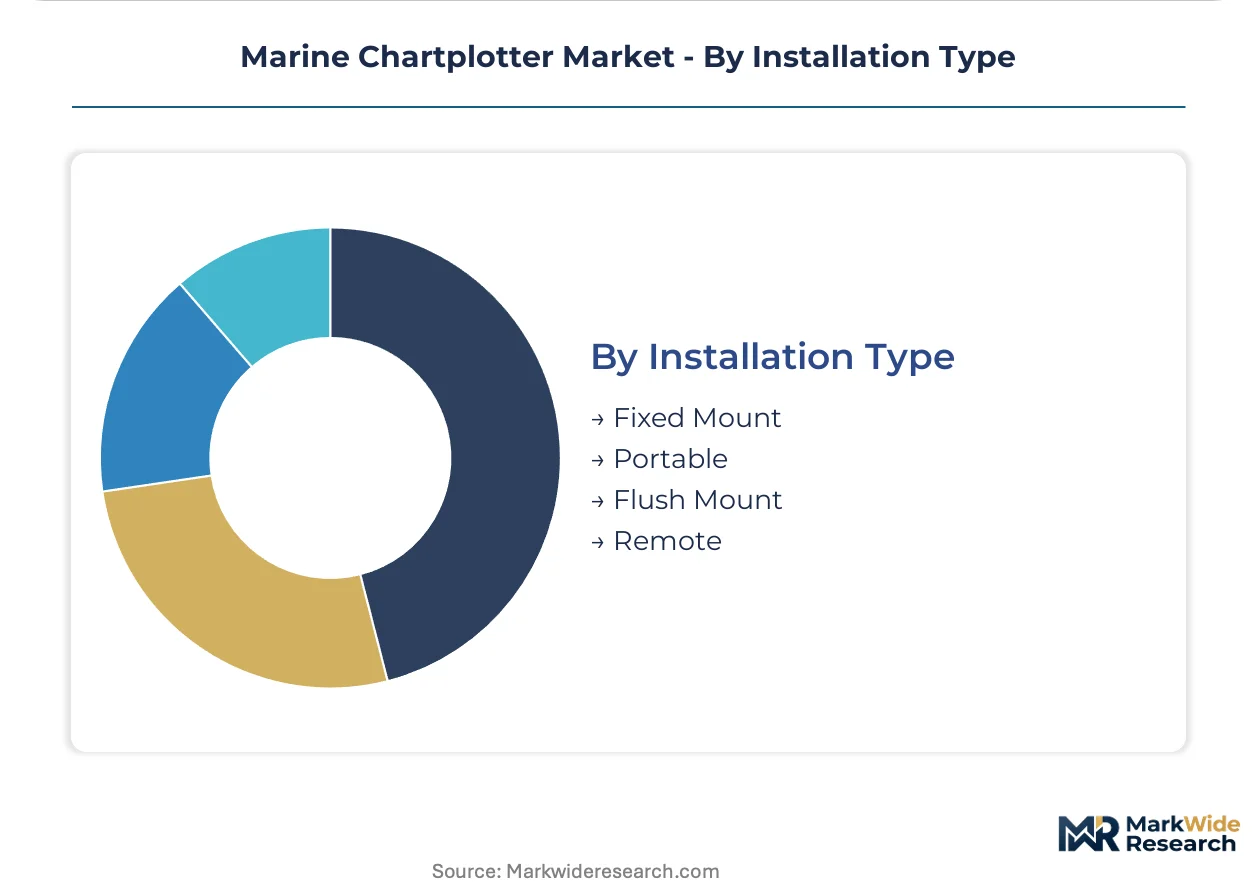
- Fixed Mount:Permanent helm installations with dedicated power and antenna routing dominate new vessel production. Boat builders specify these configurations to streamline commissioning workflows.
- Portable:Suction-cup or bracket-mounted units serve anglers on multiple vessels or rental fleets. Limited antenna performance constrains offshore reliability.
- Flush Mount:Panel-integrated displays deliver clean aesthetics on premium sailing yachts and sportfishing boats. Installation complexity requires professional marine electronics technicians.
- Remote:Wireless secondary displays enable multi-station operation on large vessels. Network security protocols from IEC 61162-460 standards are filtering into recreational specifications.
Factory output flows predominantly through Fixed Mount configurations. Aftermarket growth is strongest in Flush Mount retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida's coastal marina infrastructure anchors marine chartplotter procurement volume, with recreational boating density and Coast Guard enforcement creating concentrated hardware demand across the United States.
United States
Coastal state marina expansion in Florida, California, and Texas drives recreational boater demand for networked NMEA 2000 systems. US Coast Guard NVIC 01-16 mandates encrypted data logging for inspected passenger vessels, forcing hardware redesigns. The Great Lakes manufacturing corridor consolidates boat builder procurement around single-source electronics packages.
China
Commercial shipping fleet modernization under SOLAS Chapter V ECDIS requirements sustains type-approved hardware demand. The country's national maritime regulator enforces carriage compliance for cargo vessels operating through Shanghai and Ningbo-Zhoushan ports. Yangtze River Delta shipyards specify integrated bridge systems for newbuild export tankers.
Japan
Deep-sea commercial fishing operations require professional-grade sonar integration with bathymetric mapping capabilities. METI industrial standards shape domestic product certification timelines for marine electronics manufacturers. Nagoya-based industrial clusters specialize in CHIRP transducer fabrication for regional export markets.
Germany
Inland waterway cargo operators on the Rhine-Danube corridor adopt ECDIS-compliant chartplotting for fleet navigation safety. CE marking and EU maritime safety regulations harmonize product standards across North Sea and Baltic trade routes. Bavaria's precision electronics sector supplies multi-constellation GNSS receiver modules to European system integrators.
Australia
Recreational boating participation along Queensland and New South Wales coastlines sustains aftermarket retrofit demand for networked devices. The country's national maritime safety authority enforces electronic chart carriage for commercial fishing vessels exceeding specified tonnage thresholds. Perth-based marine electronics distributors service Indian Ocean charter operations with professional-grade bathymetric systems.
Marine Chartplotter Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue mobile application and software-only charting solutions. Market structure consolidates around vertically integrated hardware manufacturers and specialized marine electronics houses. Three archetypes dominate: full-stack bridge system integrators, sonar-specialized commercial suppliers, and GPS-engine developers controlling upstream silicon. Competitive moves center on OEM specification agreements with boat builders and backward integration into GNSS chipset supply.
Within the integrated systems tier, Garmin and Furuno Electric exemplify contrasting strategic positions. Garmin leverages in-house GPS engine development to synchronize hardware-software performance across product lines. Furuno Electric anchors the commercial-grade sonar specialization archetype through deep-sea fishing and cargo vessel applications. Raymarine occupies a distinctive position in sailing yacht segments where wind-overlay chartplotting commands premium software module pricing.
| Leading Market Players |
|---|
| Furuno Electric |
| NKE |
| Garmin |
| FLIR Systems |
| Simrad |
| Navico |
| Navionics |
| Si-Tex Marine Electronics |
| Raymarine |
| Others |
Value Chain & Pricing Dynamics
Cloud-based chart update architectures are compressing aftermarket service revenue while simultaneously shifting procurement power toward subscription-locked OEMs, concentrating margin control among vertically integrated hardware developers. This dual transformation forces tier-two manufacturers to absorb GNSS chipset volatility or surrender pricing autonomy to platform-locked distribution channels.
Pricing Analysis
Input-cost pass-through from multi-constellation GNSS silicon and high-brightness marine-grade LCD panels dominates margin structures across all product tiers. Three-tier pricing structure across premium, standard, and economy levels separates ECDIS-certified commercial systems from recreational networked devices and entry-level standalone units. Cost compression in the economy tier intensifies because smartphone navigation substitution erodes dedicated hardware demand among casual day-boaters. Charter vessel operators show least price sensitivity due to professional-grade sonar and bathymetric mapping requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Florida and Great Lakes boat builders consolidating around single-source electronics packages. Manufacturing concentration clusters in China, Taiwan, and South Korea for display panel fabrication and semiconductor foundry output. The supply chain draws from specialized CHIRP transducer production in Japan and multi-constellation GNSS receiver modules from Germany. Single-source vulnerability in East Asian panel sourcing exposes tier-one manufacturers to disruption risk. Distribution runs through marine retail networks for aftermarket retrofit demand and direct OEM specification agreements for new vessel production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as leisure maritime participation shifts specifications toward premium networked systems with NMEA 2000 protocol integration and cloud-connected chart updates.
For Market Incumbents: Hedge against smartphone navigation substitution by deepening software subscription attach rates and encrypted data logging capabilities that consumer-grade applications cannot replicate. Prioritize captive supply of GNSS chipsets to buffer semiconductor foundry allocation volatility. Defend OEM specification relationships through dedicated engineering support for Great Lakes and Florida manufacturing clusters. For New Entrants and Emerging Players: Begin with wind-overlay sailing software modules where polar plot integration commands premium positioning and incumbent specialization gaps remain widest. Target the fishing charter retrofit segment in the Gulf of Mexico and Pacific Northwest with commercial-grade bathymetric mapping solutions. Pursue direct charter operator sales bypassing traditional marine retail channel markups. For Investors and Strategic Acquirers: Valuations sit cheapest among standalone unit manufacturers facing maximum smartphone substitution pressure and lacking subscription revenue streams. Long-term viability favors vertically integrated developers controlling upstream GPS engine design and downstream OEM specification channels. Watch NMEA 2000 protocol standardization penetration rates in recreational retrofit installations as the inflection signal for aftermarket growth sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| ECDIS Certification Investment | US Coast Guard NVIC 01-16 compliance opens inspected passenger vessel procurement opportunities. |
| NMEA 2000 Protocol Integration | Unified data backbone architecture reduces installation complexity for factory electronics packages. |
| Cloud Chart Subscription Launch | Automatic notice-to-mariner updates shift value toward recurring licensing revenue streams. |
| Cybersecurity Module Development | IEC 61162-460 network security standards create certified product differentiation in recreational segments. |
| CHIRP Sonar Backward Integration | In-house transducer fabrication captures professional-grade charter vessel pricing premiums. |
Study Parameters
Multiple input streams — technical specification databases, customs trade records, and OEM procurement disclosures — were reconciled against primary interviews with marine electronics product managers, boat builder procurement directors, and Coast Guard regulatory compliance officers. Secondary validation drew from ECDIS type-approval registries, NMEA certification listings, and SEC filings of publicly traded marine electronics manufacturers. Bottom-up unit demand estimates and top-down market sizing were triangulated to constrain forecast variance.
Historical shipment data was cross-referenced against panel input from marina operators and charter fleet managers to establish baseline adoption patterns. Segmentation modeling spanned product architecture, technology integration depth, end-use intensity, and installation type across the projection horizon. CAGRs were derived from fitted growth curves calibrated to ECDIS mandate phase-in schedules and recreational boating participation trends. Industry-specific inputs included SOLAS Chapter V compliance timelines and NMEA 2000 protocol penetration rates.
Several conditions sit outside the modeled scope, including regulatory delays in cybersecurity standard adoption and unforeseen disruptions in semiconductor foundry capacity allocation. Forecasts reflect assumptions about sustained leisure maritime participation growth and stable OEM consolidation patterns. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
India Boat Davits Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Marine Airbags Market
Marine
Boat Cleat Market
Marine
US Fish Finders Market
Marine
Hydraulic Marine Cranes Market
Marine
Azimuth Thrusters Market
Marine
Marine Dynamic Positioning System Market
Marine
Digital Nautical Charts Market
Marine
North Sea Offshore Support Vessels Market
Marine
Swamp Boat Market
Marine
Ship Rudders Market
Marine
Rescue Boats Market
Marine
Electric Ship Market
Marine
Sailboat Propellers Market
Marine
Marine Chronometers Market