
 Trim Tabs Market | 2026-2036
Trim Tabs Market Size, Share, and Industry Trends Forecast 2026-2036
Trim Tabs Market Outlook
EPA marine engine emission standards is consolidating compliance costs for trim tab manufacturers serving the recreational boating sector. Bennett Marine leverages its coastal manufacturing footprint to sustain domestic supply chain advantages. Lenco Marine anchors its position through electric actuator specialization. Volvo Penta competes by integrating trim control with propulsion system electronics.
Trim tabs are adjustable control surfaces mounted on the transom of watercraft, typically constructed from marine-grade aluminum or fiber-reinforced composites, that alter running attitude to optimize fuel efficiency and ride quality. Hydraulic trim tabs dominate commercial marine applications where load capacity demands exceed electric alternatives, while electric variants capture recreational segments seeking simplified installation and digital integration. Composite material adoption accelerates in saltwater environments where corrosion resistance extends service intervals beyond aluminum equivalents.
The US Coast Guard enforces structural and stability standards for passenger vessels under 46 CFR, while ABYC publishes voluntary installation guidelines that most insurers treat as binding requirements. The EU Marine Equipment Directive governs trim tab certification for vessels operating in European waters, creating parallel testing obligations for exporters. Stakeholders must monitor emerging electrification mandates in harbor craft regulations and decide whether to develop integrated trim-stabilization systems or retain standalone product architectures.
Market Dynamics
The EPA's marine engine emission standards are consolidating compliance costs for trim tab manufacturers, forcing product redesigns that integrate electric actuation with propulsion electronics while compressing margins for standalone hydraulic suppliers.
Growth Catalysts
- 46 CFR Stability Mandates:The US Coast Guard's updated small passenger vessel regulations tighten certification requirements, expanding the addressable fleet for compliant trim tab systems.
- Composite Material Substitution:Saltwater corrosion resistance in fiber-reinforced polymers extends service intervals beyond aluminum equivalents, driving replacement cycles in Gulf Coast recreational fleets.
- Electric Actuator Proliferation:Digital integration capabilities in electric trim tabs align with recreational boater demand for simplified installation and smartphone-enabled control interfaces.
Market Restraints
- Aluminum Price Volatility:Marine-grade aluminum input costs fluctuate with energy-intensive smelting economics, compressing margins for traditional hydraulic tab manufacturers.
- Hydraulic Supplier Concentration:Commercial marine load capacity requirements lock segments into hydraulic architectures controlled by a narrow supplier base concentrated in coastal manufacturing clusters.
- EU Marine Equipment Directive Parallel Testing:Exporters face duplicative certification obligations for European waters, extending time-to-market and raising compliance overhead.
Strategic Opportunities
- Harbor Craft Electrification Mandates:Emerging zero-emission requirements for port vessels create demand for integrated trim-stabilization systems that share power electronics with electric propulsion.
- ABYC-Insurer Alignment:Voluntary installation guidelines treated as binding by marine insurers open channel partnerships with underwriters seeking risk mitigation through certified installations.
- Digital Twin Convergence:Real-time hull attitude data from trim tabs is integrating with vessel monitoring systems, enabling predictive maintenance subscriptions.
Industry Challenges
- Marine Electrician Skill Scarcity:Electric actuator deployment outpaces certified installer availability in dispersed coastal service networks.
- Legacy Hydraulic Integration Friction:Retrofit compatibility with existing boat control architectures requires custom mechanical interfaces that extend engineering cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Trim Tabs Market |
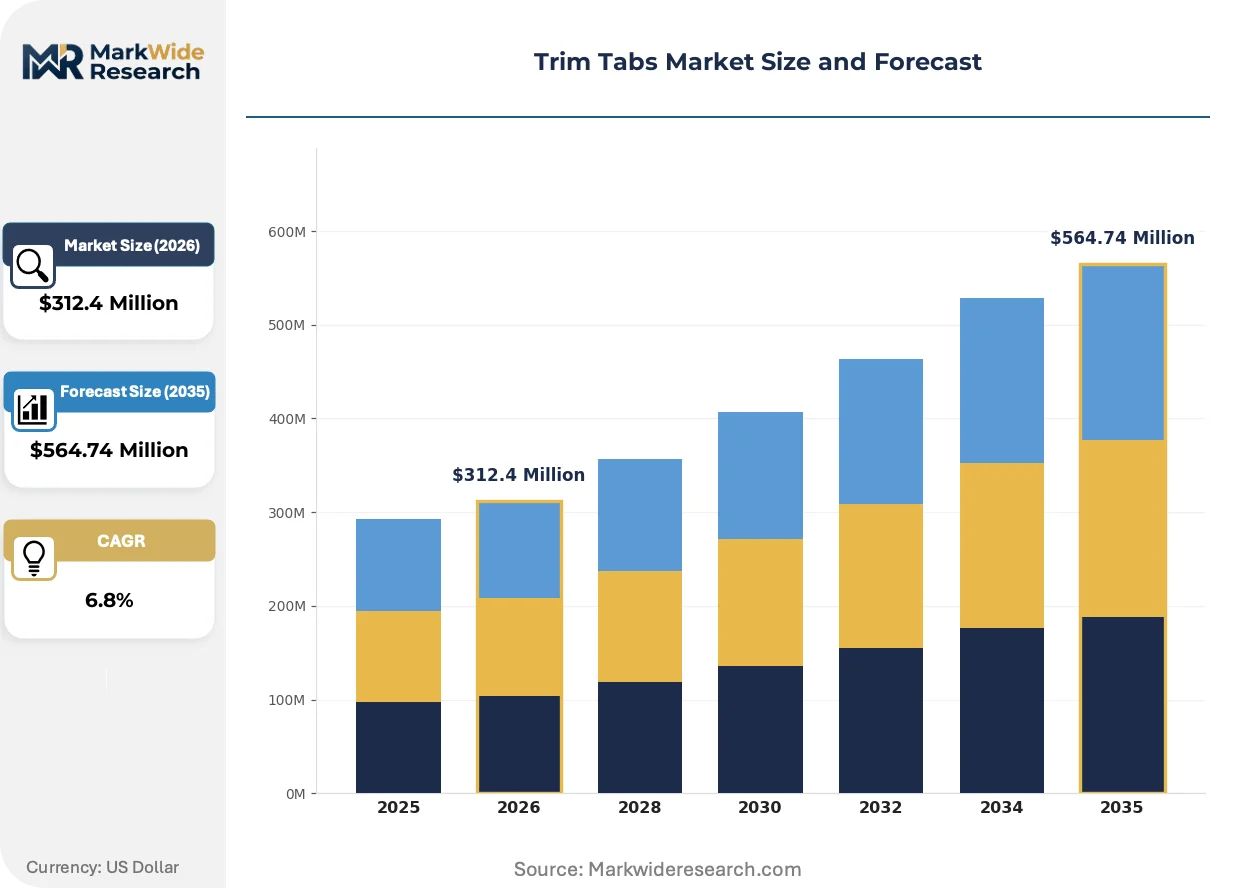
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Hydraulic, Electric, Pneumatic Application: Marine, Automotive, Aerospace, Industrial Material: Aluminum, Steel, Composite, Plastic End User: OEMs, Aftermarket, Commercial, Recreational |
| Companies Covered | Bennett Marine, Lenco Marine, Volvo Penta, Linear Devices Corporation, Zipwake, T-H Marine, Smart Tabs, CMC Marine, Trim Master Marine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Trim Tabs Market Strategic Shifts
Electrification architectures are compressing the boundary between propulsion and control surfaces, with trim tab functionality migrating from standalone mechanical systems into unified vessel management platforms.
Brushless DC actuators with integrated position feedback are integrating with CAN bus networks to enable synchronized tab adjustment with engine trim and joystick docking systems. Coastal Florida charter operators are adopting these configurations fastest, drawn to reduced wiring complexity and centralized diagnostics. This convergence is compressing the addressable market for standalone hydraulic component suppliers.
REACH substance restrictions on hydraulic fluids are forcing reformulation of traditional actuation chemistries used in European commercial fleets. The industrial consequence is accelerated validation timelines for bio-based alternatives and supplier consolidation around compliant fluid portfolios. Baltic Sea passenger vessel operators are responding by pre-emptively specifying electric architectures in newbuild contracts.
Recreational boaters are compressing replacement cycles for control electronics as smartphone-native interfaces become baseline expectations. Digital-native buyers in the 35-50 demographic are displacing traditional gauge-panel installations with app-integrated systems. This preference shift is most visible in Gulf Coast states where saltwater exposure already drives shorter equipment lifecycles and faster technology refresh rates.
Trim Tabs Market Segmentation
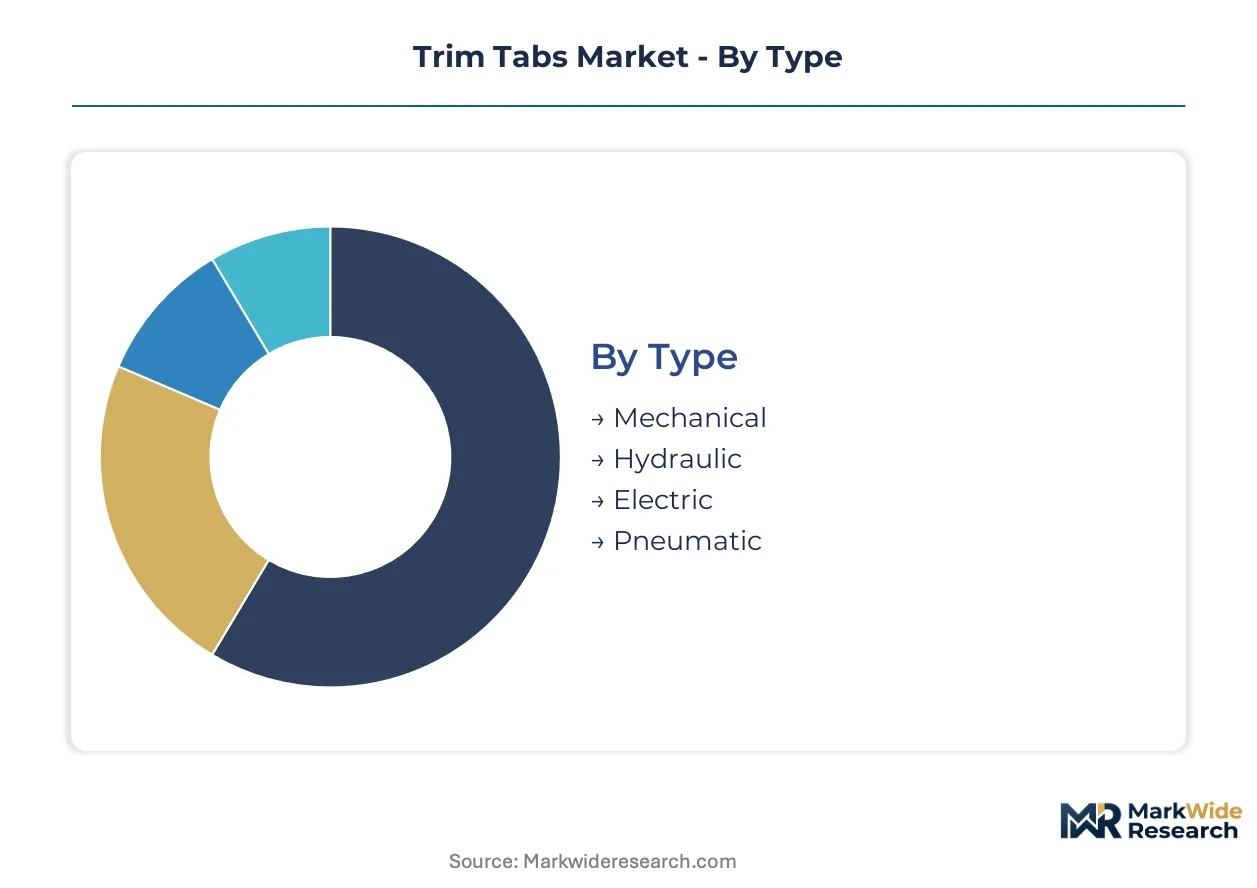
Trim tab procurement patterns diverge sharply across vessel types and operating environments. Segmentation reveals where capital deployment concentrates and which material-actuation combinations command premium positioning.
Type:
Capital intensity peaks with hydraulic systems requiring dedicated pump infrastructure and sealed plumbing networks. Electric architectures reduce upfront outlays but demand sophisticated motor control electronics.
- Mechanical:Manual linkage systems with cable-actuated adjustment mechanisms. Demand persists in small craft under 20 feet across Gulf Coast rental fleets where operator simplicity outweighs precision requirements.
- Hydraulic:Pressurized fluid networks with marine-grade cylinders rated for high-load commercial applications. Offshore supply vessels operating under US Coast Guard 46 CFR mandates concentrate demand here where torque capacity exceeds electric alternatives.
- Electric:Brushless DC actuators with integrated position feedback and CAN bus integration. Coastal Florida recreational installations favor these for smartphone-enabled control and reduced maintenance intervals in saltwater environments.
- Pneumatic:Compressed air systems with diaphragm actuators. Niche deployment in specialized industrial marine applications where explosion-proof ratings apply.
Most installed capacity flows through Hydraulic systems. Expansion is steepest in Electric configurations.
Application:
Application segmentation tracks where hull attitude control delivers measurable operational returns versus where it remains a comfort feature.
- Marine:Transom-mounted control surfaces for watercraft spanning recreational runabouts to commercial passenger vessels. EPA marine engine emission standards are tightening integration requirements with propulsion electronics across US-flagged fleets.
- Automotive:Aerodynamic stabilizers for high-performance and racing vehicles. Limited addressable market concentrated in aftermarket tuning segments.
- Aerospace:Flight control surface trim mechanisms for general aviation. Regulatory certification under FAA airworthiness directives constrains supplier entry.
- Industrial:Process equipment stabilization and heavy machinery leveling systems. Demand fragments across construction and material handling equipment OEMs.
Marine applications absorb the dominant share of production volume. Automotive aftermarket channels are gaining share fastest among non-marine categories.
Material:
Material selection directly correlates with corrosion exposure severity and replacement cycle economics.
- Aluminum:Marine-grade alloys with anodized or powder-coated finishes. Price volatility in smelting economics compresses margins for traditional hydraulic tab manufacturers serving commercial fleets.
- Steel:Carbon and stainless grades for industrial and heavy commercial marine applications where impact resistance outweighs weight penalties.
- Composite:Fiber-reinforced polymers with UV-stabilized gel coats. Saltwater charter operators in Florida and Gulf Coast states are specifying these to extend service intervals beyond aluminum equivalents.
- Plastic:Injection-molded thermoplastics for small craft and cost-sensitive recreational segments. Limited load capacity restricts deployment to outboard-powered vessels under 150 horsepower.
Aluminum retains the largest installed base. Composite substitution is climbing the fastest in saltwater recreational applications.
End User:
End user segmentation separates specification authority from purchasing behavior across vessel lifecycle stages.
- OEMs:Original equipment manufacturers integrating trim tabs at hull construction. Boat builders in coastal manufacturing clusters are consolidating around electric actuator suppliers offering CAN bus compatibility.
- Aftermarket:Retrofit installations by vessel owners and marine service providers. Skill scarcity among certified marine electricians constrains electric system deployment in dispersed coastal networks.
- Commercial:Passenger vessel operators and workboat fleets under regulatory compliance mandates. US Coast Guard stability requirements under 46 CFR drive certified system specifications.
- Recreational:Private boat owners prioritizing ride quality and fuel efficiency. Digital-native buyers in the 35-50 demographic are displacing traditional gauge panels with app-integrated electric systems.
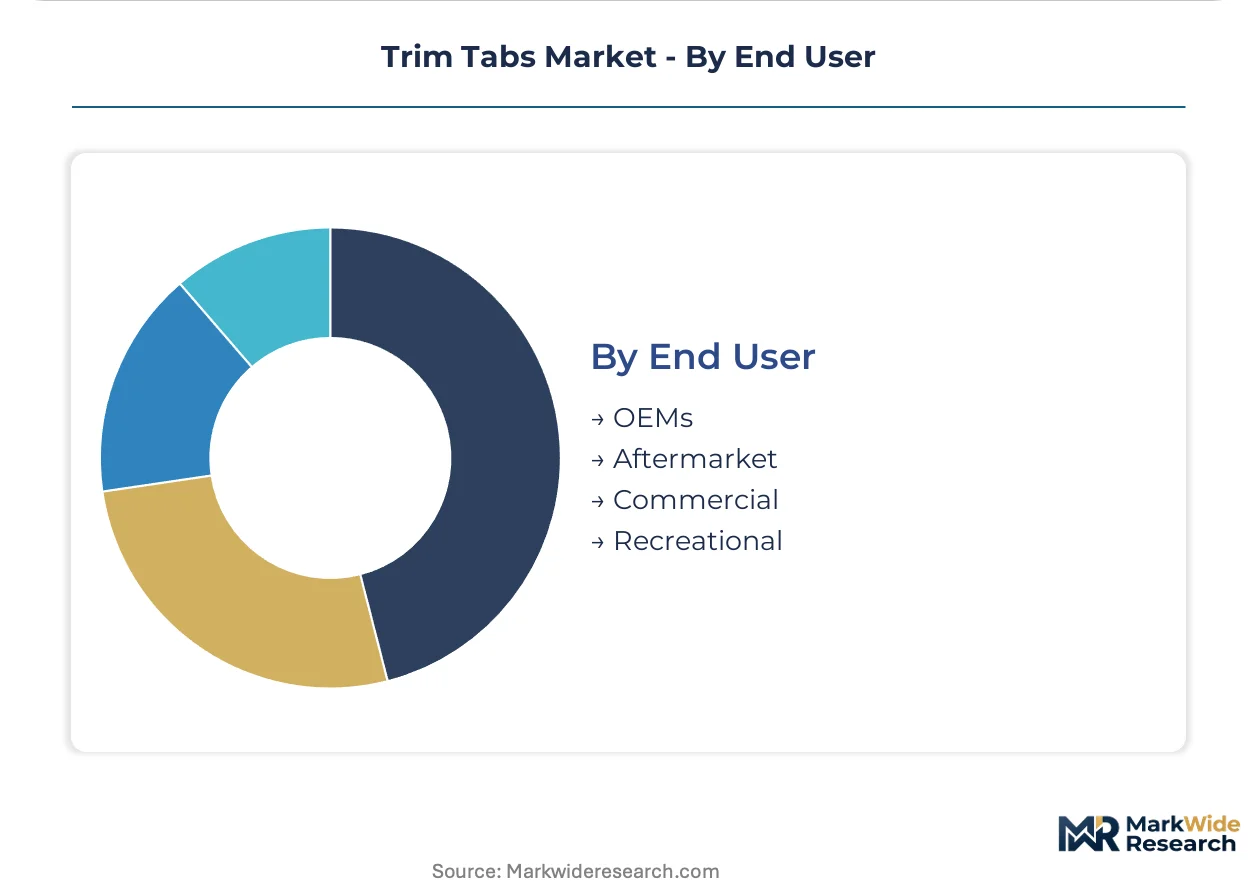
Aftermarket channels move the highest unit volumes. OEM specification of integrated electric systems is gaining share fastest among newbuild contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine electrician skill pools concentrate in coastal manufacturing clusters across five countries, shaping regional deployment capacity for electric actuator systems.
United States
Gulf Coast charter operators drive composite material substitution for saltwater corrosion resistance. The US Coast Guard enforces 46 CFR stability mandates that tighten certification requirements for small passenger vessels. Florida's coastal manufacturing corridor hosts expanding installations of electric trim tab systems in recreational boating fleets.
Germany
Baltic Sea passenger vessel operators pre-emptively specify electric architectures in newbuild contracts to navigate REACH substance restrictions on hydraulic fluids. The country's national environmental regulator enforces bio-based fluid validation timelines for commercial marine applications. Hamburg's port industrial cluster anchors supplier consolidation around compliant fluid portfolios.
China
Harbor craft electrification mandates create demand for integrated trim-stabilization systems sharing power electronics with electric propulsion. The Ministry of Ecology and Environment advances zero-emission requirements for port vessels under national dual carbon goals. The Yangtze River Delta manufacturing basin concentrates production of brushless DC actuators with CAN bus integration capabilities.
Italy
Composite material adoption accelerates in Mediterranean recreational fleets seeking extended service intervals beyond aluminum equivalents. The EU Marine Equipment Directive governs trim tab certification for vessels operating in European waters, creating parallel testing obligations. Liguria's yacht building corridor specializes in fiber-reinforced polymer specification for premium saltwater applications.
Australia
Digital-native recreational boaters in the 35-50 demographic displace traditional gauge-panel installations with app-integrated electric systems. The country's national maritime safety authority aligns voluntary installation guidelines with insurer risk mitigation requirements. Queensland's Gold Coast marine service network faces certified installer scarcity constraining electric system deployment.
Trim Tabs Market Competitive Environment
The competitive structure tilts toward coastal manufacturing specialists with captive supply chain control over marine-grade aluminum and fiber-reinforced composites. Three player archetypes dominate: electric actuator specialists leveraging digital integration capabilities, hydraulic system incumbents defending commercial marine load capacity positions, and integrated propulsion-electronics suppliers absorbing trim control into unified vessel management platforms. M&A activity concentrates among electric architecture providers seeking installer network expansion, while strategic partnerships proliferate between composite material suppliers and saltwater-focused OEMs.
Among North American coastal specialists, Bennett Marine, Lenco Marine, and Volvo Penta occupy distinct positioning vectors. Bennett Marine represents the legacy hydraulic incumbent archetype with established commercial marine certification pathways. Lenco Marine exemplifies the electric actuator specialization model that recreational segments favor for simplified installation. Volvo Penta anchors the integrated propulsion-electronics convergence pattern, absorbing trim functionality into unified vessel management architectures rather than standalone mechanical systems.
| Leading Market Players |
|---|
| Bennett Marine |
| Lenco Marine |
| Volvo Penta |
| Linear Devices Corporation |
| Zipwake |
| T-H Marine |
| Smart Tabs |
| CMC Marine |
| Trim Master Marine |
| Others |
Value Chain & Pricing Dynamics
Marine-grade aluminum price indices cascade through trim tab manufacturing tiers, compressing margins for hydraulic system producers while electric actuator suppliers offset material exposure through electronics integration and software-enabled service bundles.
Pricing Analysis
Unbundled component sales dominate commercial marine procurement, while recreational segments favor integrated packages combining hardware, installation, and digital control interfaces. Three-tier pricing structure across premium, standard, and economy levels separates CAN bus-enabled electric systems from basic hydraulic configurations and entry-level mechanical tabs. Cost compression in aluminum-intensive hydraulic tiers is intensifying because smelting energy economics transmit volatility into input costs. Charter fleet operators exhibit highest price sensitivity, whereas OEM specification committees prioritize certification compliance over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from US Coast Guard certified vessel operators mandate qualified suppliers across both hydraulic fluid networks and electric actuator electronics, preventing single-source dependencies in critical stability systems. Manufacturing gravity centers on the United States, China, and Italy, with composite material fabrication concentrating in Mediterranean yacht-building corridors and brushless DC motor production anchoring in the Yangtze River Delta. Supply chains draw from marine-grade aluminum billet, fiber-reinforced polymer resin systems, and semiconductor motor controllers. Single-source vulnerability in specialized hydraulic cylinder casting creates exposure for commercial fleet operators. Distribution runs through coastal marine service networks and OEM direct specification channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The trim tabs market functions as a stable compounder, with regulatory stability mandates under 46 CFR generating replacement-driven demand cycles that resist cyclical downturns.
For Market Incumbents: Anchor defensive positioning through captive supply of fiber-reinforced composite materials and backward integration into marine-grade aluminum finishing capabilities. Electric actuator specialists threaten hydraulic incumbents through CAN bus integration; certification investment in US Coast Guard type approval pathways preserves specification authority in passenger vessel segments. For New Entrants and Emerging Players: Marine service networks in dispersed coastal regions represent the most penetrable channel architecture, given certified electrician scarcity constrains electric system deployment. Target aftermarket retrofit installations in Gulf Coast recreational fleets where saltwater corrosion accelerates replacement cycles. Pursue white-label manufacturing partnerships with established marine electronics distributors to bypass OEM specification barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with electric actuator specialists possessing CAN bus integration capabilities and installer training infrastructure. Five-to-ten year viability hinges on harbor craft electrification mandate expansion beyond pilot programs. Monitor Baltic Sea passenger vessel procurement patterns as lead indicator for hydraulic-to-electric architecture substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Actuator Manufacturing Scale-Up | Brushless DC production expansion captures recreational segment preference for digital integration. |
| Composite Material Backward Integration | In-house fiber-reinforced polymer fabrication secures saltwater corrosion-resistant supply for Gulf Coast demand. |
| Installer Certification Program Development | Marine electrician training infrastructure alleviates deployment bottlenecks in dispersed coastal service networks. |
| CAN Bus Protocol Licensing Agreement | Standardized communication interfaces enable synchronization with Volvo Penta and other propulsion electronics. |
| US Coast Guard Type Approval Investment | 46 CFR certification pathways unlock specification access for small passenger vessel operators under tightened mandates. |
Study Parameters
Direct dialogue with trim tab product managers, marine OEM procurement directors, Coast Guard certification engineers, and coastal service network operators grounded qualitative findings in operational reality. Secondary validation drew from EPA marine engine emission filings, US Coast Guard 46 CFR regulatory dockets, ABYC installation guideline publications, and EU Marine Equipment Directive certification databases. Bottom-up and top-down triangulation cross-checked unit shipment estimates against aluminum and composite material consumption patterns.
Bottom-up modeling aggregated vessel fleet data by propulsion type and operating environment, while top-down analysis tracked marine electronics and control surface procurement across OEM and aftermarket channels. Segmentation dimensions included actuation technology, material composition, end-user category, and regional regulatory cluster. CAGRs were derived from fitted trend analysis against historical replacement cycle data and regulatory mandate implementation schedules. Harbor craft electrification timelines and REACH hydraulic fluid restriction enforcement velocity served as industry-specific forecast inputs.
Revisions become necessary when EPA emission standard enforcement intensity shifts, aluminum smelting capacity disruptions materialize, or harbor craft electrification mandates accelerate beyond pilot program scope. Deviation in US Coast Guard 46 CFR stability mandate implementation timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
GCC ROV Market
Marine
Marine Spreader Lights Market
Marine
Marine Airbags Market
Marine
Autonomous Ships Market
Marine
Global Discount-Marine Trenchers Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Marine Asset Integrity Services Market
Marine
Japan Marine Composites Market
Marine
Sailboat Market
Marine
Electric Boat Market
Marine
Electric Boat and Ship Market
Marine
Recreational Vessel Battery Market
Marine
Sailboat Propellers Market
Marine
Boat Ladder Market
Marine
Swamp Boat Market
Marine
Boat Cleat Market