
 Deep-V Boat Market | 2026-2036
Deep-V Boat Market Size, Share, and Industry Trends Forecast 2026-2036
Deep-V Boat Market Analytics
NMMA certification is redrawing competitive boundaries for hull manufacturers seeking retail distribution. Brunswick Corporation leverages its vertical integration across engine and boat production to sustain pricing power. Lund Boats anchors its position through aluminum Deep-V specialization in freshwater angling segments. White River Marine Group competes via scale advantages across multiple hull brands and dealer networks.
A Deep-V boat employs a hull design with a sharp deadrise angle, typically twenty degrees or more at the transom, that slices through waves rather than riding over them. Fiberglass variants dominate offshore sport and leisure configurations where weight tolerance supports higher horsepower ratings, while aluminum Deep-V hulls from builders like Crestliner and G3 Boats lead in freshwater fishing applications where trailering and durability matter. Outboard engine pairings command the largest volume position across all boat types, though sterndrive configurations retain margin concentration in premium leisure segments. Fishing boats represent the most mature category with established replacement cycles, whereas sports boats show the fastest structural expansion as performance-oriented buyers upgrade hull specifications.
US Coast Guard safety standards govern flotation, structural integrity, and capacity labeling for all vessels sold in American waters. EPA marine engine emissions regulations under the Clean Air Act are forcing powertrain redesigns that cascade into hull-engine integration requirements. NMMA certification provides voluntary but market-critical quality verification that most major retailers now require. Stakeholders must monitor how evolving carbon intensity rules reshape engine type preferences and material selection across the value chain.
Market Dynamics
EPA marine engine emissions regulations under the Clean Air Act are forcing powertrain redesigns that cascade into hull-engine integration requirements, compressing development timelines for manufacturers across all material categories.
Growth Catalysts
- NMMA Certification Mandates:Major retailers now require voluntary quality verification for shelf placement, pulling manufacturers toward standardized hull testing protocols that reduce warranty exposure.
- Aluminum Hull Innovation:Freshwater angling segments in the Great Lakes region are expanding purchases of specialized aluminum Deep-V designs that optimize trailering weight and trail durability.
- Outboard Engine Advancement:Higher horsepower ratings from integrated powertrain suppliers are enabling larger fiberglass hull configurations in offshore sport applications.
Market Restraints
- Fiberglass Raw Material Volatility:Resin and gelcoat input costs fluctuate with petrochemical feedstock pricing, pressuring margin structures in premium hull segments.
- Supply Concentration Risk:Outboard engine production concentrates among a handful of powertrain specialists, creating bottlenecks during emissions certification cycles.
- Sterndrive Technical Limitations:Inboard-outboard configurations face displacement ceilings that restrict adoption in high-horsepower offshore applications.
Strategic Opportunities
- Gulf Coast State Expansion:Recreational angling demand across Louisiana, Texas, and Florida coastal markets remains underpenetrated for specialized Deep-V fishing configurations.
- Electric Powertrain Convergence:Battery-electric propulsion systems are converging with lightweight aluminum hull designs to create new product categories for inland waterway restrictions.
- Direct-to-Consumer Channels:Manufacturer-owned digital platforms are bypassing traditional dealer networks to capture margin in custom-order sport boat segments.
Industry Challenges
- Marine Technician Shortage:Hull-engine integration complexity requires specialized fiberglass and mechanical skills that vocational programs are not producing at replacement rates.
- NMMA Certification Timeline Compression:Extended testing protocols for flotation and structural integrity are delaying new model launches by entire selling seasons.
- Legacy Sterndrive Inventory:Dealer lots carry depreciating inboard-outboard stock that competes with new outboard configurations for showroom positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deep-V Boat Market |
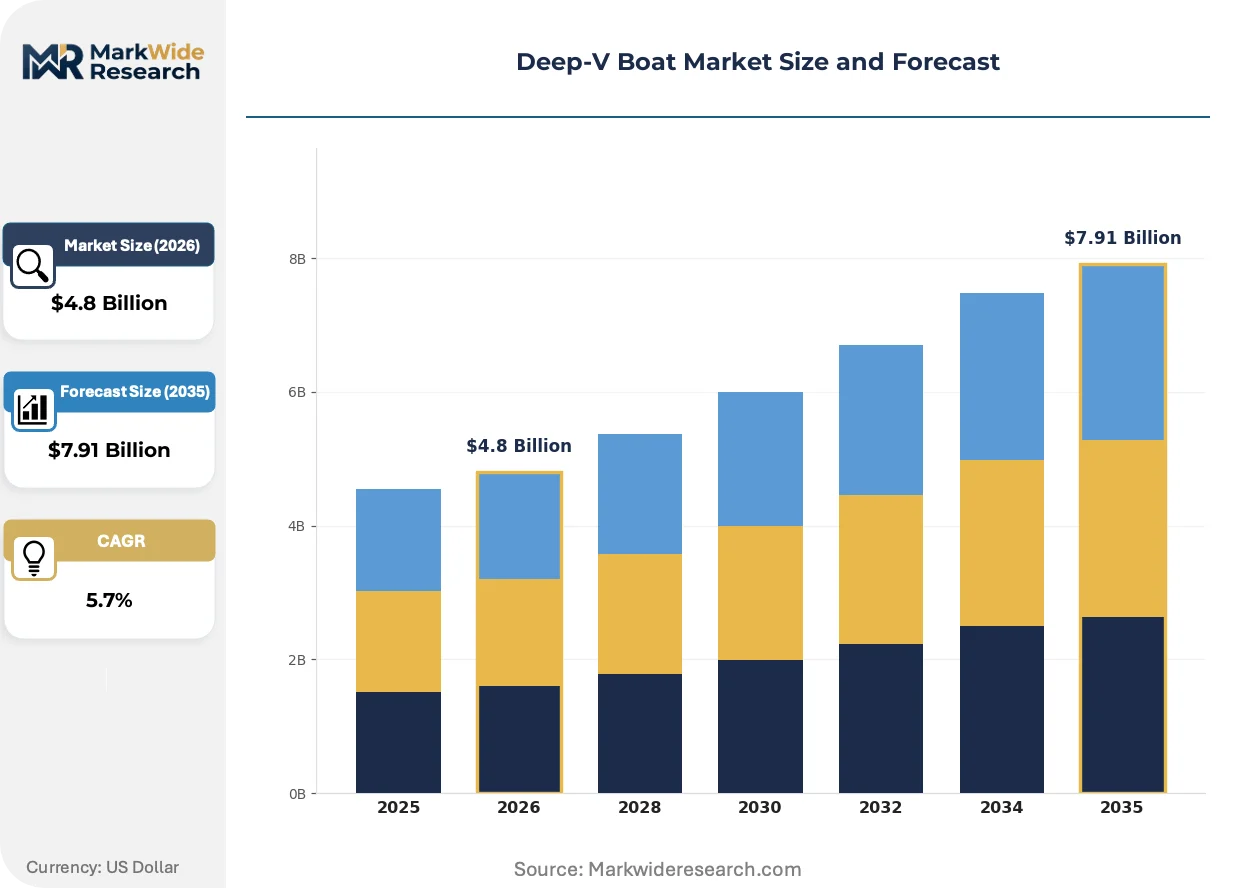
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Boat Type: Fishing Boats, Leisure Boats, Utility Boats, Sports Boats Material: Fiberglass, Aluminum, Composite, Wood Engine Type: Outboard, Inboard, Sterndrive, Jet Drive End User: Individual Consumers, Commercial Fisheries, Charter Services, Government Agencies |
| Companies Covered | Alumacraft Boats, Brunswick Corporation, Crestliner Boats, Lund Boats, White River Marine Group, G3 Boats, Polar Kraft Boats, SeaArk Boats, Qingdao Lian Ya Boat Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deep-V Boat Market Evolving Landscape
Powertrain electrification and digital hull design tools are compressing traditional development cycles while reshaping buyer expectations across recreational boating segments.
Modular battery-electric propulsion architecture is decomposing the historical bundling of engine and hull specifications. Freshwater fishing operators in Minnesota and Wisconsin are piloting electric Deep-V configurations for lake access restrictions. This technology is decomposing the traditional horsepower-based segmentation that organized dealer inventory and pricing tiers for decades.
EPA Tier 3 marine emissions standards are tightening hydrocarbon and NOx limits for gasoline outboards. Engine manufacturers are redesigning fuel injection and exhaust after-treatment systems that add weight and alter transom mounting geometry. Sterndrive leisure configurations face the steepest compliance cost increases, accelerating buyer migration toward outboard alternatives.
Buyer research behavior has shifted toward video-centric evaluation before dealership visits. YouTube and manufacturer-hosted virtual sea trials are displacing traditional boat show attendance among first-time purchasers in the Great Lakes region. This pattern concentrates information discovery into digital channels that reward vertical video formats and spec-sheet transparency over in-person sales consultation.
Deep-V Boat Market Segmentation
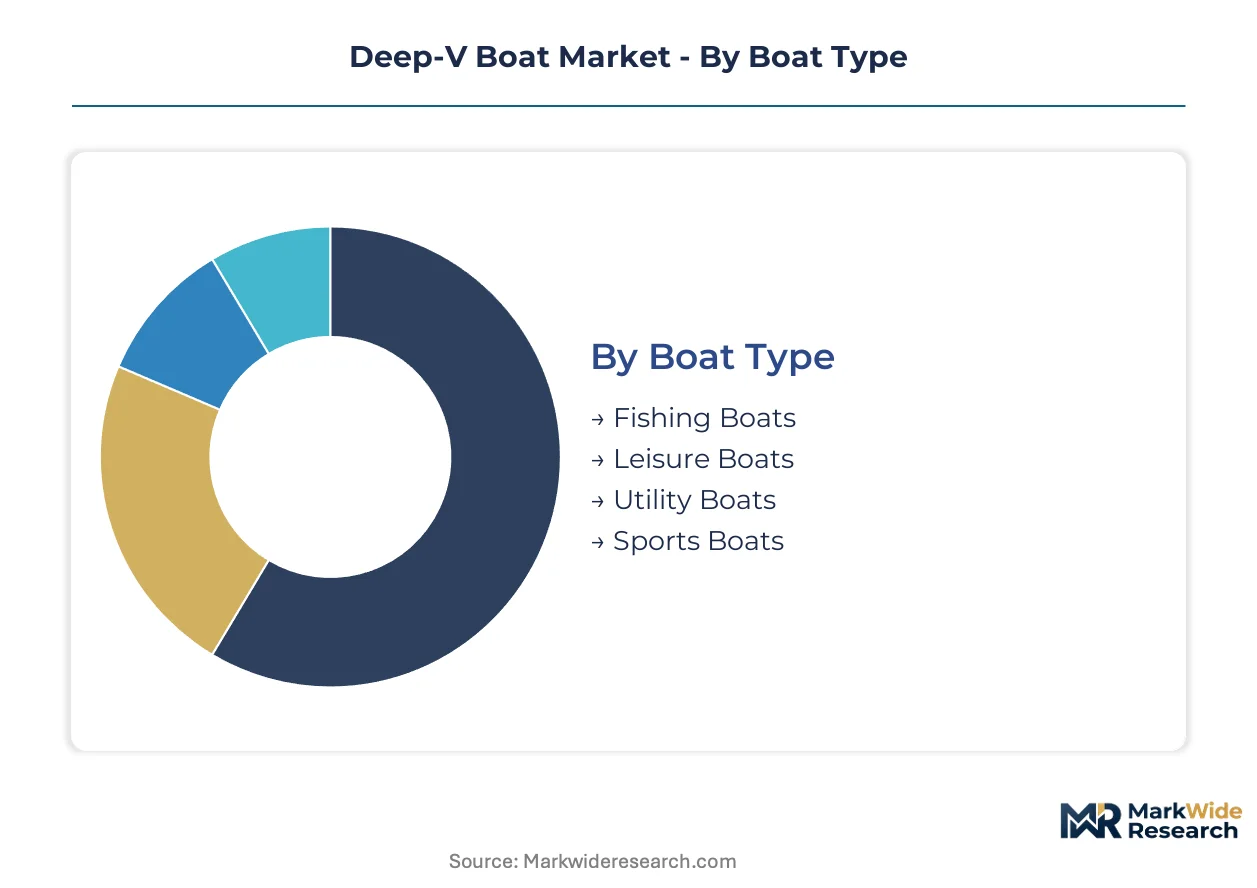
Deep-V boat purchasing decisions cascade through four interconnected dimensions that reshape manufacturing priorities and channel economics. Hull material selection determines production asset intensity, while engine configuration governs aftermarket service revenue. End-user type dictates pricing tolerance and customization depth.
Boat Type:
Margin pools concentrate in specialized fishing configurations where replacement cycles and accessory attachment rates sustain dealer profitability.
- Fishing Boats:Aluminum and fiberglass hulls optimized for rod storage, livewell systems, and trolling motor mounting dominate freshwater and inshore saltwater applications. Demand clusters across Minnesota, Wisconsin, and Michigan where walleye and bass tournaments drive specification requirements.
- Sports Boats:High-performance fiberglass Deep-V designs prioritize hull speed and handling in rough water. Florida coastal buyers upgrading from bowriders are expanding this segment most quickly as outboard horsepower ratings climb.
- Leisure Boats:Comfort-oriented configurations blend Deep-V seaworthiness with cabin amenities for family cruising.
- Utility Boats:Workhorse aluminum designs serve patrol, rescue, and commercial transport functions with minimal feature content.
The dominant share belongs to Fishing Boats, while Sports Boats is closing the gap fastest.
Material:
Cost tier stratification separates premium fiberglass from value-engineered aluminum production.
- Fiberglass:Gelcoat-finished hulls tolerate higher horsepower mounting and complex curvature for hydrodynamic efficiency. Gulf Coast offshore anglers in Texas and Louisiana specify fiberglass for bluewater durability against salt corrosion.
- Aluminum:Welded or riveted hull sheets reduce trailering weight and repair cost for freshwater operators. Great Lakes region purchases concentrate here due to seasonal haul-out requirements and road transport constraints.
- Composite:Hybrid material systems combining resin transfer molding with structural cores.
- Wood:Traditional cold-molded or plank-on-frame construction for restoration and custom builds.
Fiberglass commands the largest revenue base, though Aluminum is gaining share fastest in northern state markets.
Engine Type:
Application requirements drive divergent powertrain selection across displacement and operating environment.
- Outboard:Transom-mounted engines dominate volume through modularity, shallow draft, and service accessibility. EPA Tier 3 emissions compliance is compressing development timelines for fuel injection redesigns that add weight and alter mounting geometry.
- Sterndrive:Inboard-outboard configurations retain position in premium leisure segments where cabin space optimization matters. Technical displacement ceilings restrict adoption in high-horsepower offshore applications.
- Inboard:Direct-drive or V-drive arrangements for specialized ski and wake applications.
- Jet Drive:Impeller-based propulsion for shallow river and rescue operations.
Outboard holds the volume lead, while Sterndrive faces steepest share erosion from emissions cost pressure.
End User:
Customer type determines specification complexity and procurement channel structure.
- Individual Consumers:Retail purchasers through dealer networks or manufacturer direct platforms. YouTube and virtual sea trials are displacing traditional boat show attendance among first-time buyers in the Great Lakes region.
- Commercial Fisheries:Fleet operators prioritizing durability and fuel efficiency over amenity content.
- Charter Services:Day-trip and multi-day operators requiring passenger capacity and reliability.
- Government Agencies:US Coast Guard, state natural resource departments, and municipal patrol fleets with bid-based procurement.
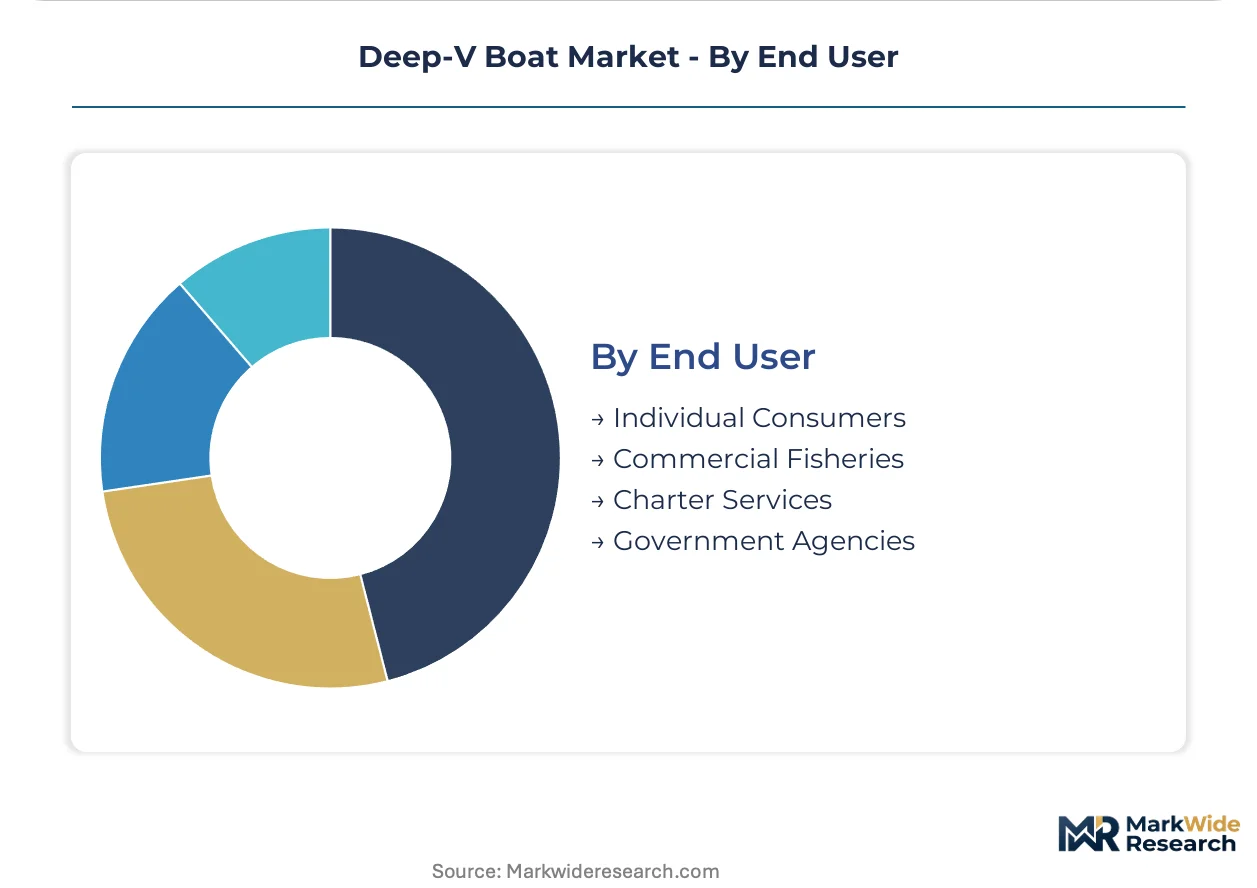
Individual Consumers generate the dominant revenue share, while Charter Services is expanding most quickly in Gulf Coast coastal markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational anglers in the United States drive the dominant share of Deep-V boat procurement, with freshwater tournament fishing and offshore saltwater applications creating distinct regional specification clusters across North American waters.
United States
Walleye and bass tournament circuits across Minnesota, Wisconsin, and Michigan sustain aluminum Deep-V demand for trailering efficiency and seasonal haul-out durability. EPA Tier 3 marine emissions standards under the Clean Air Act are compressing powertrain development timelines for outboard manufacturers serving these markets. Brunswick Corporation's vertical integration across engine and boat production anchors manufacturing concentration in the Great Lakes industrial corridor.
Canada
Multi-species freshwater angling in Ontario and Quebec expands purchases of welded aluminum hulls optimized for rocky shoreline navigation and extended trailering distances. Transport Canada vessel construction standards govern flotation and structural integrity requirements for all boats sold in Canadian waters. Manufacturing clusters in Peterborough, Ontario, and the Montreal area supply regional demand through established dealer networks serving provincial park access points.
Mexico
Sportfishing tourism along Baja California and the Yucatán Peninsula generates demand for fiberglass Deep-V configurations capable of offshore bluewater operations. Mexican environmental regulations under SEMARNAT coordinate with international emissions protocols for marine engines operating in coastal economic zones. Cabo San Lucas and Cancún serve as charter fleet concentration points where hull durability against salt corrosion determines specification requirements.
Australia
Reef fishing and estuary angling across Queensland and New South Wales sustain aluminum Deep-V adoption for shallow draft and beach launch accessibility. Australian Maritime Safety Authority standards govern commercial and recreational vessel safety certification requirements. Manufacturing concentration in Brisbane and the Gold Coast supplies domestic demand while exporting specialized designs to Pacific island markets.
United Kingdom
Sea angling clubs and charter operators along England's south coast and Scottish western isles procure Deep-V hulls for North Atlantic rough-water handling. Maritime and Coastguard Agency safety regulations enforce construction standards for vessels operating in UK territorial waters. Boatbuilding heritage in Southampton and Plymouth sustains specialized fiberglass production for offshore leisure applications.
Deep-V Boat Market Competitive Landscape
Player mix skews toward vertically integrated marine conglomerates and specialized aluminum fabricators competing across distinct freshwater and saltwater application tiers. Market structure concentrates around three strategic archetypes: diversified marine conglomerates with captive engine supply, aluminum hull specialists serving regional angling markets, and fiberglass builders targeting offshore performance segments. Competitive dynamics center on NMMA certification acquisition for retail distribution access and emissions-compliant powertrain integration partnerships.
Among North American-based fabricators, Brunswick Corporation exemplifies the conglomerate archetype through its integrated engine and boat production capabilities. Lund Boats and Crestliner Boats occupy positions within the aluminum specialization tier, serving Great Lakes freshwater angling segments with trailering-optimized hull designs. White River Marine Group represents scale-driven multi-brand consolidation across diverse price points and geographic markets.
| Leading Market Players |
|---|
| Alumacraft Boats |
| Brunswick Corporation |
| Crestliner Boats |
| Lund Boats |
| White River Marine Group |
| G3 Boats |
| Polar Kraft Boats |
| SeaArk Boats |
| Qingdao Lian Ya Boat Co. Ltd. |
| Others |
Value Network & Pricing Analysis
Capacity utilization at fiberglass resin plants in Texas and Louisiana sets price floors across premium hull segments, while aluminum sheet mills in the Midwest anchor cost structures for freshwater fishing configurations. This scale concentration creates divergent margin profiles between offshore sport and inland angling product tiers.
Pricing Analysis
Cost-plus contracts with petrochemical feedstock indexation dominate fiberglass hull procurement between manufacturers and Gulf Coast resin suppliers. Three-tier pricing structure across premium, standard, and economy levels separates NMMA-certified configurations from uncertified builds and entry-level utility designs. Pricing pressure stems from EPA Tier 3 compliance costs cascading into transom mounting geometry redesigns. Charter fleet operators in Florida and Louisiana exhibit highest price sensitivity due to fuel economy mandates, while individual tournament anglers in Minnesota and Wisconsin tolerate premium tiers for hull durability.
Supply Chain Analysis
Inbound logistics costs through Gulf Coast port congestion and container availability constraints in Houston and New Orleans shape raw material delivery schedules for gelcoat and marine-grade aluminum. Supply concentration rests on Mexico for fiberglass resin precursors, Canada for aluminum sheet, and domestic US production for marine plywood and hardware. Resin and gelcoat input dependencies create exposure to petrochemical price volatility. Single-source vulnerability concentrates in outboard engine powertrain supply from integrated manufacturers. Distribution runs through NMMA-certified dealer networks with manufacturer-owned digital platforms emerging as secondary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powertrain-hull integration platforms are restructuring competitive boundaries as electric propulsion systems create new interoperability standards between battery architecture and transom specifications. This ecosystem shift rewards manufacturers controlling both hull design and powertrain partnerships.
For Market Incumbents: Shield aluminum hull market share in Great Lakes states by accelerating welded hull automation investments before emerging electric-focused entrants achieve scale. Lock in exclusive battery-electric powertrain distribution agreements with emerging propulsion specialists to forestall dealer network poaching. Vertical integration into outboard engine service training addresses the marine technician shortage threatening aftermarket revenue retention. For New Entrants and Emerging Players: Aftermarket electric conversion kits for legacy aluminum hulls represent the most penetrable service-layer gap, as incumbents under-serve Minnesota and Wisconsin lake associations facing combustion restrictions. Target Gulf Coast charter operators with lease-to-own electric configurations that bypass capital-intensive dealer inventory requirements. Pursue direct-to-consumer digital platforms with virtual sea trial integration to circumvent established NMMA certification barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aluminum hull specialists with captive service networks and seasonal storage facilities in northern states. Long-term viability centers on manufacturers bridging freshwater and saltwater application expertise through material innovation. Monitor EPA marine emissions rulemaking timelines as the critical inflection signal for powertrain technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| NMMA Certification Acceleration | Retail distribution access hinges on flotation and structural integrity testing protocols that major retailers now mandate. |
| Electric Powertrain Integration | Battery-electric propulsion partnerships with Minnesota and Wisconsin lake authorities create first-mover regulatory advantage. |
| Dealer Network Consolidation | Scale economies in service training and parts inventory defend margin against manufacturer direct-to-consumer encroachment. |
| Aluminum Hull Automation | Robotic welding investments in Great Lakes manufacturing clusters compress labor costs for freshwater angling segments. |
| Virtual Sea Trial Platforms | YouTube-centric buyer research behavior rewards video-first digital channels that displace traditional boat show attendance. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across hull fabricators, outboard engine manufacturers, and marine dealer networks. Primary interviews captured perspectives from boatyard operations managers, tournament angling organizers, NMMA certification engineers, and charter fleet procurement officers. Secondary validation drew from EPA marine emissions filings, US Coast Guard safety standard updates, NMMA certification databases, and regional trade association registration data. Bottom-up hull production estimates triangulated against top-down recreational boating expenditure surveys.
Across the analysis window, volume and value outputs reflect segmentation modeling across hull material, engine configuration, boat type, and end-user category with geographic disaggregation to state-level demand clusters. CAGRs were derived from trend extrapolation of replacement cycle frequencies and powertrain technology transition curves. Industry-specific forecast inputs incorporated EPA Tier 3 compliance cost pass-through assumptions and aluminum versus fiberglass buyer preference shifts in northern state markets.
Forecasts assume regulatory continuity in EPA marine emissions standards and US Coast Guard safety regimes; material policy shifts would require re-modeling of powertrain development timelines and hull-engine integration requirements. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Marine Asset Integrity Services Market
Marine
Ship/Boat Keel Market
Marine
Electric Boat Market
Marine
Marine Elevators Market
Marine
Marine Glass Market
Marine
Asia-Pacific Electric Boat Market
Marine
Marine Big Data Market
Marine
Marine Stabilizers Market
Marine
Marine Navigation System Market
Marine
Marine LED Lights Market
Marine
Asia-Pacific Marine Communication Systems Market
Marine
Singapore Container Transshipment Market
Marine
Asia-Pacific Leisure Boat Marine Coating Market
Marine
Boat Steering Systems Market
Marine
Digital Nautical Charts Market
Marine
Autonomous Underwater Vehicle (AUV) Market