
 South America Automotive High Performance Electric Vehicles Market | 2026-2036
South America Automotive High Performance Electric Vehicles Market Size, Share, and Industry Trends Forecast 2026-2036
South America Automotive High Performance Electric Vehicles Market Analytics
Market Context
The gap between premium performance specifications and commodity electric mobility is shifting wider across South America as battery costs diverge and thermal management separates entry from flagship segments. Porsche AG leverages its motorsport engineering heritage to sustain price premiums in Brazilian and Argentine showrooms. Tesla Inc. anchors its regional position through direct-to-consumer channel control and proprietary supercharger placement. BYD Co. Ltd. competes on manufacturing scale, occupying the mid-premium tier with localized assembly partnerships.
Technical Definition and Segment Structure
South America Automotive High Performance Electric Vehicles denote battery-electric passenger and light commercial vehicles engineered for sustained output exceeding 150 kW, incorporating liquid-cooled battery architectures, multi-motor torque vectoring, and sub-five-second acceleration capability for enthusiast and fleet-performance applications. Sports EVs command the highest margin pools due to low-volume exclusivity and carbon-fiber structural premiums, while luxury EVs lead absolute volume across São Paulo and Buenos Aires metropolitan corridors. Lithium-ion battery technology dominates installed capacity, though solid-state chemistries attract R&D allocation for thermal stability in tropical operating conditions.
Regulatory Framework and Outlook
Brazil's ANFAVEA emissions protocols and Argentina's national automotive regulator enforce escalating efficiency benchmarks that restrict internal-combustion performance variants and redirect OEM development budgets toward electrified powertrains. ANVISA safety certification requirements for high-voltage systems add compliance layers that favor established multinationals with in-house homologation teams. Stakeholders must monitor how Chile's energy regulator and Colombia's mining-energy planning unit coordinate cross-border charging standards, as interoperability decisions will determine which battery architectures achieve Andean scale.
Market Dynamics
Brazil's Inovar-Auto successor frameworks and Argentina's efficiency mandates are redirecting OEM engineering budgets from internal-combustion performance variants toward electrified powertrains, compressing development timelines for liquid-cooled battery architectures.
Growth Catalysts
- ANFAVEA emissions protocols:Brazil's automotive association enforces escalating efficiency benchmarks that restrict high-output combustion engines and mandate electrified alternatives for fleet operators.
- Charging infrastructure density:São Paulo state's supercharger corridor deployment outpaces Andean markets, concentrating affluent buyer pools and reducing range anxiety for performance EV purchasers.
- Lithium-ion thermal management:Advances in liquid-cooled battery architectures enable sustained 150 kW output in tropical operating conditions, opening enthusiast segments previously blocked by thermal derating.
Market Restraints
- Lithium carbonate volatility:Argentina's salt flat extraction constraints and Chilean state quota policies concentrate cathode material supply, amplifying cell cost swings for high-capacity performance packs.
- ANVISA certification timelines:Brazil's health regulator adds homologation layers for high-voltage systems that favor established multinationals with in-house compliance teams, extending market entry for new entrants.
- Grid interconnection gaps:Northeast Brazilian states and Colombian Andean corridors lack 350 kW charging backbones, capping performance EV utility outside metropolitan cores.
Strategic Opportunities
- Colombian mining-energy coordination:The national planning unit's cross-border charging standard negotiations create first-mover advantages for battery architectures achieving Andean interoperability.
- Fleet-performance electrification:Brazilian logistics operators are expanding procurement of high-output electric commercial vehicles for São Paulo-Porto Alegre corridor routes, opening B2B volume pools.
- Solid-state R&D allocation:Thermal stability advantages in tropical climates are attracting development investment for next-generation chemistries that could compress premium segment pricing.
Industry Challenges
- Homologation talent scarcity:ANVISA high-voltage certification expertise concentrates in São Paulo engineering consultancies, creating recruitment bottlenecks for manufacturers establishing Brazilian assembly.
- Multi-motor integration complexity:Torque vectoring calibration for tropical humidity and altitude variation demands specialized drivetrain engineers absent from regional supplier bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Automotive High Performance Electric Vehicles Market |
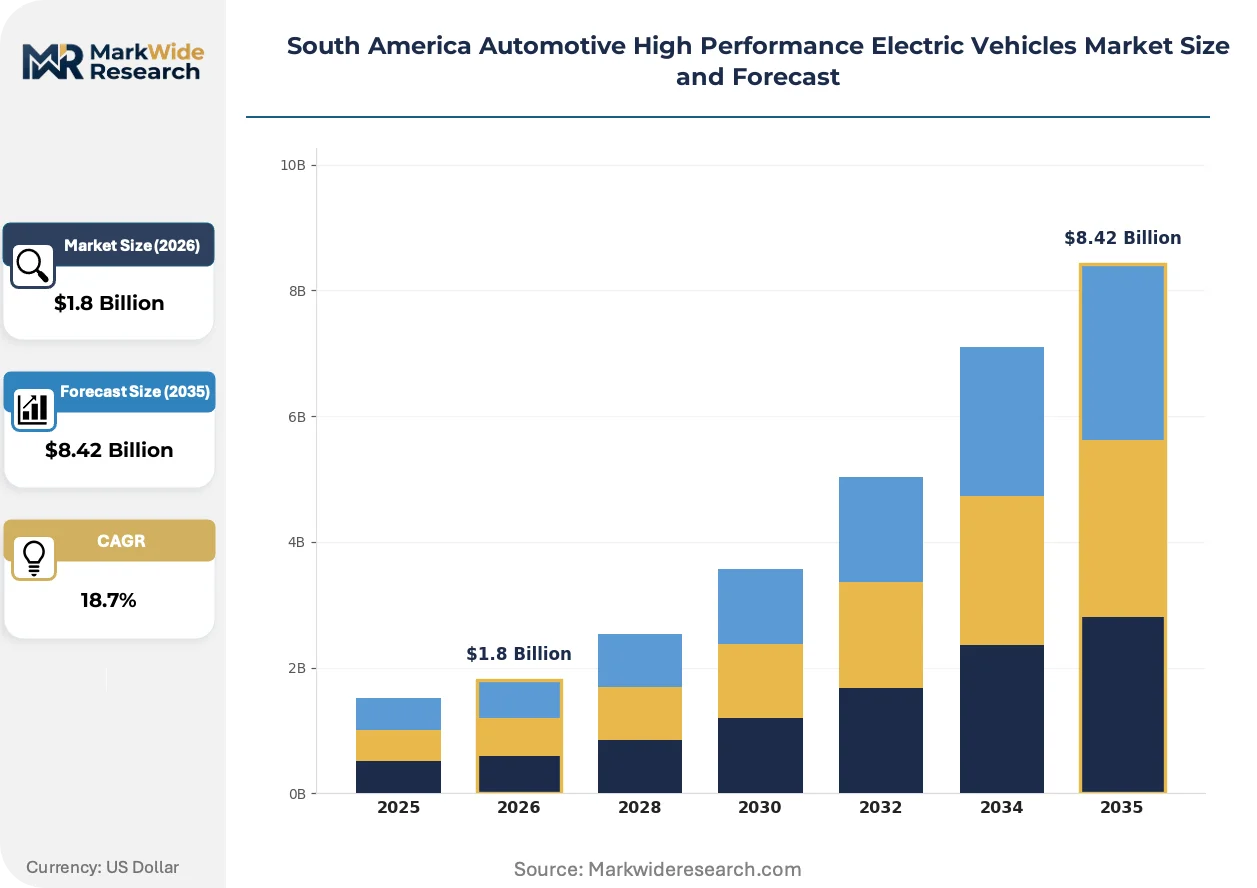
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.42 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luxury EVs, Sports EVs, Commercial EVs, SUVs Battery Technology: Lithium-ion, Solid-state, Nickel-metal Hydride, Lead-acid End User: Individual Consumers, Fleet Operators, Government Agencies, Ride-sharing Services Charging Infrastructure: Public Charging Stations, Home Chargers, Fast Chargers, Workplace Charging |
| Companies Covered | BYD Co. Ltd., Porsche AG, Tesla Inc., General Motors, Stellantis, Volkswagen AG, Renault, Rimac Automobili, BMW Group, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Automotive High Performance Electric Vehicles Market Evolving Landscape
Thermal management architectures and procurement models are actively restructuring competitive positioning in South American performance EV segments, with regulatory coordination emerging as a determinant of battery standard adoption.
Silicon-carbide power electronics enable higher switching frequencies with reduced thermal losses, critical for sustained high-output operation. São Paulo-based fleet operators and Argentine luxury buyers are adopting these inverters at accelerating rates. The technology is converging with 800-volt battery platforms to compress charging downtime and extend thermal endurance in tropical climates.
Brazil's ANFAVEA protocols and Argentina's national automotive regulator enforce efficiency benchmarks that progressively restrict internal-combustion performance variants. OEM development budgets are reallocating toward electrified powertrains to maintain compliance. Sports EV segments face the steepest engineering penalties, driving consolidation around liquid-cooled architectures capable of meeting dual certification requirements.
Direct-to-consumer channel control is displacing traditional dealership networks for premium performance EVs. Tesla's proprietary supercharger placement and BYD's localized assembly partnerships demonstrate alternative route-to-market structures. This pattern concentrates in São Paulo and Buenos Aires metropolitan corridors where digital-native buyer segments dominate initial adoption curves.
South America Automotive High Performance Electric Vehicles Market Segmentation
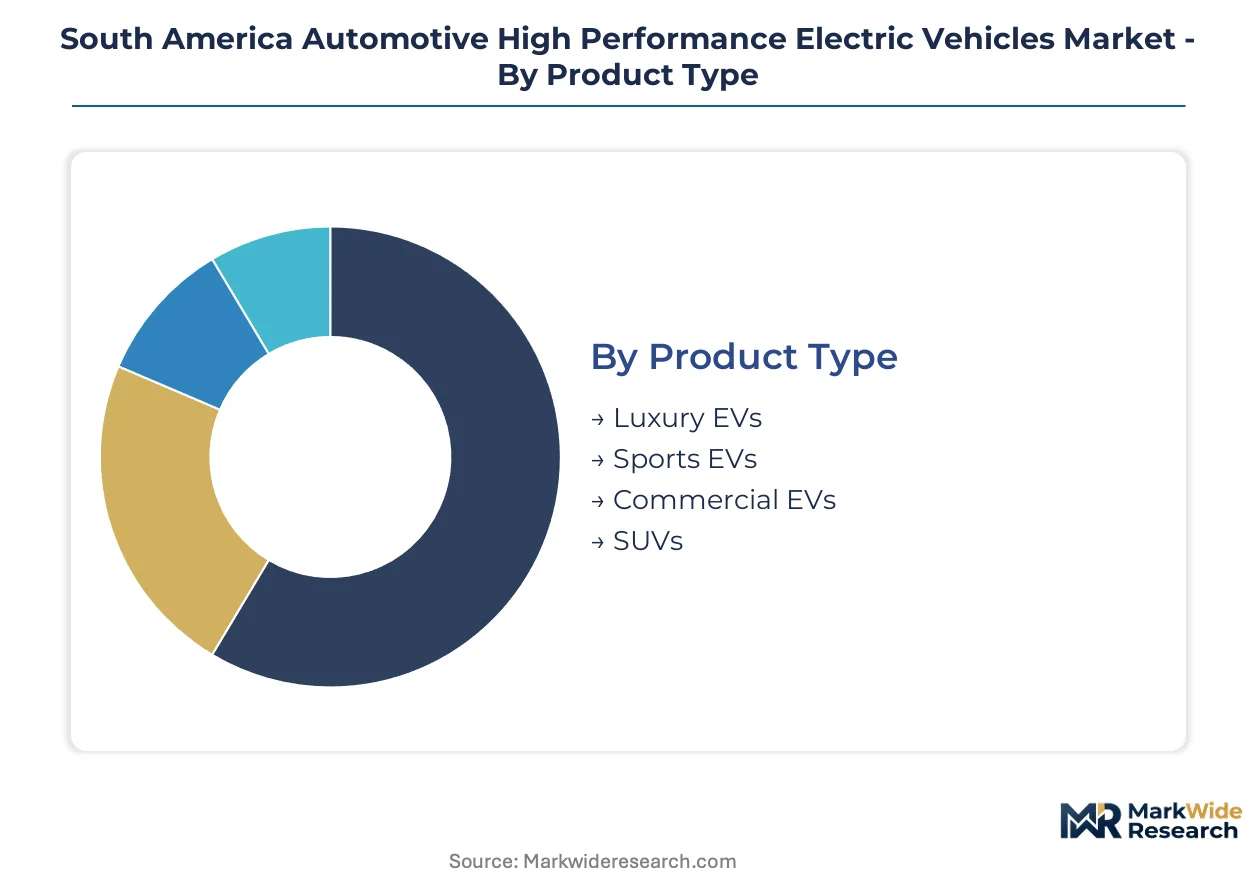
Performance EV procurement patterns diverge sharply across buyer types and use cases in South America. Battery chemistry choices and charging access constraints reshape how segments capture value across Brazilian and Argentine metropolitan corridors.
Product Type:
Purchase intent splits between badge prestige and fleet operating economics, with thermal endurance requirements varying by duty cycle intensity.
- Sports EVs:Carbon-fiber monocoque architectures and dual-motor torque vectoring define this segment. São Paulo's enthusiast buyer pool sustains low-volume exclusivity despite premium pricing tiers.
- Luxury EVs:Extended-wheelbase sedans with 800-volt platforms and air suspension dominate absolute volume. Buenos Aires and São Paulo metropolitan corridors concentrate affluent household demand where charging infrastructure density reduces range anxiety barriers.
- Commercial EVs:High-output electric vans and light trucks for São Paulo-Porto Alegre logistics routes.
- SUVs:All-wheel-drive performance crossovers with elevated thermal management capacity for Andean altitude variation.
Volume sits with Luxury EVs; growth tilts toward Commercial EVs.
Battery Technology:
Tropical operating conditions and ANFAVEA efficiency protocols concentrate R&D investment toward thermal stability improvements.
- Lithium-ion:Nickel-cobalt-manganese cathode formulations with liquid-cooled architectures dominate installed capacity. Brazilian assembly partnerships source cells through Chilean state quota channels, exposing cost volatility to Andean supply concentration.
- Solid-state:Sulfide-electrolyte prototypes promise 40% energy density gains and eliminated thermal runaway risk. Argentine salt flat extraction constraints are redirecting cathode material sourcing toward Colombian hard-rock alternatives.
- Nickel-metal Hydride:Legacy hybrid applications in commercial fleet retrofits.
- Lead-acid:Auxiliary power units for low-voltage cabin systems in budget performance variants.
Deployment concentrates on Lithium-ion; development momentum favors Solid-state.
End User:
Procurement scale and certification complexity favor established multinationals with in-house ANVISA homologation teams.
- Fleet Operators:Brazilian logistics companies are expanding high-output electric commercial vehicle procurement for corridor routes with predictable duty cycles. Operating cost arbitrage against diesel alternatives drives payback calculations.
- Individual Consumers:Digital-native buyer segments in São Paulo and Buenos Aires metropolitan areas dominate initial adoption curves. Direct-to-consumer channel control displaces traditional dealership networks for premium configurations.
- Government Agencies:Municipal procurement for executive transport fleets with local content compliance requirements.
- Ride-sharing Services:High-utilization operators prioritizing fast-charging compatibility and battery warranty terms.
Absolute volume flows to Individual Consumers; expansion velocity clusters with Fleet Operators.
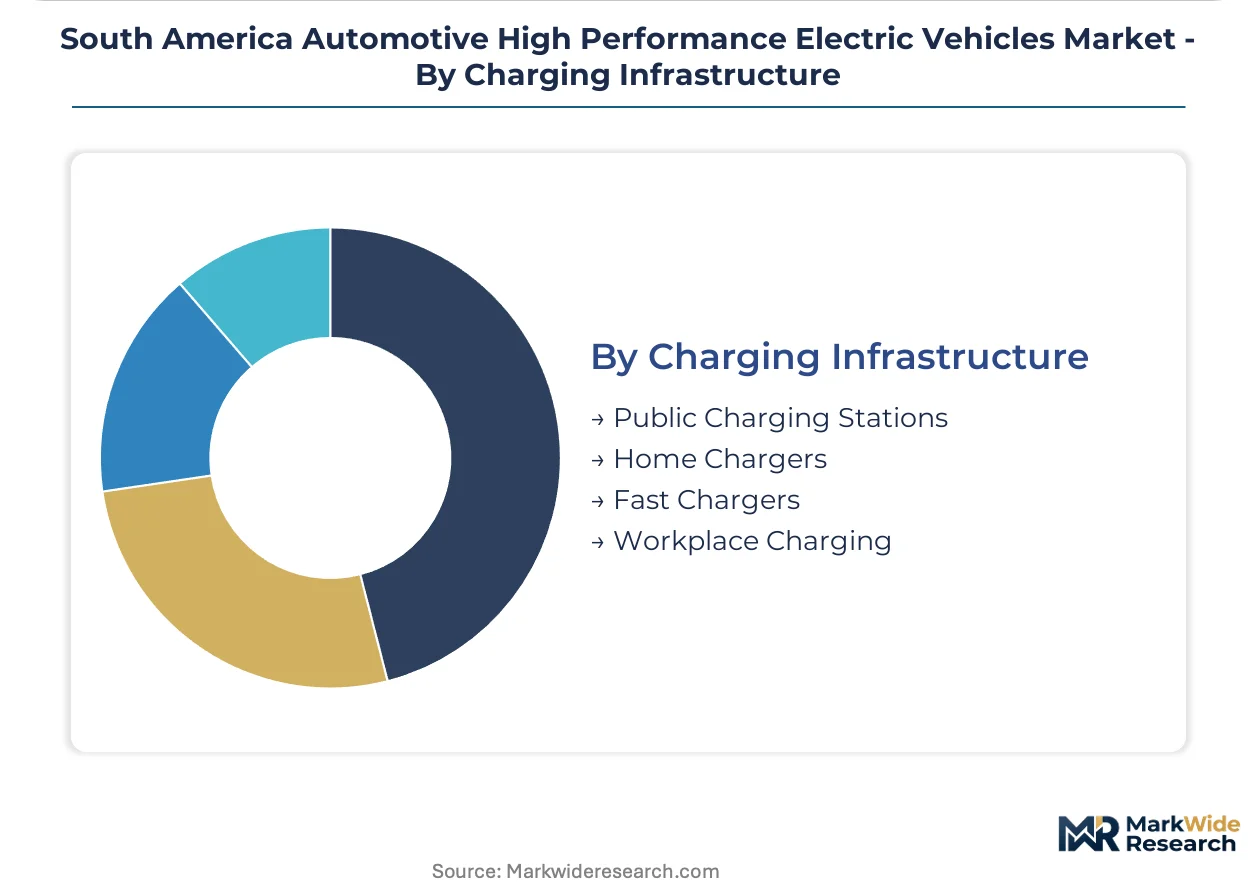
Charging Infrastructure:
Grid interconnection capacity and real estate access determine deployment feasibility across metropolitan and corridor applications.
- Fast Chargers:350 kW liquid-cooled cable systems enable sub-20-minute replenishment for 800-volt battery architectures. São Paulo state's supercharger corridor deployment outpaces Andean markets, anchoring performance EV utility.
- Public Charging Stations:AC destination chargers at retail and hospitality locations capture dwell-time revenue. Northeast Brazilian states lack distribution grid capacity for high-power backbones, capping network expansion.
- Home Chargers:Residential wallbox installations with load management for overnight replenishment.
- Workplace Charging:Employer-subsidized AC charging for commuter fleet segments.
Network density centers on Fast Chargers; penetration depth extends through Home Chargers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's supercharger corridor deployment anchors South American demand concentration, with metropolitan charging density outpacing Andean markets and concentrating affluent buyer pools for sustained high-output electric mobility.
Brazil
Fleet operators along the São Paulo-Porto Alegre logistics corridor are expanding procurement of high-output electric commercial vehicles for predictable duty cycles. ANFAVEA emissions protocols enforce escalating efficiency benchmarks that progressively restrict internal-combustion performance variants. São Paulo metropolitan area concentrates charging infrastructure investment and digital-native consumer adoption curves.
Argentina
Buenos Aires metropolitan corridors sustain absolute volume for luxury EV segments where charging infrastructure density reduces range anxiety barriers. The national automotive regulator enforces efficiency mandates that redirect OEM engineering budgets toward electrified powertrains. Córdoba's industrial belt hosts assembly partnerships adapting liquid-cooled battery architectures for local content compliance.
Chile
Atacama salt flat extraction constraints concentrate cathode material supply and amplify cell cost volatility for high-capacity performance packs. The national energy regulator coordinates cross-border charging standards that will determine which battery architectures achieve Andean scale. Santiago's metropolitan charging network expansion lags São Paulo density but attracts solid-state R&D investment for tropical thermal stability.
Colombia
Bogotá-based logistics operators are piloting high-output electric commercial vehicles for Andean altitude corridor routes with specialized thermal management requirements. The national mining-energy planning unit's cross-border charging standard negotiations create first-mover advantages for battery architectures achieving regional interoperability. Medellín's engineering consultancies develop torque vectoring calibration expertise for tropical humidity conditions.
Uruguay
Montevideo's executive transport fleet procurement prioritizes local content compliance and fast-charging compatibility for high-utilization municipal applications. The national energy utility's grid interconnection investments enable 350 kW charging backbone deployment along coastal corridors. Punta del Este's hospitality sector anchors destination charging infrastructure for luxury EV dwell-time revenue models.
South America Automotive High Performance Electric Vehicles Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal management sophistication and direct-to-consumer channel control. The vendor base organizes into three tiers: established multinationals with in-house ANVISA homologation teams, scale-driven Asian manufacturers with localized assembly partnerships, and low-volume European specialists leveraging motorsport heritage. Dominant competitive moves include strategic partnerships for charging infrastructure placement and portfolio diversification into fleet-performance commercial variants.
Among scale-driven manufacturers, BYD Co. Ltd. and Tesla Inc. exemplify alternative route-to-market structures through localized assembly and proprietary supercharger networks respectively. Porsche AG occupies a position within the heritage-premium tier, leveraging engineering credibility to sustain price premiums in Brazilian and Argentine showrooms. These three anchors demonstrate how channel control, manufacturing scale, and brand positioning create distinct competitive vectors across São Paulo and Buenos Aires metropolitan corridors.
| Leading Market Players |
|---|
| BYD Co. Ltd. |
| Porsche AG |
| Tesla Inc. |
| General Motors |
| Stellantis |
| Volkswagen AG |
| Renault |
| Rimac Automobili |
| BMW Group |
| Others |
Value Network & Pricing Analysis
Lithium carbonate spot benchmarks from Chilean state quota channels cascade through cathode material costs into tiered battery pack pricing, compressing margins for high-capacity performance architectures while amplifying cost premiums for liquid-cooled thermal management systems.
Pricing Analysis
Value-based pricing anchored to sustained kW output and thermal endurance underwrites premium positioning for sports EV configurations. Three-tier pricing structure across carbon-fiber monocoque, aluminum-intensive, and steel-platform architectures separates badge prestige tiers. Cost compression in mid-premium segments intensifies because BYD's localized assembly partnerships compress landed costs. Fleet operators exhibit highest price sensitivity due to total-cost-of-ownership calculations, while individual enthusiasts in São Paulo show lowest sensitivity to carbon-fiber structural premiums.
Supply Chain Analysis
Single-source vulnerability sits with Chilean Atacama salt flat extraction for cathode-grade lithium carbonate. Cell manufacturing concentrates in China, South Korea, and Japan, with Brazilian assembly partnerships drawing from these hubs for nickel-cobalt-manganese formulations. Logistics chokepoints through Panama Canal routes amplify lead time volatility for 800-volt power electronics. Distribution runs through São Paulo-based engineering consultancies with ANVISA homologation expertise, creating bottlenecks for new market entrants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's ANVISA high-voltage certification requirements erect a cost-of-compliance barrier that entrenches incumbents with in-house homologation teams, filtering out capital-constrained entrants unable to sustain multi-year approval timelines.
For Market Incumbents: Extend proprietary supercharger placement along São Paulo-Porto Alegre corridor routes to lock in fleet operator loyalty before charging interoperability standards crystallize. Deepen backward integration into Chilean lithium offtake agreements to insulate cell cost volatility from state quota fluctuations. Solid-state R&D partnerships with Argentine salt flat operators counter emerging thermal stability advantages from Asian competitors. For New Entrants and Emerging Players: Direct-to-consumer digital channels bypass traditional dealership networks concentrated in metropolitan São Paulo and Buenos Aires. Colombian Andean corridor logistics operators represent the most penetrable white-space segment, with Bogotá-based fleet procurement prioritizing altitude-calibrated thermal management. BYD's localized assembly partnership model offers a replicable go-to-market template for mid-premium positioning. For Investors and Strategic Acquirers: Distressed-cycle entries favor engineering consultancies with ANVISA certification expertise in São Paulo's industrial belt. Long-term viability hinges on regulatory compliance moats widening through escalating efficiency mandates across the analysis window. Watch for Chilean energy regulator announcements on cross-border charging standards as the inflection signal determining which battery architectures achieve Andean scale.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locked Chilean lithium offtake insulates Porsche's Brazilian assembly from cathode cost volatility. |
| Charging Infrastructure Partnership | Tesla's proprietary supercharger placement anchors São Paulo corridor fleet utility. |
| Software-Defined Vehicle Investment | Multi-motor torque vectoring calibration for tropical humidity demands specialized firmware development. |
| Geographic Manufacturing Footprint | Córdoba industrial belt partnerships enable Argentine local content compliance for luxury EV segments. |
| Platform Standardization | 800-volt architecture consolidation reduces thermal management complexity across sports and luxury variants. |
Research Methodology
Independent corroboration across OEM platform engineering directors, ANVISA regulatory affairs specialists, and São Paulo fleet procurement managers underwrites the qualitative findings. Secondary validation draws from ANFAVEA emissions protocol filings, Chilean state quota policy documents, and IHS Markit vehicle registration databases. Bottom-up segment sizing triangulates against top-down macroeconomic anchors across the analysis window.
Comparable-period anchoring to historical efficiency mandate implementation timelines structures the projection horizon. Segmentation dimensions span vehicle class, battery chemistry, propulsion architecture, and regional regulatory cluster. CAGRs derive from installed base growth rates moderated by charging infrastructure deployment lags. Forecast inputs incorporate lithium carbonate price elasticity and ANVISA certification timeline distributions.
The model holds under stable Chilean state quota policy and continued ANFAVEA efficiency escalation; deviation in cross-border charging standard interoperability or Argentine salt flat extraction constraints would shift volume concentration patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle Electronic Expansion Valve (EXV) Market
Electric Vehicles
Embedded System for Electric Vehicle Market
Electric Vehicles
Foldable Electric Car Market
Electric Vehicles
Hybrid Electric Vehicle Battery Market
Electric Vehicles
Japan Electric Vehicle Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Vehicle Battery Market
Electric Vehicles
EV Thermal Management System Market
Electric Vehicles
Global Electric Vehicle (EV) Management Solution Market
Electric Vehicles
Europe Automotive High Performance Electric Vehicle Market
Electric Vehicles
EV Transmission System Market
Electric Vehicles
RV SLI Battery Market
Electric Vehicles
Electric Vehicle Ambient Lighting Market
Electric Vehicles
Asia-Pacific Electric Vehicle Thermal Management System Market
Electric Vehicles
Electric Delivery Vans Market
Electric Vehicles
Global Automotive Lithium Ion Battery Controller Market