
 Plastic Surgery Scaffolds Market | 2026-2036
Plastic Surgery Scaffolds Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Surgery Scaffolds Market Intelligence
Modular scaffold kits is hardening as the dominant packaging format, letting surgeons mix polymer bases with bioactive coatings rather than buying fixed configurations. Integra LifeSciences Corporation leverages its regenerative tissue portfolio to anchor hospital procurement contracts across burn and reconstruction units. Johnson & Johnson competes through its DePuy Synthes channel, while MTF Biologics specializes in allograft-derived matrices for soft-tissue repair.
Plastic surgery scaffolds are three-dimensional porous structures, typically fabricated from collagen, polylactic acid, or polycaprolactone with pore sizes ranging from 50 to 400 microns, designed to support cell infiltration and extracellular matrix deposition during dermal or subcutaneous tissue regeneration. Hydrogels dominate current revenue owing to their injectable delivery and hydration-matching properties, though 3D-printed composites capture the fastest expansion as patient-specific geometries reduce revision rates. Electrospinning occupies the premium tier for nanofiber architectures in facial reconstruction, where surface-area-to-volume ratios direct fibroblast alignment.
The FDA's 510(k) pathway for absorbable surgical meshes shapes product development timelines and clinical evidence requirements for US market access, while the EU Medical Device Regulation mandates biological safety testing that elevates compliance costs for European entrants. ISO 10993 biocompatibility standards function as the baseline threshold for multi-jurisdiction filings. Stakeholders must weigh biodegradable polymer degradation kinetics against regulatory documentation burdens when prioritizing R&D portfolios.
Market Dynamics
Modular scaffold kits are compressing procurement cycles by letting reconstructive surgery centers customize polymer bases with bioactive coatings rather than accepting fixed configurations from single-source suppliers.
Growth Catalysts
- EU Medical Device Regulation biological safety testing:The MDR's elevated compliance requirements favor scaffold manufacturers with established ISO 10993 documentation, accelerating consolidation around proven biopolymer platforms.
- Injectable hydrogel delivery systems:Aesthetic surgery clinics in Germany's specialized clusters are prioritizing hydration-matched scaffolds that reduce operative time and post-procedure monitoring.
- Electrospun nanofiber architectures:Facial reconstruction units are specifying surface-area-to-volume ratios above 50:1 to direct fibroblast alignment in dermal regeneration protocols.
Market Restraints
- Polycaprolactone feedstock volatility:Medical-grade polymer supply concentrates among three European chemical processors, exposing scaffold fabricators to input cost swings without long-term offtake agreements.
- Degradation kinetic documentation:The FDA's 510(k) pathway requires 24-month absorption profiles for absorbable surgical meshes, extending clinical evidence timelines for novel copolymer formulations.
- Allograft-derived matrix substitution:MTF Biologics and tissue banks are capturing soft-tissue repair cases with decellularized dermal matrices that bypass synthetic scaffold regulatory burdens entirely.
Strategic Opportunities
- 3D-printed patient-specific geometries:Reconstructive centers in the United States are commissioning CT-derived scaffold designs that reduce revision rates in complex craniofacial reconstruction.
- India's CDSCO fast-track pathway:The regulator's abbreviated review for absorbable polymer implants creates first-mover advantage for manufacturers with existing CE marking or FDA clearance.
- Collagen-hydrogel composite convergence:Burn units are trialing hybrid scaffolds combining collagen's cell-adhesion properties with hydrogel injectability for irregular wound bed coverage.
Industry Challenges
- Electrospinning operator skill scarcity:Nanofiber scaffold production requires technicians trained in Taylor cone stabilization and solvent system optimization, creating bottlenecks at contract manufacturing organizations.
- Multi-jurisdiction biocompatibility certification:Scaffold developers must sequence ISO 10993 testing against FDA, EMA, and PMDA variations, stretching quality assurance timelines without guaranteed market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Surgery Scaffolds Market |
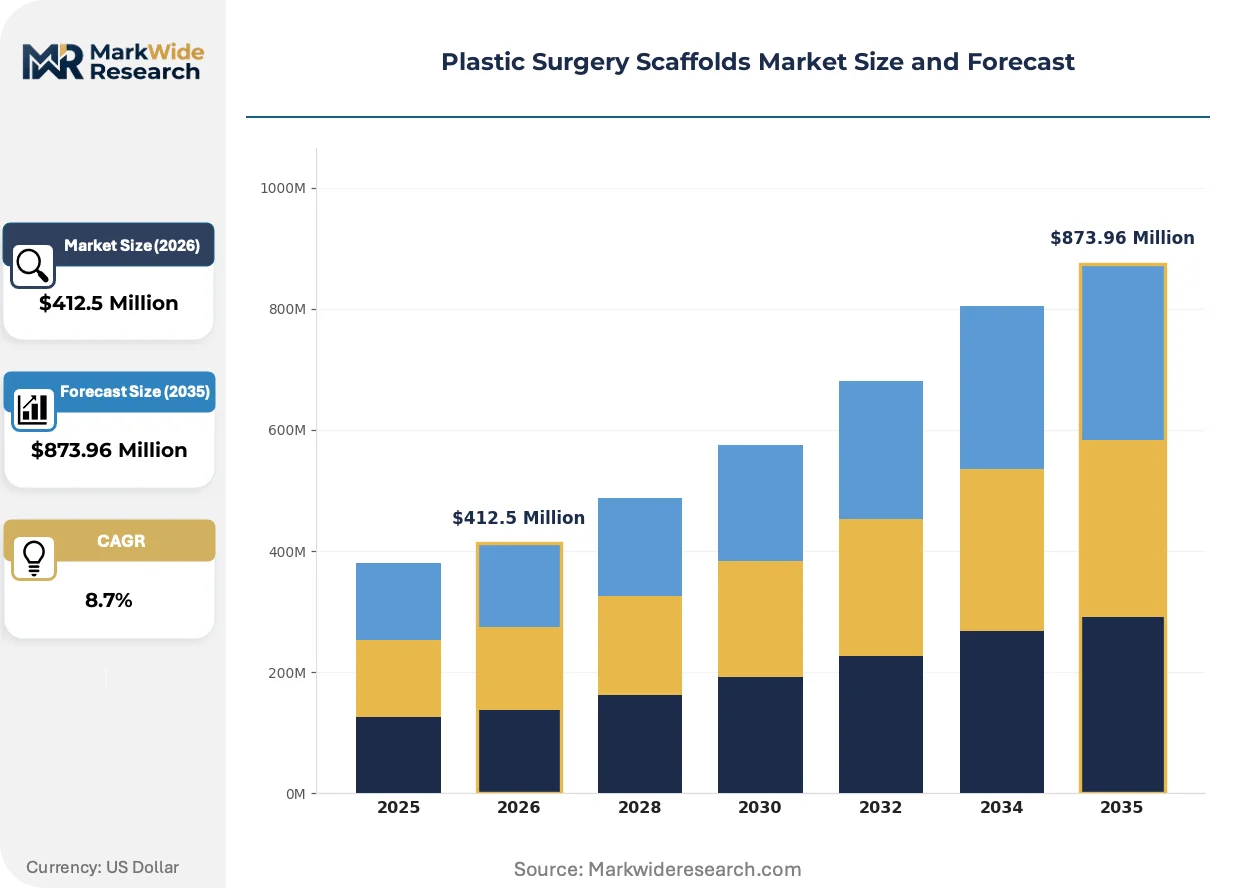
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogels, Composites, Silicone, Biodegradable Polymers Technology: 3D Printing, Electrospinning, Injection Molding, Phase Separation End User: Hospitals, Ambulatory Surgery Centers, Clinics, Research Institutions Application: Burn Treatment, Tissue Reconstruction, Cosmetic Enhancements, Regenerative Medicine |
| Companies Covered | Allergan, Integra LifeSciences Corporation, Johnson & Johnson, Medtronic, Zimmer Biomet, Sofregen Medical, Galatea Surgical, MTF Biologics, BellaSeno GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Surgery Scaffolds Market Strategic Shifts & Innovations
Biomaterial processing methods are fragmenting along performance-versus-scalability axes, with electrospinning, 3D bioprinting, and solvent-cast particulate leaching each capturing distinct reconstructive surgery niches.
4D bioprinting is converging with shape-memory polymers in scaffold architectures that self-deploy upon thermal or hydration triggers. Craniofacial reconstruction centers in South Korea and Germany are piloting these responsive structures for nasal and auricular frameworks. The technology is converging with intraoperative workflow compression by eliminating manual scaffold shaping during flap elevation.
The FDA's updated guidance on absorbable polymer implants mandates real-time degradation monitoring data for 510(k) submissions. Scaffold manufacturers must now integrate resorbable sensor elements or commit to extended clinical follow-up protocols. Burn and trauma reconstruction units in the United States are delaying procurement decisions until predicate device pathways clarify for next-generation copolymers.
Hospital procurement committees are unbundling scaffold supply from integrated reconstructive surgery service contracts. Aesthetic surgery clusters in Germany and academic medical centers in Japan are establishing direct material qualification programs that bypass traditional distributor markups. This disintermediation concentrates purchasing power among high-volume reconstructive centers while fragmenting addressable demand for mid-tier scaffold suppliers.
Plastic Surgery Scaffolds Market Segmentation
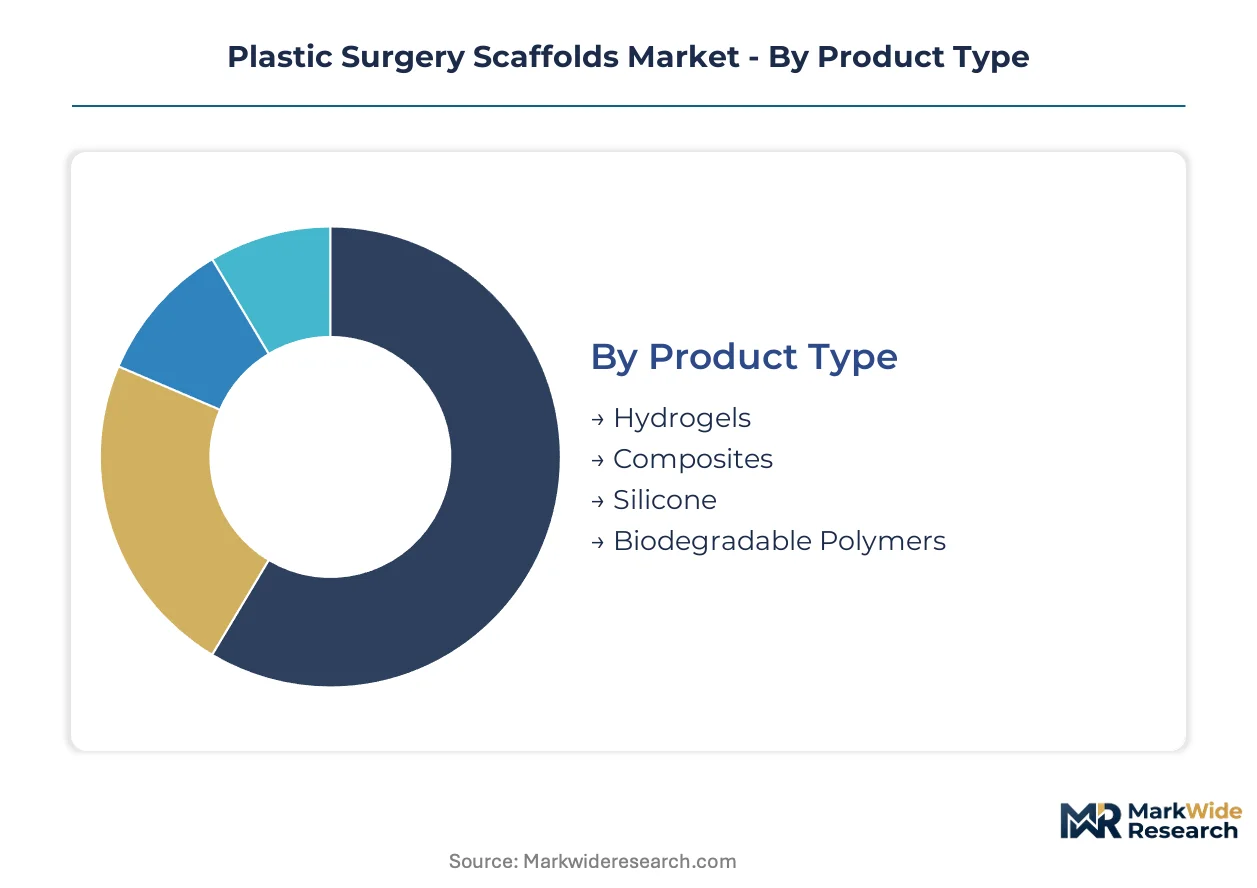
Scaffold segmentation dictates procurement workflows across reconstructive centers. Material selection and fabrication technology determine regulatory pathways, reimbursement codes, and surgeon training requirements. Understanding these divides clarifies where manufacturers should concentrate R&D investment versus where commoditization pressures dominate.
Product Type:
Upgrade cycles in scaffold procurement accelerate where hydration-matched or patient-specific formats displace legacy fixed configurations.
- Hydrogels:Cross-linked polymer networks with tunable swelling ratios deliver injectable delivery through minimally invasive cannulation. Aesthetic surgery clusters in Germany prioritize these formats for operative time compression and reduced post-procedure monitoring protocols.
- Biodegradable Polymers:Polylactic acid and polycaprolactone formulations degrade through hydrolytic cleavage, eliminating explantation surgeries. Reconstructive surgery centers in the United States specify these for pediatric craniofacial cases where permanent implants complicate future growth.
- Composites:Hybrid architectures combining ceramic reinforcement with polymer matrices enhance mechanical integrity for load-bearing applications.
- Silicone:Non-resorbable elastomer scaffolds retain permanent structural support in cosmetic and reconstructive applications.
Volume placements concentrate in hydrogels; the faster expansion belongs to biodegradable polymers.
Technology:
Cost tiers separate fabrication methods by capital intensity and operator skill requirements, with premium nanofiber formats commanding distinct procurement budgets.
- Electrospinning:Electric field-driven fiber deposition produces pore architectures below 10 microns with surface-area-to-volume ratios exceeding 50:1. Facial reconstruction units in South Korea specify these nanofiber scaffolds for dermal regeneration where fibroblast alignment determines aesthetic outcomes.
- 3D Printing:Stereolithographic and extrusion-based additive manufacturing enables CT-derived patient-specific geometries. Burn centers in the United States commission these designs for irregular wound bed coverage that reduces revision rates.
- Injection Molding:High-throughput thermoplastic processing delivers standardized scaffold geometries at scale for routine soft-tissue repair.
- Phase Separation:Thermally induced polymer-poor domain formation creates interconnected porous networks without specialized equipment.
Revenue concentrates in electrospinning for premium facial applications; 3D printing gains share fastest in complex reconstruction protocols.
End User:
Customer type determines purchasing authority structure, with integrated health systems negotiating differently than independent aesthetic clinics.
- Hospitals:Academic medical centers and tertiary referral hospitals command centralized procurement committees that bundle scaffold supply with service contracts. These institutions prioritize ISO 10993 documentation and established FDA 510(k) predicates for risk mitigation.
- Ambulatory Surgery Centers:Outpatient facilities emphasize operative efficiency and rapid patient turnover. Germany's specialized aesthetic surgery clusters favor hydrogel formats that compress procedure times and same-day discharge protocols.
- Clinics:Independent aesthetic and reconstructive practices purchase through distributor networks with limited direct manufacturer relationships.
- Research Institutions:University laboratories and contract research organizations procure experimental scaffold formats for preclinical validation studies.
Procurement volume clusters in hospitals; ambulatory surgery centers are expanding their scaffold purchasing fastest.
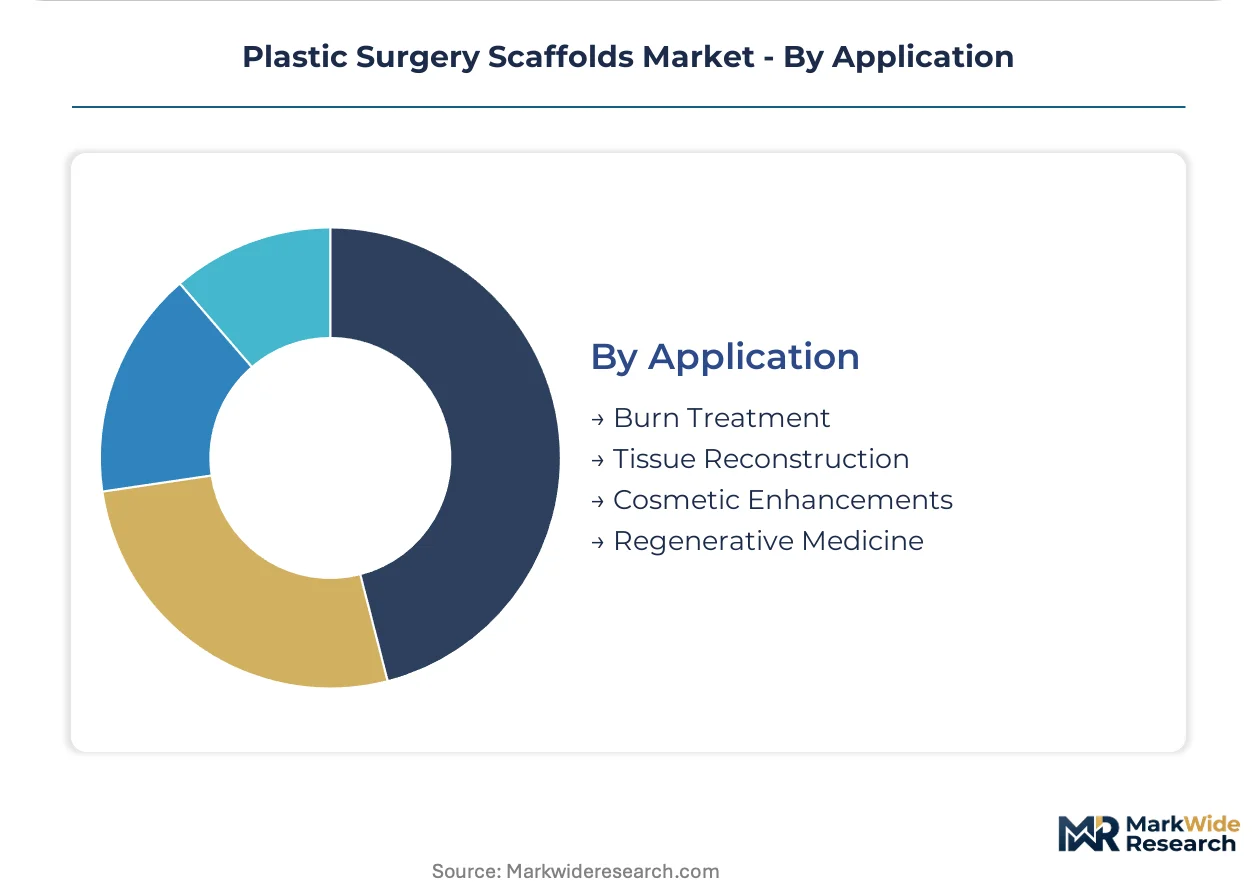
Application:
Application segmentation tracks reimbursement code availability and clinical evidence requirements, with trauma indications following distinct regulatory timelines than elective cosmetic procedures.
- Burn Treatment:Full-thickness and partial-thickness thermal injury reconstruction requires scaffolds with rapid vascular ingrowth kinetics. Collagen-hydrogel composites are gaining trial placement in United States burn units for irregular wound bed coverage.
- Tissue Reconstruction:Post-oncologic and traumatic defect repair demands mechanical integrity combined with bioresorption profiles matched to healing timelines.
- Cosmetic Enhancements:Elective aesthetic procedures prioritize predictable aesthetic outcomes and minimal downtime over structural load-bearing capacity.
- Regenerative Medicine:Cell-seeded scaffold constructs for stem cell therapy applications remain in investigational stages with limited commercial reimbursement.
Clinical utilization concentrates in tissue reconstruction; regenerative medicine applications are climbing the fastest despite reimbursement limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity clusters in Germany and the United States while consumption concentrates in specialized reconstructive surgery centers across multiple jurisdictions. Regulatory divergence between FDA 510(k) pathways and EU MDR biological safety testing creates distinct market access timelines. Procurement patterns fragment as hospital committees in high-volume markets establish direct material qualification programs.
United States
Burn and trauma reconstruction units in Texas and California drive hydrogel and 3D-printed scaffold procurement for irregular wound bed coverage. FDA's updated guidance on absorbable polymer implants mandates 24-month degradation profiles, extending clinical evidence timelines for novel copolymer submissions. The Greater Boston corridor anchors academic medical center procurement committees that bundle scaffold supply with integrated service contracts.
Germany
Specialized aesthetic surgery clusters in Bavaria and North Rhine-Westphalia prioritize hydration-matched injectable formats that compress operative time. EU Medical Device Regulation biological safety testing elevates compliance costs, favoring manufacturers with established ISO 10993 documentation. The Munich-Stuttgart axis concentrates electrospinning expertise for nanofiber facial reconstruction scaffolds where surface-area-to-volume ratios direct fibroblast alignment.
South Korea
Craniofacial reconstruction centers in Seoul specify 4D bioprinted shape-memory scaffolds for nasal and auricular frameworks that self-deploy upon thermal triggers. The Ministry of Food and Drug Safety aligns with international standards while maintaining abbreviated review pathways for absorbable polymer implants. The Seoul Capital Area hosts pilot programs eliminating manual scaffold shaping during flap elevation procedures.
India
CDSCO's fast-track pathway for absorbable polymer implants creates first-mover advantage for manufacturers with existing CE marking or FDA clearance. Maharashtra and Karnataka host emerging contract manufacturing organizations serving domestic burn units and export markets. Mumbai-Pune corridor reconstruction centers are trialing collagen-hydrogel composites for pediatric craniofacial cases where permanent implants complicate future growth.
Japan
PMDA's alignment with ISO 10993 biocompatibility standards functions as baseline threshold for multi-jurisdiction filings, stretching quality assurance timelines. The Kanto region's academic medical centers concentrate procurement volume for biodegradable polymers in post-oncologic defect repair. Tokyo-Osaka reconstructive surgery networks specify mechanical integrity matched to healing timelines for load-bearing applications.
Plastic Surgery Scaffolds Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across scaffold fabrication technologies. The vendor base stratifies into three tiers: multinational medical device conglomerates with regenerative tissue portfolios, mid-cap biopolymer fabricators with ISO 10993 documentation, and niche electrospinning specialists serving premium facial reconstruction. Consolidation pressures intensify as hospital procurement committees unbundle supply from service contracts. Dominant competitive moves include backward integration into medical-grade polymer supply and technology licensing for patient-specific 3D printing workflows.
Among diversified medical technology conglomerates, Johnson & Johnson and Medtronic occupy positions spanning multiple scaffold material categories through established hospital procurement channels. Integra LifeSciences Corporation exemplifies the regenerative tissue specialist archetype, anchoring contracts across burn and reconstruction units. MTF Biologics represents the allograft-derived matrix segment, capturing soft-tissue repair cases that bypass synthetic scaffold regulatory burdens entirely.
| Leading Market Players |
|---|
| Allergan |
| Integra LifeSciences Corporation |
| Johnson & Johnson |
| Medtronic |
| Zimmer Biomet |
| Sofregen Medical |
| Galatea Surgical |
| MTF Biologics |
| BellaSeno GmbH |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up scaffold specialists anchor supply discipline through portfolio-company coordination of medical-grade polymer offtake, translating concentrated ownership into synchronized pricing power across German and United States manufacturing clusters.
Pricing Analysis
Margin tightening in electrospun nanofiber tiers reflects capital intensity and operator skill scarcity, while standard biodegradable polymer formats face cost-down pressure from injection-molded alternatives. Three-tier pricing structure across premium nanofiber, standard thermoplastic, and economy hydrogel levels separates certification-grade ISO 10993 documentation from basic biocompatibility claims. Hospital procurement committees in academic medical centers exhibit lowest price sensitivity due to bundled service contracts, whereas independent aesthetic clinics in Germany's ambulatory surgery clusters drive hardest volume negotiations.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EU MDR compliance teams mandate qualified polymer supply from at least two of Germany, United States, and South Korea, preventing single-source vulnerability in medical-grade polycaprolactone and polylactic acid feedstock. Raw material dependencies center on caprolactone monomer, collagen isolates, and bioactive ceramic particulates. Tariff exposure on European chemical processor exports to United States burn reconstruction units constitutes the dominant structural risk. Distribution runs through specialized medical device distributors with GPO contracts for hospital systems and direct manufacturer relationships for high-volume aesthetic surgery clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
3D-printed patient-specific geometries are displacing fixed-configuration scaffold kits, compressing procurement cycles for reconstructive centers while elevating technical barriers for legacy injection-molding specialists.
For Market Incumbents: Lock in backward integration into medical-grade polymer supply to neutralize feedstock volatility from European chemical processors, while anchoring hospital procurement contracts through ISO 10993 documentation investments that exceed emerging competitor capabilities. Prioritize electrospinning capacity expansion in the Munich-Stuttgart axis to defend premium facial reconstruction positioning against South Korean 4D bioprinting entrants. For New Entrants and Emerging Players: Begin with CDSCO fast-track pathway exploitation in India, leveraging existing CE marking or FDA clearance to capture first-mover advantage in Maharashtra and Karnataka burn units before domestic contract manufacturing organizations mature. Target collagen-hydrogel composite white space where burn centers trial hybrid formats, using irregular wound bed coverage applications as the entry wedge. For Investors and Strategic Acquirers: FDA's updated 24-month degradation profile requirement is the leading indicator that clinical evidence timelines will consolidate R&D-intensive scaffold developers around proven biopolymer platforms, favoring acquisition targets with predicate device 510(k) pathways already established. Long-term viability hinges on positioning for hospital procurement committee unbundling of supply from service contracts, with electrospinning specialists and 3D printing workflow licensers representing the highest-conviction target archetypes.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Documentation Investment | CE marking and FDA 510(k) predicates accelerate multi-jurisdiction market access for biopolymer platforms. |
| Electrospinning Capacity Expansion | Munich-Stuttgart axis concentration captures premium facial reconstruction demand from South Korean craniofacial centers. |
| 3D Printing Workflow Licensing | CT-derived patient-specific geometries reduce revision rates in United States burn and trauma reconstruction units. |
| Backward Integration into Polymer Supply | Captive polycaprolactone production neutralizes input cost swings from three European chemical processors. |
| CDSCO Fast-Track Pathway Exploitation | Abbreviated review creates first-mover positioning in Maharashtra and Karnataka emerging manufacturing corridors. |
Research Approach
Document review covered FDA 510(k) submissions, EU MDR technical documentation, and ISO 10993 biocompatibility test reports, complemented by interviews with reconstructive surgeons, hospital GPO contracts managers, biomedical engineers at burn centers, and regulatory affairs leads at scaffold manufacturers. Secondary validation drew from hospital procurement databases, customs records of medical-grade polymer trade flows, and academic medical center RFP documentation. Bottom-up unit demand modeling and top-down market sizing triangulated volume estimates.
Historical absorption profiles of absorbable surgical meshes cross-referenced against expert panel input on degradation kinetic documentation timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include material chemistry, fabrication technology, end-user purchasing authority structure, and application-specific reimbursement code availability. CAGRs derived from iterative convergence of polymer feedstock cost trajectories, regulatory pathway duration assumptions, and reconstructive procedure volume elasticity.
Underlying measurement precision varies by segment; electrospun nanofiber and 3D-printed composite categories carry tighter precision than commoditized hydrogel formats due to concentrated manufacturer disclosure. Forecasts reflect assumptions on FDA predicate device pathway clarity and EU MDR notified body capacity constraints. Deviation in polycaprolactone feedstock supply consolidation or CDSCO review timeline acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Contact Lenses Market
Medical Devices
Supraglottic Device Market
Medical Devices
Mechanical Thrombectomy Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Urodynamic Catheter Market
Medical Devices
Refurbished Medical Devices Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
Medical Device Trays Market
Medical Devices
India Clear Aligners Market
Medical Devices
Depression Devices Market
Medical Devices
Osteosynthesis Devices Market
Medical Devices
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
MRI-Guided Radiation Therapy Systems Market
Medical Devices
Invisible Orthodontics Market
Medical Devices
Robotic Surgical Procedures Market
Medical Devices
Wrist Fixator Procedure Kit Market