
 Refurbished Medical Devices Market | 2026-2036
Refurbished Medical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Refurbished Medical Devices Market Outlook
Germany is rewriting how European hospitals source secondary-market medical equipment through its dense network of OEM-authorized refurbishment centers. Siemens Healthineers anchors this ecosystem with captive remanufacturing facilities that restore imaging systems to original specifications. Philips Healthcare competes through regional service hubs that extend warranty coverage on refurbished modalities across the continent. GE Healthcare dominates the North American channel with direct-to-hospital programs that control pricing and installation quality.
Refurbished medical devices are pre-owned clinical instruments restored to verified operational condition through component replacement, calibration, and safety testing against original manufacturer specifications. These units typically deliver diagnostic or therapeutic functionality at acquisition costs substantially below new-equipment benchmarks, serving capital-constrained healthcare providers. Imaging Equipment leads segment value due to extended asset lives of CT and MRI systems, while Patient Monitors represent the fastest-turn category as telemetry technology cycles shorten. Surgical Instruments concentrate margin pools in specialized electrosurgical device restoration where OEM certification commands price premiums.
FDA 510(k) clearance requirements and the EU MDR conformity assessment framework shape market access by mandating traceable quality documentation for every refurbished unit. ISO 13485 certification serves as the baseline operational credential for refurbishment facilities seeking hospital procurement eligibility. Stakeholders must monitor how emerging national regulators in Southeast Asia and Latin America adopt harmonized standards versus protective local requirements that fragment supply chains.
Market Dynamics
Capital allocation pressure on public health systems is redirecting procurement toward certified pre-owned equipment, compressing replacement cycles for imaging systems and surgical platforms while elevating refurbishment quality standards as a competitive differentiator.
Growth Catalysts
- EU MDR conformity pathways:Harmonized documentation requirements for refurbished device traceability are unlocking cross-border procurement for certified remanufacturers serving hospital networks across member states.
- India's hospital modernization programs:Government-mandated infrastructure upgrades in tier-2 and tier-3 cities are generating sustained tender volume for pre-owned diagnostic equipment with OEM-backed warranties.
- Telemetry technology obsolescence:Rapid sensor miniaturization and wireless protocol shifts are shortening patient monitor replacement cycles, accelerating secondary-market turnover for functional legacy units.
Market Restraints
- Component supply concentration:Specialized imaging detector arrays and MRI gradient coils remain captive to single-source OEM supply chains, constraining independent refurbishment capacity.
- FDA 510(k) documentation burdens:Traceability requirements for refurbished device submissions extend approval timelines and elevate compliance costs for smaller remanufacturing facilities.
- Artificial intelligence diagnostics:Cloud-native AI-enabled imaging systems with continuous algorithm updates threaten to devalue static refurbished hardware lacking software upgrade pathways.
Strategic Opportunities
- Vietnam's private hospital expansion:Foreign investment caps in healthcare infrastructure are lifting, creating entry points for refurbished equipment distributors serving Ho Chi Minh City and Hanoi medical corridors.
- Subscription-based equipment access:Per-scan pricing models for refurbished CT and MRI systems align capital outflows with patient revenue, reducing balance-sheet strain for mid-sized diagnostic centers.
- Blockchain-enabled provenance tracking:Distributed ledger systems for component replacement history and calibration records address hospital risk-officer concerns about refurbished device reliability.
Industry Challenges
- ISO 13485 auditor scarcity:Qualified certification bodies for medical device quality management systems face capacity constraints, extending facility accreditation timelines.
- Legacy system integration:Refurbished imaging platforms from prior-generation software architectures require costly middleware development to interface with hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refurbished Medical Devices Market |
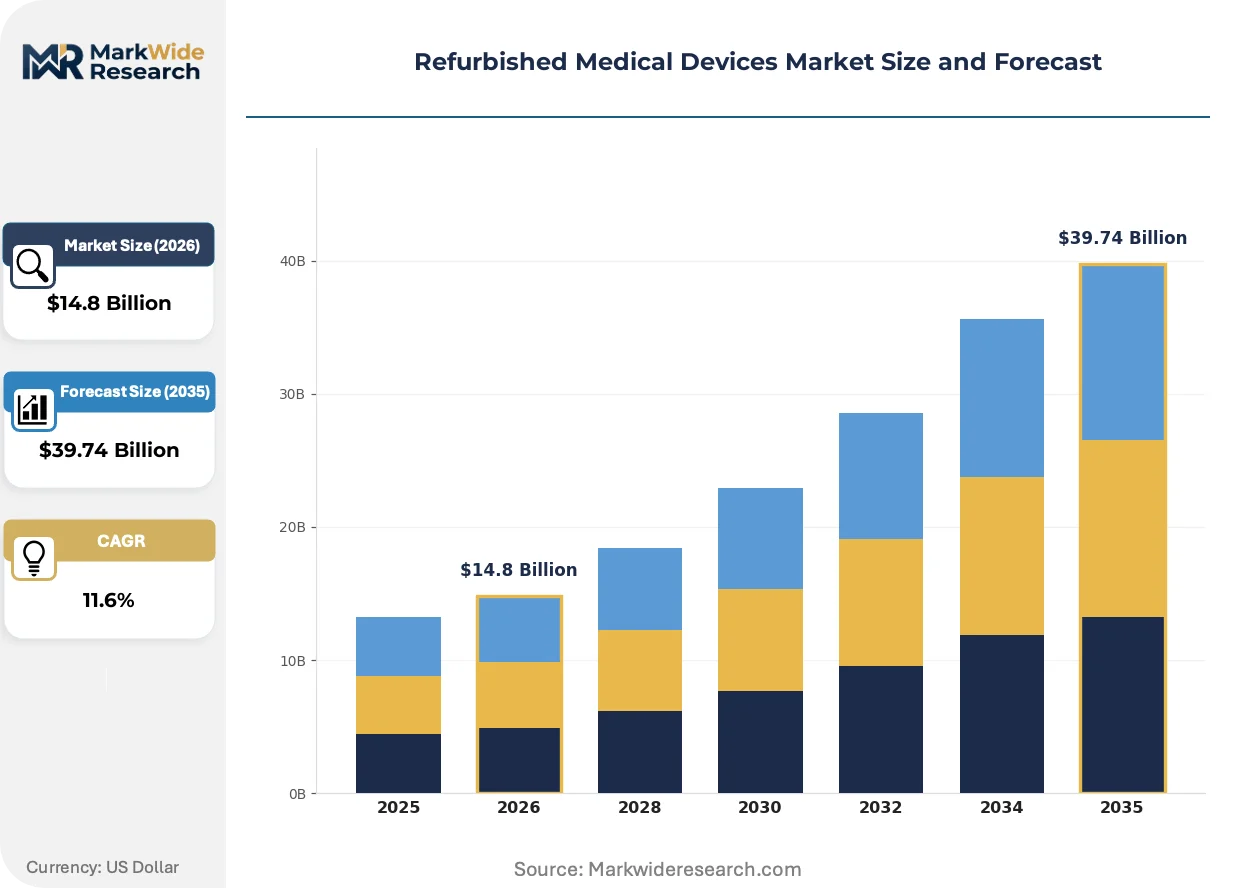
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Equipment, Surgical Instruments, Patient Monitors, Infusion Pumps End User: Hospitals, Clinics, Diagnostic Centers, Medical Schools Technology: Ultrasound, MRI, X-Ray, CT Scan Service Type: Maintenance, Certification, Repair, Quality Assurance |
| Companies Covered | GE Healthcare, Philips Healthcare, Siemens Healthineers, Soma Technology, Inc., Block Imaging International, Inc., Avante Health Solutions, Canon Medical Systems Corp., Mindray Medical International, Agito Medical A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refurbished Medical Devices Market Strategic Shifts
Refurbishment economics are being rewritten by predictive maintenance algorithms, regulatory digitization, and procurement decentralization that together compress asset valuation cycles and elevate service-contract profitability.
AI-driven predictive analytics is collapsing the information asymmetry between buyers and sellers of pre-owned medical equipment. Machine learning models trained on component failure patterns now forecast remaining useful life for CT tubes and MRI cold heads with sufficient accuracy to support warranty underwriting. Independent refurbishment facilities in Poland and the Czech Republic are deploying these tools to price risk-adjusted service contracts, while hospital procurement departments use the same datasets to negotiate residual-value guarantees.
REACH substance restrictions on hazardous materials in electrical equipment are forcing redesign of refurbishment processes for electrosurgical instruments and patient monitors. The European Chemicals Agency's expanded candidate list now covers additional flame retardants and plasticizers common in legacy device housings, compelling remanufacturers to source compliant replacement materials or restrict resale to non-EU destinations. German refurbishment centers are responding by vertically integrating polymer recompounding capabilities to maintain CE marking eligibility.
Hospital group purchasing organizations are fragmenting procurement authority to individual facility clinical engineering departments, bypassing centralized capital-equipment committees that historically favored new-device vendors. This decentralization elevates total-cost-of-ownership calculations over upfront capital expenditure metrics, benefiting refurbishment specialists with documented lifecycle performance data. The shift is most pronounced in Italy's regional health systems, where autonomy reforms have devolved imaging equipment decisions to individual hospital trusts.
Refurbished Medical Devices Market Segmentation
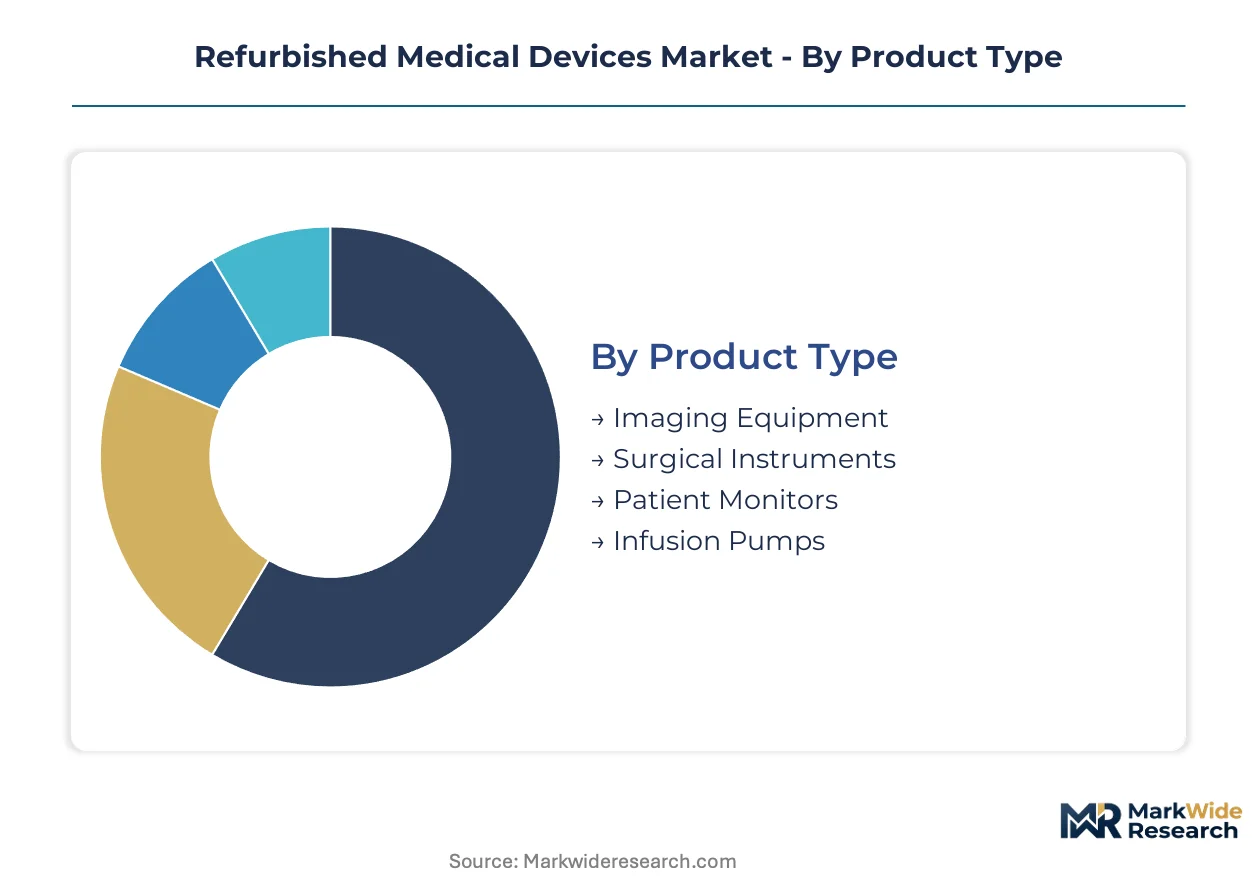
Segmentation in refurbished medical devices tracks how asset lifecycles, regulatory pathways, and procurement authority vary across equipment categories. Cycle-time differentials between imaging systems and patient monitors create distinct margin profiles and inventory risk models for refurbishment specialists.
Product Type:
Cycle times range from decades-long imaging platforms to sub-five-year patient monitor refresh rates, segmenting capital recovery horizons and service contract economics.
- Imaging Equipment:CT and MRI systems retain diagnostic utility for 15-20 years with component replacement, creating deep secondary markets where OEM-authorized refurbishment commands price premiums. Demand concentrates in Indian government hospital tenders and Vietnam's private hospital corridor as infrastructure budgets tighten.
- Patient Monitors:Telemetry devices face compressed replacement cycles as wireless protocol standards shift and sensor miniaturization accelerates, generating rapid turnover of functionally viable legacy units. Diagnostic centers in tier-2 Indian cities absorb volume for cost-sensitive bedside monitoring.
- Surgical Instruments:Electrosurgical device restoration requires specialized polymer recompounding to meet REACH substance restrictions, concentrating margin pools in certified remanufacturing facilities.
- Infusion Pumps:Drug delivery systems demand traceable calibration documentation under FDA 510(k) pathways, limiting refurbishment to facilities with ISO 13485 certification.
Imaging Equipment anchors the volume base while Patient Monitors gains share at the steepest rate.
End User:
Procurement authority fragmentation across customer types elevates total-cost-of-ownership calculations over upfront capital metrics, reshaping vendor engagement models.
- Hospitals:Public health systems under capital allocation pressure redirect procurement toward certified pre-owned equipment, with India's tier-2 and tier-3 modernization programs generating sustained tender volume.
- Diagnostic Centers:Mid-sized imaging facilities adopt subscription-based per-scan pricing for refurbished CT and MRI systems to align capital outflows with patient revenue streams.
- Clinics:Smaller outpatient facilities prioritize rapid-turn patient monitors and infusion pumps with abbreviated warranty terms.
- Medical Schools:Training institutions source legacy imaging platforms for educational use, accepting reduced software functionality at discounted acquisition costs.
Hospitals dominate current procurement value while Diagnostic Centers expand most quickly as independent imaging networks proliferate.
Technology:
Technology segments stratify by software architecture complexity and AI integration pathways that threaten to devalue static refurbished hardware lacking upgrade mechanisms.
- MRI:Superconducting magnet systems require specialized cold head replacement and cryogen management, constraining independent refurbishment capacity to OEM-captive service networks.
- CT Scan:X-ray tube replacement cycles and detector array calibration create predictable maintenance revenue streams for refurbishment specialists with component sourcing relationships.
- Ultrasound:Portable systems with shorter asset lives generate higher transaction velocity in secondary markets, particularly for point-of-care applications in clinic settings.
- X-Ray:Fixed radiography systems retain longer utility horizons with analog-to-digital retrofit pathways extending functional lifespans in budget-constrained facilities.
CT Scan technology anchors installed base value while Ultrasound climbs the fastest as point-of-care diagnostics expand.
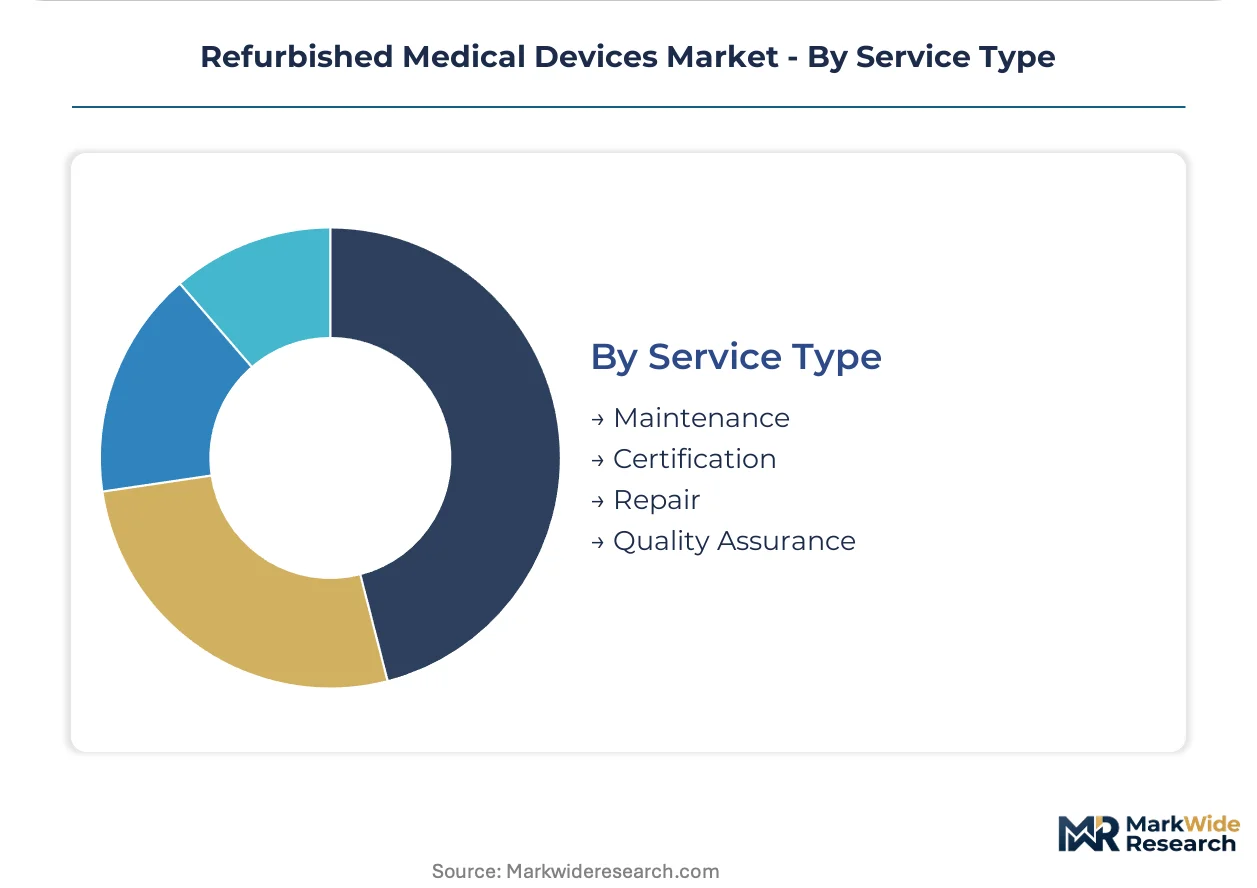
Service Type:
Service margins concentrate in certification and quality assurance where documentation burdens create barriers to entry for smaller refurbishment facilities.
- Certification:EU MDR conformity assessment and FDA 510(k) clearance pathways mandate traceable quality documentation, extending approval timelines and elevating compliance costs that favor scaled remanufacturers.
- Quality Assurance:Blockchain-enabled provenance tracking for component replacement history addresses hospital risk-officer concerns, creating differentiation for facilities with digitized calibration records.
- Maintenance:Predictive maintenance algorithms using machine learning on component failure patterns now support warranty underwriting and risk-adjusted service contract pricing.
- Repair:Component-level restoration concentrates in specialized imaging detector arrays and MRI gradient coils where single-source OEM supply chains limit independent capacity.
Certification commands the highest margin per transaction while Quality Assurance demonstrates the steepest expansion trajectory as digitization penetrates compliance workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Refurbished medical devices flow through fundamentally different procurement channels across major economies. Germany channels secondary-market equipment through OEM-captive remanufacturing networks, while India absorbs volume through government tender programs and Vietnam's private hospitals source via independent distributors.
Germany
Hospital procurement offices prioritize OEM-authorized refurbishment for imaging systems to maintain CE marking compliance under EU MDR. The country's dense network of remanufacturing facilities clusters around Erlangen and Forchheim, where Siemens Healthineers operates captive restoration centers serving hospital networks across member states.
United States
Health system capital committees redirect spending toward certified pre-owned equipment as operating margins compress. FDA 510(k) clearance pathways mandate traceable quality documentation that favors scaled remanufacturers with established regulatory submission capabilities. Independent refurbishment specialists concentrate in Midwestern states with proximity to hospital supply chains.
India
Government-mandated infrastructure upgrades in tier-2 and tier-3 cities generate sustained tender volume for pre-owned diagnostic equipment. CDSCO import regulations require refurbishment certification for secondary-market devices entering through Mumbai and Chennai ports. Hospital modernization programs prioritize CT and MRI systems with OEM-backed warranty coverage.
Vietnam
Foreign investment caps in healthcare infrastructure are lifting, creating entry points for refurbished equipment distributors. Private hospital corridors in Ho Chi Minh City and Hanoi absorb volume for cost-sensitive imaging modalities. The Ministry of Health's medical device registration framework is harmonizing toward ASEAN MDD alignment.
Poland
Regional health system autonomy reforms devolve imaging equipment decisions to individual hospital trusts, elevating total-cost-of-ownership calculations. EU MDR conformity assessment requirements channel procurement toward certified remanufacturers with documented calibration histories. Warsaw and Krakow clusters host independent refurbishment facilities deploying predictive maintenance algorithms.
Refurbished Medical Devices Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. OEM-captive remanufacturing networks control imaging system refurbishment through proprietary component supply chains and direct hospital relationships. Independent specialists compete on transaction velocity for patient monitors and surgical instruments with compressed replacement cycles. Three archetypes define competitive positioning: OEM-authorized remanufacturers with full warranty coverage, independent refurbishment facilities with ISO 13485 certification, and regional distributors aggregating secondary-market inventory. Dominant competitive moves include backward integration into component sourcing and geographic expansion through distributor partnerships.
Within the OEM-authorized tier, GE Healthcare, Philips Healthcare, and Siemens Healthineers occupy positions defined by captive remanufacturing infrastructure and direct-to-hospital service networks. GE Healthcare exemplifies scale-driven positioning through North American direct-installation programs. Philips Healthcare represents regional hub strategies extending warranty coverage across European member states. Siemens Healthineers anchors German refurbishment density with facilities restoring imaging systems to original manufacturer specifications. These three entities collectively demonstrate how OEM-captive capabilities create procurement stickiness through lifecycle service contracts and residual-value guarantees.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Siemens Healthineers |
| Soma Technology, Inc. |
| Block Imaging International, Inc. |
| Avante Health Solutions |
| Canon Medical Systems Corp. |
| Mindray Medical International |
| Agito Medical A/S |
| Others |
Value Chain & Pricing Dynamics
German OEM-captive remanufacturing facilities in Erlangen and Forchheim concentrate control over MRI gradient coils and CT detector arrays, anchoring margin pools in certification-backed warranty coverage rather than transactional equipment resale. Pricing power flows downstream to hospital procurement offices that prioritize CE-marked restoration over independent refurbishment alternatives.
Pricing Analysis
Long-term service contracts with residual-value guarantees dominate hospital procurement, displacing spot-market transactions for imaging systems. Three-tier pricing structure across OEM-authorized, ISO-certified independent, and uncertified secondary tiers reflects documentation depth and warranty duration. Cost compression in the independent tier intensifies as CDSCO and FDA submission burdens extend compliance timelines. Diagnostic centers in India's tier-2 cities exhibit highest price sensitivity, while German hospital trusts prioritize total-cost-of-ownership metrics over acquisition discounts.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts component flows for imaging detector arrays and electrosurgical instrument polymers. Manufacturing concentration in Germany, the United States, and India feeds from specialized cold head suppliers, superconducting wire producers, and REACH-compliant polymer recompounders. Single-source vulnerability in OEM-proprietary MRI gradient coils constrains independent refurbishment capacity. Distribution runs through direct-to-hospital installation programs for imaging systems and regional distributor networks for patient monitors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR digitization and AI-enabled predictive maintenance are compressing asset valuation cycles, creating a high-growth disruption window for certified remanufacturers with documented calibration histories. The regulatory inflection elevates quality assurance investments above pure cost competition.
For Market Incumbents: Build certification moats through backward integration into polymer recompounding and cold head refurbishment capabilities. Siemens Healthineers and GE Healthcare anchor defensive positioning by capturing proprietary component supply chains. Independent challengers threaten margin pools in patient monitors where wireless protocol shifts accelerate replacement cycles. Capacity addition in Poland and the Czech Republic extends geographic coverage for EU MDR-compliant service hubs. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's private hospital corridor where foreign investment caps are lifting and medical device registration frameworks harmonize toward ASEAN alignment. India's tier-3 government tenders present secondary entry points with lower certification barriers than OECD markets. A subscription-based per-scan pricing model for refurbished CT systems aligns capital outflows with patient revenue, reducing balance-sheet strain for mid-sized diagnostic centers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent refurbishment specialists in Central Europe lacking OEM-authorized status but deploying predictive maintenance algorithms. The five-to-ten year viability window favors platforms with ISO 13485 certification and digitized provenance tracking capabilities. Blockchain-enabled calibration records adoption rates signal inflection timing for premium valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR conformity assessment unlocks cross-border procurement for certified remanufacturers serving hospital networks. |
| Hospital System Partnership | Direct-to-hospital installation programs control pricing quality and capture lifecycle service contract revenue. |
| Software Companion Development | Cloud-native AI integration pathways prevent devaluation of static refurbished hardware lacking algorithm updates. |
| Backward Integration into Components | Captive supply of MRI cold heads and gradient coils constrains independent competitors and protects margin pools. |
| Reimbursement Strategy Alignment | Per-scan pricing models align capital outflows with patient revenue streams for mid-sized diagnostic centers. |
Study Parameters
Initial hypotheses were tested against primary input from hospital purchasing committees, biomedical engineers, GPO contracts managers, and refurbishment facility quality directors and refined through secondary validation. Hospital procurement databases, GPO contracts, FDA 510(k) filings, EU MDR conformity assessment records, and CDSCO import regulations anchored quantitative baselines. Bottom-up equipment transaction analysis and top-down health system capital expenditure modeling triangulated market sizing.
Demand-supply-balance framing tracked replacement cycle compression against refurbishment capacity expansion across the analysis window. Segmentation dimensions modeled included product type, end user category, technology modality, and service tier. CAGRs derived from equipment installed base aging curves and capital allocation shift assumptions. Predictive maintenance algorithm adoption rates and REACH substance restriction compliance costs informed industry-specific forecast inputs.
Stress conditions across FDA submission timeline extensions, EU MDR auditor scarcity, and AI diagnostics displacement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about hospital procurement decentralization and government tender volume sustainability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Phlebotomy Equipments Market
Medical Devices
Transcutaneous Electrical Nerve Stimulation Market
Medical Devices
Canada Contraceptive Devices Market
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Wearable Medical Device Connectivity and Cybersecurity Test Systems Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
MRI Safe Biopsy Needle Market
Medical Devices
Interatrial Shunt Market
Medical Devices
Spectacle Lens Market
Medical Devices
Global Cast Saw Devices Market
Medical Devices
Allergic Rhinitis Treatment Device Market
Medical Devices
Functional Electrical Stimulation Market