
 Mechanical Thrombectomy Devices Market | 2026-2036
Mechanical Thrombectomy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mechanical Thrombectomy Devices Market Intelligence
Aftermarket service revenue for catheter reprocessing and stent retriever refurbishment is reconfiguring margin distribution across the value chain. Penumbra leverages direct hospital contracting to sustain premium positioning in aspiration systems. Stryker Corporation anchors North American volume through its integrated stroke care platform, while Medtronic competes in European tenders with centralized logistics hubs.
Mechanical thrombectomy devices are catheter-delivered instruments designed to physically extract or dissolve intravascular clots through stent-based engagement or suction aspiration, typically requiring 0.021–0.088 inch lumen compatibility and real-time fluoroscopic guidance to restore perfusion in neurovascular and peripheral occlusions. Stent retrievers dominate procedural volumes in acute ischemic stroke intervention due to established clinical evidence and favorable reimbursement coding, while aspiration devices capture expanding share in faster-to-treat anterior circulation occlusions where direct clot ingestion reduces procedure steps. The combination method segment is gaining traction as operators deploy stent retriever-aspiration hybrid protocols to improve first-pass recanalization rates across comprehensive stroke centers.
FDA 510(k) clearance pathways and EU MDR conformity assessments shape product development timelines and commercial launch sequencing for device manufacturers seeking dual-territory approval. The AHA/ASA stroke guidelines and ESO-Karolinska recommendations directly influence hospital capital allocation toward thrombectomy-capable angiography suites. Stakeholders must monitor evolving real-world evidence requirements from CMS and national health technology assessment bodies as value-based procurement tightens evidentiary thresholds for premium device placement.
Market Dynamics
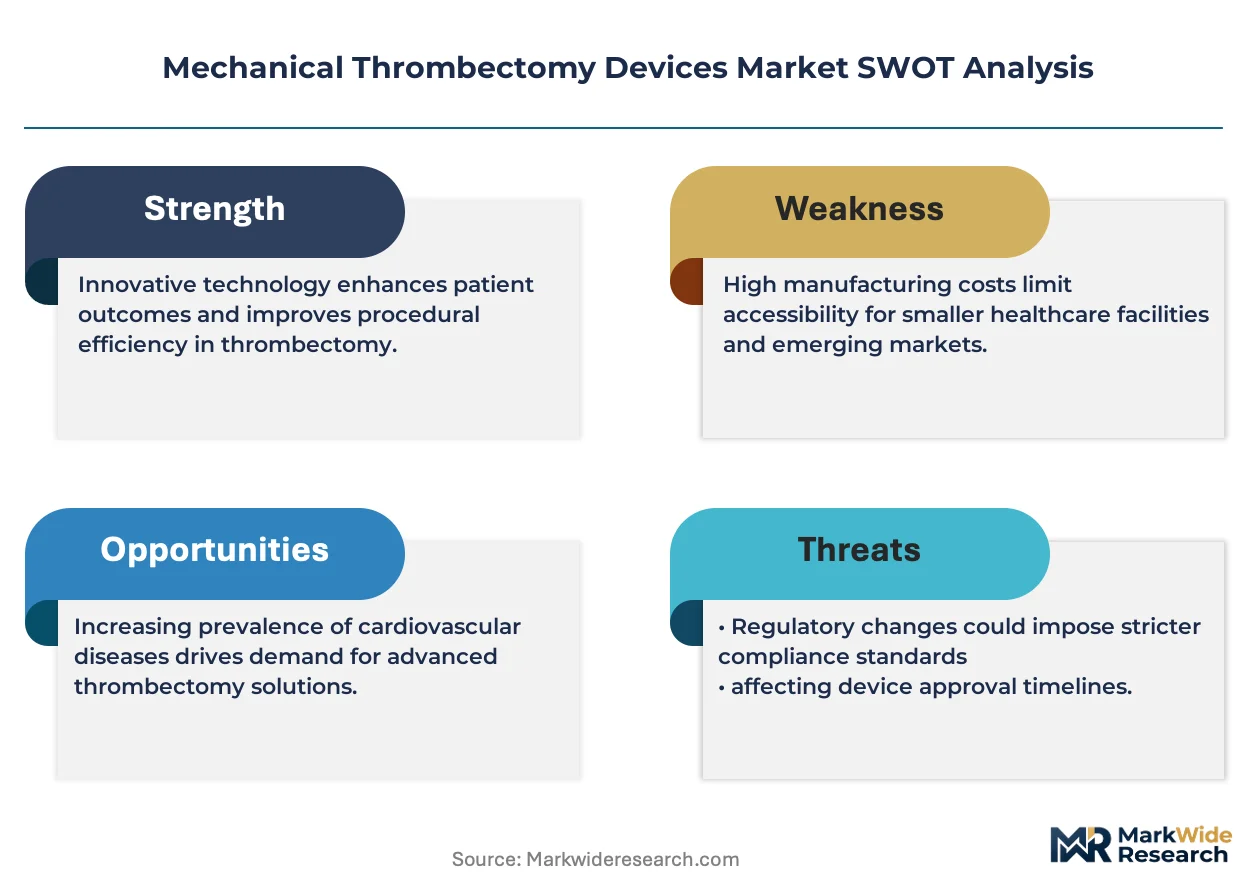
Comprehensive stroke center certification requirements are compressing hospital capital planning cycles and forcing rapid angiography suite upgrades to meet door-to-puncture time mandates.
Growth Catalysts
- AHA/ASA guideline updates:The 2019 and subsequent American Heart Association stroke guidelines expanded thrombectomy eligibility windows, triggering hospital infrastructure investments across the United States.
- Germany's integrated stroke networks:Ambulance-based triage protocols now route patients directly to thrombectomy-capable centers, concentrating procedural volumes in certified comprehensive stroke units.
- Stent retriever-aspiration hybrid protocols:Operator adoption of combination techniques is improving first-pass recanalization rates and expanding addressable patient populations.
Market Restraints
- Platinum-cobalt alloy supply concentration:Stent retriever manufacturing depends on specialized nitinol and precious metal feedstocks sourced through limited European and Japanese suppliers.
- EU MDR conformity assessment backlog:Extended notified body review timelines are delaying product launches and freezing commercial expansion for device manufacturers.
- Intravenous thrombolysis substitution:Tissue plasminogen activator (tPA) administration retains first-line protocol status in non-comprehensive stroke centers, capping mechanical thrombectomy penetration.
Strategic Opportunities
- Peripheral arterial occlusion expansion:Lower extremity thrombectomy represents an underpenetrated application with distinct reimbursement coding and lower regulatory evidentiary thresholds.
- India's PLI scheme for medical devices:Production-linked incentive structures are attracting catheter manufacturing investments to serve domestic and export markets.
- Direct-to-hospital contracting:Bypassing distributor networks enables manufacturers to capture service revenue and secure multi-year angiography suite partnerships.
Industry Challenges
- Neurointerventionalist training pipeline gaps:The Society of Vascular and Interventional Neurology reports insufficient fellowship slots to meet procedural demand growth.
- Dual FDA-EU MDR submission complexity:Divergent clinical evidence requirements force parallel rather than sequential regulatory strategies, stretching R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mechanical Thrombectomy Devices Market |
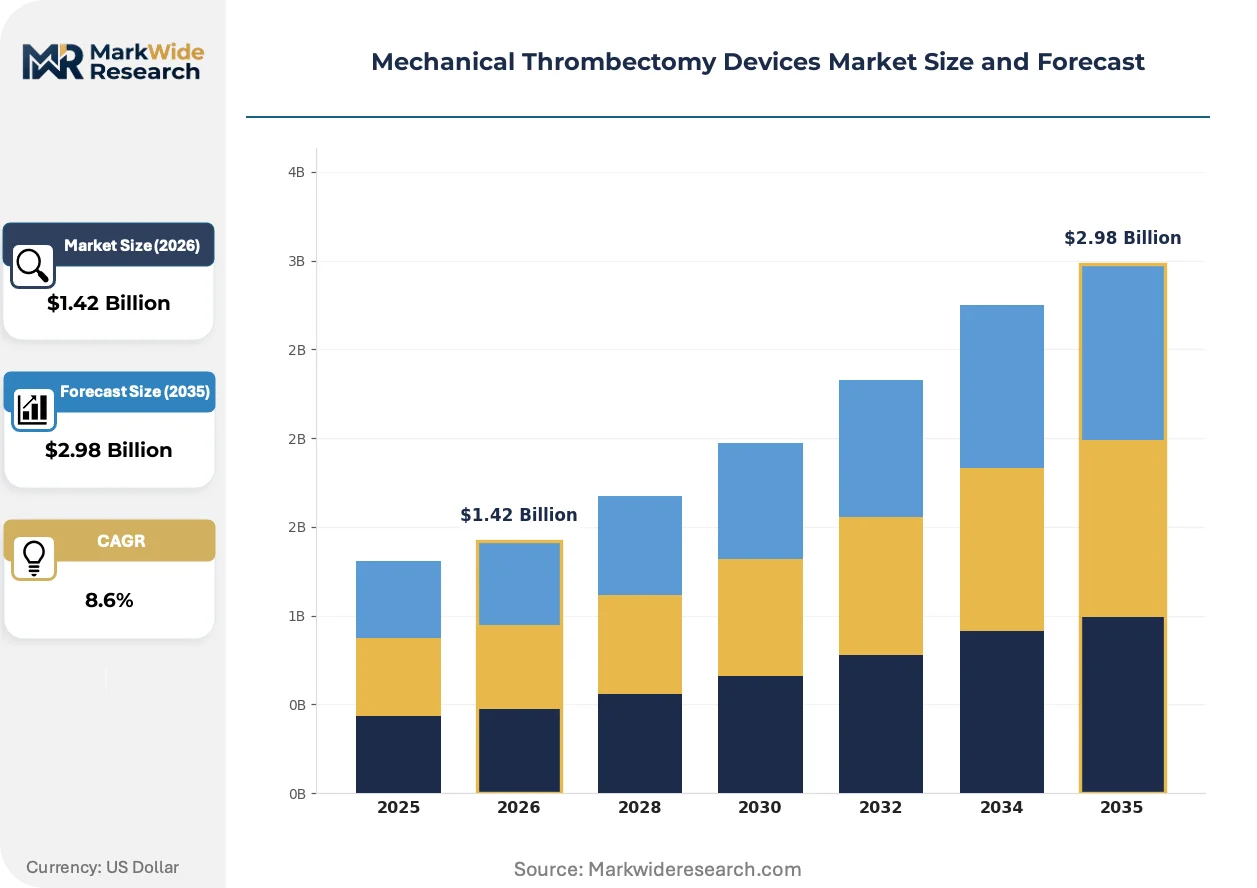
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stent Retrievers, Aspiration Devices, Neurosurgical Thrombectomy Devices, Balloon Devices End User: Hospitals, Outpatient Clinics, Surgical Centers, Rehabilitation Facilities Indication: Acute Ischemic Stroke, Deep Vein Thrombosis, Pulmonary Embolism, Peripheral Artery Occlusion Technology: Mechanical Extraction, Aspiration Technique, Combination Method, Biodegradable Material |
| Companies Covered | Penumbra, Terumo Corporation, Stryker Corporation, MicroVention, AngioDynamics, Medtronic, Johnson & Johnson, Acandis GmbH, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mechanical Thrombectomy Devices Market Strategic Shifts & Innovations
Real-world evidence generation and AI-assisted imaging interpretation are compressing treatment decision timelines and reshaping how stroke networks validate device performance.
Distal access catheter technology is virtualizing traditional guide catheter workflows. Comprehensive stroke centers in the United States and Germany are adopting 0.088-inch lumen platforms to enable direct aspiration of large-vessel occlusions. This convergence of aspiration and stent retriever capabilities is virtualizing the historical product segmentation between dedicated aspiration systems and retriever-based approaches.
EU MDR post-market surveillance requirements now mandate systematic collection of clinical follow-up data across implanted devices. Manufacturers must establish quality management systems that integrate vigilance reporting with registry participation. The aspiration device segment faces particular scrutiny as novel catheter designs trigger reclassification under stricter Class III rules.
Hospital procurement committees now unbundle device selection from angiography suite vendor relationships. Value analysis teams in the United States are negotiating direct contracts with thrombectomy device manufacturers rather than accepting bundled pricing from imaging system suppliers. This disintermediation is most visible in Texas and Florida, where independent stroke center networks have consolidated purchasing power across multiple facilities.
Mechanical Thrombectomy Devices Market Segmentation
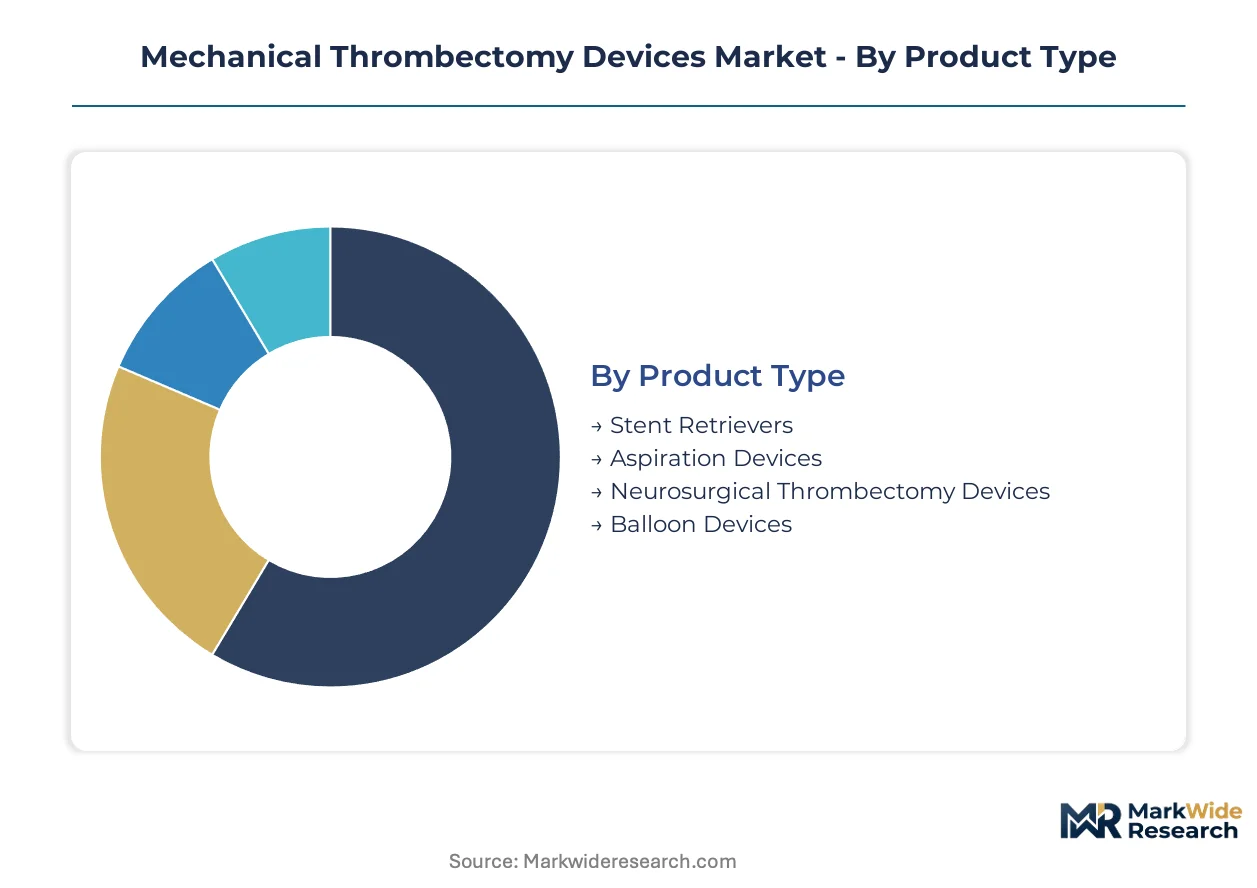
Mechanical thrombectomy devices fragment across four distinct taxonomies that shape procurement patterns and clinical deployment. Product type determines reimbursement coding and capital intensity, while indication and technology selection drive operator training requirements and procedural workflow design.
Product Type:
Cost tier differentiation separates premium catheter platforms from standard retriever systems and economy balloon configurations.
- Stent Retrievers:Nitinol mesh cylinders deploy across vessel walls to entrap thrombus for controlled withdrawal through 0.021–0.088 inch guide catheters. Demand concentrates in Germany's comprehensive stroke networks where 24-hour angiography suites prioritize first-pass recanalization reliability.
- Aspiration Devices:Large-bore suction catheters with 0.060–0.088 inch lumens enable direct clot ingestion without stent deployment, reducing procedural steps in anterior circulation occlusions. Texas and Florida stroke center networks are expanding aspiration-first protocols to compress door-to-puncture times.
- Neurosurgical Thrombectomy Devices:Specialized instruments for intracranial access through craniotomy or burr hole approaches.
- Balloon Devices:Occlusion balloon systems for flow control during clot retrieval in tortuous vasculature.
Stent retrievers command the established base. The steepest expansion runs through aspiration devices.
End User:
Application setting determines device specification requirements and service contract structures.
- Hospitals:Comprehensive stroke centers with biplane angiography suites and neurointerventionalist coverage drive demand for premium aspiration platforms and combination protocols. CMS reimbursement differentials favor thrombectomy-capable centers over primary stroke centers.
- Outpatient Clinics:Limited to diagnostic workup and tPA administration without catheter-based intervention capability.
- Surgical Centers:Peripheral arterial occlusion procedures in ambulatory settings utilize lower-complexity aspiration systems with distinct coding.
- Rehabilitation Facilities:Post-acute settings manage stroke recovery without interventional device deployment.
Hospitals concentrate procedural volume. Surgical centers are gaining share fastest in peripheral applications.
Indication:
Volume distribution reflects disease prevalence and treatment window eligibility across vascular territories.
- Acute Ischemic Stroke:Large-vessel occlusion in anterior circulation dominates procedural volumes with established Level I evidence from randomized trials. AHA/ASA guideline expansions have extended treatment windows to 24 hours in selected patients.
- Deep Vein Thrombosis:Iliofemoral clot burden drives catheter-directed thrombolysis and mechanical extraction in specialized centers.
- Pulmonary Embolism:Massive and submassive presentations utilize aspiration thrombectomy when systemic thrombolysis is contraindicated.
- Peripheral Artery Occlusion:Lower extremity ischemia represents an underpenetrated application with evolving reimbursement pathways and lower regulatory evidentiary thresholds than neurovascular indications.
Acute ischemic stroke commands the established base. Peripheral artery occlusion shows the steepest expansion trajectory.
Technology:
Customer type segmentation separates established mechanical platforms from emerging biodegradable and combination approaches.
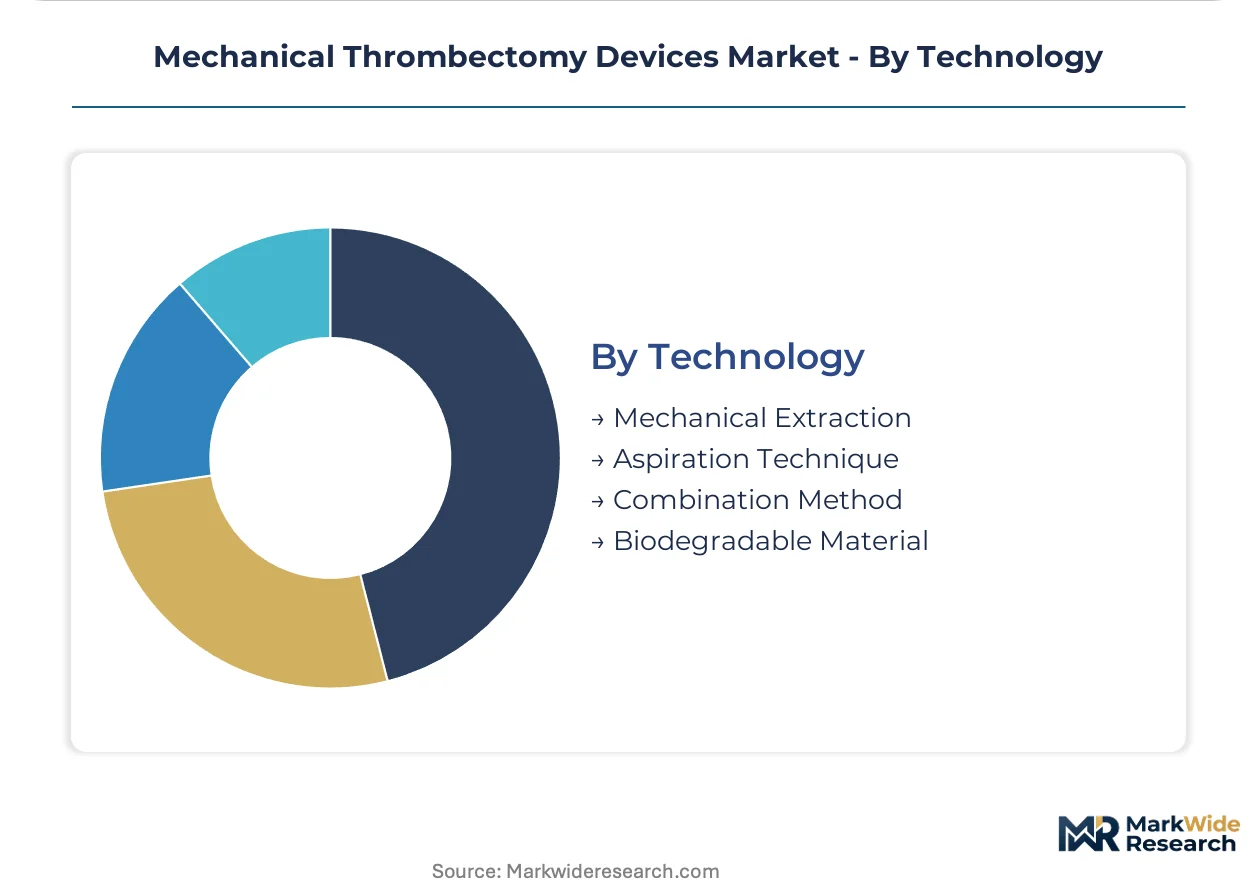
- Mechanical Extraction:Stent-based engagement and retrieval remains the reference standard with extensive real-world evidence and established operator training curricula.
- Aspiration Technique:Direct suction approaches are displacing retriever-first protocols in faster-to-treat cases.
- Combination Method:Hybrid stent retriever-aspiration protocols improve first-pass recanalization rates and are expanding addressable patient populations across comprehensive stroke centers.
- Biodegradable Material:Experimental platforms utilizing resorbable polymers aim to reduce foreign body retention but face extended EU MDR evidentiary requirements.
Mechanical extraction commands the established base. The combination method is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany demonstrate the lowest price elasticity, accepting premium catheter platforms within integrated stroke networks. Price sensitivity concentrates in India's emerging hospital sector, where procurement committees prioritize standard-tier devices under domestic manufacturing incentives.
United States
Comprehensive stroke center certification mandates from state health departments accelerate angiography suite procurement in Texas and Florida. FDA breakthrough device designations compress regulatory timelines for novel aspiration platforms. The Texas Medical Center in Houston anchors the nation's largest concentration of 24-hour thrombectomy-ready facilities.
Germany
Ambulance-based triage protocols route large-vessel occlusion patients directly to certified comprehensive stroke units, eliminating inter-hospital transfers. EU MDR conformity assessments from notified bodies like TÜV SÜD govern device commercialization timelines. The Rhine-Ruhr metropolitan region hosts the densest cluster of thrombectomy-capable angiography suites in Europe.
Japan
PMDA regulatory pathways prioritize real-world evidence from domestic stroke registries for device approvals. METI funding for neurovascular innovation supports catheter manufacturing investments. The Kanto region surrounding Tokyo concentrates procedural volumes in university-affiliated stroke centers.
India
PLI scheme incentives attract catheter manufacturing investments to serve domestic demand and export markets. CDSCO medical device rules govern import substitution strategies for foreign OEMs. Maharashtra's Mumbai-Pune corridor hosts emerging production facilities targeting Southeast Asian markets.
United Kingdom
NHS England's stroke service specifications mandate thrombectomy capability in hyper-acute stroke units by regional population thresholds. NICE technology appraisals influence hospital capital allocation toward specific device categories. London's neuroscience hospital network processes the highest procedural volumes nationally.
Mechanical Thrombectomy Devices Market Key Industry Players
Capability concentration sits with specialized neurovascular device manufacturers; scale advantage sits with diversified medtech conglomerates with integrated stroke care platforms. The market structure stratifies across three tiers: premium aspiration system specialists, full-solution platform providers, and emerging regional manufacturers. Strategic archetypes include direct-to-hospital contract specialists, multi-territory logistics hub operators, and catheter reprocessing service integrators. Competitive moves center on bypassing distributor networks and securing multi-year angiography suite partnerships.
Among diversified platform providers, Stryker Corporation and Medtronic occupy positions exemplifying contrasting geographic strategies. Penumbra represents the specialized aspiration system archetype with premium positioning. Acandis GmbH anchors the European specialist tier with concentrated regional focus. Johnson & Johnson and Boston Scientific Corporation sit within the broad-based medtech conglomerate category leveraging cross-divisional hospital relationships.
| Leading Market Players |
|---|
| Penumbra |
| Terumo Corporation |
| Stryker Corporation |
| MicroVention |
| AngioDynamics |
| Medtronic |
| Johnson & Johnson |
| Acandis GmbH |
| Boston Scientific Corporation |
| Others |
Cost & Logistics Intelligence
Platinum-cobalt alloy feedstock concentration in Japanese and European suppliers anchors margin distribution toward stent retriever refurbishment services and catheter reprocessing contracts. Aftermarket revenue streams now capture value that OEMs previously ceded to distributor networks.
Pricing Analysis
Service contract revenue tiers covering stent retriever refurbishment and aspiration catheter reprocessing drive lifetime customer value beyond initial device placement. Three-tier pricing structure across premium aspiration platforms, standard stent retriever systems, and economy balloon configurations reflects certification grade and angiography suite integration depth. Cost compression in standard-tier devices is intensifying as Indian manufacturing scales under PLI incentives. Surgical centers in peripheral arterial applications demonstrate highest price sensitivity; comprehensive stroke centers in Germany show lowest elasticity.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts nitinol wire and catheter polymer feedstock flows. Manufacturing concentration rests in Germany, Japan, and the United States for precision catheter fabrication, with emerging capacity in Maharashtra, India. Specialized nitinol alloys, platinum-cobalt radiopaque markers, and hydrophilic polymer coatings constitute critical input dependencies. Single-source vulnerability concentrates in European notified body certification bottlenecks under EU MDR. Distribution runs through direct-to-hospital contracting networks that bypass traditional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical thrombectomy devices represent a high-growth disruption as FDA breakthrough designations and AHA guideline expansions compress hospital procurement cycles toward 24-hour angiography suite mandates.
For Market Incumbents: Pre-empt aspiration-first protocol displacement by securing exclusive multi-year comprehensive stroke center partnerships before combination method standardization erodes stent retriever volume. Anchor backward integration into nitinol alloy sourcing to defend margin position against platinum-cobalt supply concentration. Prioritize EU MDR notified body relationship investment to circumvent conformity assessment backlog risks. For New Entrants and Emerging Players: Pursue peripheral arterial occlusion as the most penetrable indication, where reimbursement coding evolution and lower evidentiary thresholds reduce competitive moats. Target India's emerging hospital sector under PLI scheme manufacturing incentives for cost-advantaged export positioning. Deploy direct-to-hospital contracting with integrated reprocessing service bundles to circumvent established distributor relationships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed catheter manufacturing specialists holding EU MDR certifications but lacking US FDA clearance pathways. Five-to-ten year viability hinges on combination method patent positioning and real-world evidence generation capabilities. Monitor AHA/ASA guideline revision timing as the signal indicating inflection toward aspiration-dominant protocol adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Hospital Contracting | Bypasses distributor markups and secures multi-year angiography suite partnerships with comprehensive stroke centers. |
| EU MDR Certification Investment | Accelerates notified body approval timelines and unlocks commercial expansion across German integrated stroke networks. |
| Peripheral Arterial Indication Expansion | Captures underpenetrated lower extremity thrombectomy volumes with distinct reimbursement coding advantages. |
| Catheter Reprocessing Service Integration | Captures aftermarket revenue streams and deepens customer stickiness through refurbishment contract structures. |
| Combination Method Protocol Development | Aligns R&D roadmaps with operator adoption of hybrid stent retriever-aspiration techniques improving first-pass recanalization. |
Research Approach
Desk research of FDA 510(k) clearance databases, EU MDR notified body registries, and AHA/ASA clinical guideline archives preceded structured interviews with neurointerventionalists, hospital purchasing committee directors, and GPO contracts managers. Primary fieldwork with biomedical engineers and stroke network administrators validated secondary findings on angiography suite procurement patterns. Bottom-up procedural volume estimates triangulated against top-down manufacturer revenue segmentation.
Assumptions held fixed include AHA/ASA guideline eligibility windows and EU MDR post-market surveillance requirements; variables included operator training pipeline expansion rates and PLI scheme manufacturing capacity buildout. The analytical framework modeled product type, indication, technology platform, and end-user setting dimensions across the projection horizon. CAGRs derived from procedure volume growth trajectories and average selling price evolution by tier, incorporating catheter reprocessing penetration and direct contracting adoption curves as industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in healthcare capital expenditure cycles or platinum-cobalt alloy commodity pricing would shift the trajectory. Forecasts reflect documented assumptions on regulatory timeline continuity and reimbursement stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Extremity Tissue Expanders Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Pulmonary Function Testing System Market
Medical Devices
Dosing Units Market
Medical Devices
Europe Electric Wheelchair Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Global Surgical Drills Market
Medical Devices
Luer Lock Connector Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
North America Oxygen Concentrators Market
Medical Devices
Veterinary Ventilators Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Global Blood Ketone Meter Market
Medical Devices
Medical Fiber Optics Market