
 Osteosynthesis Devices Market | 2026-2036
Osteosynthesis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Osteosynthesis Devices Market Intelligence
The capital-intensity divergence between large-scale manufacturers and mid-tier competitors is unwinding competitive dynamics across the osteosynthesis devices landscape. Stryker Corporation leverages captive manufacturing of titanium alloy substrates to sustain margin structures that smaller rivals cannot replicate. DePuy Synthes anchors its position through deep integration with Johnson & Johnson's surgical robotics ecosystem. Zimmer Biomet Holdings differentiates via specialized trauma portfolios that dominate North American hospital procurement channels.
Osteosynthesis devices encompass metallic and polymeric implants engineered to stabilize bone fractures, correct deformities, and promote osseous union through mechanical fixation. Titanium alloy plates and screws, typically manufactured via CNC milling and additive layering, achieve tensile strengths exceeding 900 MPa while maintaining biocompatibility per ISO 5832 standards. The device-type dimension shows plates and screws capturing the dominant revenue share as workhorse trauma solutions, while bioabsorbable polymer variants represent the fastest-expanding material category as surgeons seek to eliminate secondary removal procedures. Carbon fiber-reinforced composites command premium positioning in spinal fusion applications where radiolucency enables post-operative imaging clarity.
FDA 510(k) premarket notifications and EU MDR technical documentation requirements enforce rigorous biocompatibility and fatigue-testing protocols that filter out undercapitalized entrants. ISO 13485 quality management systems and ASTM F2077 standards govern implant surface finishing and thread geometry specifications that directly influence clinical outcomes. Stakeholders must monitor evolving reimbursement thresholds for outpatient surgical centers versus traditional hospital settings as site-of-care migration reshapes purchasing authority and volume allocation across the value chain.
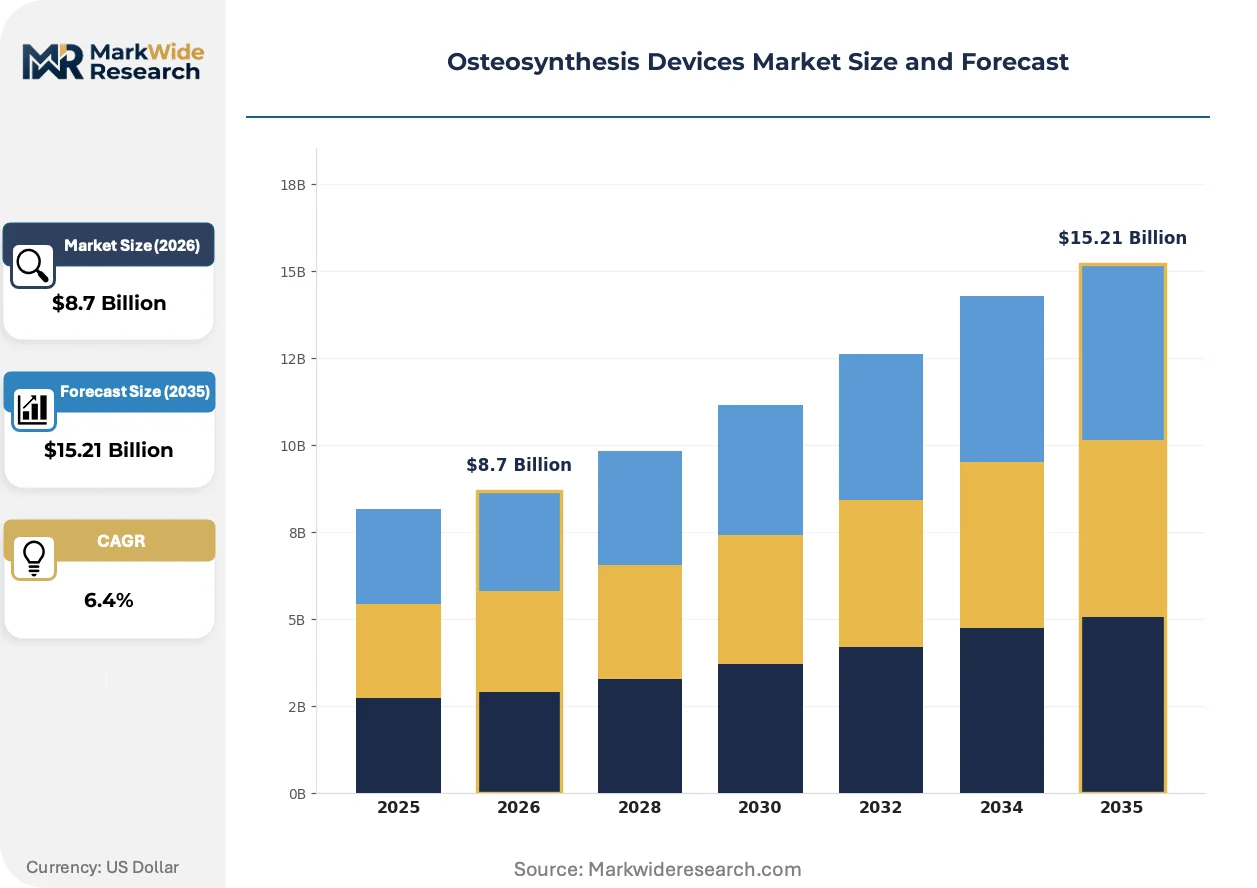
Market Dynamics
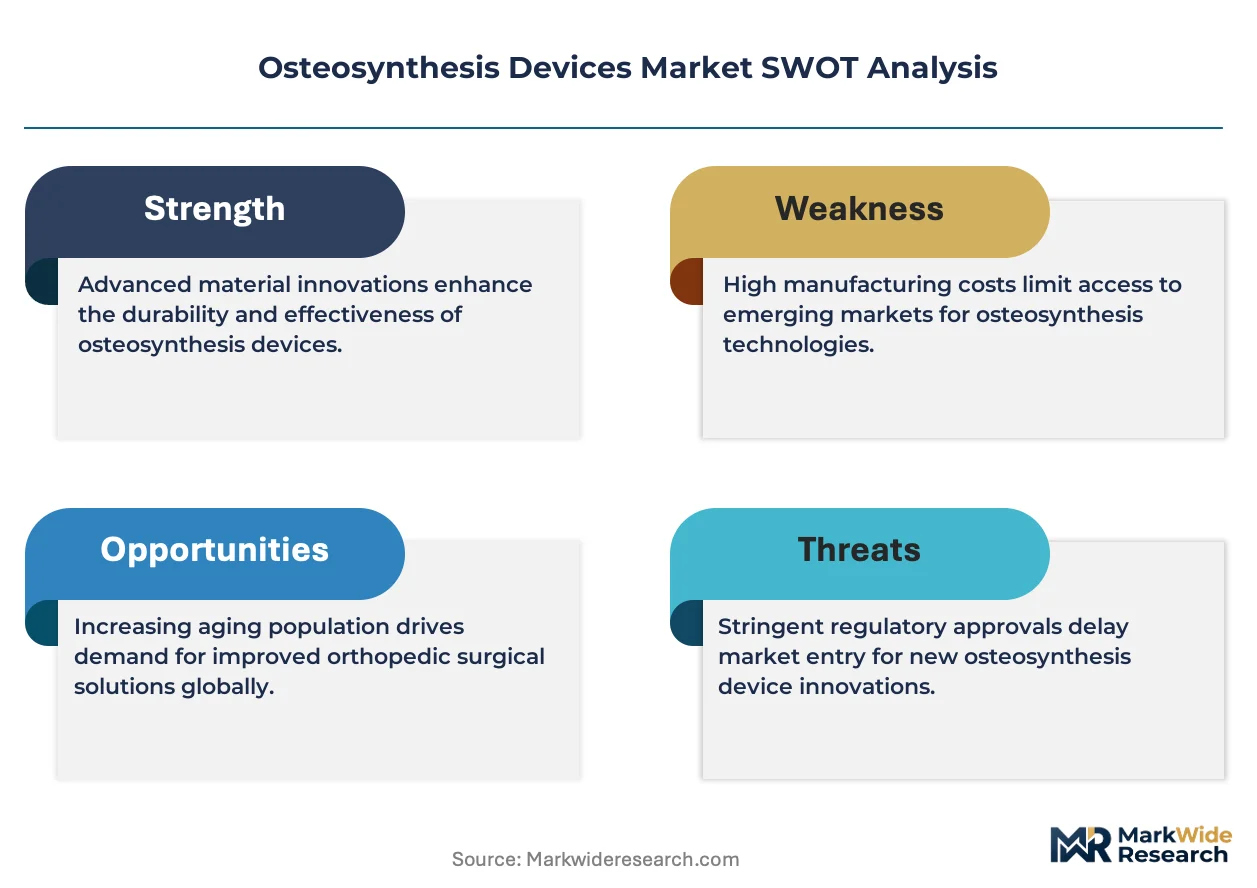
The osteosynthesis devices sector is experiencing intensified margin compression as hospital procurement consortia consolidate purchasing authority and demand price transparency across implant categories.
Growth Catalysts
- Ambulatory Surgery Center Expansion:CMS reimbursement reforms in the United States now permit outpatient fixation procedures for select fracture patterns, redirecting volume from inpatient settings.
- ISO 5832-11 Compliance:Standardization of titanium-zirconium alloy specifications accelerates regulatory clearance timelines across multiple jurisdictions.
- Additive Manufacturing Maturation:Electron beam melting and selective laser sintering enable patient-specific plate geometries that reduce operative time in complex pelvic reconstructions.
Market Restraints
- Titanium Sponge Supply Concentration:Russian and Ukrainian feedstock disruptions have elevated raw material costs for alloy substrates used in trauma plates.
- EU MDR Technical Documentation Burden:Clinical evidence requirements for legacy implant lines force portfolio rationalization decisions that shrink available SKUs.
- Bioabsorbable Polymer Performance Ceiling:Poly-L-lactide degradation kinetics remain unpredictable in load-bearing applications, limiting substitution rates for metallic hardware.
Strategic Opportunities
- India's Tier-2 Hospital Infrastructure:Government-funded trauma center networks under the Ayushman Bharat scheme create first-mover advantages for modular fixation systems.
- Digital Surgical Planning Integration:Pre-operative 3D modeling software combined with patient-specific guides enables premium pricing for complex deformity correction cases.
- Carbon Credit Incentives:China's dual carbon policy rewards manufacturers adopting recycled titanium feedstocks and energy-efficient forging processes.
Industry Challenges
- Biomechanical Testing Talent Scarcity:Fatigue testing protocols per ASTM F2077 require specialized engineers that device firms compete to recruit from aerospace and automotive sectors.
- Legacy ERP Integration:ISO 13485 quality management system upgrades demand costly middleware development to connect with existing manufacturing execution systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Osteosynthesis Devices Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Plates, Screws, Nails, Rods Material: Titanium, Stainless Steel, Bioabsorbable Polymers, Carbon Fiber Application: Fracture Repair, Arthrodesis, Osteotomy, Bone Stabilization End User: Hospitals, Surgical Centers, Orthopedic Clinics, Research Institutions |
| Companies Covered | Smith & Nephew plc, B. Braun Melsungen AG, DePuy Synthes (Johnson & Johnson), Life Spine, GS Medical LLC, Stryker Corporation, Globus Medical, MicroPort Orthopedics, Zimmer Biomet Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Osteosynthesis Devices Market Strategic Shifts & Innovations
Digital manufacturing workflows and biomaterial advances are restructuring how fixation devices transition from design to clinical deployment, with regulatory adaptation lagging technical capability.
Patient-specific instrumentation is fragmenting the traditional one-size-fits-all plate market. Additive manufacturing platforms now produce titanium lattice structures with modulus-matching properties that reduce stress shielding in osteoporotic bone. Academic medical centers in Germany and the United States are adopting these platforms for complex revision arthroplasty cases, compressing the addressable market for standard trauma plates in high-complexity procedures.
EU MDR Article 117 requirements for notified body involvement in quality system audits are extending product recertification timelines. Manufacturers must now submit updated clinical evaluation reports for implants with decade-long market histories, diverting regulatory affairs resources from new product development. The spinal fusion segment faces the most severe backlog, with some firms withdrawing legacy pedicle screw systems rather than absorbing compliance costs.
Hospital value analysis committees now dominate implant selection decisions, displacing individual surgeon preference as the primary purchasing determinant. These committees demand real-world evidence packages and total cost-of-care models that smaller manufacturers struggle to assemble. The United States exhibits this pattern most acutely, where integrated delivery networks consolidate purchasing across multiple facilities and standardize vendor contracts annually.
Osteosynthesis Devices Market Segmentation
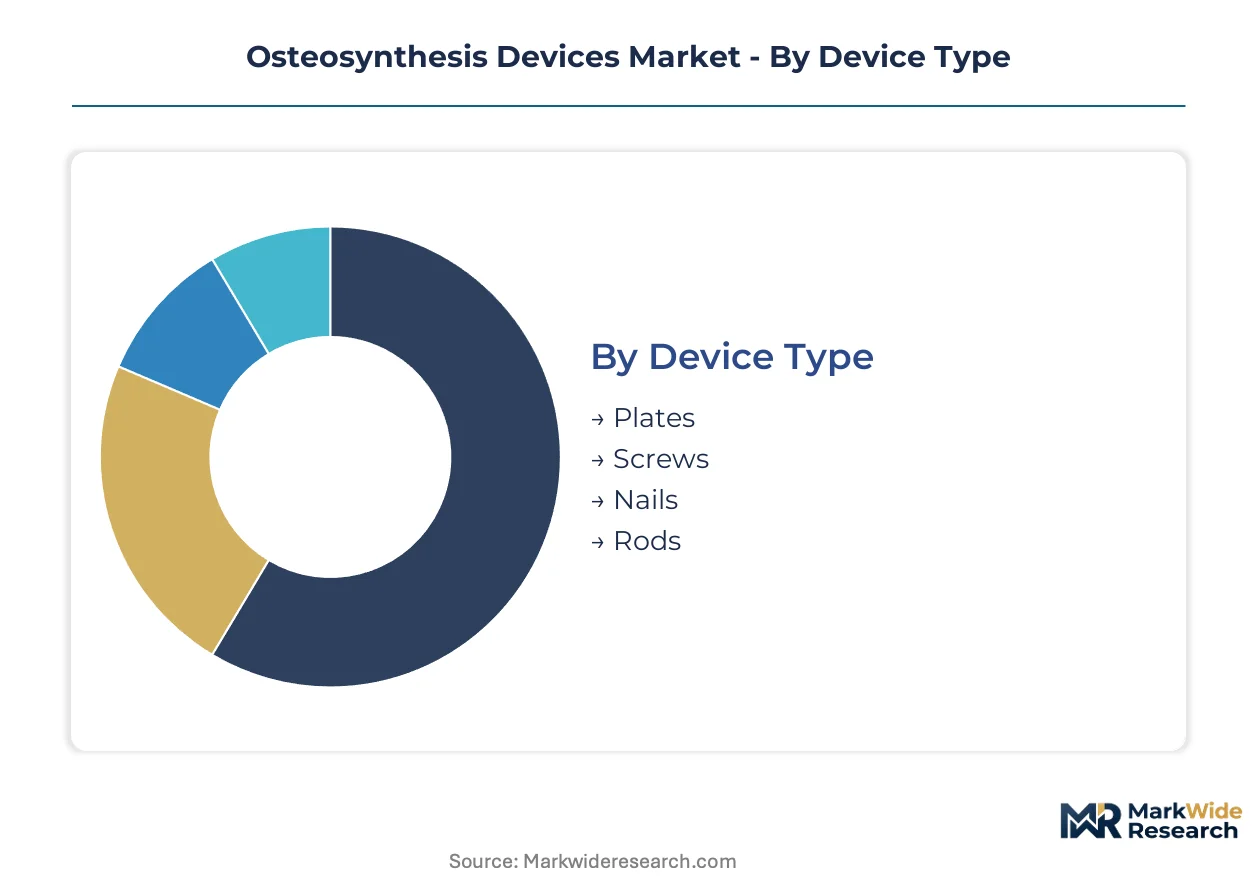
Channel configuration in osteosynthesis devices diverges sharply by procedural setting and reimbursement pathway. Hospital procurement consortia, ambulatory surgery centers, and specialized orthopedic clinics each demand distinct product configurations, packaging formats, and clinical support levels that reshape how manufacturers allocate SKU development resources.
Device Type:
Channel flow patterns separate trauma plates and screws flowing through high-volume hospital contracts from intramedullary nails and spinal rods that concentrate in specialized orthopedic centers and academic medical centers with complex deformity capabilities.
- Plates:Titanium alloy plates with locking screw interfaces constitute the workhorse trauma fixation line. Demand concentrates in United States level-I trauma centers and German university hospitals managing high-energy fracture volumes, driven by CMS reimbursement expansion for outpatient plate fixation procedures.
- Screws:Cortical and cancellous bone screws span trauma, spine, and extremity applications with thread geometries optimized per ASTM F543 standards. Orthopedic clinics in China's tier-2 cities are absorbing volume as local surgeons gain certification in minimally invasive screw placement techniques.
- Nails:Intramedullary nails for long-bone fractures require fluoroscopy-equipped operating theaters that limit placement to hospital settings.
- Rods:Spinal rods command premium positioning in deformity correction cases with pre-operative planning software integration.
Plates dominate installed base across trauma networks. Screws represent where expansion concentrates as ambulatory capabilities broaden.
Material:
Cost tier stratification separates premium titanium and carbon fiber products from standard stainless steel lines, with bioabsorbable polymers occupying an emerging premium position contingent on clinical evidence development.
- Titanium:Titanium-zirconium alloys per ISO 5832-11 specifications deliver tensile strength exceeding 900 MPa with modulus-matching properties that reduce stress shielding. United States trauma centers and Japanese orthopedic departments prioritize titanium for revision cases where bone quality is compromised.
- Stainless Steel:316LVM stainless steel retains cost advantages in emerging markets where procurement budgets constrain alloy selection. Indian government hospital tenders under Ayushman Bharat specify stainless steel for high-volume trauma fixation to manage per-procedure costs.
- Bioabsorbable Polymers:Poly-L-lactide and polyglycolide copolymers eliminate secondary removal surgery in pediatric and facial trauma applications.
- Carbon Fiber:Radiolucent carbon fiber-reinforced composites enable post-operative imaging clarity in spinal fusion constructs.
Titanium anchors revenue concentration. Bioabsorbable polymers are climbing the fastest as elimination of hardware removal procedures gains economic validation.
Application:
Volume distribution across applications correlates with population demographics, with fracture repair absorbing the largest procedure counts while arthrodesis and osteotomy concentrate in aging populations with degenerative conditions.
- Fracture Repair:Long-bone, pelvic, and periarticular fracture fixation constitutes the foundational application driving trauma implant demand. China's expanding highway infrastructure and motor vehicle density are elevating fracture volumes in provincial hospital networks.
- Arthrodesis:Joint fusion procedures for end-stage arthritis and post-traumatic degeneration require specialized plate and screw constructs. German orthopedic clinics lead European volume for ankle and hindfoot arthrodesis with integrated digital surgical planning.
- Osteotomy:Corrective bone cutting procedures for deformity correction demand patient-specific guides and modular fixation systems.
- Bone Stabilization:Prophylactic fixation and pathological fracture management support oncology and metabolic bone disease patients.
Fracture repair captures procedure volume leadership. Arthrodesis is where margin expansion concentrates as complexity premiums persist.
End User:
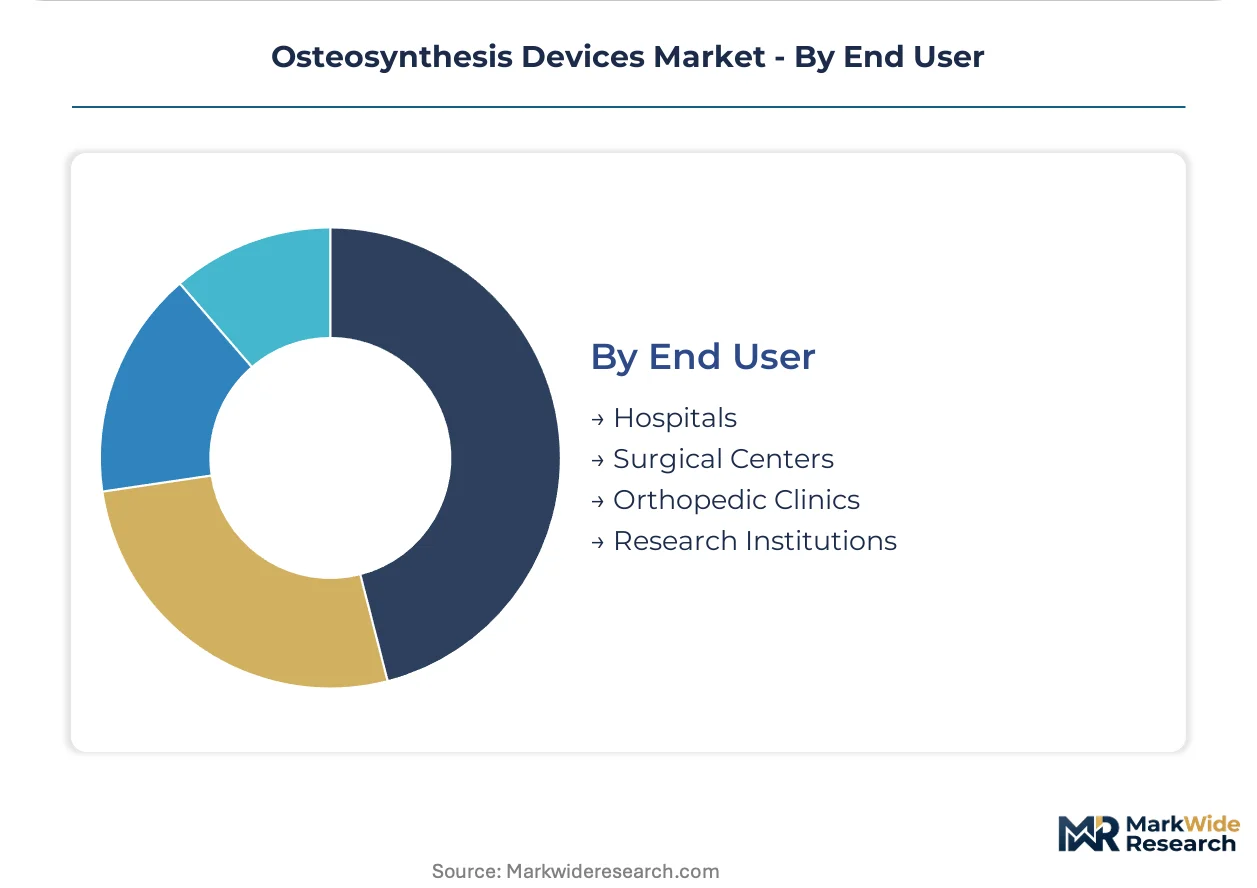
Customer type determines purchasing authority structure, with integrated delivery networks consolidating hospital buying power while surgical centers and clinics fragment decision-making across individual surgeons and value analysis committees.
- Hospitals:Level-I trauma centers and academic medical centers command the deepest product portfolios and highest ASPs. United States integrated delivery networks in Texas and Florida are standardizing osteosynthesis contracts across 10+ facility systems to extract volume discounts.
- Surgical Centers:Ambulatory surgery centers in the United States are capturing migrating trauma volume as CMS expands approved procedure lists. These facilities demand streamlined instrument sets and disposable delivery systems that reduce sterilization overhead.
- Orthopedic Clinics:Specialized private practices in Germany and Switzerland perform outpatient extremity fixation with direct implant purchasing authority.
- Research Institutions:Academic research centers drive early adoption of additive-manufactured and patient-specific constructs with limited commercial volume but outsized influence on clinical evidence generation.
Hospitals dominate current purchasing volume. Surgical centers are where channel expansion concentrates as site-of-care migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian government tenders enforce acute price sensitivity for stainless steel trauma hardware, while German university hospitals absorb premium titanium-zirconium alloys for revision cases without volume elasticity. This demand-elasticity divergence separates procurement patterns across high-income and emerging markets.
United States
Integrated delivery networks in Texas and Florida consolidate osteosynthesis contracts across 10-plus facility systems, extracting volume discounts from manufacturers. FDA 510(k) premarket notification pathways enable faster clearance timelines for titanium alloy substrates. Level-I trauma centers in Baltimore and Houston drive adoption of patient-specific additive-manufactured plates for complex pelvic reconstructions.
Germany
Academic medical centers in Berlin and Munich prioritize modulus-matched titanium implants for osteoporotic bone applications. EU MDR Article 117 requirements extend recertification timelines for legacy pedicle screw systems. The Baden-Württemberg industrial corridor hosts precision forging operations supplying alloy substrates to trauma device manufacturers.
China
Provincial hospital networks absorb rising trauma volumes from highway infrastructure expansion and motor vehicle density. NMPA regulatory harmonization with ISO 5832 standards accelerates domestic manufacturer market access. The Yangtze River Delta manufacturing cluster scales electron beam melting capacity for patient-specific implant production.
India
Ayushman Bharat government-funded trauma center networks in tier-2 cities create procurement opportunities for modular fixation systems. CDSCO import regulations favor domestic stainless steel manufacturers for high-volume fracture repair. Maharashtra's Pune-Ahmednagar industrial belt concentrates CNC milling operations for trauma plate fabrication.
Switzerland
Specialized orthopedic clinics in Zurich and Geneva perform outpatient extremity fixation with direct implant purchasing authority. Swissmedic quality system audits enforce ISO 13485 compliance that filters undercapitalized entrants. The Basel-region precision engineering ecosystem supplies thread-grinding equipment for cortical screw manufacturing.
Osteosynthesis Devices Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in osteosynthesis devices, with captive alloy supply and surgical robotics ecosystems defining the upper tier. Mid-scale manufacturers compete through trauma portfolio depth and regional hospital procurement relationships. Two strategic archetypes dominate: diversified orthopedic conglomerates with robotics integration, and focused trauma specialists with additive manufacturing capabilities. Competitive moves concentrate on M&A for patient-specific technology assets and capacity expansion in titanium sponge-adjacent forging operations.
Among diversified orthopedic conglomerates, Stryker Corporation and DePuy Synthes exemplify the integrated-leader archetype through captive manufacturing ecosystems and robotics platform alignment. Zimmer Biomet Holdings occupies a position bridging the leader and specialist tiers with concentrated trauma portfolio strength. Specialist tier representation includes Smith & Nephew plc and Globus Medical, which sit within focused spinal and extremity fixation segments without diversified robotics integration.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| B. Braun Melsungen AG |
| DePuy Synthes (Johnson & Johnson) |
| Life Spine |
| GS Medical LLC |
| Stryker Corporation |
| Globus Medical |
| MicroPort Orthopedics |
| Zimmer Biomet Holdings |
| Others |
Cost & Logistics Intelligence
Electron beam melting capacity utilization above 80 percent in the Yangtze River Delta creates scale advantages that compress per-unit titanium substrate costs while establishing price floors that smaller forging operations cannot match. This concentration of additive manufacturing infrastructure simultaneously elevates procurement power for hospital consortia and narrows margin capture for mid-tier device manufacturers lacking captive alloy supply.
Pricing Analysis
After-sales instrument set refurbishment and extended sterilization validation contracts drive lifetime value for trauma plate manufacturers. Three-tier pricing structure across premium titanium-zirconium alloys, standard titanium lines, and economy stainless steel configurations separates United States academic medical centers from Indian government tenders. Pricing pressure stems from CMS reimbursement compression for outpatient fixation procedures. Surgical centers exhibit highest price sensitivity; German university hospitals show least elasticity for modulus-matched implants.
Supply Chain Analysis
Inventory cycles extending 16-20 weeks for titanium sponge feedstock strain working capital across forging operations. Supply concentrates in China, Russia, and Ukraine for titanium sponge raw material, with secondary processing in Germany and the United States for precision alloy substrates. Electron beam melting equipment and ISO 5832-11 certified forging presses constitute critical bottlenecks. Single-source vulnerability runs through Ukrainian titanium feedstock disruptions. Distribution runs through hospital procurement consortia and GPO contracts in developed markets, direct government tenders in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in patient-specific additive manufacturing where surgeon-driven demand outpaces incumbent production capacity. Site-of-care migration from inpatient to ambulatory settings creates procurement authority niches that favor agile mid-scale competitors over integrated conglomerates.
For Market Incumbents: Fortify captive titanium alloy supply through backward integration into sponge-adjacent forging operations in the Baden-Württemberg corridor. Secure hospital system partnership contracts with embedded instrument set management services to lock out emerging additive manufacturing specialists. Priority lever rests on robotics ecosystem integration with trauma portfolio depth.
For New Entrants and Emerging Players: Differentiate on patient-specific pelvic reconstruction plates with digital surgical planning bundles. Target India's tier-2 trauma centers under Ayushman Bharat with modular stainless steel fixation systems. White-space opportunity sits in carbon fiber-reinforced spinal rods for radiolucent imaging applications. Go-to-market angle centers on direct surgeon engagement bypassing value analysis committees.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among additive manufacturing platforms with embedded software planning tools. Long-term viability favors patient-specific instrumentation capabilities over commodity trauma hardware. Acquisition target archetype: electron beam melting specialists with FDA 510(k) clearance pathways. Signal to watch: NMPA regulatory harmonization accelerating domestic Chinese manufacturer consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Patient-Specific Additive Manufacturing Scale-Up | Electron beam melting capacity in Yangtze Delta enables complex pelvic plate geometries with reduced operative time. |
| Hospital System Partnership Contracts | Integrated delivery networks in Texas and Florida consolidate purchasing across 10-plus facilities annually. |
| FDA 510(k) Premarket Notification Pathway | Expedited clearance for titanium-zirconium alloys accelerates competitive positioning in United States trauma centers. |
| Software Companion Development | Pre-operative 3D modeling integration commands premium pricing for deformity correction cases in German clinics. |
| Reimbursement Strategy Alignment | CMS outpatient procedure expansion redirects volume from inpatient settings to ambulatory surgery centers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and CMS reimbursement schedules. Interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers inform demand-side dynamics. Secondary validation draws from ISO 13485 audit records, ASTM standards documentation, and titanium alloy trade flow data. Bottom-up procedure volume estimates triangulate against top-down manufacturer revenue analysis.
Segmentation dimensions modeled span device type, material composition, application, and end-user channel across the projection horizon. Fracture repair, arthrodesis, osteotomy, and bone stabilization applications each carry distinct volume and margin profiles. CAGRs derive from procedure growth rates, site-of-care migration patterns, and material substitution trajectories. Titanium-zirconium alloy adoption curves and bioabsorbable polymer degradation kinetics constitute industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or titanium sponge supply stabilization would require recalibration. Forecasts reflect documented assumptions regarding regulatory clearance timelines and hospital consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Tracheal Tube and Airway Products Market
Medical Devices
Plethysmograph Market
Medical Devices
Mexican Intraocular Lens Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Remote Magnetic Catheter Systems Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Coronary Guidewires Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Rapid Infuser Market
Medical Devices
Canada Minimally Invasive Surgery Devices Market
Medical Devices
T-Piece Resuscitator Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Automatic Clotting Timer Systems Market
Medical Devices
Cranial Stabilization Devices Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Contact Lens Lubricant Market