
 Robotic Surgical Procedures Market | 2026-2036
Robotic Surgical Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Robotic Surgical Procedures Market Intelligence
A shift from single-source procurement to multi-vendor ecosystems is pivoting hospital purchasing strategies toward specialized platforms. Market incumbent Intuitive Surgical sustains its leadership through a vast installed base and extensive procedure data. Stryker leverages its strong position in orthopedics to drive adoption of its Mako robotic-arm assisted systems. In contrast, CMR Surgical competes with a modular, more flexible system design aimed at a broader range of surgical procedures.
Robotic surgical procedures involve the use of computer-controlled manipulators and instruments, often featuring telemanipulation, to perform minimally invasive operations with sub-millimeter precision. The core purpose is to augment surgeon dexterity and visualization, leading to smaller incisions and improved patient outcomes compared to traditional open surgery. Urologic and gynecologic procedures represent mature, high-volume segments for robotic assistance. However, orthopedic and neurosurgery applications represent the fastest-growing categories, driven by specialized system development.
Regulatory clearance from bodies like the US FDA and China's NMPA is a critical barrier to entry, requiring extensive clinical trial data. In Europe, the EU's Medical Device Regulation (MDR) imposes stricter post-market surveillance requirements, influencing lifecycle management for device manufacturers. Future investment decisions will hinge on demonstrating clear economic and clinical value propositions for new robotic platforms beyond existing surgical standards of care.
Market Dynamics
The central dynamic in the robotic surgical procedures market is the tension between the high capital investment required for system acquisition and the increasing pressure from healthcare providers and payors to demonstrate clear economic and clinical value over conventional methods.
Growth Catalysts
- Advanced Haptic Systems:The integration of sophisticated haptic feedback technology enhances surgeon control and tactile sensation, driving adoption in precision-critical fields like orthopedic joint replacement and complex soft-tissue surgery.
- Demographic Shifts:Aging populations in developed nations, particularly Japan and Germany, are increasing the incidence of age-related conditions, thereby expanding the volume of procedures such as prostatectomies and knee arthroplasties where robotic assistance is well-established.
- Application Expansion:The development of specialized instruments and software is enabling the use of robotics in previously inaccessible or high-risk areas, including microsurgical neurosurgery and cardiothoracic procedures, creating new avenues for market growth.
Market Restraints
- High Capital Expenditure:The substantial upfront cost of robotic surgical systems, coupled with expensive proprietary instruments and ongoing service contracts, presents a significant financial barrier for community hospitals and healthcare systems in emerging economies.
- Stringent Regulatory Hurdles:Rigorous pre-market approval processes, such as the clinical data requirements mandated by the US FDA and the EU's Medical Device Regulation (MDR), extend development timelines and increase costs for new entrants.
- Specialized Training Requirements:A steep learning curve for surgeons and operating room staff necessitates extensive, platform-specific training and credentialing, which can slow the pace of adoption and limit the effective utilization of installed systems.
Strategic Opportunities
- Underserved Geographic Markets:Significant growth potential exists in regions with improving healthcare infrastructure, such as Brazil and India, where the penetration of robotic surgery is low but demand for minimally invasive procedures is rising.
- Ambulatory Surgery Center (ASC) Adoption:The development of smaller, more cost-effective, and modular robotic platforms creates an opportunity to penetrate the ASC market, which requires systems with a smaller footprint and more flexible procedure-cost models.
- AI and Data Analytics Integration:Incorporating artificial intelligence for pre-operative surgical planning and machine learning algorithms for analyzing procedural data can enhance surgical outcomes and provide powerful evidence for demonstrating clinical value to payors.
Industry Challenges
- Surgical Skill Gaps:A persistent shortage of surgeons and technicians proficient in operating advanced robotic platforms creates an operational bottleneck, limiting the number of procedures that can be performed and constraining hospital ROI.
- Data Interoperability:The lack of standardization between competing robotic platforms and existing hospital information systems, such as electronic health records (EHRs), complicates the aggregation of procedural data and reinforces vendor lock-in.
- Reimbursement Variability:Inconsistent or inadequate reimbursement policies from government and private payors for certain robotic-assisted procedures can deter investment by healthcare providers, who face uncertainty regarding financial returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robotic Surgical Procedures Market |
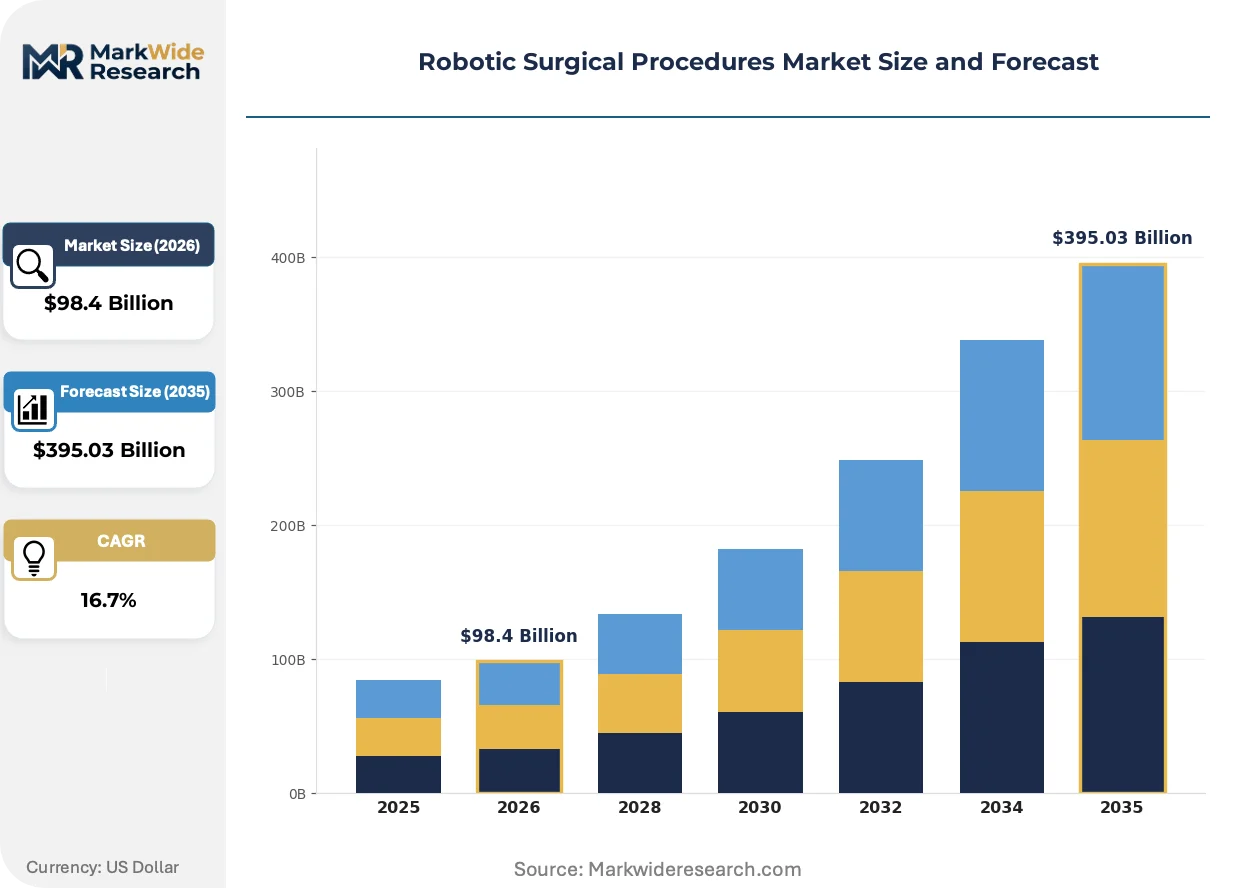
| Market Size in 2026 | $98.4 Billion |
| Market Size in 2035 | $395.03 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Cardiothoracic, Gynecologic, Urologic, Orthopedic, Neurosurgery Technology: Laparoscopic Assistance, Robotic Arm, Image-Guided Systems, Telemanipulation, Haptic Feedback End User: Academic Medical Centers, Specialty Hospitals, Surgery Centers, Teaching Institutions Deployment Model: On-Premise, Cloud-Based, Hybrid, Remote Access |
| Companies Covered | Intuitive Surgical, Stryker, Medtronic, Smith & Nephew, Zimmer Biomet, Johnson & Johnson Services, CMR Surgical, avateramedical, Accuray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robotic Surgical Procedures Market Strategic Shifts & Innovations
The convergence of advanced sensor technology and data analytics is transforming surgical robots from standalone mechanical assistants into integrated, intelligent platforms. This shift is enabling greater precision and creating new methods for evaluating surgical performance and patient outcomes.
Miniaturization of Sensory Feedback
Miniaturized force sensors and advanced haptic feedback systems provide surgeons with real-time tactile information that was absent in earlier robotic platforms. These systems are being adopted in specialties like neurosurgery and microsurgery where a delicate touch is paramount for success. This fusion of sensory data with sub-millimeter robotic accuracy is consolidating the role of robotics in highly complex operations, elevating the standard of care.
Regulatory Acceleration in Key Markets
China's National Medical Products Administration (NMPA) has implemented a "Green Channel" to fast-track the review and approval of innovative medical devices, including domestically developed surgical robots. This policy is stimulating local competition and encouraging multinational firms to establish R&D and manufacturing within China. The orthopedic and general surgery segments are most affected, prompting manufacturers to adapt their regulatory and market-entry strategies for the Chinese market.
Shift to Specialized Procurement Models
Hospital purchasing is evolving from reliance on a single, all-purpose robotic platform toward a multi-vendor strategy that uses specialized systems for different clinical departments. This model allows facilities to acquire best-in-class technology for specific service lines, such as dedicated robots for orthopedics or separate systems for urology. This trend is most prominent within large academic medical centers in the United States seeking to optimize clinical capabilities and operational efficiency.
Robotic Surgical Procedures Market Segmentation
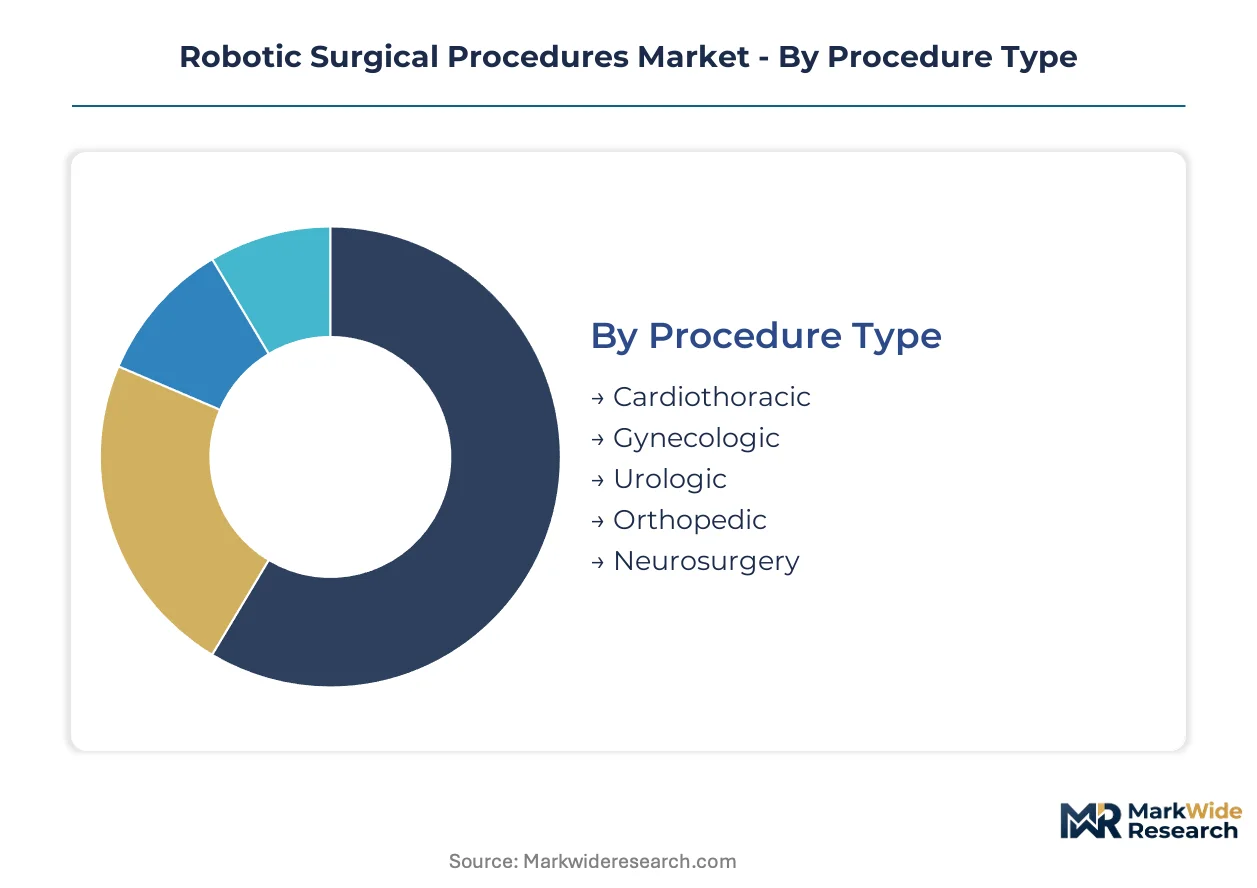
The segmentation of the robotic surgical procedures market provides a granular view of demand patterns and technological adoption across various clinical and operational dimensions. Understanding these distinct segments is crucial for manufacturers to tailor product development and for healthcare providers to optimize system procurement and utilization strategies, aligning with specific patient needs and operational capacities.
Procedure Type:
The market's procedural landscape is shaped by the precision and minimally invasive capabilities offered by robotic systems across diverse surgical disciplines.
- Orthopedic:These procedures involve joint replacement and bone reconstruction, leveraging robotic systems for sub-millimeter accuracy in implant placement and bone preparation. Demand concentrates within academic medical centers and specialized orthopedic hospitals across the United States, driven by the need for improved patient outcomes and reduced revision rates in knee and hip arthroplasties.
- Neurosurgery:Robotic assistance in neurosurgical interventions, including tumor resection and deep brain stimulation, requires extreme precision and advanced imaging integration to navigate delicate neural structures. Growth in this segment is accelerating in developed nations like Germany and Japan, where an aging population increases the incidence of neurological conditions requiring complex surgical solutions.
- Cardiothoracic:Robotic platforms facilitate minimally invasive heart and lung surgeries, reducing recovery times and surgical trauma for patients.
- Gynecologic:These operations, such as hysterectomies and myomectomies, represent a mature segment with high-volume adoption of robotic assistance due to enhanced dexterity and visualization.
- Urologic:Prostatectomies and nephrectomies are common robotic procedures, benefiting from improved surgical precision and reduced blood loss compared to traditional methods.
Urologic procedures lead on scale; Orthopedic procedures lead on momentum.
Technology:
Advancements in core robotic technologies underpin the expansion into more complex and delicate surgical applications.
- Haptic Feedback:This technology provides surgeons with tactile sensations, simulating the feeling of tissue resistance and pressure during surgery, significantly enhancing control and safety. Integration of haptic systems is critical for complex soft-tissue surgeries and microsurgical neurosurgery, improving surgeon confidence and precision in critical maneuvers.
- Robotic Arm:These systems feature articulated arms that hold and manipulate surgical instruments, providing enhanced dexterity, range of motion, and tremor reduction. Robotic arm systems are foundational in orthopedic joint replacement and general surgery, enabling precise execution of pre-planned surgical paths.
- Laparoscopic Assistance:Robotic platforms augment traditional laparoscopic techniques by offering improved 3D visualization and wristed instrumentation for minimally invasive abdominal surgeries.
- Image-Guided Systems:These technologies integrate real-time imaging (e.g., CT, MRI) with robotic navigation, allowing for precise instrument placement and intraoperative adjustments.
- Telemanipulation:This capability allows surgeons to control robotic instruments remotely from a console, translating hand movements into precise instrument actions within the patient.
Haptic Feedback systems are instrumental in improving surgical control; Robotic Arm systems form the backbone of many established platforms.
End User:
The adoption of robotic surgical systems varies significantly across different healthcare institutions based on their operational models and patient demographics.
- Academic Medical Centers:These institutions often serve as early adopters and training hubs for advanced robotic platforms, investing in cutting-edge technology for complex cases and research. Demand concentration for multi-vendor systems is notable within these centers across the United States, driven by a focus on innovation and specialized care.
- Surgery Centers:Ambulatory Surgery Centers (ASCs) seek smaller, more cost-effective, and modular robotic platforms to perform a growing number of outpatient procedures. The opportunity for market penetration in ASCs is driven by the need for flexible procedure-cost models and efficient patient turnover.
- Specialty Hospitals:Facilities focusing on specific medical areas, such as oncology or orthopedics, often invest in robotic systems tailored to their specialized procedural volumes.
- Teaching Institutions:These facilities integrate robotic surgery into their medical education curricula, training future generations of surgeons on advanced platforms.
Academic Medical Centers drive early adoption and research; Surgery Centers represent a significant growth opportunity for modular systems.
Deployment Model:
The way robotic systems are deployed reflects evolving infrastructure capabilities and the need for operational flexibility within healthcare settings.
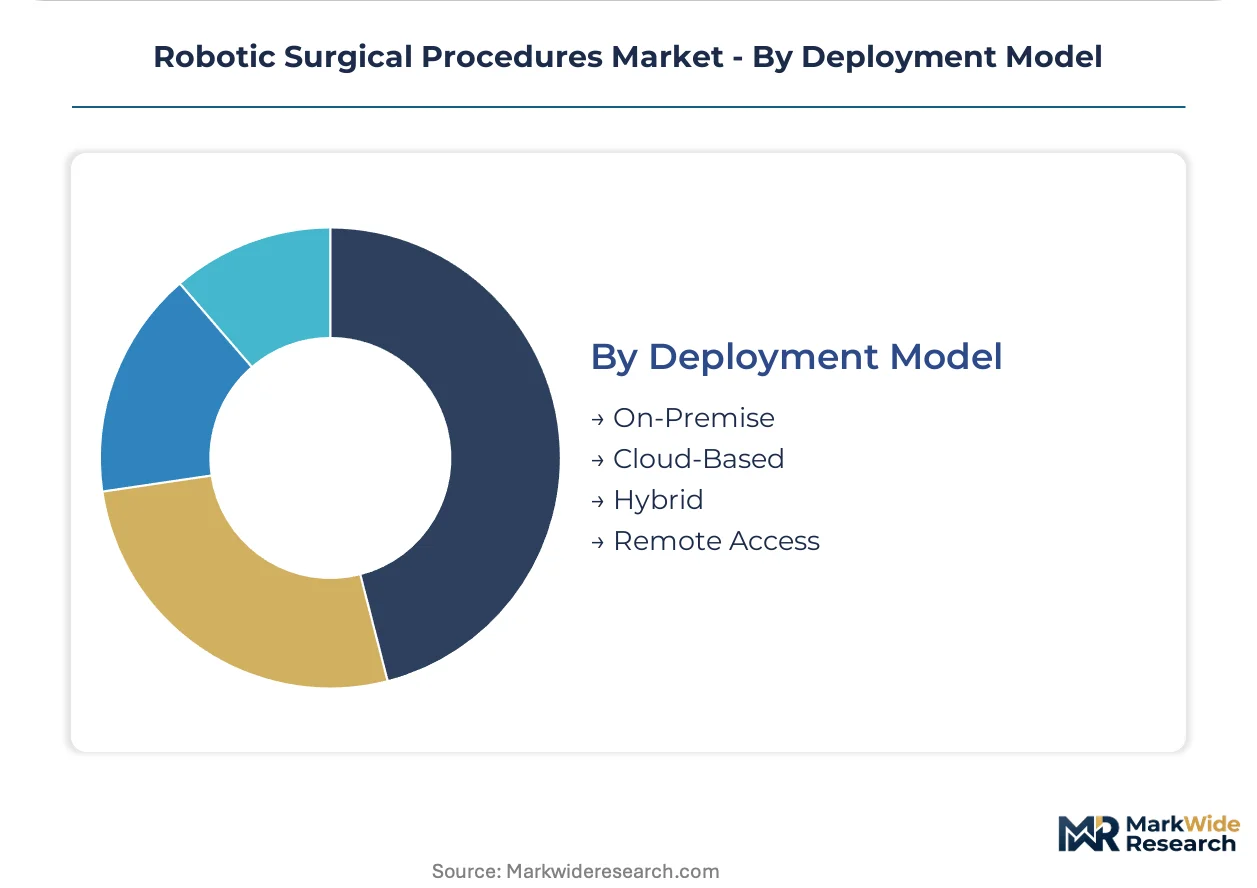
- On-Premise:This traditional model involves installing and maintaining robotic surgical systems directly within the hospital or clinic facility. On-premise deployment is dominant for large, high-capital systems, ensuring direct control over data security and system uptime for critical surgical procedures.
- Remote Access:This model enables surgeons to control robotic systems from a distant location, facilitating tele-surgery and specialist collaboration across geographical barriers. The development of robust network infrastructure and secure data transmission protocols is essential for expanding remote access capabilities in regions like Brazil and India.
- Cloud-Based:These models leverage cloud infrastructure for data storage, analytics, and software updates, potentially reducing local IT burden and enabling advanced data processing.
- Hybrid:Combining elements of on-premise and cloud-based solutions, hybrid models offer a balance of local control for critical functions and cloud flexibility for data management.
On-Premise deployment ensures direct operational control; Remote Access solutions expand surgical reach and specialist availability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers across the United States drive significant demand for robotic surgical procedures. These institutions invest in cutting-edge technology for complex cases and research. The market experiences substantial growth due to the need for advanced surgical precision and improved patient outcomes.
United States
Academic medical centers and orthopedic hospitals demand robotic systems for joint replacement and bone reconstruction. US FDA clearance presents a critical barrier for new robotic platforms. Boston's medical device cluster actively develops advanced haptic systems for surgical robotics.
Germany
An aging population increases the volume of prostatectomies and knee arthroplasties in Germany. The EU's Medical Device Regulation (MDR) imposes stricter post-market surveillance, influencing device lifecycle management. Munich's medtech hub sees investment in specialized robotic systems for neurosurgery and orthopedics.
China
Rising demand for minimally invasive procedures and domestic innovation drive robotic surgical system adoption in China. The NMPA's "Green Channel" fast-tracks review of innovative medical devices, stimulating local competition. Shanghai's medical device manufacturing base attracts multinational firms for R&D and production.
Japan
Japan's aging population and high incidence of neurological conditions accelerate demand for robotic assistance in neurosurgical interventions. PMDA approval processes ensure rigorous safety and efficacy standards for advanced medical devices. Tokyo's academic medical centers are central to the adoption and research of new robotic platforms.
India
Improving healthcare infrastructure in India boosts demand for advanced minimally invasive procedures. The CDSCO's regulatory framework guides market entry and approval of robotic surgical systems. Bengaluru's emerging medical technology sector develops cost-effective robotic solutions for broader market access.
Robotic Surgical Procedures Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized platforms and modular designs for broader surgical applications. The market features a tiered structure, combining well-entrenched incumbent leaders with innovative challengers. Strategic archetypes include comprehensive platform providers, niche technology specialists, and regional innovators. Companies focus on portfolio diversification and geographic expansion to secure market share, alongside strategic partnerships for technology co-development.
Within the established platform provider archetype, US-based Intuitive Surgical represents a market incumbent, anchoring a vast installed base and extensive procedure data. Another US-based entity, Stryker, exemplifies leadership in orthopedic-focused robotic-arm assisted systems, leveraging its strong position in joint replacement. UK-headquartered CMR Surgical occupies a position as an innovator with its modular, flexible system design, targeting a broader range of surgical procedures beyond the traditional high-volume segments. These companies collectively illustrate the diverse approaches to market penetration and technology development.
| Leading Market Players |
|---|
| Intuitive Surgical |
| Stryker |
| Medtronic |
| Smith & Nephew |
| Zimmer Biomet |
| Johnson & Johnson Services |
| CMR Surgical |
| avateramedical |
| Accuray |
Cost & Logistics Intelligence
Robotic surgical system expertise in developed nations, particularly the United States and Germany, creates significant labor-cost differentials. These specialized skill requirements influence pricing tiers for installation, maintenance, and ongoing training services.
Pricing Analysis
Input costs for high-precision components and specialized software drive the initial capital expenditure of robotic surgical systems. Value-based pricing and subscription models are prevalent, with brand premium and comprehensive after-sales service bundles differentiating offerings. Pricing pressure stems from healthcare providers demanding clear economic value propositions and demonstrable return on investment. Community hospitals and those in emerging economies are highly price-sensitive, while academic medical centers prioritize advanced features and clinical outcomes.
Supply Chain Analysis
Direct sales forces and specialized medical device distributors manage downstream supply to healthcare providers globally. Key component manufacturing concentrates in the United States, Germany, and Japan, reflecting advanced technological capabilities. High-precision optical components and advanced microcontrollers are critical raw material dependencies for system production. Single-source vulnerability for specialized sensors presents a structural supply chain risk. Regulatory approvals, such as US FDA clearance, also act as a significant gatekeeper in the supply chain flow.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The robotic surgical procedures market functions as a stable compounder, driven by the persistent demand for improved patient outcomes in complex surgical interventions. Technological advancements consistently expand application areas and enhance precision.
For Market Incumbents:To counter the threat of emerging modular platforms and increasing regulatory scrutiny, market incumbents should invest in software companion development to enhance existing system capabilities. Pursuing strategic partnerships for specialized instrument integration will broaden procedural reach. Expanding data analytics capabilities strengthens evidence for clinical value. Capacity additions in key academic medical centers reinforce market presence.
For New Entrants and Emerging Players:Enter via underserved geographic markets like India and Brazil, which exhibit rising demand for minimally invasive procedures. Focus on Ambulatory Surgery Centers (ASCs) with smaller, more cost-effective, and modular robotic platforms. A go-to-market angle emphasizing flexible procedure-cost models will resonate with budget-conscious providers. Prioritizing regulatory approval under NMPA's "Green Channel" can accelerate market entry in China.
For Investors and Strategic Acquirers:Medical device conglomerates are the most active acquirers in this space, seeking to diversify their surgical technology portfolios. The market offers long-term viability over the next decade, driven by demographic shifts and application expansion. Acquisition targets should include niche technology specialists with advanced haptic feedback or AI integration capabilities. The expansion of reimbursement policies for new robotic-assisted procedures serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Integration for Planning | Enhances surgical precision and reduces operative time for complex cases. |
| Modular System Development | Lowers capital expenditure for Ambulatory Surgery Centers seeking adoption. |
| Haptic Feedback Enhancement | Improves surgeon control in delicate microsurgical neurosurgical procedures. |
| NMPA "Green Channel" Pursuit | Accelerates market entry and stimulates domestic competition in China. |
| Hospital System Partnerships | Secures long-term procurement agreements and training contracts for new platforms. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, extensive secondary validation, and proprietary databases — were reconciled to construct this market analysis. Interviews included biomedical engineers, hospital purchasing committees, surgical department heads, and regulatory affairs specialists. Secondary data sources comprised FDA filings, EU MDR guidelines, NMPA announcements, and relevant academic medical journals. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Data stream reconciliation informed the analytical framework applied across the analysis window. Segmentation dimensions modeled included procedure type, core technology, end user categories, deployment model, and regional healthcare spending patterns. Compound annual growth rates were derived from historical trends, market drivers, and projected adoption rates. Key industry-specific forecast inputs involved aging population demographics and healthcare infrastructure investment.
Inputs from public regulatory filings and industry association reports were available through the study window; gaps in real-time hospital procurement data introduce uncertainty bands. Forecasts reflect assumptions regarding economic stability and healthcare policy continuity. Unforeseen regulatory changes or major technological breakthroughs could revise projections. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
High Frequency Chest-Wall Oscillation Devices Market
Medical Devices
Global Ventilators Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Blood Warmer Devices/Sample Warmer Market
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Organ Preservation Market
Medical Devices
Sleeve Gastrectomy Devices Market
Medical Devices
Posture Correction Market
Medical Devices
Positive Air Pressure Devices Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Global Digital Dentistry Devices Market
Medical Devices
Asia-Pacific Surgical Visualization Products Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Memory Implants Market