
 Supraglottic Device Market | 2026-2036
Supraglottic Device Market Size, Share, and Industry Trends Forecast 2026-2036
Supraglottic Device Market Insights
Ambulatory surgical centers is reorganizing procurement patterns in the Supraglottic Device Market as outpatient procedures expand faster than inpatient volumes. Medtronic leverages its broad anesthesia portfolio to sustain hospital system contracts across integrated delivery networks. Ambu A/S specializes in single-use airway devices, differentiating through disposable-focused portfolios that reduce cross-contamination risk. Smiths Group plc anchors European distribution through established critical care channel relationships.
Supraglottic devices are airway management tools inserted through the mouth to establish a patent airway without tracheal intubation, typically constructed from medical-grade silicone or PVC with inflatable cuffs sealing the perilaryngeal structure. Their primary purpose is to ventilate patients during general anesthesia or emergency resuscitation when endotracheal intubation is contraindicated or technically unfeasible. Laryngeal Mask Airway products occupy the largest revenue pool given their established clinical acceptance across anesthesia protocols, while disposable devices capture expanding share as infection control protocols tighten and hospitals prioritize single-patient-use items over reprocessing workflows. Fast Track Airway variants represent the fastest-growing product category, driven by ambulatory surgery demands for rapid emergence and reduced postoperative airway complications.
The FDA's Class II device controls and ISO 10993 biocompatibility standards govern material safety and clinical validation requirements for market entry in the United States. The EU MDR and CE marking framework in Europe impose strengthened post-market surveillance and clinical evidence obligations that lengthen approval timelines but elevate barrier levels for new entrants. Stakeholders must monitor regulatory divergence between FDA and MDR pathways when allocating product development resources and determining priority launch sequences across jurisdictions.
Market Dynamics
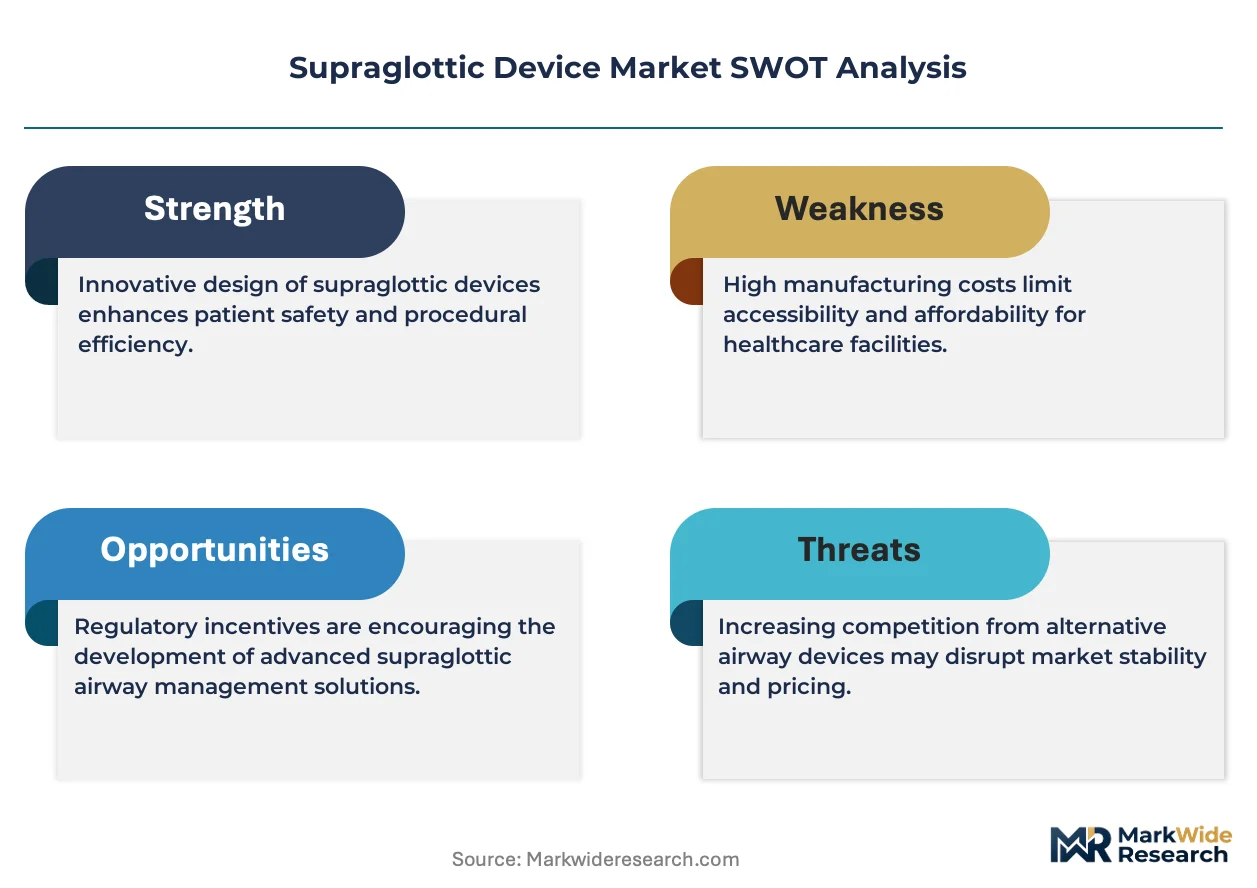
Outpatient surgical migration is compressing inpatient airway device utilization while expanding ambulatory procedure volumes, forcing manufacturers to recalibrate product portfolios toward rapid-emergence designs and single-use formats.
Growth Catalysts
- FDA Class II Premarket Notification Pathway:Streamlined clearance timelines for supraglottic devices with established predicate references accelerate commercialization compared to novel device categories requiring PMA review.
- Pre-hospital Emergency Protocol Expansion:Emergency medical services in the United States are integrating laryngeal mask airways into cardiac arrest and trauma algorithms, extending device utilization beyond operating rooms.
- Silicone Elastomer Biocompatibility:Medical-grade silicone formulations meeting ISO 10993 standards enable thinner cuff membranes and improved perilaryngeal seals, reducing airway leak rates during positive pressure ventilation.
Market Restraints
- Medical-Grade Polymer Feedstock Concentration:Specialty silicone and PVC resin production clusters in Germany and China, exposing device manufacturers to input cost volatility and geopolitical supply disruptions.
- Reusable Device Reprocessing Infrastructure:Hospitals with established central sterile processing departments face sunk-cost barriers when evaluating conversion to single-use alternatives, slowing disposable adoption curves.
- EU MDR Clinical Evidence Requirements:Strengthened post-market surveillance obligations and extended notified body review timelines lengthen approval cycles for new entrants relative to legacy CE-marked products.
Strategic Opportunities
- India Outpatient Surgery Infrastructure:Government-funded health insurance expansion and private hospital chain growth create addressable demand for cost-optimized single-use airway devices in tier-2 and tier-3 cities.
- Video-Assisted Supraglottic Insertion:Integration of disposable airway cameras with laryngeal mask delivery systems enables real-time placement confirmation, reducing failed insertion rates in training environments.
- US Ambulatory Surgery Center Joint Venture Models:Anesthesia management companies and device manufacturers are structuring risk-sharing agreements that bundle airway consumables with service contracts, capturing procedure volume at the facility level.
Industry Challenges
- ISO 18562 Biocompatibility Testing Capacity:Respiratory gas pathway evaluation requirements for new polymer formulations strain specialized laboratory capacity, extending development timelines for material innovations.
- Anesthesiologist Training Standardization:Variable simulation-based credentialing across US academic medical centers creates inconsistent insertion competency benchmarks, complicating product-specific training program design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Supraglottic Device Market |
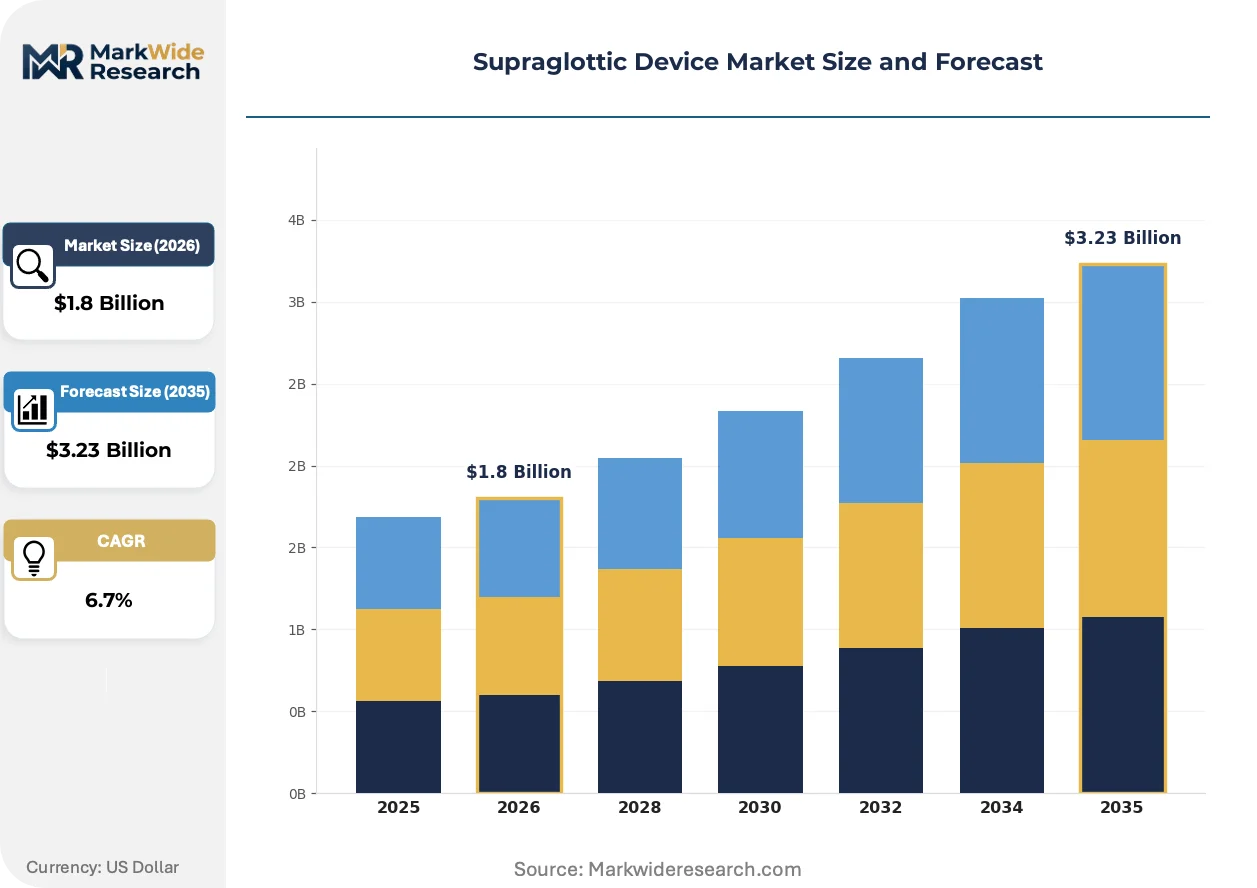
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laryngeal Mask Airway, Classic Style Airway, Fast Track Airway, Others Application: Anesthesia, Emergency Medicine, Critical Care, Airway Management End User: Hospitals, Ambulatory Surgical Centers, Emergency Departments, Pre-Hospital Services Connection Type: Reusable Devices, Disposable Devices, Custom Solutions, Others |
| Companies Covered | Teleflex Incorporated, Medtronic, Intersurgical Ltd., Ambu A/S, BD, Smiths Group plc, Medline Industries, Inc., Olympus Corporation, Verathon Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Supraglottic Device Market Trends and Innovations
Material science advances and regulatory recalibration are compressing traditional product lifecycles while ambulatory care expansion rewires procurement relationships between device suppliers and care delivery organizations.
Second-generation silicone laryngeal masks incorporating gastric access channels and bite-resistant stems are displacing standard single-lumen designs in high-risk anesthesia cases. Academic medical centers in the United States are piloting these devices in bariatric and obstetric populations where aspiration risk complicates airway management. The structural shift is compressing revenue contribution from basic laryngeal mask SKUs while expanding average selling prices for feature-differentiated variants.
EU MDR Article 120 transition timelines and strengthened notified body capacity constraints are extending CE marking intervals for supraglottic device modifications. Manufacturers with legacy product portfolios face portfolio rationalization decisions as recertification costs disproportionately burden low-volume SKUs. European anesthesia departments are observing delayed availability of incremental product improvements as firms prioritize core platform renewals over line extensions.
Group purchasing organization consolidation in the United States is compressing vendor panels and lengthening contract durations for airway management categories. Integrated delivery networks are unbundling device procurement from anesthesia service agreements, forcing direct price competition on single-use supraglottic devices. The behavioral shift is most visible in multi-hospital systems in Texas and Florida where standardized formularies now mandate single-source contracts for laryngeal mask categories.
Supraglottic Device Market Segmentation
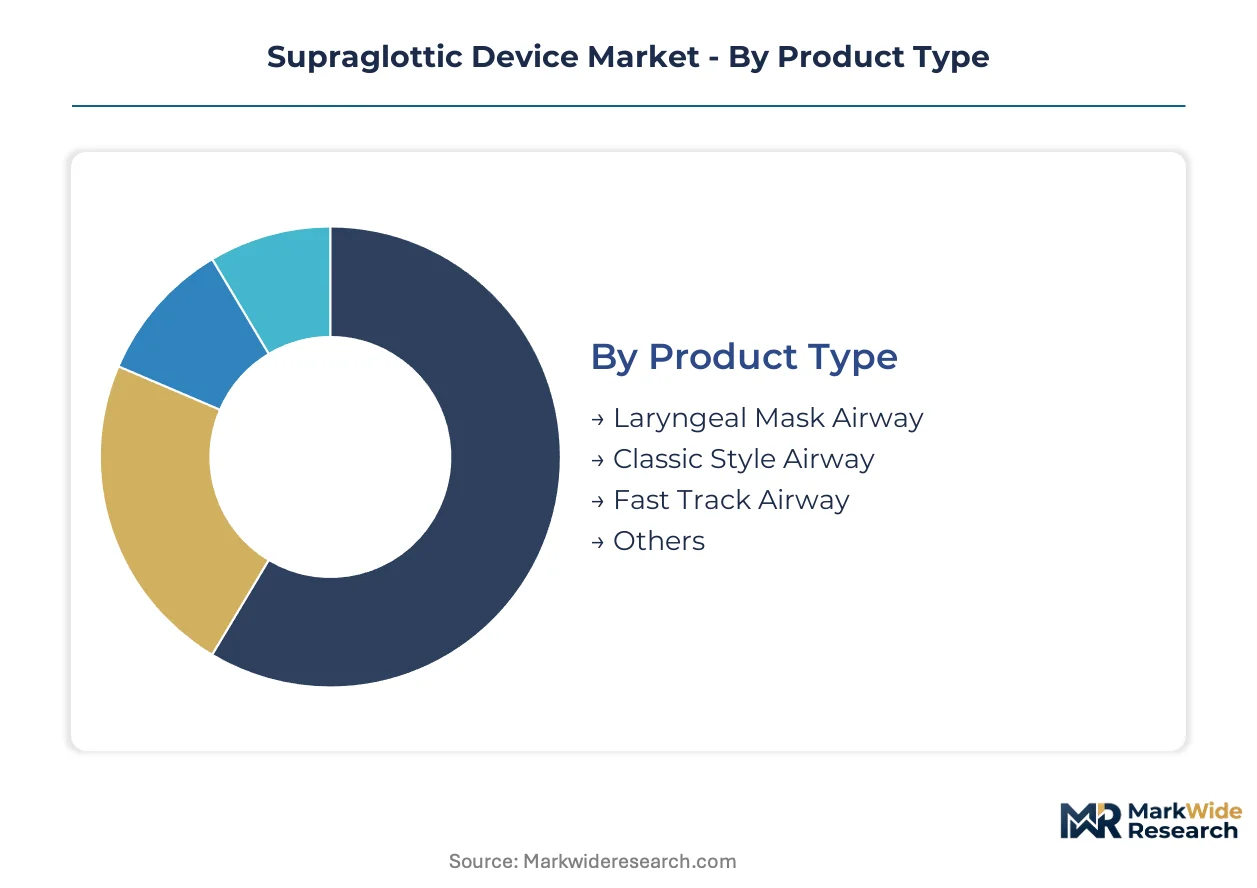
Supraglottic device segmentation reflects divergent clinical workflows across anesthesia, emergency, and critical care settings. Product architecture, patient acuity, and facility infrastructure each reshape procurement priorities and margin structures for manufacturers.
Product Type:
FDA Class II premarket notification pathways and ISO 10993 biocompatibility standards create differentiated regulatory burdens across laryngeal mask designs, with predicate-dependent clearances favoring incremental innovations over novel architectures.
- Laryngeal Mask Airway:Medical-grade silicone or PVC construction with inflatable perilaryngeal cuffs seals the hypopharynx without tracheal penetration. Demand concentrates in United States hospital operating rooms where established anesthesia protocols and training curricula sustain high utilization rates despite emerging alternatives.
- Fast Track Airway:Streamlined insertion profiles and reduced cuff pressures enable rapid emergence characteristics suited to ambulatory surgery turnover requirements. United States ambulatory surgical centers in Texas and Florida are driving fastest adoption as joint venture anesthesia models bundle these devices with service contracts.
- Classic Style Airway:First-generation designs with standard single-lumen construction and fixed curvature tubes remain prevalent in cost-constrained settings and developing markets.
- Others:Specialized variants including intubating laryngeal masks and flexible wire-reinforced designs address niche anatomical challenges and difficult airway algorithms.
Established volume favors Laryngeal Mask Airway; emerging adoption favors Fast Track Airway.
Application:
Patient acuity tiers and reimbursement structures fragment demand across scheduled procedures, unscheduled emergencies, and prolonged ventilatory support, with each application imposing distinct performance specifications on cuff seal reliability and gastric access capabilities.
- Anesthesia:Elective surgical ventilation in controlled settings demands consistent perilaryngeal seals across varying patient body mass indices and positioning requirements. United States integrated delivery networks standardize formulary selections across multi-hospital systems, compressing vendor panels and lengthening contract durations for this high-volume segment.
- Emergency Medicine:Uncontrolled airway scenarios including cardiac arrest and trauma require rapid insertion with minimal cervical spine manipulation. United States emergency medical services protocols are integrating laryngeal mask airways into pre-hospital algorithms, extending utilization beyond traditional hospital boundaries.
- Critical Care:Prolonged ventilatory support applications require enhanced gastric access channels and bite-resistant stem constructions to manage aspiration risk in sedated patients.
- Airway Management:Difficult airway algorithms and anticipated intubation scenarios utilize supraglottic devices as conduits for fiberoptic bronchoscope-guided tracheal intubation.
Reimbursement stability anchors Anesthesia volume; protocol expansion is accelerating Emergency Medicine fastest.
End User:
Capital intensity and sterilization infrastructure separate facility types, with ambulatory migration rewriting procurement relationships and single-use preference curves.
- Hospitals:Central sterile processing departments and established reusable device workflows create sunk-cost barriers to disposable conversion. United States academic medical centers pilot second-generation silicone designs with gastric access channels in bariatric and obstetric populations.
- Ambulatory Surgical Centers:Streamlined supply chains and infection control priorities favor single-use formats with rapid turnover characteristics. United States anesthesia management companies structure risk-sharing agreements that bundle airway consumables with service contracts at the facility level.
- Emergency Departments:Unpredictable patient volumes and space constraints drive preference for compact, ready-to-deploy disposable configurations.
- Pre-Hospital Services:Emergency medical services vehicles and air ambulance platforms require ruggedized packaging and extended shelf stability for field deployment.
Installed base concentration sustains Hospitals; volume growth is climbing fastest in Ambulatory Surgical Centers.
Connection Type:
Material science advances and reprocessing economics collide in procurement decisions, with polymer formulations and sterilization validation requirements determining total cost of ownership calculations.
- Disposable Devices:Single-patient-use silicone or PVC construction eliminates cross-contamination risk and reprocessing labor costs. United States group purchasing organization consolidation is mandating single-source contracts for laryngeal mask categories, intensifying price competition on disposable SKUs.
- Reusable Devices:Autoclavable silicone construction with reinforced cuffs withstands repeated sterilization cycles in hospital central processing departments. European facilities with established reprocessing infrastructure face extended CE marking intervals under EU MDR Article 120 transition timelines, delaying availability of incremental product improvements.
- Custom Solutions:Patient-specific modifications and proprietary connector interfaces address specialized anatomical requirements and equipment compatibility challenges.
- Others:Hybrid configurations and rental programs bridge capital and operating expenditure preferences for mid-sized facilities.
Infection control protocols are displacing Reusable Devices; procurement flexibility is expanding Custom Solutions fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical-grade silicone manufacturers export cuff membrane components to United States device assemblers, creating a transatlantic trade corridor that concentrates raw material sourcing in Central Europe while final production and clinical validation occur in North American markets.
United States
Ambulatory surgical centers in Texas and Florida drive fastest volume expansion as anesthesia management companies bundle airway consumables with service contracts. FDA Class II premarket notification requirements streamline clearance timelines for predicate-referenced designs. Pre-hospital emergency medical services in California integrate laryngeal mask airways into cardiac arrest protocols, extending utilization beyond hospital boundaries.
Germany
Specialty silicone elastomer production clusters in Bavaria and Baden-Württemberg supply perilaryngeal cuff membranes to global device manufacturers. EU MDR Article 120 transition timelines extend CE marking intervals for legacy product modifications. Medical polymer research facilities in Munich advance thinner membrane formulations that reduce airway leak rates during positive pressure ventilation.
China
Domestic hospital chains in tier-2 and tier-3 cities expand procurement of cost-optimized single-use airway devices as government-funded health insurance broadens surgical access. NMPA medical device registration requirements govern market entry for imported and locally manufactured supraglottic products. Manufacturing concentration in Jiangsu and Zhejiang provinces serves both domestic demand and export markets across Southeast Asia.
India
Private hospital chain growth in Maharashtra and Karnataka creates addressable demand for disposable airway management tools in outpatient surgery settings. CDSCO medical device rules impose registration and import licensing requirements that shape product launch sequencing. Medical device distributors in Delhi-NCR and Chennai anchor procurement networks that reach tier-2 city surgical centers.
United Kingdom
Integrated critical care supply chains sustain demand for reusable silicone laryngeal masks in National Health Service hospitals with established central sterile processing infrastructure. MHRA post-Brexit regulatory frameworks diverge from EU MDR pathways, creating separate conformity assessment requirements. Academic medical centers in London and Manchester pilot second-generation gastric access designs in bariatric surgical populations.
Supraglottic Device Market Competitive Landscape
Player mix skews toward diversified medical device conglomerates with broad anesthesia portfolios alongside single-use specialists focused on infection control positioning. Market structure concentrates revenue among five to seven firms with established hospital system contracts and group purchasing organization relationships. Three archetypes dominate: integrated multinationals leveraging cross-category bundling, disposable-focused innovators emphasizing cross-contamination reduction, and regional distributors anchoring geographic procurement networks. Competitive moves center on joint venture anesthesia service agreements at the facility level and portfolio rationalization under tightened EU MDR recertification costs.
Within the integrated multinational tier, Medtronic and Smiths Group plc exemplify conglomerate positioning through broad critical care and anesthesia device portfolios that sustain hospital system contracts. Ambu A/S occupies the single-use specialist archetype, with its corporate structure and naming convention indicating Danish origin and disposable-focused market positioning. Teleflex Incorporated and BD represent North American-domiciled diversified manufacturers with established United States distribution infrastructure. These named entities anchor competitive dynamics without specifying individual product configurations or strategic initiatives beyond archetype-typical positioning patterns.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Medtronic |
| Intersurgical Ltd. |
| Ambu A/S |
| BD |
| Smiths Group plc |
| Medline Industries, Inc. |
| Olympus Corporation |
| Verathon Inc. |
| Others |
Pricing and Supply Chain Analysis
FDA Class II premarket notification requirements gate both supplier qualification and price differentiation simultaneously, as predicate-referenced clearances enable faster market entry while ISO 10993 biocompatibility certifications stratify device tiers across anesthesia procurement channels. This regulatory architecture concentrates pricing power with manufacturers holding established predicate portfolios, while new entrants face extended validation timelines that compress margin flexibility.
Pricing Analysis
Second-generation silicone laryngeal masks with gastric access channels command 40-60% premiums over standard single-lumen designs, while first-generation Classic Style devices face accelerating price erosion in cost-constrained developing markets. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 10993 certification tiers, brand heritage in anesthesia protocols, and volume scale in group purchasing organization contracts. Pricing pressure stems from GPO consolidation in the United States, particularly in Texas and Florida multi-hospital systems, where single-source mandates intensify direct competition on disposable SKUs. Ambulatory surgical centers exhibit highest price sensitivity due to joint venture anesthesia models bundling consumables with service contracts, while academic medical centers prioritize feature differentiation over unit cost.
Supply Chain Analysis
Strategic stockpiling of medical-grade silicone elastomers dominates inventory strategy as German and Chinese feedstock concentration exposes device assemblers to geopolitical disruption risk. Specialty silicone production clusters in Bavaria and Baden-Württemberg supply perilaryngeal cuff membranes, while PVC resin manufacturing concentrates in Jiangsu and Zhejiang provinces serving domestic and Southeast Asian markets. Raw material dependencies center on medical-grade silicone formulations, PVC compounds meeting ISO 10993 standards, and inflation valve components. Single-source vulnerability in German silicone elastomer supply creates tariff exposure and logistics chokepoint risk. Distribution runs through integrated delivery network procurement offices, group purchasing organization contract administrators, and regional medical device distributors reaching tier-2 city surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR Article 120 transition timelines and strengthened notified body capacity constraints are compressing product lifecycles and forcing portfolio rationalization decisions that favor scaled incumbents over fragmented challengers.
For Market Incumbents: Fortify hospital system contract retention by accelerating second-generation gastric access device launches ahead of EU MDR recertification deadlines, while deepening backward integration into medical-grade silicone supply through captive partnerships with Bavarian elastomer manufacturers. Ambu A/S and disposable-focused specialists threaten margin structures through infection control positioning; counter by bundling airway portfolios with anesthesia service joint ventures in high-growth ambulatory surgical center markets. For New Entrants and Emerging Players: Video-assisted supraglottic insertion training represents a service-layer gap where incumbents under-serve anesthesiologist credentialing standardization needs across United States academic medical centers. Target tier-2 and tier-3 cities in India and China where government-funded health insurance expansion outpaces established distribution infrastructure. Deploy direct-to-facility education partnerships with anesthesia management companies as the primary go-to-market angle. For Investors and Strategic Acquirers: EU MDR reshapes the acquisition landscape by disproportionately burdening low-volume SKU portfolios with recertification costs, creating distressed asset opportunities among mid-tier European manufacturers. Long-term viability favors scaled platforms with predicate-rich FDA portfolios and established GPO relationships over single-product innovators. Monitor notified body capacity constraints as the signal indicating accelerated consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Predicate-referenced clearances compress commercialization timelines against PMA-track competitors. |
| CE Marking Pathway Optimization | MDR Article 120 transition planning preserves European market access for core platform SKUs. |
| Hospital System Partnership | Integrated delivery network formulary standardization locks out competing vendors across multi-site contracts. |
| Software Companion Development | Video-assisted insertion training modules differentiate placement confirmation capabilities in academic settings. |
| Reimbursement Strategy | CMS procedural coding alignment secures coverage stability for ambulatory surgical center utilization. |
Research Methodology
A standing panel of anesthesiologists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers provided ongoing calibration across primary interview rounds, with secondary validation drawing from FDA 510(k) filings, EU MDR notified body documentation, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up demand modeling across ambulatory surgical center procedure volumes and top-down market sizing through manufacturer revenue triangulation ensured cross-verification.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning product architecture, patient acuity tier, facility infrastructure type, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity coefficients and device utilization intensity metrics, incorporating anesthesia protocol adoption curves and pre-hospital emergency services integration rates as industry-specific forecast inputs.
Underlying assumptions cover regulatory pathway stability, silicone feedstock supply continuity, and ambulatory surgical center joint venture expansion rates, with deviation risk concentrated in EU MDR notified body capacity constraints and geopolitical disruption to German-Chinese polymer supply corridors. Revision becomes warranted when FDA predicate clearance timelines or MDR recertification cost burdens cross thresholds that alter manufacturer portfolio rationalization decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Acute External Ventricular Drain Market
Medical Devices
US Clear Aligners Market
Medical Devices
Facial Implant Market
Medical Devices
Cholesterol Monitors Market
Medical Devices
India Hemostats Market
Medical Devices
India Spinal Fusion Devices Market
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Anesthesia Face Masks Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
Cytology Brush Market
Medical Devices
Electric Acupuncture Devices Market
Medical Devices
Smart Syringe Pumps Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Global Medical Drones Market