
 North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market | 2026-2036
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market Size, Share, and Industry Trends Forecast 2026-2036
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market Analytics
Recurring maintenance and software-defined surgical planning modules are expanding what device vendors monetize beyond the initial hardware placement. Glaukos Corporation leverages its integrated surgical ecosystem to capture ongoing service revenue from implant monitoring. Alcon sustains competitive pressure through broad cataract-glaucoma combination procedure portfolios. Johnson & Johnson anchors its position via deep R&D investment in sustained-release drug-device platforms.
Micro Invasive Glaucoma Surgery devices constitute miniature implantable or disposable instruments—typically under 1 mm in cross-section—designed to restore physiological aqueous outflow through Schlemm's canal or suprachoroidal pathways without conjunctival dissection. Stent and shunt product categories dominate current volume as established trabecular meshwork bypass designs achieve predictable intraocular pressure reduction. Minimally invasive delivery modes command expanding share by shortening recovery windows and enabling office-based or ambulatory surgical center workflows. Open-angle glaucoma indication segments retain the largest addressable base while refractory glaucoma subsets attract premium pricing for rescue interventions.
FDA 510(k) and premarket approval pathways govern device entry in the United States, while Health Canada and COFEPRIS regulate parallel access in Canada and Mexico respectively. CMS national coverage determinations and provincial health technology assessments directly shape physician adoption economics across the three North American jurisdictions. Stakeholders must monitor evolving real-world evidence requirements that increasingly condition payer reimbursement on demonstrated long-term intraocular pressure stability.
Market Dynamics
CMS reimbursement decisions for MIGS procedures are compressing the window between FDA clearance and commercial adoption, forcing manufacturers to front-load health economic evidence generation alongside traditional safety trials.
Growth Catalysts
- Ambulatory Surgical Center Expansion:CMS facility fee differentials for ASC-based MIGS procedures are redirecting case volume away from hospital outpatient departments across Texas and Florida surgical networks.
- FDA Breakthrough Device Designation:Expedited review pathways for sustained-release drug-device combinations are shortening time-to-market for next-generation trabecular meshwork bypass systems.
- Glaucoma Patient Density Clusters:California's aging demographic concentration and established academic medical center infrastructure generate predictable referral pipelines for MIGS specialists.
Market Restraints
- Titanium Alloy Input Volatility:Stent manufacturing depends on medical-grade titanium supply chains concentrated in aerospace-adjacent foundries, exposing device margins to commodity price swings.
- Single-Surgeon Practice Concentration:MIGS procedure economics require high case volumes that concentrate in metropolitan surgical hubs, leaving rural patient access dependent on mobile surgical unit deployment.
- Trabeculectomy Substitution Persistence:Medicare Advantage plans in certain markets maintain prior authorization requirements favoring established filtering surgery over MIGS for moderate-advanced glaucoma stages.
Strategic Opportunities
- Mexico Market Development:COFEPRIS regulatory harmonization initiatives and private hospital chain expansion in Mexico City and Monterrey create first-mover positioning for MIGS device registration.
- Suprachoroidal Shunt Convergence:Integration of micro-scale sensor telemetry with suprachoroidal drainage devices enables real-time intraocular pressure monitoring post-implantation.
- Office-Based Procedure Channel:Standalone ophthalmology clinics in Texas and Arizona are acquiring in-office surgical suites to capture facility fees previously directed to ASC joint ventures.
Industry Challenges
- Glaucoma Fellowship Training Pipeline:The specialized surgical skill set for angle-based MIGS procedures requires dedicated fellowship exposure, yet accredited program slots remain constrained relative to retiring specialist replacement needs.
- Real-World Evidence Collection Infrastructure:Payer demands for longitudinal intraocular pressure stability data force manufacturers to fund independent patient registries, adding post-market surveillance cost layers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market |
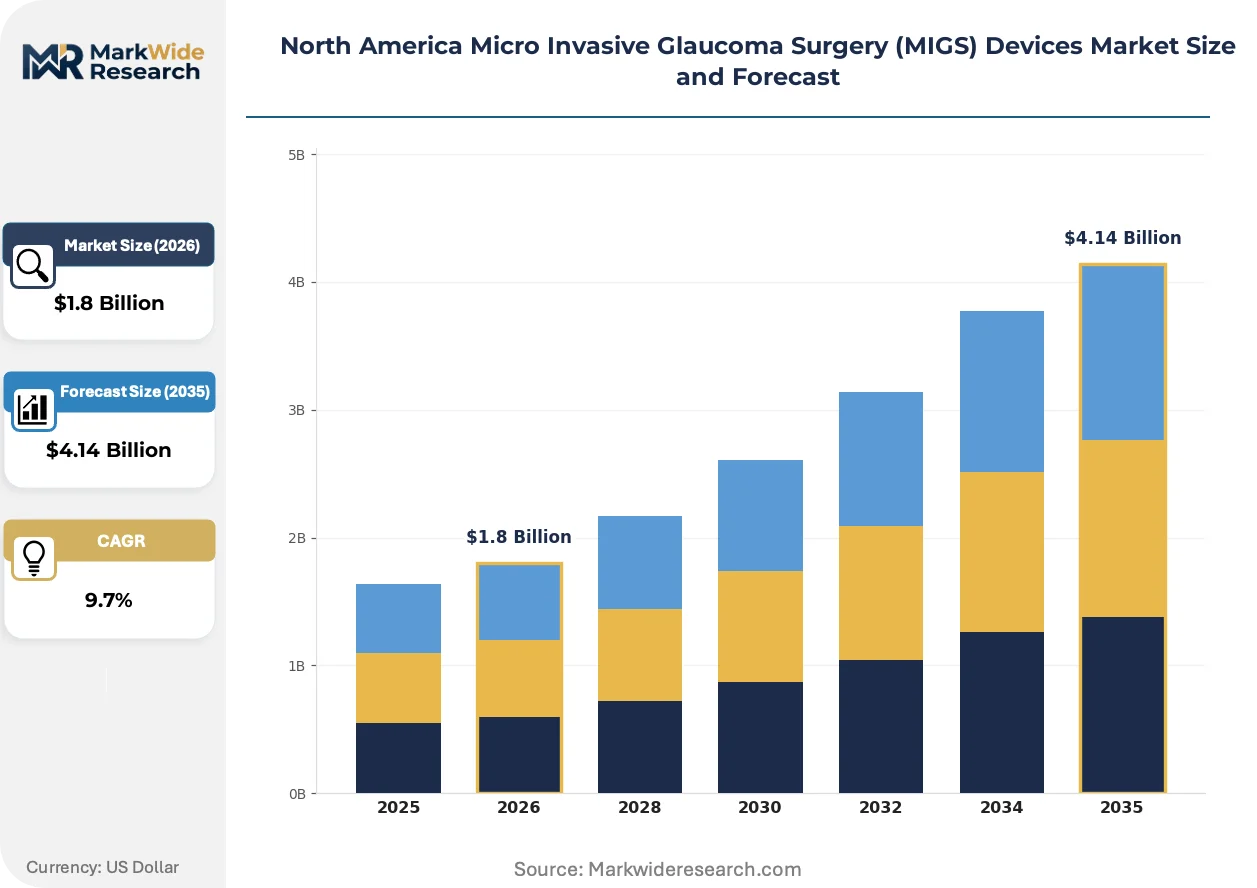
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shunts, Stents, Implants, Devices Delivery Mode: Invasive, Minimally Invasive, Non-invasive, Surgical End User: Ophthalmology Clinics, Hospitals, Research Centers, Ambulatory Surgical Centers Indication: Open-angle Glaucoma, Angle-closure Glaucoma, Pediatric Glaucoma, Refractory Glaucoma |
| Companies Covered | Glaukos Corporation, Alcon, Johnson & Johnson, AbbVie Inc., Carl Zeiss Meditec AG, New World Medical, Santen Pharmaceutical, Lumenis, IRIDEX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market Evolving Landscape
Device architecture is converging around biocompatible polymer platforms that enable drug-eluting functionality without hardware redesign, while surgical planning software migrates toward cloud-based subscription models.
Drug-eluting MIGS implants are unifying pressure reduction and pharmaceutical delivery into single-procedure interventions. Ophthalmology clinics in California and Florida are adopting these hybrid systems for moderate glaucoma stages. This convergence is unifying previously separate pharmaceutical and device procurement budgets into consolidated capital allocations.
FDA's evolving guidance on combination product classification is restructuring premarket submission strategies for drug-device platforms. Manufacturers now front-load quality system documentation to address both Center for Devices and Radiological Health and Center for Drug Evaluation and Review requirements simultaneously. Sustained-release implant categories face the steepest compliance trajectory under this dual-track framework.
After-sales service unbundling is fragmenting traditional device-vendor relationships. Ambulatory surgical centers in Texas are negotiating direct maintenance contracts with third-party surgical instrument servicers, bypassing manufacturer service departments. This disintermediation concentrates in high-volume MIGS practices seeking to compress per-case overhead.
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market Segmentation
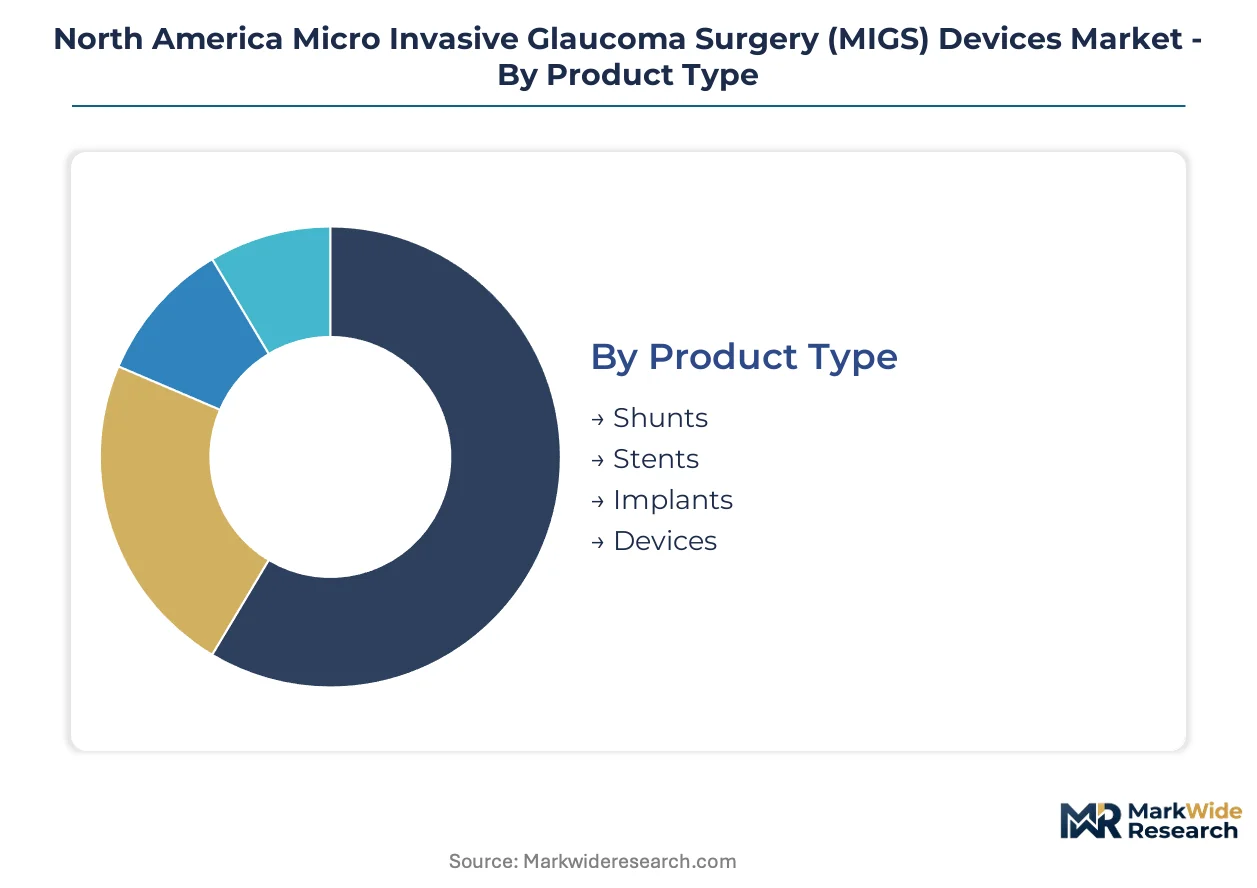
Segmentation reveals how MIGS device procurement patterns diverge across clinical settings and patient populations. Understanding these splits enables vendors to align R&D investment with the highest-margin procedure categories and reimbursement pathways.
Product Type:
Volume leadership rests with trabecular meshwork bypass designs, while premium pricing attaches to drug-eluting platforms and sustained-release combinations.
- Shunts:Suprachoroidal drainage devices redirect aqueous humor through alternative outflow pathways using biocompatible polymer construction. Demand clusters in California academic medical centers managing refractory glaucoma cases where conventional filtration has failed.
- Stents:Trabecular meshwork bypass implants—typically under 1 mm in cross-section—restore physiological outflow through Schlemm's canal without conjunctival dissection. Texas ASC networks favor these for rapid case turnover and predictable facility fee economics.
- Implants:Reservoir-based systems enable localized pharmaceutical delivery alongside pressure reduction.
- Devices:Disposable instrumentation and surgical planning hardware complete the procedural ecosystem.
Mature deployment sits with Stents. Newer deployment is concentrated in Shunts.
Delivery Mode:
Procedure economics are driving a decisive shift toward techniques that compress recovery windows and enable ambulatory workflows.
- Minimally Invasive:Angle-based approaches through clear corneal incisions eliminate scleral flap construction and reduce postoperative management burden. Florida ophthalmology clinics are converting standalone glaucoma procedures to this modality to capture facility fees previously directed to hospital outpatient departments.
- Invasive:Conjunctival dissection and scleral flap techniques persist in specific rescue scenarios.
- Non-invasive:Laser-based trabeculoplasty and cyclophotocoagulation serve as bridging therapies.
- Surgical:Traditional incisional approaches retain relevance for combined cataract-glaucoma interventions.
Minimally Invasive delivery is gaining share fastest as ASC infrastructure expands across the Sun Belt.
End User:
Facility type determines both procurement authority and the sophistication of service contracts vendors must negotiate.
- Ambulatory Surgical Centers:High-volume MIGS specialists in Texas and Arizona are acquiring dedicated ophthalmology suites to consolidate facility fees and instrument turnover. These buyers negotiate direct maintenance contracts with third-party servicers, bypassing manufacturer service departments.
- Ophthalmology Clinics:Standalone practices in California and Florida are deploying in-office surgical infrastructure to capture procedures previously referred to ASC joint ventures.
- Hospitals:Academic medical centers maintain complex case referral pipelines and fellowship training programs.
- Research Centers:Investigational device exemption trials and real-world evidence registries concentrate in established glaucoma research consortia.
Procurement sophistication is highest in Ambulatory Surgical Centers. Volume expansion is steepest in Ophthalmology Clinics.
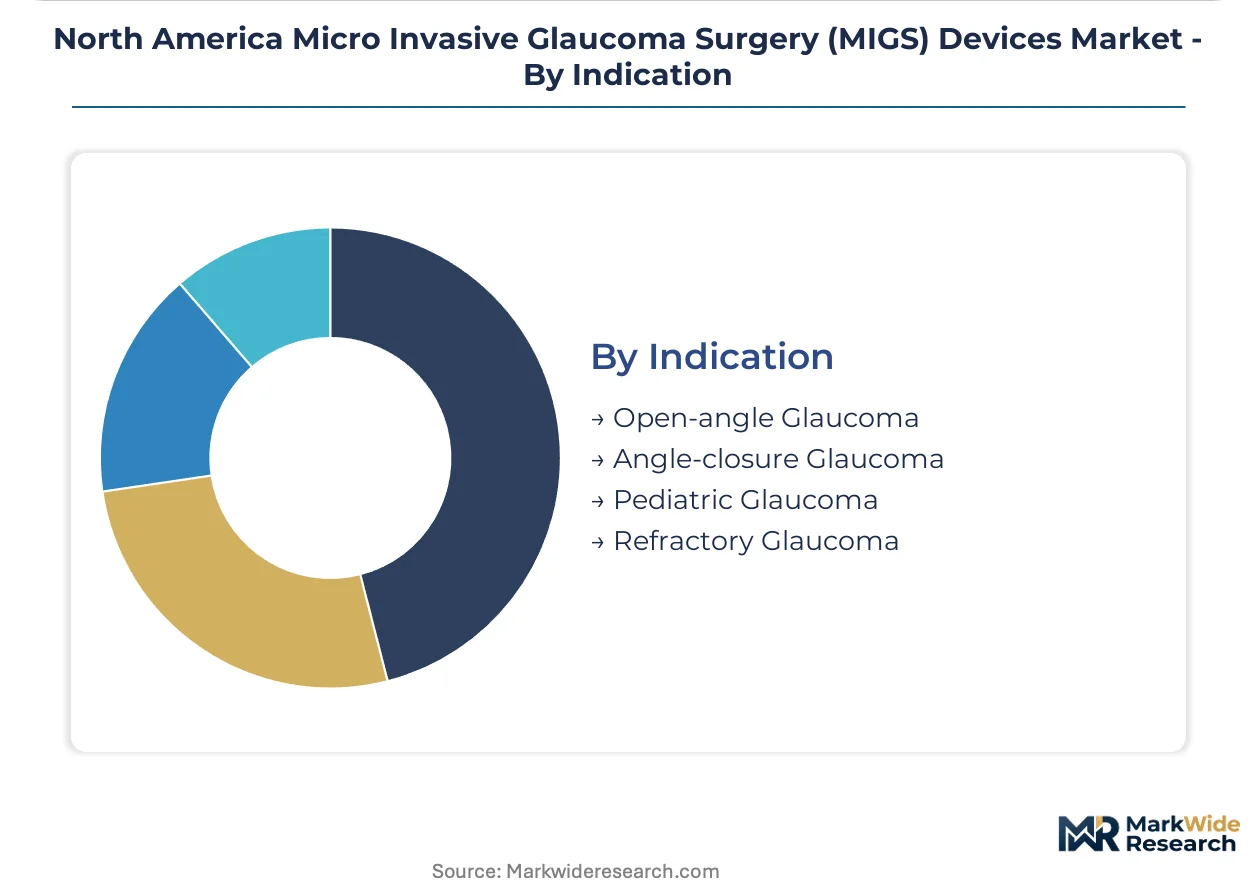
Indication:
Addressable patient populations vary dramatically in size, reimbursement intensity, and competitive dynamics.
- Open-angle Glaucoma:The predominant disease subtype drives baseline procedure volume across all North American markets. California's aging demographic concentration generates predictable referral pipelines for primary surgical intervention at moderate disease stages.
- Refractory Glaucoma:Failed prior surgical or medical therapy creates premium pricing opportunities for rescue interventions. Medicare Advantage prior authorization requirements in certain markets still favor trabeculectomy over MIGS for this subset.
- Angle-closure Glaucoma:Anatomical variations require modified surgical approaches and specialized training.
- Pediatric Glaucoma:Congenital and juvenile forms demand distinct device sizing and long-term monitoring protocols.
Open-angle Glaucoma represents the largest addressable base. Refractory Glaucoma commands the steepest pricing premium per procedure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturing concentrates in aerospace-adjacent foundries supplying medical-grade titanium, while procedure demand clusters in aging coastal demographics. California, Texas, and Florida absorb the majority of MIGS interventions due to glaucoma patient density and specialized surgical infrastructure.
United States
FDA premarket approval pathways and CMS reimbursement decisions shape commercial access across the country. Medicare Advantage plans in certain markets maintain prior authorization requirements favoring established filtering surgery over MIGS for moderate-advanced stages. California's aging demographic concentration and established academic medical center infrastructure generate predictable referral pipelines for MIGS specialists.
Canada
Provincial health technology assessments directly shape physician adoption economics alongside Health Canada regulatory oversight. Private hospital chain expansion in Toronto and Vancouver creates concentrated demand for premium intervention categories. Ontario and British Columbia lead procedure volume due to demographic concentration and specialized ophthalmology fellowship programs.
Mexico
COFEPRIS regulatory harmonization initiatives and private hospital chain expansion in Mexico City and Monterrey create first-mover positioning for device registration. The country's national pharmaceutical regulator has streamlined combination product classification for sustained-release platforms. Guadalajara medical device manufacturing clusters are attracting contract manufacturing partnerships for titanium alloy component fabrication.
Texas
CMS facility fee differentials for ASC-based MIGS procedures are redirecting case volume away from hospital outpatient departments across Texas surgical networks. Standalone ophthalmology clinics are acquiring in-office surgical suites to capture facility fees previously directed to ASC joint ventures. Houston and Dallas-Fort Worth metropolitan areas concentrate high-volume MIGS specialists with dedicated ophthalmology infrastructure.
Florida
Florida ophthalmology clinics are converting standalone glaucoma procedures to minimally invasive modalities to capture facility fees previously directed to hospital outpatient departments. The state's retiree demographic concentration generates sustained demand for primary surgical intervention at moderate disease stages. Miami and Tampa academic medical centers maintain complex case referral pipelines and fellowship training programs.
North America Micro Invasive Glaucoma Surgery (MIGS) Devices Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the MIGS device ecosystem. The vendor base clusters around three strategic tiers: integrated surgical ecosystem providers, broad ophthalmology portfolio conglomerates, and specialized angle-based intervention developers. Consolidation pressure intensifies as reimbursement compression forces scale efficiencies in health economic evidence generation. Dominant competitive moves include strategic partnerships for sustained-release drug-device combinations and geographic expansion into underpenetrated ambulatory surgical center networks.
Within the integrated ecosystem tier, Glaukos Corporation exemplifies the surgical platform model capturing ongoing service revenue from implant monitoring. Alcon and Johnson & Johnson occupy positions as diversified ophthalmology conglomerates leveraging broad cataract-glaucoma combination procedure portfolios. Johnson & Johnson anchors the sustained-release drug-device convergence through deep R&D investment in pharmaceutical-eluting platforms.
| Leading Market Players |
|---|
| Glaukos Corporation |
| Alcon |
| Johnson & Johnson |
| AbbVie Inc. |
| Carl Zeiss Meditec AG |
| New World Medical |
| Santen Pharmaceutical |
| Lumenis |
| IRIDEX Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade titanium alloy feedstock from aerospace-adjacent foundries flows through three pricing tiers before reaching ambulatory surgical centers, with commodity volatility at the smelter level compressing margins for device manufacturers locked into long-term hospital system contracts.
Pricing Analysis
Margin tightening in standard stent tiers reflects CMS reimbursement compression and third-party servicer disintermediation in Texas ASC networks. Three-tier pricing structure across premium drug-eluting, standard trabecular bypass, and economy disposable instrumentation segments stratifies by FDA breakthrough designation status and bundled after-sales monitoring. Cost-down pressure on economy tiers accelerates because high-volume ASC buyers negotiate direct maintenance contracts bypassing manufacturer service departments. Ophthalmology clinics converting to in-office surgical suites exhibit highest price sensitivity, while academic medical centers managing refractory cases show lowest sensitivity due to premium rescue intervention budgets.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume ASC procurement, while distributor networks serve lower-volume ophthalmology clinics. Titanium alloy supply concentrates in US aerospace-adjacent foundries and Guadalajara medical device manufacturing clusters, with biocompatible polymer feedstock sourcing from Germany and Japan. Raw material dependencies rest on medical-grade titanium, specialized polymer resins, and precision-machined delivery instrumentation. Single-source vulnerability in aerospace-titanium supply chains exposes device margins to commodity price swings when defense procurement cycles surge. Distribution runs through manufacturer-direct sales forces for tier-one accounts and regional distributors for fragmented clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America MIGS market is becoming a vertical-integration race, with control over sustained-release pharmaceutical supply and real-world evidence registry infrastructure emerging as the decisive downstream lever separating ecosystem winners from component suppliers.
For Market Incumbents: Anchor position through captive supply of drug-eluting polymer platforms and exclusive ASC maintenance contracts in Texas and Florida networks. Defensive consolidation must address third-party servicer disintermediation threatening recurring revenue streams. Deepen control over real-world evidence collection infrastructure to satisfy payer demands for longitudinal intraocular pressure stability data. For New Entrants and Emerging Players: Sensor-telemetry integration for suprachoroidal shunts offers a technology-first wedge against established trabecular bypass incumbents. Mexico's COFEPRIS harmonization pathway and private hospital expansion in Mexico City represent the most penetrable geographic white space. Target office-based procedure channels in Arizona and Texas clinics acquiring in-office surgical infrastructure, using reimbursement strategy consulting as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA breakthrough device designation awards for sustained-release combinations are the leading indicator that a target's regulatory de-risking timeline has compressed. Long-term viability in this market hinges on owning both device hardware and pharmaceutical delivery components rather than single-product positioning. Acquisition focus should center on mid-cap developers with dual-track FDA submissions already filed. Watch for CMS national coverage determinations expanding MIGS procedure codes as the signal that reimbursement tailwinds are accelerating.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review pathways compress time-to-market for drug-device combinations competing in premium tiers. |
| ASC Joint Venture Partnership | Facility fee capture in Texas and Florida redirects case volume from hospital outpatient departments. |
| Real-World Evidence Registry Funding | Independent patient registries satisfy payer demands for longitudinal intraocular pressure stability documentation. |
| COFEPRIS Registration First-Mover Positioning | Regulatory harmonization in Mexico City and Monterrey opens underpenetrated private hospital channels. |
| Drug-Eluting Platform Convergence | Unified pressure reduction and pharmaceutical delivery consolidates previously separate procurement budgets. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews with glaucoma fellowship program directors, ASC operations managers, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) and PMA submission databases, CMS national coverage determinations, Health Canada device licensing records, and COFEPRIS registration filings. Bottom-up procedure volume estimates by state and facility type were triangulated against top-down manufacturer shipment data.
Segment-level modeling addressed product type, delivery mode, end-user facility category, and glaucoma indication severity across the projection horizon. CAGRs were derived from procedure volume trajectories, reimbursement rate assumptions, and technology substitution curves. Industry-specific forecast inputs included CMS facility fee differential trends, fellowship training program expansion rates, and titanium alloy price indices.
Several conditions sit outside the modeled scope, including abrupt FDA guidance changes on combination product classification, major Medicare Advantage plan consolidation affecting prior authorization patterns, and geopolitical disruption to aerospace-titanium supply chains. Forecasts reflect assumptions about sustained CMS reimbursement stability and gradual COFEPRIS harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Memory Implants Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Smart Stairlift Market
Medical Devices
Peri-Implantitis Market
Medical Devices
Medical Face Shield Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
Global Electroceuticals Market
Medical Devices
Medical Oxygen Concentrators Market
Medical Devices
Otoacoustic Emissions Hearing Screener Market
Medical Devices
Global Casting Devices Market
Medical Devices
Organ Care Market
Medical Devices
Medical Polyimide Tubing Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
Intelligent Prosthetics Market