
 Global Plastic Surgery Software Market | 2026-2036
Global Plastic Surgery Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Plastic Surgery Software Market Foresight
Enterprise-grade HIPAA compliance and SOC 2 Type II certification is collapsing into baseline expectations rather than premium positioning. Symplast leverages cloud-native architecture to dominate the mobile-first segment for plastic surgeons. ModMed sustains R&D intensity across integrated EHR-practice management suites for aesthetic specialties. Nextech anchors geographic dominance in North American mid-market aesthetic clinics through channel control and specialty-specific workflows.
Plastic surgery software encompasses clinical and operational platforms engineered to manage patient imaging, surgical simulation, practice workflows, and regulatory documentation across cosmetic and reconstructive procedures, typically integrating DICOM-compliant image rendering with HL7 FHIR interoperability standards. Simulation software occupies the highest-margin tier as surgeons demand photorealistic 3D modeling for preoperative consultation and informed consent documentation. Patient management software leads volume adoption across aesthetic clinics seeking unified scheduling, billing, and outcome tracking. Cloud-based deployment is displacing on-premise installations as clinics prioritize remote accessibility and reduced IT overhead.
The FDA enforces 21 CFR Part 820 quality system regulations for software-as-medical-device classifications, while HIPAA mandates encryption and access controls for protected health information in all patient-facing platforms. The EU MDR and GDPR impose parallel clinical evidence and data residency requirements that shape product roadmaps for vendors seeking transatlantic market access. Stakeholders must monitor evolving FDA guidance on AI-enabled surgical simulation tools and determine whether to pursue premarket notification pathways or predicate device equivalency claims.
Market Dynamics
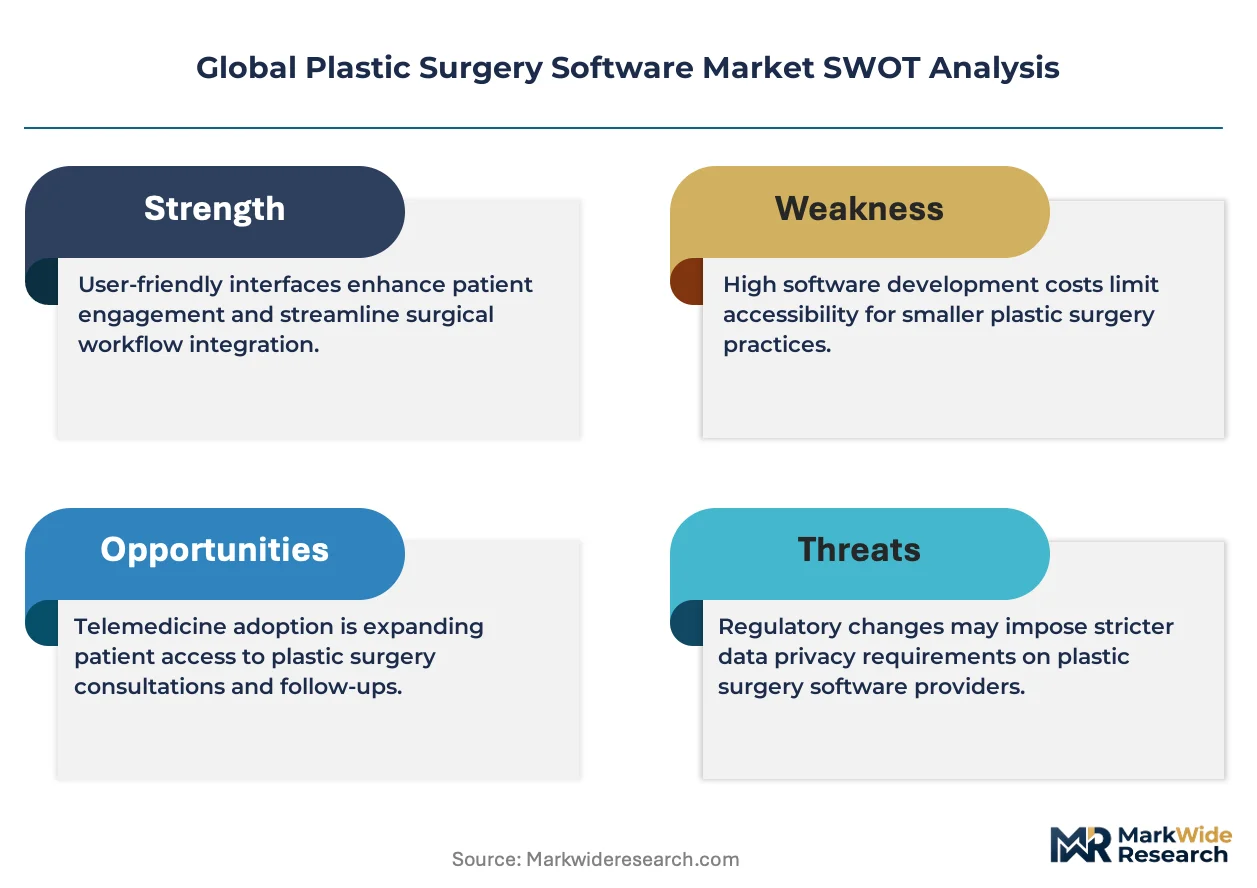
Cloud-native deployment architectures are compressing IT infrastructure cycles across aesthetic practices, forcing incumbent vendors to rebuild core platforms or surrender mid-market share to mobile-first entrants.
Growth Catalysts
- HL7 FHIR Interoperability Mandates:The US ONC's 21st Century Cures Act enforcement compels EHR-agnostic data exchange, accelerating replacement of legacy siloed systems in multi-location cosmetic surgery groups.
- Seoul Metropolitan Cluster Density:South Korea's concentrated Gangnam-gu aesthetic corridor generates specialized workflow demands for high-volume consultation scheduling and multilingual patient portals.
- Photorealistic 3D Simulation:GPU-accelerated rendering engines enable sub-minute facial morphing during live consultations, converting browser-based tools from novelty to clinical necessity.
Market Restraints
- FDA 21 CFR Part 820 Validation Costs:Software-as-medical-device classification demands exhaustive design controls and risk documentation, consuming 18-24 month development timelines for imaging modules.
- AWS-Google Cloud-Azure Concentration:Cloud infrastructure dependency among three hyperscalers exposes practices to egress fee volatility and regional outage cascades.
- On-Premise Technical Debt:Legacy Windows Server installations in established practices block API-first integrations, trapping data in disconnected PACS archives.
Strategic Opportunities
- Brazil's Underpenetrated Outpatient Sector:São Paulo's emerging aesthetic chains lack integrated practice management, creating first-mover advantage for Portuguese-localized cloud suites.
- AI-Enabled Surgical Outcome Prediction:Machine learning models trained on preoperative imaging datasets enable risk-adjusted consent protocols and malpractice premium reductions.
- EU MDR Article 10 Clinical Evidence Pathways:Simulation software with validated clinical performance data qualifies for CE marking under medical device regulations, opening transatlantic revenue streams.
Industry Challenges
- DICOM-HL7 Integration Specialist Scarcity:Practices struggle to hire engineers fluent in both medical imaging standards and modern REST API architectures, delaying cloud migration projects.
- SOC 2 Type II Audit Duration:Boutique software vendors face 6-9 month certification cycles that stall enterprise sales pipelines at security review stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Plastic Surgery Software Market |
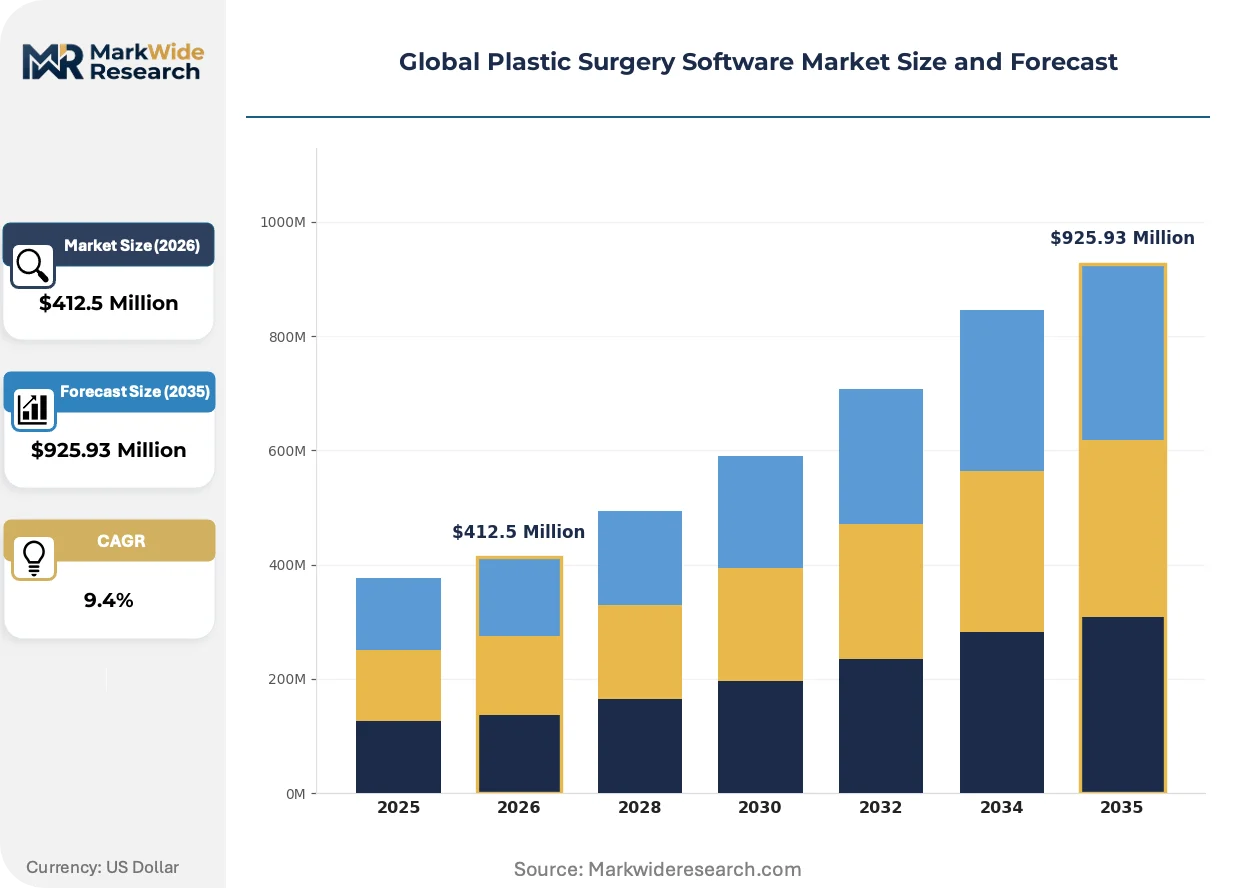
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $925.93 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Simulation Software, Patient Management Software, Imaging Software, Practice Management Software Application: Facial Reconstruction, Breast Surgery, Body Contouring, Minimally Invasive Procedures End User: Plastic Surgeons, Aesthetic Clinics, Medical Spas, Cosmetic Dermatologists Deployment Mode: Cloud-Based, On-Premise, Hybrid, Mobile Applications |
| Companies Covered | Symplast, Pabau, PatientNow, 4D EMR, Remedly, ModMed, AdvancedMD, Ambula Health, Nextech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Plastic Surgery Software Market Shifts & Advancements
Generative AI is rewriting preoperative consultation workflows while regulatory frameworks on both sides of the Atlantic harden compliance requirements for algorithmic clinical tools.
Edge-deployed inference engines for real-time facial analysis are fragmenting the traditional server-client architecture of surgical simulation platforms. Boutique aesthetic clinics in Dubai and Miami Beach are piloting tablet-native rendering that eliminates on-premise workstation dependencies. This decentralization is fragmenting vendor pricing power and enabling subscription tiers previously inaccessible to solo practitioners.
The EU AI Act's high-risk system classification for medical device software is triggering conformity assessment obligations for any surgical planning tool with autonomous decision-support features. German and French notified bodies are backlogged with CE marking applications, delaying product launches by 8-14 months. Vendors are responding by stripping automated recommendations from initial releases, shipping deterministic rule-based versions instead.
Subscription-based consumption models are displacing perpetual license structures across North American mid-market clinics. Private equity-backed aesthetic rollups in Texas and Florida now mandate SaaS-native platforms with standardized outcome dashboards for portfolio-wide benchmarking. This financialization of practice management is most visible in the Sun Belt, where acquisition-driven consolidation demands interoperable reporting across formerly independent entities.
Global Plastic Surgery Software Market Segmentation
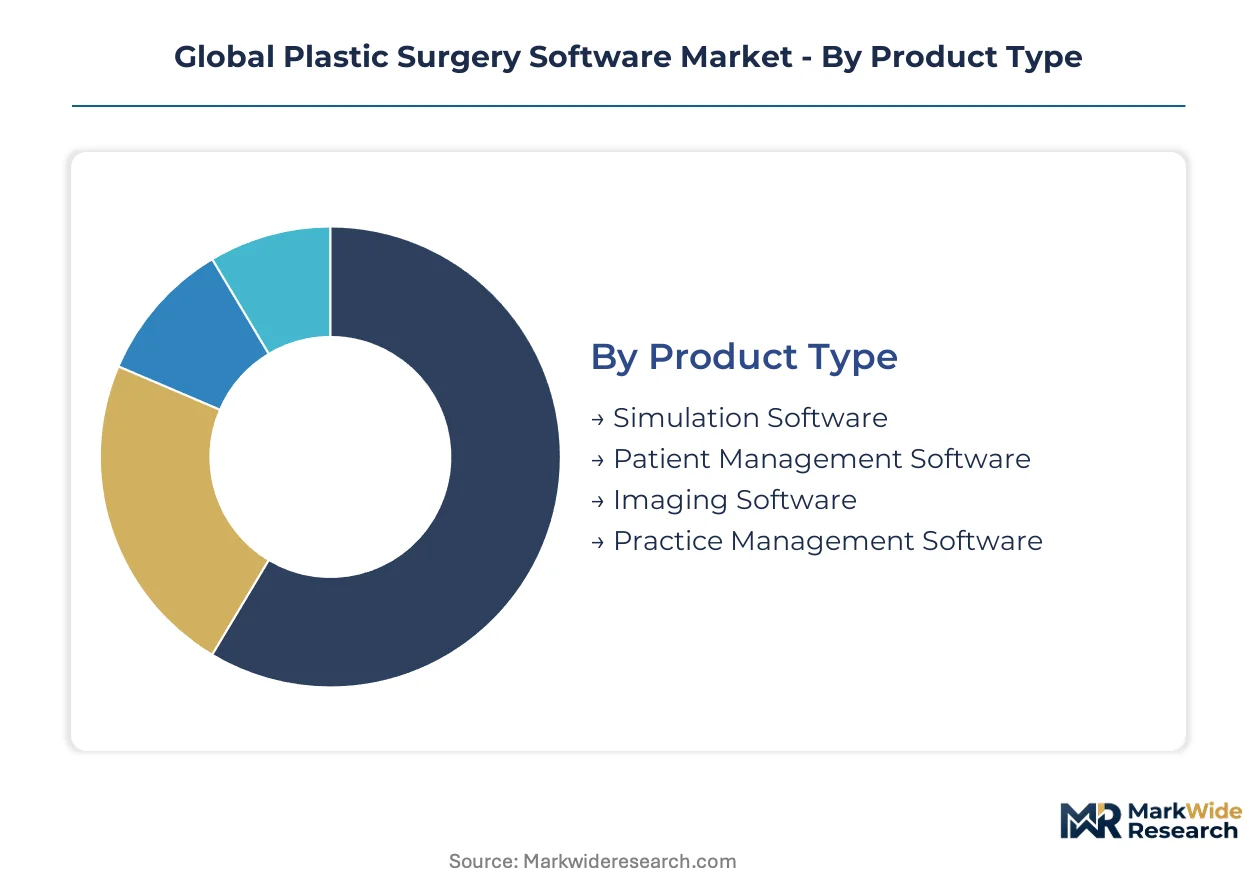
Segmentation in plastic surgery software reflects divergent regulatory burdens and clinical workflows across cosmetic versus reconstructive specialties. Vendors must architect platforms that satisfy FDA 21 CFR Part 820 design controls for simulation modules while maintaining lightweight deployment for cash-pay aesthetic clinics.
Product Type:
FDA classification intensity separates high-margin simulation tools from operational platforms subject to lighter oversight.
- Simulation Software:GPU-accelerated 3D rendering engines generate photorealistic facial morphing for preoperative consultation. Demand concentrates in Seoul's Gangnam-gu aesthetic corridor where high-volume consultation throughput requires sub-minute rendering latency.
- Patient Management Software:Unified scheduling, billing, and outcome tracking platforms integrate HL7 FHIR interoperability for multi-location practice groups. Adoption accelerates across Texas and Florida private equity-backed aesthetic rollups demanding standardized dashboards for portfolio benchmarking.
- Imaging Software:DICOM-compliant visualization tools for surgical planning and postoperative documentation.
- Practice Management Software:End-to-end operational platforms encompassing inventory, staff scheduling, and financial reporting.
Established volume favors Patient Management Software; emerging adoption favors Simulation Software.
Application:
Procedure reimbursement pathways dictate software investment priority, with reconstructive cases requiring comprehensive documentation and cosmetic cases emphasizing conversion optimization.
- Facial Reconstruction:Craniomaxillofacial planning tools integrate with hospital PACS networks for trauma and congenital defect correction. Demand clusters at academic medical centers in the United States and Germany where reconstructive fellowship programs drive advanced simulation adoption.
- Breast Surgery:Augmentation and reduction planning modules require implant database integration and asymmetry analysis algorithms. Brazilian outpatient chains in São Paulo represent the steepest expansion trajectory for Portuguese-localized cloud suites.
- Body Contouring:Liposuction and abdominoplasty visualization tools for patient expectation management.
- Minimally Invasive Procedures:Injection planning and thread lift simulation for medical spa environments.
Reconstructive documentation requirements anchor Facial Reconstruction; aesthetic volume growth propels Breast Surgery.
End User:
Credentialing standards and liability exposure create distinct procurement patterns across surgeon-led practices versus institutional settings.
- Plastic Surgeons:Board-certified specialists demand CE-marked simulation tools for validated clinical performance data under EU MDR Article 10 pathways. German and French notified body backlogs delay product launches by 8-14 months for this segment.
- Aesthetic Clinics:Multi-procedure facilities prioritize mobile-first platforms with remote accessibility. Miami Beach and Dubai boutique clinics pilot tablet-native rendering eliminating on-premise workstation dependencies.
- Medical Spas:Non-surgical service providers seeking lightweight scheduling and consent management.
- Cosmetic Dermatologists:Physician extenders requiring integration with dermatology-specific EHR systems.
Regulatory validation investment targets Plastic Surgeons; deployment simplicity wins Aesthetic Clinics.
Deployment Mode:
Infrastructure control preferences fragment across generational practice ownership and IT staffing capabilities.
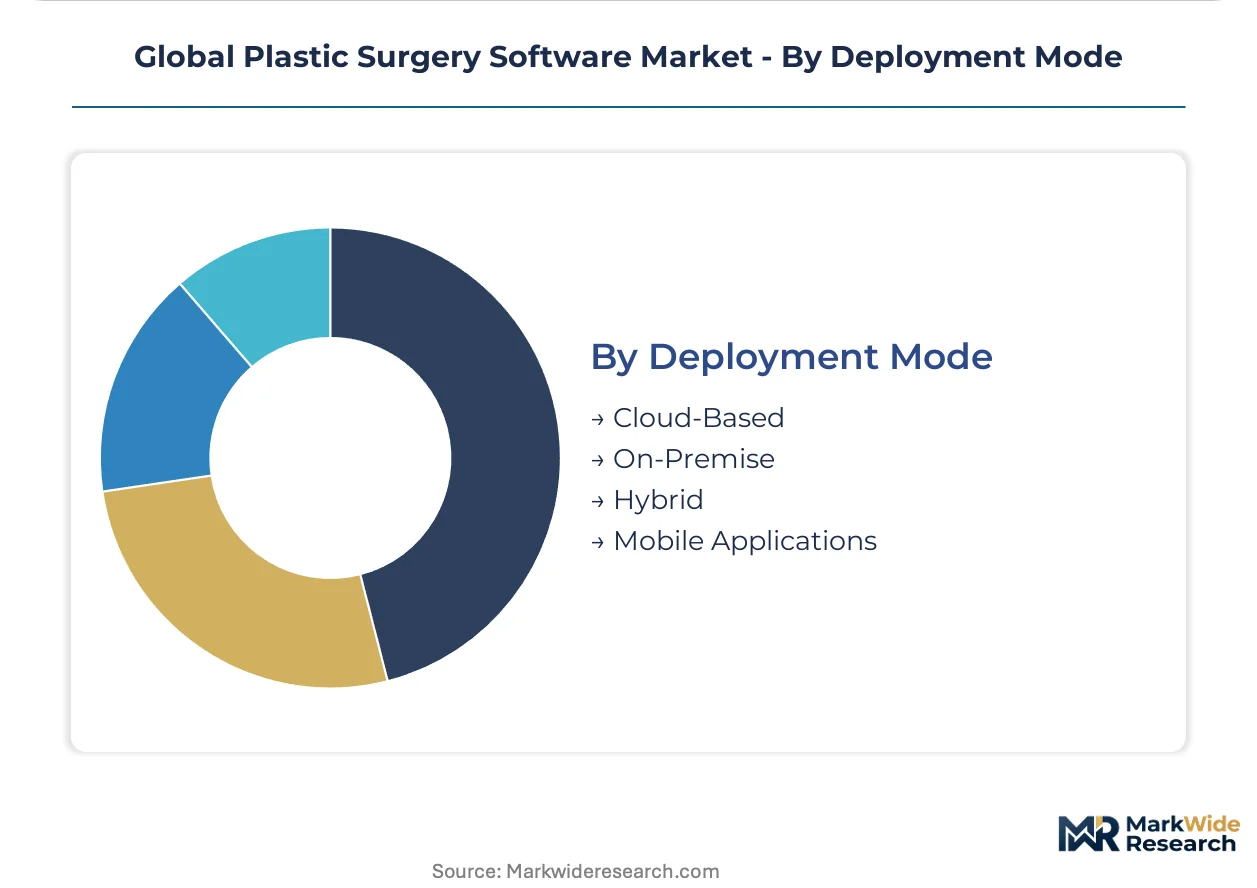
- Cloud-Based:SaaS-native architectures with AWS-Google Cloud-Azure hyperscaler dependency enable remote accessibility and reduced IT overhead. Egress fee volatility and regional outage cascades represent concentrated risk exposure.
- On-Premise:Legacy Windows Server installations in established practices block API-first integrations, trapping data in disconnected PACS archives and delaying migration timelines.
- Hybrid:Mixed architectures preserving sensitive imaging on local storage while leveraging cloud for operational functions.
- Mobile Applications:iOS and Android-native consultation tools for bedside patient engagement.
Technical debt accumulation favors Hybrid as transitional architecture; greenfield deployment favors Cloud-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud infrastructure providers concentrate disproportionately in the United States, while specialized software vendors distribute across Germany, South Korea, Brazil, and the UAE to capture localized regulatory and workflow requirements.
United States
FDA's 21 CFR Part 820 quality system regulation tightens validation requirements for imaging and simulation tools, compelling vendors to maintain exhaustive design controls. HIPAA mandates encryption and access controls for protected health information across all patient-facing platforms. Aesthetic clinics in Texas and Florida now mandate SaaS-native platforms with standardized outcome dashboards for private equity-backed portfolio benchmarking.
Germany
EU MDR Article 10 clinical evidence pathways require validated performance data for CE marking of simulation software, with notified bodies backlogged 8-14 months. GDPR imposes strict data residency requirements that shape product roadmaps for transatlantic vendors. Academic medical centers in Bavaria and North Rhine-Westphalia drive advanced simulation adoption through reconstructive fellowship programs.
South Korea
MFDS medical device regulations parallel EU MDR requirements for software-as-medical-device classifications. The Seoul metropolitan area's Gangnam-gu aesthetic corridor generates specialized workflow demands for high-volume consultation scheduling and multilingual patient portals. GPU-accelerated rendering engines enable sub-minute facial morphing during live consultations in this high-density cluster.
Brazil
ANVISA oversees medical device software registration with evolving pathways for AI-enabled surgical planning tools. São Paulo's emerging aesthetic chains lack integrated practice management systems, creating first-mover advantage for Portuguese-localized cloud suites. Outpatient sector underpenetration concentrates demand generation in the Southeast region.
United Arab Emirates
MOHAP regulates health information technology with emphasis on data localization for patient records. Dubai's boutique aesthetic clinics pilot tablet-native rendering that eliminates on-premise workstation dependencies. The emirate's medical tourism positioning drives demand for multilingual patient engagement platforms and remote consultation capabilities.
Global Plastic Surgery Software Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with cloud-native specialists commanding premium positioning against legacy on-premise incumbents. The vendor base stratifies across three tiers: mobile-first entrants, integrated EHR-practice management suites, and specialty-specific workflow platforms. Dominant competitive moves include M&A rollups by private equity-backed aesthetic consolidators and API-first partnership strategies to bypass legacy technical debt.
Within the mobile-first tier, Symplast exemplifies cloud-native architecture dominance for plastic surgeons seeking bedside consultation tools. ModMed and Nextech occupy positions in the integrated suite segment, with the former representing R&D-intensive EHR-practice management convergence and the latter anchoring geographic concentration in North American mid-market aesthetic clinics through channel control mechanisms.
| Leading Market Players |
|---|
| Symplast |
| Pabau |
| PatientNow |
| 4D EMR |
| Remedly |
| ModMed |
| AdvancedMD |
| Ambula Health |
| Nextech |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 820 quality system regulation gates both vendor qualification and price differentiation simultaneously, compelling simulation software developers to absorb validation costs that stratify offerings across certified and uncertified tiers while cloud infrastructure concentration compresses margins for operational platforms.
Pricing Analysis
FDA 21 CFR Part 820 dictates the pricing tier structure across plastic surgery software, separating SOC 2 Type II-certified cloud suites from uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects validation depth, with GPU-accelerated simulation modules commanding premium positioning due to design control documentation. Cost compression in mid-market patient management software is intensifying because AWS-Google Cloud-Azure hyperscaler dependency exposes practices to egress fee volatility. Solo practitioners in Miami Beach and Dubai boutique clinics exhibit highest price sensitivity, while academic medical centers in Germany and the United States demonstrate lowest sensitivity to certification-driven premiums.
Supply Chain Analysis
Port congestion along Asia-Pacific trade lanes elevates inbound logistics costs for GPU hardware destined for Seoul's Gangnam-gu rendering clusters. Software development concentrates in the United States, Germany, and South Korea, with cloud infrastructure provisioning anchored in hyperscaler data centers across Virginia, Frankfurt, and Singapore. Raw material dependencies span NVIDIA A100/H100 accelerators, DICOM-compliant imaging libraries, and HL7 FHIR interoperability modules. Single-source vulnerability in GPU supply chains threatens sub-minute facial morphing latency guarantees. Distribution runs through direct SaaS provisioning and channel partnerships with aesthetic practice management consultants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI integration is accelerating market disruption, with EU AI Act high-risk system classification creating regulatory friction that separates adaptive vendors from compliance-lagged competitors.
For Market Incumbents: Secure SOC 2 Type II certification renewal cycles ahead of enterprise procurement reviews to defend against mobile-first entrants like Symplast. Deepen backward integration into cloud-native architectures to escape legacy Windows Server technical debt that traps data in disconnected PACS archives. Channel control through specialty-specific workflow partnerships anchors geographic dominance against integrated suite competitors.
For New Entrants and Emerging Players: Differentiate on tablet-native rendering for Dubai and Miami Beach boutique clinics where on-premise workstation elimination creates first-mover advantage. Target São Paulo's emerging aesthetic chains with Portuguese-localized cloud suites in an underpenetrated outpatient sector. Pursue API-first partnership strategies with private equity-backed aesthetic rollups demanding standardized outcome dashboards.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed aesthetic consolidators in Texas and Florida now mandating SaaS-native platforms for portfolio-wide benchmarking. Long-term viability hinges on EU MDR Article 10 clinical evidence pathway completion for transatlantic revenue expansion. Monitor German and French notified body backlog clearance as inflection indicator for simulation software launch timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance opens transatlantic revenue streams for simulation vendors. |
| Platform Integration | HL7 FHIR interoperability mandates accelerate replacement of legacy siloed systems. |
| Strategic Partnership | API-first alliances with hyperscalers bypass legacy technical debt for cloud migration. |
| Acquisition of Specialist Firm | DICOM-HL7 integration talent scarcity drives consolidation of scarce engineering capabilities. |
| Geographic Expansion | Portuguese-localized cloud suites capture São Paulo's emerging aesthetic chain demand. |
Research Methodology
Initial hypotheses were tested against primary input from plastic surgeons, aesthetic clinic operators, biomedical engineers, and GPO contracts managers and refined through secondary validation against FDA 510(k) filings, EU MDR notified body decisions, hospital procurement databases, and hyperscaler capex disclosures. Bottom-up sizing of cloud deployment volumes across Texas and Florida private equity-backed rollups was triangulated against top-down estimates of Seoul metropolitan cluster software spend.
Variance decomposition across deployment mode, organization size, procedure type, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectory modeling incorporating AI-enabled surgical outcome prediction adoption curves and MFDS medical device registration timelines. GPU rendering latency requirements and multilingual patient portal localization costs fed directly into price elasticity estimates.
Decision-makers should treat outputs as directional under assumptions of sustained HIPAA enforcement and EU AI Act implementation timelines; material deviation in notified body processing speeds or hyperscaler pricing would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Health Solutions
Distance Health Technologies Market
Digital Health Solutions
Pharmacovigilance (PV) and Drug Safety Software Market
Digital Health Solutions
Electronic Data Capture Systems Market
Digital Health Solutions
Medical Virtual Reality Operating Systems Market
Digital Health Solutions
Augmented and Virtual Reality in Healthcare Market
Digital Health Solutions
UAE Mhealth Market
Digital Health Solutions
Cloud Technologies in Healthcare Market
Digital Health Solutions
Asia-Pacific Eclinical Solutions Market
Digital Health Solutions
Teleradiology Software Market
Digital Health Solutions
Eclinical Solutions Market
Digital Health Solutions
Global Metaverse in Healthcare Market
Digital Health Solutions
Mhealth Services Market
Digital Health Solutions
Digital Therapeutics and Wellness Market
Digital Health Solutions
Global Patient Portal Market
Digital Health Solutions
Global Smart Hospital Market
Digital Health Solutions
North America Patient Support Technology Market