
 Outpatient Oncology Infusion Market | 2026-2036
Outpatient Oncology Infusion Market Size, Share, and Industry Trends Forecast 2026-2036
Outpatient Oncology Infusion Market Analysis
Modular infusion protocol bundling is hardening as the dominant service configuration, pushing cancer centers to package drug delivery with patient monitoring and supportive care into standardized episodes. Fresenius Kabi leverages its parenteral nutrition and oncology portfolio to anchor hospital-adjacent outpatient sites. Becton, Dickinson and Company sustains technology leadership in closed-system transfer devices for hazardous drug handling. Baxter competes through integrated medication delivery platforms that span premixed solutions to smart pump ecosystems.
Outpatient oncology infusion denotes the administration of antineoplastic agents, biologics, and supportive therapies in non-inpatient settings using vascular access devices, ambulatory pumps, and closed-system transfer mechanisms with filtration specifications typically ranging from 0.2 to 1.2 microns, designed to deliver cytotoxic and targeted compounds while minimizing healthcare-acquired infection risk and preserving patient functional status. Intravenous infusion dominates procedure volume across cancer types, though subcutaneous delivery is gaining protocol share for monoclonal antibodies engineered for depot absorption. Immunotherapy within drug type classifications commands expanding capacity investment as checkpoint inhibitors require extended infusion durations and specialized hypersensitivity monitoring. Cancer centers as an end-user segment concentrate margin pools through dedicated pharmacy compounding infrastructure and pharmacy benefit carve-outs.
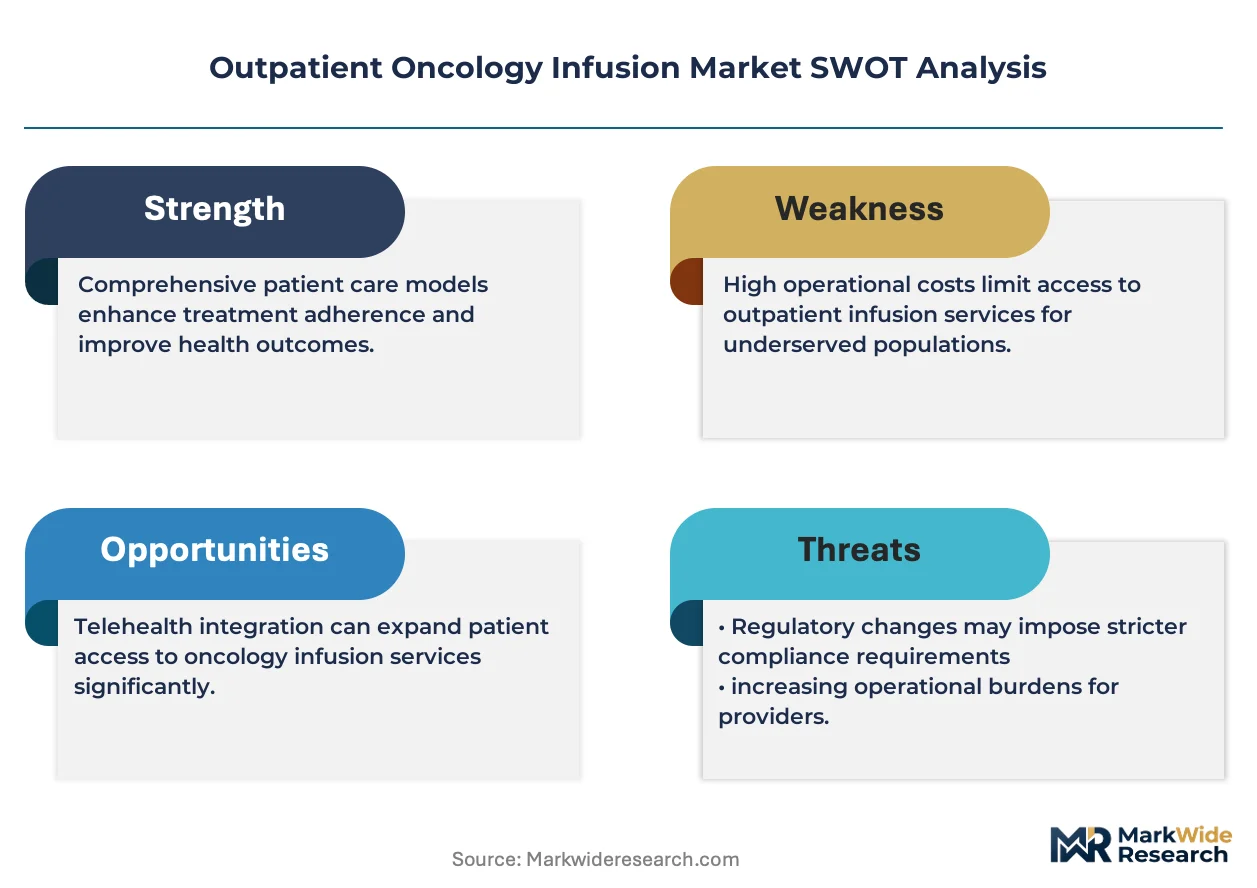
The FDA oversees oncology drug approval and infusion safety labeling, while the USP <800> standard governs hazardous drug handling in compounding and administration environments, jointly elevating capital requirements for compliant outpatient infrastructure. State pharmacy boards layer additional oversight on sterile compounding operations, creating variable licensure thresholds that fragment multi-site operator expansion timelines. Stakeholders must weigh site-of-care migration momentum against reimbursement volatility and capital intensity of USP <800>-compliant cleanroom investments.
Market Dynamics
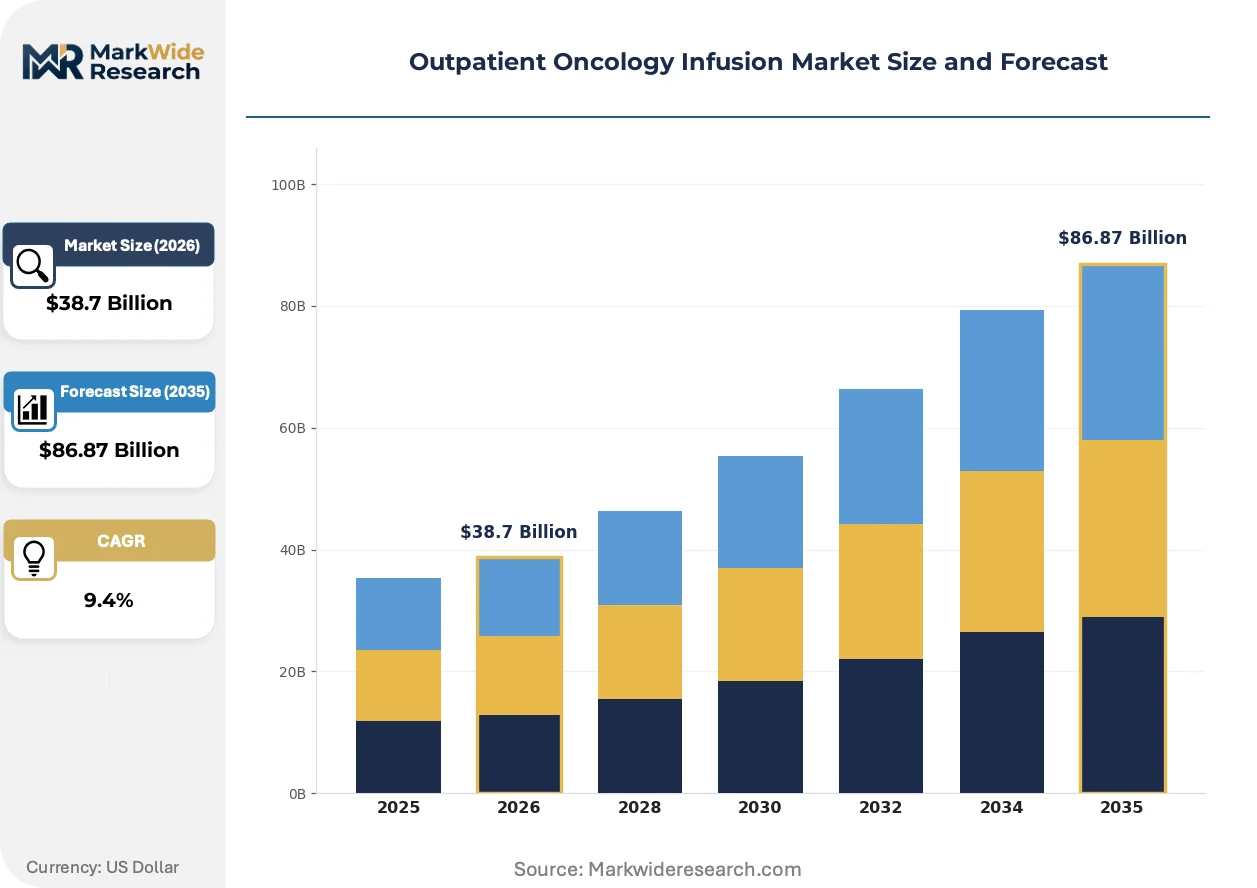
Site-neutral Medicare reimbursement is compressing hospital-based infusion margins and accelerating capital migration toward freestanding cancer centers with USP <800>-compliant compounding infrastructure.
Growth Catalysts
- IRA Drug Pricing Reform:Medicare price negotiations for infused oncology therapies reduce patient cost-sharing burdens and expand treatment access at outpatient sites.
- Monoclonal Antibody Engineering:Extended half-life biologics enable subcutaneous administration protocols that shift volume from infusion centers to home settings.
- Community Cancer Center Expansion:United States-based regional networks are building dedicated outpatient infusion wings to capture site-of-care arbitrage.
Market Restraints
- USP <800> Capital Burden:Hazardous drug handling requirements mandate negative-pressure cleanroom investments exceeding two million dollars per facility.
- Platinum-Based Drug Supply Concentration:Cisplatin and carboplatin API manufacturing concentrates in India and China, exposing formulators to geopolitical supply interruptions.
- Closed-System Transfer Device Patent Thickets:BD and Equashield IP portfolios create licensing friction for generic device entrants.
Strategic Opportunities
- Rural Health Clinic Exemption Leverage:CMS 340B drug pricing eligibility extends to remote outpatient infusion sites serving underserved counties.
- Home Infusion Nursing Networks:Specialized oncology home care platforms capture extended-duration immunotherapy administration outside fixed facilities.
- Digital Therapeutic Adjunct Bundling:Remote patient monitoring platforms pair with infusion protocols to reduce emergency department utilization.
Industry Challenges
- Compounding Pharmacy Workforce Gap:Board-certified oncology pharmacists with sterile hazardous drug credentials remain scarce relative to facility expansion timelines.
- EHR-Infusion Pump Interoperability:Legacy hospital information systems require costly middleware development to integrate smart pump data streams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outpatient Oncology Infusion Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $86.87 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infusion Type: Intravenous, Subcutaneous, Oral, Intramuscular Cancer Type: Breast Cancer, Lung Cancer, Colorectal Cancer, Lymphoma End User: Clinics, Hospitals, Homecare, Cancer Centers Drug Type: Chemotherapy, Targeted Therapy, Immunotherapy, Hormonal Therapy |
| Companies Covered | Fresenius Kabi, IRadimed Corporation, Becton, Dickinson and Company, Terumo Corporation, Teleflex, Baxter, ICU Medical, Inc, Nipro Corporation, B. Braun Melsungen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outpatient Oncology Infusion Market Emerging Trajectories
Closed-system engineering and digital integration are compressing administration error rates while regulatory pressure on hazardous drug exposure accelerates device replacement cycles.
Closed-system transfer devices with integrated filtration and vapor containment are unifying drug preparation and administration safety protocols into single-workflow platforms. Community-based cancer centers in the United States are adopting these systems at replacement rates exceeding thirty percent annually. This unification is compressing capital expenditure timelines by eliminating separate engineering controls for compounding versus administration zones.
The FDA's updated guidance on accelerated approval confirmatory trial requirements is tightening post-market evidence obligations for infused oncology therapies. Manufacturers must now complete randomized trials prior to conversion to full approval or face withdrawal. Checkpoint inhibitor developers are responding by embedding real-world evidence collection into infusion center partnerships.
Episode-based payment contracts are displacing fee-for-service chemotherapy administration in United States commercial and Medicare Advantage networks. Cancer centers are consolidating pharmacy benefit management relationships to capture bundled margins across drug acquisition, infusion nursing, and supportive care. This restructuring is most visible in Florida and Texas markets where vertical health system consolidation has preceded payer contract renegotiations.
Outpatient Oncology Infusion Market Segmentation
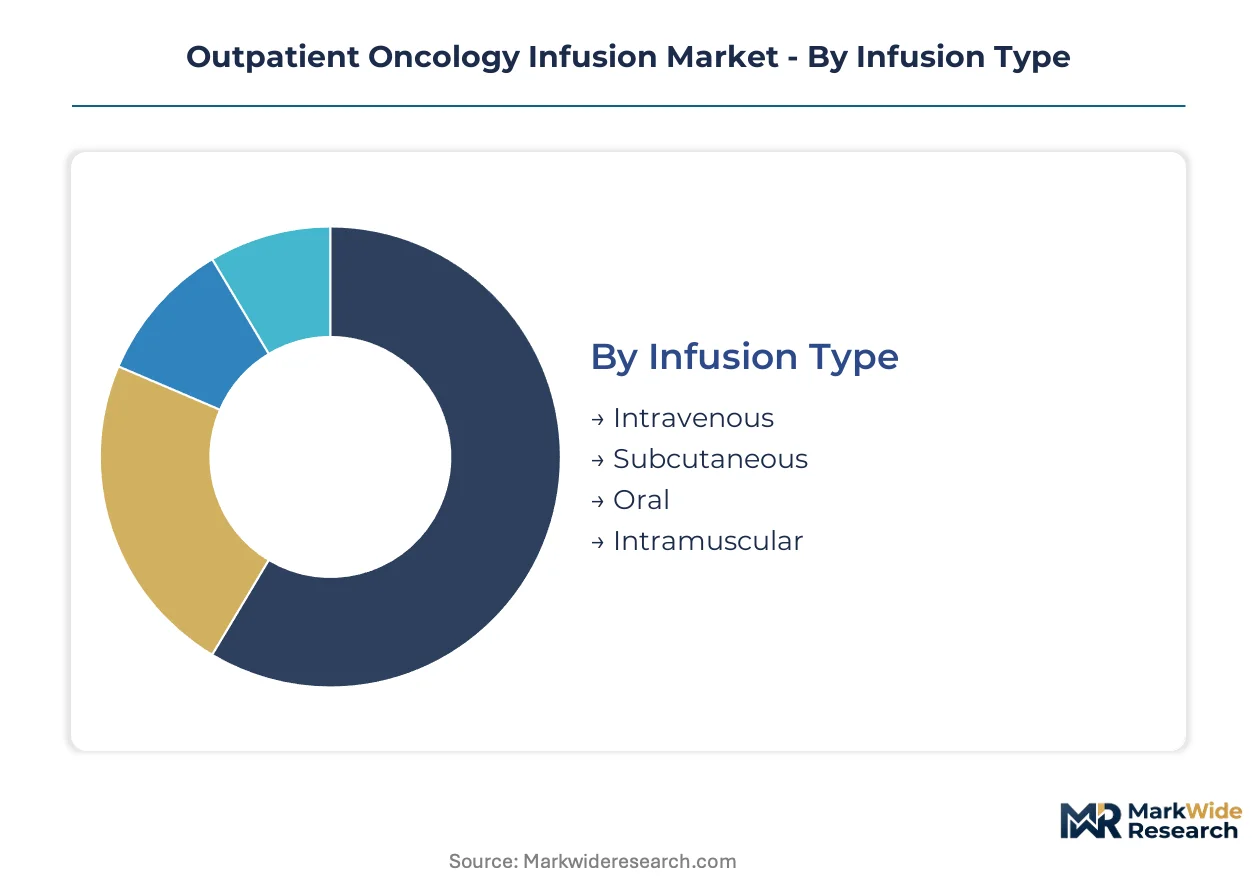
Outpatient oncology infusion markets fragment across delivery modality, malignancy type, and site of care. Each segmentation axis carries distinct capital requirements, reimbursement profiles, and regulatory compliance burdens that reshape competitive positioning.
Infusion Type:
Supply concentration in vascular access devices and ambulatory pump manufacturing clusters around specific delivery modalities, creating procurement leverage for high-volume purchasers.
- Intravenous:Central and peripheral venous access delivers cytotoxic agents, biologics, and supportive therapies through infusion pumps with programmable flow rates. United States cancer centers concentrate demand here as Medicare site-neutral payment compresses hospital margins and drives volume toward freestanding facilities with dedicated pharmacy infrastructure.
- Subcutaneous:Depot-formulation monoclonal antibodies and long-acting supportive therapies bypass vascular access requirements entirely. Homecare settings capture expanding share as extended half-life engineering reduces administration frequency and enables nursing visits outside fixed facilities.
- Oral:Self-administered targeted agents shift monitoring burden to telehealth platforms and retail pharmacy networks.
- Intramuscular:Limited application for hormonal depot injections and select supportive care agents in community clinic settings.
Today's leader: Intravenous. Tomorrow's challenger: Subcutaneous.
Cancer Type:
Protocol complexity and infusion duration vary sharply by malignancy, concentrating specialized capacity investment in high-burden disease categories.
- Breast Cancer:Adjuvant and neoadjuvant chemotherapy regimens, HER2-directed therapy, and CDK4/6 inhibitor combinations create sustained infusion demand. United States community cancer centers build dedicated breast oncology wings to capture recurring patient volumes across multi-year treatment arcs.
- Lung Cancer:Checkpoint inhibitor monotherapy and combination regimens require extended infusion durations with hypersensitivity monitoring. Academic medical centers concentrate Phase I trial capacity here as immunotherapy development pipelines prioritize thoracic malignancies.
- Colorectal Cancer:Oxaliplatin-based FOLFOX protocols and anti-EGFR maintenance therapy sustain outpatient infusion scheduling.
- Lymphoma:Rituximab-based regimens and CAR-T bridging therapy demand specialized nursing for cytokine release syndrome surveillance.
Breast cancer anchors current capacity planning. Lung cancer commands the steepest expansion trajectory.
End User:
Site-of-care economics and USP 800 compliance thresholds fragment end-user segments by capital intensity and payer mix.
- Cancer Centers:Dedicated outpatient facilities with in-house sterile compounding and pharmacy benefit carve-outs capture bundled episode payments. United States regional networks expand these assets to exploit site-neutral reimbursement arbitrage against hospital-based competitors.
- Clinics:Rural health clinic exemptions enable 340B drug pricing access for remote infusion services in underserved counties.
- Hospitals:Declining Medicare margins accelerate divestiture of outpatient infusion to joint venture partners or freestanding operators.
- Homecare:Specialized oncology nursing networks extend immunotherapy administration beyond fixed facility walls.
Cancer centers consolidate margin pools today. Homecare platforms are gaining share fastest.
Drug Type:
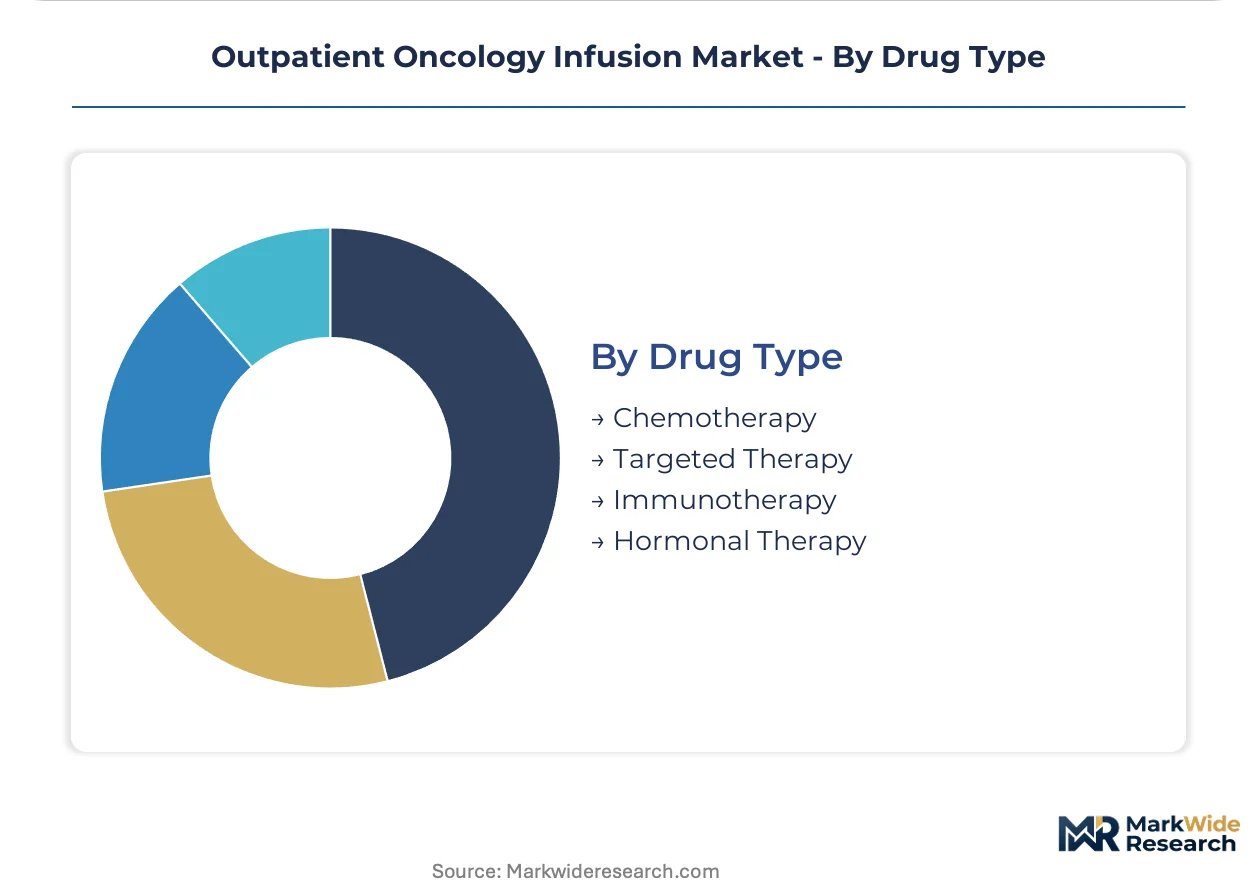
Mechanism of action determines infusion infrastructure requirements, from hazardous drug containment to cold chain and hypersensitivity preparedness.
- Immunotherapy:Checkpoint inhibitors require extended observation periods and rapid-response protocols for immune-related adverse events. United States infusion centers invest in dedicated immunotherapy bays with extended nursing ratios as IRA drug pricing reform expands patient access.
- Chemotherapy:Platinum agents, taxanes, and antimetabolites demand USP 800-compliant negative-pressure engineering and closed-system transfer devices. Supply concentration in Indian and Chinese API manufacturing exposes formulators to geopolitical interruption risk.
- Targeted Therapy:Oral tyrosine kinase inhibitors dominate, with intravenous formulations limited to monoclonal antibody conjugates.
- Hormonal Therapy:LHRH agonist depot injections and aromatase inhibitor support occupy limited infusion chair time.
Immunotherapy commands capital deployment priority. Chemotherapy retains volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Outpatient oncology infusion services originated within United States academic medical centers during the 1980s, where early chemotherapy protocols migrated from inpatient wards to dedicated ambulatory units. This institutional model subsequently diffused to Germany, Japan, and Switzerland as regulatory frameworks for hazardous drug handling matured.
United States
Medicare site-neutral payment policies and IRA drug pricing reform are accelerating capital migration toward freestanding cancer centers with USP <800>-compliant infrastructure. The FDA's Oncology Center of Excellence maintains accelerated approval pathways for infused immunotherapies. Houston's Texas Medical Center and Manhattan's Memorial Sloan Kettering corridor concentrate the nation's highest infusion chair density.
Germany
EMA centralized marketing authorizations for oncology biologics standardize infusion protocols across federal states, while statutory health insurance funds negotiate episode-based reimbursement contracts. The country's national pharmaceutical regulator enforces GMP standards for sterile compounding that exceed baseline EU requirements. Baden-Württemberg's Heidelberg University Hospital network anchors south German outpatient oncology capacity expansion.
Switzerland
Swissmedic's streamlined approval timelines for breakthrough oncology therapies attract Phase III trial concentration from multinational sponsors. Cantonal health insurance systems reimburse infusion services at premium rates that sustain hospital-adjacent outpatient profitability. Basel's Roche headquarters proximity generates specialized nursing workforce pools for monoclonal antibody administration.
Japan
PMDA's sakigake designation system fast-tracks domestic development of infused immuno-oncology agents, while METI promotes medical device innovation in closed-system transfer engineering. Universal health coverage eliminates patient cost barriers to extended-duration checkpoint inhibitor protocols. Tokyo's Kanto region and Osaka's Kansai corridor host the highest density of hospital-affiliated infusion centers.
India
CDSCO's phased implementation of bioequivalence requirements for biosimilar monoclonal antibodies is expanding affordable infusion access through corporate hospital chains. The country's national pharmaceutical regulator harmonizes with ICH guidelines for oncology drug development. Mumbai's Maharashtra cluster and Bengaluru's Karnataka corridor concentrate medical tourism-oriented outpatient chemotherapy capacity.
Outpatient Oncology Infusion Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology integration and hazardous drug containment capabilities. The vendor base stratifies between integrated medication delivery platform specialists and component-focused device manufacturers. Three archetypes dominate: hospital-adjacent service integrators, closed-system engineering specialists, and vascular access device generalists. Competitive moves concentrate on USP <800>-compliant cleanroom partnerships and smart pump interoperability certifications.
Among German-based parenteral therapy specialists, Fresenius Kabi and B. Braun Melsungen AG exemplify the hospital-adjacent service integrator archetype through their combined device and pharmaceutical portfolios. Becton, Dickinson and Company occupies a position within the closed-system engineering tier, representing technology leadership in hazardous drug containment. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across the infusion safety value chain.
| Leading Market Players |
|---|
| Fresenius Kabi |
| IRadimed Corporation |
| Becton, Dickinson and Company |
| Terumo Corporation |
| Teleflex |
| Baxter |
| ICU Medical, Inc |
| Nipro Corporation |
| B. Braun Melsungen AG |
| Others |
Supply Flow & Price Mechanics
Freestanding cancer centers with USP 800-compliant infrastructure command pricing leverage through bundled episode payments that compress hospital margins under Medicare site-neutral reimbursement. Their concentrated procurement volumes extract tiered discounts from closed-system transfer device manufacturers and parenteral drug suppliers.
Pricing Analysis
Episode-based payment contracts for chemotherapy administration separate premium-tier cancer centers with in-house compounding from standard-tier hospital outpatient departments and economy-tier rural clinic exemptions. Price differentiation rests on USP 800 certification grade and pharmacy benefit carve-out depth. Cost compression in hospital-based infusion is intensifying because site-neutral reimbursement erodes legacy cost-shifting advantages. Community cancer centers exhibit lowest price sensitivity due to 340B drug pricing eligibility, while independent physician practices face acute margin pressure.
Supply Chain Analysis
Board-certified oncology pharmacists with sterile hazardous drug credentials remain scarce in United States and German manufacturing geographies relative to facility expansion timelines. Active pharmaceutical ingredient production for platinum-based agents draws from India and China, while closed-system transfer device assembly concentrates in United States and German industrial corridors. Single-source vulnerability in Chinese cisplatin precursor supply exposes formulators to geopolitical interruption. Distribution runs through GPO-negotiated contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Site-of-care arbitrage between United States hospital-based and freestanding infusion settings rewards capital deployment in jurisdictions with favorable 340B eligibility and state pharmacy board licensure efficiency.
For Market Incumbents: Lock in compounding pharmacy workforce pipelines through university partnership programs and board certification sponsorships. Secure backward integration into closed-system transfer device supply through exclusive distribution agreements with BD or Equashield to preempt generic device entrants from capturing share under patent cliff scenarios. For New Entrants and Emerging Players: Enter via rural health clinic exemption pathways in underserved United States counties where CMS 340B pricing creates immediate margin advantage. Home infusion nursing networks for extended-duration immunotherapy represent the most penetrable segment, with go-to-market traction through Medicare Advantage plan direct contracting. For Investors and Strategic Acquirers: Hospital-adjacent service integrators with combined device and pharmaceutical portfolios are the most active acquirers in this space, targeting distressed hospital outpatient infusion assets. Long-term viability hinges on IRA drug pricing reform durability and USP 800 enforcement consistency. Watch FDA accelerated approval withdrawal rates as inflection indicator for immunotherapy pipeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| USP 800 Cleanroom Partnership | Joint ventures with pharmacy design firms accelerate compliant facility deployment in competitive United States markets. |
| Smart Pump Interoperability Certification | EHR integration partnerships with Epic and Cerner reduce nursing documentation burden and error rates. |
| Home Infusion Nursing Network Buildout | Specialized oncology nursing platforms capture immunotherapy volume migrating beyond fixed facility walls. |
| 340B Drug Pricing Optimization | Rural health clinic exemption structuring maximizes pharmaceutical margin capture in underserved counties. |
| Real-World Evidence Collection Partnership | Checkpoint inhibitor developers embed post-market surveillance into infusion center operations for FDA compliance. |
Methodological Framework
Bottom-up cancer center capacity modeling reconciled against top-down infusion device shipment tracking forms the analytical core of this study. Primary interviews with oncology pharmacy directors, infusion nursing managers, GPO contract specialists, and USP 800 compliance consultants combined with secondary validation against FDA 510(k) filings, CMS Medicare cost report data, state pharmacy board licensure databases, and hospital procurement disclosures. Triangulation between demand-side utilization patterns and supply-side manufacturing capacity ensures cross-verified outputs.
Input-output matrices map infusion type, cancer indication, site of care, and drug mechanism dimensions across the projection horizon. CAGRs derive from segmented volume trajectories weighted by reimbursement rate evolution and regulatory compliance cost curves. Forecast inputs incorporate IRA drug pricing implementation pace and USP 800 enforcement variance across state pharmacy boards.
The model holds under stable Medicare site-neutral reimbursement and IRA drug pricing durability; deviation in FDA accelerated approval withdrawal rates or platinum API supply interruptions would shift capacity investment timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and workforce availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Pharyngeal Neoplasm Market
Oncology
Colorectal Cancer Screening Market
Oncology
Global Cancer Supportive Care Drugs Market
Oncology
Tumor Ablation Market
Oncology
Asia Pacific Cancer Immunotherapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
Kinase Inhibitors for Cancer Treatment Market
Oncology
Bone Metastasis Market
Oncology
Global HER-2 Negative Breast Cancer Market
Oncology
Peritoneal Cancer Treatment Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Sterile Oncology Injectable Market
Oncology
Europe Radiotherapy Market
Oncology
Interventional Oncology Ablation Market
Oncology
Europe Tumor Ablation Market
Oncology
Cancer API Market