
 Wrist Fixator Procedure Kit Market | 2026-2036
Wrist Fixator Procedure Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Wrist Fixator Procedure Kit Market Analytics
Outpatient orthopedic clinics is bifurcating demand away from traditional hospital purchasing, as ambulatory settings seek streamlined, single-use kits that reduce sterilization overhead and procedure turnaround time. DePuy Synthes leverages its trauma portfolio breadth to supply integrated fixation systems across multiple care settings. Stryker anchors its position through proprietary pin-to-bar configurations that target complex distal radius fractures. Zimmer Biomet differentiates via modular kit architectures that accommodate both standard and patient-specific anatomical variations.
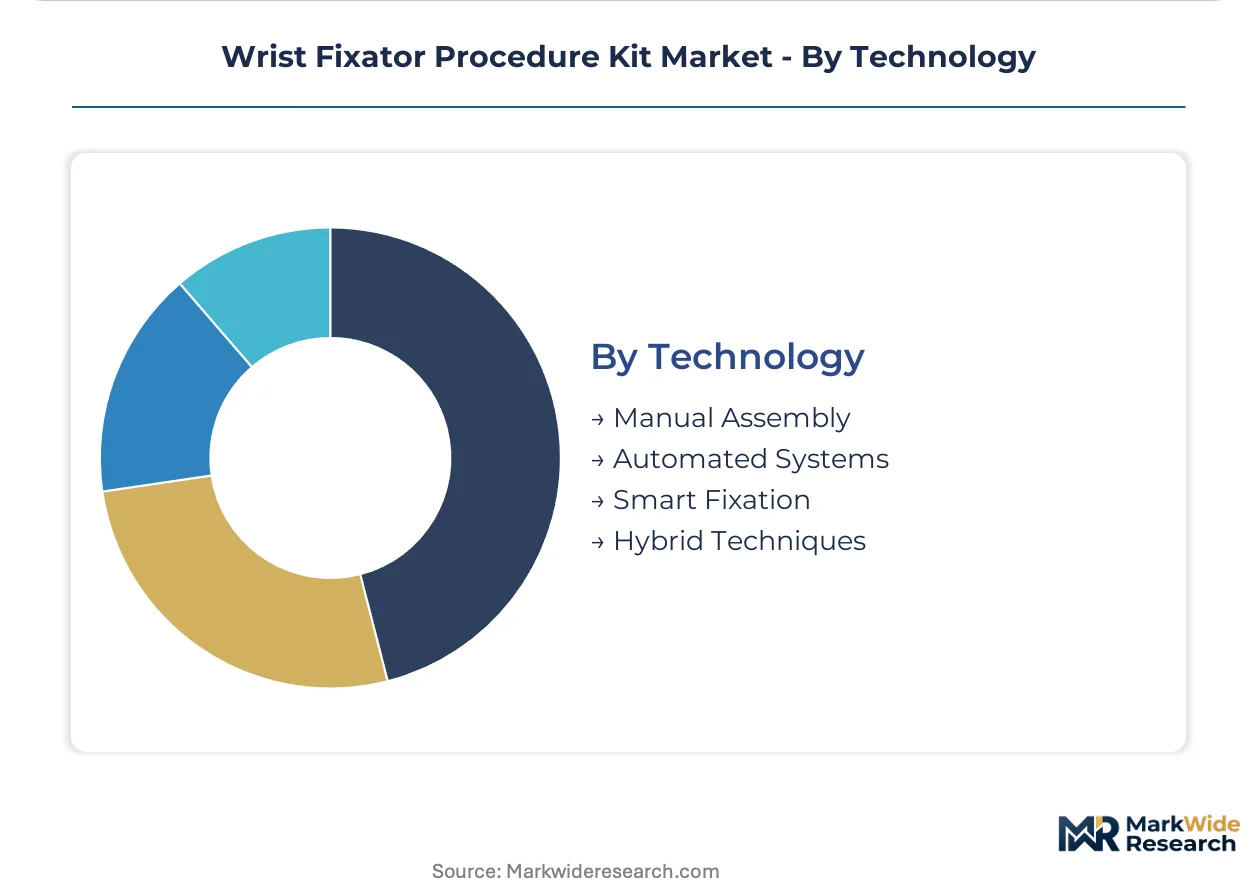
A wrist fixator procedure kit comprises sterilized assemblies of external fixation pins, connecting bars, clamps, and instrumentation required for stabilizing distal radius and carpal fractures without internal implantation. Kits typically specify pin diameters ranging from 1.5 mm to 2.5 mm, construct stiffness measured in Newtons per millimeter, and compatibility with fluoroscopic imaging during intraoperative adjustment. External fixators command the largest revenue pool due to their dominance in polytrauma and open fracture protocols, while smart fixation technology represents the fastest-expanding segment as sensor-enabled constructs permit postoperative monitoring of fracture site micromotion. Manual assembly retains volume leadership in cost-sensitive markets, though hybrid techniques are capturing margin-rich niches where surgeons combine conventional frames with computer-assisted reduction.
FDA 510(k) premarket notification and EU MDR conformity assessment govern kit sterilization validation, biocompatibility testing, and clinical evidence requirements for wrist fixation devices. ISO 13485 quality management standards and ASTM F1541 mechanical testing protocols further constrain design freedom while ensuring construct reliability under cyclic loading. Stakeholders must monitor evolving reimbursement thresholds for outpatient fixation procedures and anticipate how FDA breakthrough device designation criteria might accelerate smart fixation platform approvals.
Market Dynamics
Outpatient migration is compressing hospital purchasing power while elevating kit standardization requirements across ambulatory surgery centers and orthopedic clinics. This structural shift forces manufacturers to redesign packaging, sterilization protocols, and instrumentation density for settings lacking central sterile processing departments.
Growth Catalysts
- EU MDR transition:Harmonized conformity assessment procedures accelerate cross-border kit distribution among European orthopedic networks, reducing redundant testing burdens for manufacturers with notified body partnerships.
- Distal radius fracture volume:Aging demographics in Germany, the United States, and China sustain procedural demand requiring external fixation as first-line stabilization for osteoporotic bone.
- Smart sensor integration:Load-cell and strain-gauge embedded constructs enable remote monitoring of fracture site micromotion, expanding reimbursable postoperative care pathways.
Market Restraints
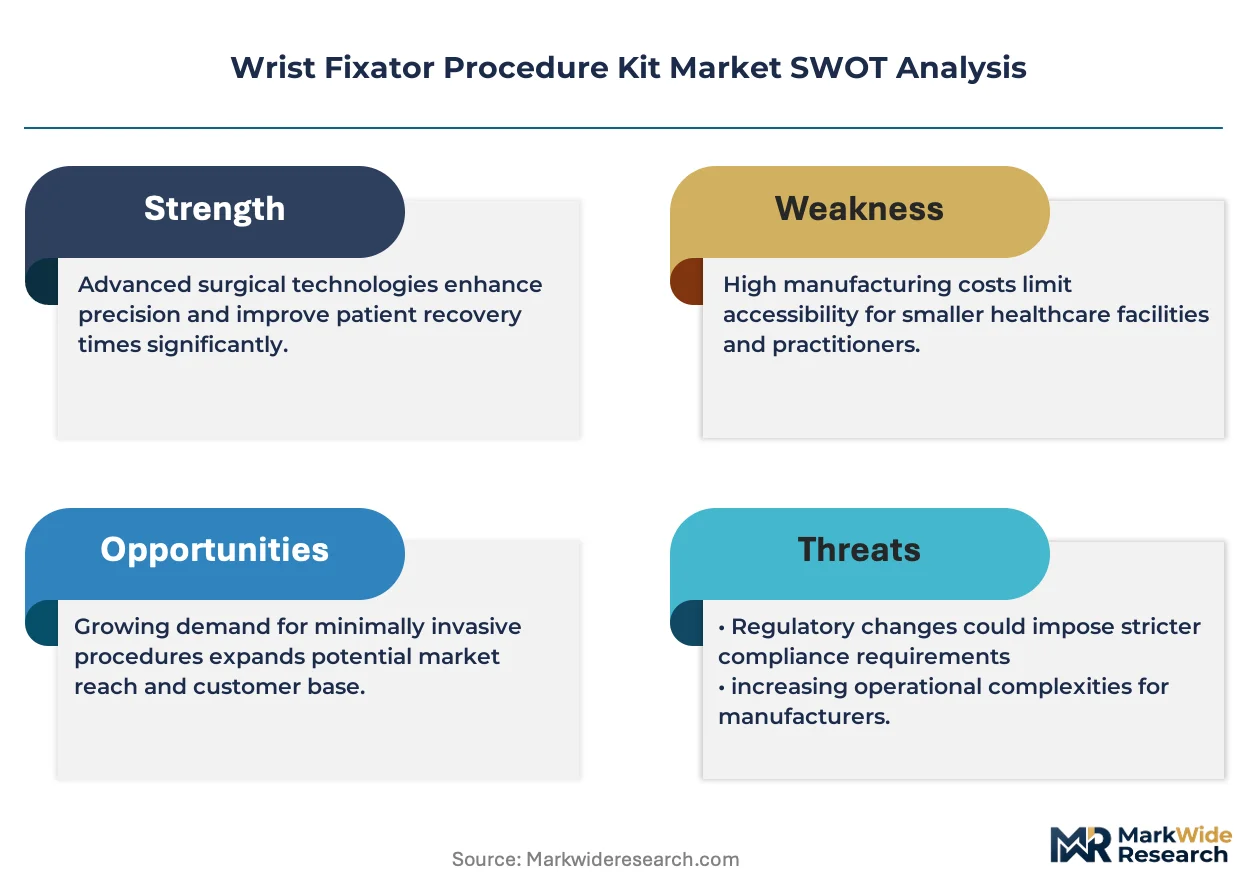
- Titanium alloy cost volatility:Pin and bar raw material price swings compress gross margins for kit assemblers without long-term supply agreements.
- Supply concentration in precision machining:German and Swiss contract manufacturers dominate high-tolerance clamp production, creating single-source vulnerability.
- Reimbursement compression:CMS and private payers narrow outpatient procedure fee schedules, forcing kit economics toward lower instrumentation counts per case.
Strategic Opportunities
- India trauma infrastructure:Government hospital upgrading programs create first-mover advantage for kit suppliers establishing sterilization partnerships with state medical supply corporations.
- FDA breakthrough device pathway:Sensor-enabled smart fixators qualify for expedited review, compressing time-to-market for postoperative monitoring platforms.
- Direct-to-ambulatory distribution:Bypassing traditional hospital purchasing consortia through specialized orthopedic distributor networks captures margin in high-volume outpatient settings.
Industry Challenges
- EU MDR technical documentation:Clinical evidence requirements for legacy kit configurations demand retrospective data aggregation that delays certificate renewal.
- Surgeon training standardization:Variable residency exposure to external fixation techniques creates adoption friction for advanced hybrid constructs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wrist Fixator Procedure Kit Market |
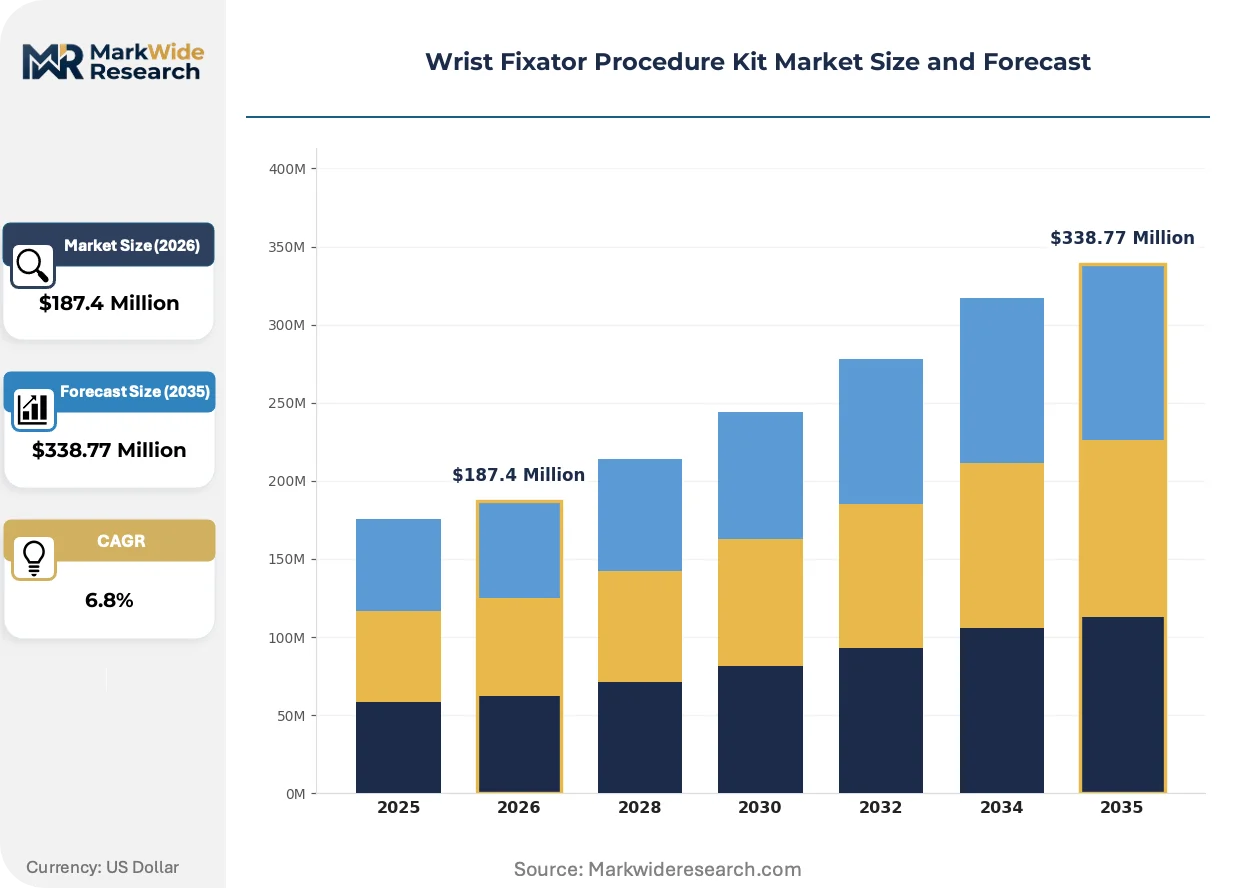
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Fixators, Splints, Implants, Accessories End User: Hospitals, Surgical Centers, Rehabilitation Facilities, Orthopedic Clinics Application: Trauma Surgery, Orthopedic Surgery, Emergency Care, Sports Medicine Technology: Manual Assembly, Automated Systems, Smart Fixation, Hybrid Techniques |
| Companies Covered | Acumed, Citieffe s.r.l., DePuy Synthes, Stryker, Zimmer Biomet, Smith & Nephew, Orthofix, Aike (Shanghai) Medical Instrument Co., Ltd., DJO Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wrist Fixator Procedure Kit Market Evolving Landscape
Modular kit architectures are displacing fixed-configuration systems as surgeons demand intraoperative flexibility for complex fracture patterns. Three converging developments are redefining product development priorities and competitive differentiation.
Carbon fiber composite connecting bars are decomposing the historical dominance of stainless steel and titanium in frame construction. Academic medical centers in the United States and Germany now specify radiolucent materials to eliminate fluoroscopic shadowing during reduction maneuvers. This material transition is compressing metal bar volume while elevating composite sourcing requirements for kit assemblers.
EU MDR Article 10 clinical evaluation mandates are extending kit sterilization validation timelines by requiring biological safety documentation beyond prior directive thresholds. Manufacturers must now commission post-market clinical follow-up studies for predicate devices used in 510(k) equivalency arguments. Small-to-mid tier suppliers without dedicated regulatory affairs teams face capital constraints that favor consolidation with notified body-integrated competitors.
Subscription-based kit replenishment contracts are replacing transactional purchasing in United States ambulatory surgery center networks. These arrangements bundle single-use instrumentation with predictive case volume analytics, displacing capital-intensive sterilization equipment investments. The model concentrates procurement authority with multi-site orthopedic management organizations rather than individual surgeon preference.
Wrist Fixator Procedure Kit Market Segmentation
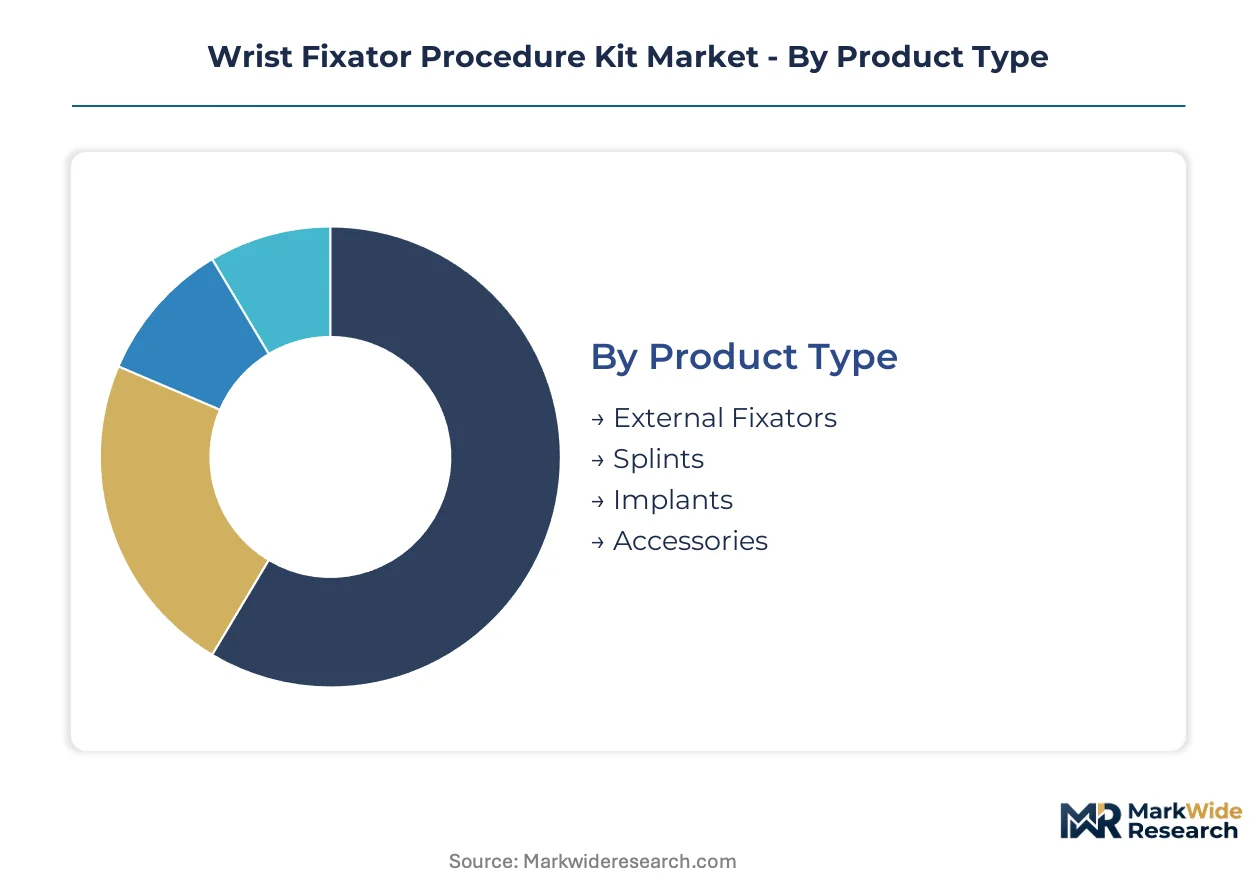
Wrist fixator procedure kits serve divergent clinical workflows across trauma bays, ambulatory surgery centers, and rehabilitation settings. Segmentation reveals how kit configuration, sterilization protocols, and instrumentation density must adapt to each channel's throughput requirements and regulatory constraints.
Product Type:
External fixators flow primarily through hospital trauma centers and surgical centers managing polytrauma, while splints and accessories concentrate in orthopedic clinics with limited sterile processing capacity.
- External Fixators:These kits contain carbon fiber or titanium connecting bars, pin clamps, and sterilized instrumentation for stabilizing distal radius and carpal fractures without internal implantation. Demand concentrates in United States and German trauma centers where fluoroscopic-guided reduction protocols require radiolucent frame materials. CMS reimbursement thresholds for outpatient fixation procedures constrain kit economics toward standardized instrumentation counts.
- Smart Fixation:Sensor-enabled constructs with embedded load-cells and strain-gauges permit remote monitoring of fracture site micromotion through postoperative care pathways. Academic medical centers in Germany and China are piloting these platforms for osteoporotic fracture management where healing complications drive readmission costs.
- Splints:Prefabricated and custom-molded immobilization devices for non-operative fracture management and post-fixator transition.
- Implants:Internal fixation hardware including plates and screws for definitive stabilization following initial external fixation.
- Accessories:Supplementary components including pin site care kits, dressing materials, and patient education resources.
By volume, external fixators lead hospital purchasing. By growth pace, smart fixation is expanding most quickly.
End User:
Cost tier stratification separates capital-intensive hospital procurement from lean ambulatory models, with reimbursement compression driving divergence in kit standardization requirements.
- Hospitals:Level I trauma centers and academic medical centers manage complex polytrauma with high-instrumentation kits requiring central sterile processing departments. FDA 510(k) clearance pathways govern sterilization validation for these high-throughput settings.
- Orthopedic Clinics:Outpatient settings demand single-use, pre-sterilized kits that eliminate sterilization overhead and reduce procedure turnaround time. These clinics in the United States are migrating toward subscription-based replenishment contracts that bundle instrumentation with predictive case volume analytics.
- Surgical Centers:Ambulatory surgery centers balance cost containment with clinical capability for distal radius fracture stabilization.
- Rehabilitation Facilities:Post-acute settings focus on splint management and fixator removal protocols rather than initial stabilization procedures.
Hospitals retain the highest absolute kit consumption. Orthopedic clinics are gaining share fastest as outpatient migration accelerates.
Application:
Volume concentration in trauma surgery creates procurement scale, while sports medicine applications generate premium pricing for athlete-specific recovery timelines.
- Trauma Surgery:Emergency stabilization of distal radius fractures in polytrauma patients requires rapid-deployment external fixator kits with standardized pin configurations. Aging demographics in the United States, Germany, and China sustain procedural demand for osteoporotic bone management.
- Sports Medicine:Athlete-specific fixation protocols prioritize early mobilization and radiolucent materials to enable accelerated return-to-play timelines.
- Orthopedic Surgery:Elective procedures for complex fracture patterns and revision fixation.
- Emergency Care:Initial stabilization in emergency departments prior to definitive surgical management.
Trauma surgery dominates procedure volume. Sports medicine commands the steepest expansion trajectory as professional athletic programs invest in specialized fixation protocols.
Technology:
Maturity gradients separate established manual techniques from emerging automated and sensor-integrated platforms, with hybrid approaches capturing margin-rich niches.
- Manual Assembly:Conventional pin-to-bar frame construction retains volume leadership in cost-sensitive markets and resource-constrained settings. EU MDR technical documentation requirements for legacy kit configurations demand retrospective clinical data aggregation that delays certificate renewal for smaller manufacturers.
- Hybrid Techniques:Combinations of conventional external frames with computer-assisted reduction and intraoperative navigation target complex intra-articular fractures. German and Swiss academic centers are standardizing these protocols for distal radius reconstruction.
- Automated Systems:Mechanized pin insertion and frame assembly devices for standardized fracture patterns.
- Smart Fixation:Fully integrated sensor platforms with wireless data transmission for remote postoperative monitoring.
Manual assembly leads by installed base. Hybrid techniques are climbing the fastest as surgeon training programs expand computer-assisted reduction curricula.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision component manufacturers supply high-tolerance clamps to trauma centers across the United States and China, creating a critical trade-flow corridor that shapes kit standardization requirements in destination markets.
United States
CMS reimbursement compression and ASC network expansion drive demand for single-use, pre-sterilized kits that eliminate central sterile processing overhead. FDA 510(k) clearance pathways govern sterilization validation timelines for outpatient fixation platforms. Academic medical centers in Boston and Philadelphia pilot smart sensor constructs for osteoporotic fracture monitoring.
Germany
Aging demographics and high-volume distal radius procedures sustain demand for radiolucent carbon fiber frame systems. EU MDR Article 10 clinical evaluation mandates extend certificate renewal timelines for legacy kit configurations. The Baden-Württemberg precision machining cluster dominates high-tolerance clamp production for European orthopedic networks.
China
Government hospital upgrading programs and trauma infrastructure investment accelerate kit adoption in provincial medical centers. NMPA registration requirements align with international sterilization validation standards for imported components. The Yangtze River Delta manufacturing base expands domestic production capacity for external fixation pins and connecting bars.
India
State medical supply corporation sterilization partnerships create procurement scale for trauma kit distribution in government hospital networks. CDSCO medical device rules govern import registration for foreign-manufactured fixation components. Maharashtra and Karnataka host emerging orthopedic distributor networks targeting ambulatory clinic expansion.
Switzerland
Swissmedic certification requirements and precision engineering heritage sustain premium positioning for high-tolerance fixation instrumentation. Academic medical centers in Zurich and Geneva standardize hybrid computer-assisted reduction protocols for complex intra-articular fractures. The Basel region hosts contract manufacturers supplying clamp subassemblies to German kit assemblers.
Wrist Fixator Procedure Kit Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with trauma portfolio breadth, creating tiered competition between integrated system suppliers and specialized fixation component manufacturers. Three archetypes dominate: multinational device conglomerates with cross-portfolio synergies, regional precision machining specialists supplying high-tolerance subassemblies, and emerging smart fixation platform developers targeting postoperative monitoring niches. Competitive moves concentrate on M&A for regulatory capabilities and strategic partnerships with ambulatory surgery center networks.
Among diversified orthopedic conglomerates, DePuy Synthes, Stryker, and Zimmer Biomet occupy positions that exemplify the integrated system supplier archetype. These companies anchor competitive dynamics through portfolio breadth that spans multiple fixation modalities and care settings. Their scale enables simultaneous compliance with FDA 510(k) and EU MDR requirements while maintaining distribution infrastructure across hospital and ambulatory channels.
| Leading Market Players |
|---|
| Acumed |
| Citieffe s.r.l. |
| DePuy Synthes |
| Stryker |
| Zimmer Biomet |
| Smith & Nephew |
| Orthofix |
| Aike (Shanghai) Medical Instrument Co., Ltd. |
| DJO Global |
| Others |
Value Network & Pricing Analysis
Sixty-day sterilization validation timelines for EU MDR certification compress inventory turns for kit assemblers while elevating pricing power for German and Swiss contract manufacturers with notified body partnerships. This lead-time concentration forces ambulatory buyers into premium positioning for pre-validated single-use configurations.
Pricing Analysis
The technology-generation pricing gap separates legacy manual fixator kits from sensor-enabled smart constructs and emerging hybrid navigation platforms. Three-tier pricing structure across premium smart fixation, standard carbon fiber external fixators, and economy stainless steel configurations dominates procurement. Price differentiation stems from EU MDR certification tier and fluoroscopic compatibility grade. Pricing pressure stems from CMS reimbursement compression on outpatient procedures, forcing kit economics toward reduced instrumentation counts. Orthopedic clinics exhibit highest price sensitivity due to subscription contract economics, while academic trauma centers prioritize radiolucent performance over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor high-tolerance clamp production for European and North American orthopedic networks. The Yangtze River Delta in China feeds carbon fiber bar and titanium pin fabrication. Kit assembly draws from precision-machined subcomponents, sterilized single-use instrumentation, and radiolucent composite materials. Single-source vulnerability concentrates in Baden-Württemberg contract manufacturers supplying clamp subassemblies. Distribution runs through specialized orthopedic distributor networks targeting ambulatory surgery center consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as outpatient migration from hospital trauma bays to orthopedic clinics accelerates kit standardization demand.
For Market Incumbents: Fortify regulatory affairs capabilities to navigate EU MDR Article 10 clinical evaluation mandates for legacy kit configurations. Deepen backward integration into carbon fiber composite sourcing to offset titanium alloy cost volatility. Prioritize sterilization partnerships with multi-site orthopedic management organizations to lock subscription replenishment contracts. For New Entrants and Emerging Players: Lead with smart fixation platforms targeting academic medical centers in Germany and China piloting remote fracture monitoring. Target state medical supply corporation partnerships in India where government hospital upgrading programs create procurement scale. Position through direct-to-ambulatory distribution bypassing traditional hospital purchasing consortia. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EU MDR technical documentation requirements favor notified body-integrated acquirers over capital-constrained mid-tier suppliers. Target precision machining specialists with Swissmedic or German notified body relationships. Watch FDA breakthrough device designation awards as inflection signal for smart fixation platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Accelerates cross-border kit distribution through harmonized conformity assessment procedures. |
| Smart Sensor Platform Development | Qualifies for FDA breakthrough device pathway and expands reimbursable postoperative monitoring. |
| Ambulatory Surgery Center Partnership | Captures margin in high-volume outpatient settings migrating from hospital purchasing. |
| Carbon Fiber Composite Integration | Eliminates fluoroscopic shadowing for academic centers standardizing reduction protocols. |
| Subscription Replenishment Contracts | Displaces capital-intensive sterilization investments in United States orthopedic clinic networks. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body certificates, hospital procurement databases, and CMS reimbursement schedules. Bottom-up kit volume estimates triangulated against top-down trauma procedure incidence data.
Across the analysis window, the forecasting framework modeled product type segmentation by technology maturity, end-user channel cost tier, and application workflow intensity. CAGRs derived from procedure volume elasticity to aging demographics and ambulatory migration velocity. Smart fixation adoption curves incorporated academic medical center pilot expansion timelines.
Forecasts assume regulatory continuity in FDA 510(k) clearance pathways and EU MDR conformity assessment; material policy shifts would require re-modeling. Specific risks include titanium alloy price volatility, reimbursement compression acceleration, and supply concentration disruption in German precision machining. Recalibration cycles align with material shifts in outpatient migration velocity and smart fixation platform clinical evidence accumulation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
North America Ultrasound Devices Market
Medical Devices
Global Wheelchair Market
Medical Devices
Global Pelvic Floor Electric Stimulator Market
Medical Devices
Global Blood Processing Devices and Consumables Market
Medical Devices
Asia-Pacific Ostomy Care and Accessories Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Nasal Irrigation Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Global Stent Graft Balloon Catheter Market
Medical Devices
Global Bioabsorbable Stents Market
Medical Devices
Oxygen Generator Market
Medical Devices
Portable Ultrasound Devices Market
Medical Devices
Spinal Trauma Devices Market
Medical Devices
Body Contouring Devices and Procedures Market