
 Medical Device Trays Market | 2026-2036
Medical Device Trays Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Trays Market Outlook
EU MDR is rebalancing the cost-of-entry calculus for tray manufacturers serving European hospitals, forcing substantial investments in biocompatibility documentation and post-market surveillance infrastructure. Medtronic leverages its vertically integrated sterilization services to absorb these compliance costs internally. Stryker Corporation anchors its tray portfolio through dedicated R&D centers focused on automated assembly compatibility. Mölnlycke Health Care differentiates via proprietary polymer formulations that exceed MDR migration-test thresholds.
Medical device trays are rigid or semi-rigid containment systems, typically fabricated from medical-grade polymers such as polyethylene terephthalate glycol or anodized aluminum, engineered to organize, protect, and present instruments during surgical, diagnostic, or sterilization workflows. Their primary commercial purpose centers on reducing perioperative setup time, preventing instrument damage, and maintaining sterility integrity through validated sealing mechanisms. Surgical trays currently dominate volume due to procedure-volume correlation, while sterilization trays command premium positioning as hospitals migrate toward pre-validated, ready-to-use formats that compress central processing department throughput. Composite materials represent the fastest-expanding material category, displacing conventional plastics in laparoscopic and robotic surgery applications where thermal resistance and dimensional stability under autoclave cycling prove critical.
FDA 21 CFR Part 820 quality system regulations, ISO 11607 packaging standards, and EU MDR Annex I general safety requirements collectively dictate tray design specifications, sterilization validation protocols, and clinical evidence thresholds for market access. These frameworks intensify demand for pre-validated tray systems that shift liability burden from hospitals to original equipment manufacturers. Stakeholders must monitor evolving EPA scrutiny of ethylene oxide sterilization residues, as this chemistry underpins the majority of tray sterilization cycles and any restriction would force rapid process revalidation across the supply base.
Market Dynamics
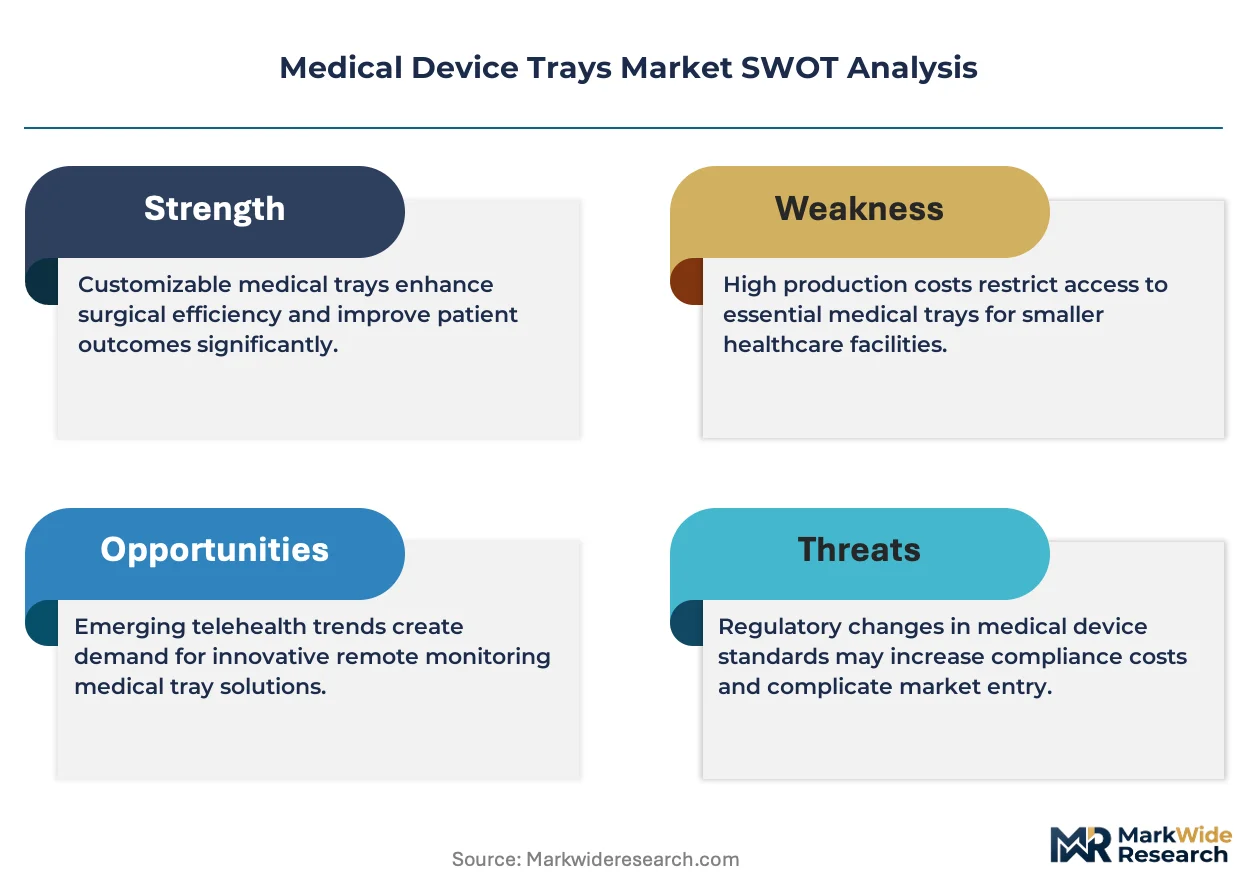
Hospital consolidation is compressing vendor bases and forcing tray manufacturers to absorb sterilization validation costs previously borne by healthcare facilities, fundamentally restructuring pricing power and liability allocation across the supply chain.
Growth Catalysts
- Ambulatory surgical center expansion:Outpatient procedure volume is pulling tray consumption into non-hospital settings, creating dedicated product lines for lower-throughput sterilization workflows.
- FDA 21 CFR Part 820 enforcement:Quality system regulations are accelerating hospital preference for pre-validated tray systems that transfer compliance burden to original equipment manufacturers.
- Composite material thermal performance:Advanced polymer formulations are penetrating laparoscopic and robotic surgery applications where autoclave cycling resistance proves decisive.
Market Restraints
- Ethylene oxide regulatory exposure:EPA scrutiny of sterilization residues threatens process revalidation costs across the majority of tray sterilization cycles.
- EU MDR documentation burden:Biocompatibility testing and post-market surveillance requirements are elevating cost-of-entry for European market access.
- Medical-grade polymer supply concentration:PETG and specialty resin feedstocks face pricing volatility tied to petrochemical input fluctuations.
Strategic Opportunities
- Ready-to-use sterilization formats:Pre-validated tray systems are capturing central processing department outsourcing demand in United States hospital networks.
- Automated assembly compatibility:Robotic surgery instrument sets require tray geometries optimized for machine handling, opening dedicated R&D investment lanes.
- Indian hospital infrastructure buildout:Greenfield medical device manufacturing zones under PLI scheme are creating localized tray demand from domestic device producers.
Industry Challenges
- Sterilization process engineering talent:Ethylene oxide alternative validation and radiation sterilization transition require scarce specialized expertise.
- Legacy central processing department integration:Pre-validated tray adoption confronts established hospital workflows and capital equipment amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Trays Market |
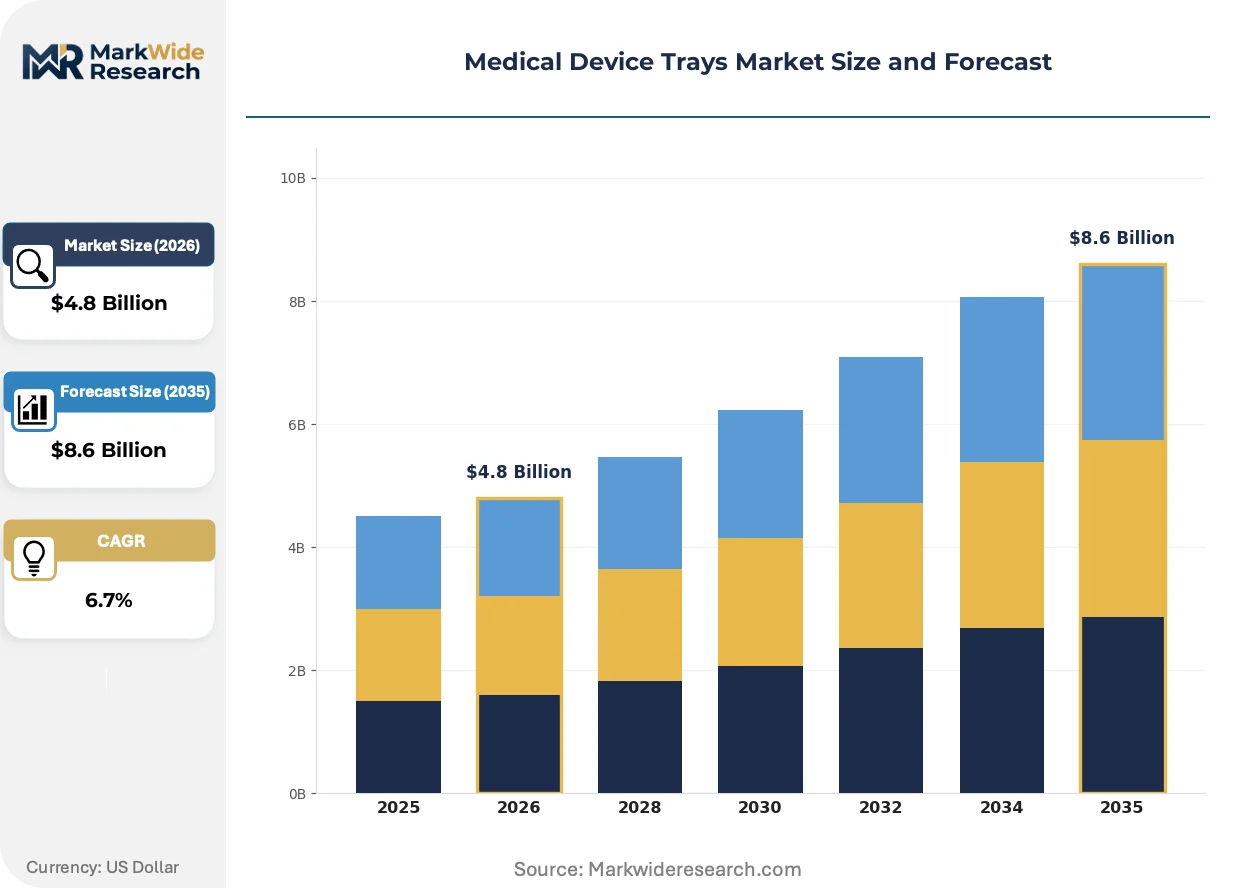
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Trays, Diagnostic Trays, Sterilization Trays, Storage Trays Material Type: Plastic, Metal, Aluminum, Composite End User: Hospitals, Clinics, Research Labs, Nursing Homes Manufacturing Stage: Custom-Molded, Standardized, Automated, Manual |
| Companies Covered | Medtronic, Becton, Dickinson and Company (BD), Stryker Corporation, Johnson & Johnson, Cardinal Health, Steris Corporation, Getinge Group, Mölnlycke Health Care, 3M Health Care, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Trays Market Strategic Shifts
Material science breakthroughs and regulatory validation protocols are converging to redefine tray performance standards, with thermal stability and migration-test compliance emerging as the primary axes of product differentiation.
Composite polymer formulations incorporating ceramic fillers and high-performance thermoplastics are decentralizing tray manufacturing away from conventional PETG and aluminum dominance. Robotic surgery centers and advanced laparoscopic suites are adopting these materials at accelerated pace to withstand repeated autoclave exposure without dimensional degradation. This thermal performance leap is decentralizing competitive advantage toward compounders with proprietary formulation capabilities rather than conventional converters.
EU MDR Annex I general safety requirements are tightening migration-test thresholds for polymer contact with surgical instruments. Manufacturers serving European hospitals must now document biocompatibility across extended material contact scenarios, compressing time-to-market for new tray geometries. Sterilization tray categories face the steepest compliance burden, as these products undergo the most aggressive thermal cycling and chemical exposure profiles.
Hospital procurement departments are consolidating vendor panels and demanding outcome guarantees on sterility maintenance. Group purchasing organizations are displacing individual hospital contracting for tray systems, bundling sterilization validation services into multi-year supply agreements. This concentration is most visible in United States health systems where consolidation has reduced independent purchasing authority at individual facility levels.
Medical Device Trays Market Segmentation
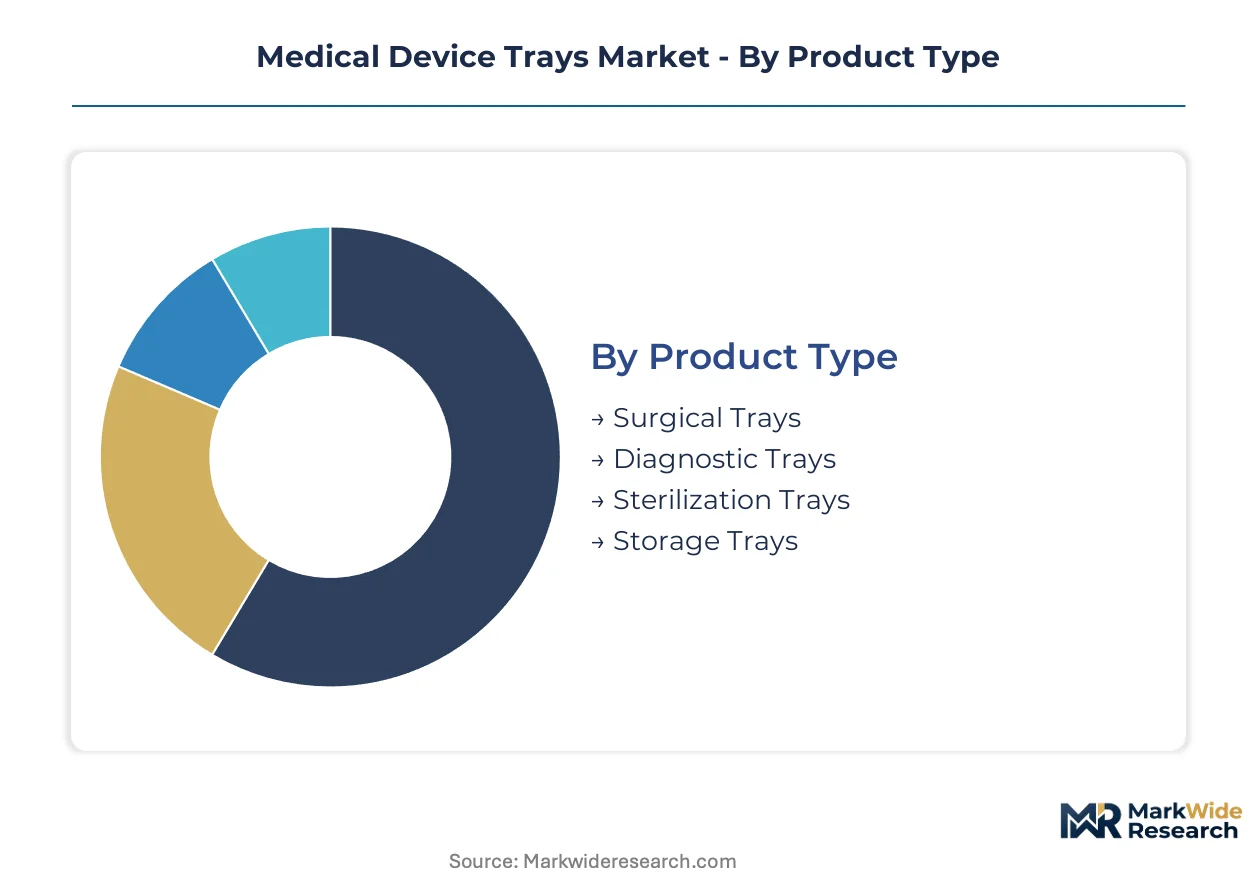
Tray specification varies sharply by clinical workflow intensity and sterilization protocol requirements. Manufacturers configure material formulations and sealing mechanisms around specific procedure types rather than offering universal platforms.
Product Type:
Hospital procurement teams prioritize tray durability against their central processing department throughput targets and instrument replacement budgets.
- Surgical Trays:Rigid containment systems engineered for immediate instrument access during operative procedures, typically fabricated from anodized aluminum or high-impact polymers. Demand concentrates in United States ambulatory surgical centers where turnover time directly affects revenue per operating room.
- Sterilization Trays:Validated barrier systems with integrated lid-sealing mechanisms designed for ethylene oxide or steam autoclave cycles. United States hospital networks migrating to pre-validated formats absorb these at premium positioning to compress central processing department liability.
- Diagnostic Trays:Lightweight polymer formats organizing instruments for non-surgical examination workflows.
- Storage Trays:Semi-rigid containment for long-term instrument housing between procedures.
Volume sits with Surgical Trays; growth tilts toward Sterilization Trays.
Material Type:
Material selection tracks thermal cycling frequency and regulatory migration-test thresholds rather than unit cost alone.
- Composite:Ceramic-filled polymer matrices delivering dimensional stability through repeated autoclave exposure above 134°C. Robotic surgery centers in Germany and United States adopt these formulations where instrument precision tolerances demand zero thermal deformation.
- Plastic:Medical-grade PETG and polyethylene variants dominate high-volume disposable applications. Pricing volatility in petrochemical feedstocks compresses converter margins, particularly for converters without backward integration into resin supply.
- Metal:Stainless steel and anodized aluminum formats for heavy instrument sets.
- Aluminum:Lightweight metallic options for transport-intensive workflows.
Plastic commands current volume; Composite gains share fastest on thermal performance differentiation.
End User:
Facility type dictates sterilization infrastructure investment and tray validation burden allocation.
- Hospitals:Integrated health systems with captive central processing departments or outsourced sterilization partnerships. United States consolidation trends force standardized tray specifications across multi-facility networks, privileging vendors with validated quality management systems under FDA 21 CFR Part 820.
- Clinics:Outpatient settings with limited autoclave capacity favoring pre-sterilized, single-use formats. Demand clusters in ophthalmology and dermatology practices where procedure volume supports disposable economics.
- Research Labs:Non-clinical settings with flexible validation requirements.
- Nursing Homes:Long-term care facilities with minimal surgical instrument processing needs.
Hospitals anchor procurement volume; Clinics present the steepest expansion trajectory on ambulatory migration.
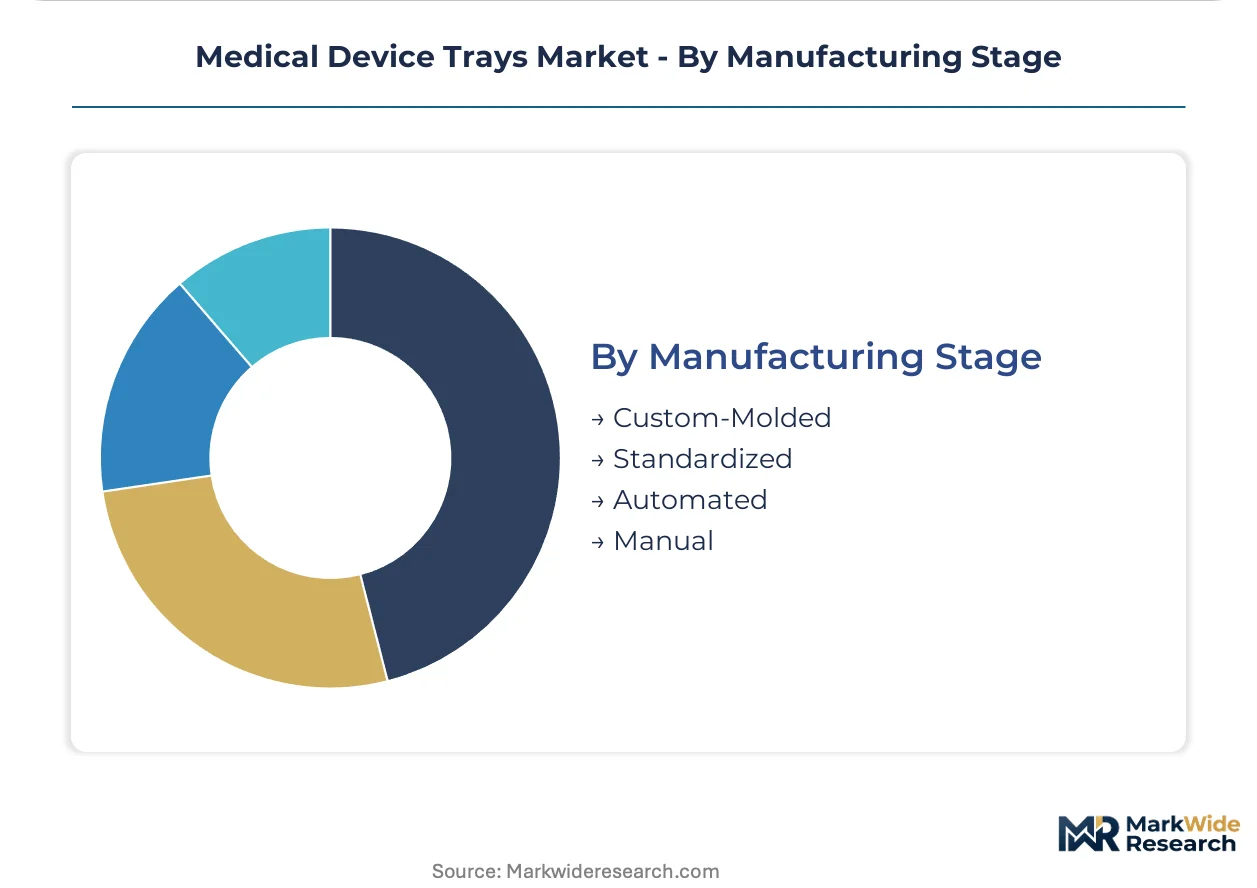
Manufacturing Stage:
Production methodology determines scalability against customization requirements and regulatory documentation depth.
- Automated:Robotic assembly lines producing standardized geometries with validated process controls for FDA submission packages. Stryker Corporation and Medtronic deploy these configurations for high-volume surgical tray families where lot-to-lot consistency proves critical.
- Custom-Molded:Tooling-intensive production for proprietary instrument sets requiring dimensional matching to specific device geometries. EU MDR documentation burdens favor manufacturers with established biocompatibility testing protocols for novel polymer contact scenarios.
- Standardized:Catalog formats with minimal configuration variation.
- Manual:Labor-intensive assembly for low-volume specialty applications.
Automated output dominates unit economics; Custom-Molded captures margin concentration on proprietary instrument integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for medical device manufacturing is accelerating tray demand from domestic producers establishing operations in greenfield zones near Delhi-NCR and Gujarat.
United States
Ambulatory surgical center expansion in Florida and Texas is pulling tray consumption into outpatient settings. FDA 21 CFR Part 820 enforcement compresses vendor panels, privileging manufacturers with validated quality management systems. Minneapolis-St. Paul anchors sterilization services concentration where vertically integrated device producers absorb compliance costs internally.
Germany
Robotic surgery centers in Bavaria and Baden-Württemberg adopt composite polymer trays for thermal cycling resistance above 134°C. EU MDR Annex I migration-test thresholds force biocompatibility documentation investments. Tuttlingen's surgical instrument cluster generates specialized tray demand for precision instrument sets exported across Europe.
China
Domestic device manufacturers in Jiangsu and Zhejiang provinces scale tray procurement as NMPA registration requirements tighten. Dual carbon goals push hospitals toward reusable sterilization formats. Suzhou's medical device manufacturing zone concentrates tray converters serving both domestic and export markets.
India
Greenfield hospital infrastructure in Maharashtra and Karnataka creates localized tray demand from domestic device producers. CDSCO medical device rules align with global harmonization initiatives, elevating documentation standards. Andhra Pradesh's medical device manufacturing zones under PLI scheme attract tray suppliers co-locating with instrument producers.
Japan
Aging demographics expand surgical procedure volume in Tokyo and Osaka metropolitan areas. PMDA QMS ordinances enforce process validation requirements comparable to FDA standards. Chubu region's precision manufacturing base supplies high-tolerance trays for minimally invasive surgery instrument sets.
Medical Device Trays Market Competitive Environment
United States producers anchor one tier; European specialists hold differentiated positions on regulatory compliance depth. The vendor base stratifies across three tiers: diversified medical device conglomerates with captive tray operations, dedicated sterilization packaging specialists, and regional converters serving single-use disposable segments. Consolidation pressure intensifies as hospital group purchasing organizations displace individual facility contracting. Two dominant competitive moves define current positioning: backward integration into polymer compounding capabilities, and strategic partnerships with robotic surgery platform developers for instrument-set-specific geometries.
Among diversified conglomerates, Medtronic, Stryker Corporation, and Mölnlycke Health Care exemplify distinct archetypes. Medtronic represents vertically integrated sterilization services absorption of regulatory compliance costs. Stryker Corporation anchors automated assembly compatibility investments for robotic surgery workflows. Mölnlycke Health Care occupies a position defined by proprietary polymer formulation capabilities exceeding EU MDR migration-test thresholds. These three entities collectively illustrate how competitive advantage decentralizes toward compounders with validated biocompatibility protocols rather than conventional converters dependent on commodity resin supply.
| Leading Market Players |
|---|
| Medtronic |
| Becton, Dickinson and Company (BD) |
| Stryker Corporation |
| Johnson & Johnson |
| Cardinal Health |
| Steris Corporation |
| Getinge Group |
| Mölnlycke Health Care |
| 3M Health Care |
| Others |
Value Chain & Pricing Dynamics
Automated assembly line deployment across tray manufacturing compresses unit economics while concentrating production among capital-intensive operators capable of validated process controls under FDA 21 CFR Part 820. This technological transition simultaneously elevates entry barriers for regional converters and transfers pricing power toward integrated sterilization service providers.
Pricing Analysis
Short lead-time premiums apply to pre-validated sterilization trays required for emergency surgical instrument sets, while spot inventory of standard PETG formats trades at discounts. Contract-based long-term offtake dominates hospital procurement through group purchasing organizations, with price differentiation driven by ISO 11607 certification tier and customization level for robotic surgery compatibility. Pricing pressure stems from hospital consolidation forcing standardized specifications across multi-facility networks. Ambulatory surgical centers exhibit highest price sensitivity due to disposable economics; integrated health systems with captive central processing departments show lowest sensitivity on validated barrier systems.
Supply Chain Analysis
Single-source vulnerability sits with medical-grade PETG resin production concentrated in the United States, Germany, and China. Raw material dependencies center on petrochemical feedstocks, specialty ceramic fillers for composite formulations, and anodized aluminum sheet. Supply chain risk manifests as tariff exposure on polymer imports from Asia-Pacific manufacturing zones. Distribution runs through medical device distributors and direct hospital contracts, with sterilization validation services increasingly bundled into multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in medical device trays is becoming a vertical-integration race, with backward integration into polymer compounding capabilities and forward integration into sterilization services representing the decisive upstream and downstream levers.
For Market Incumbents: Anticipate EPA restrictions on ethylene oxide sterilization residues by accelerating radiation sterilization validation and absorbing revalidation costs through captive sterilization infrastructure. Defend market position by securing exclusive supply agreements with robotic surgery platform developers for instrument-set-specific tray geometries, while expanding automated assembly capacity in Minneapolis-St. Paul and Tuttlingen clusters to maintain cost leadership against emerging composite material specialists. For New Entrants and Emerging Players: EU MDR in Europe opens a window for proprietary polymer formulation specialists capable of exceeding Annex I migration-test thresholds with documented biocompatibility protocols. Target ambulatory surgical centers in Florida and Texas with pre-sterilized, single-use diagnostic tray formats optimized for ophthalmology and dermatology workflows. Establish go-to-market presence through group purchasing organization vendor panel applications rather than direct hospital contracting. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified medical device conglomerates seeking sterilization packaging capabilities. Long-term viability favors compounders with validated biocompatibility testing infrastructure over conventional converters dependent on commodity resin supply. Watch FDA enforcement actions on 21 CFR Part 820 quality system violations as inflection indicator for consolidation acceleration among mid-cap manufacturers lacking compliance documentation depth.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Annex I compliance unlocks European hospital procurement at premium positioning. |
| Hospital System Partnership | Multi-year sterilization validation bundling compresses central processing department liability transfer. |
| Backward Integration into Polymer Compounding | Proprietary ceramic-filled formulations exceed thermal cycling thresholds for robotic surgery applications. |
| Automated Assembly Line Deployment | Validated process controls under FDA 21 CFR Part 820 secure group purchasing organization vendor status. |
| Software Companion Development | Digital tray tracking integrates with hospital inventory management and instrument traceability systems. |
Study Parameters
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and SEC 10-K disclosures from medical device manufacturers, complemented by interviews with central processing department managers, biomedical engineers, group purchasing organization contracts managers, and sterilization validation specialists. Secondary validation drew from ISO 11607 packaging standards, EPA ethylene oxide emission reports, and customs trade data on medical-grade polymer imports. Bottom-up tray volume estimates triangulated against top-down healthcare expenditure projections.
Segment-level outputs across surgical, sterilization, diagnostic, and storage tray categories tracked material type migration patterns and end-user facility dynamics over the projection horizon. The analytical framework modeled product type, material formulation, manufacturing stage automation level, and geographic regulatory cluster as primary segmentation dimensions. CAGRs derived from procedure volume correlations, ambulatory surgical center expansion trajectories, and composite material penetration curves in robotic surgery applications.
Caveats apply where EPA ethylene oxide restrictions, EU MDR documentation burden escalation, or hospital consolidation pace could materially shift the outlook for sterilization tray demand and manufacturer cost structures. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Distal Embolic Filters Market
Medical Devices
Oxygen Conservers Market
Medical Devices
Asthma Spacers Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Arthroscopy Devices Market
Medical Devices
Wearable Atrial Fibrillation Detection Devices Market
Medical Devices
Global Canes and Crutches Market
Medical Devices
Minimally Invasive Laser Therapy Devices Market
Medical Devices
Hearing Loop Market
Medical Devices
Leadless Pacemakers Market
Medical Devices
Heart Closure Devices Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Low Vision Aids Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
US Medical Display Monitors Market