
 MRI-Guided Radiation Therapy Systems Market | 2026-2036
MRI-Guided Radiation Therapy Systems Market Size, Share, and Industry Trends Forecast 2026-2036
MRI-Guided Radiation Therapy Systems Market Outlook
Oncology clinics are unwinding the historical hospital-centric procurement pattern for advanced radiation platforms. Elekta AB leverages its integrated MR-linac architecture to sustain installed-base loyalty across Nordic and North American reference sites. ViewRay Technologies Inc. anchors its competitive stance on real-time adaptive software workflows that differentiate hardware-light subscription models. Siemens Healthineers AG dominates the imaging subsystem supply chain, extending component access to third-party radiation OEMs that lack captive MR development.
MRI-guided radiation therapy systems combine magnetic resonance imaging with linear accelerator or cobalt-60 delivery to enable soft-tissue visualization during live beam administration, typically operating at 0.35T to 1.5T field strengths with dedicated radiofrequency shielding. These platforms serve the primary purpose of enabling adaptive replanning when tumor position or morphology shifts between or during treatment fractions. System hardware captures the dominant value pool given capital intensity and service attachment rates, while adaptive radiotherapy software represents the fastest-expanding margin segment as recurring license revenue scales with installed-base utilization. Prostate cancer applications lead current clinical utilization volumes, though brain tumor protocols are gaining traction where magnetic-field-compatible immobilization and dosimetry validation have matured.
The FDA 510(k) and CE marking pathways under the EU MDR impose substantial clinical evidence requirements on real-time imaging claims, slowing market entry for novel adaptive algorithms while privileging incumbents with predicate-device portfolios. Japan's PMDA maintains distinct magnetic-field exposure limits for operator safety that shape coil and shielding specifications for Asia-Pacific regulatory submissions. Stakeholders must monitor how reimbursement coding for online adaptive sessions evolves relative to standard fraction billing, as this determines hospital ROI timelines and replacement-cycle urgency.
Market Dynamics
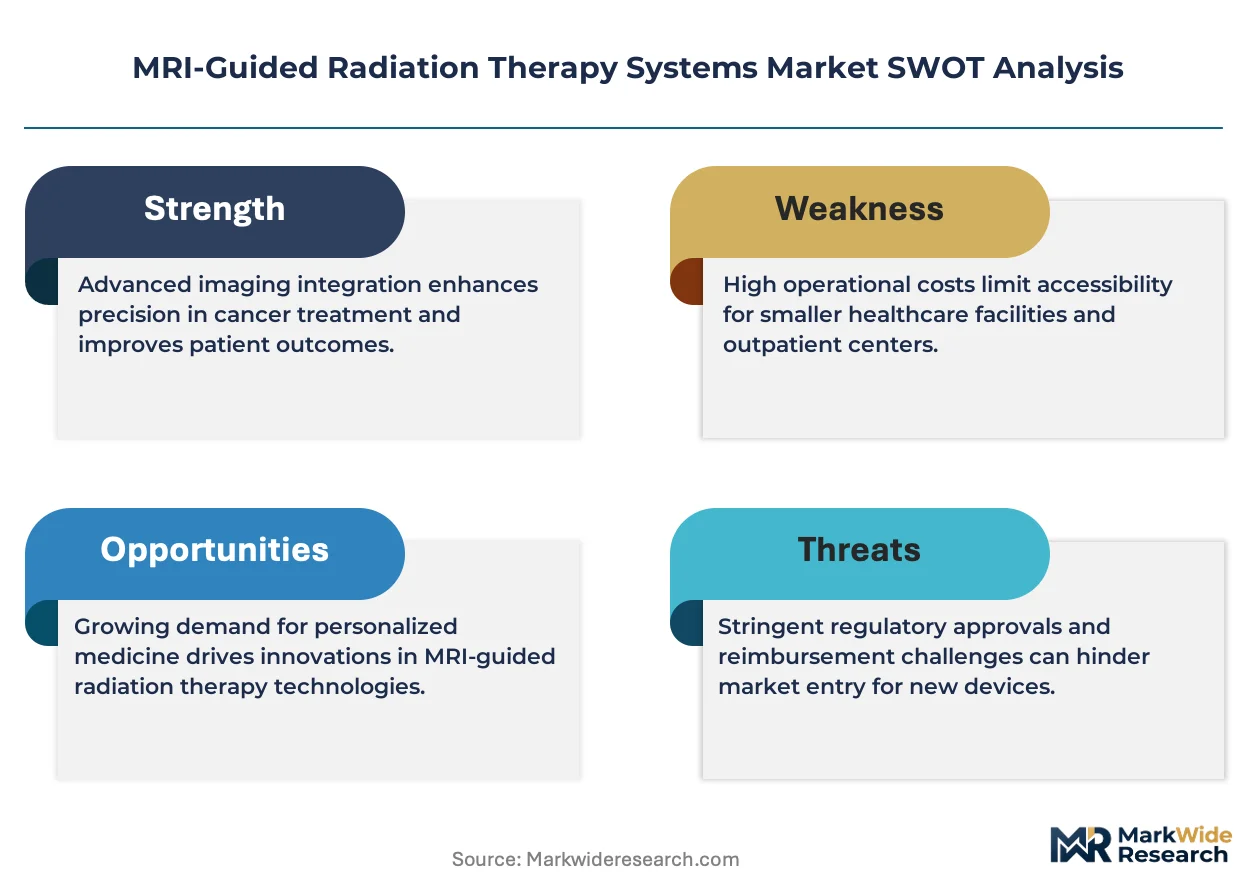
The FDA and CE marking frameworks under EU MDR are tightening real-time imaging requirements for precision delivery, forcing oncology clinics to accelerate replacement cycles for legacy linear accelerator platforms that lack integrated MR guidance capabilities.
Growth Catalysts
- Adaptive Replanning Protocols:Real-time soft-tissue visualization during beam administration enables same-session plan modification, reducing geographic miss rates in prostate and brain tumor treatments. Nordic reference sites are scaling utilization to justify capital deployment.
- Japan PMDA Magnetic-Field Exposure Standards:Operator safety limits for coil and shielding specifications create regulatory clarity that accelerates Asia-Pacific submissions for hybrid MR-linac architectures.
- Prostate Cancer Clinical Utilization:High fraction volumes in urology departments generate recurring service revenue that amortizes hardware acquisition costs across shorter payback periods.
Market Restraints
- Superconducting Magnet Supply Concentration:Cryogenic cooling system fabrication concentrates among specialized Japanese and German component suppliers, creating single-source vulnerability for 1.5T platform manufacturers.
- Radiofrequency Shielding Material Costs:Copper and mu-metal price volatility directly impacts bill-of-materials for integrated bunker designs, compressing margin on fixed-price installation contracts.
- Cobalt-60 Substitution Threat:Teletherapy units using gamma-emitting isotopes offer lower capital entry points for clinics that defer adaptive capability, particularly in cost-constrained Eastern European markets.
Strategic Opportunities
- Brain Tumor Protocol Expansion:Magnetic-field-compatible immobilization and dosimetry validation advances are opening cranial indications where historical CT-guidance delivered inferior soft-tissue contrast.
- Software-First Subscription Models:Adaptive radiotherapy platforms are unbundling from hardware sales, enabling per-fraction licensing that penetrates mid-tier oncology networks unable to justify full capital expenditure.
- Indian PLI Scheme for Medical Devices:Domestic manufacturing incentives for precision radiation equipment reduce import duty exposure for multinational OEMs establishing local assembly for Asia-Pacific distribution.
Industry Challenges
- Medical Physics Workforce Scarcity:The specialized training required for MR-safe dosimetry and real-time plan adaptation outpaces academic program output, constraining installed-base utilization rates.
- Legacy LINAC Integration Complexity:Retrofitting existing vaults with magnetic-field-compatible beam delivery requires structural reinforcement that extends installation timelines and disrupts ongoing patient throughput.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI-Guided Radiation Therapy Systems Market |
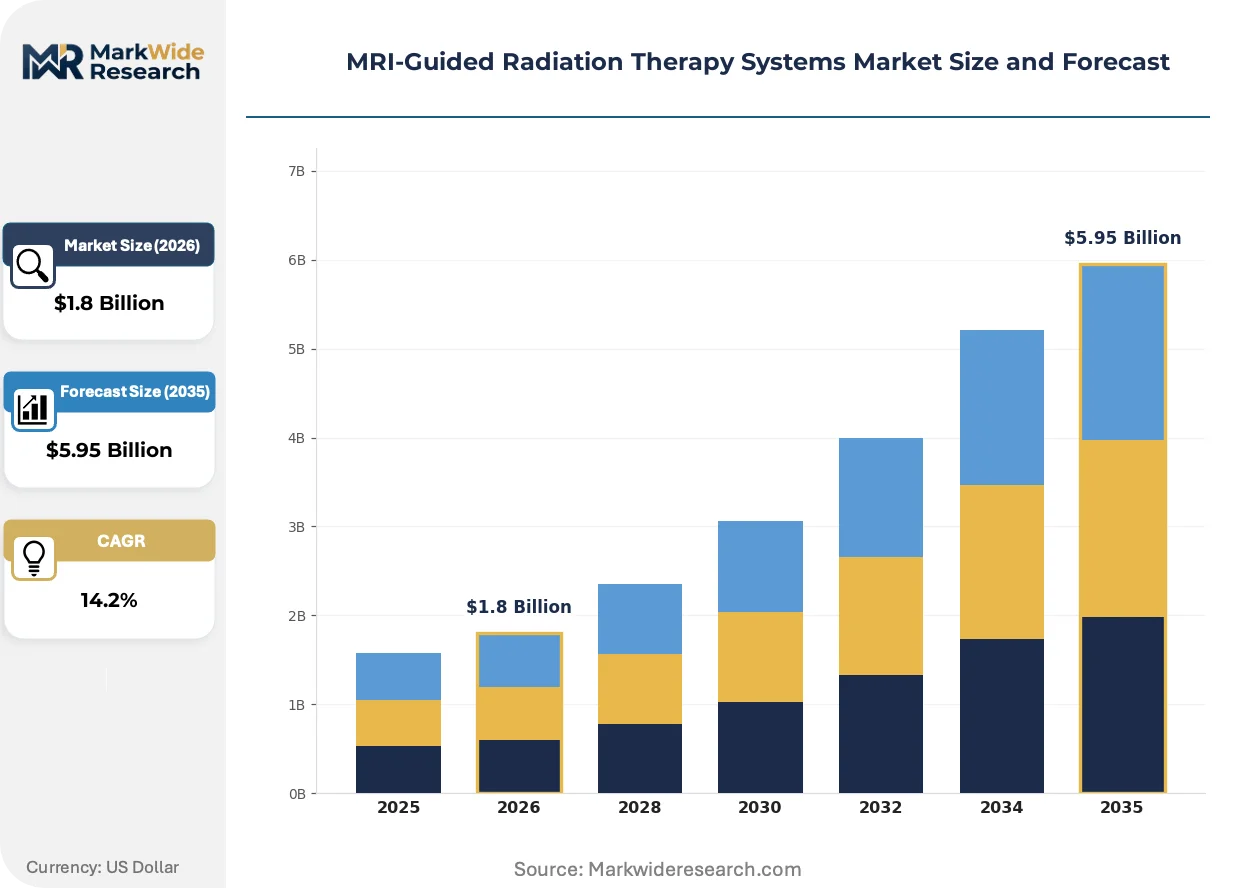
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: System, Software, Accessories, Treatment Planning Tools End User: Hospitals, Cancer Treatment Centers, Research Institutions, Oncology Clinics Technology: Adaptive Radiotherapy, Image-Guided Therapy, Stereotactic Radiotherapy, Hyperthermia Treatment Application: Prostate Cancer, Breast Cancer, Brain Tumors, Gynecological Cancers |
| Companies Covered | ViewRay Technologies Inc., Elekta AB, Siemens Healthineers AG, Koninklijke Philips N.V., GE Healthcare, Varian Medical Systems Inc., Accuray Incorporated, Hitachi Ltd., Brainlab AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI-Guided Radiation Therapy Systems Market Strategic Shifts
Real-time adaptive software workflows are compressing the traditional hardware-centric business model, while regulatory convergence around soft-tissue imaging claims is standardizing evidence requirements across major jurisdictions.
Radiofrequency coil arrays for intra-fraction motion tracking are miniaturizing from rigid fixed geometries to flexible multi-channel configurations that conform to patient anatomy. Community oncology networks in the United States are piloting these surface coils to reduce setup variability without dedicated radiographer staffing. This coil miniaturization is enabling same-day simulation-to-treatment workflows that compress reimbursement cycles.
The EU MDR's strengthened clinical evidence requirements for real-time imaging predicates are extending 510(k) equivalence pathways for adaptive algorithm submissions. Manufacturers must now compile prospective imaging validation studies that previously relied on retrospective phantom data. Brain tumor protocols face the steepest compliance burden given magnetic-field distortion effects on small-field dosimetry.
Hospital procurement committees are unbundling service contracts from capital equipment financing, demanding itemized uptime guarantees and software update schedules. Independent radiation oncology groups in Germany are leading this disintermediation, negotiating direct adaptive software licenses that bypass OEM bundled pricing. This contract unbundling is most visible in metropolitan clusters where multiple vendor platforms operate within referral network catchment areas.
MRI-Guided Radiation Therapy Systems Market Segmentation
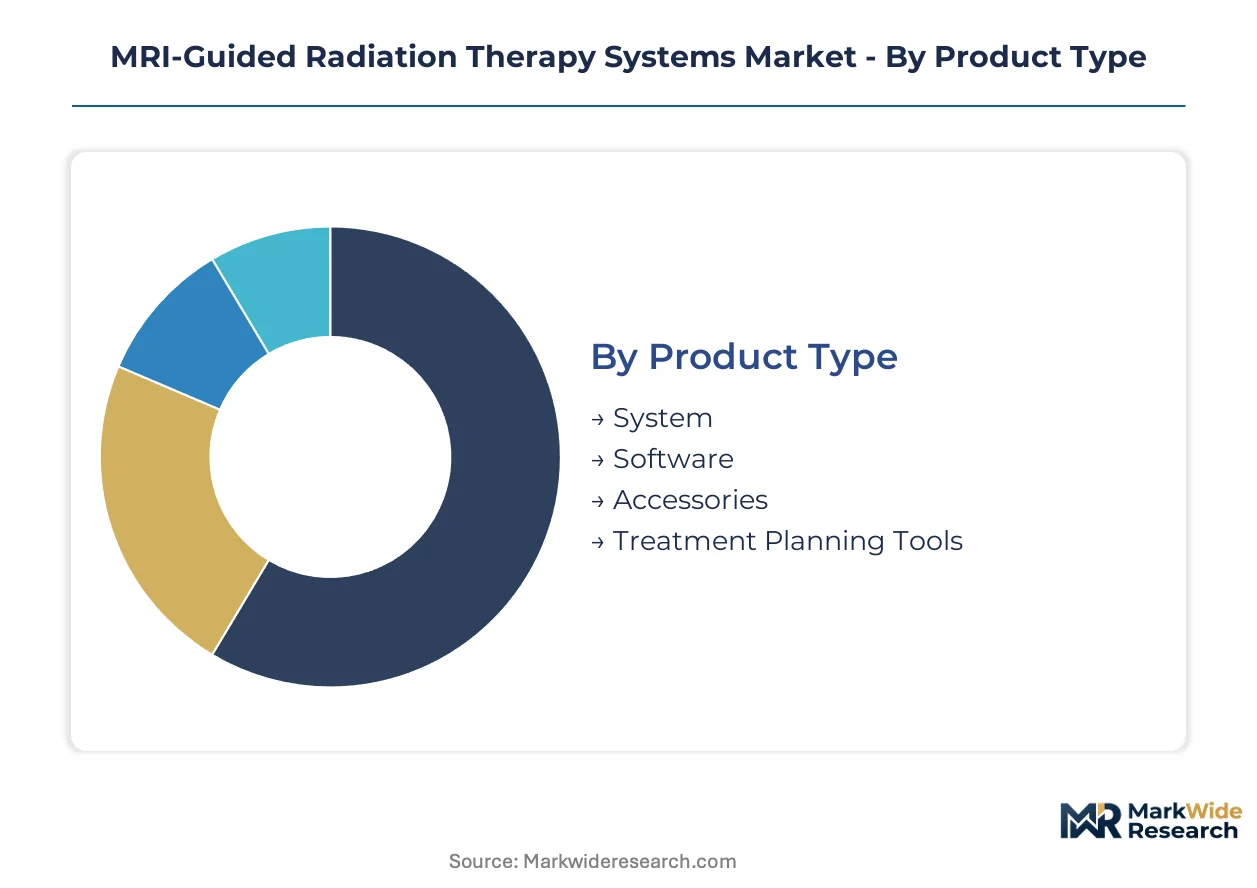
Segmentation in MRI-guided radiation therapy reveals how capital intensity, clinical workflow integration, and regulatory complexity distribute value across hardware, software, and service layers. Understanding these divisions illuminates where procurement committees concentrate budget authority and which segments drive recurring revenue streams.
Product Type:
System hardware dominates domestic procurement in the United States, Germany, and Japan where reference sites anchor regional training networks. Software and accessories follow export-led patterns into emerging markets lacking captive MR development capabilities.
- System:Integrated MR-linac platforms operating at 0.35T to 1.5T field strengths with dedicated radiofrequency shielding. United States hospital procurement committees prioritize these capital-intensive installations where service attachment rates amortize acquisition across prostate and brain tumor protocols.
- Software:Adaptive radiotherapy platforms enabling real-time plan modification during beam administration. German oncology networks are unbundling these licenses from hardware sales, negotiating direct per-fraction pricing that bypasses OEM bundled structures.
- Accessories:Surface coil arrays and magnetic-field-compatible immobilization devices. Japanese PMDA exposure limits shape shielding specifications for Asia-Pacific distribution.
- Treatment Planning Tools:Dosimetry validation systems for small-field cranial applications. Research institutions in Nordic countries drive specification requirements.
System hardware commands the established base. The steepest expansion runs through adaptive radiotherapy software.
End User:
Customer concentration varies by reimbursement coding maturity, with hospital networks leveraging capital reserves against community clinics pursuing subscription models.
- Hospitals:Academic medical centers with dedicated radiation oncology departments and existing bunker infrastructure. These institutions in the United States and Germany absorb extended installation timelines for magnetic-field-compatible vault retrofitting.
- Cancer Treatment Centers:Specialized facilities with high fraction volumes in urology and neuro-oncology. Prostate cancer utilization rates in these centers generate service revenue that shortens hardware payback periods.
- Research Institutions:Sites conducting prospective imaging validation studies for EU MDR and FDA 510(k) predicate-device portfolios. Brain tumor protocol development concentrates here.
- Oncology Clinics:Community networks piloting same-day simulation-to-treatment workflows with flexible coil arrays. These clinics in metropolitan United States clusters are disintermediating from hospital-centric procurement patterns.
Hospitals anchor the installed base. Oncology clinics are climbing the fastest as software-first models penetrate mid-tier networks.
Technology:
Technology adoption correlates with medical physics workforce density, constraining utilization in markets where MR-safe dosimetry training lags platform installation.
- Adaptive Radiotherapy:Real-time soft-tissue visualization with same-session plan modification. Nordic reference sites are scaling these protocols to justify capital deployment across prostate and brain indications.
- Image-Guided Therapy:Intra-fraction motion tracking using miniaturized radiofrequency coil arrays. United States community networks deploy these to reduce setup variability without dedicated radiographer staffing.
- Stereotactic Radiotherapy:High-precision delivery for small cranial lesions. Magnetic-field distortion effects on dosimetry create compliance burdens under EU MDR evidence requirements.
- Hyperthermia Treatment:Thermal augmentation combined with MR guidance. Research applications dominate given magnetic-field-compatible heating system complexity.
Image-guided therapy commands the established base. Adaptive radiotherapy is gaining share fastest as regulatory convergence standardizes soft-tissue imaging claims.
Application:
Clinical utilization volumes concentrate where magnetic-field-compatible immobilization and dosimetry validation have matured, with expansion contingent on protocol standardization.
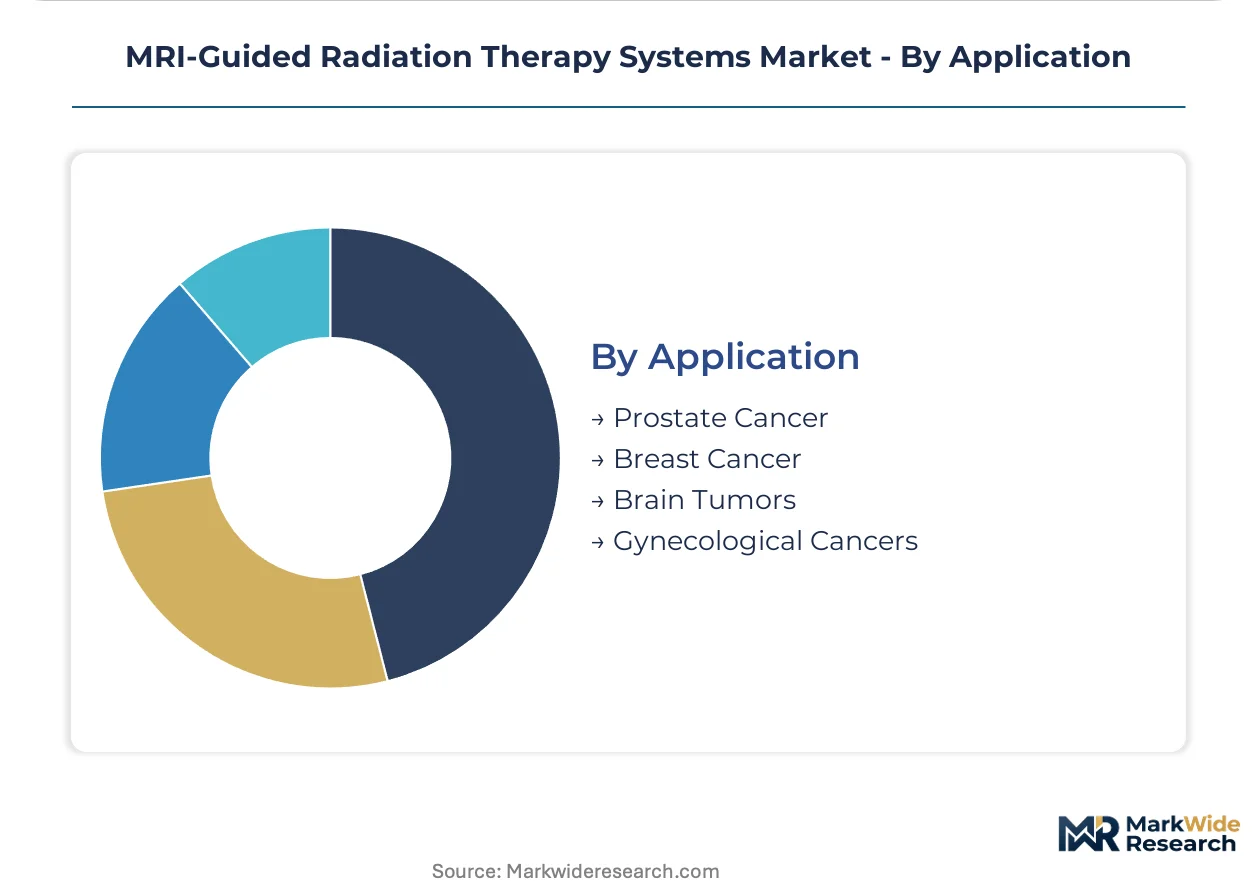
- Prostate Cancer:High fraction volumes in urology departments with established MR-safe positioning systems. German and United States cancer treatment centers generate recurring service revenue from these workflows.
- Breast Cancer:Soft-tissue visualization advantages over CT-guidance for mobile targets. Adoption accelerates where surface coil miniaturization enables prone positioning.
- Brain Tumors:Cranial indications where magnetic-field distortion effects on small-field dosimetry have been validated. EU MDR prospective imaging studies are extending 510(k) equivalence pathways for these protocols.
- Gynecological Cancers:Adaptive replanning for anatomical shifts during multi-week treatment courses. Research institutions in Japan are advancing coil specifications for these applications.
Prostate cancer commands the established base. Brain tumors are expanding most quickly as immobilization and dosimetry validation mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and specialized cancer treatment facilities concentrate procurement authority in markets with mature reimbursement frameworks for adaptive radiotherapy sessions. Hospital networks in the United States, Germany, and Japan absorb capital-intensive installations where service attachment rates amortize acquisition costs. Emerging demand in India and Australia follows software-first subscription models that bypass full hardware expenditure.
United States
FDA 510(k) predicate-device portfolios privilege incumbents with established real-time imaging claims, accelerating replacement cycles for legacy linear accelerator platforms. Community oncology networks in metropolitan clusters pilot same-day simulation-to-treatment workflows with flexible coil arrays. The Greater Boston and Pacific Northwest regions anchor reference site networks that train medical physicists on MR-safe dosimetry protocols.
Germany
Independent radiation oncology groups negotiate direct adaptive software licenses that bypass OEM bundled pricing structures. CE marking under EU MDR imposes prospective imaging validation requirements that extend equivalence pathways for brain tumor protocols. The North Rhine-Westphalia and Bavaria regions concentrate hospital procurement committees with dedicated bunker infrastructure for magnetic-field-compatible vault retrofitting.
Japan
PMDA magnetic-field exposure limits for operator safety shape coil and shielding specifications for Asia-Pacific regulatory submissions. High fraction volumes in urology departments generate recurring service revenue that shortens hardware payback periods. The Kanto region around Tokyo hosts the highest density of proton and MR-linac hybrid installations.
India
The PLI scheme for medical devices reduces import duty exposure for multinational OEMs establishing local assembly for regional distribution. Mid-tier oncology networks pursue software-first subscription models unable to justify full capital expenditure. The Maharashtra and Karnataka states concentrate emerging cancer treatment centers in metropolitan Mumbai and Bangalore clusters.
Australia
TGA convergence with FDA and EU MDR standards streamlines regulatory submissions for adaptive algorithm platforms. Research institutions conduct prospective imaging validation studies that support predicate-device portfolios for Asia-Pacific expansion. The New South Wales and Victoria states anchor clinical trial networks for brain tumor protocol development.
MRI-Guided Radiation Therapy Systems Market Competitive Environment
Player mix skews toward integrated system manufacturers with captive MR development capabilities and imaging subsystem suppliers extending component access to third-party radiation OEMs. The market structure concentrates around Nordic and German engineering heritage combined with Japanese precision component fabrication. Two strategic archetypes dominate: full-stack MR-linac architects controlling hardware-software integration, and modular imaging subsystem vendors enabling hybrid configurations. Competitive moves center on unbundling service contracts from capital financing and licensing adaptive algorithms on per-fraction pricing models.
Among integrated system architects, Elekta AB and ViewRay Technologies Inc. exemplify contrasting approaches to installed-base loyalty. Elekta leverages its Swedish engineering heritage to sustain reference site networks across Nordic and North American academic centers. ViewRay anchors its positioning on real-time adaptive software workflows that differentiate hardware-light subscription offerings. Siemens Healthineers AG occupies the imaging subsystem tier, extending MR component access to radiation OEMs lacking captive magnetic resonance development. These three entities collectively represent the competitive structure: full-stack integration, software-centric disruption, and upstream component supply.
| Leading Market Players |
|---|
| ViewRay Technologies Inc. |
| Elekta AB |
| Siemens Healthineers AG |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Varian Medical Systems Inc. |
| Accuray Incorporated |
| Hitachi Ltd. |
| Brainlab AG |
| Others |
Value Chain & Pricing Dynamics
Long-term service attachment contracts lock in both superconducting magnet supply access and predictable maintenance pricing for United States hospital procurement committees. These multi-year agreements shield oncology networks from copper and mu-metal volatility while securing priority component allocation from Japanese cryogenic cooling system fabricators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate bunker construction and installation services across German and Japanese reference sites. Three-tier pricing structure across premium adaptive software bundles, standard hardware-service packages, and economy coil-only configurations separates academic medical centers from community oncology networks. Pricing pressure stems from cobalt-60 teletherapy substitution in Eastern European markets where capital constraints defer MR-linac adoption. Community oncology clinics exhibit highest price sensitivity, while Nordic academic centers absorb premium positioning for training network access.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Yokohama port congestion periodically delay superconducting magnet delivery to European and Asia-Pacific assembly facilities. Cryogenic cooling system fabrication concentrates in Japan and Germany, while radiofrequency coil winding draws from specialized suppliers in Switzerland and the United States. Single-source vulnerability for 1.5T platform superconducting magnets creates structural risk if geopolitical restrictions disrupt Japanese component flows. Distribution runs through OEM-direct hospital procurement committees in mature markets, with third-party radiation OEMs accessing imaging subsystems via Siemens Healthineers component licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MRI-guided radiation therapy sits in early-cycle expansion as prostate cancer protocol standardization accelerates replacement demand for legacy linear accelerator platforms. Adaptive software unbundling from hardware sales extends addressable market penetration into mid-tier oncology networks previously priced out of capital-intensive installations.
For Market Incumbents: Compound installed-base loyalty through predictive maintenance service contracts that preempt third-party service competition. Deepen backward integration into radiofrequency coil manufacturing to capture margin from surface array miniaturization trends. Prioritize FDA 510(k) predicate accumulation for brain tumor protocols before EU MDR evidence requirements harden further.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market entry for novel adaptive algorithms with retrospective phantom data packages. White-space concentrates in Indian PLI scheme manufacturing partnerships and Australian TGA-aligned Asia-Pacific distribution hubs. Software-first per-fraction licensing penetrates community oncology networks unable to justify full MR-linac capital deployment.
For Investors and Strategic Acquirers: Capital is best deployed toward adaptive radiotherapy software specialists with EU MDR prospective imaging validation studies already filed. Long-term viability favors platforms with recurring license revenue scaling independently of hardware replacement cycles. Monitor reimbursement coding evolution for online adaptive sessions as the inflection signal determining hospital ROI timelines and replacement-cycle urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR prospective imaging validation accelerates brain tumor protocol equivalence submissions. |
| Hospital System Partnership | Academic medical center alliances anchor reference site networks for medical physicist training. |
| Software Companion Development | Real-time adaptive algorithms differentiate hardware-light subscription models from capital-intensive sales. |
| Reimbursement Strategy | Online adaptive session coding determines oncology clinic ROI timelines and platform replacement urgency. |
| Backward Integration | In-house radiofrequency coil production captures margin from flexible surface array miniaturization. |
Study Parameters
The analysis maps integrated MR-linac systems, adaptive radiotherapy software, surface coil accessories, and treatment planning tools, each validated through hospital procurement committee interviews. Primary fieldwork engaged radiation oncologists, medical physicists, biomedical engineers, and GPO contracts managers across United States, German, and Japanese reference sites. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation, PMDA submission databases, and hospital procurement records. Bottom-up segment sizing triangulated against top-down market aggregation from OEM installed-base disclosures.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end user archetype, technology protocol, and cancer application. CAGRs derived from regression analysis of historical replacement cycles and penetration rate assumptions. Industry-specific forecast inputs incorporated reimbursement coding evolution timelines and medical physics workforce training program output.
Underlying assumptions cover stable regulatory pathways for real-time imaging claims, with deviation risk concentrated in EU MDR evidence requirement tightening and cobalt-60 substitution acceleration in cost-constrained markets. Forecasts reflect these documented conditions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bluetooth Hearing Aids Market
Medical Devices
Single-Lead ECG Monitors Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Global Cranial Fixation and Stabilization Systems Market
Medical Devices
Microcurrent Facial Market
Medical Devices
Global Medical Cannula Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Middle East and Africa Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Polyglyconate Sutures Market
Medical Devices
Global Optical Biometry Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Bioactive Fillings Market
Medical Devices
Electroencephalography (EEG) Amplifier System Market
Medical Devices
Asthma Spacers Market