
 Hospital Privacy Screens Market | 2026-2036
Hospital Privacy Screens Market Size, Share, and Industry Trends Forecast 2026-2036
Hospital Privacy Screens Market Analysis
Hospital supply chain procurement is reconfiguring around consolidated purchasing agreements and direct manufacturer relationships. Medline Industries leverages its extensive distribution network to sustain volume leadership across acute care accounts. Silentia AB anchors its position through specialized infection-control screen systems designed for Nordic hospital protocols. KwickScreen competes via rapid-deployment portable architectures that address emergency department throughput demands.
Hospital privacy screens are physical barriers engineered from fabric, vinyl, or metal substrates with antimicrobial coatings, typically measuring 180-200 cm in height and designed for rapid sanitization between patient encounters. Their primary purpose is to ensure patient dignity, control airborne pathogen dispersion, and enable flexible spatial reconfiguration within clinical environments. Portable screens represent the fastest-expanding product category as hospitals prioritize surge-capacity flexibility over fixed infrastructure. Fabric and vinyl materials dominate current procurement, though metal-framed acoustic panels command premium positioning in surgical units where noise reduction intersects with privacy requirements.
FDA medical device regulations and Joint Commission accreditation standards shape material selection and cleaning protocol documentation for privacy screen deployments in US healthcare facilities. OSHA workplace safety guidelines and EPA-registered antimicrobial claims further constrain supplier qualification and product labeling requirements. Stakeholders must monitor evolving infection control mandates and sustainability disclosure pressures as procurement criteria increasingly weight lifecycle environmental impact alongside clinical performance specifications.
Market Dynamics
Hospital privacy screens face structural pressure from infection-control protocol escalation, where Joint Commission accreditation audits and FDA medical device cleanliness standards now mandate antimicrobial surface documentation and sanitization traceability that legacy fabric systems cannot satisfy.
Growth Catalysts
- Antimicrobial coating chemistry:Silver-ion and copper-infused substrates now satisfy EPA-registered claims for pathogen reduction, qualifying screens as active infection-control devices rather than passive furniture.
- US hospital construction cycles:Renovation spending in acute care facilities drives replacement demand as older fixed-panel installations reach end-of-life and fail current material specifications.
- Joint Commission protocols:Accreditation surveys now score privacy screen cleanability as an environmental-of-care metric, forcing non-compliant facilities into accelerated procurement.
Market Restraints
- Aluminum and steel input volatility:Metal-framed acoustic panels face margin compression from commodity price swings that fabric-vinyl alternatives avoid.
- Supply concentration in textile coating:Three specialty chemical suppliers control antimicrobial additive formulation, creating qualification bottlenecks for new screen manufacturers.
- Technical limitation in acoustic performance:Current portable architectures cannot achieve surgical-unit noise reduction targets below 35 dB without fixed installation.
Strategic Opportunities
- Underpenetrated outpatient surgical centers:Ambulatory facilities in the United States lack standardized privacy infrastructure and represent greenfield deployment for rapid-deployment portable systems.
- EU MDR compliance services:European manufacturers can capture premium positioning by bundling technical documentation and post-market surveillance for clinical investigation requirements.
- RFID-enabled asset tracking:Converging inventory management and infection-control workflows allows screen fleets to integrate with hospital IoT infrastructure.
Industry Challenges
- Biocompatibility testing timelines:ISO 10993 cytotoxicity and sensitization studies extend product development cycles by 14-18 months for novel antimicrobial substrates.
- Legacy anchor-and-track infrastructure:Fixed-panel replacement requires structural assessment of ceiling grid capacity that delays portable conversion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hospital Privacy Screens Market |
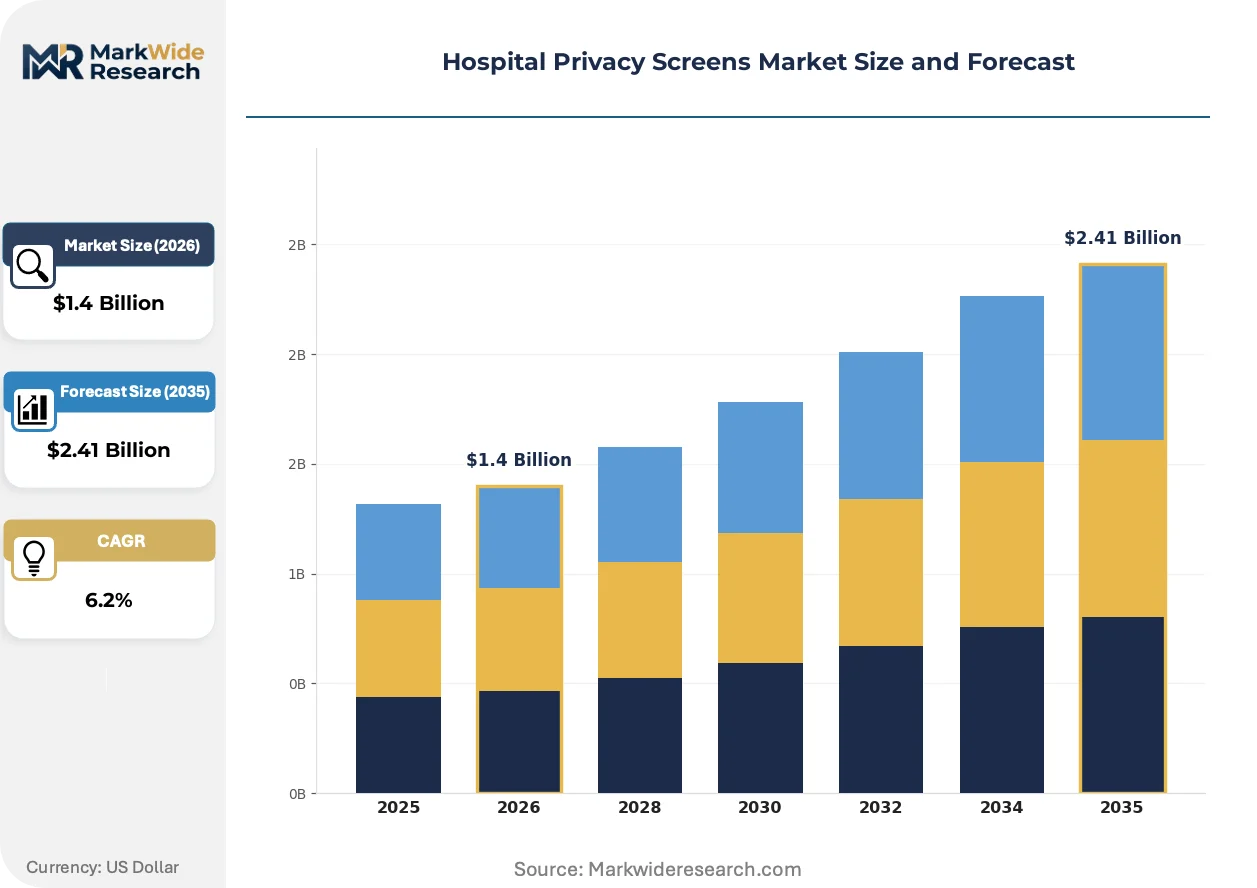
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.41 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-mounted Screens, Portable Screens, Folding Partitions, Acoustic Panels Material: Fabric, Vinyl, Wood, Metal End User: Hospitals, Clinics, Long-term Care Facilities, Emergency Rooms Application: Patient Privacy, Waiting Areas, Exam Rooms, Surgical Units |
| Companies Covered | GF Health Products, Inc., Omnimed, Silentia AB, KwickScreen, R&B Wire Products, Inc., Medline Industries, Inc., Halyard Health, Inc., Dynarex Corporation, AliMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hospital Privacy Screens Market Emerging Trajectories
Privacy screen evolution centers on material science breakthroughs that bridge infection control with operational flexibility, while procurement digitization and regulatory documentation automation reshape how hospitals evaluate and deploy these assets.
Photocatalytic titanium dioxide coatings are digitizing the sanitization workflow by enabling continuous surface decontamination under ambient LED lighting. Surgical units in academic medical centers are piloting these substrates to reduce terminal cleaning labor. The technology is digitizing compliance documentation through embedded sensors that log activation cycles for Joint Commission audit trails.
EPA's emerging per- and polyfluoroalkyl substances restrictions are forcing reformulation of stain-resistant fabric treatments used in privacy screens. Manufacturers must phase out long-chain fluorocarbon chemistry by 2025 or face registration cancellation. Vinyl-coated polyester suppliers are accelerating migration to silicone-based alternatives, though these materials carry 15-20% cost premiums and reduced durability ratings.
Hospital supply chains are consolidating purchasing through regional group purchasing organizations that negotiate multi-year screen fleet contracts with built-in refresh cycles. This disintermediates traditional distributor relationships and forces manufacturers to maintain direct field service capabilities. The phenomenon is most visible in the United States, where HealthTrust and Premier contracts now specify antimicrobial performance tiers rather than product brands.
Hospital Privacy Screens Market Segmentation
Privacy screen procurement decisions cascade through multiple technical and operational dimensions. Hospitals weigh infection-control performance against spatial flexibility, while material specifications determine sanitization compliance and lifecycle economics.
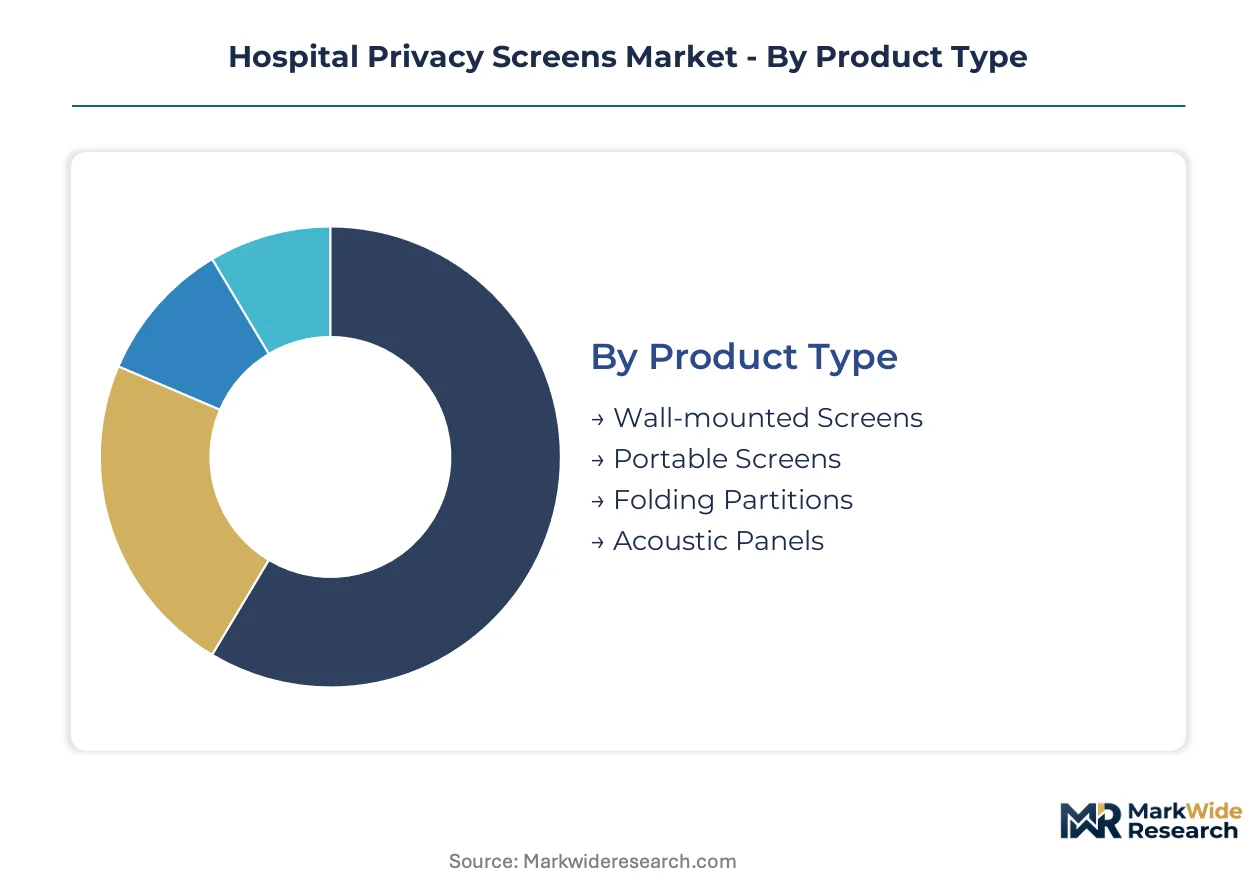
Product Type:
After-sales service intensity varies sharply across product architectures, with portable systems demanding fleet management and rapid-deployment training while fixed installations require structural engineering support.
- Portable Screens:Freestanding wheeled units with collapsible frames enable surge-capacity reconfiguration in emergency departments. Acute care hospitals in the United States prioritize these for throughput optimization during patient volume spikes.
- Wall-mounted Screens:Fixed track-and-panel systems anchor to ceiling grids or wall studs for permanent privacy infrastructure. These dominate surgical unit renovations where structural integration justifies higher capital outlay.
- Folding Partitions:Accordion-style multi-panel systems bridge fixed and portable use cases with moderate reconfigurability.
- Acoustic Panels:Sound-dampening substrates with metal framing address noise reduction requirements in procedural areas.
Wall-mounted screens hold the largest share; momentum sits with portable screens.
Material:
Cost tier stratification separates premium antimicrobial substrates from commodity alternatives, with coating chemistry driving qualification timelines and EPA registration status.
- Fabric:Woven polyester or cotton-poly blends with topical antimicrobial treatments offer lightweight deployability at lower price points. These face Joint Commission audit pressure due to porosity challenges in terminal cleaning protocols.
- Vinyl:Coated polyester or PVC substrates provide impermeable surfaces that satisfy FDA medical device cleanliness documentation. Hospitals in the United States favor these for emergency department high-turnover zones.
- Metal:Aluminum or steel framing with perforated or solid panel construction supports acoustic dampening and structural durability.
- Wood:Laminate-finished panels serve aesthetic requirements in administrative or reception contexts with lower sanitization frequency.
Vinyl captures the dominant procurement volume; metal substrates command the steepest expansion trajectory in surgical acoustic applications.
End User:
Customer type segmentation reveals divergent procurement authority structures, with hospital system GPO contracts contrasting against individual facility purchasing in smaller settings.
- Hospitals:Acute care facilities with centralized supply chain operations drive antimicrobial specification escalation through multi-year fleet contracts.
- Emergency Rooms:Dedicated ED units within hospital campuses or freestanding emergency centers prioritize rapid-deployment portable architectures for surge flexibility.
- Clinics:Outpatient and ambulatory settings underpenetrated by standardized privacy infrastructure represent greenfield portable system deployment.
- Long-term Care Facilities:Skilled nursing and assisted living environments balance infection control with residential aesthetics in material selection.
Hospitals anchor procurement volume; emergency rooms are gaining share fastest through dedicated surge-capacity investments.
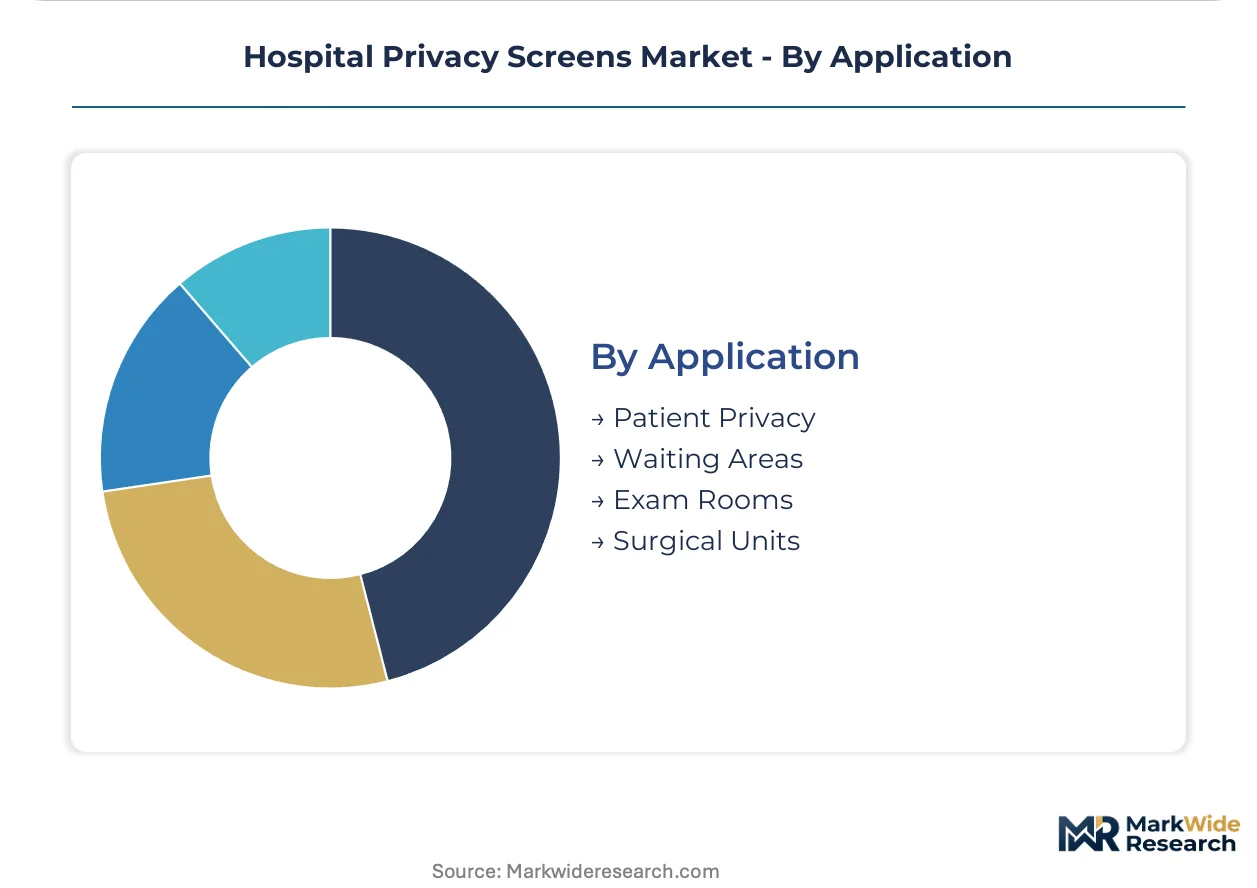
Application:
Application segmentation tracks functional performance requirements from basic visual privacy to combined acoustic-pathogen control in specialized clinical zones.
- Patient Privacy:Bedside and bay separation in general medical-surgical units constitutes the core functional requirement driving base-model procurement.
- Surgical Units:Operating rooms and procedural suites demand concurrent noise reduction below 35 dB and airborne pathogen containment, limiting viable solutions to fixed acoustic-panel architectures.
- Exam Rooms:Outpatient consultation spaces require moderate reconfigurability with rapid sanitization between encounters.
- Waiting Areas:Public zone privacy solutions balance aesthetic integration with lower-frequency cleaning protocols.
Patient privacy holds the largest installed base; surgical units concentrate premium pricing and technical innovation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States, where Joint Commission accreditation mandates and hospital construction cycles sustain premium procurement, while European markets face margin compression from EU MDR compliance costs and public procurement austerity.
United States
Acute care renovation spending and emergency department surge-capacity investments drive replacement demand for portable privacy systems. The FDA's medical device cleanliness standards and OSHA workplace safety guidelines enforce antimicrobial surface documentation and sanitization traceability. Major hospital systems in Texas, California, and the Northeast Corridor consolidate purchasing through HealthTrust and Premier group purchasing organizations.
Germany
Hospital infrastructure modernization programs and surgical unit acoustic requirements sustain demand for fixed-panel metal-framed systems. The EU Medical Device Regulation and ECHA REACH compliance frameworks extend qualification timelines for novel antimicrobial substrates. Industrial clusters in Baden-Württemberg and North Rhine-Westphalia host specialized textile coating suppliers serving Nordic hospital protocol specifications.
United Kingdom
NHS estate renewal initiatives and infection control procurement frameworks elevate material specifications toward EPA-registered antimicrobial claims. The Care Quality Commission inspection regime scores environmental cleanliness as a core performance metric. London and Southeast England acute trusts lead portable system deployment for emergency department throughput optimization.
Japan
Aging hospital infrastructure replacement and surgical unit noise reduction mandates sustain premium acoustic panel demand. METI industrial standards and PMDA medical device registration requirements constrain rapid product iteration for foreign suppliers. The Kanto region around Tokyo concentrates procurement authority for national hospital network standardization.
Australia
Public hospital capital works programs and private health facility expansion drive greenfield privacy infrastructure deployment. The Therapeutic Goods Administration medical device framework and state-based health procurement policies enforce biocompatibility documentation. New South Wales and Victoria health districts lead rapid-deployment portable system adoption for surge flexibility.
Hospital Privacy Screens Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in coating chemistry and textile substrates. The vendor base stratifies across three tiers: multinational distributors with GPO contract leverage, regional fabricators with direct hospital relationships, and specialty coating suppliers controlling antimicrobial additive formulation. Consolidated purchasing through group purchasing organizations disintermediates traditional distribution channels. Dominant competitive moves include backward integration into textile coating capabilities and geographic expansion through regional service hub establishment.
Among North American distributors, Medline Industries, Inc. and GF Health Products, Inc. occupy positions within the consolidated tier, while Silentia AB exemplifies the European specialist archetype with infection-control system focus. KwickScreen represents the rapid-deployment portable architecture segment. These named entities anchor broader patterns of procurement consolidation and product specialization visible across the competitive set.
| Leading Market Players |
|---|
| GF Health Products, Inc. |
| Omnimed |
| Silentia AB |
| KwickScreen |
| R&B Wire Products, Inc. |
| Medline Industries, Inc. |
| Halyard Health, Inc. |
| Dynarex Corporation |
| AliMed |
| Others |
Supply Flow & Price Mechanics
Specialty chemical suppliers in Germany and the United States control antimicrobial additive formulation, concentrating margin capture upstream while downstream screen manufacturers compete on configured-to-order service capabilities. This concentration forces pricing power toward coating chemistry providers and away from finished-goods assemblers.
Pricing Analysis
Configured-to-order portable systems with embedded RFID tracking and custom antimicrobial specifications command 40-60% premiums over standard vinyl folding partitions. Three-tier pricing structure across premium, standard, and economy levels separates EPA-registered silver-ion substrates from topical antimicrobial treatments and untreated fabric alternatives. Price differentiation hinges on certification grade and customization level. Pricing pressure stems from aluminum and steel input volatility squeezing metal-framed acoustic panel margins. Outpatient surgical centers exhibit highest price sensitivity; academic medical centers with GPO contracts show lowest sensitivity due to bundled fleet refresh cycles.
Supply Chain Analysis
Extended payment terms from 60 to 90 days now dominate procurement contracts as hospital systems leverage balance-sheet strength to shift working capital burdens onto manufacturers. Geographic supply concentration centers on China for vinyl-coated polyester substrates, Germany for specialty antimicrobial chemical formulation, and the United States for aluminum extrusion and metal framing components. Raw material dependencies include silver-ion additives, copper-infused polymers, and medical-grade vinyl sheeting. Single-source vulnerability in textile coating chemistry creates qualification bottlenecks. Distribution runs through regional GPOs that disintermediate traditional medical-surgical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital privacy screens sit in early-cycle expansion as emergency department surge-capacity mandates and Joint Commission audit scoring create structural replacement demand that outpaces traditional furniture procurement cycles.
For Market Incumbents: Insulate margin pools by deepening captive supply of antimicrobial coating chemistry through backward integration into textile treatment capabilities, and anchor hospital system relationships through direct field service hubs that bypass distributor intermediation. The threat of RFID-enabled inventory management convergence demands defensive investment in IoT-integrated product architectures. For New Entrants and Emerging Players: Establish a beachhead in underpenetrated outpatient surgical centers where standardized privacy infrastructure remains absent and procurement authority sits at facility level rather than centralized GPO contracts. Target freestanding emergency centers in Texas and Florida experiencing rapid volume expansion. A go-to-market angle bundling rapid-deployment training with antimicrobial documentation compliance accelerates initial penetration. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialists with demonstrated EU MDR technical documentation capabilities and existing Nordic hospital protocol relationships that can be leveraged for premium positioning. Long-term viability over the next decade rests on regulatory compliance service bundling rather than commodity hardware manufacturing. The signal to watch is EPA registration status migration from passive furniture claims to active infection-control device classification.| Strategic Initiative | Industry Significance |
|---|---|
| Antimicrobial Coating Backward Integration | Captures margin pools concentrated in German and US specialty chemical suppliers. |
| RFID-Enabled Asset Tracking Development | Integrates screen fleets with hospital IoT infrastructure for Joint Commission audit trails. |
| EU MDR Compliance Service Bundling | Captures premium positioning through technical documentation and post-market surveillance. |
| Direct Field Service Hub Establishment | Bypasses distributor disintermediation from HealthTrust and Premier GPO consolidation. |
| Photocatalytic Titanium Dioxide Pilot Programs | Positions manufacturers for continuous decontamination demand in academic medical centers. |
Methodological Framework
A spread of perspectives from hospital procurement managers, GPO contracts specialists, biomedical engineers, and antimicrobial coating R&D directors converged on the working assumptions driving this analysis. Primary interviews with acute care facility supply chain executives and secondary validation through FDA medical device registration databases, EPA antimicrobial claim filings, hospital construction spending reports, and Joint Commission accreditation scoring data anchored the demand-side assessment. Bottom-up facility-level procurement modeling and top-down market sizing triangulation cross-checked volume estimates.
Demand-supply-balance framing shaped the analytical approach across the projection horizon. Segmentation dimensions modeled include product architecture, material substrate, end-user facility type, and application zone. CAGRs were derived from replacement cycle analysis, construction spending correlation, and regulatory mandate timing. Industry-specific forecast inputs encompassed Joint Commission audit scoring weighting for environmental-of-care metrics and EPA registration status migration timelines for antimicrobial claims.
Stress conditions across aluminum and steel commodity volatility, antimicrobial chemical supply concentration, and hospital capital expenditure cyclicality were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and GPO contract consolidation velocity. Macroeconomic contraction, delayed EPA enforcement, or breakthrough photocatalytic substrate adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Healthcare Products
Global Clinical Trial Consumables Market
Healthcare Products
Blood and Organ Bank Market
Healthcare Products
Antimicrobial Furniture Market
Healthcare Products
North America Adult Incontinence Products Market
Healthcare Products
Europe Blood and Blood Components Market
Healthcare Products
Blood and Blood Components Market
Healthcare Products
Cooling Mattress Market
Healthcare Products
Artificial Saliva Market
Healthcare Products
Ejiao Health Products Market
Healthcare Products
Nursing Products Market
Healthcare Products
Patient Cleansing Products Market
Healthcare Products
Smoking Cessation Aids Market
Healthcare Products
Medical Products Market
Healthcare Products
Hand Sanitizer Market
Healthcare Products
Consumer Healthcare Market
Healthcare Products
Menstrual Sponge Market