
 Urodynamic Catheter Market | 2026-2036
Urodynamic Catheter Market Size, Share, and Industry Trends Forecast 2026-2036
Urodynamic Catheter Market Analytics
Sensor miniaturization and wireless telemetry integration is tilting urodynamic catheter architecture toward disposable, data-rich platforms that reduce cross-contamination risk while expanding ambulatory compatibility. Laborie leverages its vertically integrated urology portfolio to control both hardware and software workflows in premium diagnostic suites. Cook Medical anchors North American supply through concentrated manufacturing of multi-lumen configurations for complex pressure-flow studies. Teleflex Incorporated competes on global channel density, particularly in European hospital systems where tender consolidation favors broad-line distributors.
Urodynamic catheters are single-use or limited-use sterile tubes, typically manufactured from medical-grade PVC, silicone, or polyurethane, designed to measure intravesical pressure, urethral pressure, and urinary flow rate during controlled filling and voiding studies; their primary commercial purpose is to objectively diagnose bladder outlet obstruction, detrusor overactivity, and neurogenic voiding dysfunction. Multi-channel catheters command the deepest margin pools because they bundle pressure sensing, EMG compatibility, and temperature compensation in one sterile SKU that commands premium positioning against basic urethral lines. Wireless monitoring represents the fastest-expanding technology segment as clinics seek to untether patients from bedside electromechanical systems and capture natural voiding patterns in home or ambulatory settings.
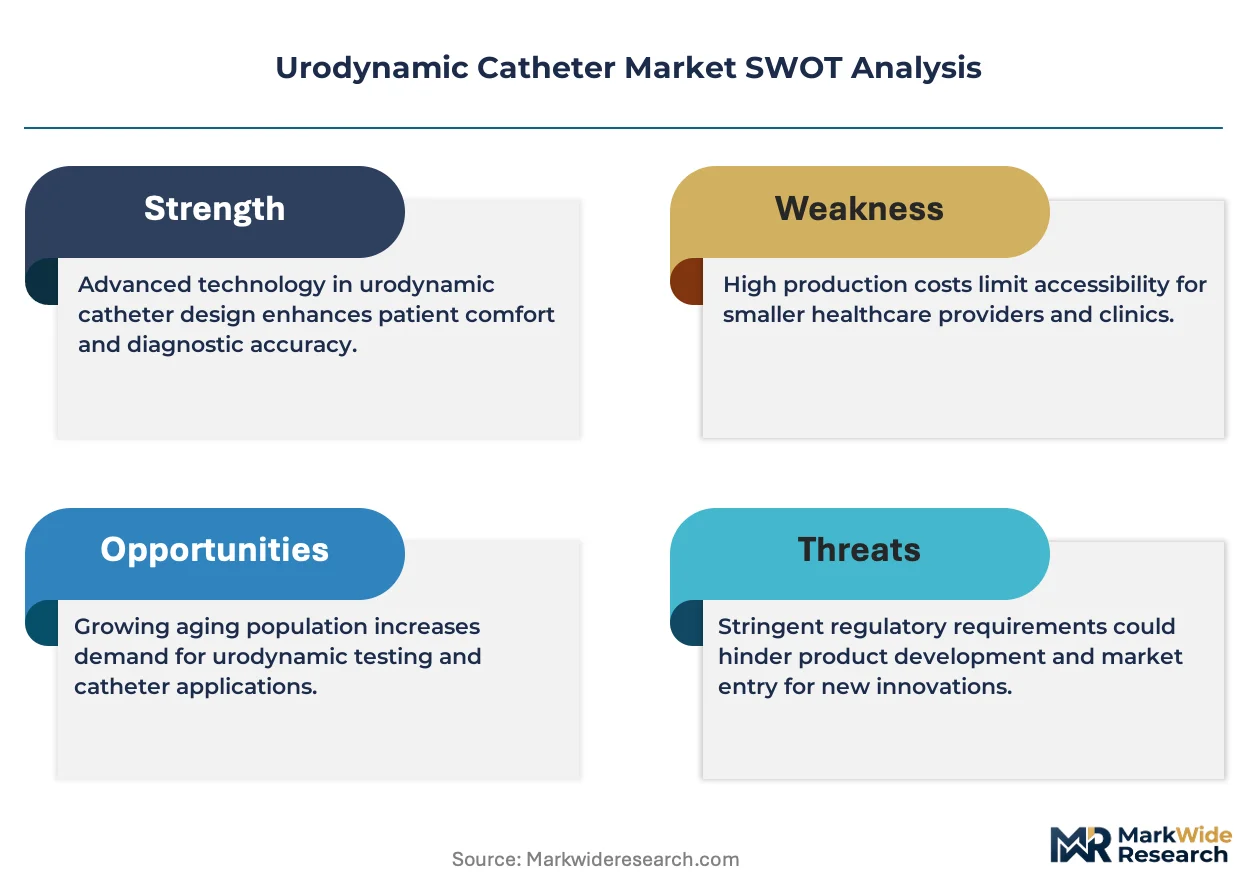
The FDA's 510(k) clearance framework and the EU Medical Device Regulation (MDR) impose divergent clinical evidence requirements, with European notified bodies demanding more extensive biocompatibility documentation for long-dwell sensor materials while the FDA emphasizes substantial equivalence to predicate devices. ISO 13485 quality management certification has become a baseline market-access credential rather than a differentiator, compressing margins for second-tier suppliers unable to absorb audit costs. Stakeholders must monitor how CMS reimbursement adjustments for office-based urodynamic procedures reshape site-of-care economics between hospitals and independent diagnostic centers.
Market Dynamics
Wireless telemetry is compressing the traditional bedside urodynamic workstation into disposable sensor-integrated catheters, forcing capital equipment manufacturers to pivot toward consumable-centric revenue models and software licensing.
Growth Catalysts
- Same-day diagnostic mandates:Hospital outpatient clinics in the United States are expanding ambulatory urology capacity to capture CMS-reimbursed office-based procedures, pulling catheter volume toward higher-margin multi-channel SKUs.
- MDR biocompatibility standards:European notified bodies are enforcing stricter long-dwell sensor material documentation, which paradoxically advantages pre-certified suppliers and accelerates consolidation among compliant manufacturers.
- Aging urology patient pools:Demographic pressure in Germany, Japan, and the United States is expanding the addressable population for pressure-flow studies and neurogenic dysfunction diagnosis.
Market Restraints
- Medical-grade silicone price volatility:Raw material concentration among Asian petrochemical suppliers creates margin compression for catheter manufacturers locked into annual supply contracts.
- Predicate device dependency:FDA 510(k) substantial equivalence requirements limit architectural innovation, as novel sensor geometries must map to cleared legacy designs.
- Reimbursement code fragmentation:Divergent CPT and HCPCS coding for complex versus basic urodynamic studies creates revenue uncertainty that dampens capital commitment from independent diagnostic centers.
Strategic Opportunities
- Home-based ambulatory monitoring:Wireless catheter systems enable natural voiding pattern capture outside clinical settings, opening reimbursement negotiations with private payers for remote diagnostic codes.
- PLI scheme manufacturing:India's production-linked incentive framework for medical devices offers tariff advantages for export-oriented catheter assembly serving Middle Eastern and Southeast Asian markets.
- Sensor-EMG convergence:Integration of pressure transducers with surface electromyography channels creates premium bundled SKUs that command pricing separation from commodity urethral lines.
Industry Challenges
- ISO 13485 audit backlog:Notified body capacity constraints are extending quality management certification timelines, delaying market entry for second-tier suppliers.
- Legacy EMG system incompatibility:Wireless catheter data protocols require middleware development to interface with installed-base urodynamic workstations, adding integration cost and technical risk.
- Cleanroom capacity scarcity:Sterile catheter manufacturing demands Class 7 or better environments, and available square footage concentrates among established contract manufacturers with multi-year client queues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Urodynamic Catheter Market |
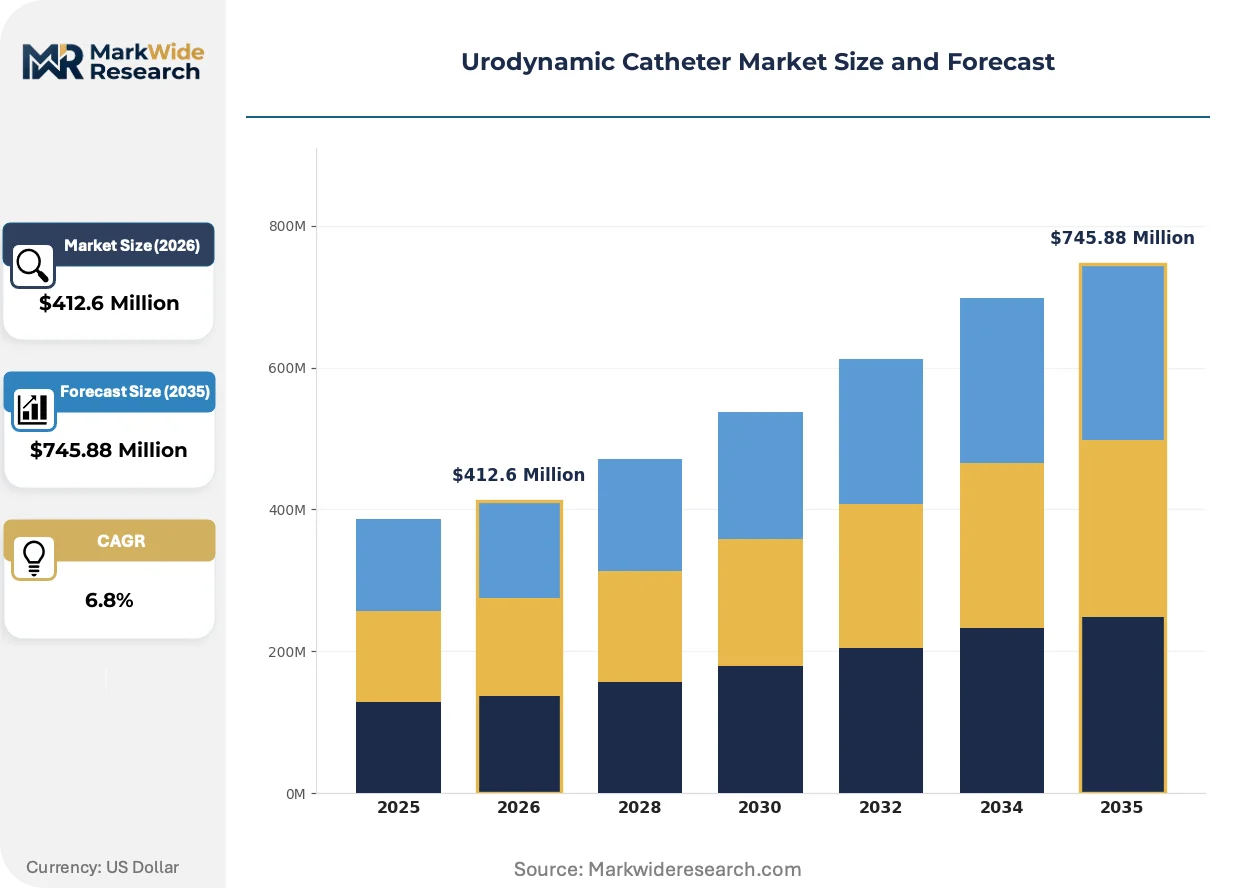
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $745.88 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Urethral Catheters, Suprapubic Catheters, Disposable Catheters, Multi-channel Catheters End User: Hospitals, Clinics, Home Healthcare, Diagnostic Centers Application: Bladder Function Testing, Pressure Measurement, Flow Rate Assessment, Continent Urinary Diversion Technology: Electromechanical Systems, Pressure Sensors, Flow Meters, Wireless Monitoring |
| Companies Covered | Laborie, Cook Medical, Teleflex Incorporated, Digitimer Ltd, Mediplus Ltd, Albyn Medical, CooperSurgical, Medica SpA, Boston Scientific Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Urodynamic Catheter Market Evolving Landscape
Disposable sensor architectures are displacing reusable electromechanical systems across diagnostic urology, with three convergent developments reshaping product roadmaps and procurement criteria.
Micro-electromechanical pressure transducers embedded in catheter tips are hybridizing fluid-filled lumen designs with solid-state sensing, enabling multi-point pressure mapping without column height artifacts. Academic medical centers in the United States and university hospitals in Germany are piloting these platforms for complex voiding dysfunction protocols. The technology is hybridizing competitive positioning, as pure-play sensor suppliers partner with catheter OEMs to displace traditional hydraulic instrumentation.
EU MDR Article 10 technical documentation requirements are expanding clinical evidence thresholds for long-dwell implantable sensors, forcing manufacturers to commission extended biocompatibility studies under ISO 10993-5 and ISO 10993-10 protocols. This regulatory friction is compressing the viable supplier base to firms with dedicated regulatory affairs teams and notified body relationships. High-complexity multi-lumen configurations face the steepest compliance cost escalation, accelerating share concentration among vertically integrated urology portfolios.
Hospital procurement committees are unbundling after-sales service from capital equipment contracts, treating urodynamic catheters as standalone consumable categories with separate vendor qualification. This purchasing behavior is fragmenting supplier relationships, as catheter manufacturers bypass traditional workstation OEM distribution channels to contract directly with materials management. The shift is most visible in United States hospital outpatient departments and German Klinikum networks seeking to standardize across multiple diagnostic platforms.
Urodynamic Catheter Market Segmentation
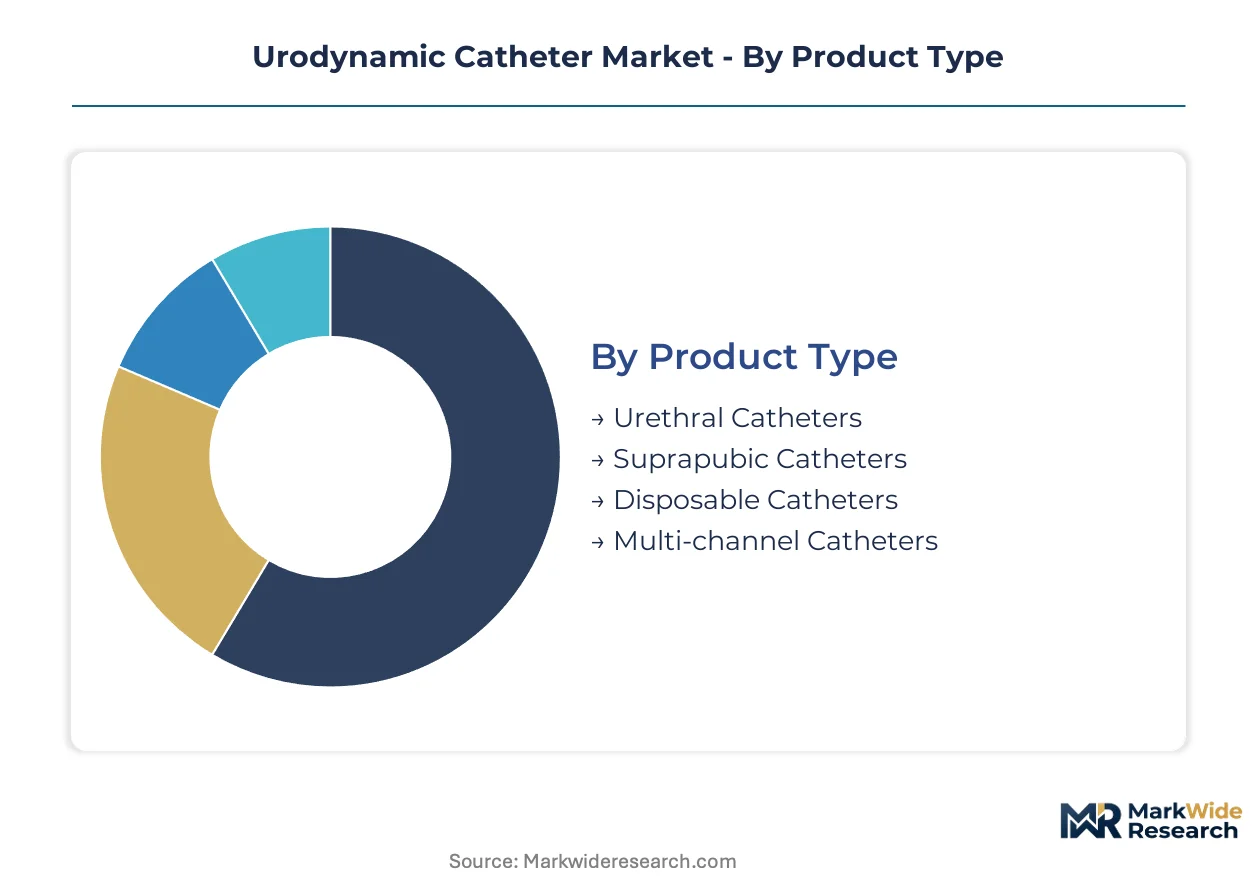
Urodynamic catheter procurement varies sharply across clinical settings, with product architecture, technology integration, and reimbursement environment each filtering which segments capture volume. Manufacturers must align sterile disposable design with site-specific workflow constraints and diagnostic complexity thresholds.
Product Type:
Use-case spectrum spans acute diagnostic precision to chronic indwelling management, with catheter lumen count and dwell duration determining clinical deployment.
- Multi-channel Catheters:These configurations bundle pressure sensing, EMG compatibility, and temperature compensation in a single sterile SKU. Hospital outpatient urology clinics in the United States are standardizing on these platforms for same-day diagnostic protocols that maximize CMS reimbursement per encounter.
- Disposable Catheters:Single-use sterile designs manufactured from medical-grade PVC or polyurethane eliminate cross-contamination protocols. Ambulatory surgery centers favor these for rapid turnover between pressure-flow studies, though per-unit costs accumulate faster than reusable alternatives.
- Urethral Catheters:Transurethral insertion designs remain the default for routine bladder function assessment in general hospital settings.
- Suprapubic Catheters:Percutaneous bladder access configurations serve neurogenic dysfunction patients requiring long-term drainage without urethral trauma.
The dominant share belongs to multi-channel catheters, while disposable catheters are closing the gap fastest.
End User:
Cost tier stratification separates capital-intensive hospital systems from lean independent operators, with reimbursement clarity determining site-of-care migration.
- Hospitals:Academic medical centers and community hospital systems maintain captive urodynamic suites with dedicated electromechanical workstations. These facilities absorb premium multi-channel catheter costs through bundled procedural reimbursement.
- Diagnostic Centers:Independent urodynamic laboratories compete on throughput and payer contract breadth. These operators minimize consumable spend per study while maximizing daily case volume to offset fixed equipment amortization.
- Clinics:Office-based urology practices leverage CMS office-based procedure codes for lower-acuity diagnostic workups.
- Home Healthcare:Post-acute and hospice settings deploy basic urethral lines for chronic drainage management rather than diagnostic pressure studies.
Hospitals retain the deepest penetration, though diagnostic centers are expanding capacity most aggressively.
Application:
Volume concentrates in functional bladder assessment, with complex voiding dysfunction protocols commanding premium positioning against routine flow measurement.
- Bladder Function Testing:Comprehensive cystometric evaluation combining filling sensation, compliance, and detrusor contractility assessment. German university hospitals and United States academic centers are piloting solid-state sensor integration for artifact reduction during natural fill protocols.
- Pressure Measurement:Intravesical and urethral pressure profiling for outlet obstruction quantification. This application demands the highest sensor precision and drives multi-channel catheter specification in tertiary referral centers.
- Flow Rate Assessment:Uroflowmetry studies using catheter-integrated or standalone flow meters for initial screening.
- Continent Urinary Diversion:Specialized protocols for post-surgical neobladder or conduit patients requiring customized catheter geometry.
Bladder function testing holds the largest installed base, while pressure measurement is scaling fastest among complex case referrals.
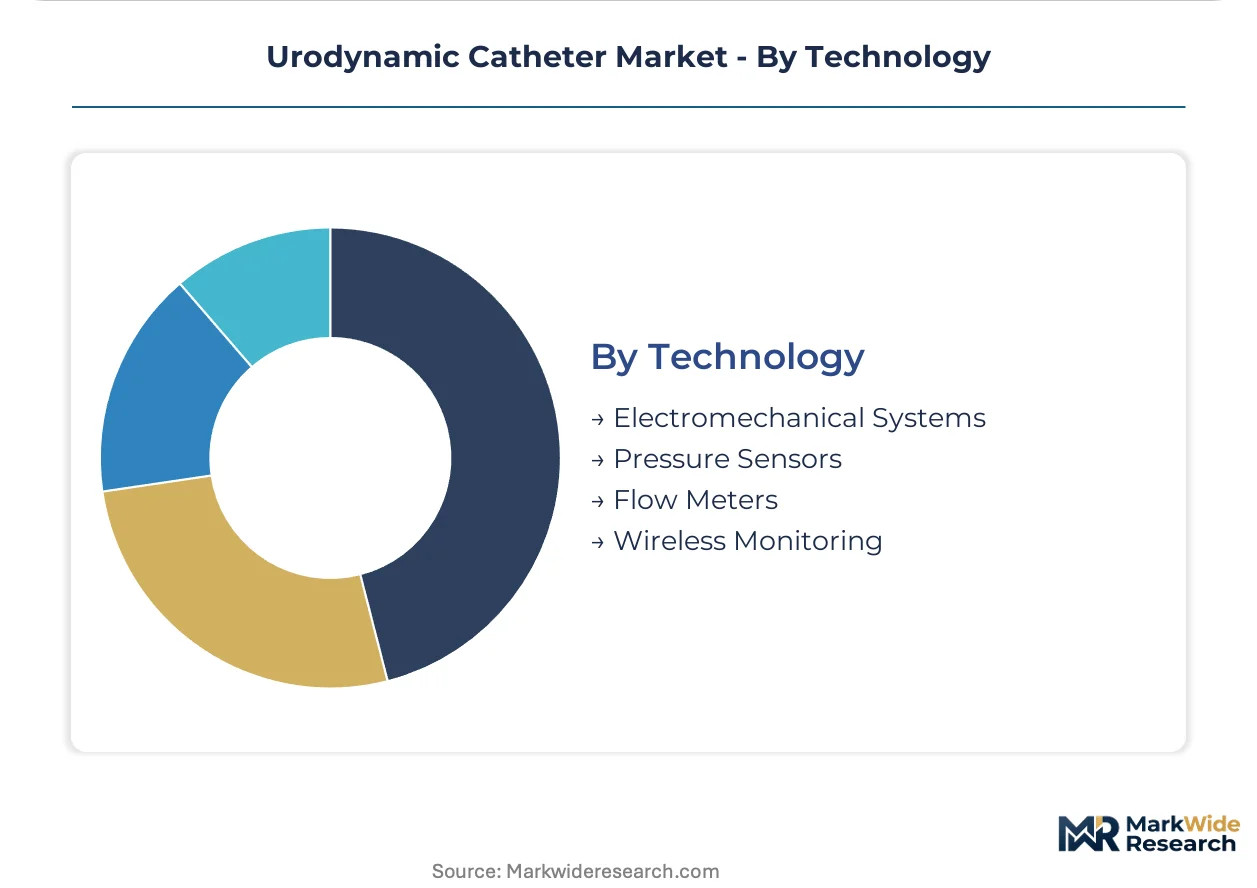
Technology:
Supply concentration in sensor manufacturing and wireless telemetry modules is compressing the viable supplier base to firms with semiconductor partnerships.
- Wireless Monitoring:Telemetry-integrated catheters untether patients from bedside electromechanical systems. United States outpatient clinics and German Klinikum networks are piloting these platforms for ambulatory voiding pattern capture outside traditional clinical environments.
- Pressure Sensors:MEMS-based or fiber-optic transducers embedded at catheter tips enable multi-point pressure mapping without fluid column artifacts. These components hybridize with traditional lumen designs in next-generation platforms.
- Electromechanical Systems:Legacy hydraulic pressure transduction through fluid-filled lumens remains standard in cost-sensitive installations.
- Flow Meters:Gravimetric or rotating disc mechanisms for urine volume and velocity quantification, often paired with pressure channels in integrated diagnostic workstations.
Wireless monitoring commands the steepest expansion trajectory, while pressure sensors are consolidating share through MEMS cost reduction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German catheter manufacturers export precision-engineered multi-lumen configurations to United States hospital systems, while United States-based sensor-integrated platforms serve European ambulatory clinics seeking wireless telemetry compatibility.
United States
Hospital outpatient urology clinics in the United States are expanding same-day diagnostic capacity to capture CMS-reimbursed office-based procedures, pulling volume toward premium multi-channel SKUs. The FDA's updated 510(k) pathway for urological devices compresses time-to-market for sensor-integrated designs. Academic medical centers in Boston and the Research Triangle pilot solid-state pressure transducers for complex voiding dysfunction protocols.
Germany
German university hospitals and Klinikum networks drive demand for artifact-reducing MEMS-based pressure mapping in natural fill cystometry studies. The EU MDR imposes stricter biocompatibility documentation for long-dwell sensor materials, advantaging pre-certified suppliers with dedicated regulatory affairs teams. Manufacturing clusters in Baden-Württemberg and Bavaria concentrate sterile catheter production for export to Middle Eastern and Southeast Asian markets.
Japan
Japan's aging demographic expands the addressable population for neurogenic voiding dysfunction diagnosis and pressure-flow studies in tertiary referral centers. The PMDA's quality management requirements align with ISO 13485 standards, creating streamlined pathways for European and United States manufacturers with existing certifications. Tokyo and Osaka metropolitan areas host concentrated urodynamic diagnostic capacity in university-affiliated hospitals.
India
India's production-linked incentive scheme for medical devices attracts export-oriented catheter assembly operations serving price-sensitive Middle Eastern and African markets. The CDSCO's evolving device registration framework creates compliance differentiation between established importers and domestic manufacturers. Manufacturing investment concentrates in Gujarat and Karnataka special economic zones with tariff advantages for sterile disposable production.
United Kingdom
NHS procurement consolidation favors suppliers with broad urology portfolios capable of bundling catheters with diagnostic workstations and software licensing. The Medicines and Healthcare products Regulatory Agency's post-Brexit alignment with EU MDR technical documentation requirements maintains market access continuity. London and Southeast England academic centers pilot wireless telemetry platforms for ambulatory voiding pattern capture outside traditional clinical settings.
Urodynamic Catheter Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The supplier base concentrates among vertically integrated urology portfolios and focused catheter manufacturers with semiconductor partnerships. Three archetypes dominate: premium diagnostic suite integrators controlling hardware-software workflows; sterile disposable specialists with concentrated manufacturing footprints; and global channel distributors leveraging tender consolidation in European hospital systems. Competitive moves center on backward integration into sensor manufacturing and direct contracting with hospital materials management bypassing traditional OEM distribution.
Within the premium diagnostic suite tier, Laborie and Cook Medical exemplify contrasting strategic positions. Laborie leverages its vertically integrated urology portfolio to control both hardware and software workflows in premium diagnostic suites. Cook Medical anchors North American supply through concentrated manufacturing of multi-lumen configurations for complex pressure-flow studies. Teleflex Incorporated sits within the global channel distribution archetype, competing on density particularly in European hospital systems where tender consolidation favors broad-line distributors.
| Leading Market Players |
|---|
| Laborie |
| Cook Medical |
| Teleflex Incorporated |
| Digitimer Ltd |
| Mediplus Ltd |
| Albyn Medical |
| CooperSurgical |
| Medica SpA |
| Boston Scientific Corporation |
| Others |
Value Network & Pricing Analysis
Medical-grade silicone price volatility originating from Asian petrochemical suppliers compresses margin pools across all catheter tiers while simultaneously forcing manufacturers toward multi-source qualification strategies and regional assembly diversification. This input-cost uncertainty widens spreads between premium sensor-integrated SKUs and commodity urethral lines, as only vertically integrated portfolios can absorb raw material swings without destabilizing tiered pricing architectures.
Pricing Analysis
Electromechanical-to-wireless generational pricing gaps separate legacy hydraulic systems from MEMS-embedded premium platforms and emerging telemetry-native designs. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) certification depth, with ISO 13485-plus-MDR dual-compliant suppliers commanding 40-60% spreads over single-certification competitors. Pricing pressure stems from tender consolidation in German Klinikum networks and NHS procurement frameworks that bundle catheters with workstation service contracts. Ambulatory surgery centers exhibit highest price sensitivity due to per-case reimbursement caps, while academic medical centers prioritize artifact-reducing sensor precision over unit economics.
Supply Chain Analysis
Export-control restrictions on MEMS pressure transducer manufacturing equipment limit technology transfer to emerging production hubs, concentrating high-precision sensor supply among established semiconductor foundries in Germany, Japan, and the United States. Raw material flows draw from medical-grade silicone producers in South Korea and China, polyurethane resin specialists in Belgium and the Netherlands, and precision extrusion equipment fabricators in Switzerland and Italy. Single-source vulnerability concentrates in Class 7 cleanroom capacity, where multi-year client queues at established contract manufacturers create allocation bottlenecks for second-tier catheter OEMs. Distribution runs through GPO contracts in United States hospital systems, direct tender participation in German Klinikum networks, and broad-line distributors serving European hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of qualified regulatory affairs capacity combined with extended ISO 13485 audit timelines creates a structural bottleneck that favors incumbents with dedicated notified body relationships and punishes aspirants lacking compliance infrastructure.
For Market Incumbents: Pre-empt wireless telemetry commoditization by capturing exclusive sensor-EMG convergence IP and locking multi-year GPO contracts before next-generation platforms reach price parity. Defend margin position through backward integration into MEMS transducer manufacturing, eliminating semiconductor partner dependency that emerging players cannot replicate. Threat vector: pure-play sensor suppliers partnering with catheter OEMs to displace hydraulic instrumentation. For New Entrants and Emerging Players: Build out sterile disposable manufacturing in India's PLI scheme special economic zones, leveraging tariff advantages to serve price-sensitive Middle Eastern and African markets before established suppliers relocate capacity. Target diagnostic centers in United States secondary metros where reimbursement code fragmentation has dampened capital commitment from incumbent suppliers. Go-to-market angle: unbundled consumable pricing that bypasses traditional workstation OEM distribution channels. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors sensor-integrated platform specialists over legacy hydraulic equipment manufacturers. Long-term viability centers on semiconductor partnership depth and software workflow integration rather than standalone catheter manufacturing scale. Acquisition target archetype: catheter OEMs with captive regulatory affairs teams and notified body relationships that compress time-to-market for MDR-compliant designs. Signal to watch: CMS reimbursement adjustments for remote diagnostic codes that would validate home-based ambulatory monitoring business models.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-EMG Convergence Development | Creates premium bundled SKUs commanding pricing separation from commodity urethral lines in tertiary referral centers. |
| MDR Dual-Certification Investment | Compresses viable supplier base to firms with dedicated regulatory affairs teams and notified body relationships. |
| PLI Scheme Manufacturing Buildout | Offers tariff advantages for export-oriented catheter assembly serving Middle Eastern and Southeast Asian markets. |
| Direct Hospital Materials Management Contracting | Bypasses traditional workstation OEM distribution channels fragmented by procurement committee unbundling behavior. |
| Wireless Telemetry Reimbursement Strategy | Opens private payer negotiations for remote diagnostic codes validating home-based ambulatory monitoring platforms. |
Research Methodology
Cross-validation between hospital procurement database analysis and clinician workflow observation anchors the qualitative findings on site-of-care migration and catheter specification trends. Primary interviews with urology department heads, biomedical engineering directors, GPO contracts managers, and sterile processing supervisors combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital capital equipment procurement records. Bottom-up demand modeling triangulates against top-down market sizing across product type, end user, application, and technology segmentation dimensions.
Calibration against historical procedure volume trajectories and reimbursement code utilization patterns shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include catheter lumen count, site-of-care setting, diagnostic complexity tier, sensor technology generation, and regional regulatory cluster. CAGRs derive from fitted growth curves applied to procedure volume forecasts adjusted for technology substitution elasticities. Industry-specific inputs incorporate CMS office-based procedure code expansion timelines and EU MDR notified body capacity constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pure-play sensor suppliers or contract manufacturing consolidators would shift outcomes beyond modeled ranges. Material shifts in FDA 510(k) substantial equivalence requirements or CMS reimbursement adjustments for wireless diagnostic platforms would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Tracheobronchial Stent Grafts Market
Medical Devices
Middle East and Africa Sleep Apnea Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
South Korea Minimally Invasive Surgery Devices Market
Medical Devices
Asia-Pacific Viscosupplementation Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Laparoscopic Surgical Robot Market
Medical Devices
United States Aesthetic Devices Market
Medical Devices
Pulmonology Devices Market
Medical Devices
Removable Partial Dentures Market
Medical Devices
Tracheobronchial Suction Catheters Market
Medical Devices
Creatinine Meter Market
Medical Devices
Asia-Pacific Medical Device Regulatory Affairs Market
Medical Devices
Intelligent Electronic Sphygmomanometers Market
Medical Devices
Transcutaneous Oximetry Systems Market
Medical Devices
C-Arms Devices Market