
 Invisible Orthodontics Market | 2026-2036
Invisible Orthodontics Market Size, Share, and Industry Trends Forecast 2026-2036
Invisible Orthodontics Market Intelligence
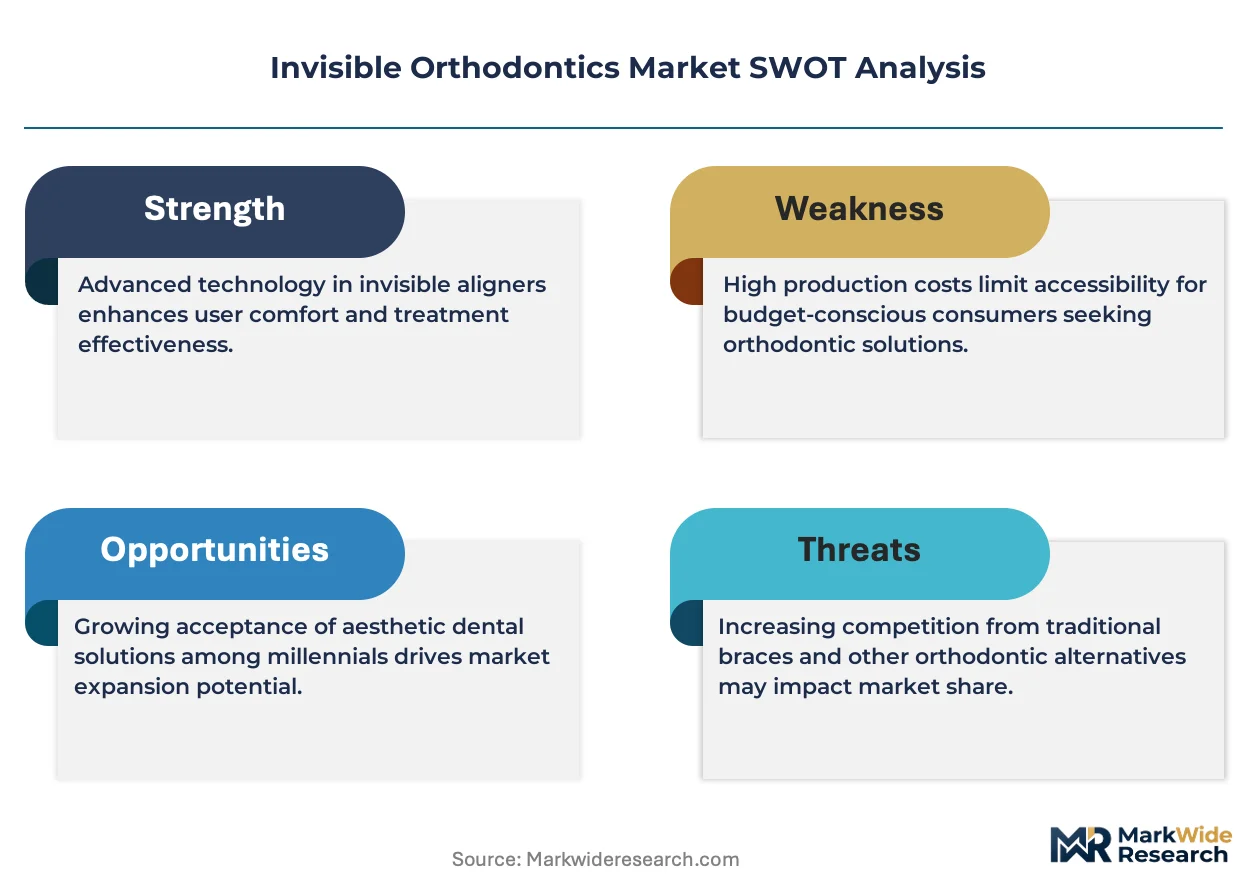
The historical monopoly of orthodontists on complex case planning is unwinding as digital workflows empower general practitioners. Align Technology leverages its vast clinical database and first-mover advantage in the clear aligner space. In contrast, Angel Aligner competes aggressively on price and service in Asian markets, building a significant regional presence. Envista Holdings positions its Spark aligner system as a premium alternative for orthodontist-led treatment plans.
Invisible orthodontics refers to a category of dental appliances designed to straighten teeth with minimal aesthetic impact during treatment. These systems use either a series of custom-made, transparent polymer aligners or fixed brackets mounted on the lingual surface of the teeth. Clear aligners represent the fastest-growing product type, capturing share from traditional braces due to patient preference. While orthodontists remain the primary end-user channel, dental clinics are an expanding frontier for simpler teeth alignment cases.
Market access hinges on regulatory clearance for medical devices, governed by bodies like the US FDA, China's NMPA, and requirements for CE marking in Europe. These regulations mandate clinical data to support safety and efficacy claims, creating significant barriers to entry for new manufacturers. Future competitive differentiation will depend on navigating the evolving landscape of remote monitoring services and direct-to-consumer business models.
Market Dynamics
The decentralization of orthodontic treatment planning represents the central force shaping the market. Digital imaging, treatment simulation software, and 3D printing are enabling general dental practitioners to manage cases historically reserved for specialist orthodontists, broadening the provider base.
Growth Catalysts
- Advances in 3D Printing:The use of advanced stereolithography and digital light processing enables the mass-customized production of clear aligners with high precision, reducing manufacturing time and costs for producers while improving the fit for patients.
- Aesthetic Dental Demand:A rising focus on personal appearance and discretionary income, particularly within the middle class in countries like China and Brazil, drives patient demand for less conspicuous teeth straightening solutions over traditional metal braces.
- Cosmetic Dentistry Expansion:General dental clinics are actively expanding their service menus to include cosmetic procedures like clear aligners, creating a new and rapidly growing distribution channel that complements the traditional orthodontist-led model.
Market Restraints
- Regulatory Scrutiny:Stringent regulatory pathways for medical devices, such as the US FDA's 510(k) clearance process and China's NMPA registration, create high entry barriers and extend time-to-market for new aligner systems.
- High Treatment Cost:The premium price of invisible orthodontic treatments compared to conventional braces limits affordability and access for a significant portion of the potential patient population, particularly in developing economies without private insurance coverage.
- Clinical Limitations:While effective for mild to moderate cases, clear aligners face technical limitations in treating severe malocclusions, such as significant tooth extractions or surgical cases, which still require traditional orthodontic appliances.
Strategic Opportunities
- Teledentistry Integration:Incorporating AI-powered remote monitoring platforms allows for fewer in-office appointments, improving patient convenience and enabling dental professionals to manage a larger patient base more efficiently, opening new service revenue streams.
- Underpenetrated Geographic Markets:Significant growth potential exists in markets across Southeast Asia and Latin America, where orthodontic penetration is low but consumer awareness and demand for aesthetic treatments are increasing rapidly.
- Material Science Innovation:Development of next-generation thermoplastic materials that can provide more consistent force application over time and offer better stain resistance presents a key avenue for product differentiation and improved clinical outcomes.
Industry Challenges
- Intellectual Property Litigation:The market is characterized by frequent and costly patent disputes surrounding aligner design, manufacturing processes, and digital treatment planning software, creating legal risks for both established companies and new entrants. *Digital Workflow Training Gap: A shortage of orthodontists and general dentists proficient in using the complex digital tools for intraoral scanning, treatment simulation, and case management creates a bottleneck for wider technology adoption.
- Data Interoperability:A lack of standardization between different digital scanner and software platforms creates friction for dental practices, complicating workflows and limiting the ability to seamlessly switch between different aligner systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Invisible Orthodontics Market |
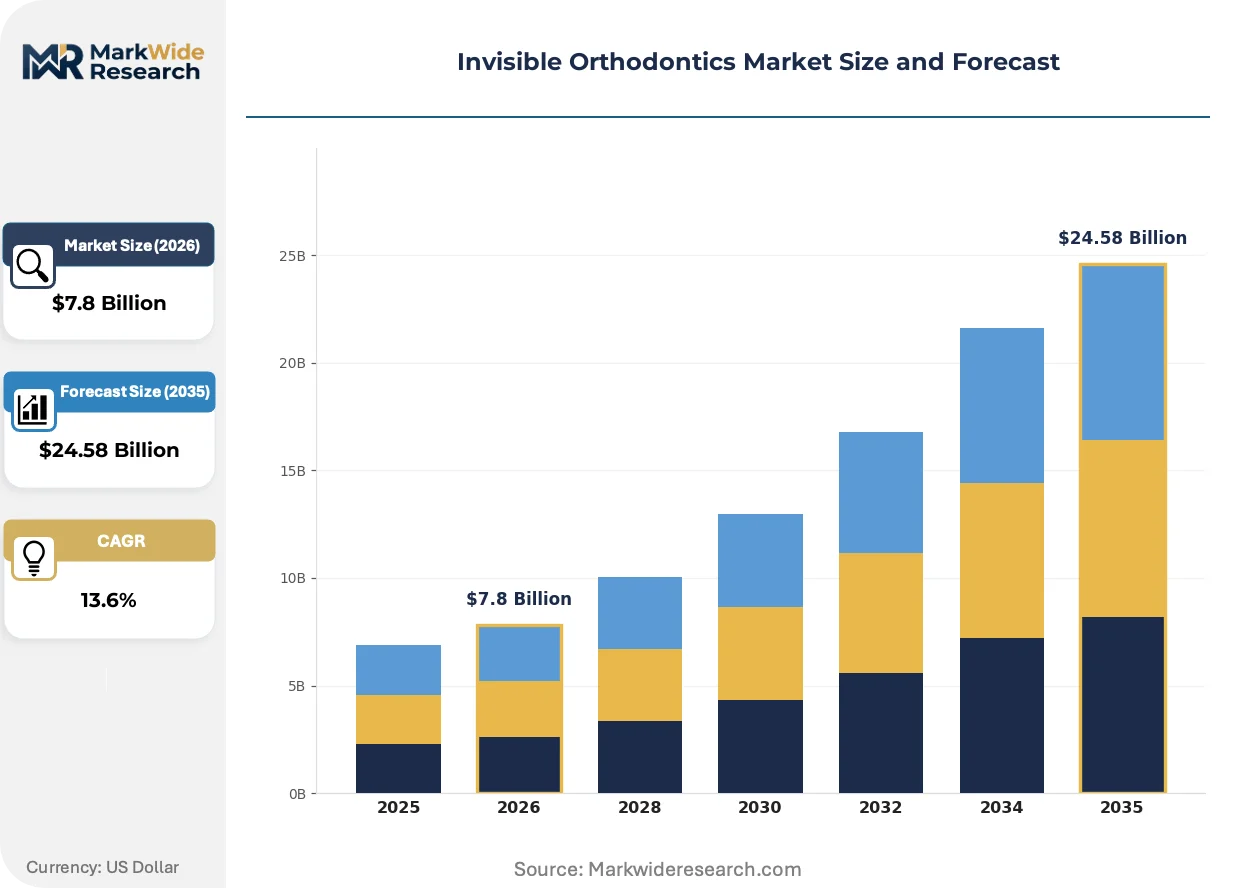
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.58 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clear Aligners, Lingual Braces, Ceramic Braces, Self-Ligating Braces, Retainers Application: Teeth Alignment, Overbite Correction, Underbite Treatment, Crossbite Adjustment, Teeth Whitening Enhancement End User: Orthodontists, Dental Clinics, Dental Laboratories, Cosmetic Dentists, Dental Hospitals Service Type: In-Office Treatment, Remote Monitoring, Consultation, Maintenance Services, Follow-Up Care |
| Companies Covered | Align Technology, Dentsply Sirona, Envista Holdings, Solventum Corporation, Angel Aligner, Institut Straumann AG, SCHEU DENTAL GmbH, SmileDirectClub, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Invisible Orthodontics Market Strategic Shifts & Innovations
The convergence of advanced material science, patient-centric digital platforms, and evolving regulatory frameworks is fundamentally altering the competitive landscape. This shift democratizes access to orthodontic care while simultaneously raising the bar for clinical efficacy and product differentiation.
Technology and Product Evolution
Proprietary multilayer polymers are a key area of innovation, designed to provide a more flexible yet consistent application of force for tooth movement. Orthodontists and premium-focused dental groups are rapidly adopting these advanced materials to achieve more predictable clinical outcomes and reduce treatment times. This focus on material science is supplanting reliance on generic, single-layer plastics, creating a new axis of competition.
Regulatory and Policy Shifts
Europe's Medical Device Regulation (MDR) mandates more rigorous clinical evidence and post-market surveillance for all medical devices, including clear aligners. This directive increases the compliance burden, demanding substantial investment in clinical trials and quality management systems to obtain or maintain a CE marking. Consequently, smaller manufacturers and new market entrants face significant hurdles, potentially leading to market consolidation around players with greater regulatory resources.
Demand-Side and Behavioral Shifts
A notable shift toward teledentistry-supported treatment models is gaining traction for mild-to-moderate alignment cases. This model disrupts the traditional cycle of frequent in-person appointments by leveraging digital tools for remote consultations and progress monitoring. This consumer-driven preference for convenience and accessibility is most visible in North American and European markets, especially among younger, digitally native patient demographics.
Invisible Orthodontics Market Segmentation
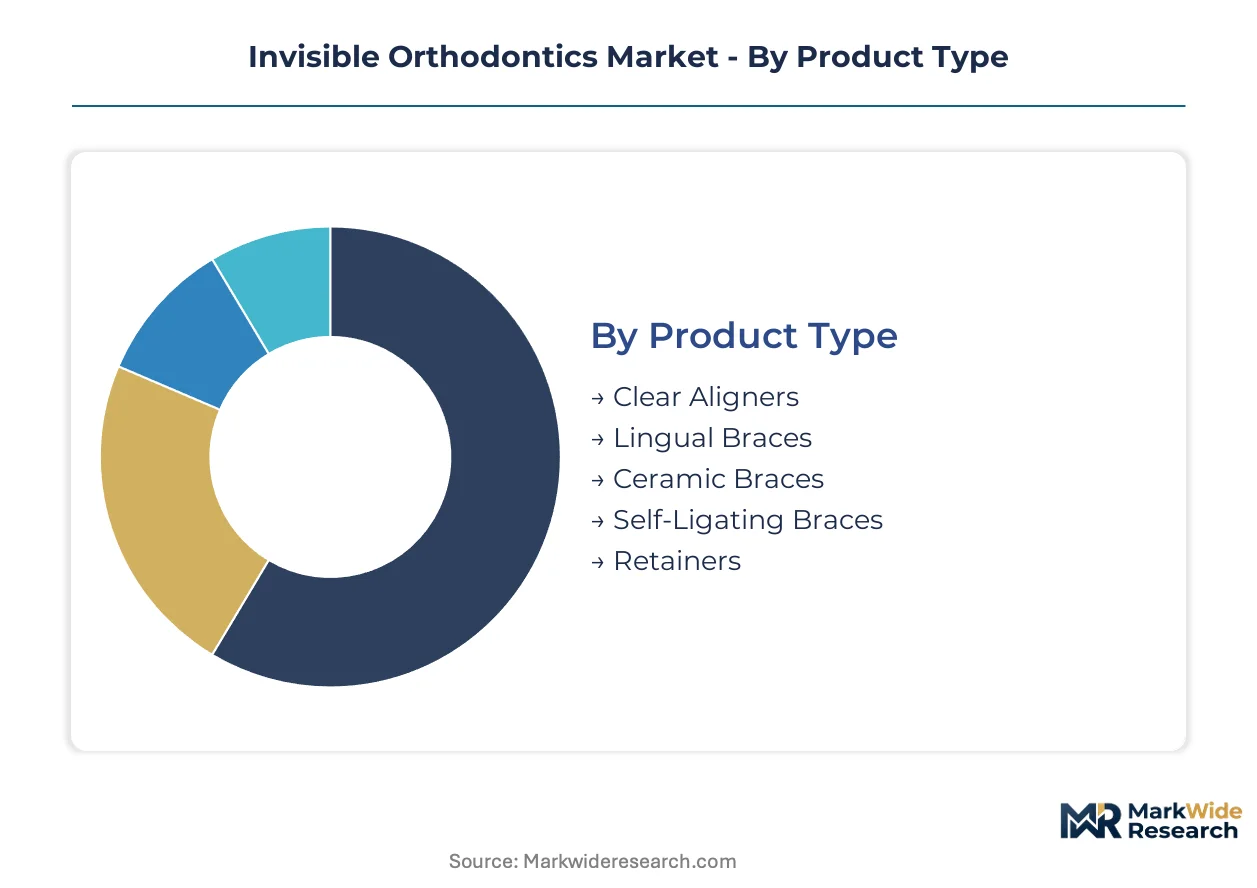
Market segmentation provides a granular view of the invisible orthodontics landscape, revealing distinct product preferences, end-user behaviors, and service delivery models. Understanding these categories is crucial for identifying growth pockets and tailoring product development to specific market needs.
Product Type:
Margin pools in product type segmentation are concentrated within advanced material solutions.
- Clear Aligners:These are custom-made, transparent thermoplastic trays designed to gradually shift teeth into desired positions. Demand is concentrating in China, driven by a growing middle class seeking aesthetic dental solutions.
- Lingual Braces:Fixed orthodontic appliances are bonded to the back surface of the teeth, offering a completely invisible treatment option. Demand for these premium solutions is stable among patients prioritizing absolute discretion.
- Ceramic Braces:These use tooth-colored or clear brackets and wires, providing a less conspicuous alternative to traditional metal braces.
- Self-Ligating Braces:These fixed braces use a built-in clip mechanism to hold the archwire, reducing friction and potentially treatment time.
- Retainers:Custom-made devices are worn after orthodontic treatment to maintain the corrected tooth position and prevent relapse.
Lingual Braces holds installed capacity. Clear Aligners is rotating up the share rankings.
Application:
Application segmentation highlights the functional areas driving patient engagement.
- Teeth Alignment:This primary application addresses general malocclusions and aesthetic concerns by straightening misaligned teeth. Patient preference in North America and Europe favors less visible methods for minor to moderate corrections.
- Overbite Correction:These treatments address cases where the upper front teeth significantly overlap the lower front teeth. Digital treatment planning software aids in precise force application for these specific cases.
- Underbite Treatment:This application focuses on correcting conditions where the lower front teeth extend out in front of the upper front teeth.
- Crossbite Adjustment:This involves correcting situations where upper teeth bite inside lower teeth, requiring specific aligner designs for effective movement.
- Teeth Whitening Enhancement:While not a primary function, aligner trays can sometimes be used to facilitate professional teeth whitening alongside orthodontic treatment.
Teeth Alignment represents the fastest-growing trajectory for patient demand.
End User:
Customer type differentiation reveals the primary channels for treatment delivery.
- Orthodontists:These specialists are trained to diagnose, prevent, and treat dental and facial irregularities, managing complex cases with invisible orthodontic systems. They remain the primary channel for premium aligner systems like Envista Holdings' Spark.
- Dental Clinics:General dental practitioners increasingly offer clear aligner treatments for simpler cases, expanding their service offerings beyond traditional procedures. This channel is growing rapidly in urban centers across China.
- Dental Laboratories:These facilities manufacture custom aligners and other orthodontic appliances based on prescriptions from dental professionals.
- Cosmetic Dentists:These practitioners focus on improving the appearance of teeth and smiles, integrating invisible orthodontics into broader aesthetic treatment plans.
- Dental Hospitals:These institutions provide comprehensive dental care, including orthodontic services, often handling a mix of routine and complex cases.
Orthodontists maintain the largest share of patient volume, while Dental Clinics are expanding most quickly.
Service Type:
Service type maturity defines the operational models gaining traction among practitioners.
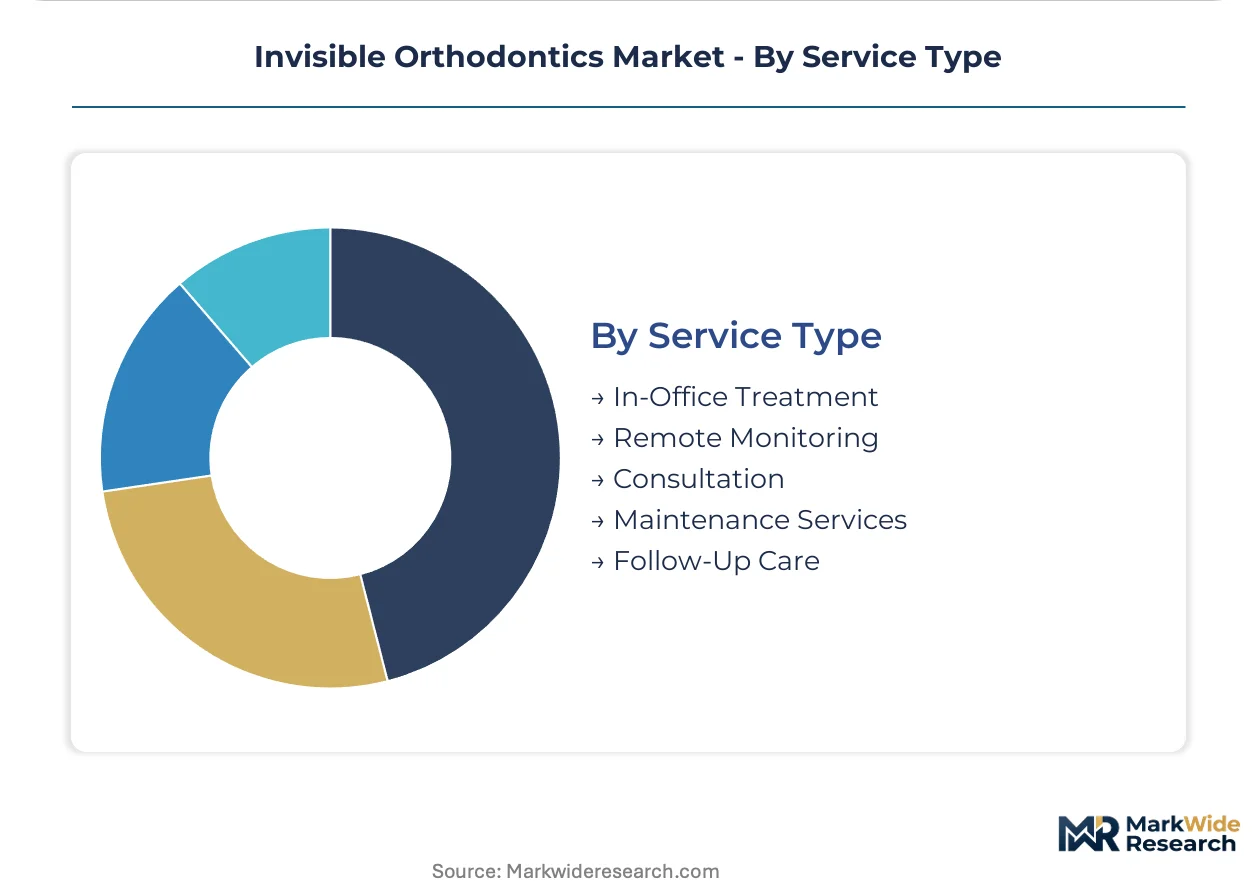
- In-Office Treatment:This traditional model involves regular appointments at a dental practice for adjustments and progress monitoring. It remains the standard for complex orthodontic cases requiring direct professional oversight.
- Remote Monitoring:This service leverages digital platforms and AI to track patient progress between fewer in-office visits, enhancing convenience. This model is gaining significant traction in North American and European markets.
- Consultation:Initial appointments involve diagnosis, treatment planning, and discussion of options with the patient before treatment initiation.
- Maintenance Services:These include post-treatment care, such as retainer checks and adjustments, to ensure long-term stability of orthodontic results.
- Follow-Up Care:Regular post-treatment visits monitor tooth stability and overall oral health after the active phase of orthodontics.
In-Office Treatment secures the majority of existing service revenue, with Remote Monitoring climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The invisible orthodontics market exhibits a notable pricing-power asymmetry, with premium solutions dominating North American and European markets while aggressive price competition defines Asian regions. This regional divergence reflects varying disposable incomes, regulatory landscapes, and patient preferences for aesthetic dental treatments. Strategic investments in digital infrastructure and teledentistry solutions are reshaping market access across these geographies.
United States
Aesthetic dental demand and high disposable incomes drive significant clear aligner adoption across the United States. The US FDA's 510(k) clearance process mandates rigorous clinical data, creating substantial market entry barriers for new aligner systems. Silicon Valley's innovation ecosystem fosters rapid development of teledentistry platforms and AI-powered remote monitoring solutions.
Germany
Germany shows strong demand for premium invisible orthodontic solutions, valuing precision engineering and predictable clinical outcomes. Europe's Medical Device Regulation (MDR) imposes stringent clinical evidence and post-market surveillance requirements for CE marking. The medical technology cluster in Bavaria, particularly around Munich, leads innovation in proprietary multilayer polymer development for aligner systems.
China
China's expanding middle class fuels substantial demand for aesthetic dental solutions, driving rapid growth in clear aligner adoption. China's NMPA registration requirements present a significant regulatory hurdle for foreign manufacturers entering this competitive market. Urban centers like Shanghai and Beijing are witnessing a rapid expansion of general dental clinics offering invisible orthodontics for simpler cases.
Brazil
Brazil experiences rising demand for less conspicuous teeth straightening, driven by increasing discretionary income and focus on personal appearance. The country's national health regulatory agency mandates specific approvals for medical devices, influencing market access for aligner systems. In São Paulo, the private dental sector actively integrates digital imaging and 3D printing technologies to enhance invisible orthodontic treatment.
India
India's urban population and rising incomes contribute to a growing interest in cosmetic dentistry, including invisible orthodontic treatments. The CDSCO regulates medical devices, requiring local clinical data and manufacturing compliance for market authorization. The Delhi-NCR region, with its expanding private healthcare infrastructure, shows a notable increase in dental clinics offering clear aligner solutions.
Invisible Orthodontics Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the invisible orthodontics market. The market exhibits a tiered structure, with established global players focusing on premium innovation and regional specialists competing on aggressive pricing. Strategic archetypes include vertically integrated solution providers, specialized material science innovators, and digitally-focused service platforms. Companies primarily pursue strategic partnerships for technology co-development and geographic expansion into underpenetrated markets.
Within the premium innovation archetype, Align Technology exemplifies a global leader leveraging extensive clinical data and established market presence for advanced clear aligner solutions. Envista Holdings occupies a position catering to orthodontist-led treatment plans with its premium Spark aligner system, emphasizing clinical predictability and professional oversight. Angel Aligner, conversely, represents a regional specialist archetype, building significant presence through aggressive price and service strategies, particularly in Asian markets and other cost-sensitive regions. These players collectively illustrate the diverse competitive approaches defining the invisible orthodontics landscape.
| Leading Market Players |
|---|
| Align Technology |
| Dentsply Sirona |
| Envista Holdings |
| Solventum Corporation |
| Angel Aligner |
| Institut Straumann AG |
| SCHEU DENTAL GmbH |
| SmileDirectClub |
| 3M |
Cost & Logistics Intelligence
Europe's Medical Device Regulation (MDR) mandates rigorous clinical evidence, gating both aligner system supply qualification and influencing price differentiation for compliant products.
Pricing Analysis
Significant price asymmetry characterizes the invisible orthodontics market, with premium solutions dominating North America and Europe while aggressive price competition defines Asian regions. The market operates on a tiered pricing structure, with premium offerings from companies like Align Technology commanding higher prices due to brand and proprietary multilayer polymers. Aggressive price competition from regional specialists like Angel Aligner, particularly in Asian markets, creates downward pricing pressure. Patients in developing economies without private insurance coverage exhibit the highest price sensitivity, contrasting with lower sensitivity in affluent Western markets.
Supply Chain Analysis
Managing inventory and lead times for custom-made clear aligners presents a unique supply chain challenge, given the mass customization requirements. The supply chain for invisible orthodontics draws heavily from specialized manufacturers in China for high-volume production, while material science innovation often centers in regions like Germany. Key dependencies include advanced thermoplastic polymers and 3D printing resins. A significant supply chain risk involves intellectual property litigation surrounding aligner designs and manufacturing processes. Distribution runs primarily through direct channels to orthodontists and general dental clinics, with some direct-to-consumer models emerging for simpler cases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The invisible orthodontics market faces a critical bottleneck in the widespread adoption of digital workflows, highlighting a scarcity of proficient dental professionals.
For Market Incumbents:Fortify market position by investing heavily in next-generation thermoplastic materials and expanding clinical data for complex malocclusions. This counters aggressive price competition from regional players and addresses regulatory scrutiny for efficacy claims. Incumbents must also deepen channel control through exclusive partnerships with orthodontists, leveraging their established trust. Continuous R&D in AI-powered treatment planning further strengthens their premium offering.
For New Entrants and Emerging Players:Anchor in underpenetrated geographic markets like Southeast Asia and Latin America, targeting the rapidly expanding general dental clinic segment. Focus on simpler teeth alignment cases where clinical limitations of clear aligners are less pronounced. A compelling go-to-market angle involves offering cost-effective aligner systems bundled with comprehensive digital workflow training for general practitioners. Emphasize teledentistry integration to improve patient convenience and reduce overhead for clinics.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting upwards across the clear aligner manufacturing sub-segment due to R&D in advanced materials and digital infrastructure. The market demonstrates strong long-term viability for aesthetic dental solutions over the next decade. Acquisition targets should prioritize vertically integrated material science innovators or AI-powered teledentistry platforms with established regulatory clearances. The signal to watch is the pace of regulatory approvals for novel materials or remote monitoring solutions, indicating market readiness for next-generation offerings.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Proprietary Multilayer Polymers | Enhances clinical outcomes and differentiation against generic clear aligners. |
| Expand Teledentistry Platforms | Improves patient convenience and broadens market access for remote monitoring services. |
| Secure NMPA/FDA Clearances | Unlocks access to major growth markets like China and the United States. |
| Partnership with Dental Clinics | Expands distribution channels beyond traditional orthodontists for simpler cases. |
| Develop AI-powered Treatment Planning | Increases precision and efficiency in case management for dental professionals. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary validation. Primary data involved discussions with orthodontists, dental clinic owners, material scientists, and regulatory experts across key geographies. Secondary sources included SEC filings of public companies, medical device registries from US FDA and China NMPA, industry association reports, and peer-reviewed academic journals. This approach enabled robust bottom-up and top-down triangulation of market estimates.
The forecast framework projects market dynamics across the analysis window, utilizing a robust quantitative model. Segmentation dimensions modeled included product type, application, end user, service type, and regional adoption patterns. Compound annual growth rates were derived from historical trends, future projections of technology adoption, and economic indicators. Key forecast inputs included advancements in 3D printing technology and the expansion of cosmetic dentistry services.
Material uncertainties — including evolving regulatory landscapes and unexpected shifts in consumer preferences — sit outside the modeled envelope. Forecasts reflect assumptions regarding current market conditions and technology trajectories. Revision becomes warranted when significant technological breakthroughs or major policy changes cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global IV Infusion Pump Accessories Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Controlled-Release Drug Delivery Technology Market
Medical Devices
Continuous Positive Airway Pressure (CPAP) Interface Devices Market
Medical Devices
Rapid Infuser Market
Medical Devices
Global Automatic Stair Climbing Wheelchair Market
Medical Devices
Global Corneal Topographers Market
Medical Devices
Global Medical Device Connectors Market
Medical Devices
North America Renal Denervation Devices Market
Medical Devices
Elastomeric Infusion Pump Market
Medical Devices
Powered Wheelchair Market
Medical Devices
Smart Medical Loupes Market
Medical Devices
Italy Aesthetic Devices Market
Medical Devices
Tissue Embedding Center Market
Medical Devices
Europe Organ Preservation Market
Medical Devices
Wearable Pulse Oximeters Market