
 Plastic Antioxidants Market | 2026-2036
Plastic Antioxidants Market Size, Share, and Industry Trends Forecast 2026-2036
Plastic Antioxidants Market Intelligence
The substitution of traditional metal components with high-performance engineering plastics in automotive applications is hardening the requirement for advanced thermal stabilizers. BASF SE leverages its chemical synthesis capabilities to offer a broad portfolio for diverse polymer systems. Songwon Industrial Co. Ltd. specializes in polymeric antioxidants, providing long-term heat stability for demanding end uses. Evonik Industries AG competes through its focus on specialty phosphites and blends for process stabilization.
Plastic antioxidants are chemical additives that inhibit the oxidation of polymers, a process initiated by heat, light, or mechanical stress. These compounds function as radical scavengers or peroxide decomposers, preserving material properties like strength and color. Hindered phenols and phosphites represent the largest product type segments, serving as primary and secondary antioxidants, respectively. In applications, packaging films demand high-purity grades for food contact compliance, while automotive parts require superior long-term thermal stability.
Product formulation and market access are governed by regulations like Europe's REACH framework and the US EPA's Toxic Substances Control Act. In Asia, China's GB standards and Japan's Chemical Substances Control Law impose strict requirements on new chemical registrations and food-contact material safety. Navigating these divergent regional compliance pathways while developing cost-effective, high-performance formulations remains a central strategic challenge for manufacturers.
Market Dynamics
The market's central dynamic is the tension between the push for circular economy models, which increases the use of thermally degraded recycled polymers, and the pull from stringent chemical safety regulations like REACH and TSCA, which restrict certain stabilizer chemistries.
Growth Catalysts
- Automotive Lightweighting:The replacement of metal in under-hood components with engineering plastics necessitates advanced antioxidants to ensure long-term thermal stability against engine heat and oxidative environments.
- Recycled Content Mandates:Policies in Europe and parts of North America requiring minimum post-consumer recycled (PCR) content in packaging and durable goods drive demand for stabilizers to restore the processing and service life properties of reclaimed polymers.
- Food Packaging Evolution:Advances in flexible and rigid packaging for extended shelf life require high-purity, low-migration antioxidant grades that comply with strict food-contact regulations from bodies like the FDA and EFSA.
Market Restraints
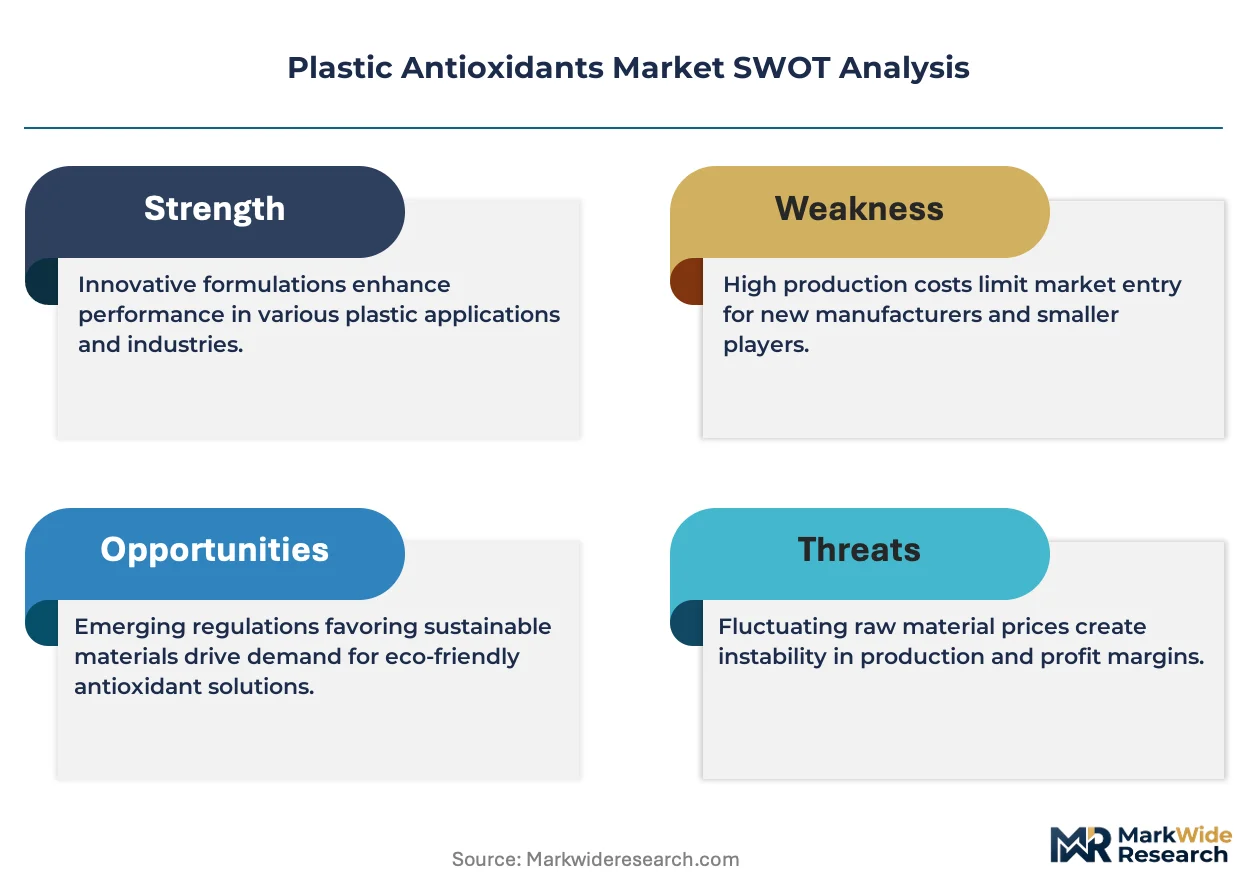
- Raw Material Volatility:The cost of key precursors like phenol and phosphorus derivatives is directly linked to fluctuating petrochemical feedstock prices, creating unpredictable manufacturing costs and margin pressure.
- Regulatory De-selection:Continuous evaluation of chemical substances under frameworks like REACH can lead to the reclassification or restriction of established antioxidants, forcing costly and time-consuming reformulations.
- Substitution by Polymer Producers:Some integrated resin manufacturers are developing and marketing pre-stabilized polymer grades, which can reduce the addressable market for standalone antioxidant compounders and masterbatchers.
Strategic Opportunities
- Bio-Based Antioxidants:Developing and commercializing antioxidants derived from renewable sources, such as tocopherols (Vitamin E) or lignin, addresses market demand for sustainable additives in green plastics. *Synergistic Blends: Creating customized "one-pack" systems that combine primary (hindered phenol) and secondary (phosphite) antioxidants offers enhanced performance and processing efficiency for specific applications like polyolefin films.
- High-Heat Electronics:The build-out of 5G infrastructure and electric vehicle battery systems creates new demand for stabilizers in polymers used for connectors, casings, and insulation that must resist high thermal loads.
Industry Challenges
- Global Compliance Harmonization:Managing a product portfolio that meets the divergent and evolving food-contact and chemical registration requirements of the US EPA, ECHA in Europe, and China's SAMR is a major technical and administrative hurdle.
- Formulation Expertise Scarcity:A limited talent pool of polymer scientists and chemists with deep expertise in antioxidant mechanisms and long-term polymer degradation testing slows down innovation and customer support.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plastic Antioxidants Market |
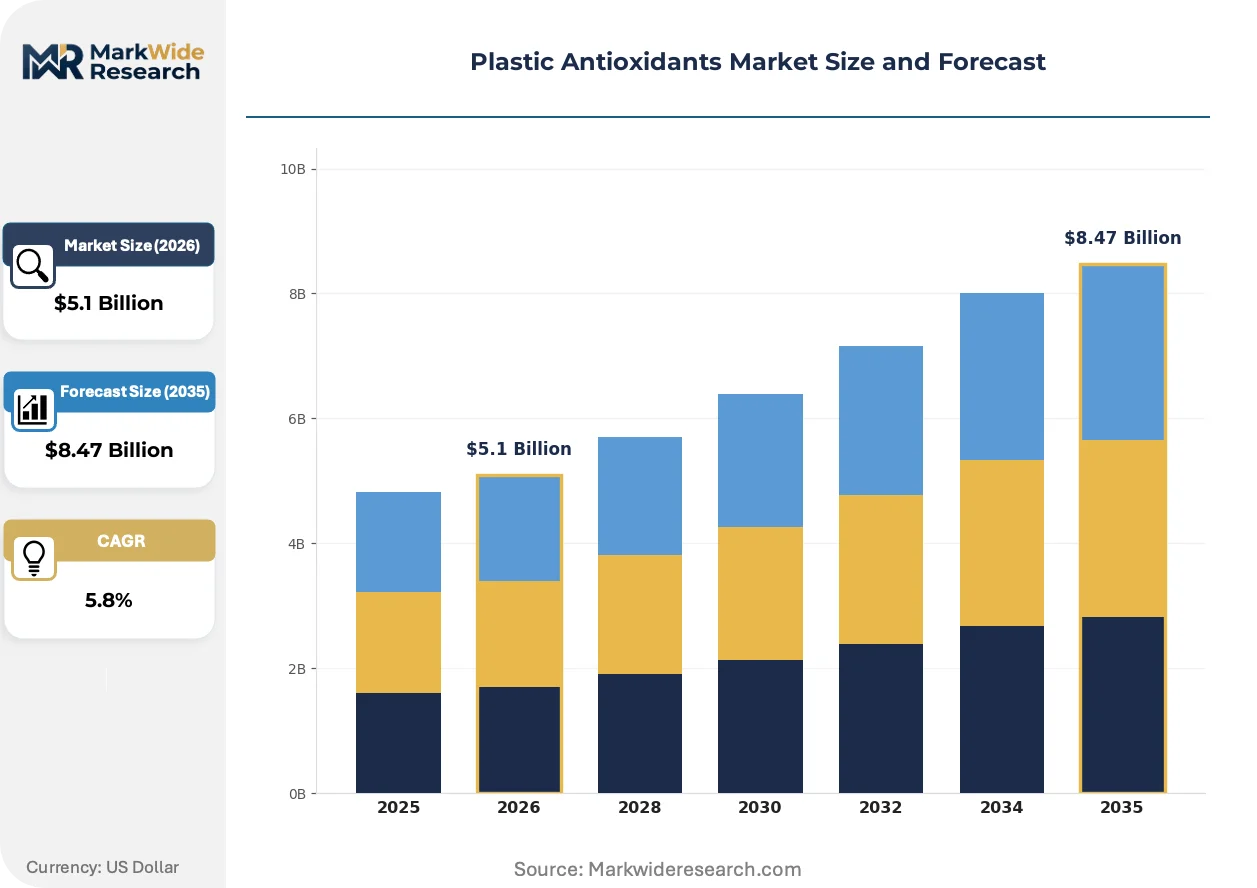
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $8.47 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hindered Phenols, Phosphites, Thioesters, Aminic Antioxidants, Polymeric Antioxidants Application: Packaging Films, Electrical Components, Automotive Parts, Industrial Films, Housewares End User Industry: Consumer Electronics, Vehicle Manufacturing, Packaging Manufacturers, Textile Producers, Construction Materials Form: Powder, Granule, Liquid, Flake, Pellet |
| Companies Covered | Lanxess AG, SI Group, BASF SE, Dover Chemical Corporation, 3V Sigma S.p.A., Clariant AG, Adeka Corporation, Evonik Industries AG, Songwon Industrial Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plastic Antioxidants Market Strategic Shifts & Innovations
Product development is pivoting toward higher-performance and more sustainable solutions. Formulators are creating specialized antioxidant systems that address the dual challenges of harsher processing conditions for recycled materials and stricter global regulations on chemical migration and safety.
Polymeric antioxidants, which feature a high molecular weight, provide exceptional thermal stability with very low volatility. Automotive and appliance manufacturers are adopting these additives to prevent degradation and discoloration in components exposed to long-term heat. This technology is integrating permanent stabilization into the polymer backbone itself, significantly reducing the risk of additive migration and improving compliance with food-contact standards.
Europe's REACH regulation continues to drive chemical substitution and product reformulation across the industry. The framework’s ongoing substance evaluation process places scrutiny on established antioxidant chemistries, compelling manufacturers to invest in toxicological testing and develop safer alternatives. This regulatory pressure most affects suppliers to the packaging and consumer goods sectors, who must now validate next-generation stabilizers to maintain market access.
A notable shift in purchasing behavior involves moving from raw antioxidant powders to dust-free physical forms like pellets, granules, or pre-blended masterbatches. This change simplifies material handling, improves dosing accuracy in automated manufacturing environments, and enhances workplace safety by minimizing airborne particulates. The trend is most advanced in the high-volume injection molding and extrusion sectors in Germany, Japan, and the United States.
Plastic Antioxidants Market Segmentation
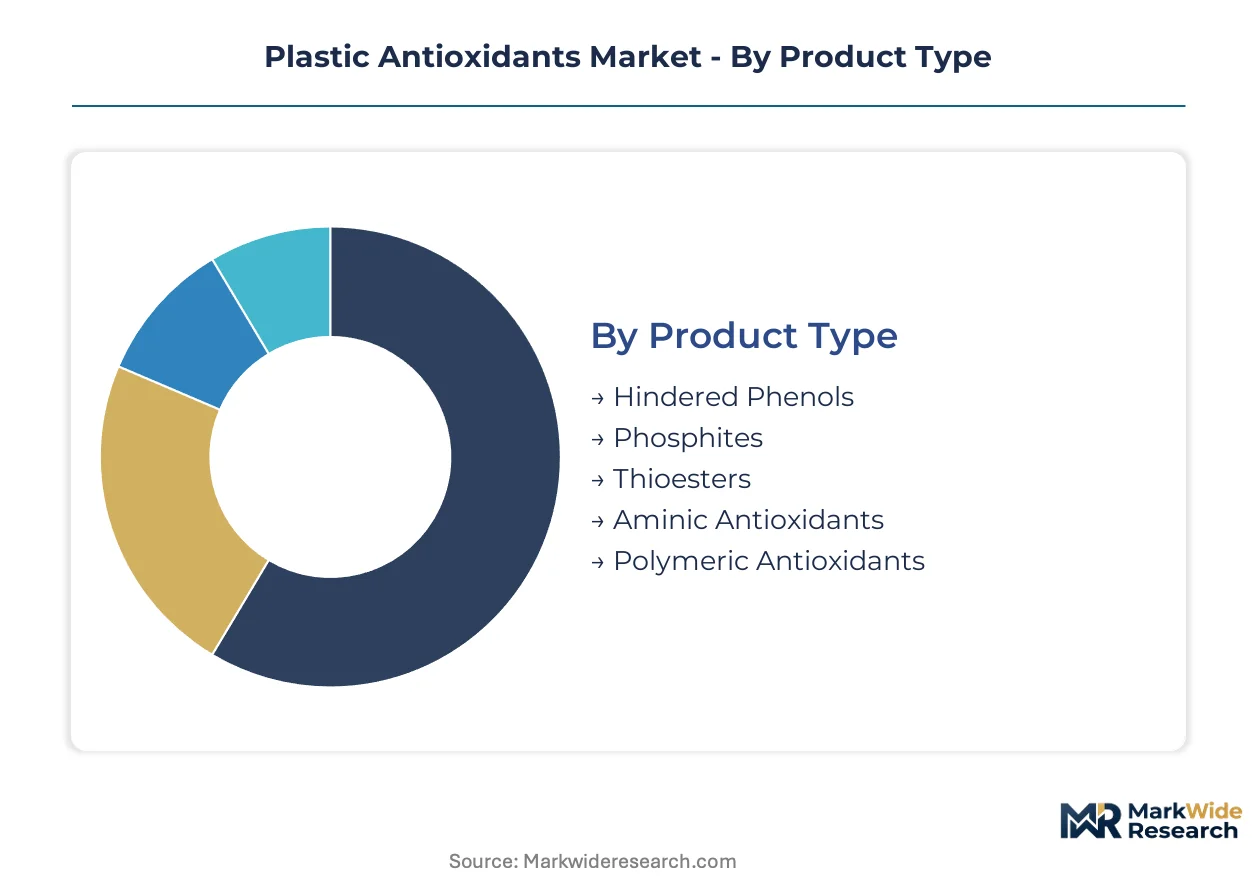
The plastic antioxidants market segments reflect the diverse chemical requirements of polymer matrices and the varied performance needs across end-use applications. Understanding these distinctions is critical for manufacturers to tailor formulations that meet both technical specifications and stringent regulatory compliance.
Product Type:
Navigating the complex landscape of chemical approvals, specific product types of plastic antioxidants face varying levels of scrutiny from regulators like the FDA and ECHA.
- Hindered Phenols:These primary antioxidants function as radical scavengers, effectively interrupting the oxidative degradation chain reactions in polymers. Demand concentrates in polyolefin stabilization for packaging and automotive applications, requiring low-migration grades for food contact compliance.
- Polymeric Antioxidants:Characterized by high molecular weight, these additives offer superior long-term thermal stability and significantly reduced migration potential due to their non-volatile nature. Automotive and appliance manufacturers increasingly adopt these for components exposed to prolonged heat, aligning with stricter material safety standards.
- Phosphites:Functioning as secondary antioxidants, phosphites decompose hydroperoxides formed during polymer processing, protecting material integrity.
- Thioesters:These secondary antioxidants provide long-term heat stability, often used in conjunction with primary antioxidants for synergistic effects.
- Aminic Antioxidants:Primarily utilized in polyamides and polyurethanes, aminic antioxidants offer excellent heat and oxidation resistance in demanding industrial applications.
Leading the category by volume: Hindered Phenols. Growing fastest: Polymeric Antioxidants.
Application:
Diverse application sectors impose distinct performance demands on plastic antioxidants, ranging from UV resistance to long-term thermal stability.
- Packaging Films:This segment requires high-purity, low-migration antioxidant grades to ensure compliance with strict food-contact regulations from bodies like the FDA and EFSA. Demand is driven by the need for extended shelf life and material integrity in flexible packaging.
- Automotive Parts:The replacement of metal components with engineering plastics in vehicles necessitates advanced antioxidants to provide superior long-term thermal stability against engine heat and oxidative environments. This supports automotive lightweighting initiatives.
- Electrical Components:Antioxidants protect sensitive polymer components in electronics from thermal degradation and electrical stress, ensuring device longevity.
- Industrial Films:These films require stabilizers to withstand harsh environmental conditions, including UV exposure and chemical contact, in agricultural and construction uses.
- Housewares:Antioxidants prevent discoloration and embrittlement in consumer goods, maintaining aesthetic appeal and functional performance over time.
Manufacturers strategically focus on Automotive Parts for high-value applications and Packaging Films for volume-driven markets.
End User Industry:
End-user industries dictate procurement patterns and specific technical requirements for plastic antioxidants, influencing formulation complexity and supply chain integration.
- Vehicle Manufacturing:This industry demands highly stable antioxidant systems for engineering plastics used in under-hood and interior components, ensuring long-term performance and safety. The shift to electric vehicles further emphasizes high-heat resistance.
- Packaging Manufacturers:Driven by consumer goods and food industries, this sector requires cost-effective, high-purity antioxidants that comply with global food contact regulations for various film and rigid packaging formats.
- Consumer Electronics:Antioxidants protect polymer casings and internal components from thermal degradation, extending the lifespan of devices like smartphones and laptops.
- Textile Producers:Stabilizers prevent yellowing and degradation of synthetic fibers during processing and end-use, maintaining fabric quality and durability.
- Construction Materials:Antioxidants are critical for PVC profiles, pipes, and other plastic building components to resist weathering and UV degradation, ensuring structural integrity.
The Vehicle Manufacturing sector represents a mature but evolving segment, while Packaging Manufacturers drive continuous innovation in high-volume grades.
Form:
The physical form of plastic antioxidants significantly impacts processing efficiency, dust control, and dosing accuracy in polymer compounding operations.
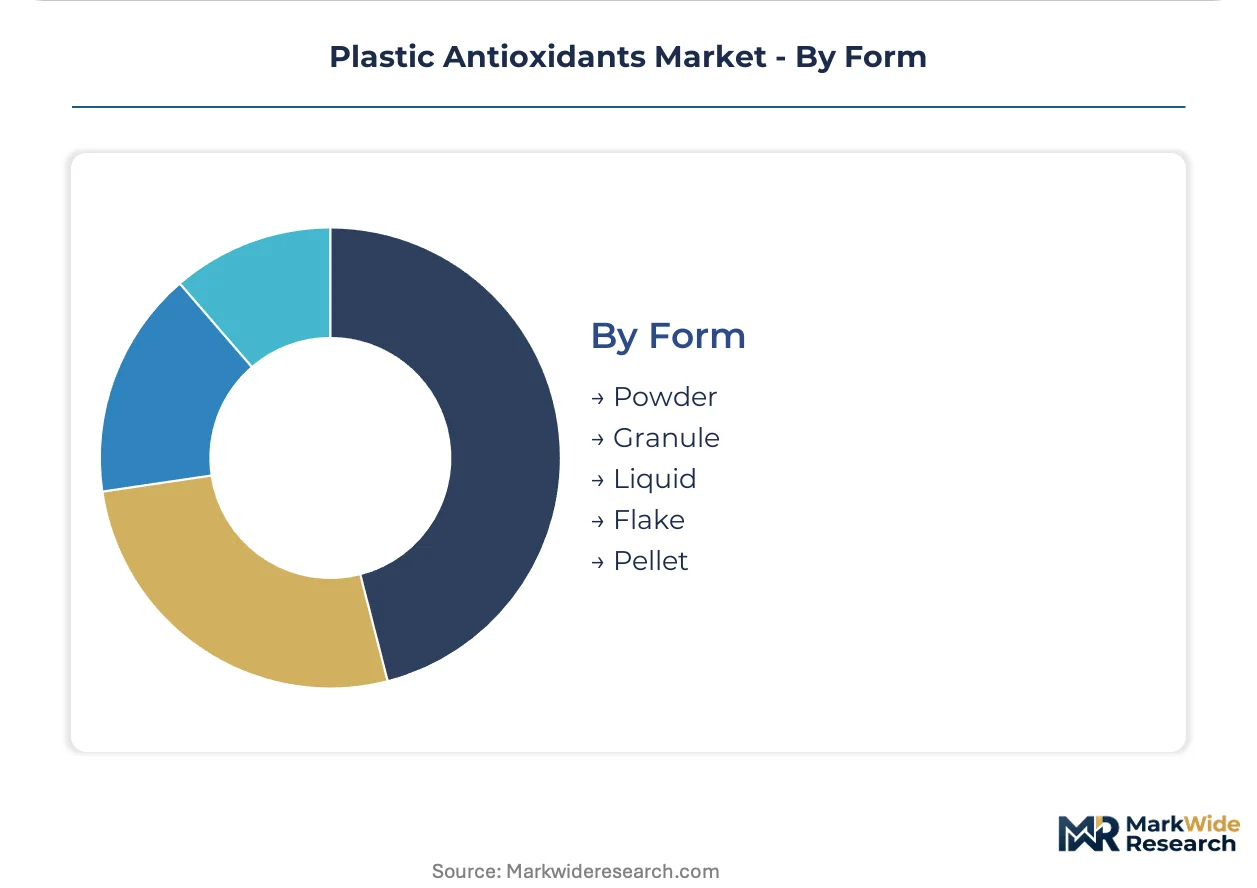
- Pellet:These dust-free, free-flowing forms are highly preferred for automated dosing systems in high-volume injection molding and extrusion, minimizing airborne particulates. The trend is advanced in Germany, Japan, and the United States.
- Granule:Granular forms offer good handling characteristics and accurate dosing, commonly used in masterbatch production and various compounding processes. They provide a balance between performance and cost.
- Powder:Powdered antioxidants offer high surface area for dispersion but present challenges with dust generation and handling.
- Liquid:Liquid forms are used for specific polymer systems requiring low-temperature incorporation or for certain coating applications.
- Flake:Flake forms provide an alternative to powders, often used in applications where a larger particle size is acceptable for dispersion.
Industry preference is shifting towards Pellet and Granule forms to enhance workplace safety and streamline automated production lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for plastic antioxidants is concentrating in regions with significant polymer processing capacity. China's coastal manufacturing regions, in particular, drive substantial consumption due to large-scale production of various plastic goods. This geographic focus influences both supply chain logistics and regulatory compliance strategies.
China
Demand for antioxidants in China is high due to its vast polymer processing industry and the push for recycled content. China's GB standards impose strict requirements on new chemical registrations and food-contact material safety. Coastal manufacturing hubs like the Yangtze River Delta and Pearl River Delta are major centers for polymer compounding and automotive component production.
United States
Automotive lightweighting and packaging innovation fuel antioxidant demand across the United States. The US EPA's Toxic Substances Control Act (TSCA) governs chemical substance registration and use. States like Michigan and Ohio host significant automotive manufacturing clusters requiring advanced thermal stabilizers.
Germany
European automotive manufacturing and circular economy initiatives drive demand for high-performance plastic antioxidants in Germany. Europe's REACH framework heavily influences product formulation and market access for chemical additives. The Rhine-Ruhr region and Bavaria are key centers for specialty chemical production and polymer processing.
Japan
High-purity grades for food contact packaging and automotive components are critical demand drivers in Japan. Japan's Chemical Substances Control Law imposes stringent requirements on chemical substances. Industrial zones around Tokyo and Nagoya concentrate advanced polymer processing and electronics manufacturing.
India
The expanding automotive and packaging sectors in India contribute significantly to antioxidant consumption. BIS standards and CDSCO regulations guide material safety and chemical approvals for plastic applications. Manufacturing clusters in Gujarat and Maharashtra are rapidly expanding their polymer processing capabilities.
Plastic Antioxidants Market Key Industry Players
Strategic partnerships dominate the current landscape, as companies seek to expand their product portfolios and geographic reach. The market structure exhibits a tiered consolidation, with large chemical conglomerates competing alongside specialized additive producers. These players can be categorized into multinational chemical giants, niche polymeric antioxidant specialists, and regional compounders. Portfolio diversification into sustainable and high-performance solutions is another key competitive move.
Within the multinational chemical giants, BASF SE and Evonik Industries AG exemplify broad chemical synthesis capabilities and specialty product development. These large entities offer diverse portfolios for various polymer systems, often including phosphite and hindered phenol chemistries. Songwon Industrial Co. Ltd. occupies a position as a specialized provider of polymeric antioxidants, focusing on long-term heat stability for demanding end-use applications. These companies navigate complex global regulatory frameworks to maintain market access.
| Leading Market Players |
|---|
| Lanxess AG |
| SI Group |
| BASF SE |
| Dover Chemical Corporation |
| 3V Sigma S.p.A. |
| Clariant AG |
| Adeka Corporation |
| Evonik Industries AG |
| Songwon Industrial Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Europe's REACH framework, with its stringent chemical substance evaluation, gates qualified supply and commands premium-tier pricing access for compliant plastic antioxidants. This regulatory landscape compels manufacturers to invest significantly in product safety and performance validation.
Pricing Analysis
Volume-driven segments like packaging films exhibit tighter margins compared to high-performance automotive applications. The dominant pricing structure is contract-based long-term offtake for major polymer producers. Price differentiation stems from specialized quality grades for food contact compliance and customization levels for specific polymer systems. Pricing pressure stems from fluctuating petrochemical feedstock prices for phenol and phosphorus derivatives. Packaging manufacturers are most price-sensitive, while vehicle manufacturing demands high-performance grades with less sensitivity.
Supply Chain Analysis
Direct-to-OEM channels handle large-volume polymer producer demand, while specialized distributors serve smaller compounders. Geographic supply concentration centers in China, Germany, and the United States, reflecting major chemical production hubs. The supply chain draws heavily from raw materials like phenol and phosphorus derivatives. Raw material price volatility represents a significant structural risk for antioxidant manufacturers. The dominant downstream structure involves direct sales to large polymer producers and indirect sales through distributors to smaller processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plastic antioxidants market is a cost-of-compliance story, where Europe's REACH framework creates a significant barrier-to-entry moat for established, compliant players.
For Market Incumbents:Acquire specialized intellectual property in bio-based antioxidant chemistries to diversify product portfolios. Invest in advanced R&D for next-generation polymeric antioxidants, addressing the threat of regulatory de-selection for conventional chemistries. Form strategic partnerships with polymer producers to integrate stabilization solutions early in the development cycle. Expand manufacturing capacity in key regional hubs like China to serve localized demand for high-volume applications.
For New Entrants and Emerging Players:Launch high-purity, low-migration antioxidant grades targeting the underpenetrated and rapidly evolving food packaging segment. Focus on sustainable solutions, such as bio-based antioxidants, to appeal to brand owners prioritizing green plastics. Leverage advanced material science to develop niche additives for high-heat electronics, offering superior thermal stability. A go-to-market angle emphasizing regulatory compliance and customized solutions for specific polymer systems provides differentiation.
For Investors and Strategic Acquirers:The increasing adoption of recycled content mandates is the leading indicator that demand for high-performance stabilizers will remain robust for the long term. Target acquisition archetypes include specialized additive producers with strong R&D capabilities in polymeric or bio-based antioxidants. A specific signal to watch is the rate of new chemical registrations for sustainable antioxidant alternatives, indicating market acceptance and regulatory approval pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Serves rapidly expanding polymer processing demand in China and India. |
| Bio-Based Antioxidant R&D | Addresses consumer and regulatory demand for sustainable plastic additives. |
| Customized One-Pack Systems | Offers enhanced processing efficiency and performance for specific polymer applications. |
| Strategic Regulatory Partnerships | Navigates complex global compliance pathways, ensuring market access. |
| Advanced Polymer Testing Facilities | Validates long-term thermal stability for demanding automotive and electronics uses. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for comprehensive market sizing. The analysis combined extensive primary interviews with polymer scientists, procurement leads at OEMs, R&D directors, and regulatory affairs specialists. This approach ensured a robust understanding of market dynamics, triangulating quantitative data with qualitative insights from industry experts. Bottom-up and top-down data validation techniques were applied to ensure accuracy across all segments.
Market volume and value outputs were modeled at a granular level across product type, application, end-user industry, form, and regional production hubs. The analytical framework integrated historical market performance with forward-looking projections throughout the forecast period. Compound annual growth rates were derived from detailed analysis of market drivers, restraints, and strategic opportunities. Key industry-specific forecast inputs included recycled polymer content mandates and automotive lightweighting trends.
Raw material price volatility, new regulatory restrictions, and technological disruption are the dominant revision risks for market forecasts. These forecasts reflect assumptions regarding economic stability and policy continuity across major regions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Anti-Settling Agents Market
Additives
Ammonium Phosphatide Market
Additives
Asia-Pacific Fuel Additives Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Global Cement Additives Market
Additives
Extrusion Aids Market
Additives
Shortstop Inhibitor Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Pectin Market
Additives
Clouding Agents Market
Additives
United Kingdom Feed Additives Market
Additives
Sodium Benzoate Market
Additives
Inorganic Rheology Modifiers Market
Additives
Global Corrosion Inhibitor Market
Additives
Global Cement and Concrete Additives Market